
 Indonesia Architectural Coatings Market | 2026-2036
Indonesia Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Architectural Coatings Market Foresight
SNI 06-6755-2001 for interior wall coatings is redrawing competitive access, forcing reformulation investments before market entry. PPG Indonesia leverages its global color-matching technology to sustain premium positioning in Jakarta's commercial tower segment. Mowilex anchors its presence through deep distribution into secondary cities beyond Java. AkzoNobel N.V. differentiates via water-based architectural systems that comply with tightening volatile organic compound thresholds.
Architectural coatings comprise resin-binder systems—typically acrylic, alkyd, or epoxy—dispersed in water or solvent carriers, applied to protect and decorate building substrates against moisture, ultraviolet degradation, and mechanical wear. Emulsion formulations lead volume due to their compatibility with Indonesia's humid tropical climate and shorter drying cycles. Solvent-borne systems retain share in industrial structure applications where chemical resistance and film hardness outweigh environmental considerations. Acrylic formulations capture expanding share among contractors serving government infrastructure tenders that specify low-odor, quick-recoat properties.
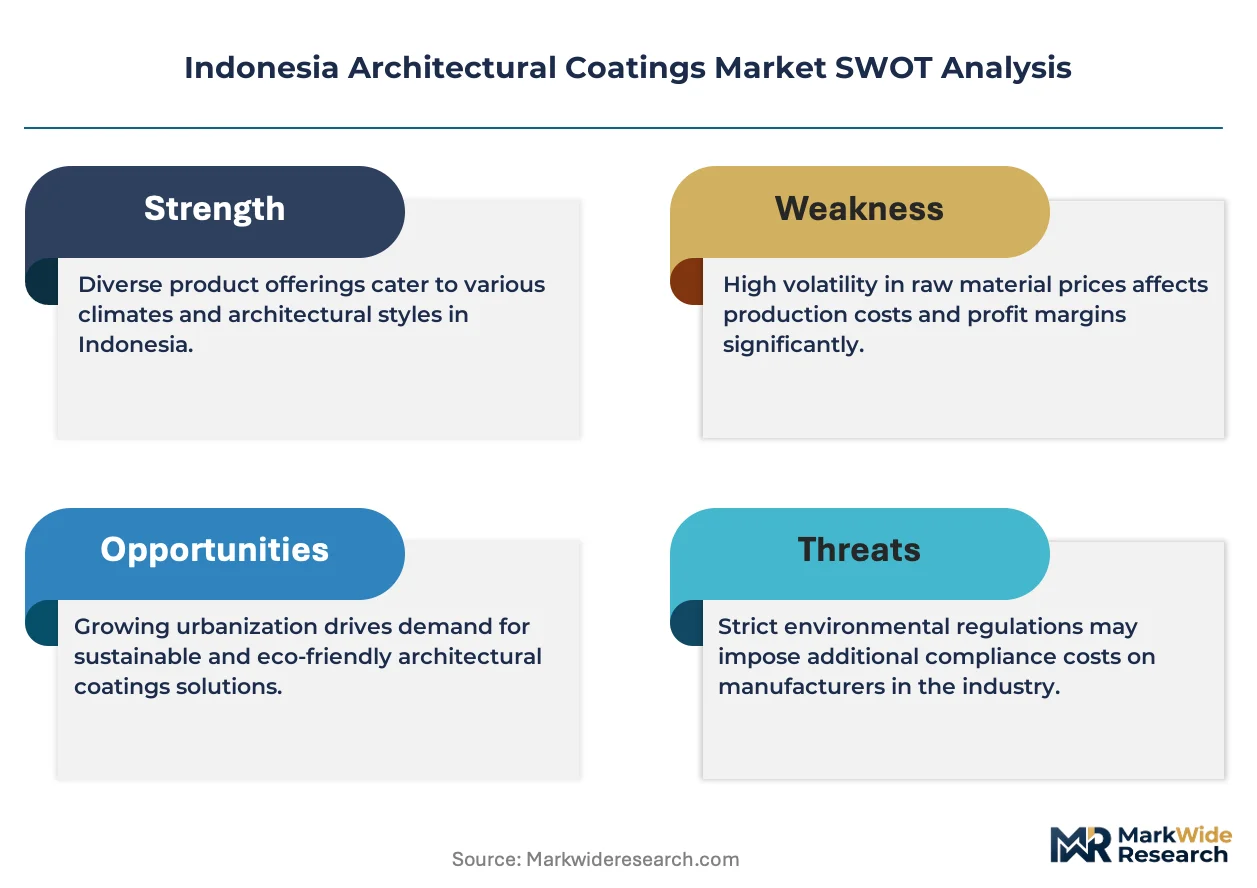
BIS-equivalent SNI standards and Indonesia's Ministry of Public Works regulations govern product approval for state-funded construction, while the Ministry of Environment enforces emission controls that push manufacturers toward compliant chemistries. The national green building council's certification program shapes architect and government agency procurement criteria, tilting specifications toward verified sustainable formulations. Stakeholders must monitor enforcement consistency across provincial building departments to anticipate where compliance costs will concentrate or relax.
Market Dynamics
Indonesia's mandatory SNI certification for architectural coatings is forcing multinational suppliers to rebuild formulations at local pilot plants before commercial registration, compressing entry timelines and concentrating technical investment in Greater Jakarta's industrial corridors.
Growth Catalysts
- Java residential construction:High-rise developers in Greater Jakarta specify low-VOC emulsion systems for interior wall applications, pulling volume from solvent-borne alternatives.
- SNI 06-6755-2001 compliance:Indonesia's national standard for interior wall coatings creates a quality floor that rewards pre-certified suppliers with state tender access.
- Water-based acrylics:Quick-dry properties align with monsoon construction windows, accelerating contractor adoption across humid tropical sites.
Market Restraints
- Titanium dioxide volatility:Pigment cost swings compress margin buffers for mid-tier suppliers serving price-sensitive provincial markets.
- Import dependency for specialty resins:Epoxy and alkyd feedstock concentration in Northeast Asian supply chains exposes formulators to freight rate spikes and currency mismatches.
- Solvent-borne substitution ceiling:Industrial structure applications in petrochemical and marine segments retain chemical resistance requirements that water-based systems cannot yet match.
Strategic Opportunities
- Secondary city distribution:Surabaya, Medan, and Makassar construction booms lack dedicated coating distribution infrastructure, rewarding early logistics investment.
- Green Building Council Indonesia certification:Verified sustainable formulations unlock architect specification in premium commercial towers and government office projects.
- Digital color-matching kiosks:Hardware-software convergence enables contractor-grade tinting at building material retailers outside Java, reducing lead times for custom orders.
Industry Challenges
- Formulation chemist scarcity:Local talent pools lack experience in humidity-stable resin design, forcing reliance on expatriate technical staff or foreign R&D support.
- SNI testing queue congestion:Certification backlogs at Ministry of Industry laboratories delay product launches by six to twelve months, freezing working capital in pre-registered inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Architectural Coatings Market |
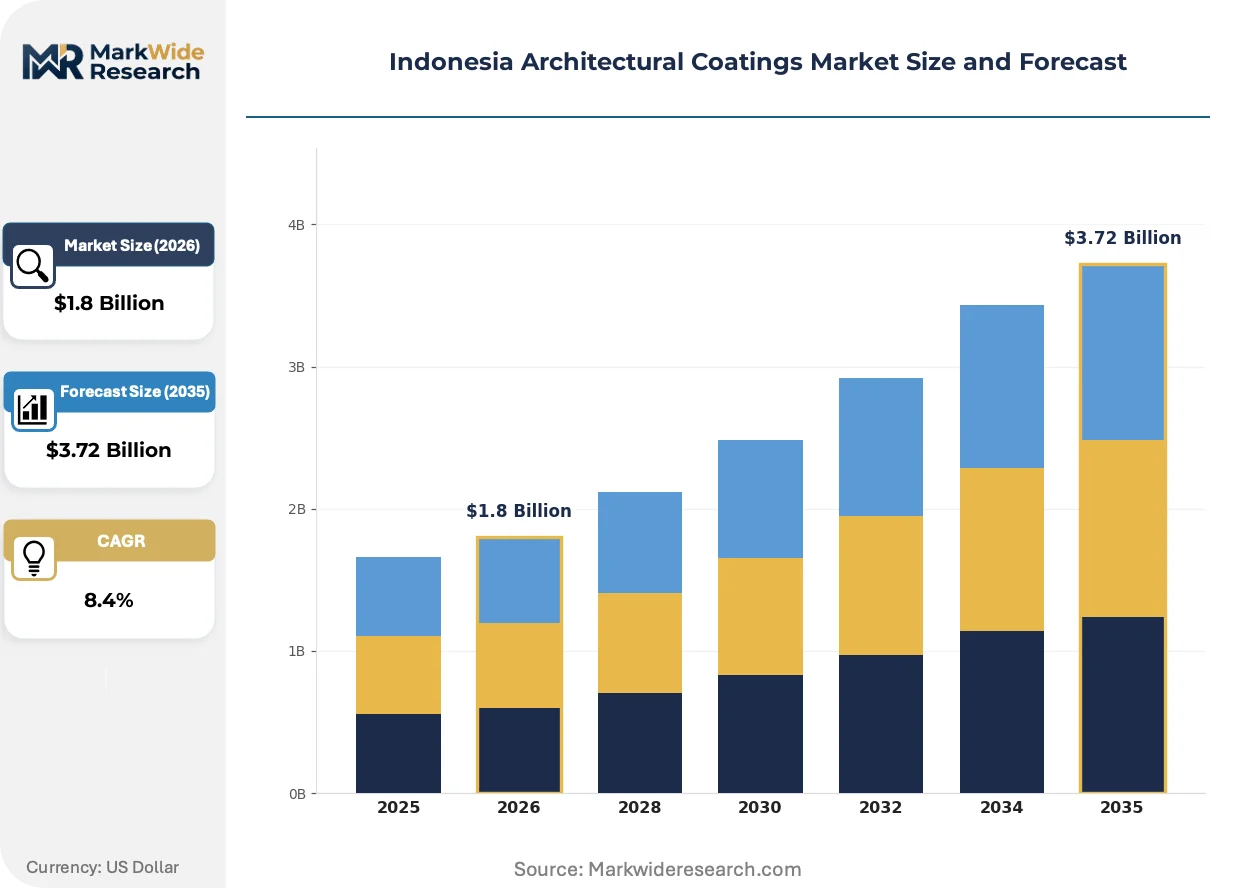
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion, Solvent-Borne, Powder Coatings, Stains Application: Residential, Commercial Buildings, Industrial Structures, Infrastructure Formulation: Acrylic, Polyester, Epoxy, Alkyd End User: Contractors, Private Homeowners, Architects, Government Agencies |
| Companies Covered | PPG Indonesia, Mowilex, AkzoNobel N.V., Kansai Paint Co Ltd, PT Propan Raya, Nippon Paint Holdings Co., Ltd., Avian Brands, Asian Paints, Jotun, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Architectural Coatings Market Shifts & Advancements
Formulation chemistry and specification behavior are diverging across Indonesia's construction value chain, with regulatory pressure and contractor workflow demands pulling innovation in distinct directions.
Nano-scale functional additives are miniaturizing protective capabilities into thinner film builds. Silica and zinc oxide nanoparticles embedded in acrylic matrices deliver ultraviolet blocking and antimicrobial properties without the gloss trade-offs of conventional high-build systems. Specifiers in Jakarta's premium residential segment are specifying these formulations for facade durability guarantees exceeding ten years. The technology is miniaturizing the distinction between decorative and protective coating categories, compressing supplier portfolios into unified product lines.
Indonesia's Ministry of Environment enforcement of volatile organic compound thresholds is tightening discharge permits for solvent-borne production facilities. Industrial park operators in Cilegon and Gresik are denying tenancy to coating manufacturers lacking water-based process lines. State-funded infrastructure tenders now incorporate low-odor specifications that exclude traditional alkyd formulations from bridge and highway structure contracts.
Contractor purchasing is fragmenting across project-specific procurement platforms that disintermediate traditional distributor relationships. Mid-size construction firms in Bandung and Semarang are sourcing direct from manufacturer regional depots to capture volume rebates previously reserved for national distributors. This pattern concentrates in government infrastructure verticals where tender transparency requirements favor documented supply chain compression.
Indonesia Architectural Coatings Market Segmentation
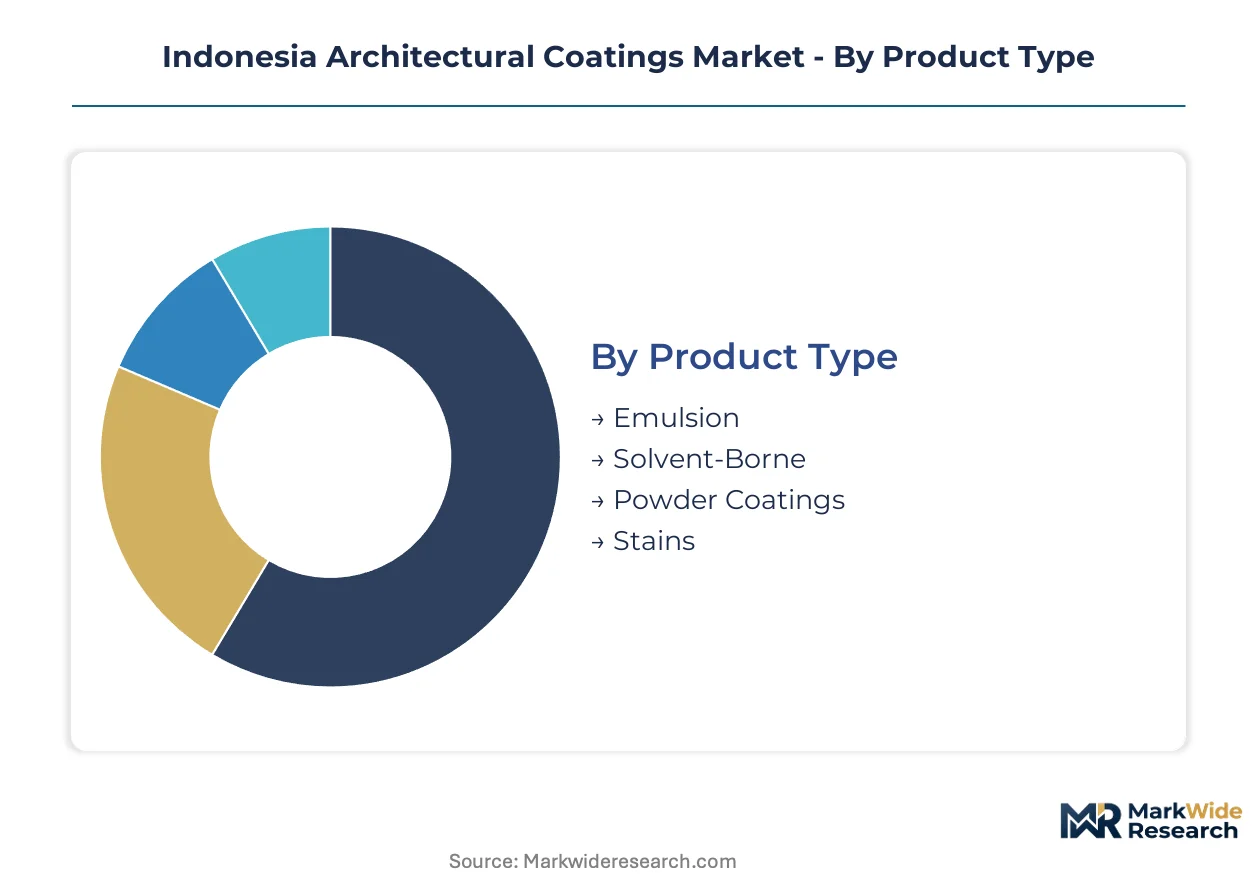
Segmentation in Indonesia's architectural coatings market reveals how formulation chemistry, application requirements, and procurement authority intersect to create distinct margin pools. Understanding these divides allows suppliers to align R&D investment with where specification power actually sits.
Product Type:
Margin concentration follows the water-based transition, with premium capture shifting from solvent systems toward compliant emulsion technologies.
- Emulsion:Water-dispersed acrylic and vinyl acetate copolymers dominate interior and exterior wall applications across Java's high-rise residential towers. Greater Jakarta developers specify low-VOC emulsion systems to meet Green Building Council Indonesia criteria and accelerate monsoon-season recoat schedules.
- Solvent-Borne:Alkyd and polyurethane systems retain structural share where chemical resistance and film hardness outweigh environmental compliance costs. Industrial structure applications in Cilegon's petrochemical zones and Gresik's marine facilities continue to specify solvent-borne epoxies for substrate protection against aggressive chemical exposure.
- Powder Coatings:Thermoset formulations applied via electrostatic spray to metal architectural elements, concentrated in commercial facade and infrastructure railing segments.
- Stains:Penetrating oil and water-based systems for timber protection in residential decking and heritage restoration projects.
The dominant share belongs to Emulsion, while Powder Coatings is climbing the fastest as metal facade specifications expand in premium commercial towers.
Application:
Volume flows toward residential construction, but tender transparency in government verticals is compressing distributor margins and rewarding direct manufacturer relationships.
- Residential:Interior wall and ceiling coatings specified by developers across Greater Jakarta, Surabaya, and Bandung. Low-OC emulsion systems with quick-dry properties align with compressed construction windows in Indonesia's humid tropical climate.
- Commercial Buildings:Facade and interior specifications set by architects pursuing Green Building Council Indonesia certification. Premium acrylic and nano-modified formulations command specification in Jakarta's Grade-A office towers.
- Industrial Structures:Chemical plants, power generation facilities, and marine infrastructure requiring high-build epoxy and polyurethane protection systems.
- Infrastructure:Bridge, highway, and port structures governed by Ministry of Public Works tenders incorporating low-odor and durability specifications.
Residential absorbs the largest volume, though Infrastructure is expanding most quickly as state-funded construction accelerates across secondary cities.
Formulation:
Resin selection determines compliance trajectory and technical service intensity, with acrylic systems capturing specification share as alkyd faces regulatory pressure.
- Acrylic:Water-based emulsions and solvent-borne thermoplastics offering UV resistance and color retention for exterior applications. Government infrastructure tenders specifying quick-recoat properties are pulling contractor adoption toward acrylic systems.
- Polyester:Thermoset powder and liquid formulations for metal substrate protection in commercial facade and industrial equipment applications.
- Epoxy:Two-component systems delivering chemical resistance and adhesion to concrete and steel in industrial and infrastructure environments.
- Alkyd:Oil-modified polyester resins in solvent-borne decorative and protective coatings facing displacement by water-based alternatives under tightening Ministry of Environment discharge permits.
Acrylic holds the specification lead, while Epoxy is gaining share fastest in industrial structure applications where performance requirements resist substitution.
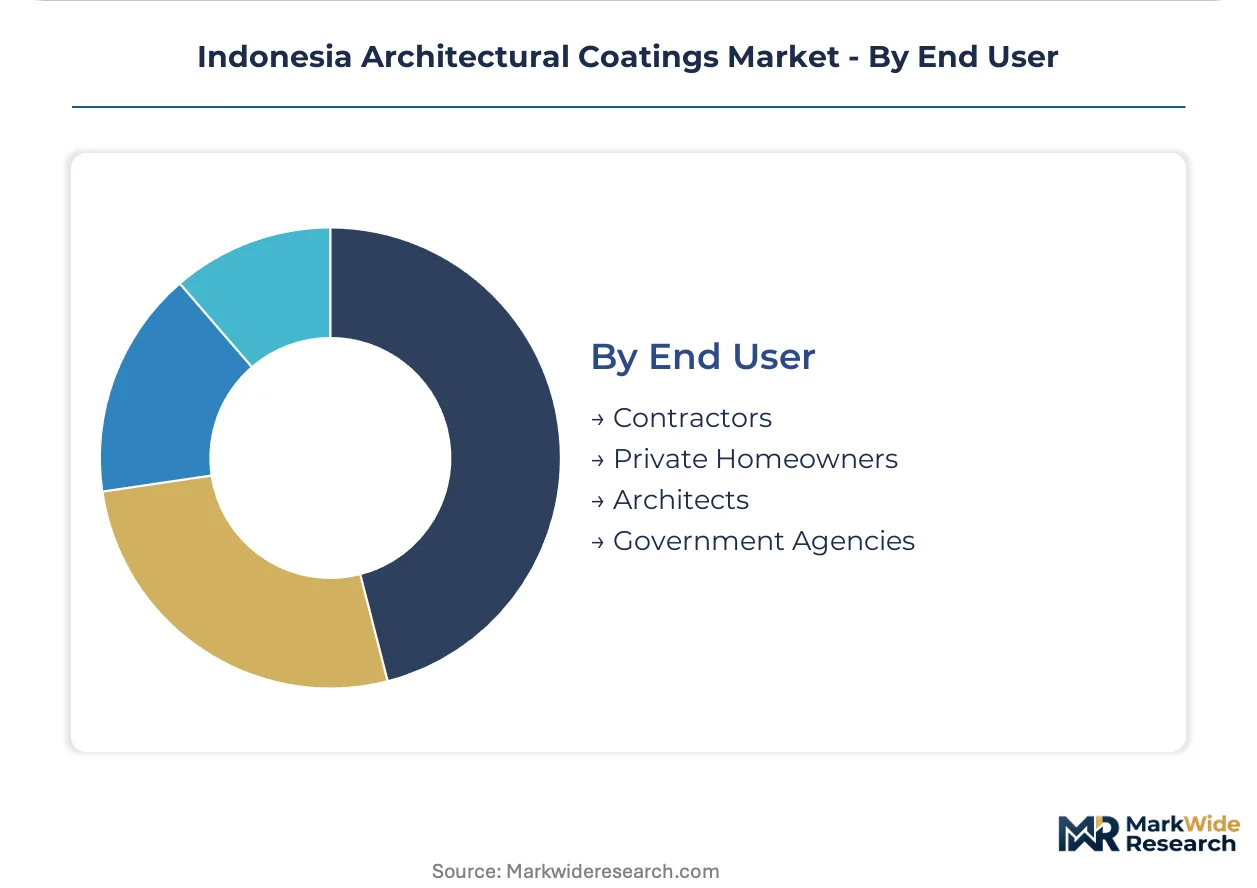
End User:
Procurement authority is fragmenting as contractors build direct manufacturer relationships and government tender transparency requirements reshape distribution economics.
- Contractors:Mid-size construction firms in Bandung and Semarang sourcing direct from regional manufacturer depots to capture volume rebates. Workflow demands prioritize quick-dry formulations compatible with monsoon construction schedules.
- Private Homeowners:Retail purchasers in secondary cities driving demand for pre-tinted emulsion systems through building material retailers.
- Architects:Specification authority in premium commercial and residential towers, with Green Building Council Indonesia certification requirements tilting selections toward verified low-VOC formulations.
- Government Agencies:Ministry of Public Works and state-owned enterprise procurement governed by SNI certification requirements and documented supply chain transparency rules.
Contractors command the largest procurement volume, yet Government Agencies are consolidating specification power fastest through mandatory certification and tender transparency mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Developers and government procurement officers concentrate purchasing power in Java's urban corridors, with secondary city contractors emerging as volume growth vectors beyond the capital region.
Greater Jakarta
High-rise residential towers and Grade-A commercial offices drive specification of low-VOC emulsion systems. Green Building Council Indonesia certification requirements filter tender access for state-funded projects. Bekasi and Tangerang industrial zones host formulation pilot plants serving multinational registration requirements.
Surabaya
East Java's construction boom lacks dedicated coating distribution infrastructure, creating logistics gaps for contractor direct-sourcing. Ministry of Public Works tenders for port and highway structures specify SNI-certified durability guarantees. Gresik's petrochemical zones sustain solvent-borne epoxy demand for chemical-resistant applications.
Bandung
Mid-size construction firms source direct from manufacturer regional depots to capture volume rebates. West Java's building departments enforce SNI compliance with variable consistency, creating regulatory uncertainty for new entrants. Cimahi industrial corridors concentrate tinting and blending operations serving provincial contractors.
Medan
North Sumatra's residential and commercial construction accelerates without established coating distribution networks. Provincial procurement offices adopt Ministry of Environment discharge permit standards unevenly, fragmenting compliance costs. Belawan port proximity exposes formulators to resin import freight volatility from Northeast Asian supply chains.
Makassar
Sulawesi's infrastructure expansion and nickel processing facility construction generate protective coating demand. Government agency tenders incorporate low-odor specifications that displace traditional alkyd formulations. Makassar's emerging logistics hubs attract early distribution investment from Java-based suppliers.
Indonesia Architectural Coatings Market Competitive Landscape
Player mix skews toward multinational specialists with certified formulation capabilities and domestic distributors with secondary city reach. Market structure concentrates specification power among SNI-pre-certified suppliers, compressing margins for uncertified entrants. Two archetypes dominate: global technology licensors with color-matching platforms, and regional distributors with provincial logistics depth. Competitive moves center on local pilot plant commissioning and direct contractor relationship building.
Among multinational coating suppliers, PPG Indonesia and AkzoNobel N.V. represent the technology-licensor archetype with global formulation platforms adapted for Indonesian compliance. Mowilex occupies a position within the domestic distribution-focused tier, anchoring secondary city penetration strategies. These three exemplify how SNI certification timelines and reformulation investments filter competitive access.
| Leading Market Players |
|---|
| PPG Indonesia |
| Mowilex |
| AkzoNobel N.V. |
| Kansai Paint Co Ltd |
| PT Propan Raya |
| Nippon Paint Holdings Co., Ltd. |
| Avian Brands |
| Asian Paints |
| Jotun |
| Others |
Supply & Pricing Matrix
SNI 06-6755-2001 certification gates both supply qualification and price differentiation simultaneously, bifurcating the market between pre-certified suppliers commanding tender access premiums and uncertified competitors trapped in commoditized retail channels. Reformulation investments at local pilot plants concentrate technical costs in Greater Jakarta's industrial corridors, while provincial buyers face extended lead times and freight-adjusted pricing.
Pricing Analysis
Cost-plus contracts with titanium dioxide indexation dominate raw material procurement between formulators and pigment suppliers, passing commodity volatility through to end-user pricing. Three-tier pricing structure across premium, standard, and economy levels separates SNI-certified emulsion systems from solvent-borne alternatives and uncertified imports. Pricing pressure stems from titanium dioxide cost swings compressing margin buffers for mid-tier suppliers serving price-sensitive provincial markets. Government contractors exhibit lowest price sensitivity due to tender transparency requirements, while retail homeowners in secondary cities drive hardest bargain hunting.
Supply Chain Analysis
Strait of Malacca transit underwrites resin feedstock security for Indonesian formulators sourcing specialty epoxies and alkyds from Northeast Asian supply chains. Manufacturing concentration in China, South Korea, and Japan feeds Indonesia's import dependency for high-performance resin systems. Raw material dependencies center on titanium dioxide from Chinese chloride-process plants, acrylic monomers from Singaporean crackers, and epoxy hardeners from Japanese specialty chemical producers. Single-source vulnerability concentrates in titanium dioxide supply where Chinese environmental enforcement periodically idles pigment capacity. Distribution runs through national distributors with Java warehousing and direct manufacturer depots serving contractor direct-sourcing in Bandung and Semarang.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as water-based acrylic systems displace solvent-borne alkyds under tightening Ministry of Environment discharge permits. Incumbents must fortify formulation capabilities and distribution control to retain specification power.
For Market Incumbents: Secure SNI certification pipeline priority at Ministry of Industry laboratories to freeze out competitor registration timelines. Deepen backward integration into acrylic monomer supply through Singaporean cracker partnerships or captive Southeast Asian resin production. Defensive positioning against Mowilex's secondary city distribution depth requires preemptive logistics investment in Surabaya and Makassar corridor warehousing. For New Entrants and Emerging Players: Technical service gaps in humidity-stable resin design create entry vectors for specialist formulators with expatriate chemist networks. Target Surabaya's infrastructure tender vertical where SNI-certified durability specifications outrun established supplier capacity. Digital color-matching kiosk deployment at building material retailers outside Java offers differentiated go-to-market angle against national distributor incumbents. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across water-based emulsion manufacturing as Ministry of Environment enforcement mandates process line conversions. Five-to-ten year viability favors acquirers of SNI-pre-certified domestic formulators with underutilized pilot plant capacity in Greater Jakarta industrial zones. Signal to watch is certification queue clearance rates at Ministry of Industry laboratories as inflection indicator for working capital release velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Supply | Captive resin supply insulates margin compression from Singaporean cracker price volatility. |
| SNI Certification Fast-Track Investment | Pre-certified status unlocks Ministry of Public Works tender access before competitors clear registration queues. |
| Secondary City Distribution Buildout | Surabaya and Makassar logistics hubs capture contractor direct-sourcing volume outside Java. |
| Digital Color-Matching Kiosk Deployment | Hardware-software convergence reduces custom order lead times for provincial building material retailers. |
| Green Building Council Indonesia Formulation Partnership | Verified sustainable coatings specification secures architect selection in premium commercial tower projects. |
Research Methodology
Initial hypotheses were tested against primary input from formulation chemists at multinational coating suppliers, procurement managers at Greater Jakarta developers, distribution channel heads at building material retailers, and regulatory affairs leads navigating SNI certification processes, then refined against secondary validation from Ministry of Industry registration databases, Ministry of Public Works tender documentation, Green Building Council Indonesia certification records, and customs import data for titanium dioxide and specialty resin feedstocks. Bottom-up volume estimates from contractor consumption patterns triangulated against top-down market sizing from production capacity disclosures.
Variance decomposition across the projection horizon isolates volume drivers by product type, application vertical, formulation chemistry, and end-user procurement authority, with CAGRs derived from segment-level growth trajectory modeling. Segmentation dimensions span emulsion versus solvent-borne versus powder coating technologies, residential versus commercial versus industrial versus infrastructure applications, acrylic versus epoxy versus alkyd resin systems, and contractor versus government agency versus architect versus retail homeowner procurement channels. Forecast inputs incorporate monsoon season construction windows, SNI enforcement consistency variation across provincial building departments, and titanium dioxide price cycle amplitude.
Underlying assumptions cover Ministry of Environment discharge permit tightening trajectory and SNI laboratory capacity expansion, with deviation risk concentrated in certification queue congestion duration and Northeast Asian resin supply chain disruption frequency. Practitioners should keep alternative scenarios live as provincial regulatory enforcement heterogeneity and titanium dioxide supply volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Asia-Pacific Facade Market
Building Materials
Asia-Pacific Kinetic Tiles Market
Building Materials
Singapore Architectural Coatings Market
Building Materials
Middle East and Africa Concrete Admixtures Market
Building Materials
Engineered Wood Product Market
Building Materials
Pozzolana Cement Market
Building Materials
Rapid Strength Concrete Market
Building Materials
Foam Concrete Market
Building Materials
Timber Frames Market
Building Materials
United States Construction Materials Market
Building Materials
Qatar Cement Market
Building Materials
Global White Cement Market
Building Materials
Germany Aluminum Door and Window Market
Building Materials
Global Fiber Cement Siding Market
Building Materials
Italy Facade Market
Building Materials
Low-E Construction Glass Market