
 Global Bendamustine Injection Market | 2026-2036
Global Bendamustine Injection Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bendamustine Injection Market Foresight
Oncology formulation specialists is redrawing competitive boundaries in bendamustine manufacturing. Teva leverages its established generic injectable infrastructure across North American hospital networks. Eagle Pharmaceuticals differentiates through ready-to-use solution formats that reduce compounding burden in cancer treatment centers. Mylan sustains cost-competitive positions in multi-dose vial supply across European oncology clinics.
Bendamustine hydrochloride injection is an alkylating antineoplastic agent supplied as a lyophilized powder or liquid concentrate requiring reconstitution or dilution before intravenous administration, with typical dosing at 100-120 mg/m² over two consecutive days in 28-day cycles for chronic lymphocytic leukemia and non-Hodgkin's lymphoma protocols. Single-dose vials command premium positioning in hospital pharmacies where waste reduction protocols dominate procurement criteria, while ready-to-use solutions represent the fastest-expanding format as oncology clinics prioritize pharmacy efficiency and reduced preparation error risk. Prefilled syringes occupy a nascent but growing niche in specialty pharmacy channels serving outpatient infusion centers.
FDA sterility guidelines, EMA GMP Annex 1 revisions for sterile medicinal products, and WHO prequalification standards collectively elevate manufacturing compliance costs while restricting market entry for non-specialized producers. These frameworks channel procurement toward validated suppliers with dedicated oncology injectable suites and established regulatory dossiers. Stakeholders must monitor evolving bioequivalence requirements for complex generic alternatives as patent cliffs approach for originator formulations.
Market Dynamics
FDA sterility guideline revisions and EMA GMP Annex 1 updates are compressing manufacturing capacity while channeling procurement toward validated oncology injectable specialists with dedicated sterile suites.
Growth Catalysts
- Chronic Lymphocytic Leukemia Protocol Expansion:Oncology clinics in the United States, Germany, and Japan are extending bendamustine-based regimens into earlier treatment lines, broadening addressable patient populations.
- EMA GMP Annex 1 Revision:Stricter sterile manufacturing standards are accelerating facility upgrades among established producers, creating compliance-based competitive moats that deter marginal entrants.
- Ready-to-Use Formulation Demand:Hospital pharmacies and infusion centers are prioritizing pre-mixed solutions that eliminate compounding steps and reduce preparation error risk.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for bendamustine hydrochloride concentrates in a limited number of specialized chemical synthesis facilities, creating single-source vulnerability.
- FDA Sterile Injectable Compliance Costs:Facility validation, environmental monitoring, and contamination control investments have escalated capital requirements for new market entrants.
- Lyophilized Powder Processing Complexity:Freeze-drying cycle optimization and moisture specification adherence demand specialized equipment and extended batch release timelines.
Strategic Opportunities
- Outpatient Infusion Center Expansion:Prefilled syringe formats targeting specialty pharmacy channels serving ambulatory oncology settings remain underdeveloped relative to hospital-focused vial supply.
- Japan PMDA Regulatory Pathway:The Ministry of Health, Labour and Welfare's streamlined review for oncology generics offers accelerated market access for dossier-ready manufacturers.
- Closed-System Transfer Device Integration:Compatibility with hazardous drug containment systems used in US hospital pharmacies represents a format differentiation vector.
Industry Challenges
- Sterile Manufacturing Workforce Scarcity:Qualified aseptic processing operators and quality assurance specialists command premium compensation in competitive biologics and injectables labor markets.
- Multi-Jurisdictional Dossier Harmonization:Reconciling FDA, EMA, PMDA, and WHO prequalification requirements demands dedicated regulatory affairs capacity and extended submission preparation cycles.
- Legacy Vial Format Inventory Stranding:Hospital pharmacies with substantial lyophilized powder stockpiles face transition friction toward ready-to-use alternatives despite operational efficiency gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bendamustine Injection Market |
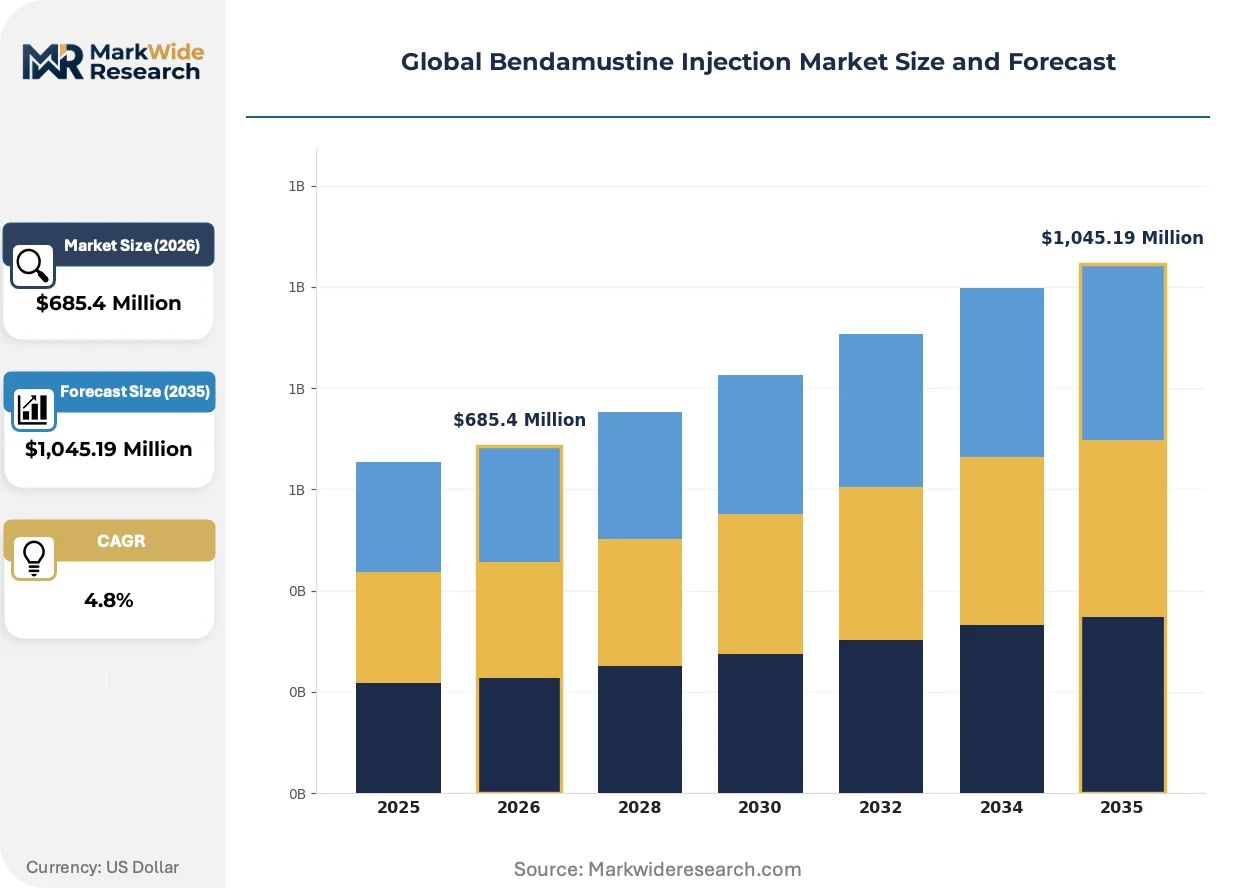
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-dose Vials, Multi-dose Vials, Prefilled Syringes, Ready-to-Use Solutions Therapy Area: Chronic Lymphocytic Leukemia, Non-Hodgkin’s Lymphoma, Multiple Myeloma, Mantle Cell Lymphoma End User: Cancer Treatment Centers, Oncology Clinics, Research Institutes, Specialty Pharmacies Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Sales |
| Companies Covered | MundiPharma, Natco Pharma, Teva, Miracalus Pharma, Emcure, Eisai, Mylan, Apotex Corp, Eagle Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bendamustine Injection Market Shifts & Advancements
Manufacturing format evolution and regulatory compliance automation are restructuring competitive advantage sources in bendamustine supply, with pharmacy workflow optimization replacing pure cost competition as the primary value lever.
Ready-to-use bendamustine solution formats are bifurcating the market between premium-positioned liquid concentrates and traditional lyophilized powders requiring reconstitution. Hospital pharmacies with high patient throughput are adopting pre-mixed solutions to compress preparation time and reduce compounding error exposure. This technology is bifurcating procurement criteria, with efficiency-focused centers accepting per-dose premiums while cost-constrained institutions retain powder formats.
EMA GMP Annex 1 revisions for sterile medicinal products are mandating enhanced environmental monitoring and contamination control strategies across European manufacturing sites. Facility operators must implement real-time viable particle detection and revised cleanroom classification protocols. German and Swiss contract manufacturers are responding with dedicated oncology sterile suites segregated from general injectable production.
Buyer consolidation among US hospital systems and oncology clinic networks is compressing supplier negotiation cycles and unbundling traditional distribution relationships. Integrated delivery networks are centralizing pharmacy procurement decisions and demanding format standardization across their infusion footprints. This concentration is most visible in Texas and Florida metropolitan clusters where specialty pharmacy carve-outs from major health systems have accelerated.
Global Bendamustine Injection Market Segmentation
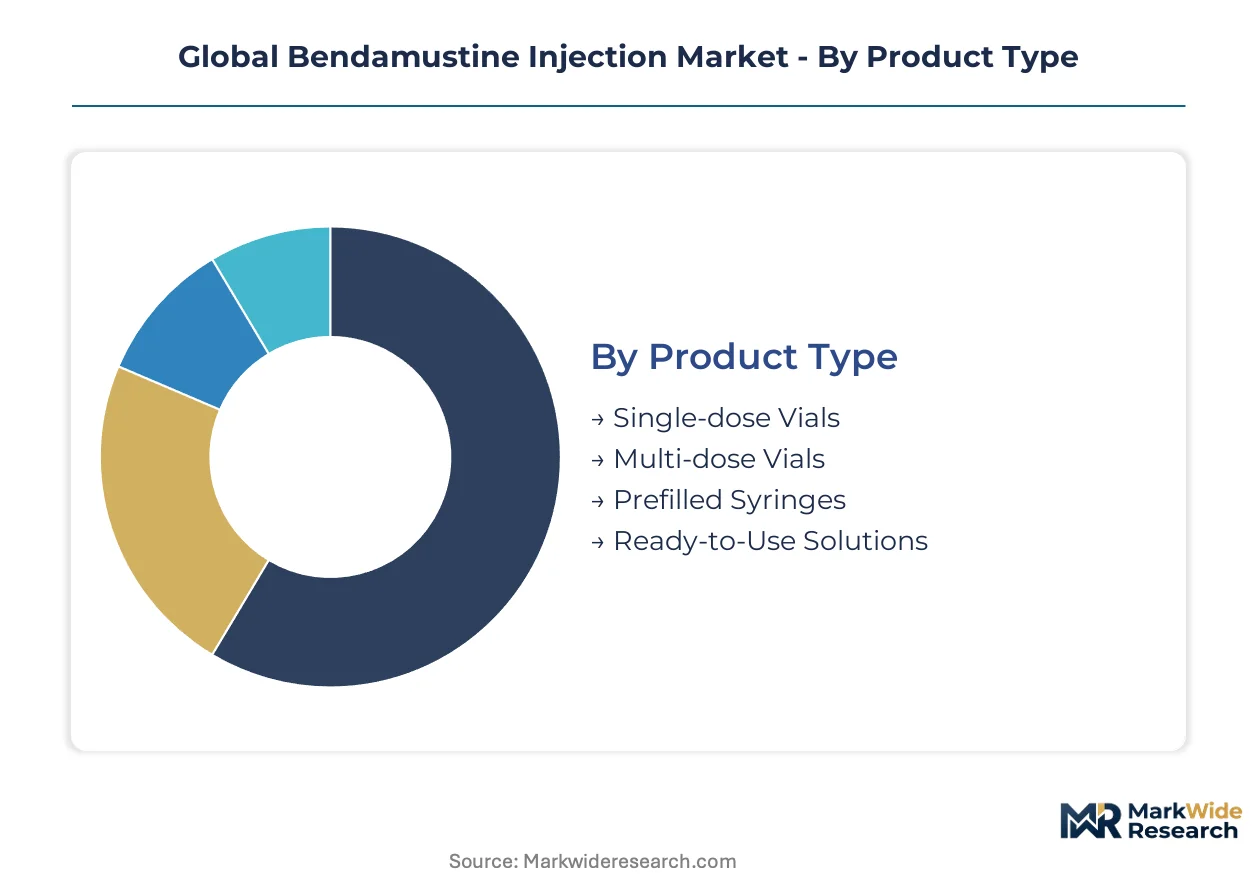
Segmentation in bendamustine injection supply reveals how formulation formats, therapy applications, and procurement channels intersect to create distinct competitive battlegrounds. Procurement patterns diverge sharply between hospital systems prioritizing waste reduction and outpatient networks seeking workflow efficiency.
Product Type:
Hospital pharmacies and specialty infusion centers channel demand toward formats matching their compounding capabilities and patient throughput requirements.
- Ready-to-Use Solutions:Pre-mixed liquid concentrates eliminate reconstitution steps and reduce preparation error exposure in high-volume oncology clinics. United States hospital systems with centralized pharmacy operations are adopting these formats despite per-dose premiums, driven by Joint Commission safety protocols and nursing labor cost containment.
- Single-dose Vials:Lyophilized powder or liquid in unit-dose packaging aligns with waste reduction mandates and controlled substance tracking in German and Japanese hospital pharmacies. These formats command premium positioning where regulatory frameworks penalize multi-dose vial sharing or partial-dose wastage.
- Multi-dose Vials:Cost-efficient bulk packaging serves European oncology clinics with established aseptic compounding infrastructure and stable patient cohorts.
- Prefilled Syringes:Ambulatory infusion centers and specialty pharmacy channels in the United States are piloting these formats for outpatient bendamustine administration.
By volume, multi-dose vials lead. By growth pace, ready-to-use solutions are climbing the fastest.
Therapy Area:
Clinical protocol expansion and reimbursement positioning determine which indications absorb manufacturing capacity and drive format innovation.
- Chronic Lymphocytic Leukemia:Bendamustine-based regimens have migrated into earlier treatment lines across United States, German, and Japanese treatment guidelines. This indication consumes the largest share of manufacturing output and shapes FDA and EMA bioequivalence study requirements for generic entrants.
- Non-Hodgkin's Lymphoma:Follicular lymphoma protocols in European oncology networks sustain steady demand for combination therapy vial formats. EMA GMP Annex 1 compliance investments concentrate here due to established reimbursement pathways and mature clinical evidence bases.
- Mantle Cell Lymphoma:Niche indication with concentrated demand in academic medical centers running investigator-initiated trials.
- Multiple Myeloma:Experimental protocols and combination studies at research institutes drive limited, high-specification demand for clinical-grade supply.
Chronic lymphocytic leukemia anchors volume absorption. Mantle cell lymphoma shows the steepest expansion trajectory as protocols broaden.
End User:
Customer type dictates packaging requirements, cold chain specifications, and regulatory documentation depth.
- Cancer Treatment Centers:Integrated hospital-based facilities in Texas and Florida metropolitan clusters centralize procurement for multi-site infusion networks. These buyers demand format standardization and closed-system transfer device compatibility.
- Oncology Clinics:Independent and hospital-affiliated outpatient settings in Germany and Japan prioritize ready-to-use solutions to minimize pharmacy infrastructure investment.
- Specialty Pharmacies:United States hub-and-spoke distribution models for oral oncology are extending into injectable fulfillment, requiring distinct labeling and patient counseling protocols.
- Research Institutes:Academic medical centers running phase II and III trials require investigator-sponsored IND documentation and batch-specific certificates of analysis.
Cancer treatment centers dominate volume procurement. Specialty pharmacies are gaining share fastest as outpatient administration expands.
Distribution Channel:
Channel structure determines pricing transparency, inventory risk allocation, and last-mile cold chain responsibility.
- Hospital Pharmacies:Direct contracting with manufacturers or through group purchasing organizations concentrates procurement power in United States integrated delivery networks. These buyers negotiate format exclusivity and demand 340B pricing compliance where applicable.
- Direct Sales:Manufacturer-to-institution relationships in Japan bypass wholesale markup through PMDA-authorized specialty distributors with oncology cold chain certification.
- Retail Pharmacies:Limited role given storage requirements and hazardous handling protocols; serves rare outpatient prescription scenarios in European markets.
- Online Pharmacies:Emerging channel for patient support program fulfillment and specialty pharmacy platform integration in United States markets with established digital health infrastructure.
Hospital pharmacies command the largest volume flow. Direct sales channels are expanding most quickly as manufacturers build institutional relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States cancer treatment centers consume bendamustine primarily in ready-to-use solution formats, while German and Japanese institutions retain lyophilized powder protocols that emphasize waste reduction and cold chain efficiency over pharmacy labor savings.
United States
Integrated delivery networks in Texas and Florida metropolitan clusters centralize procurement for multi-site infusion networks. FDA sterility guideline revisions compel manufacturers to validate closed-system transfer device compatibility. Hospital pharmacies in Houston and Dallas prioritize pre-mixed solutions to compress nursing preparation time.
Germany
Oncology clinics in Bavaria and North Rhine-Westphalia extend bendamustine-based regimens into earlier chronic lymphocytic leukemia treatment lines. EMA GMP Annex 1 revisions mandate enhanced environmental monitoring and contamination control strategies. Swiss and German contract manufacturers in Basel and Frankfurt operate dedicated oncology sterile suites segregated from general injectable production.
Japan
Academic medical centers in Tokyo and Osaka sustain concentrated demand for clinical-grade supply in mantle cell lymphoma investigator-initiated trials. PMDA streamlined review pathways for oncology generics accelerate market access for dossier-ready manufacturers. Specialty distributors with oncology cold chain certification bypass wholesale markup through direct manufacturer relationships.
United Kingdom
NHS England cancer treatment centers in London and the Midlands absorb substantial volumes of multi-dose vial formats aligned with cost-containment mandates. MHRA alignment with EMA GMP Annex 1 standards elevates compliance requirements for sterile injectable imports. Hospital pharmacies in Manchester and Birmingham balance format standardization pressures against legacy lyophilized powder inventories.
India
CDSCO-regulated manufacturing facilities in Maharashtra and Gujarat supply active pharmaceutical ingredient for global bendamustine hydrochloride production. Domestic oncology clinics in Delhi and Mumbai prioritize cost-efficient multi-dose vial procurement for established non-Hodgkin's lymphoma protocols. Contract research organizations in Hyderabad support bioequivalence studies for generic entrants approaching patent cliffs.
Global Bendamustine Injection Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in bendamustine injection supply. Generic injectable infrastructure and oncology formulation expertise separate the upper tier from mid-scale competitors. Three archetypes dominate: established pharmaceutical conglomerates with sterile manufacturing networks, oncology-focused specialists with ready-to-use capabilities, and API-integrated Indian manufacturers with cost-competitive positioning. Capacity expansion and regulatory dossier harmonization represent the dominant competitive moves across both tiers.
Among North American-based manufacturers, Teva and Eagle Pharmaceuticals exemplify contrasting strategic positions within the oncology injectable space. Teva leverages established generic infrastructure across hospital networks, while Eagle Pharmaceuticals occupies a specialist position emphasizing ready-to-use solution formats. Indian manufacturers including Natco Pharma and Emcure anchor the API-integrated tier with cost-competitive supply positions. Mylan sustains European market presence through multi-dose vial supply aligned with clinic infrastructure preferences.
| Leading Market Players |
|---|
| MundiPharma |
| Natco Pharma |
| Teva |
| Miracalus Pharma |
| Emcure |
| Eisai |
| Mylan |
| Apotex Corp |
| Eagle Pharmaceuticals |
| Others |
Supply & Pricing Matrix
FDA sterility guideline revisions and EMA GMP Annex 1 standards gate both supplier qualification and price differentiation simultaneously, compressing manufacturing capacity toward validated oncology injectable specialists while segmenting procurement tiers by compliance investment depth. Hospital systems with centralized pharmacy operations accept per-dose premiums for ready-to-use solutions, while cost-constrained European clinics retain lyophilized powder formats anchored in established cold chain infrastructure.
Pricing Analysis
Long-term offtake agreements dominate procurement between integrated delivery networks and established manufacturers, while spot purchasing persists for clinical-grade supply in academic research settings. Price differentiation rests on format convenience and regulatory dossier completeness, with ready-to-use solutions commanding premiums over multi-dose vials. Cost compression in lyophilized powder tiers intensifies as Indian API-integrated manufacturers expand European market presence. Oncology clinics in Germany and Japan exhibit highest price sensitivity due to reimbursement pressure, while United States hospital systems prioritize nursing labor cost containment over unit price.
Supply Chain Analysis
Just-in-time inventory strategies predominate among United States hospital pharmacies with high patient throughput, whereas Japanese specialty distributors maintain strategic stockpiles to buffer PMDA inspection cycles. Active pharmaceutical ingredient manufacturing concentrates in India and China, with finished dose formulation anchored in Germany, Switzerland, and the United States. Bendamustine hydrochloride synthesis draws from specialized chemical intermediates and controlled-substance precursors subject to international scheduling conventions. Single-source vulnerability in API supply creates structural risk exposure. Distribution runs through manufacturer-direct relationships in Japan and group purchasing organization channels in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as format bifurcation between ready-to-use solutions and traditional lyophilized powders creates distinct competitive niches. Outpatient infusion center expansion and specialty pharmacy channel development generate white-space demand underserved by incumbent hospital-focused supply structures.
For Market Incumbents: Fortify regulatory dossier harmonization across FDA, EMA, and PMDA jurisdictions to defend against emerging Indian API-integrated competitors with streamlined oncology generic pathways. Expand dedicated sterile suite capacity in Basel and Frankfurt corridors to capture EMA GMP Annex 1 compliance premiums. Prioritize closed-system transfer device compatibility as a format differentiation lever in United States integrated delivery network procurement. For New Entrants and Emerging Players: Japan PMDA streamlined review for oncology generics offers accelerated market access for dossier-ready manufacturers with existing sterile injectable infrastructure. Prefilled syringe formats for ambulatory infusion centers in Texas and Florida metropolitan clusters represent the most penetrable white-space segment. Pursue hub-and-spoke specialty pharmacy partnerships as the primary go-to-market angle, bypassing traditional hospital pharmacy gatekeeper consolidation. For Investors and Strategic Acquirers: EMA GMP Annex 1 implementation reshapes the acquisition landscape by elevating compliance-based competitive moats and stranding legacy facility assets. Five-to-ten year viability favors mid-scale oncology injectable specialists with ready-to-use capabilities and established institutional relationships over pure API players facing formulation margin compression. Target acquisition archetype: German or Swiss contract manufacturers with dedicated oncology sterile suites and existing EMA regulatory dossiers. Monitor FDA sterility guideline enforcement intensity as the primary inflection signal for capacity valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Harmonization | EMA, FDA, and PMDA alignment reduces submission preparation cycles for generic oncology entrants. |
| Ready-to-Use Manufacturing Scale-Up | Liquid concentrate capacity expansion captures Joint Commission safety protocol premiums in United States hospital systems. |
| Closed-System Transfer Device Integration | Compatibility with hazardous drug containment systems differentiates format positioning in 340B-eligible procurement. |
| Specialty Pharmacy Channel Partnership | Hub-and-spoke distribution models extend injectable fulfillment into outpatient infusion center networks. |
| API Backward Integration | Captive bendamustine hydrochloride supply insulates against single-source concentration risk in Indian and Chinese synthesis facilities. |
Research Methodology
Initial hypotheses were tested against primary input from oncology pharmacy directors, sterile manufacturing quality assurance leads, hospital procurement managers, and regulatory affairs specialists at generic injectable firms, then refined through secondary validation. FDA 483 inspection observations, EMA GMP inspection reports, ClinicalTrials.gov protocol registries, and United States 340B program participation databases supplied corroborating evidence. Bottom-up demand modeling across format types and therapy indications triangulated against top-down manufacturer capacity assessments.
Variance decomposition across product format, therapy area, end-user type, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented volume absorption curves and price trajectory assumptions. Chronic lymphocytic leukemia protocol expansion rates, sterile manufacturing compliance cost escalations, and specialty pharmacy channel penetration curves served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable regulatory enforcement intensity and continued reimbursement support for bendamustine-based regimens; material deviation in FDA sterility guideline implementation or EMA GMP Annex 1 inspection frequency would warrant model refresh. Practitioners should keep alternative scenarios live as outpatient infusion center expansion rates and biosimilar competitive entry timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
2-Valent HPV Vaccine (2vHPV) Market
Pharmaceuticals
Latin America Meglitinide Market
Pharmaceuticals
Global Systemic Lupus Erythematosus Drugs Market
Pharmaceuticals
Over the Counter (OTC) Drugs Market
Pharmaceuticals
Clindamycin Palmitate Hcl Market
Pharmaceuticals
Global Bone Morphogenetic Protein Market
Pharmaceuticals
North America Travel Vaccines Market
Pharmaceuticals
Korea Pharmaceutical Market
Pharmaceuticals
Periodontal Therapeutics Market
Pharmaceuticals
Asia-Pacific Adenomyosis Drugs Market
Pharmaceuticals
Hyoscine Market
Pharmaceuticals
Global Central Nervous System (CNS) Stimulant Drugs Market
Pharmaceuticals
Mitotane Market
Pharmaceuticals
Meglitinide Market
Pharmaceuticals
Inotropic Agent Market
Pharmaceuticals
Europe Oral Anti-Diabetic Drug Market