
 Global Testosterone Replacement Therapy Market | 2026-2036
Global Testosterone Replacement Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Testosterone Replacement Therapy Market Foresight
Specialty clinics are rotating toward long-acting depot formulations as the preferred first-line intervention for hypogonadism management. AbbVie leverages its established transdermal portfolio to sustain brand loyalty among endocrinology practices, while Eli Lilly and Company anchors its position through sustained-release injection platforms. Bayer competes on manufacturing scale for intramuscular products across European hormone therapy centers.
Testosterone replacement therapy encompasses exogenous administration of synthetic or bioidentical testosterone to restore physiological androgen levels in patients with clinically confirmed deficiency states, utilizing formulations ranging from cypionate and enanthate esters to hydroalcoholic gel vehicles designed for controlled percutaneous absorption. The therapy serves to reverse symptomatic hypogonadism, preserve bone mineral density, and maintain hematopoietic and metabolic homeostasis in affected patient populations. Gels and topical delivery systems dominate current prescription volumes due to patient convenience and dose titration flexibility, while subcutaneous pellet implants represent the fastest-expanding segment as hormone therapy centers seek reduced administration burden for chronic patients. Oral capsules command premium positioning where hepatic first-pass metabolism concerns have been addressed through lymphatic absorption technologies.
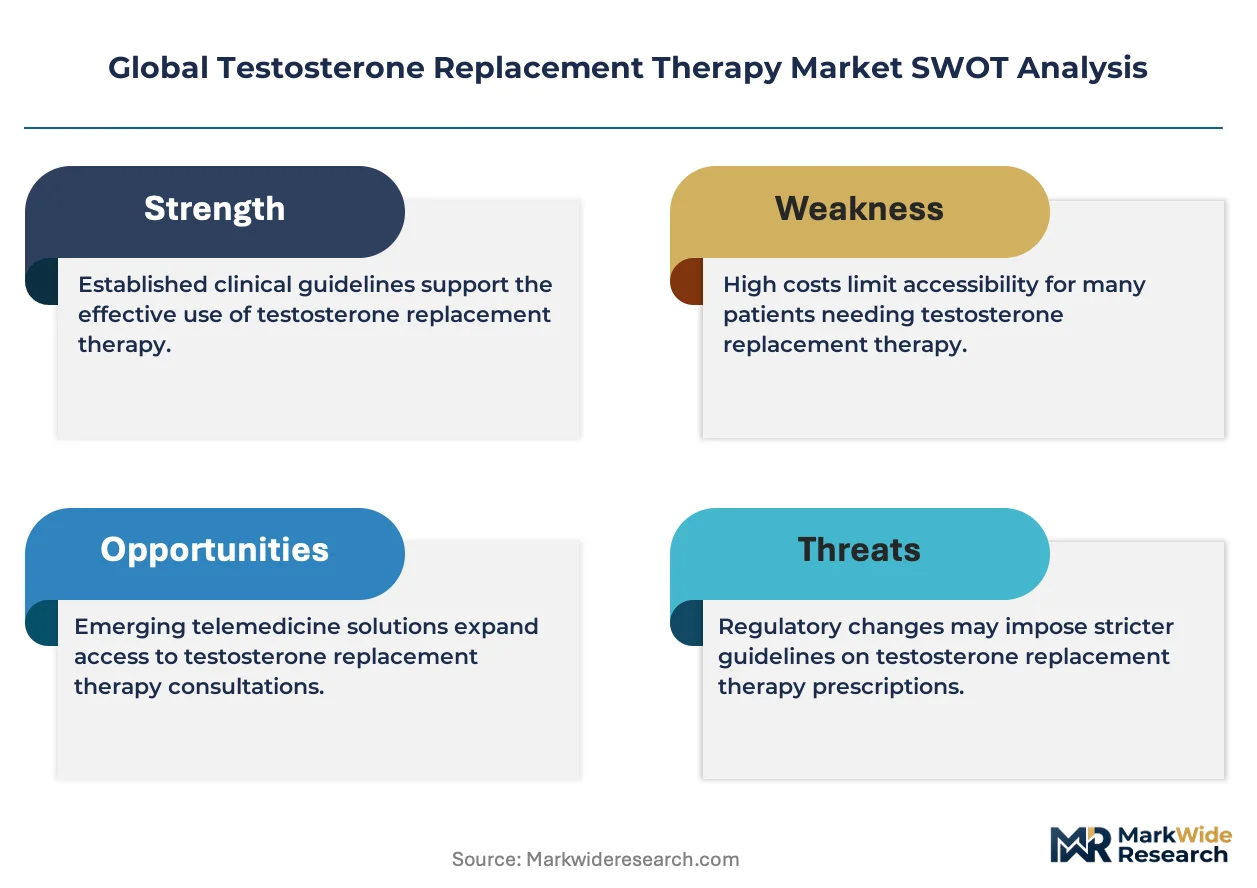
FDA bioequivalence requirements for abbreviated new drug applications constrain generic testosterone entry, while EMA pharmacovigilance frameworks mandate ongoing cardiovascular outcome monitoring across the European Union. The EU AI Act introduces algorithmic scrutiny for diagnostic protocols that determine treatment eligibility in automated clinical workflows. Stakeholders must monitor regulatory divergence between FDA risk evaluation strategies and EMA's evolving endocrine disruptor classification for synthetic steroid compounds.
Market Dynamics
Long-acting depot formulations are compressing administration frequency from weekly injections to quarterly intervals, fundamentally altering patient adherence economics and clinic capacity planning across hormone therapy networks.
Growth Catalysts
- Aging Male Demographics:Expanding populations over 50 years in the United States, Germany, and Japan drive diagnostic screening volumes through urology and endocrinology practices.
- FDA Bioequivalence Pathways:Evolving abbreviated new drug application standards for generic testosterone formulations create predictable approval timelines for follow-on products.
- Subcutaneous Pellet Technology:Implantable testosterone delivery systems reduce nursing burden in specialty clinics and improve patient compliance metrics.
Market Restraints
- API Supply Concentration:Testosterone cypionate and enanthate raw material production clusters in Chinese and Indian chemical manufacturing zones, exposing formulation networks to single-source risk.
- Cardiovascular Surveillance Mandates:EMA pharmacovigilance frameworks require ongoing outcome monitoring that extends clinical trial timelines and post-market study costs.
- Topical Formulation Saturation:Hydroalcoholic gel vehicles face absorption variability concerns and transference risk that limit pediatric household eligibility.
Strategic Opportunities
- Lymphatic Absorption Oral Capsules:Bypass-hepatic first-pass technologies open premium positioning for patients contraindicated for injection or topical routes.
- Automated Diagnostic Protocols:The EU AI Act creates compliant pathways for algorithmic eligibility determination in integrated health systems.
- Home Administration Training:Subcutaneous autoinjector platforms enable self-management programs that decompress specialty clinic capacity in the United States.
Industry Challenges
- Endocrine Disruptor Reclassification:EMA's evolving synthetic steroid compound taxonomy threatens formulation reregistration timelines and environmental disposal protocols.
- Multi-Jurisdiction Compliance Architecture:Divergent FDA risk evaluation strategies versus EMA cardiovascular monitoring requirements force parallel quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Testosterone Replacement Therapy Market |
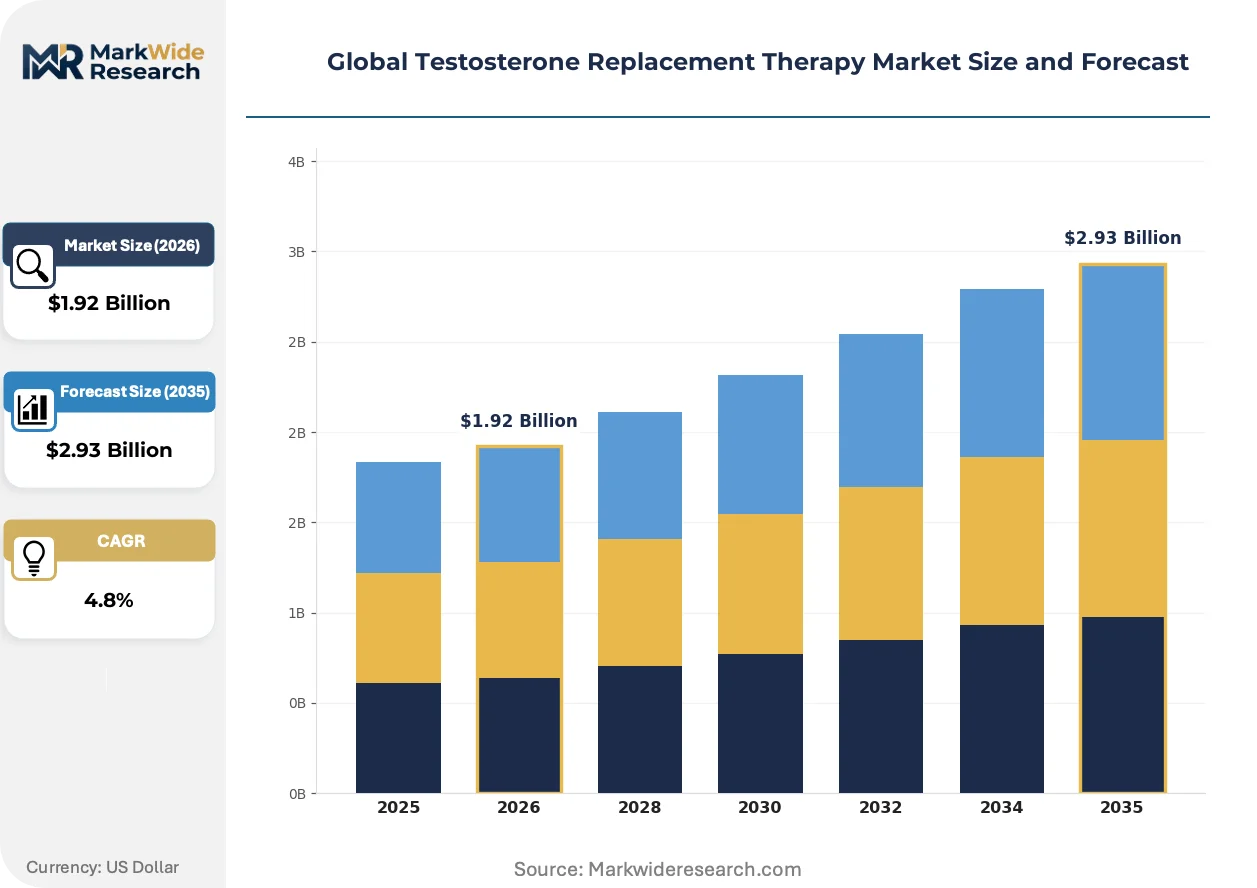
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $2.93 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injections, Gels, Patches, Pellets, Oral Capsules Therapy Area: Hypogonadism, Andropause, Delayed Puberty, Gender Dysphoria End User: Specialty Clinics, Hormone Therapy Centers, Urology Clinics, Geriatric Care Facilities Delivery Mode: Topical, Intramuscular, Subcutaneous, Oral, Transdermal |
| Companies Covered | Eli Lilly and Company, Teva Pharmaceutical Industries, AbbVie, Ferring Pharmaceuticals, Besins Healthcare, Endo International, Bayer, Viatris, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Testosterone Replacement Therapy Market Shifts & Advancements
Formulation chemistry and diagnostic automation are converging to compress treatment initiation timelines while expanding eligible patient pools beyond traditional hypogonadism definitions.
Subcutaneous testosterone pellet implants are decomposing the historical dominance of intramuscular injection protocols in chronic patient management. Hormone therapy centers in the United States and Germany are adopting quarterly implant cycles to reduce nursing labor allocation and minimize peak-trough serum fluctuations. This shift is compressing reimbursement structures around administration frequency rather than drug cost alone.
The EU AI Act is introducing mandatory algorithmic transparency requirements for diagnostic protocols that determine testosterone deficiency eligibility in automated clinical workflows. European hormone therapy networks must now document decision-tree logic for laboratory threshold interpretation and symptom scoring algorithms. Germany and France are experiencing the earliest compliance deadlines, with specialty clinics restructuring electronic health record integrations to meet explainability standards.
Direct-to-patient pharmacy fulfillment is displacing traditional clinic-dispensed testosterone products in the United States as telemedicine protocols mature. Patients now receive autoinjector training through virtual consultation platforms, with home delivery replacing in-person pharmacy visits. This channel rotation is most pronounced in Texas and Florida, where independent urology practices have partnered with compounding pharmacies for personalized dosing regimens.
Global Testosterone Replacement Therapy Market Segmentation
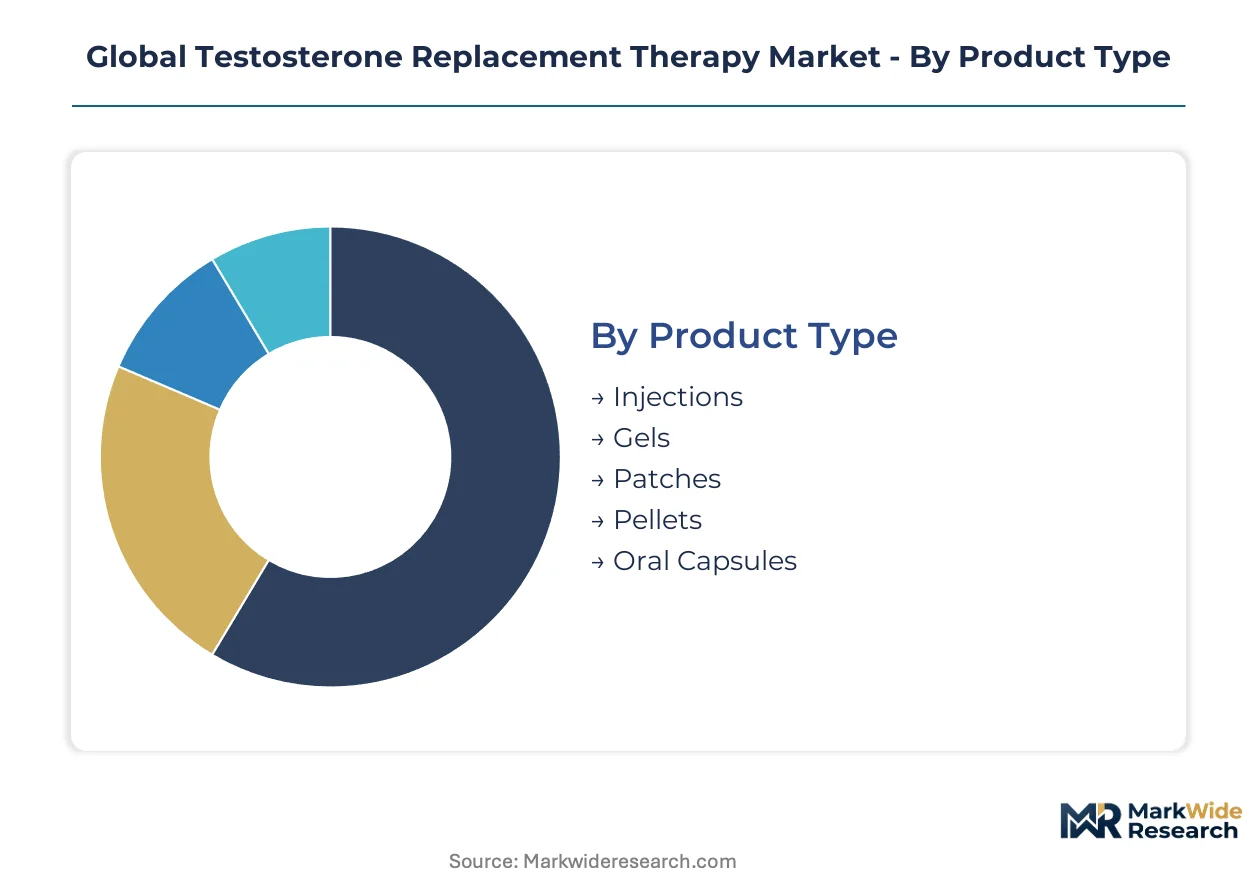
Testosterone replacement therapy markets fragment across formulation chemistry, clinical indication, and care setting. Each segment carries distinct reimbursement profiles, regulatory pathways, and patient adherence economics that reshape competitive positioning.
Product Type:
Domestic formulation dominates injectable and gel production in the United States and Germany, while pellet and oral capsule manufacturing clusters in specialized European contract development facilities serving export markets.
- Injections:Cypionate and enanthate esters in oil-based vehicles enable precise dose titration through intramuscular or subcutaneous routes. Demand concentrates in United States urology networks where weekly self-administration protocols reduce clinic visit burden for chronic patients.
- Gels:Hydroalcoholic vehicles with 1-1.62% testosterone concentration deliver controlled percutaneous absorption for dose flexibility. German hormone therapy centers favor these formulations for geriatric populations requiring gradual titration to minimize erythrocytosis risk.
- Patches:Reservoir or matrix designs provide steady-state delivery but face skin irritation limitations that constrain chronic use.
- Pellets:Crystalline testosterone implants enable 3-6 month dosing intervals through subcutaneous insertion.
- Oral Capsules:Lymphatic absorption technologies bypass hepatic first-pass metabolism for patients with injection or topical contraindications.
Injections command the established base. The steepest expansion runs through pellets.
Therapy Area:
Cost tier stratification separates acute intervention protocols from chronic maintenance programs, with diagnostic complexity and monitoring intensity determining reimbursement levels across indication categories.
- Hypogonadism:Primary and secondary testicular failure states with confirmed morning testosterone below 300 ng/dL drive the majority of prescription volumes. United States endocrinology practices prioritize this segment for long-acting depot conversion to improve adherence metrics.
- Andropause:Age-related testosterone decline with symptomatic presentation attracts controversy over diagnostic thresholds. Japanese geriatric networks apply conservative laboratory cutoffs that limit eligible populations relative to Western protocols.
- Delayed Puberty:Constitutional delay and hypogonadotropic conditions require pediatric endocrinology oversight with growth monitoring.
- Gender Dysphoria:Masculinizing hormone therapy for transgender male and non-binary patients follows distinct dosing protocols with mental health clearance requirements.
Hypogonadism absorbs the dominant share of formulation volumes. Gender dysphoria applications are climbing the fastest as access protocols standardize.
End User:
Volume concentration varies by patient acuity, with high-complexity cases gravitating toward integrated hormone therapy centers while stable maintenance patients distribute across community urology practices.
- Specialty Clinics:Multidisciplinary endocrinology practices manage complex comorbidities including metabolic syndrome and osteoporosis. German university-affiliated centers lead adoption of automated diagnostic protocols under EU AI Act compliance frameworks.
- Hormone Therapy Centers:Dedicated facilities optimize workflow around testosterone pellet insertion and monitoring. United States standalone centers in Texas and Florida have pioneered direct-to-patient pharmacy fulfillment models.
- Urology Clinics:Male-focused practices dominate initial diagnostic screening and first-line gel prescriptions.
- Geriatric Care Facilities:Long-term care settings manage testosterone therapy alongside polypharmacy regimens with fall-risk considerations.
Urology clinics anchor first-line diagnosis. Hormone therapy centers are gaining share fastest through procedure-based revenue models.
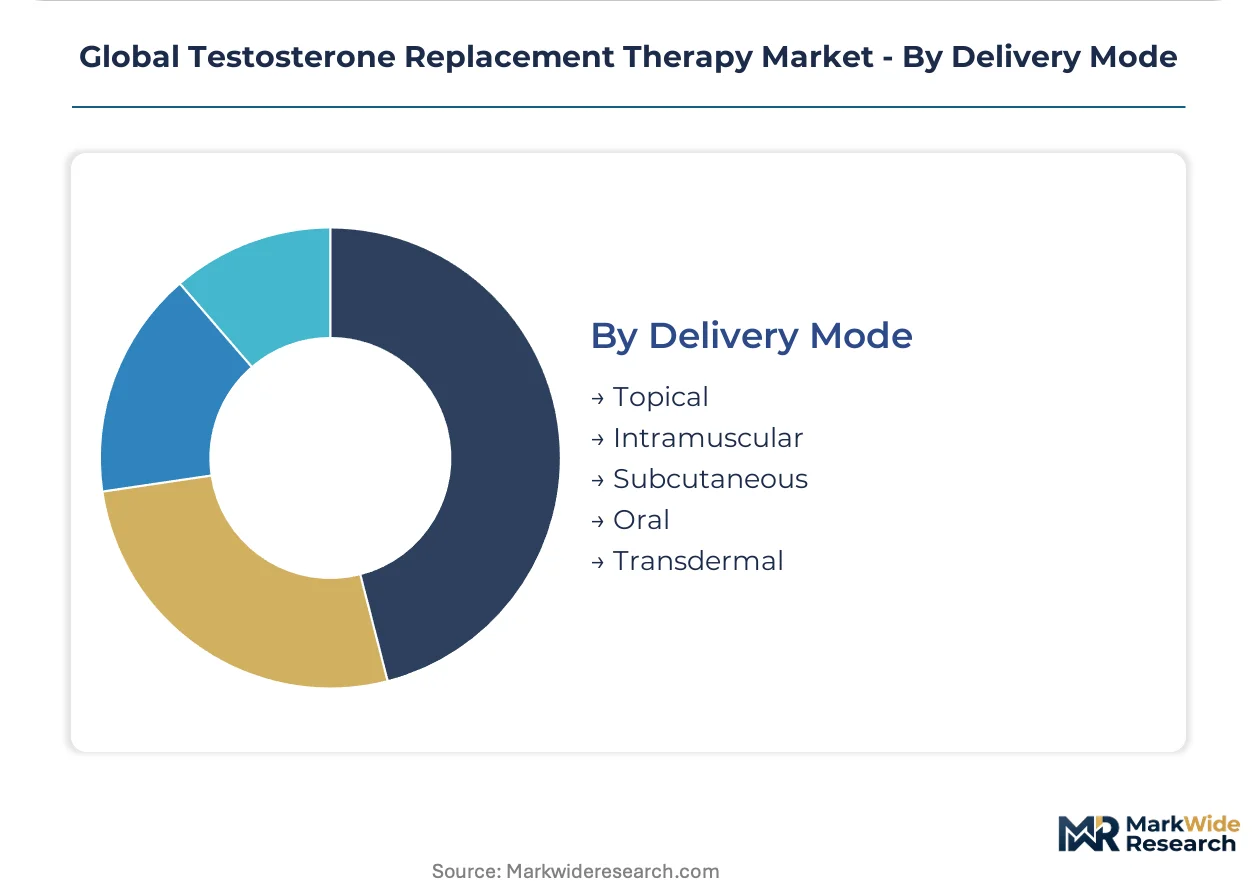
Delivery Mode:
Supply concentration in active pharmaceutical ingredient production shapes formulation availability, with Chinese and Indian chemical manufacturers dominating testosterone ester supply for injectable and pellet segments.
- Topical:Gels, solutions, and creams applied to shoulders or upper arms with transference precautions. United States pharmacy benefit managers favor these for formulary placement due to generic competition and patient self-management capacity.
- Intramuscular:Deep gluteal or deltoid injection of oil-based esters historically dominated chronic therapy. German clinics are rotating toward subcutaneous alternatives to reduce nursing labor and patient discomfort.
- Subcutaneous:Shallow abdominal or thigh injection of shorter-needle formulations and pellet implants. Japanese regulatory pathways for autoinjector devices are accelerating home administration adoption.
- Oral:Lymphatic-absorption capsules and buccal tablets bypass hepatic metabolism through novel formulation chemistry.
- Transdermal:Patch and gel systems with distinct pharmacokinetic profiles for steady-state maintenance.
Topical delivery holds the volume base. Subcutaneous routes are expanding most quickly through pellet technology and autoinjector platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian and Chinese active pharmaceutical ingredient manufacturers supply testosterone esters to formulation networks in the United States, Germany, and Japan, creating concentrated trade corridors that shape regional market dynamics.
United States
Texas and Florida hormone therapy centers pioneer direct-to-patient pharmacy fulfillment models through telemedicine partnerships. FDA abbreviated new drug application pathways for generic testosterone formulations create predictable approval timelines. Independent urology practices in these states now source personalized dosing regimens from compounding pharmacies.
Germany
German university-affiliated endocrinology centers lead EU AI Act compliance for automated diagnostic protocols in testosterone deficiency screening. EMA pharmacovigilance frameworks mandate ongoing cardiovascular outcome monitoring that extends post-market study timelines. Bavarian hormone therapy networks restructure electronic health record integrations to meet algorithmic explainability standards.
Japan
Japanese geriatric networks apply conservative laboratory cutoffs for age-related testosterone decline that limit eligible populations relative to Western protocols. PMDA regulatory pathways for subcutaneous autoinjector devices accelerate home administration adoption. Tokyo-based endocrinology practices prioritize sustained-release platforms to reduce clinic visit frequency.
India
Indian chemical manufacturers concentrate production of testosterone cypionate and enanthate raw materials for export to formulation facilities. CDSCO oversight of active pharmaceutical ingredient quality standards shapes supply reliability for international buyers. Mumbai and Hyderabad manufacturing zones serve as primary export hubs for testosterone ester supply.
United Kingdom
London and Southeast England endocrinology practices balance NHS reimbursement constraints with patient demand for long-acting depot formulations. MHRA alignment with EMA endocrine disruptor classification frameworks threatens formulation reregistration timelines. Private hormone therapy clinics in the capital expand capacity for subcutaneous pellet insertion procedures.
Global Testosterone Replacement Therapy Market Competitive Landscape
Listed leaders compete with private specialists across formulation chemistry and delivery platform development. The vendor base fragments across transdermal portfolios, injectable platforms, and implantable technologies. Three archetypes dominate: established pharmaceutical conglomerates with diversified hormone portfolios, mid-cap specialists focused on depot formulation innovation, and generic manufacturers exploiting FDA bioequivalence pathways. Capacity expansion in pellet manufacturing and strategic partnerships for autoinjector distribution represent the dominant competitive moves.
Among diversified pharmaceutical conglomerates, Eli Lilly and Company and AbbVie occupy positions anchored in sustained-release and transdermal platforms respectively. Bayer exemplifies the manufacturing-scale archetype for intramuscular products across European hormone therapy centers. These three entities represent distinct strategic postures: Lilly through injection platform specialization, AbbVie via transdermal brand loyalty, and Bayer leveraging production volume for cost-positioned supply.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Teva Pharmaceutical Industries |
| AbbVie |
| Ferring Pharmaceuticals |
| Besins Healthcare |
| Endo International |
| Bayer |
| Viatris |
| Pfizer |
| Others |
Supply & Pricing Matrix
Pellet-to-gel substitution in chronic patient management is redrawing procurement geography while compressing reimbursement economics across United States hormone therapy networks. This formulation rotation concentrates manufacturing demand in European contract development facilities for crystalline testosterone implants, simultaneously elevating price premiums for quarterly administration intervals against weekly injection benchmarks.
Pricing Analysis
Generational pricing gaps separate established intramuscular injection platforms from emerging subcutaneous autoinjector systems and next-generation lymphatic-absorption oral capsules. Three-tier pricing structure across premium, standard, and economy levels stratifies by administration convenience and monitoring intensity, with FDA bioequivalence-certified generics anchoring the economy tier. Pricing pressure stems from compounding pharmacy competition in Texas and Florida direct-to-patient channels. Urology practices exhibit highest price sensitivity, while university-affiliated endocrinology centers prioritize clinical outcome metrics over acquisition cost.
Supply Chain Analysis
Strait of Hormuz transit vulnerability exposes testosterone cypionate and enanthate supply chains to geopolitical disruption, though actual API movement flows through maritime corridors serving Mumbai and Hyderabad manufacturing zones. Chinese and Indian chemical producers supply raw testosterone esters to formulation facilities in the United States, Germany, and Japan. Single-source concentration in Hubei and Gujarat chemical parks creates regulatory audit cascade risks. Distribution runs through specialized cold-chain logistics serving hormone therapy centers and hospital pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across delivery mode preferences and diagnostic automation readiness is spawning addressable niches for differentiated positioning. Patient self-administration demand is splitting the market into clinic-dependent and home-managed cohorts with divergent service requirements.
For Market Incumbents: Consolidate formulation portfolios around long-acting depot technologies to preempt pellet substitution threats from mid-cap specialists. Deepen backward integration into testosterone ester API production to insulate margin structures from Indian and Chinese supply volatility. Secure FDA bioequivalence certification for abbreviated new drug application filings before generic entry accelerates. For New Entrants and Emerging Players: Home administration training and virtual consultation platforms represent underserved service layers where established pharmaceutical conglomerates maintain minimal presence. Target standalone hormone therapy centers in Texas and Florida seeking autoinjector platform partnerships to decompress nursing capacity. Pursue compounding pharmacy alliances for personalized dosing regimens as the primary go-to-market pathway. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors subcutaneous delivery specialists over transdermal incumbents. Five-to-ten year viability hinges on automated diagnostic protocol compliance under EU AI Act frameworks and cardiovascular outcome data generation. Watch EMA endocrine disruptor reclassification timelines as the critical inflection signal for synthetic steroid compound valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Pellet Manufacturing Scale-Up | Quarterly implant cycles reduce nursing labor allocation in United States hormone therapy centers. |
| Autoinjector Platform Development | Subcutaneous self-administration training decompresses specialty clinic capacity in Texas and Florida. |
| EU AI Act Compliance Investment | Algorithmic explainability standards reshape diagnostic protocol integrations in German university centers. |
| API Supply Diversification | Backward integration into testosterone ester production mitigates single-source concentration in Chinese chemical parks. |
| Direct-to-Patient Pharmacy Fulfillment | Telemedicine partnerships displace traditional clinic-dispensed products in independent urology practices. |
Research Methodology
Operator-level perspectives from endocrinology practice managers, hormone therapy center administrators, urology clinic procurement leads, and pharmaceutical regulatory affairs specialists anchored the qualitative base. These primary engagements combined with secondary validation through FDA abbreviated new drug application filings, EMA pharmacovigilance databases, ClinicalTrials.gov testosterone intervention records, and hospital formulary placement data. Bottom-up prescription volume modeling and top-down market sizing triangulated across formulation chemistry segments and regional regulatory clusters.
Sensitivity analysis tested forecast robustness against bioequivalence approval delays, cardiovascular outcome study readouts, and API supply disruption scenarios. The analytical framework segmented by product type, therapy area, end user, and delivery mode across the projection horizon, with administration route adoption curves and reimbursement structure evolution as primary demand drivers. CAGRs derived from patient population demographics, diagnostic screening expansion rates, and formulation switching elasticity parameters.
Underlying assumptions cover FDA bioequivalence pathway predictability and EMA cardiovascular monitoring continuity, with deviation risk concentrated in endocrine disruptor reclassification timing and Indian API manufacturing audit outcomes. Practitioners should keep alternative scenarios live as EU AI Act compliance deadlines and subcutaneous autoinjector regulatory pathways evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Antiretroviral (ARV) Agents Market
Pharmaceuticals
Atorvastatin Diepoxide Calcium Salt Market
Pharmaceuticals
Global Anorexiants Market
Pharmaceuticals
Metaxalone Market
Pharmaceuticals
Pancrelipase Market
Pharmaceuticals
Long-Acting Beta-Agonists Market
Pharmaceuticals
US Over the Counter Drugs Market
Pharmaceuticals
Middle-East and Africa Sodium-Dependent Glucose Co-Transporter 2 Inhibitors Market
Pharmaceuticals
Glioblastoma Treatment Drugs Market
Pharmaceuticals
Global Bendamustine Injection Market
Pharmaceuticals
Hepatitis - B Therapeutics Market
Pharmaceuticals
Preeclampsia Therapeutics Market
Pharmaceuticals
Latin America Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Global DNA Repair Drugs Market
Pharmaceuticals
Tetanus Market
Pharmaceuticals
Diuretic Drugs Market