
 Acne Therapeutics Market | 2026-2036
Acne Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Acne Therapeutics Market Outlook
Combination therapy kits that bundle retinoids with benzoyl peroxide is restructuring how prescribers and patients evaluate first-line regimens. Galderma leverages its integrated dermatology platform to sustain loyalty among specialist prescribers across North America and Europe. Sun Pharmaceutical Industries Ltd. anchors its position through aggressive generic penetration of oral antibiotic categories. AbbVie Inc. competes by extending its immunology-derived R&D pipeline into inflammatory acne pathways.
Acne therapeutics encompass pharmacological agents and physical interventions designed to modulate sebum production, bacterial colonization, inflammation, and keratinocyte turnover, typically formulated as gels, creams, oral tablets, or light-emitting devices with specified concentrations of active compounds. These products serve the clinical and consumer objective of reducing lesion count, preventing scarring, and improving dermatological quality of life across persistent and episodic disease presentations. Topicals and oral medications together constitute the dominant revenue architecture, though light therapy devices are capturing margin pools in cash-pay aesthetic channels where reimbursement friction remains minimal. Retinoid-based treatment methods retain the highest prescription loyalty among adults, while benzoyl peroxide formulations dominate over-the-counter pharmacy volumes through lower price points and established tolerability profiles.
The US FDA regulates prescription acne therapeutics through its Center for Drug Evaluation and Research, requiring substantial evidence of efficacy for new molecular entities and maintaining strict adverse-event reporting for isotretinoin via the iPLEDGE risk management program. The European Medicines Agency enforces additional pharmacovigilance obligations through the EudraVigilance system, particularly for systemic retinoids with teratogenic potential. China's National Medical Products Administration has accelerated local approval pathways for innovative topical formulations, reshaping where multinational sponsors prioritize clinical trial investment. Stakeholders must monitor how evolving reproductive-toxicity labeling standards across these jurisdictions will influence physician prescribing confidence and patient acceptance of oral therapies.
Market Dynamics
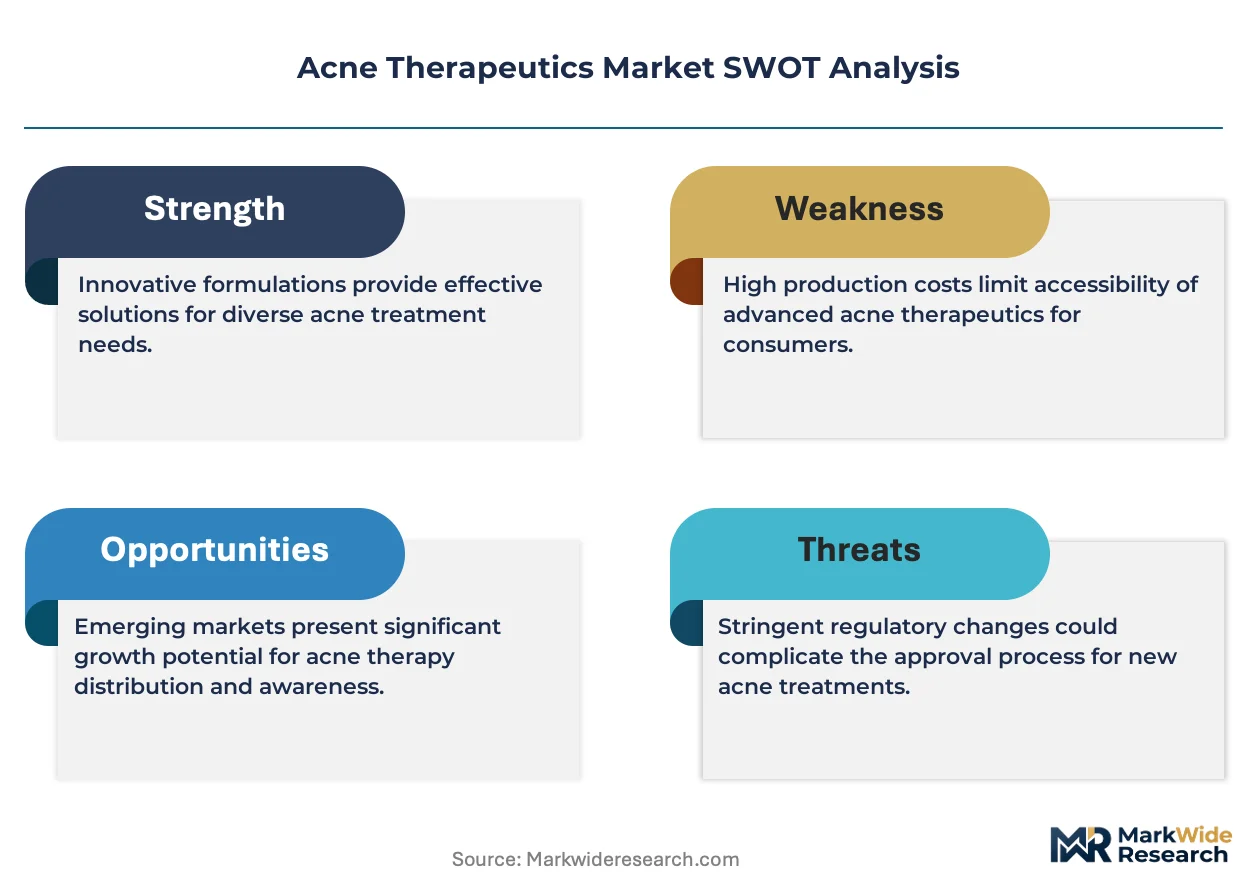
The US FDA's tightened labeling requirements for topical retinoids are forcing manufacturers to reformulate products and restructure clinical trial protocols, redirecting R&D investment toward tolerability optimization rather than novel mechanism discovery.
Growth Catalysts
- Telemedicine platform expansion:Direct-to-consumer digital health channels in the United States are channeling prescriptions toward both branded and generic therapeutics, expanding addressable patient populations beyond traditional dermatology clinic access.
- iPLEDGE program maturation:The FDA's risk management framework for isotretinoin has stabilized prescriber confidence in oral retinoid therapy, reducing liability friction that previously constrained systemic treatment adoption.
- Adult acne patient volume:Persistent adult acne presentations are driving repeat visits to dermatology clinics, the fastest-expanding end-use channel identified in patient flow data.
Market Restraints
- Teratogenic liability costs:Systemic retinoids carry reproductive toxicity risks that elevate pharmacovigilance spending and restrict prescribing to certified providers, compressing margins on oral therapies.
- API supply concentration:Active pharmaceutical ingredient production for benzoyl peroxide and clindamycin concentrates among a limited supplier base in India and China, exposing formulators to input volatility and quality inconsistency.
- Antibiotic resistance protocols:Stewardship guidelines from the WHO and national health agencies are shortening permissible oral antibiotic treatment durations, limiting revenue capture from traditional tetracycline-class therapies.
Strategic Opportunities
- Combination kit white space:Bundled retinoid-benzoyl peroxide regimens represent underdeveloped positioning between pure prescription and pure over-the-counter channels, offering margin expansion through adherence packaging.
- Light therapy device reimbursement:Cash-pay aesthetic channels for LED and laser devices face minimal reimbursement friction compared to pharmaceutical pathways, attracting capital toward physical intervention modalities.
- NMPA accelerated pathways:China's National Medical Products Administration has streamlined local approval timelines for innovative topical formulations, incentivizing sponsors to relocate clinical trial investment toward Asia-Pacific sites.
Industry Challenges
- Formulation stability expertise:Retinoid degradation chemistry requires specialized compounding knowledge that resides within a narrow talent pool, constraining speed-to-market for new topical entrants.
- EudraVigilance reporting burden:The European Medicines Agency's adverse event collection system imposes data infrastructure requirements that smaller sponsors struggle to resource without partnership structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acne Therapeutics Market |
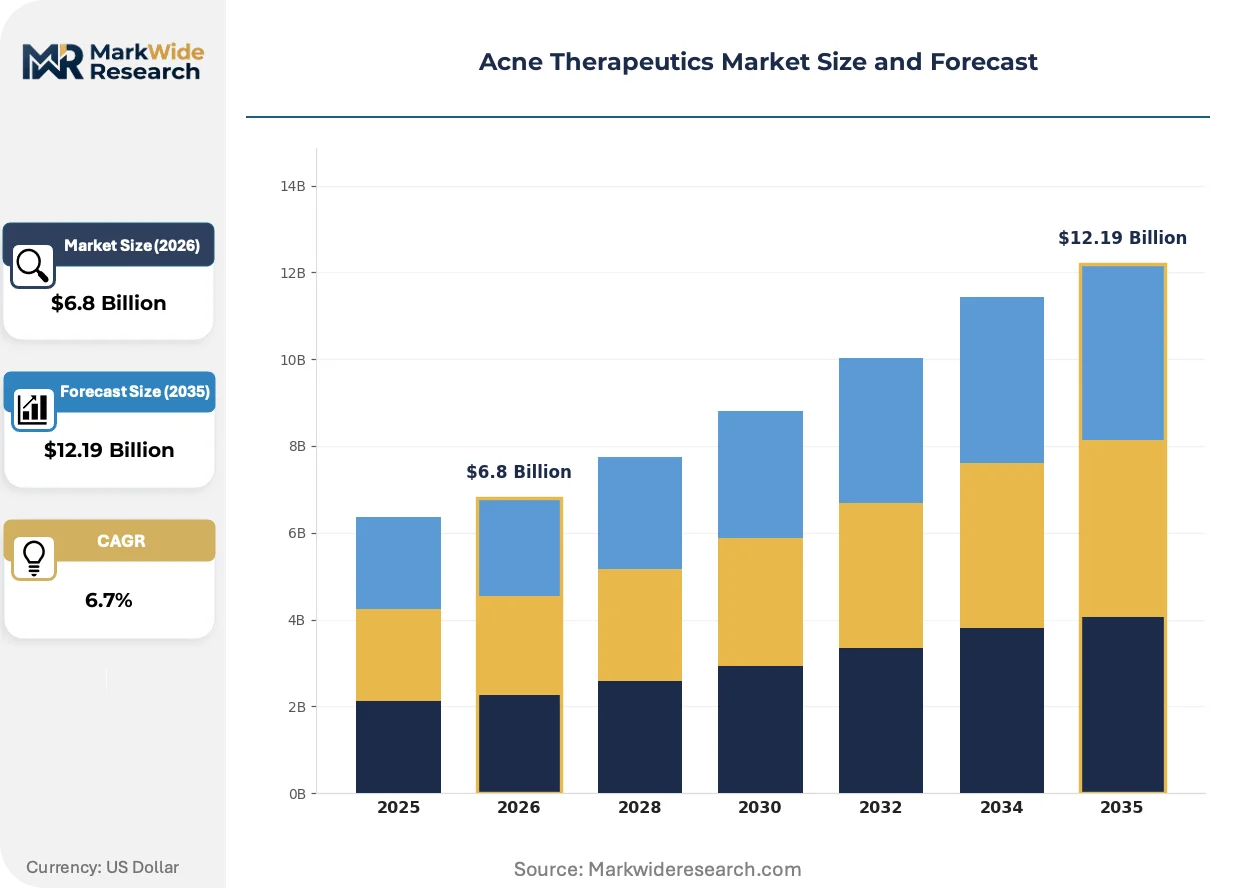
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topicals, Oral Medications, Light Therapy, Chemical Peels Treatment Method: Antibiotics, Retinoids, Benzoyl Peroxide, Salicylic Acid End User: Dermatology Clinics, Hospitals, Home Care, Pharmacies Age Group: Adolescents, Adults, Children, Seniors |
| Companies Covered | Johnson & Johnson, Galderma, Bausch Health Companies Inc., AbbVie Inc., GlaxoSmithKline plc, Sun Pharmaceutical Industries Ltd., Bayer AG, Teva Pharmaceutical Industries Ltd., Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acne Therapeutics Market Strategic Shifts
Reformulation science and digital distribution infrastructure are converging to reshape how prescribers and patients interact with acne therapy portfolios, compressing traditional channel hierarchies.
Microencapsulated retinoid delivery systems are integrating controlled-release polymers that buffer skin irritation while maintaining comedolytic efficacy. Dermatology clinics in the United States are adopting these formulations at accelerating rates for adult patients with sensitive skin phenotypes. This technology is integrating tolerability improvements that expand the addressable population beyond traditional retinoid candidates, compressing discontinuation rates that previously limited lifetime value per patient.
The EMA's evolving pharmacovigilance obligations through EudraVigilance are mandating real-world safety data collection for systemic retinoids with teratogenic potential. Sponsors must now maintain post-authorization surveillance infrastructure that adds fixed cost layers to European commercialization strategies. Oral isotretinoin manufacturers serving Germany, France, and Italy are responding by consolidating distribution through specialty pharmacy networks capable of pregnancy prevention program administration.
Subscription-based replenishment models are displacing episodic pharmacy purchasing for maintenance-phase topical therapies. Telemedicine platforms in the United States are capturing patient relationships through automated shipment programs that lock in brand loyalty after initial consultation. This behavioral shift concentrates most visibly among millennial and Generation X demographics managing persistent adult acne through continuous low-dose regimens rather than acute flare treatment.
Acne Therapeutics Market Segmentation
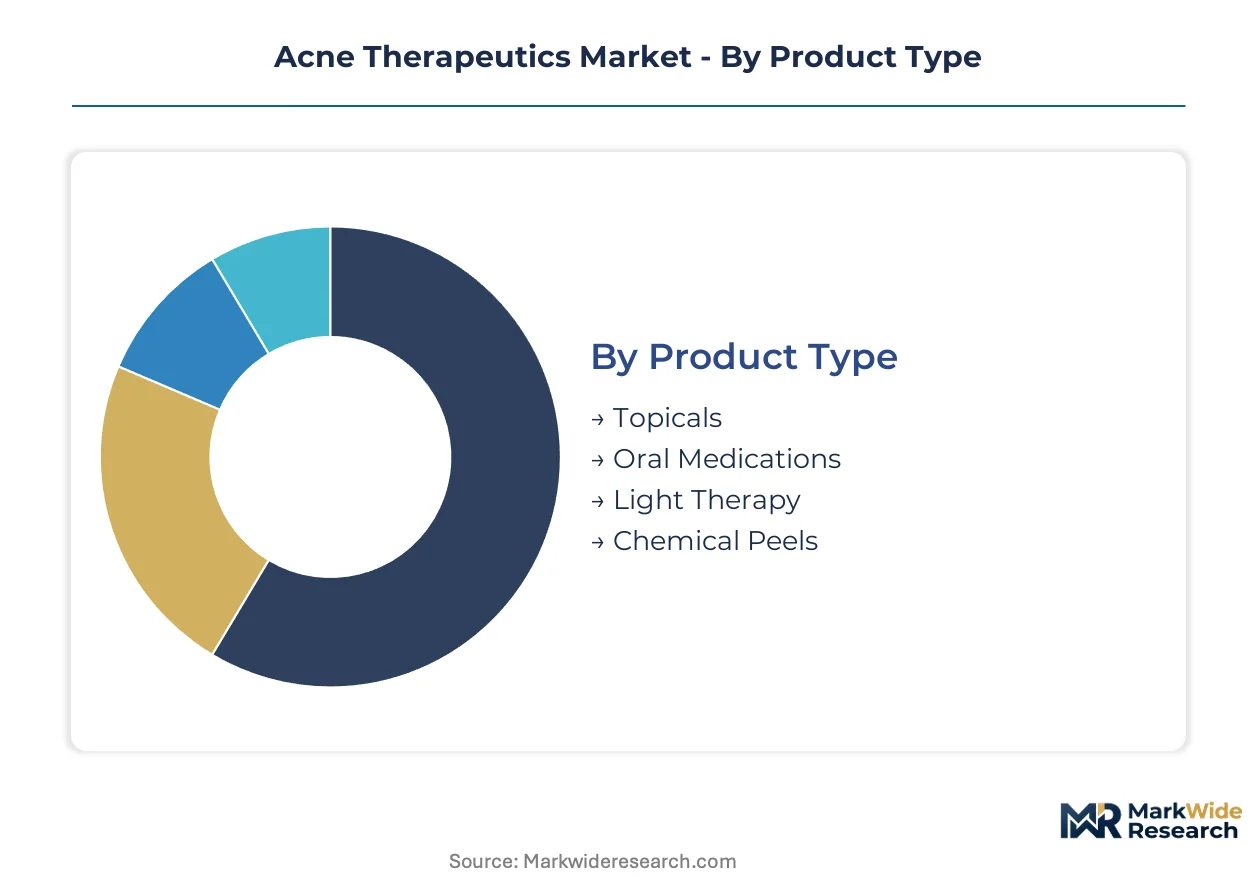
Segmentation in acne therapeutics reveals distinct channel economics and patient journey patterns. Prescribers, payers, and patients each weight product attributes differently across these dimensions, creating parallel market architectures that rarely overlap completely.
Product Type:
Patient tolerability thresholds and reimbursement access shape initial product selection more than efficacy differentials alone.
- Topicals:Formulated as gels, creams, lotions, and foams with specified active concentrations for localized skin delivery. Demand concentrates in the United States through telemedicine platforms channeling subscription-based replenishment for maintenance-phase regimens, driven by adult patients managing persistent presentations through continuous low-dose application.
- Oral Medications:Systemic therapies including antibiotics, hormonal agents, and retinoids administered in tablet or capsule form. Prescription volume clusters in dermatology clinics across Germany, France, and Italy where EMA-mandated pregnancy prevention programs require specialty pharmacy distribution infrastructure.
- Light Therapy:LED and laser devices emitting specified wavelengths to reduce bacterial colonization and inflammation. Cash-pay aesthetic channels in the United States capture margin pools with minimal reimbursement friction compared to pharmaceutical pathways.
- Chemical Peels:Acid-based exfoliation procedures administered in clinical settings or as supervised home kits.
Topicals lead on scale; light therapy leads on momentum.
Treatment Method:
Mechanism of action determines prescriber confidence, regulatory burden, and patient adherence patterns across markets.
- Retinoids:Vitamin A derivatives modulating keratinocyte turnover and sebum production through nuclear receptor activation. FDA tightened labeling requirements for topical formulations are forcing reformulation investments toward tolerability optimization, while oral isotretinoin prescribing stabilizes under the mature iPLEDGE risk management framework.
- Antibiotics:Tetracycline-class and macrolide agents targeting Cutibacterium acnes colonization. WHO stewardship guidelines and national protocols are shortening permissible treatment durations, compressing revenue capture from traditional systemic courses in prescriber-heavy markets.
- Benzoyl Peroxide:Oxidizing agent with bactericidal and comedolytic properties available across prescription and over-the-counter channels.
- Salicylic Acid:Beta-hydroxy acid exfoliant penetrating follicles to dissolve sebaceous debris.
Retinoids dominate prescriber loyalty; benzoyl peroxide commands pharmacy volume.
End User:
Channel selection reflects disease severity, insurance configuration, and patient convenience preferences in parallel.
- Dermatology Clinics:Specialist facilities providing diagnostic evaluation and prescription management. Patient visit data shows this channel expanding most quickly as persistent adult acne drives repeat consultations across the United States and Western Europe.
- Home Care:Self-administered maintenance regimens following initial clinical consultation. Telemedicine platforms are locking in patient relationships through automated shipment programs that concentrate among millennial and Generation X demographics.
- Hospitals:Acute care settings managing severe nodulocystic presentations or treatment complications.
- Pharmacies:Retail and specialty dispensaries handling prescription fulfillment and over-the-counter selection.
Dermatology clinics lead on growth trajectory; pharmacies retain volume concentration.
Age Group:
Disease natural history and hormonal status create distinct therapeutic windows with varying compliance economics.
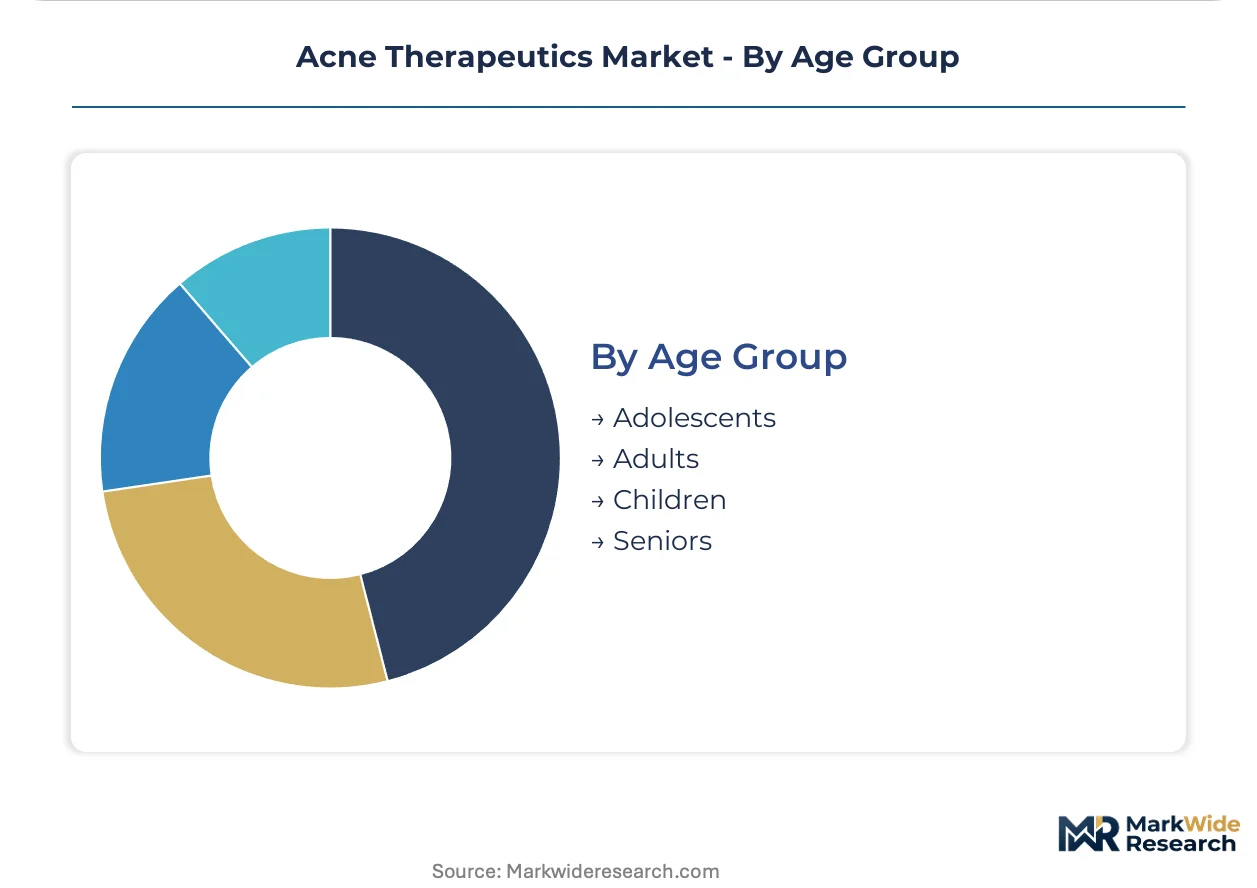
- Adults:Patients beyond adolescence experiencing persistent or late-onset presentations. This demographic concentrates demand for retinoid-based maintenance regimens and drives subscription model adoption through digital health channels in the United States.
- Adolescents:Puberty-associated presentations forming the traditional peak incidence population. Prescribing patterns here face heightened antibiotic stewardship scrutiny from pediatric and primary care gatekeepers.
- Children:Pre-pubertal presentations requiring specialized pediatric dermatology evaluation.
- Seniors:Age-associated hormonal shifts triggering late-onset presentations in smaller incident populations.
Adults lead on revenue per patient; adolescents retain incident volume concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acne therapeutics trace their modern commercial lineage to postwar pharmaceutical development in the United States and Switzerland, where retinoid chemistry first achieved scalable production. Regulatory frameworks established in these markets subsequently diffused to Asia-Pacific and Latin American jurisdictions.
United States
Direct-to-consumer telemedicine platforms and subscription-based replenishment models concentrate demand among millennial and Generation X adults managing persistent presentations. The FDA's iPLEDGE risk management program for isotretinoin stabilizes prescriber confidence in oral retinoid therapy. Boston and San Francisco anchor dermatology clinic expansion as patient visit volumes climb for adult acne consultations.
Germany
Dermatology clinics in Berlin, Munich, and Hamburg drive prescription volume for systemic therapies requiring specialty pharmacy distribution. The EMA's EudraVigilance pharmacovigilance obligations mandate real-world safety data collection for teratogenic retinoids. The Rhine-Ruhr industrial corridor hosts formulation facilities serving continental European markets with benzoyl peroxide and clindamycin production.
China
The National Medical Products Administration's accelerated approval pathways for innovative topical formulations are redirecting multinational clinical trial investment toward Shanghai and Beijing sites. Local demand for maintenance-phase retinoid regimens expands through hospital-affiliated dermatology departments. The Yangtze River Delta cluster concentrates contract manufacturing organizations serving domestic and export markets.
India
Active pharmaceutical ingredient production for benzoyl peroxide and oral antibiotics concentrates in Gujarat and Maharashtra, exposing formulators to input quality variability. The CDSCO's evolving bioequivalence standards shape generic penetration strategies for multinational sponsors. Hyderabad and Mumbai anchor Sun Pharmaceutical Industries Ltd.'s manufacturing footprint for antibiotic categories.
Brazil
ANVISA's regulatory harmonization with FDA standards facilitates branded therapeutic entry while preserving price-sensitive generic substitution patterns. São Paulo's dermatology clinic density exceeds national averages, concentrating demand for combination therapy kits. The Southeast region's pharmacy retail chains dominate over-the-counter benzoyl peroxide distribution volume.
Acne Therapeutics Market Competitive Environment
The competitive structure tilts toward integrated dermatology specialists with established prescriber relationships and generic manufacturers with cost-optimized API access. Consolidation pressure operates at the premium tier where R&D-derived portfolios command loyalty, while fragmentation persists in commoditized oral antibiotic categories. Two archetypes dominate: multinational pharmaceutical conglomerates leveraging immunology and dermatology pipelines, and emerging market generic houses capturing volume through price compression. Competitive moves center on reformulation investments for tolerability optimization and specialty pharmacy distribution partnerships for teratogenic therapy administration.
Among North American and European pharmaceutical conglomerates, Johnson & Johnson and Galderma occupy positions exemplifying the integrated dermatology platform archetype, while AbbVie Inc. represents the immunology-derived pipeline extension strategy. Sun Pharmaceutical Industries Ltd. anchors the emerging market generic penetration archetype through aggressive oral antibiotic category capture. These three companies collectively illustrate how geographic origin and corporate structure shape competitive positioning without converging on identical capability profiles.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Galderma |
| Bausch Health Companies Inc. |
| AbbVie Inc. |
| GlaxoSmithKline plc |
| Sun Pharmaceutical Industries Ltd. |
| Bayer AG |
| Teva Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| Others |
Value Chain & Pricing Dynamics
Retinoid tolerability certification tiers bifurcate the acne therapeutics landscape into premium microencapsulated formulations and commodity benzoyl peroxide generics, with each tier commanding distinct supply chain configurations and margin architectures. FDA labeling requirements for topical retinoids elevate compliance costs for premium players while Indian and Chinese API suppliers anchor economy-tier pricing through volume-scale benzoyl peroxide production.
Pricing Analysis
Subscription-based replenishment models for maintenance-phase topicals dominate US pricing architecture, separating premium branded retinoids from standard generic antibiotics and economy OTC benzoyl peroxide. Price differentiation rests on telemedicine platform access and tolerability certification tier rather than raw efficacy metrics. Cost compression in oral antibiotic categories intensifies as WHO stewardship protocols shorten permissible treatment durations. Cash-pay aesthetic channels exhibit lowest price sensitivity for light therapy devices, while pharmacy OTC volumes face highest sensitivity to per-unit cost.
Supply Chain Analysis
Dual-sourcing mandates from multinational formulators require qualified API suppliers in both India and China for benzoyl peroxide and clindamycin production. Raw material dependencies center on retinol precursors, controlled-release polymers, and specialty oxidation catalysts. Single-source vulnerability concentrates in Gujarat-based benzoyl peroxide manufacturers subject to quality inconsistency events. Distribution runs through specialty pharmacy networks for teratogenic oral therapies and telemedicine-platform direct fulfillment for maintenance topicals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acne therapeutics represents a late-cycle quality story where adult patient demand shifts toward premium tolerability-optimized formulations over commodity clearance. Microencapsulated retinoid delivery systems capture this specification migration through reduced discontinuation rates and higher lifetime value per patient.
For Market Incumbents: Deepen specialty pharmacy distribution partnerships for iPLEDGE-compliant oral isotretinoin administration to lock out generic substitution threats. Expand backward integration into microencapsulation polymer supply to defend margin position against API cost volatility from Indian suppliers. Prioritize certification investment for EudraVigilance reporting infrastructure to sustain European market access. For New Entrants and Emerging Players: NMPA accelerated approval pathways in China open a window for innovative topical formulations targeting hospital-affiliated dermatology departments. White-space concentration sits in combination kit positioning between pure prescription and pure OTC channels. Target telemedicine platform partnerships as the most penetrable go-to-market angle for US market entry. For Investors and Strategic Acquirers: Asymmetric upside sits with emerging market generic houses possessing captive API access and immunology-derived pipeline extensions from established dermatology platforms. Five-to-ten year viability favors sponsors with integrated tolerability optimization capabilities rather than single-mechanism discovery bets. Watch FDA reproductive-toxicity labeling revisions as the critical inflection signal for oral therapy prescribing confidence.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Controlled-release polymer partnerships buffer skin irritation while expanding retinoid candidacy to sensitive phenotypes. |
| Specialty Pharmacy Network Consolidation | iPLEDGE-compliant distribution infrastructure locks in prescriber relationships for teratogenic oral therapies. |
| Telemedicine Platform Integration | Subscription replenishment models capture millennial and Generation X patient relationships through automated shipment programs. |
| API Supplier Qualification Expansion | Dual-sourcing mandates from multinational formulators reduce Gujarat and Maharashtra concentration risk. |
| EudraVigilance Data Infrastructure Buildout | Real-world safety surveillance capabilities satisfy EMA post-authorization obligations for systemic retinoid commercialization. |
Study Parameters
Bottom-up dermatology clinic and telemedicine platform modeling reconciled against top-down API production and formulation capacity tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Cross-referencing prescription volume data against benzoyl peroxide and retinoid API trade flows enables supply-side triangulation.
Historical trendline analysis of patient visit patterns, prescription fulfillment rates, and discontinuation metrics across treatment modalities establishes baseline trajectory assumptions. Segmentation modeling incorporates treatment line, dosage form, administration route, patient population age cohort, and regional regulatory cluster. CAGRs derive from fitted growth curves adjusted for iPLEDGE program maturation effects and NMPA pathway acceleration. Forecast inputs include antibiotic stewardship protocol adoption rates and telemedicine platform penetration by demographic cohort.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt FDA labeling revisions or API supply disruptions. Projections reflect assumptions regarding prescriber confidence stability and patient adherence to maintenance regimens. Deviation in reproductive-toxicity regulatory thresholds would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Tissue Plasminogen Activator Market
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
Global Polio Vaccines Market
Pharmaceuticals
Hydroxyzine Market
Pharmaceuticals
US Oral Solid Dosage Contract Manufacturing Market
Pharmaceuticals
Global Lidocaine Market
Pharmaceuticals
Global Recombinant Vaccines Market
Pharmaceuticals
Meperidine Market
Pharmaceuticals
Europe Anesthesia Drugs Market
Pharmaceuticals
Hyoscine-N-Butyl Bromide Market
Pharmaceuticals
Global Pediatric Vaccines Market
Pharmaceuticals
Global Psoriasis Drugs Market
Pharmaceuticals
Europe FMD Vaccine Market
Pharmaceuticals
PARP Inhibitors Market
Pharmaceuticals
Acetaminophen Injection Market
Pharmaceuticals
Soft Capsules Drugs CMO Market