
 Authorized Generics Market | 2026-2036
Authorized Generics Market Size, Share, and Industry Trends Forecast 2026-2036
Authorized Generics Market Outlook
Wholesale distribution networks is reconfiguring how authorized generics reach pharmacy shelves and hospital formularies. Teva Pharmaceuticals Industries leverages its vertically integrated manufacturing footprint to sustain supply continuity across multiple therapeutic categories. Sandoz anchors the European authorized generic landscape through its Novartis heritage, while Mylan competes aggressively on price in the cardiovascular and central nervous system segments.
Authorized generics are pharmaceutical products approved under an existing New Drug Application but marketed without the originator brand name, typically manufactured by the innovator company or a designated partner using identical active ingredients and bioequivalence profiles. These products serve the primary commercial purpose of pre-empting independent generic competition, extending revenue streams near patent expiry, or fulfilling settlement obligations in Hatch-Waxman litigation. Prescription medications dominate volume as originator firms deploy authorized generics to defend market position against Paragraph IV challengers, while the hospital end user segment captures concentrated demand through group purchasing organization contracts. Distribution channel dynamics favor direct sales for large institutional buyers, though wholesalers retain leverage in fragmented retail pharmacy markets.
The US FDA oversees ANDA approvals and bioequivalence standards, while the EMA coordinates centralized marketing authorization procedures across European member states, and India's CDSCO governs export-oriented manufacturing compliance for contract producers supplying authorized generic programs. Regulatory frameworks shape market access timelines, with 505(b)(2) applications creating alternative pathways for modified formulations that complicate pure authorized generic strategies. Stakeholders must monitor patent cliff calendars and litigation settlement disclosures to anticipate authorized generic launch windows before independent competitors file.
Market Dynamics
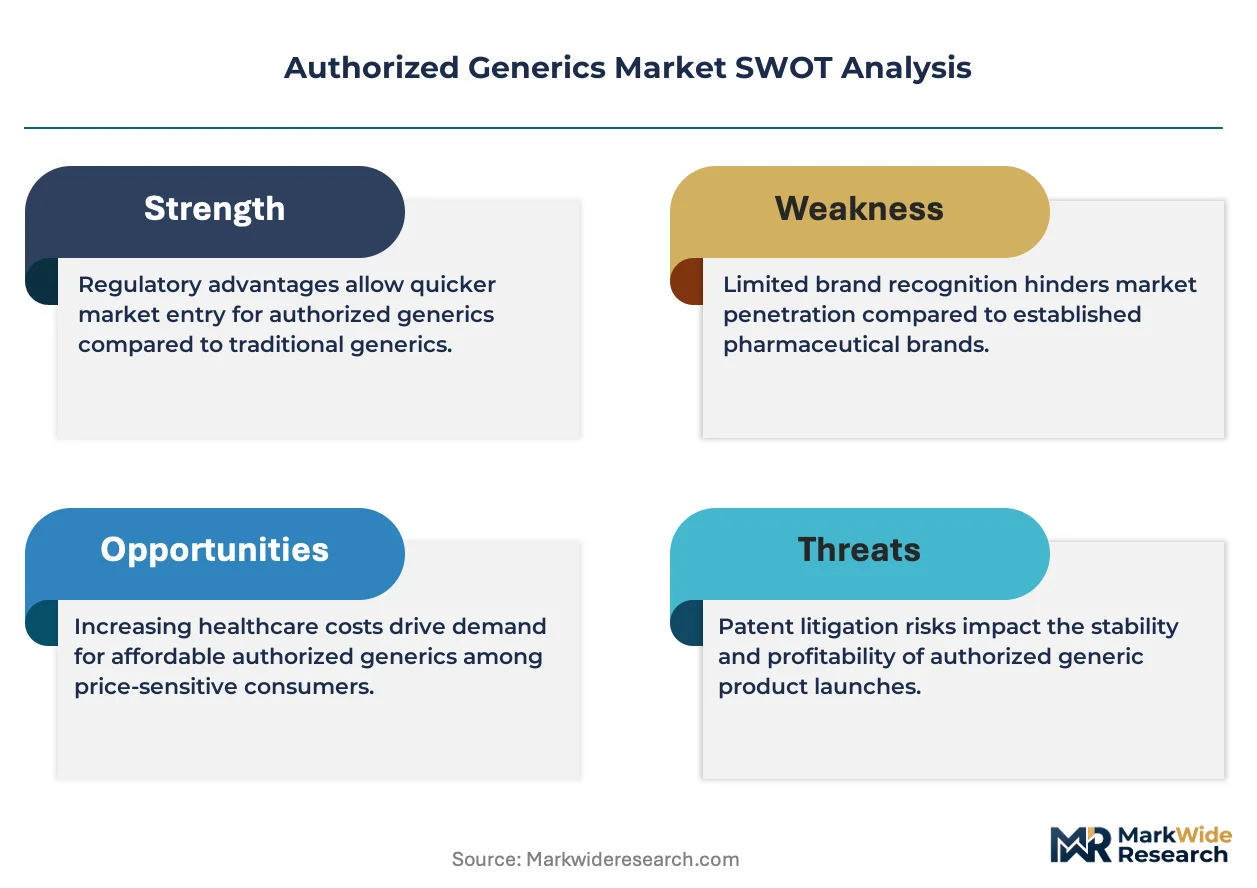
Patent litigation settlements and Paragraph IV challenge dynamics are reconfiguring how originator firms deploy authorized generics as defensive instruments against independent generic entrants. The ANDA pathway's procedural efficiencies compress launch windows and intensify pre-emptive positioning strategies.
Growth Catalysts
- First-to-File Exclusivity Dynamics:The US FDA's 180-day exclusivity provisions for first Paragraph IV filers incentivize originator firms to launch authorized generics before independent competitors secure market position.
- Retail Pharmacy Substitution Programs:Major pharmacy chains are expanding automatic generic substitution protocols, creating pull-through demand for authorized generic alternatives with identical bioequivalence profiles.
- Hatch-Waxman Settlement Obligations:Patent litigation settlements frequently mandate authorized generic launches as compromise mechanisms, institutionalizing recurring revenue streams near compound expiry.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing concentrates in India and China, exposing authorized generic programs to geopolitical friction and export control volatility.
- ANDA Approval Timelines:US FDA backlog fluctuations and complete response letter cycles extend time-to-market for authorized generic entrants, eroding defensive launch windows.
- Independent Generic Price Erosion:Post-exclusivity periods trigger rapid price compression from multiple ANDA holders, compressing authorized generic margin sustainability.
Strategic Opportunities
- Hospital GPO Contract Penetration:Group purchasing organization consolidation creates concentrated procurement channels where authorized generics secure formulary placement through direct manufacturer agreements.
- Biologics Authorized Generic Pathways:The US FDA's emerging framework for biosimilar reference product substitutions opens defensive positioning opportunities for biologic originator firms.
- 505(b)(2) Hybrid Formulations:Modified delivery mechanisms and combination products create authorized generic extensions that complicate pure generic replication.
Industry Challenges
- Complex Generic Manufacturing Expertise:Controlled-release formulations and inhalation devices require specialized production capabilities scarce among contract manufacturers.
- Litigation Disclosure Timing:Settlement agreement confidentiality provisions obscure authorized generic launch windows, complicating supply chain and inventory planning.
- Multi-Jurisdiction Regulatory Synchronization:Divergent bioequivalence standards across the US FDA, EMA, and India's CDSCO fragment global authorized generic deployment strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Authorized Generics Market |
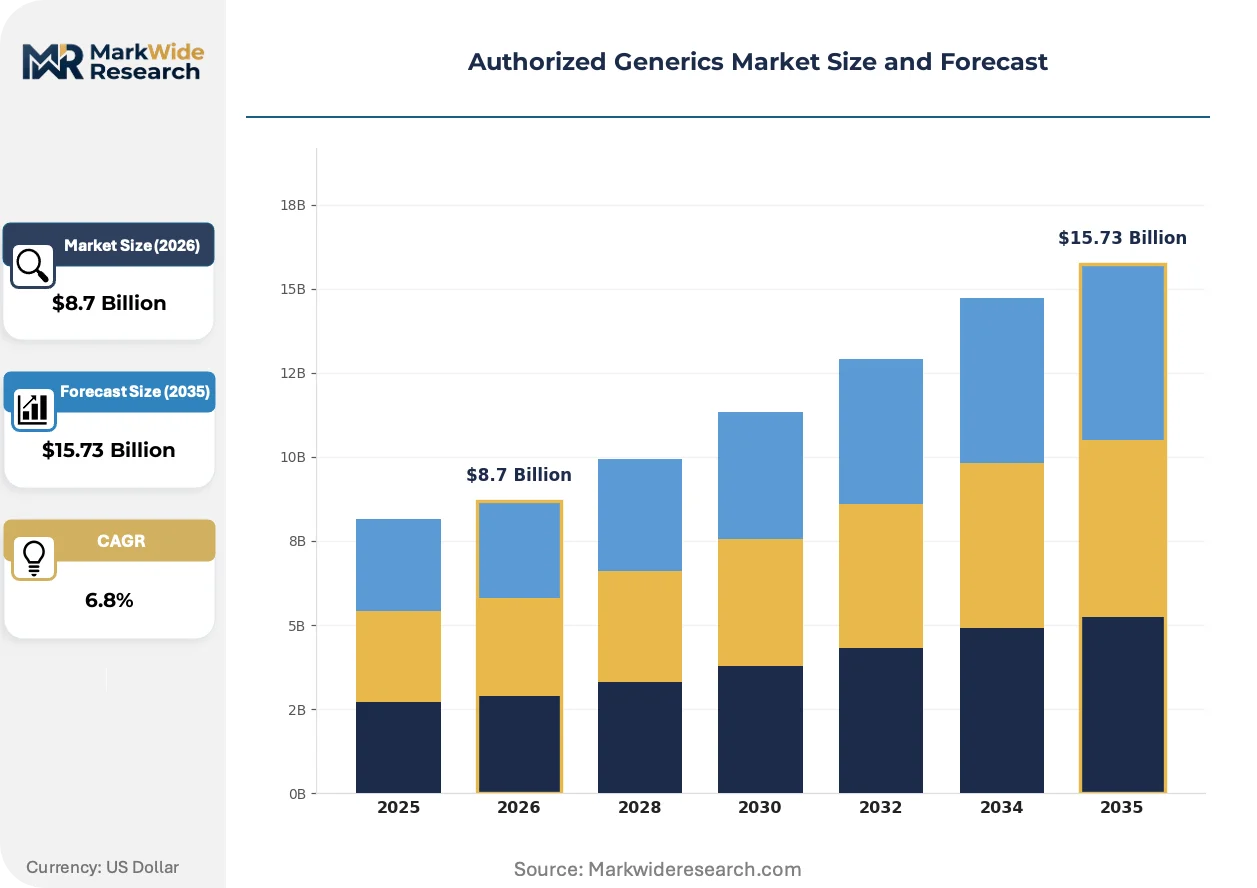
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Medications, Over-the-Counter Drugs, Biologics, Vaccines End User: Pharmacies, Hospitals, Physicians, Clinics Distribution Channel: Direct Sales, Wholesalers, Online Retailers, Distributors Regulatory Approval: ANDA, NDA, 505(b)(2) Applications, Exemptions |
| Companies Covered | Sandoz, Teva Pharmaceuticals Industries, Mylan, Pfizer, Sun Pharmaceutical Industries, Novartis, Dr. Reddy's Laboratories, Aspen Pharmacare Holdings, Lupin Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Authorized Generics Market Strategic Shifts
Authorized generic deployment strategies are migrating from reactive patent defense toward proactive portfolio lifecycle management. Innovator firms now integrate authorized generic planning into pre-clinical development timelines.
Continuous manufacturing technologies are migrating from batch production toward integrated real-time release systems. Sandoz and Teva Pharmaceuticals are retrofitting oral solid dose facilities with PAT-enabled production lines. This migration from traditional batch validation is compressing FDA inspection cycles and accelerating post-approval change management for authorized generic programs.
The US FDA's revised bioequivalence guidance for narrow therapeutic index drugs is tightening pharmacokinetic study requirements. This regulatory recalibration elevates authorized generic attractiveness, as originator-manufactured products carry inherent bioequivalence credibility. Cardiovascular and central nervous system therapeutic categories face the steepest compliance burden under these tightened standards.
Hospital procurement consolidation is displacing fragmented wholesaler-mediated purchasing with direct manufacturer contracting. Large health systems in the United States are leveraging authorized generic availability to extract volume commitments and price protection from originator firms. This concentration is most visible in oncology and anti-infective therapeutic classes where formulary control determines market access.
Authorized Generics Market Segmentation
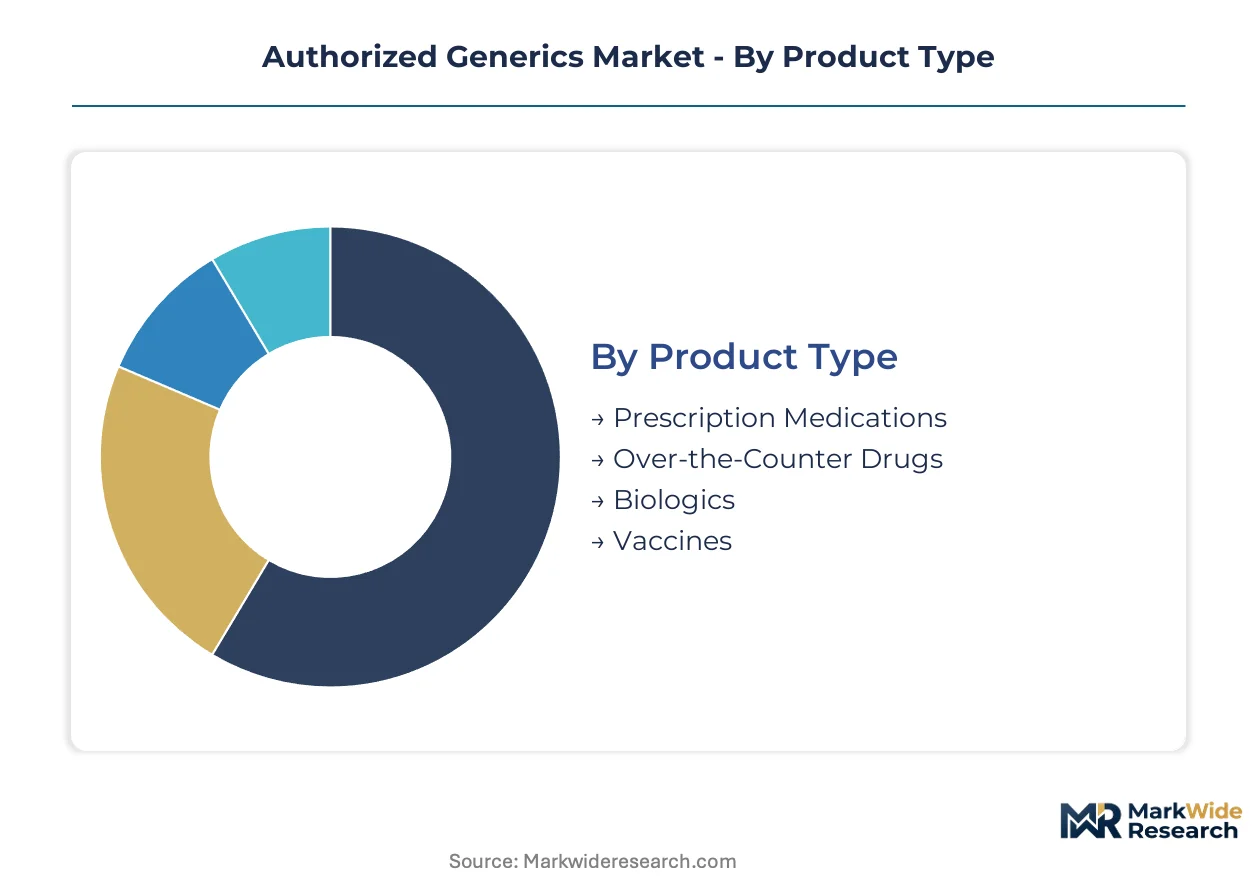
Authorized generics require precise segmentation because product type determines regulatory pathway complexity, while distribution channel selection directly impacts formulary access speed. End user concentration shapes pricing power, and approval mechanism choice dictates competitive defense timing.
Product Type:
After-sales pharmacovigilance intensity varies dramatically across product categories, with biologics demanding continuous safety monitoring that prescription medications rarely require.
- Prescription Medications:Small-molecule compounds dominate authorized generic deployment, with identical active ingredients and bioequivalence profiles to originator brands. Demand concentrates in cardiovascular and central nervous system therapeutic categories where Teva Pharmaceuticals and Mylan pursue aggressive substitution strategies against Paragraph IV challengers.
- Over-the-Counter Drugs:Self-administered products with simplified labeling requirements and accelerated FDA review timelines. Retail pharmacy chains in the United States leverage automatic substitution protocols to capture margin expansion in analgesic and gastrointestinal segments.
- Biologics:Complex proteins requiring specialized cold-chain distribution and immunogenicity surveillance.
- Vaccines:Preventive biologics with batch-specific release testing and national immunization program procurement.
Prescription medications hold the largest share; momentum sits with biologics as the FDA clarifies biosimilar substitution frameworks.
End User:
Procurement consolidation is forcing authorized generic suppliers to reconfigure account management resources around high-volume institutional buyers.
- Pharmacies:Retail chains and independent dispensaries drive volume through automatic generic substitution protocols. CVS Health and Walgreens in the United States extract price concessions through volume commitments, while hospital outpatient pharmacies capture oncology and anti-infective authorized generics through 340B program eligibility.
- Hospitals:Inpatient facilities with group purchasing organization contracts that centralize formulary decisions. Premier and Vizient in the United States leverage authorized generic availability to secure multi-year price protection from originator firms facing patent expiry.
- Physicians:Direct prescribing influence in specialty therapeutic areas.
- Clinics:Ambulatory care sites with limited inventory capacity.
Hospitals command the deepest authorized generic penetration; clinics are expanding most quickly as infusion centers proliferate.
Distribution Channel:
Margin compression across channel tiers is compelling authorized generic manufacturers to bypass intermediary markups where buyer scale permits.
- Direct Sales:Manufacturer-to-institution contracting that eliminates wholesaler margins. Large health systems in the United States negotiate directly with Novartis heritage operations for Sandoz authorized generics, capturing price advantages unavailable through fragmented retail channels.
- Wholesalers:McKesson and AmerisourceBergen maintain leverage in retail pharmacy markets where fragmented buying power prevents direct manufacturer engagement.
- Online Retailers:Mail-order pharmacies with automated refill systems.
- Distributors:Regional logistics specialists serving rural and specialty pharmacy segments.
Direct sales generate the steepest expansion trajectory; wholesalers retain defensive positioning in independent pharmacy networks.
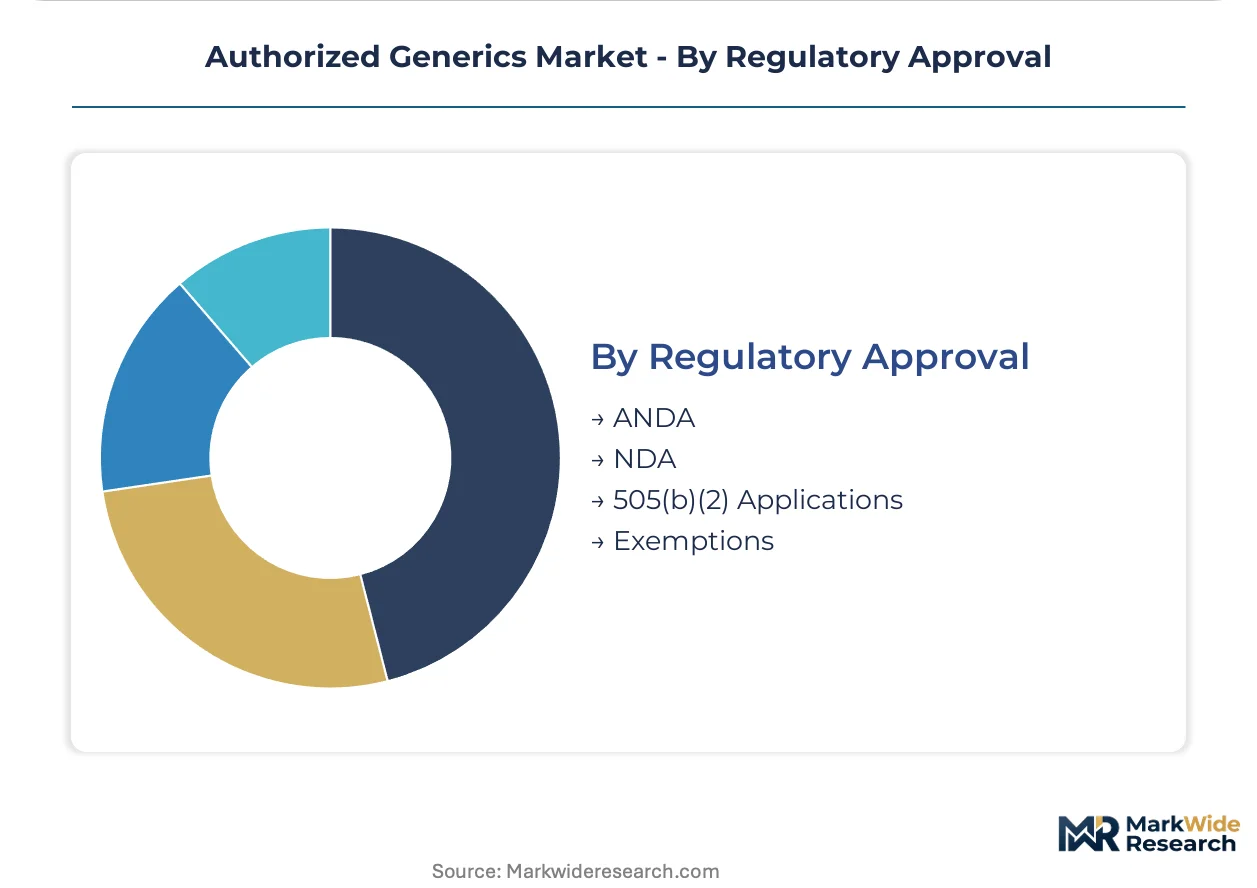
Regulatory Approval:
Pathway selection determines both development cost structure and competitive exclusivity duration for authorized generic entrants.
- ANDA:Abbreviated New Drug Applications under Hatch-Waxman provisions that reference listed drugs without repeating clinical efficacy studies. The US FDA's streamlined bioequivalence requirements compress approval timelines for small-molecule authorized generics manufactured by originator-designated partners.
- NDA:Full New Drug Applications requiring independent clinical data packages.
- 505(b)(2) Applications:Hybrid pathways permitting reference to published literature and prior FDA findings for modified formulations.
- Exemptions:Regulatory waivers for specific public health or supply continuity scenarios.
ANDA approvals dominate volume; 505(b)(2) applications are gaining share fastest as originator firms pursue formulation extensions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while European markets compress margins through centralized procurement. German hospital networks extract deeper concessions than American retail chains. Indian manufacturing clusters supply active ingredients that determine cost structures across both regions.
United States
Paragraph IV litigation settlements generate recurring authorized generic launch windows as originator firms deploy defensive products. The FDA's ANDA pathway streamlines approvals for designated manufacturing partners. New Jersey and Pennsylvania host concentrated pharmaceutical operations where Teva Pharmaceuticals maintains vertically integrated production facilities.
Germany
Hospital group purchasing organizations centralize formulary decisions that favor authorized generics with proven bioequivalence profiles. The EMA coordinates centralized marketing authorization procedures that reduce regulatory fragmentation across member states. Baden-Württemberg and Bavaria house specialized manufacturing operations where Sandoz leverages its Novartis heritage for European distribution.
India
Contract manufacturing organizations supply active pharmaceutical ingredients to authorized generic programs worldwide. The CDSCO governs export-oriented compliance for facilities producing under originator-designated partnerships. Hyderabad and Mumbai clusters concentrate formulation expertise that supports global defensive launches near patent expiry.
Switzerland
Specialty pharmaceutical operations focus on complex generic formulations requiring advanced manufacturing capabilities. Swissmedic maintains stringent bioequivalence standards that reinforce originator-manufactured product credibility. Basel anchors European headquarters operations for firms coordinating multi-jurisdictional authorized generic deployments.
United Kingdom
Retail pharmacy chains expand automatic substitution protocols that accelerate authorized generic uptake post-launch. The Medicines and Healthcare products Regulatory Agency aligns with EMA procedures while maintaining national flexibility for urgent supply continuity measures. Southeast England concentrates distribution infrastructure serving National Health Service procurement channels.
Authorized Generics Market Competitive Environment
Originator-affiliated manufacturers and independent generic specialists split the market between defensive patent strategies and pure price competition. Market structure tilts toward consolidation as litigation settlements mandate recurring authorized generic partnerships. Three archetypes dominate: vertically integrated innovators managing lifecycle extensions, designated contract manufacturers with regulatory expertise, and hybrid players spanning both authorized and independent generic portfolios. Capacity expansion and strategic licensing agreements represent the primary competitive moves as firms secure manufacturing flexibility ahead of patent cliff calendars.
Among originator-affiliated specialists, Sandoz and Teva Pharmaceuticals exemplify the vertically integrated archetype, while Mylan occupies a position bridging authorized and independent generic strategies. Sandoz leverages its Novartis heritage across European hospital networks. Teva Pharmaceuticals sustains supply continuity through captive manufacturing footprints in multiple therapeutic categories. Mylan competes aggressively on price within cardiovascular and central nervous system segments where authorized generic defenses prove most effective.
| Leading Market Players |
|---|
| Sandoz |
| Teva Pharmaceuticals Industries |
| Mylan |
| Pfizer |
| Sun Pharmaceutical Industries |
| Novartis |
| Dr. Reddy's Laboratories |
| Aspen Pharmacare Holdings |
| Lupin Limited |
| Others |
Value Chain & Pricing Dynamics
API supply concentration in India and China determines both pricing tier spreads and supply chain shape for authorized generic programs. Originators face margin compression when active pharmaceutical ingredient export controls disrupt cost structures, while hospital GPOs exploit this dependency to extract volume-based price concessions.
Pricing Analysis
The customization-premium spread separates standard ANDA products from 505(b)(2) formulation extensions with modified delivery mechanisms. Pricing stratifies across originator-branded authorized generics, designated partner products, and pure independent generic substitutes based on bioequivalence certification tier and manufacturing pedigree. Cost compression in the cardiovascular and central nervous system segments is intensifying because multiple Paragraph IV filers trigger rapid post-exclusivity price erosion. Hospital procurement committees demonstrate the highest price sensitivity through GPO-negotiated multi-year contracts, while specialty pharmacy segments retain lower sensitivity due to formulary control priorities.
Supply Chain Analysis
Contract-manufacturing concentration rests with Dr. Reddy's Laboratories, Lupin Limited, and Sun Pharmaceutical Industries for API production serving authorized generic programs. Finished dose formulation draws from facilities in India, China, and Switzerland, with Hyderabad and Mumbai clusters anchoring global supply. Active pharmaceutical ingredient dependencies hinge on imported starting materials, specialized excipients for controlled-release formulations, and cold-chain biologics components. Single-source vulnerability concentrates in oncology API precursors subject to export license requirements. Distribution runs through McKesson and AmerisourceBergen for retail pharmacy networks, while direct manufacturer contracting dominates hospital institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Authorized generic markets exhibit accelerating buyer power consolidation through hospital GPO mergers and pharmacy chain acquisitions. This concentration shifts pricing leverage toward procurement committees that demand multi-year volume commitments from originator firms.
For Market Incumbents: Build regulatory filing moats by pre-positioning 505(b)(2) applications before Paragraph IV challengers secure first-to-file exclusivity. Sandoz and Teva Pharmaceuticals should deepen captive API production in India to mitigate tariff exposure on imported starting materials. Secure formulary lock-in through direct contracting with Premier and Vizient before patent expiry windows open.
For New Entrants and Emerging Players: Hospital outpatient pharmacies in the United States represent the most penetrable entry point for authorized generic specialists lacking originator heritage. Target 340B-eligible infusion centers with limited inventory capacity that prioritize supply continuity over brand recognition. Pursue regulatory affairs partnerships with established CDSCO-registered manufacturers to compress ANDA approval timelines.
For Investors and Strategic Acquirers: The market sits at a litigation-settlement peak phase that favors vertically integrated manufacturers with captive API supply. Long-term viability hinges on backward integration into complex generic capabilities including controlled-release and inhalation device expertise. Watch FDA bioequivalence guidance revisions for narrow therapeutic index drugs as the primary inflection signal for authorized generic attractiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| ANDA Filing Acceleration | Compresses approval timelines through FDA pre-submission meetings and bioequivalence study design alignment. |
| API Backward Integration | Captures cost control over imported starting materials from Hyderabad and Mumbai manufacturing clusters. |
| Hospital GPO Direct Contracting | Secures multi-year formulary placement with Premier and Vizient before independent generic entry. |
| 505(b)(2) Formulation Extension | Creates authorized generic moats through modified delivery mechanisms that complicate pure generic replication. |
| Continuous Manufacturing Retrofit | Enables PAT-enabled production lines that accelerate FDA inspection cycles for Sandoz and Teva facilities. |
Study Parameters
Initial hypotheses were tested against primary input from regulatory affairs directors, hospital formulary managers, GPO contracts specialists, and API procurement leads and refined through secondary validation. FDA ANDA approval databases, EMA centralized marketing authorization records, ClinicalTrials.gov pharmacokinetic study registrations, and CDSCO manufacturing facility inspection reports provided structured benchmarks. Bottom-up demand modeling across prescription medication, over-the-counter, and biologics segments triangulated with top-down market sizing from originator firm disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions included product type, end user concentration, distribution channel structure, and regulatory approval pathway complexity. CAGRs were derived from patent cliff calendars, litigation settlement disclosure patterns, and ANDA filing velocity trends. Forecast inputs incorporated FDA backlog fluctuation scenarios and API export control risk weightings.
Macroeconomic conditions sit as an overlay; deviation in rupee-dollar exchange rates, ocean freight indices, or biologics cold-chain logistics costs would shift the trajectory. Quarterly review of FDA complete response letter issuance rates, Paragraph IV filing volumes, and GPO contract renewal announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Central Nervous System (CNS) Stimulant Drugs Market
Pharmaceuticals
Global Diphtheria Vaccine Market
Pharmaceuticals
Josamycin Market
Pharmaceuticals
Disease-Modifying Agents Market
Pharmaceuticals
Cough and Cold Preparations Market
Pharmaceuticals
Latin America Sodium-Glucose Cotransport-2 (SGLT-2) Inhibitor Market
Pharmaceuticals
Dipeptide Peptidase 4 Inhibitors Market
Pharmaceuticals
Motilium Market
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
Adrenocorticotropic Hormone [ACTH] Market
Pharmaceuticals
Anti-Platelet Agents Market
Pharmaceuticals
Global Alteplase Market
Pharmaceuticals
Global Pharmaceutical Traceability Market
Pharmaceuticals
Thrombosis Drugs Market
Pharmaceuticals
Global Nasal Drug Delivery Technology Market
Pharmaceuticals
Antihistamines Market