
 Anti-Radiation Drugs Market | 2026-2036
Anti-Radiation Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Radiation Drugs Market Outlook
Advanced chelation chemistry and synthetic radioprotectant platforms is rewriting how developers formulate next-generation countermeasures against ionizing radiation exposure. Amgen Inc. leverages its biologics manufacturing infrastructure to sustain supply chain resilience for complex protein-based radioprotectants. Humanetics Corporation anchors its position through deep specialization in small-molecule radiomitigators derived from established pharmacological scaffolds. Soligenix Inc. competes in the biodefense contracting channel with government-funded development programs for radiation-induced injury.
Anti-radiation drugs comprise pharmaceutical agents designed to prevent, mitigate, or treat tissue damage caused by acute exposure to ionizing radiation, including thiol-based free radical scavengers, cytokine modulators, and heavy metal chelators formulated for rapid biodistribution and hematopoietic stem cell protection. Potassium Iodide dominates the product type landscape due to established thyroid blocking protocols and low-cost mass production, while Prussian Blue occupies a narrower but critical niche for internal contamination with radioactive cesium and thallium. Cancer Treatment leads the therapy area segmentation by volume, reflecting integration of radioprotectants into radiation oncology protocols to reduce normal tissue toxicity during curative regimens.
The U.S. FDA governs approval pathways for medical countermeasures under the Animal Rule, while the U.S. Department of Health and Human Services coordinates stockpiling requirements through the Strategic National Stockpile program. EMA's Committee for Medicinal Products for Human Use maintains parallel guidance for radiological emergency preparedness across European member states, creating dual jurisdictional compliance burdens for developers seeking transatlantic market access. Stakeholders must monitor how evolving biodefense procurement frameworks and radiological threat assessments reshape prioritization of development pipelines and manufacturing capacity commitments.
Market Dynamics
Federal biodefense procurement mandates are compressing development timelines for radiological countermeasures, while the FDA's Animal Rule creates unique efficacy validation pathways that reshape competitive positioning across the supply base.
Growth Catalysts
- Strategic National Stockpile mandates:The U.S. Department of Health and Human Services maintains continuous procurement cycles for post-exposure therapies, creating predictable demand anchors for domestic manufacturers.
- EMA radiological preparedness frameworks:Parallel guidance across European member states for medical countermeasures is expanding addressable market access for developers achieving dual-jurisdiction compliance.
- Cancer radioprotection integration:Radiation oncology protocols increasingly incorporate hematopoietic stem cell protectants to reduce normal tissue toxicity during curative regimens.
Market Restraints
- Isotope supply concentration:Production of certain radiolabeled compounds depends on aging reactor infrastructure concentrated in Belgium and South Africa, creating single-point vulnerability.
- Animal Rule validation costs:FDA requirements for efficacy demonstration in appropriate animal models impose capital-intensive study designs without human clinical data pathways.
- Thiol compound instability:Free radical scavenger formulations face shelf-life limitations that complicate long-term stockpiling logistics for emergency deployment.
Strategic Opportunities
- Synthetic radioprotectant platforms:Next-generation small-molecule scaffolds derived from non-thiol chemistries offer improved stability profiles for extended stockpile rotation cycles.
- Japan's nuclear emergency protocols:METI-coordinated preparedness programs create procurement channels for thyroid blocking agents and decorporation therapies beyond Western markets.
- Cytokine modulation convergence:Combination therapies pairing hematopoietic growth factors with anti-inflammatory biologics represent underexplored efficacy enhancement vectors.
Industry Challenges
- Specialized toxicology expertise scarcity:Radiation biology and dosimetry assessment capabilities concentrate within national laboratories and select academic centers, constraining workforce pipeline development.
- Multi-year certification timelines:Animal Rule compliance dossiers require extensive radiation exposure facility partnerships that extend time-to-revenue for novel molecular entities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Radiation Drugs Market |
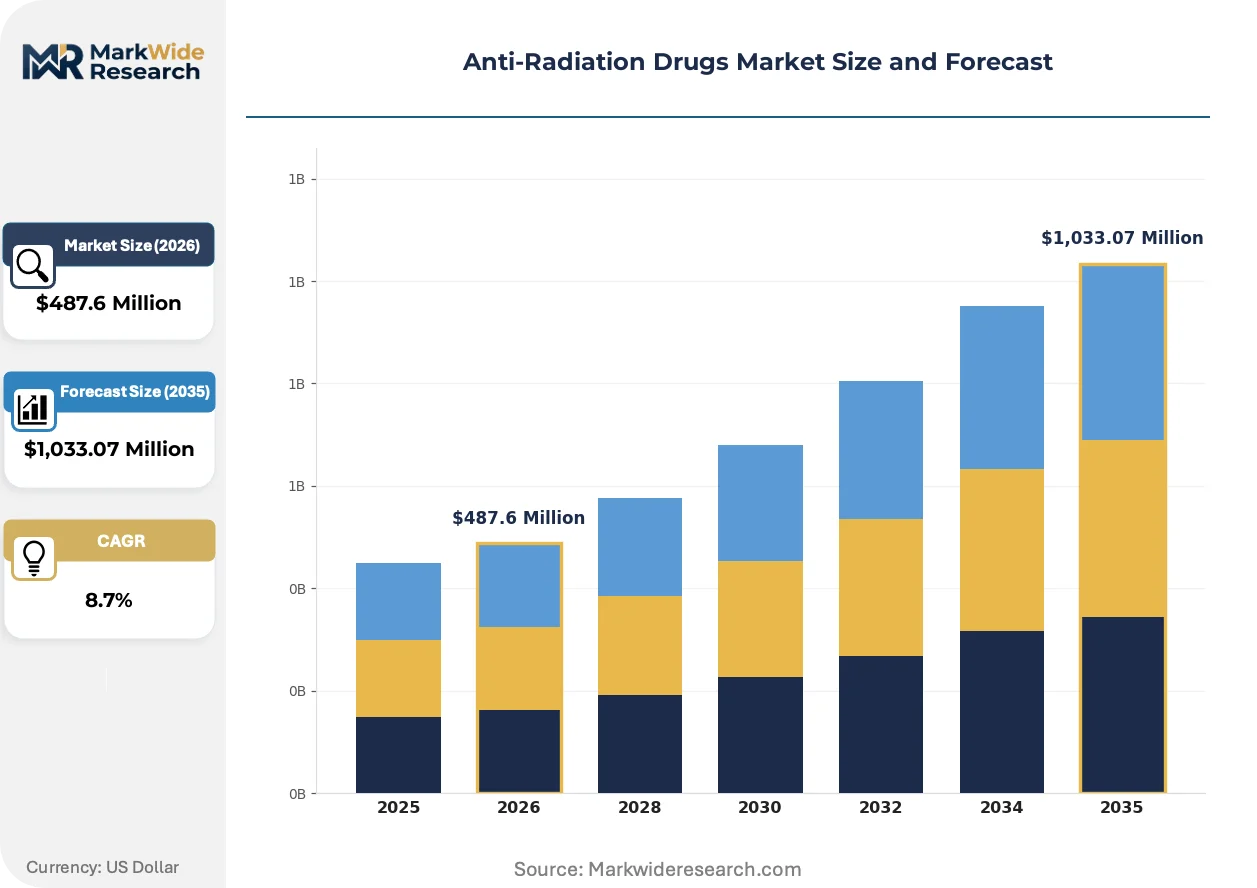
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potassium Iodide, Calcium DTPA, Prussian Blue, Sodium Bicarbonate Therapy Area: Cancer Treatment, Post-Exposure Therapy, Prophylaxis, Radiation Injury End User: Hospitals, Research Institutions, Military Facilities, Pharmaceutical Companies Delivery Mode: Oral, Intravenous, Injection, Sublingual |
| Companies Covered | Amgen Inc., Humanetics Corporation, Soligenix Inc., Partner Therapeutics Inc., Anbex Inc., BTG International Inc., RxBio Inc., Onconova Therapeutics, Chrysalis BioTherapeutics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Radiation Drugs Market Strategic Shifts
Formulation science and biodistribution engineering are redefining therapeutic windows for radioprotectant compounds, while regulatory harmonization efforts accelerate cross-border deployment readiness.
Synthetic non-thiol radioprotectants employing novel free radical scavenging mechanisms are rendering obsolete traditional cysteamine-based compounds with narrow therapeutic indices. Military medical research programs and select radiation oncology centers are piloting these next-generation platforms for acute exposure scenarios. The shift is compressing development timelines for formulations with superior stability and reduced emetogenic side effect profiles.
EMA's Committee for Medicinal Products for Human Use issued updated guidance on radiological emergency preparedness that tightens quality standards for decentralized manufacturing of potassium iodide tablets. The framework requires validated cold-chain alternatives for stockpile distribution, forcing reformulation investments among generic manufacturers. European member states with nuclear power infrastructure are prioritizing compliance to avoid supply gaps during emergency response windows.
Hospital pharmacy committees are consolidating procurement authority for radioprotectants under centralized emergency preparedness officers rather than decentralized oncology purchasing. The concentration is displacing traditional distributor relationships in favor of direct manufacturer contracts with guaranteed surge capacity clauses. This pattern is most pronounced across U.S. academic medical centers with designated radiation injury treatment capabilities.
Anti-Radiation Drugs Market Segmentation
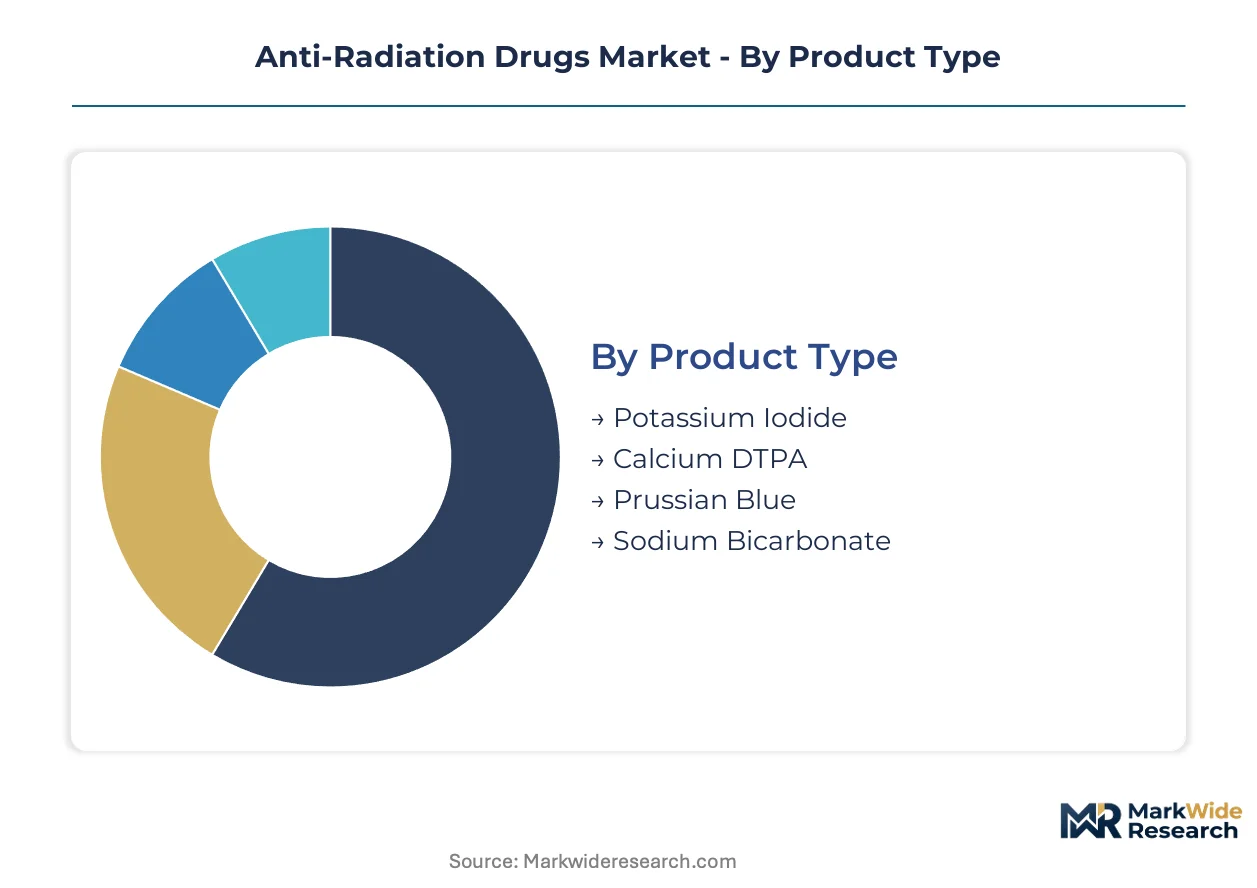
Segmentation in the anti-radiation drugs market reveals distinct procurement patterns across therapeutic applications and institutional buyers. Product chemistry, delivery urgency, and stockpiling logistics create divergent margin structures and competitive dynamics within each category.
Product Type:
Mature mass-production platforms dominate volume, while emerging synthetic chemistries capture development investment.
- Potassium Iodide:Thiol-based thyroid blocking agent with decades of validated shelf-life data and low-cost tablet manufacturing. Demand concentrates in federal stockpiling programs across the United States, Japan, and European nuclear states, constrained by batch rotation requirements and geographic dispersion logistics.
- Prussian Blue:Insoluble ferric hexacyanoferrate complex formulated for gastrointestinal absorption of radioactive cesium and thallium. Procurement channels center on military medical services and specialized radiation treatment facilities, driven by internal contamination protocols following nuclear incidents.
- Calcium DTPA:Heavy metal chelator for transuranic element decorporation with intravenous administration requirements.
- Sodium Bicarbonate:Alkalinizing agent used in uranium exposure protocols with established hospital pharmacy distribution.
Potassium Iodide retains volume leadership; synthetic radioprotectant platforms hold the steepest expansion curve.
Therapy Area:
Application scope ranges from scheduled oncology protocols to emergency deployment scenarios with divergent reimbursement pathways.
- Cancer Treatment:Radioprotectants integrated into curative radiation oncology regimens to reduce normal tissue toxicity during fractionated dosing. Demand concentrates in academic medical centers with designated radiation injury treatment capabilities, driven by expanding adjuvant therapy protocols and patient volume growth.
- Post-Exposure Therapy:Acute administration following unintended radiation exposure including decorporation agents and hematopoietic stem cell protectants. Procurement is anchored by the U.S. Strategic National Stockpile and parallel European emergency preparedness frameworks, constrained by Animal Rule validation timelines.
- Prophylaxis:Pre-exposure administration for occupational radiation workers and nuclear facility personnel.
- Radiation Injury:Treatment of established tissue damage including cytokine modulation and supportive care protocols.
Cancer Treatment commands the largest addressable patient base; Post-Exposure Therapy shows the most concentrated procurement authority consolidation.
End User:
Buyer sophistication spans centralized federal procurement to decentralized research acquisition with contrasting contract structures.
- Hospitals:Primary channel for clinical radioprotectant administration encompassing emergency departments and radiation oncology units. Demand concentrates in U.S. academic medical centers with Level 1 trauma designation and radiation injury treatment capabilities, driven by Joint Commission emergency preparedness mandates.
- Military Facilities:Specialized procurement for armed forces medical services and combat support hospitals. Investment flows through biodefense contracting channels with multi-year development agreements, constrained by classified threat assessment protocols and surge capacity requirements.
- Research Institutions:Preclinical and clinical trial supply for radiobiology investigation.
- Pharmaceutical Companies:Active pharmaceutical ingredient sourcing and contract manufacturing relationships.
Hospitals represent the broadest geographic footprint; Military Facilities demonstrate the most concentrated single-buyer contract value.
Delivery Mode:
Administration route determines stability requirements, distribution infrastructure, and emergency deployment feasibility.
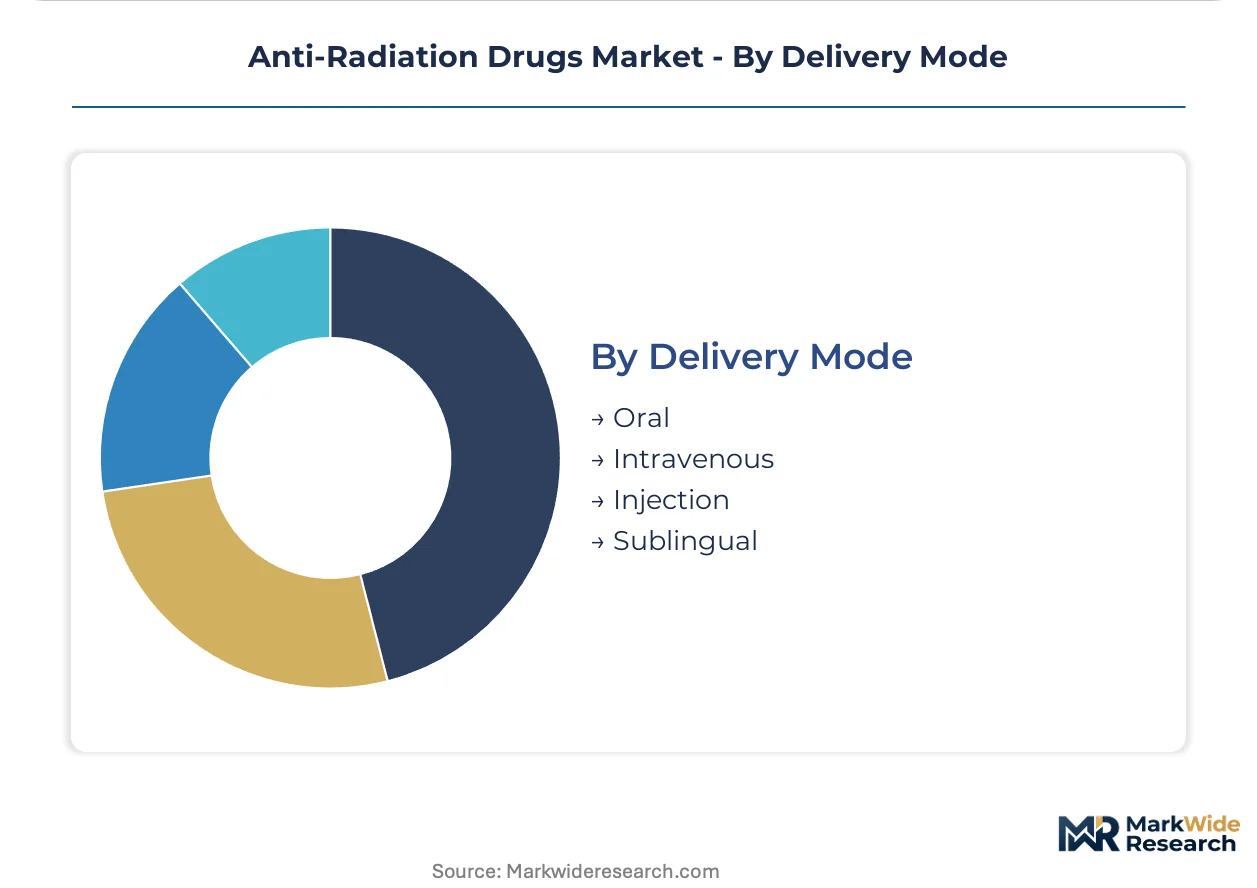
- Oral:Tablet and liquid formulations for thyroid blocking and decorporation therapies with ambient storage compatibility. Demand concentrates in civilian emergency stockpiles and outpatient oncology protocols, driven by self-administration feasibility and minimal cold-chain dependency.
- Intravenous:Chelator and cytokine formulations requiring clinical administration and controlled temperature distribution. Procurement centers on hospital pharmacy and military medical logistics, constrained by shelf-life limitations and infusion infrastructure requirements.
- Injection:Intramuscular delivery for rapid biodistribution in field conditions.
- Sublingual:Mucosal absorption for patients with compromised gastrointestinal function.
Oral delivery retains stockpile volume dominance; Intravenous administration captures the highest per-dose valuation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based manufacturers dominate export flows to allied biodefense stockpiles across Japan and European nuclear states. Procurement corridors concentrate on federal emergency preparedness networks rather than commercial distribution channels.
United States
The Strategic National Stockpile mandates continuous procurement cycles for post-exposure therapies. FDA's Animal Rule creates specialized efficacy validation pathways for radiological countermeasures. Maryland and Virginia host concentrated biodefense contracting operations near national laboratory complexes.
Japan
METI-coordinated nuclear emergency protocols drive thyroid blocking agent procurement beyond Western markets. The country's national pharmaceutical regulator maintains stringent quality standards for decentralized manufacturing compliance. Tokyo and Osaka medical centers anchor radiation injury treatment capabilities with designated surge capacity.
Germany
Radiation oncology integration of hematopoietic stem cell protectants expands addressable patient bases. EMA's Committee for Medicinal Products for Human Use governs parallel guidance for emergency preparedness frameworks. Bavaria and Baden-Württemberg concentrate academic medical centers with Level 1 trauma designations.
Switzerland
Swissmedic oversight of radiological medical countermeasures attracts dual-jurisdiction compliance investments. The country's national pharmaceutical regulator coordinates with European member states on quality standard harmonization. Basel and Zurich host specialized toxicology expertise and radiation biology assessment capabilities.
United Kingdom
Biodefense infrastructure investments align with NATO radiological threat assessment protocols. The country's national pharmaceutical regulator maintains emergency use authorization pathways modeled on FDA frameworks. London and Oxford academic medical centers consolidate procurement authority under centralized emergency preparedness officers.
Anti-Radiation Drugs Market Competitive Environment
On the supply side, the industry is structured around tiered specialization with distinct competitive vectors separating mass-production generic platforms from development-stage synthetic radioprotectants. Large-cap biologics manufacturers and small-molecule specialists occupy parallel rather than overlapping competitive spaces. Two strategic archetypes dominate: established pharmaceutical companies leveraging biologics manufacturing infrastructure, and biodefense contractors anchoring government-funded development programs. Competitive moves concentrate on strategic partnerships with national laboratories and portfolio diversification into non-thiol chemistries.
Within the biologics manufacturing tier, Amgen Inc. and Humanetics Corporation exemplify divergent platform strategies. Amgen Inc. represents large-cap infrastructure deployment for complex protein-based radioprotectants. Humanetics Corporation occupies a position emphasizing small-molecule radiomitigators derived from established pharmacological scaffolds. Soligenix Inc. anchors the biodefense contracting channel with government-funded development program participation.
| Leading Market Players |
|---|
| Amgen Inc. |
| Humanetics Corporation |
| Soligenix Inc. |
| Partner Therapeutics Inc. |
| Anbex Inc. |
| BTG International Inc. |
| RxBio Inc. |
| Onconova Therapeutics |
| Chrysalis BioTherapeutics Inc. |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on FDA-certified Animal Rule validation facilities determines both the steep premium commanded by validated radioprotectant manufacturers and the geographic clustering of production capacity around national laboratory complexes in Maryland and Virginia. This concentration creates pricing tier spreads exceeding standard pharmaceutical margins while forcing buyers into long-term offtake contracts with guaranteed surge clauses.
Pricing Analysis
Next-generation synthetic non-thiol radioprotectants command substantial premiums over legacy cysteamine-based compounds with narrow therapeutic indices. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA Animal Rule validation status, EMA dual-jurisdiction compliance, and biodefense contracting tier. Pricing pressure stems from generic potassium iodide manufacturers competing on federal stockpile rotation contracts with compressed margins. Military procurement officers demonstrate lowest price sensitivity due to classified threat assessment protocols, while civilian emergency preparedness programs face budgetary constraints.
Supply Chain Analysis
Contract manufacturing concentration rests with specialized radiation biology facilities partnered with national laboratories in the United States, complemented by European CMOs achieving EMA decentralized manufacturing compliance for potassium iodide. Active pharmaceutical ingredient sourcing draws from established thiol chemistry producers in India and China, with synthetic radioprotectant precursors anchored in Swiss and German specialty chemical clusters. Single-source vulnerability concentrates in aging reactor infrastructure for isotope-labeled compounds. Distribution runs through the Strategic National Stockpile logistics network and parallel European emergency preparedness frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in radiation biology training and dosimetry assessment are expanding faster than pharmaceutical product sales, creating recurring revenue layers with superior retention characteristics.
For Market Incumbents: Entrench position through backward integration into synthetic radioprotectant precursor manufacturing and captive supply of Animal Rule validation facility partnerships. Consolidation around non-thiol chemistry platforms defends against generic erosion of legacy thiol compounds. FDA emergency use authorization pathway expertise constitutes a defendable moat against emerging entrants lacking regulatory dossier experience. For New Entrants and Emerging Players: Geographic underpenetration in Japan's METI-coordinated nuclear emergency protocols offers procurement channels beyond saturated Western biodefense markets. White-space targets include cytokine modulation combination therapies and sublingual delivery formats for compromised gastrointestinal function. Go-to-market positioning should emphasize dual-jurisdiction compliance investment to unlock EMA procurement alongside FDA channels. For Investors and Strategic Acquirers: Specialized toxicology expertise holders with national laboratory partnerships represent the most defensible acquisition archetype in this market. Long-term viability hinges on synthetic radioprotectant platform validation timelines and stockpile rotation contract renewal patterns. Monitor FDA Animal Rule guidance revisions as the critical inflection signal for development pipeline prioritization.| Strategic Initiative | Industry Significance |
|---|---|
| Animal Rule Validation Partnership | Secures FDA efficacy pathway for radiological countermeasures without human clinical trials. |
| Synthetic Radioprotectant Platform Development | Non-thiol chemistries extend shelf-life beyond legacy thiol compound instability constraints. |
| Dual-Jurisdiction Compliance Investment | EMA-FDA parallel dossier preparation expands addressable procurement beyond single-market dependence. |
| Biodefense Contracting Channel Anchoring | Multi-year development agreements with HHS provide predictable revenue against commercial volatility. |
| Radiation Biology Workforce Pipeline Development | Academic center partnerships address specialized toxicology expertise scarcity constraining expansion. |
Study Parameters
A spread of perspectives from biodefense procurement officers, radiation oncology formulary directors, FDA regulatory affairs specialists, and national laboratory toxicologists converged on the working assumptions underlying this analysis. Primary interviews combined with secondary validation from FDA Animal Rule guidance documents, EMA Committee for Medicinal Products for Human Use radiological preparedness frameworks, Strategic National Stockpile procurement records, and hospital emergency preparedness mandate filings. Bottom-up segmentation modeling triangulated against top-down federal budget appropriation analysis.
Demand-supply-balance framing anchored the forecast framework across the analysis window, with patient volume projections in radiation oncology, federal stockpiling mandates, and military medical service requirements constituting demand inputs. Segmentation dimensions encompassed product chemistry platform, therapy area application, end-user procurement authority, and delivery mode stability requirements. CAGRs derived from weighted scenario analysis across biodefense threat assessment revisions and radioprotectant clinical integration timelines.
Practitioners should monitor FDA guidance revisions on synthetic radioprotectant validation, EMA decentralized manufacturing compliance enforcement, and isotope reactor infrastructure investments for early signals requiring forecast adjustment. Quarterly review of federal stockpile rotation contract awards and radiation oncology protocol adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Carbapenem Antibiotics Market
Pharmaceuticals
Global Corticosteroids Market
Pharmaceuticals
Omega 3 Prescription Drugs Market
Pharmaceuticals
Emergency Contraceptive Pills Market
Pharmaceuticals
Pharmaceuticals Lipids Market
Pharmaceuticals
Influenza Antiviral Market
Pharmaceuticals
Anthrax Treatment Market
Pharmaceuticals
Global Ebola Virus Vaccine Market
Pharmaceuticals
Germany Pharmaceutical 3PL Market
Pharmaceuticals
Global Intravenous Immunoglobulin Market
Pharmaceuticals
Global Anti-Neoplastic Agents Market
Pharmaceuticals
Global Hepatitis a Vaccine Market
Pharmaceuticals
Urticaria Drugs Market
Pharmaceuticals
Trenbolone Enanthate Market
Pharmaceuticals
Latin America Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Global Manidipine Hydrochloride Market