
 Oil and Gas Field Services Market | 2026-2036
Oil and Gas Field Services Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Field Services Market Analysis
Integrated service bundling is repositioning procurement patterns across offshore developments. Schlumberger Limited leverages its digital platform stack to anchor long-term drilling contracts. Halliburton Company competes through specialized pressure pumping fleets in North American shale basins. Baker Hughes Company differentiates via turbomachinery integration that extends from reservoir characterization through production optimization.
Oil and gas field services encompass the specialized equipment, technical labor, and project management required to drill, complete, maintain, and enhance hydrocarbon wells, typically operating at pressures exceeding 10,000 psi and temperatures above 150°C in deepwater environments. Drilling services command the largest revenue share due to capital intensity and rig day-rate structures. Well completion represents the fastest-growing service category as operators target longer lateral lengths and higher stage counts in unconventional reservoirs. National oil companies and international oil companies constitute the dominant end-user segment, though independent operators are gaining share through private-equity-backed consolidation.
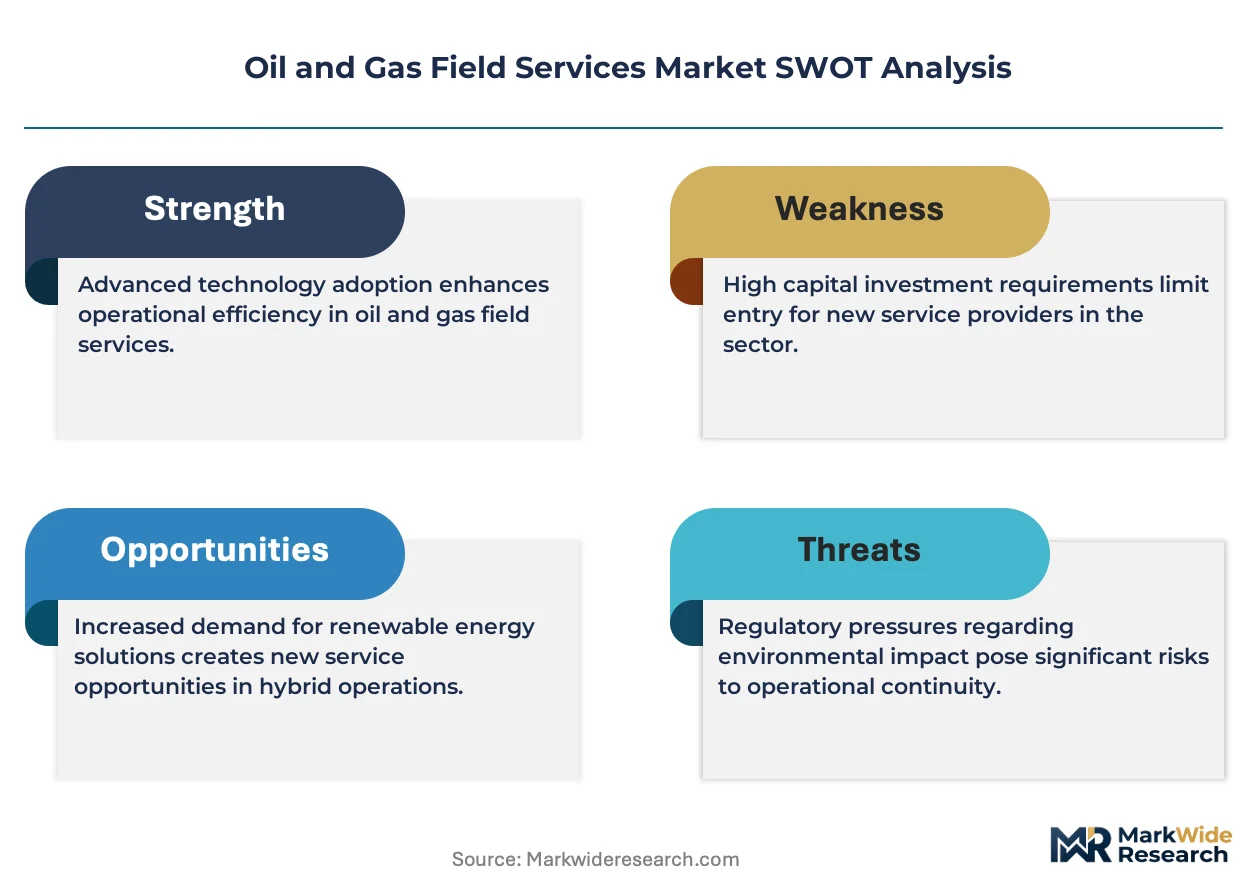
The US EPA enforces methane performance standards under the Clean Air Act that mandate leak detection and repair protocols across production facilities. Brazil's ANP requires local content minimums for offshore equipment procurement, shaping supplier qualification criteria. The EU Green Deal and F-Gas Regulation restrict high-global-warming-potential fluids in compression equipment, redirecting R&D toward alternative chemistries. Stakeholders must monitor regulatory divergence between jurisdictions and calibrate compliance investments against project return thresholds.
Market Dynamics
Deepwater exploration budgets are redirecting capital toward longer-cycle offshore developments, compressing demand for short-cycle shale services while expanding subsea engineering requirements in frontier basins.
Growth Catalysts
- Pre-salt development mandates:Brazil's ANP local content rules are forcing international oil companies to qualify domestic suppliers for subsea trees and riser systems.
- Methane detection automation:The US EPA's updated leak detection and repair protocols are accelerating sensor deployment across Permian and Bakken production facilities.
- Subsea tieback economics:Operators in Guyana's Stabroek Block are sanctioning satellite field developments that bypass fixed platform infrastructure.
Market Restraints
- Specialized vessel scarcity:Heavy-lift crane vessels capable of installing 2,000-ton modules command day rates exceeding $400,000, constraining project scheduling flexibility.
- Alloy supply concentration:Super duplex stainless steel forgings for high-pressure wellheads depend on a limited supplier base in Western Europe and Japan.
- Permitting timeline extension:The US Bureau of Ocean Energy Management has lengthened environmental review periods for Gulf of Mexico drilling plans.
Strategic Opportunities
- Carbon capture retrofit engineering:Existing offshore platform infrastructure in the UK North Sea qualifies for government-backed carbon storage licensing rounds.
- Electrification of drilling rigs:Grid-connected power systems are displacing diesel generators in Norway's mature basin operations.
- Decommissioning liability management:Mexico's CNH is transferring late-life asset abandonment obligations to specialized contractors through integrated service agreements.
Industry Challenges
- Subsea controls engineering talent:The specialized skill set combining hydraulics, electronics, and metallurgy faces generational replacement gaps in Aberdeen and Houston.
- Legacy SCADA integration:Brownfield production facilities require protocol translation layers to connect 1990s-vintage control systems with modern digital twins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Field Services Market |
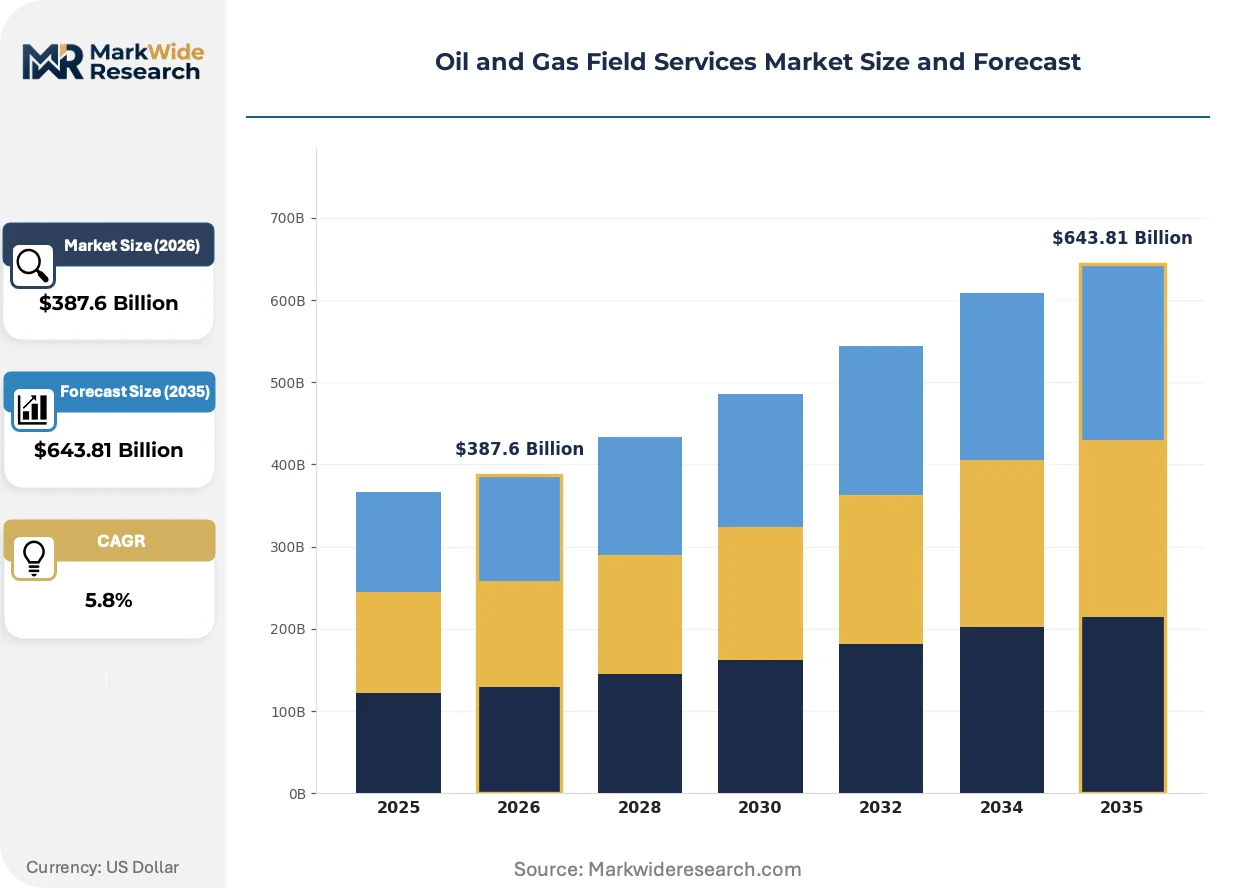
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $643.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Drilling Services, Well Completion, Production Services, Workover Services Equipment Type: Drilling Rigs, Pumping Units, Pressure Pumping Equipment, Compression Equipment Application: Onshore Operations, Offshore Operations, Exploration, Production End User: Independent Operators, National Oil Companies, International Oil Companies, Service Companies |
| Companies Covered | Schlumberger Limited, Halliburton Company, Baker Hughes Company, Weatherford International, China Oilfield Services Limited, TechnipFMC plc, Nabors Industries, National Oilwell Varco, Expro Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Field Services Market Emerging Trajectories
Digital thread architectures are collapsing the traditional separation between reservoir modeling and real-time drilling optimization, enabling closed-loop decision systems that compress cycle times.
Modular subsea processing units are decentralizing field development economics by eliminating topside facility requirements. Petrobras and ExxonMobil are deploying standardized seabed separation modules across pre-salt and deepwater Guyana developments. This architecture is decentralizing project sanctioning authority from corporate headquarters to basin-level asset teams.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in offshore compression equipment, redirecting turbomachinery R&D toward ammonia and CO2 refrigerant cycles. Equipment suppliers must recertify product lines under the updated MDR machinery safety framework. North Sea operators face the most immediate compliance deadlines, accelerating fleet replacement decisions.
Integrated service contracting is displacing discrete equipment procurement in offshore developments. National oil companies in Brazil and Guyana now bundle drilling, completion, and subsea installation under single-source agreements. This concentration is most visible in the pre-salt layer, where operators prioritize schedule certainty over unit cost minimization.
Oil and Gas Field Services Market Segmentation
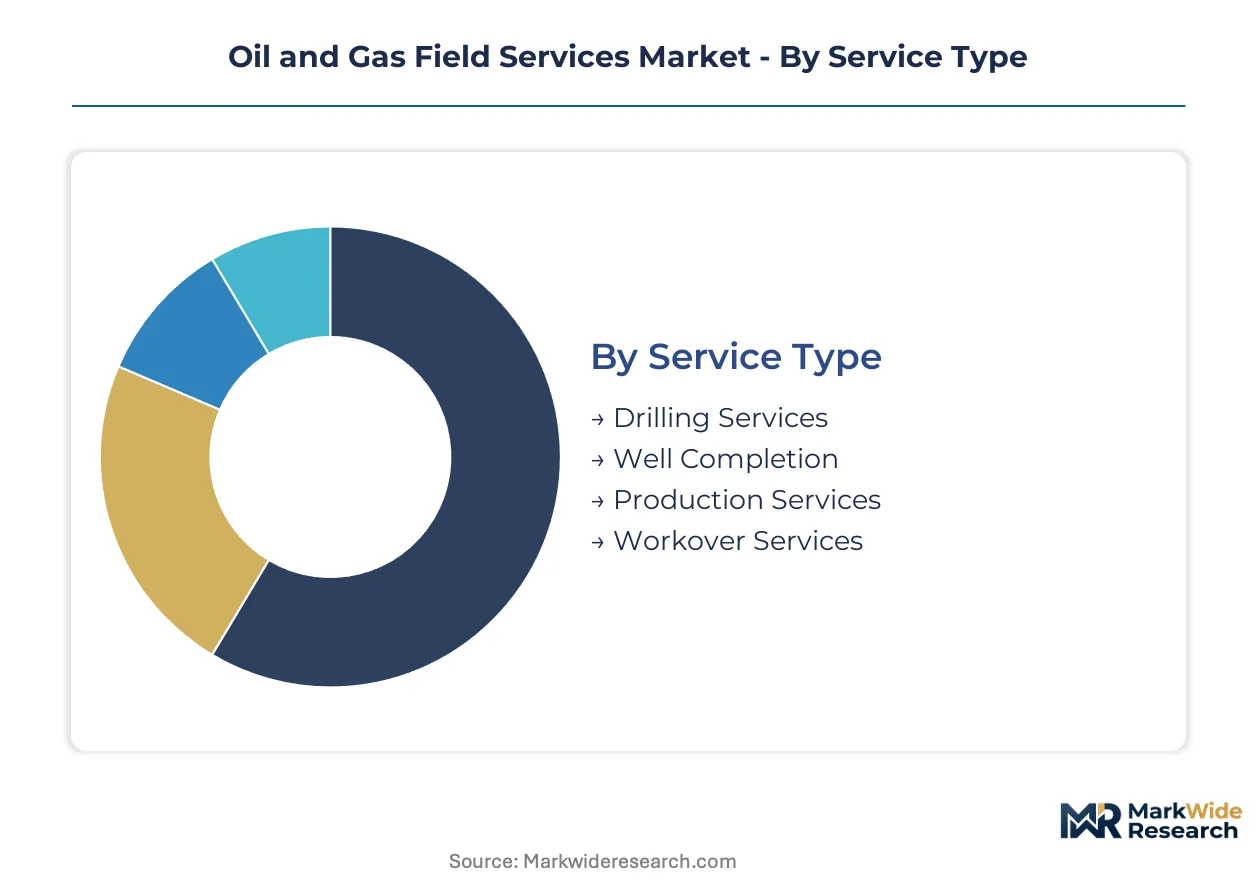
Service differentiation in oil and gas field services determines contract structures, capital allocation, and margin profiles across the value chain. Procurement patterns vary sharply between short-cycle shale work and multi-year offshore developments, requiring suppliers to calibrate capabilities against specific buyer archetypes.
Service Type:
Capital intensity and contract duration drive buyer selection criteria across service categories.
- Drilling Services:Rig day-rate structures dominate revenue recognition, with ultra-deepwater drillships commanding premiums above $400,000 daily. Demand concentrates in Brazil's pre-salt basins and Guyana's Stabroek Block, where ExxonMobil and Petrobras prioritize schedule certainty over unit cost minimization.
- Well Completion:Multi-stage hydraulic fracturing and intelligent completion systems enable longer lateral lengths in unconventional reservoirs. North American independent operators are expanding stage counts per well, pushing service intensity higher in Permian and Bakken sub-basins.
- Production Services:Artificial lift optimization and flow assurance maintain hydrocarbon throughput across mature fields.
- Workover Services:Well intervention and recompletion activities extend asset life in declining basins.
Volume sits with Drilling Services; growth tilts toward Well Completion.
Equipment Type:
Specification requirements diverge between high-pressure unconventional applications and corrosive offshore environments.
- Drilling Rigs:AC-powered top drives and automated pipe handling reduce crew requirements while improving safety metrics. Onshore super-spec rigs in the US Southwest now feature 7,500-psi pressure ratings and 1.5-million-pound hook loads.
- Pressure Pumping Equipment:Electric fracturing fleets are displacing diesel-powered units in emissions-sensitive basins. Proppant delivery systems and high-pressure pumps face utilization pressure as operator drilling budgets compress.
- Pumping Units:Beam pumps and progressive cavity systems dominate artificial lift installations.
- Compression Equipment:Gas gathering and processing applications require centrifugal and reciprocating compression packages.
Revenue concentrates in Drilling Rigs; specification innovation centers on Pressure Pumping Equipment.
Application:
Development economics and regulatory exposure shape operator preferences across operating environments.
- Offshore Operations:Subsea tiebacks and floating production systems enable frontier basin development without fixed platform infrastructure. Guyana's Stabroek Block developments exemplify this architecture, with ExxonMobil sanctioning satellite fields that bypass traditional topside requirements.
- Onshore Operations:Pad drilling and multi-well zipper fracs maximize surface efficiency in shale basins. US independent operators are consolidating drilling locations to reduce surface footprint and streamline supply logistics.
- Exploration:Seismic acquisition and appraisal drilling carry high technical risk and capital exposure.
- Production:Sustained hydrocarbon extraction from proven reservoirs generates recurring service demand.
Activity levels favor Onshore Operations; capital allocation is shifting toward Offshore Operations.
End User:
Contracting sophistication and counterparty risk tolerance vary systematically across buyer categories.
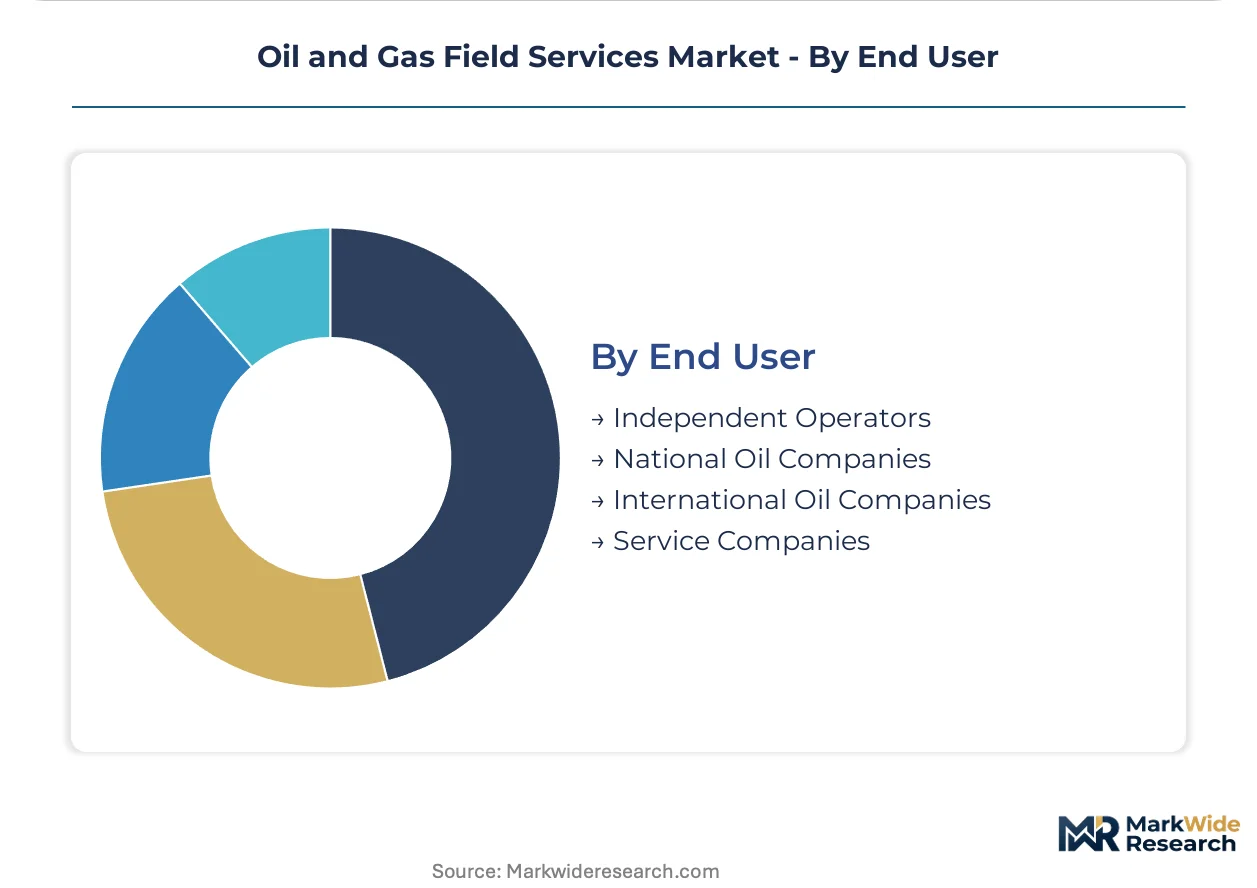
- International Oil Companies:Integrated project management and long-term alliance agreements anchor procurement strategies. ExxonMobil and Shell prioritize digital platform integration and performance-based contracting across drilling and completion portfolios.
- National Oil Companies:Local content mandates and technology transfer requirements shape supplier qualification. Brazil's ANP rules force international service providers to qualify domestic fabricators for subsea equipment procurement.
- Independent Operators:Private-equity-backed consolidation is expanding scale and bargaining power in North American shale basins.
- Service Companies:Subcontracting relationships and equipment leasing arrangements support tier-2 and tier-3 market participation.
Contract value concentrates with International Oil Companies; procurement flexibility is expanding fastest among Independent Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes more oilfield services than any other nation while Brazil and Guyana drive frontier exploration investment. Production growth concentrates in offshore basins with pre-salt geology. Regulatory divergence between EPA methane rules and Brazil's local content mandates shapes supplier qualification requirements.
United States
Permian Basin operators deploy electric fracturing fleets and automated drilling rigs to meet EPA methane performance standards. The Bureau of Ocean Energy Management has extended environmental review timelines for Gulf of Mexico drilling plans. Houston anchors the global headquarters concentration for drilling contractors and pressure pumping specialists.
Brazil
Pre-salt development mandates from ANP require international operators to qualify domestic fabricators for subsea trees and riser systems. Petrobras sanctions satellite field developments that bypass fixed platform infrastructure through subsea tieback architectures. Rio de Janeiro hosts the engineering cluster coordinating vessel mobilization for Búzios and Mero field expansions.
Guyana
ExxonMobil's Stabroek Block developments generate concentrated demand for deepwater drilling and subsea installation services. The government negotiates production sharing agreements that prioritize local supplier development alongside international contractor participation. Georgetown functions as the logistics coordination hub for offshore supply base operations.
Norway
Grid-connected drilling rig electrification advances under government-backed carbon reduction programs targeting North Sea mature basin operations. The F-Gas Regulation accelerates turbomachinery replacement with ammonia and CO2 refrigerant cycles. Stavanger maintains the subsea engineering talent pool despite generational replacement gaps in controls specialization.
Saudi Arabia
Aramco's long-term drilling contracts emphasize integrated project management and digital platform integration across conventional and unconventional portfolios. Local content requirements intensify for in-country manufacturing of wellheads and artificial lift systems. Dhahran anchors the R&D concentration for reservoir characterization and production optimization technologies.
Oil and Gas Field Services Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct capability tiers. Tier-1 integrated service providers anchor long-term alliances through digital platform stacks and bundled contracting structures. Tier-2 equipment specialists concentrate on pressure pumping fleets, subsea hardware, or directional drilling tools. Competitive moves center on integrated service contracting expansion and electrification technology partnerships.
Among Houston-based integrated service providers, Schlumberger Limited and Halliburton Company exemplify the digital-platform tier anchoring multi-year offshore development contracts. Baker Hughes Company occupies a position within the turbomachinery and subsea systems specialization cluster. China Oilfield Services Limited represents the state-backed national champion archetype with fleet scale advantages in Asia-Pacific basins.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International |
| China Oilfield Services Limited |
| TechnipFMC plc |
| Nabors Industries |
| National Oilwell Varco |
| Expro Group |
| Others |
Supply Flow & Price Mechanics
Electric fracturing fleet deployment across Permian Basin operations is compressing diesel-powered equipment margins while concentrating supplier qualification authority among emissions-compliant vendors. This technology transition simultaneously raises capital barriers for service tier entry and redirects procurement volume toward integrated providers with grid-connection capabilities.
Pricing Analysis
Cost-down pressure on pressure pumping services accelerates as electric fleet utilization spreads through emissions-sensitive basins. Project-based contracting dominates offshore developments, with three-tier pricing structure across premium, standard, and economy levels differentiated by equipment specification and crew certification grade. Price differentiation traces to EPA methane compliance tier and local content fulfillment status under Brazil's ANP rules. Independent operators in North American shale exhibit highest price sensitivity, while pre-salt developers prioritize schedule certainty over unit cost minimization.
Supply Chain Analysis
Specialized welding and controls engineering talent shortages in Aberdeen and Houston constrain super duplex forging throughput for high-pressure wellheads. Manufacturing concentration rests on Western European and Japanese metallurgical suppliers for critical subsea components, with raw material dependencies spanning nickel alloy feedstock, high-pressure hydraulic systems, and subsea electronics modules. Single-source vulnerability concentrates in heavy-lift crane vessel availability, where limited fleet capacity commands premium day rates. Distribution runs through integrated service contractors bundling discrete equipment categories under single-source agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heavy-lift vessel scarcity and specialized alloy forging bottlenecks prop pricing power for qualified suppliers across deepwater developments. This supply-constrained structure favors incumbents with anchored fleet positions and long-term charter agreements.
For Market Incumbents: Anchor long-term contracting relationships through digital platform integration and performance-based drilling alliances. Defensive consolidation should prioritize backward integration into subsea controls engineering talent pools in Aberdeen and Stavanger to offset generational replacement gaps. Threat exposure concentrates in electrification technology partnerships that bypass traditional equipment procurement channels.
For New Entrants and Emerging Players: Enter via carbon capture retrofit engineering for UK North Sea platform infrastructure, where government-backed licensing rounds create immediate service demand. White-space availability concentrates in decommissioning liability management under Mexico's CNH integrated service agreements. Go-to-market positioning should emphasize specialized SCADA protocol translation for brownfield digital twin integration.
For Investors and Strategic Acquirers: Re-rating potential sits with turbomachinery specialists possessing ammonia refrigerant cycle certification under EU F-Gas Regulation timelines given accelerated North Sea fleet replacement decisions. Long-term viability over the 5-10 year horizon hinges on electrification technology positioning and subsea engineering talent depth. Signal to monitor: EPA methane rule enforcement intensity across Permian production facilities as indicator of sensor deployment demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Service Contracting Expansion | Bundling drilling, completion, and subsea installation under single-source agreements reduces counterparty risk for Petrobras and ExxonMobil developments. |
| Electrification Technology Partnership | Grid-connected rig power systems displace diesel generators in Norway's mature basin operations under government-backed carbon reduction programs. |
| Carbon Capture Retrofit Engineering | Existing UK North Sea platform infrastructure qualifies for government-backed carbon storage licensing rounds requiring specialized contractor capabilities. |
| Subsea Controls Talent Acquisition | Hydraulics-electronics-metallurgy skill gaps in Aberdeen and Houston constrain project execution capacity for pre-salt and deepwater developments. |
| Local Content Qualification Investment | Brazil's ANP mandates force international service providers to certify domestic fabricators for subsea trees and riser systems procurement. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with drilling contractors, subsea engineering directors, procurement leads at international oil companies, and regulatory affairs specialists at national oil companies. Secondary validation drew from ANP local content reports, EPA enforcement disclosures, SEC 10-K filings from listed service providers, and vessel mobilization databases. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segment-level granularity modeled service type, equipment category, operating environment, and end-user contracting sophistication across the projection horizon. CAGRs derived from regression analysis against exploration budget trajectories, rig count forecasts, and subsea installation backlogs. Industry-specific inputs incorporated pre-salt development sanctioning timelines under Brazil's ANP framework and EPA methane detection equipment deployment mandates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence between EPA methane rules and EU F-Gas Regulation timelines. Forecasts reflect documented assumptions regarding exploration budget allocation, vessel availability, and alloy supply continuity. Material deviation in pre-salt sanctioning velocity or heavy-lift fleet expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Underwater Monitoring System for Oil and Gas Market
Oil & Gas
Oil and Gas Fittings Market
Oil & Gas
Indonesia Coal Market
Oil & Gas
Riserless Light Well Intervention Market
Oil & Gas
Crude Oil Assay Testing Services Market
Oil & Gas
Microbial Enhanced Oil Recovery Market
Oil & Gas
Malaysia Oilfield Services Market
Oil & Gas
Expandable Liner Hanger System Market
Oil & Gas
Digital Oilfield Services Market
Oil & Gas
Middle-East and Africa Frac Stack Market
Oil & Gas
Russian Federation Oil and Gas Midstream Market
Oil & Gas
Rig and Oilfield Mats Market
Oil & Gas
Peru Oil and Gas Downstream Market
Oil & Gas
Injection Well Market
Oil & Gas
Asia-Pacific Natural Gas Market
Oil & Gas
Middle-East and Africa Pigging Services Market