
 Middle East Natural Gas Market | 2026-2036
Middle East Natural Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Natural Gas Market Foresight
The UAE's net-zero by 2050 commitment is pivoting procurement toward lower-carbon gas supplies across Middle East utilities. Saudi Aramco leverages its master gas system to sustain domestic supply while scaling blue hydrogen pilot projects. QatarEnergy anchors global LNG export capacity through North Field East and West expansion phases. ADNOC competes on cost efficiency at its Hail and Ghasha sour gas developments.
Middle East natural gas encompasses hydrocarbon reservoirs with methane concentrations typically exceeding 85 percent, often requiring acid gas removal or nitrogen rejection before pipeline injection or liquefaction. The resource serves as feedstock for power generation, petrochemical synthesis, and increasingly hydrogen production across Gulf industrial zones. Liquefied natural gas dominates export monetization through Qatari mega-trains and emerging UAE floating facilities. Pipeline gas retains structural priority in Saudi Arabia's industrial corridor linkage between Ghawar and Jubail. Compressed natural gas occupies a niche in fleet transportation across Iranian urban centers where pipeline density supports retail dispensing infrastructure.
Saudi Arabia's national regulator enforces gas flaring reduction mandates that reshape field development economics, while Iran's national petroleum framework conditions foreign participation on technology transfer for South Pars pressure maintenance. The UAE's environmental standards for sulfur recovery at sour gas plants exceed regional baselines and filter equipment supplier qualification. Stakeholders must monitor carbon border adjustment mechanisms in European destination markets that threaten to discount unabated Middle East LNG cargoes.
Market Dynamics
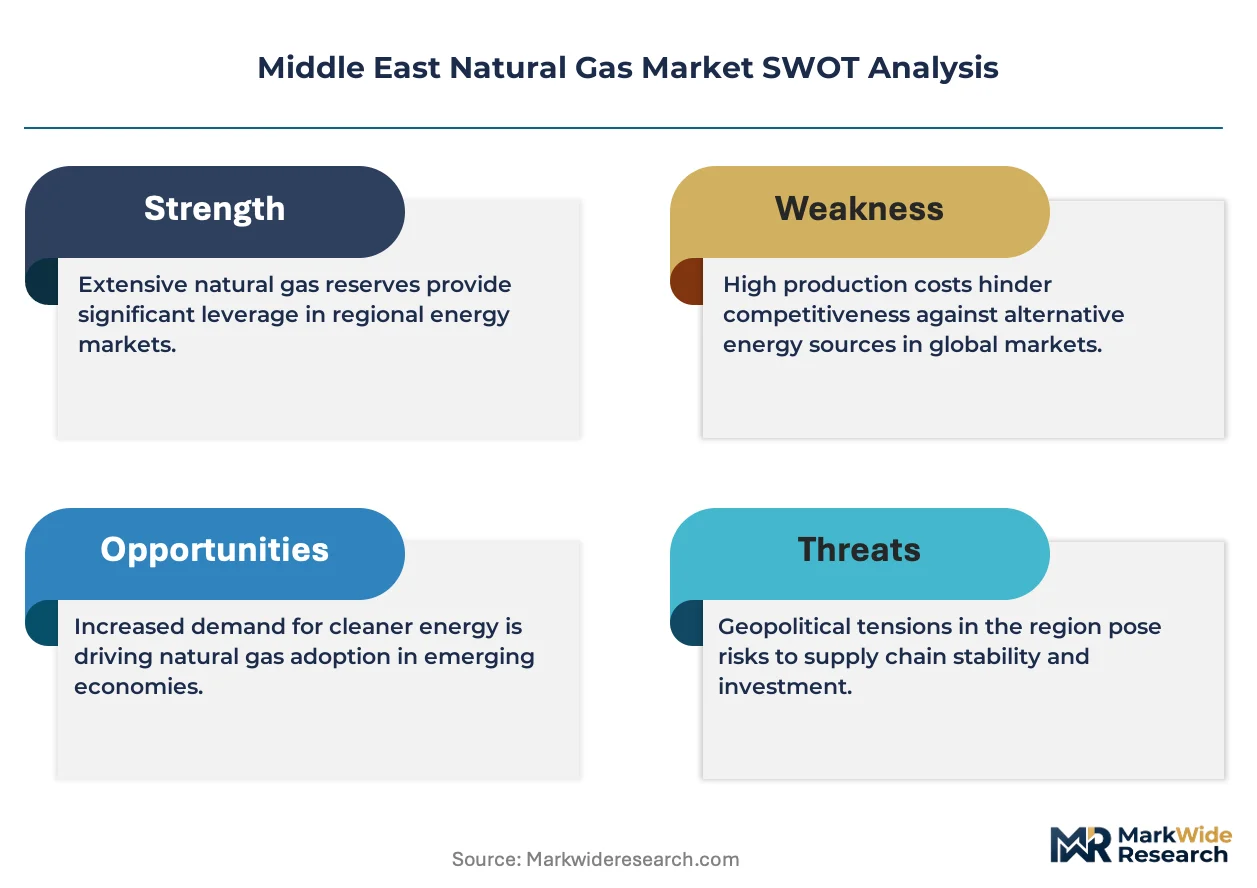
Carbon border adjustment mechanisms in European destination markets are forcing Gulf producers to integrate carbon capture at upstream facilities or face cargo discounts. QatarEnergy, Saudi Aramco, and ADNOC now compete on certified low-carbon LNG rather than volume alone.
Growth Catalysts
- North Field Expansion:QatarEnergy's mega-train additions anchor incremental supply capacity serving Asian and European offtake contracts. Methane concentrations exceeding 85 percent reduce processing intensity per unit exported.
- Saudi Green Initiative:Domestic carbon capture mandates at sour gas plants redirect associated gas toward blue hydrogen pilot projects rather than flaring. The framework incentivizes pressure maintenance technology deployment at mature reservoirs.
- UAE Net-Zero Procurement:Emirates-based utilities now contract for certified lower-carbon gas supplies, filtering equipment vendor qualification through sulfur recovery standards that exceed regional baselines.
Market Restraints
- South Pars Technology Transfer Conditions:Iran's petroleum framework requires foreign partners to surrender pressure maintenance intellectual property, deterring capital deployment at the world's largest shared reservoir.
- Acid Gas Removal Cost Structure:Sour gas developments at Hail, Ghasha, and South Pars require amine-based treatment systems that consume 8-12 percent of produced energy, eroding field economics at marginal wells.
- European Carbon Border Adjustment:Unabated Middle East LNG faces prospective tariff exposure in EU destination markets, compressing netbacks for producers without certified capture integration.
Strategic Opportunities
- Iran Post-Sanctions Rehabilitation:South Pars phases 11-24 await international drilling rigs and subsea installation capacity, representing latent supply potential exceeding Qatari expansion volumes.
- Blue Hydrogen Feedstock Pivot:Saudi Arabia's master gas system can redirect methane toward hydrogen cracking facilities at Jubail Industrial City, capturing carbon dioxide for enhanced oil recovery.
- Floating LNG Monetization:UAE offshore sour gas fields at Ghasha suit compact liquefaction vessels avoiding pipeline construction through congested coastal zones.
Industry Challenges
- Subsea Compression Engineering Shortage:North Field East and West phases require electrically driven seabed compressors; qualified installation contractors concentrate among Norwegian and Italian specialists.
- Sulfur Recovery Unit Certification Delays:UAE environmental standards for Claus process emissions extend equipment qualification timelines by 14-18 months versus regional baselines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Natural Gas Market |
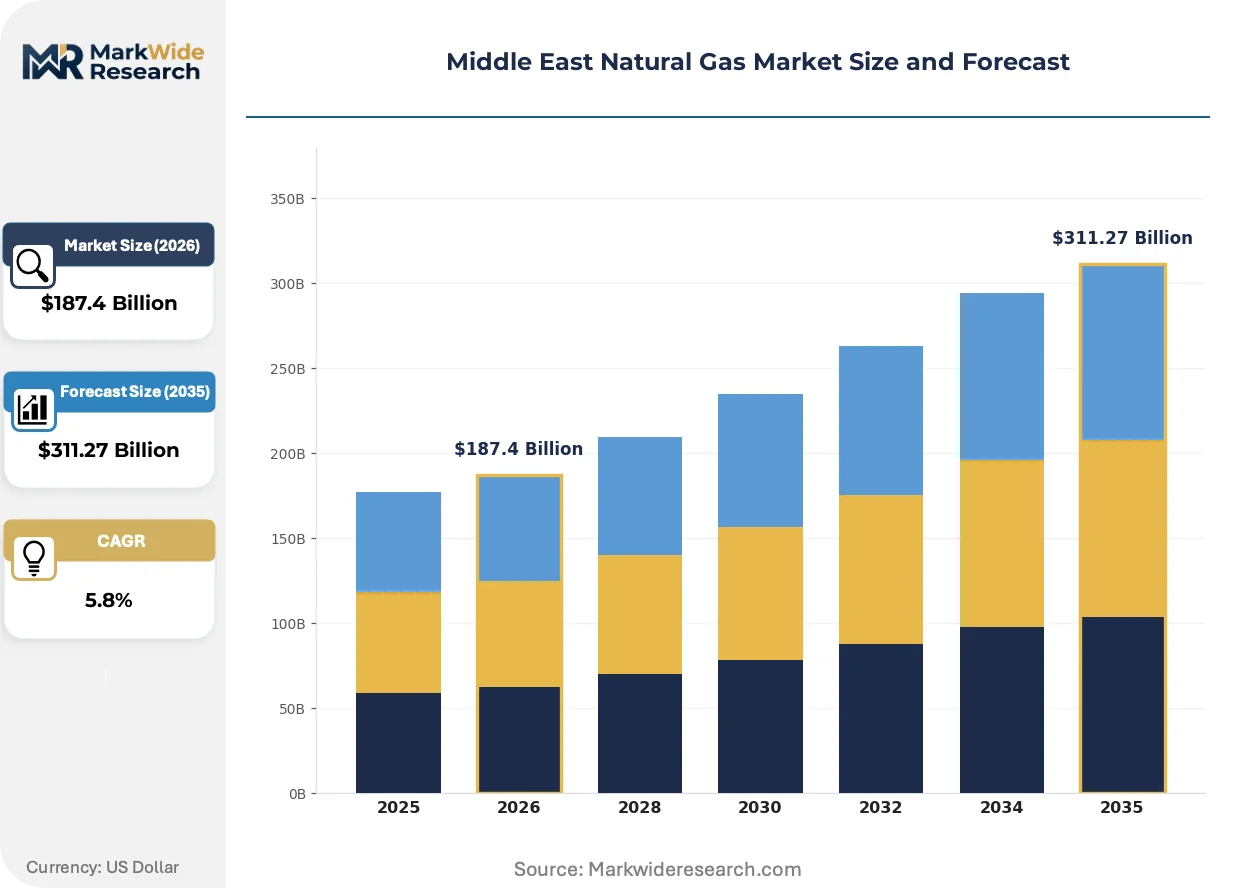
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquefied Natural Gas, Compressed Natural Gas, Gas-to-Liquids, Pipeline Gas End User: Power Generation, Industrial Sector, Residential Market, Transportation Application: Heating, Cooking, Electricity Generation, Fuel Delivery Mode: Pipeline, Truck, Ship, Distribution Center |
| Companies Covered | National Iranian Oil Company (NIOC), ExxonMobil, Saudi Aramco, BP, TotalEnergies, QatarEnergy, Shell, Chevron, Abu Dhabi National Oil Company (ADNOC), Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Natural Gas Market Shifts & Advancements
Electrification of compression and liquefaction trains is reshaping operational emissions profiles across Gulf megaprojects. Digital reservoir management and modular processing units are compressing development cycles.
Subsea electric compression is overtaking platform-based gas reinjection at Qatar's North Field West expansion. QatarEnergy deploys seabed pumps eliminating surface facility footprints and halving offshore construction duration. This architecture is compressing project sanction-to-first-gas timelines below conventional North Sea benchmarks.
Saudi Arabia's gas flaring reduction mandates are forcing satellite field tiebacks into the master gas system rather than standalone processing. SFDA enforcement of zero-routine-flaring deadlines by 2030 redirects marginal field economics toward gathering network extensions. Producers respond by prioritizing reservoir clusters within 50 kilometers of existing trunk lines.
Buyer contracting patterns are hardening around certified carbon intensity clauses rather than destination flexibility. Japanese and South Korean utilities now require cargo-specific methane leakage documentation upstream of liquefaction. This specification is filtering supplier qualification toward integrated producers with reservoir-to-terminal emissions monitoring.
Middle East Natural Gas Market Segmentation
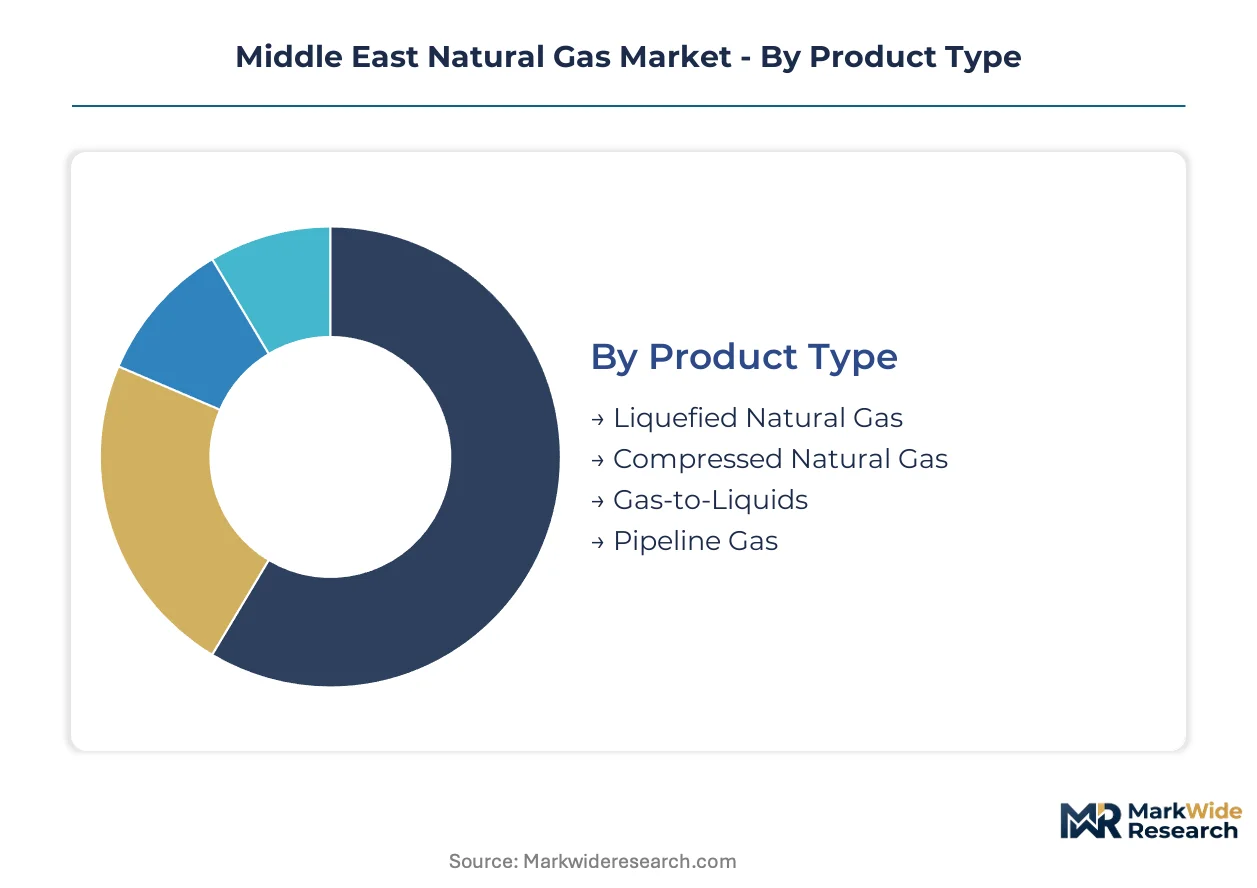
Middle East natural gas segmentation reveals how resource characteristics and infrastructure availability dictate monetization pathways. Methane concentration, acid gas content, and proximity to liquefaction facilities determine whether gas flows to power plants, chemical complexes, or export terminals.
Product Type:
Technology intensity and capital requirements separate pipeline-ready gas from processed derivatives requiring cryogenic or catalytic transformation.
- Liquefied Natural Gas:Cryogenic liquefaction at minus 162 degrees Celsius enables Qatari mega-trains and UAE floating facilities to serve Asian and European offtakers. QatarEnergy's North Field East and West expansions anchor regional capacity, with methane concentrations exceeding 85 percent reducing per-unit processing energy.
- Pipeline Gas:Dry gas with minimal acid gas content moves through Saudi Aramco's master gas system linking Ghawar to Jubail Industrial City. SFDA flaring reduction mandates accelerate tieback of satellite fields into existing trunk infrastructure.
- Compressed Natural Gas:Fleet transportation fuel in Iranian urban corridors where pipeline density supports retail dispensing at pressures above 200 bar.
- Gas-to-Liquids:Fischer-Tropsch synthesis converts methane to synthetic diesel and lubricants at Oman's Sur refinery complex.
Mature deployment sits with Pipeline Gas. Newer deployment is concentrated in Liquefied Natural Gas.
End User:
Customer scale and contract duration shape procurement patterns across utility, industrial, and distributed segments.
- Power Generation:Combined-cycle turbines across GCC states replace oil-burning steam units. Emirates-based utilities now require certified lower-carbon gas supplies under net-zero procurement frameworks.
- Industrial Sector:Petrochemical crackers and hydrogen production facilities at Jubail and Ruwais consume methane as feedstock. ADNOC's Hail and Ghasha sour gas developments compete on cost efficiency for ammonia and methanol synthesis.
- Residential Market:Distribution networks in Iranian cities and Saudi population centers serve heating and cooking loads through pressure-regulated municipal systems.
- Transportation:Bus and taxi fleets in Tehran and Dubai operate on compressed natural gas where retail infrastructure exists.
Industrial Sector contracts carry the longest duration. Power Generation is expanding most quickly as oil displacement accelerates.
Application:
End-use function determines specification requirements from heating value to sulfur content limits.
- Electricity Generation:Gas turbines require consistent methane content and minimal hydrogen sulfide to prevent hot corrosion of blade coatings. Saudi Arabia's Green Initiative mandates carbon capture integration at sour gas plants serving power utilities.
- Fuel:Marine bunkering and heavy transport applications accept wider specification ranges. QatarEnergy certifies cargo-specific methane leakage documentation for Japanese and South Korean buyers.
- Heating:Residential and commercial boilers operate on pipeline gas with standardized calorific values across UAE distribution networks.
- Cooking:Municipal distribution systems deliver odorized gas to household appliances with pressure regulation at building entry points.
Heating and Cooking represent established demand basins. Electricity Generation is gaining share fastest as Gulf utilities decarbonize.
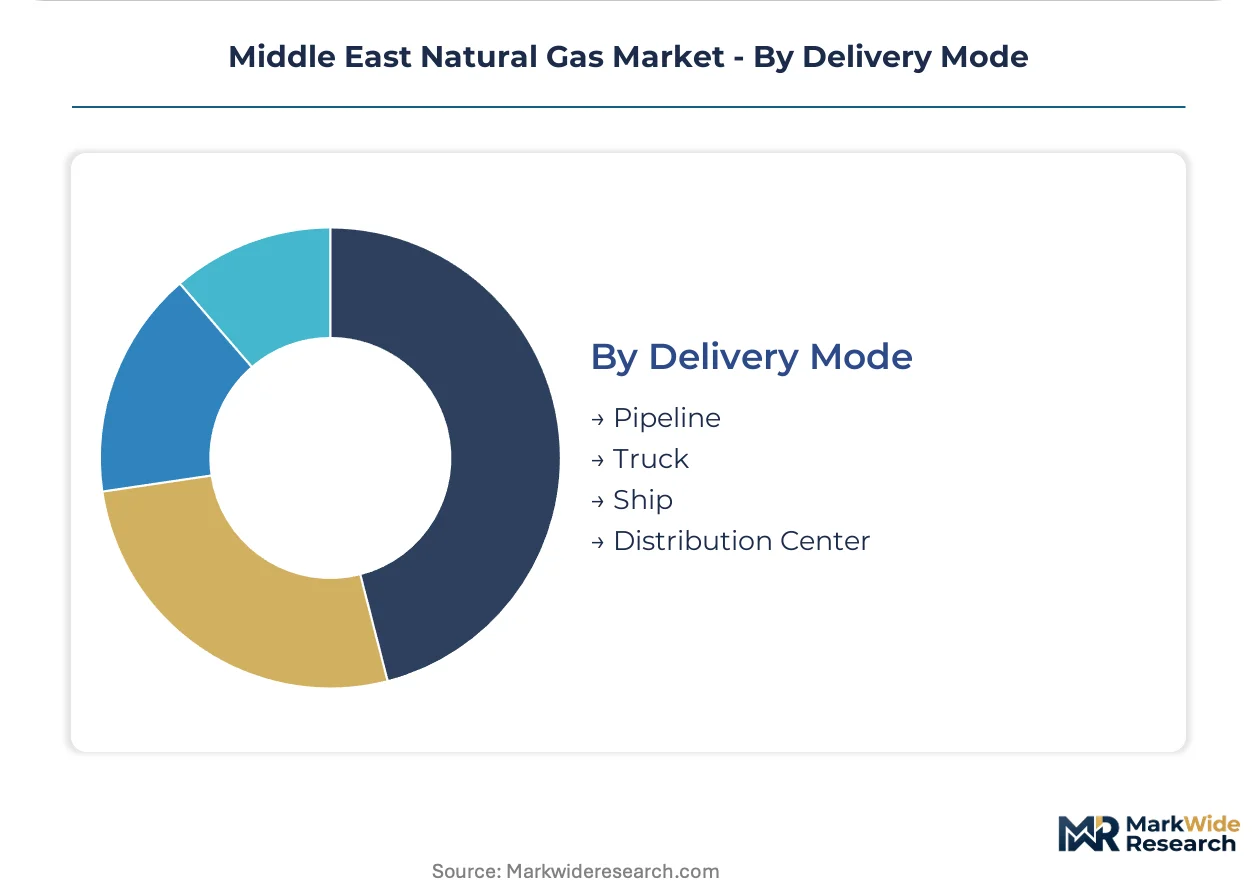
Delivery Mode:
Physical infrastructure constraints and cargo scale dictate transportation economics across the value chain.
- Pipeline:Saudi Aramco's master gas system and Iranian trunk lines move dry gas to industrial corridors. SFDA zero-routine-flaring deadlines by 2030 prioritize reservoir clusters within 50 kilometers of existing infrastructure.
- Ship:Q-Max and Q-Flex vessels transport Qatari LNG to Asian terminals. European carbon border adjustment mechanisms threaten netbacks for unabated cargoes.
- Truck:Compressed natural gas tube trailers serve industrial facilities beyond pipeline reach in Oman's interior.
- Distribution Center:Coastal storage and regasification terminals at Fujairah and Sohar buffer supply for regional offtakers.
Pipeline infrastructure carries mature volumes. Ship-based delivery is climbing the fastest as LNG export capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle East produces more natural gas than it consumes, with Qatar and Saudi Arabia driving surplus capacity while Iran holds latent reserves constrained by sanctions. Export infrastructure concentrates in Qatari mega-trains and Saudi pipeline corridors, whereas Iranian fields await rehabilitation.
Qatar
QatarEnergy's North Field East and West expansions anchor regional LNG export growth through electrically driven seabed compressors. The national petroleum regulator mandates methane leakage documentation for all cargoes bound for Asian utilities. Industrial activity clusters at Ras Laffan Industrial City, where mega-train additions compress sanction-to-first-gas timelines below conventional benchmarks.
Saudi Arabia
Saudi Aramco's master gas system links Ghawar field production to Jubail Industrial City petrochemical complexes and power utilities. SFDA enforces zero-routine-flaring deadlines by 2030, redirecting satellite field economics toward gathering network extensions. Carbon capture integration at sour gas plants serves blue hydrogen pilot projects under the Saudi Green Initiative framework.
United Arab Emirates
ADNOC competes on cost efficiency at Hail and Ghasha sour gas developments while Emirates-based utilities contract for certified lower-carbon supplies. MOHAP environmental standards for sulfur recovery exceed regional baselines, extending Claus process equipment qualification timelines. Fujairah's coastal storage and regasification terminals buffer supply for regional offtakers beyond pipeline reach.
Iran
NIOC manages South Pars phases 11-24, representing latent supply potential exceeding Qatari expansion volumes pending sanctions relief. The national petroleum framework conditions foreign participation on pressure maintenance technology transfer, deterring capital deployment. Tehran's compressed natural gas retail infrastructure serves bus and taxi fleets where pipeline density supports municipal dispensing.
Middle East Natural Gas Market Competitive Landscape
The competitive structure tilts toward state-controlled national oil companies with integrated upstream-to-export architectures. QatarEnergy, Saudi Aramco, and ADNOC dominate capacity decisions through sovereign balance sheet backing rather than project finance constraints. International oil companies occupy non-operating partner positions, contributing subsea engineering and liquefaction technology in exchange offtake rights. Competitive moves concentrate on carbon intensity certification and blue hydrogen feedstock positioning rather than conventional volume expansion.
Among state-controlled producers, QatarEnergy and Saudi Aramco exemplify the integrated NOC archetype with captive liquefaction and pipeline infrastructure. ADNOC occupies a position within the cost-competitive sour gas specialist tier, leveraging UAE environmental standards to filter equipment vendor qualification. International partners including ExxonMobil, Shell, and TotalEnergies sit within the technology-and-capital provider tier, securing equity LNG offtake through engineering contributions to North Field and Ghasha developments.
| Leading Market Players |
|---|
| National Iranian Oil Company (NIOC) |
| ExxonMobil |
| Saudi Aramco |
| BP |
| TotalEnergies |
| QatarEnergy |
| Shell |
| Chevron |
| Abu Dhabi National Oil Company (ADNOC) |
| Others |
Supply & Pricing Matrix
Subsea compression engineering concentration among Norwegian and Italian specialists widens pricing-tier spreads between integrated mega-projects and marginal field developments, as labor-cost differentials for qualified installation contractors cascade through project sanction economics.
Pricing Analysis
Cost-down pressure on sour gas developments accelerates because amine-based acid gas removal systems consume 8-12 percent of produced energy, eroding margins at Hail, Ghasha, and South Pars marginal wells. Contract-based long-term offtake agreements dominate Qatari mega-train exports, while spot-indexed cargoes face compression from European carbon border adjustment exposure. Price differentiation hinges on certified carbon intensity documentation and sulfur recovery compliance grades. Industrial offtakers at Jubail and Ruwais exhibit highest price sensitivity due to feedstock cost pass-through mechanics, whereas Japanese and South Korean utilities prioritize certification premiums over unit economics.
Supply Chain Analysis
Direct-to-utility channels anchor Qatari LNG offtake through Q-Max and Q-Flex vessel charters, while pipeline trunk lines feed Saudi Arabia's master gas system. Geographic supply concentrates in Qatar, Saudi Arabia, and the UAE, with Iranian latent capacity constrained by sanctions. Raw material dependencies center on amine solvents for acid gas treatment, subsea compression hardware, and Claus process catalysts for sulfur recovery. Single-source vulnerability sits with Norwegian and Italian subsea installation contractors for North Field West electrification. Distribution runs through Ras Laffan liquefaction terminals, Fujairah coastal storage, and Jubail Industrial City pipeline corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East natural gas sector is transitioning from conventional platform-based processing to seabed electrification, with subsea compression technology displacing surface facility architectures across North Field expansions.
For Market Incumbents: Cement carbon intensity certification leadership by integrating reservoir-to-terminal methane monitoring before European border adjustments take effect. Deepen upstream control over sour gas treatment technology to defend margins against amine energy-cost erosion at marginal wells. Prioritize master gas system extensions to satellite fields within 50 kilometers of existing trunk infrastructure before SFDA zero-routine-flaring deadlines. For New Entrants and Emerging Players: SFDA flaring reduction mandates in Saudi Arabia open a window for modular gas gathering technology providers serving satellite field tiebacks. Target compressed natural gas retail infrastructure in Iranian urban corridors where pipeline density supports fleet conversion but dispensing networks remain underdeveloped. Pursue joint-venture structures with NIOC for South Pars pressure maintenance technology transfer under post-sanctions rehabilitation scenarios. For Investors and Strategic Acquirers: Re-rating potential sits with sour gas cost-efficiency specialists given UAE environmental standards extending equipment qualification timelines and filtering vendor competition. Five-to-ten-year viability favors producers with integrated carbon capture architectures serving blue hydrogen feedstock demand. Watch Qatari methane leakage documentation requirements as the signal for certification premium capture across Asian offtake contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Subsea Electric Compression Deployment | QatarEnergy's seabed pumps halve offshore construction duration versus platform-based alternatives. |
| Carbon Capture Integration | Saudi Aramco redirects sour gas carbon dioxide toward Jubail blue hydrogen and enhanced oil recovery. |
| Master Gas System Extension | Satellite field tiebacks into Saudi trunk infrastructure satisfy SFDA zero-routine-flaring compliance. |
| Floating LNG Monetization | ADNOC's Ghasha offshore development avoids pipeline construction through congested UAE coastal zones. |
| Certified Low-Carbon Supply Contracts | Emirates-based utilities now mandate documented methane leakage upstream of liquefaction for procurement qualification. |
Research Methodology
Multi-period observation of North Field expansion timelines, SFDA regulatory enforcement patterns, and European carbon border adjustment developments anchored the trend analysis, supplemented by interviews with utility planning officers at GCC power generation companies, EPC contractors specializing in subsea compression, and fuel supply specialists at Asian LNG offtakers. Secondary validation drew from IEA natural gas market reports, EIA international energy data, project development databases tracking Qatari mega-train progress, and SEC filings of international oil companies with Middle East equity positions. Bottom-up field economics modeling and top-down regional demand projections were triangulated against disclosed contract volumes.
Segment-weighting across product type, end user, application, and delivery mode dimensions structured the analytical framework over the projection horizon. CAGRs were derived from production capacity buildout schedules, flaring reduction mandate compliance curves, and carbon intensity certification adoption rates. Industry-specific forecast inputs included QatarEnergy's disclosed sanction-to-first-gas timelines and ADNOC's sour gas development cost structures at Hail and Ghasha.
Caveats apply where sanctions relief timelines for Iranian South Pars rehabilitation, European carbon border adjustment implementation scope, or subsea compression contractor capacity constraints could materially shift the outlook. Forecasts reflect base-case assumptions regarding regulatory enforcement continuity and technology deployment schedules. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
North America Proppants Market
Oil & Gas
Reservoir Analysis Market
Oil & Gas
Oil and Gas Fabrication Market
Oil & Gas
Smart Pipeline Pigging Market
Oil & Gas
Asia-Pacific Underground Coal Gasification Market
Oil & Gas
Southeast Asia Oil and Gas EPC Market
Oil & Gas
Drilling Mud Desander and Desilter Market
Oil & Gas
Middle-East and Africa Liner Hanger System Market
Oil & Gas
Bunker Liners Market
Oil & Gas
Asia Pacific Upstream Oil and Gas Services Market
Oil & Gas
Oil and Gas Cloud Applications Market
Oil & Gas
Asia-Pacific Oilfield Services Market
Oil & Gas
Downhole Motor Market
Oil & Gas
South and Central America Oil Field Services Market
Oil & Gas
United States Artificial Lift Systems Market
Oil & Gas
Kazakhstan Oil and Gas Market