

Floating Skimmer Market Size, Share, and Industry Trends Forecast 2026-2036
Floating Skimmer Market Insights
The gap between premium and commodity floating skimmer tiers is broadening as oil spill recovery specifications diverge from basic wastewater maintenance requirements. DESMI leverages its North Sea engineering heritage to dominate offshore containment applications. Elastec sustains competitive positioning through specialized disc skimmer configurations for inland waterway cleanup. Lamor anchors its portfolio with hydraulic drive systems engineered for Arctic operating conditions.
A floating skimmer is a mechanical separation device that removes immiscible liquids, debris, or contaminants from water surfaces through gravity-driven weir action, rotating disc adhesion, or belt conveyance, typically operating at flow rates between 5 and 500 cubic meters per hour depending on viscosity and specific gravity of the target pollutant. Weir skimmers lead product type demand due to their simplicity and minimal moving parts, while solar powered systems represent the fastest-growing technology segment as remote monitoring capabilities expand. Oil spill recovery applications command premium margins owing to regulatory-mandated response time requirements, whereas wastewater treatment constitutes the volume base across municipal procurement cycles.
The EPA enforces Clean Water Act discharge standards that mandate oil-water separation efficiency above 15 parts per million for industrial outfalls, directly shaping product certification requirements and procurement specifications. ISO 14001 environmental management protocols and OPA 90 oil pollution liability frameworks further constrain market access for uncertified equipment suppliers. Stakeholders must monitor evolving PFAS contamination protocols, as emerging regulatory scope expansion could redefine skimmer performance benchmarks for synthetic foam and film removal.
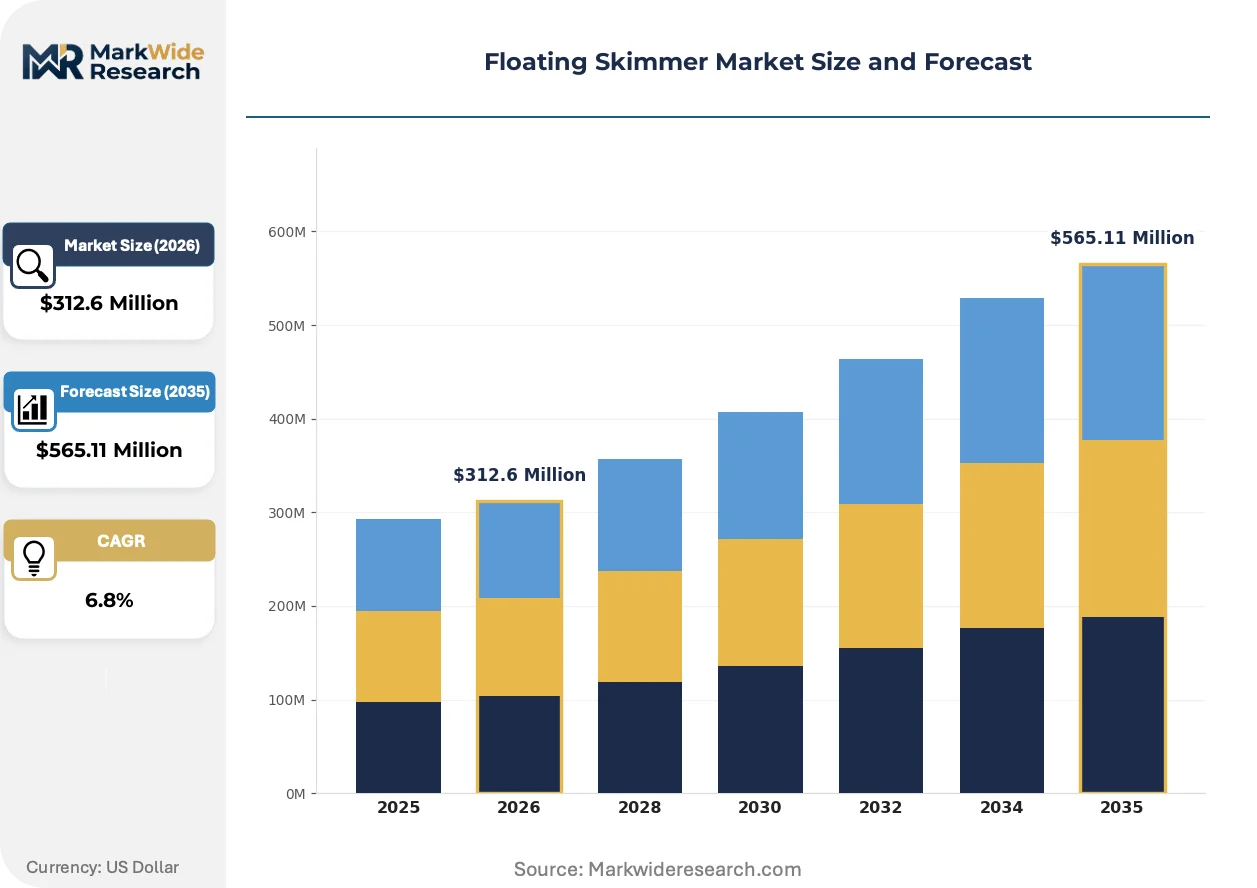
Market Dynamics
The floating skimmer market is experiencing structural pressure from diverging performance standards between municipal wastewater utilities and offshore oil spill responders, forcing manufacturers to maintain dual certification portfolios without scale economies.
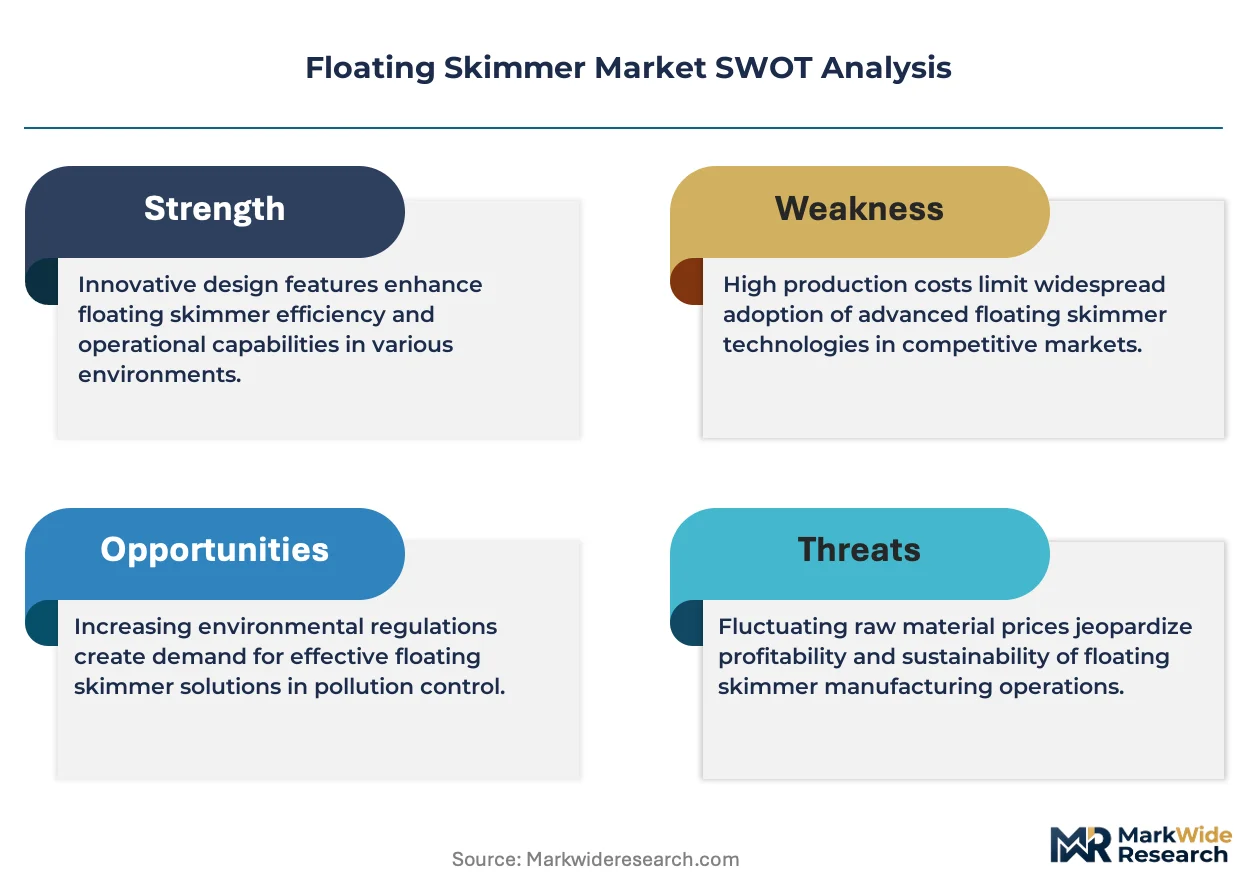
Growth Catalysts
- EPA Clean Water Act enforcement:Tightening discharge limits for industrial outfalls mandate oil-water separation efficiency above 15 parts per million, compelling facility upgrades and replacement cycles.
- Solar-powered remote monitoring:Photovoltaic skimmer systems with telemetry integration reduce operational labor costs for reservoir and tailings pond maintenance.
- Arctic infrastructure expansion:Ice-resistant hydraulic drive systems address year-round containment needs in northern latitudes where seasonal ice previously halted operations.
Market Restraints
- Specialized alloy supply concentration:Marine-grade stainless steel and corrosion-resistant polymers face sourcing bottlenecks from concentrated Asian suppliers, creating input cost volatility.
- Dual certification burden:ISO 14001 environmental management and OPA 90 oil pollution liability frameworks impose overlapping compliance costs that favor incumbent suppliers with established testing relationships.
- PFAS contamination protocol uncertainty:Emerging regulatory scope expansion for synthetic foam removal threatens to invalidate existing skimmer performance benchmarks before replacement technology matures.
Strategic Opportunities
- PFAS remediation white space:Synthetic foam and film removal capabilities represent an unaddressed application segment as environmental agencies expand contaminant monitoring scope.
- Equipment-as-a-service models:Municipal water authorities are piloting subscription-based skimmer deployments that bundle maintenance and regulatory reporting.
- EU Green Deal alignment:Circular economy procurement criteria create preference for skimmers with recyclable polymer construction and remanufactured hydraulic components.
Industry Challenges
- Cross-disciplinary engineering talent scarcity:Skimmer design requires simultaneous expertise in fluid dynamics, marine corrosion science, and automated control systems.
- Legacy SCADA integration complexity:Municipal utilities operate decades-old distributed control systems that resist seamless telemetry integration with modern skimmer monitoring platforms.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floating Skimmer Market Trends and Innovations
Active innovation in the floating skimmer market centers on three vectors: system architecture flexibility, regulatory scope expansion, and procurement model transformation. Each trend is compressing traditional competitive advantages and opening entry points for specialized suppliers.
Modular weir skimmer architecture is modularizing across flow rate classes, allowing municipal utilities to standardize on single manufacturer platforms while scaling from 5 to 500 cubic meters per hour through interchangeable weir heads. Water authorities in the United States are adopting these configurable systems to reduce spare parts inventory complexity. The approach is compressing margins for custom-engineered solutions while rewarding suppliers with broad product matrices.
REACH chemical substance restrictions in Europe are accelerating material substitution in belt and disc skimmer construction, with perfluorinated compound limitations driving fluoropolymer replacement in adhesive surfaces. Industrial outfall operators face reformulation timelines that compress equipment qualification windows. German chemical manufacturers are responding with bio-based surface treatments that meet separation efficiency standards without restricted substance content.
Asset performance guarantees are displacing capital purchase models in municipal procurement, with Ohio and Pennsylvania water authorities requiring contractors to assume operational risk for skimmer effectiveness. Equipment suppliers must now price lifetime maintenance and regulatory compliance into upfront contracts. This shift concentrates demand among vendors with proven field service networks and predictive maintenance capabilities.
Floating Skimmer Market Segmentation
Floating skimmer procurement diverges sharply across end-use contexts, with oil spill responders prioritizing rapid deployment specifications while municipal utilities emphasize lifecycle cost minimization. Manufacturers must engineer platform flexibility to address these incompatible performance hierarchies without fragmenting production runs.
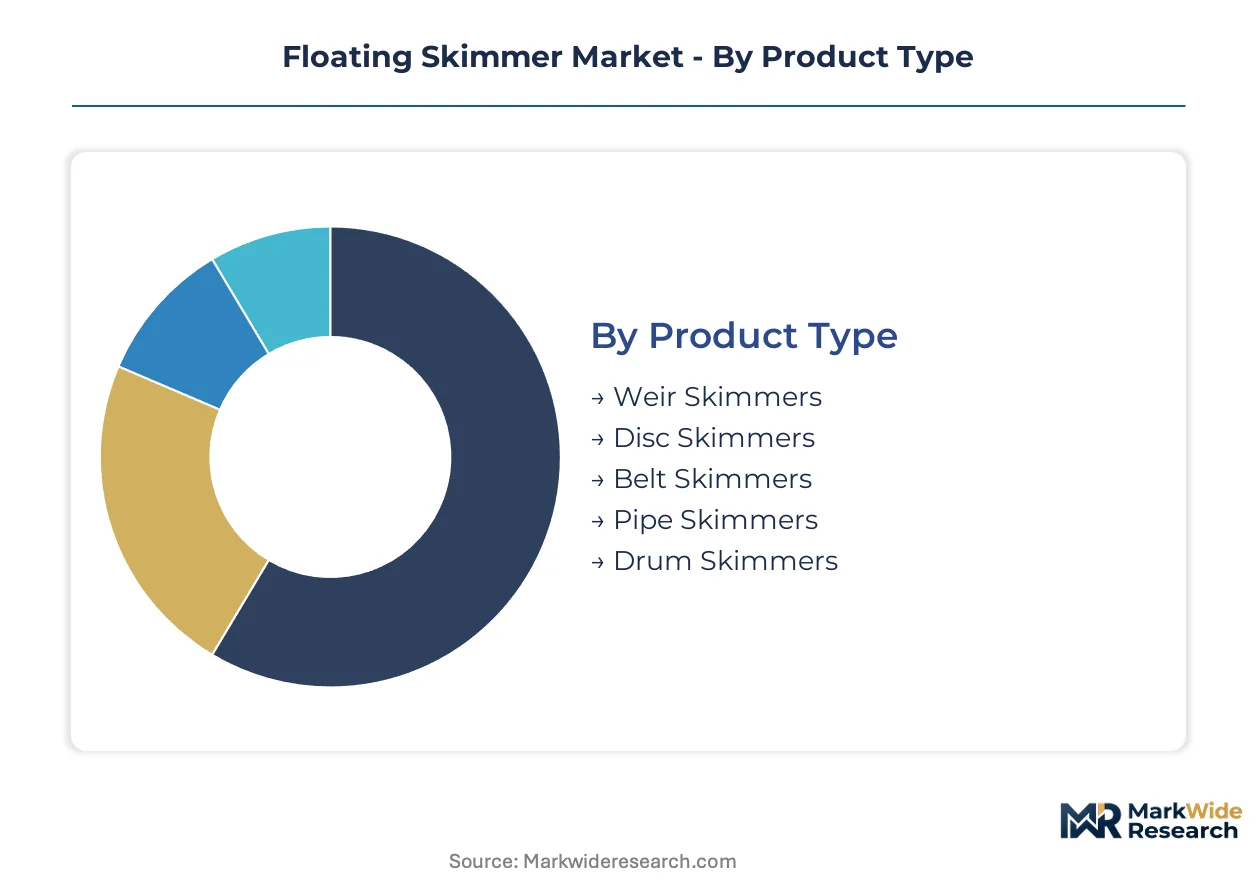
Product Type:
Replacement cycles vary dramatically by skimmer architecture, with weir systems requiring periodic weir head refurbishment while disc configurations demand adhesive surface renewal at shorter intervals.
- Weir Skimmers:Gravity-driven weir action separates immiscible liquids through adjustable overflow geometry, operating with minimal moving parts that reduce mechanical failure risk. Municipal water authorities in the United States concentrate procurement here for reservoir maintenance, driven by EPA Clean Water Act discharge compliance mandates that favor proven separation reliability.
- Disc Skimmers:Rotating disc adhesion captures surface contaminants through oleophilic surface coatings, enabling selective oil recovery at viscosity ranges unsuited to weir mechanisms. Inland waterway cleanup operations in the Midwest and Gulf Coast regions specify these configurations for rapid deployment scenarios where containment timeframes compress operational windows.
- Belt Skimmers:Continuous belt conveyance with scraper assemblies handles heavy debris loads in industrial outfall applications.
- Pipe Skimmers:Submerged intake configurations suit aquaculture pond maintenance where surface disturbance minimization protects stock health.
- Drum Skimmers:Cylindrical rotating elements address high-viscosity industrial effluent in petrochemical facility discharge management.
Weir skimmers sit at the top of the volume ranking, with solar-powered disc configurations climbing the fastest in remote monitoring deployments.
Technology:
Power source selection directly determines operational autonomy and telemetry integration potential, with remote site accessibility favoring photovoltaic architectures over tethered alternatives.
- Gas Compression:Pneumatic actuation systems deliver high torque density for Arctic operating conditions where electric motor efficiency degrades, with hydraulic fluid compatibility concerns driving specification in northern Canadian and Alaskan installations.
- Electric Motor:Standard AC and DC drive configurations dominate municipal wastewater infrastructure, where grid connectivity eliminates fuel logistics and variable frequency control enables precise flow rate modulation for diurnal load variation.
- Hydraulic Drive:Closed-loop fluid power systems tolerate submersion and thermal cycling in offshore containment applications.
- Solar Powered Systems:Photovoltaic arrays with battery storage and cellular telemetry enable unattended reservoir monitoring, gaining share fastest in western United States water authority procurement.
- Pneumatic Drive:Compressed air systems suit hazardous area classifications where electrical ignition risks constrain motor deployment.
Electric motor drives anchor current procurement volumes, though solar powered systems are expanding most quickly as telemetry integration becomes standard specification.
Application:
Margin structures invert across application contexts, with regulatory-mandated response timelines in oil recovery commanding premium pricing against cost-optimized municipal wastewater specifications.
- Oil Spill Recovery:Rapid deployment mandates under OPA 90 liability frameworks require skimmer systems achieving operational status within four hours of incident notification, with performance guarantees and crew training bundled into procurement contracts that sustain premium vendor margins.
- Wastewater Treatment:Municipal procurement cycles emphasize capital cost minimization and standardized spare parts inventory, with Ohio and Pennsylvania water authorities piloting equipment-as-a-service models that transfer operational risk to contractors.
- Water Surface Cleaning:Debris and algae removal for aesthetic and ecological maintenance in urban water bodies.
- Industrial Discharge Management:Continuous oil-water separation for manufacturing outfall compliance with EPA effluent limitations guidelines.
- Aquaculture Maintenance:Protein skimming and surface film removal in intensive fish farm operations.
Wastewater treatment generates the highest unit volumes, while oil spill recovery commands the steepest expansion trajectory as climate-related incident frequency rises.
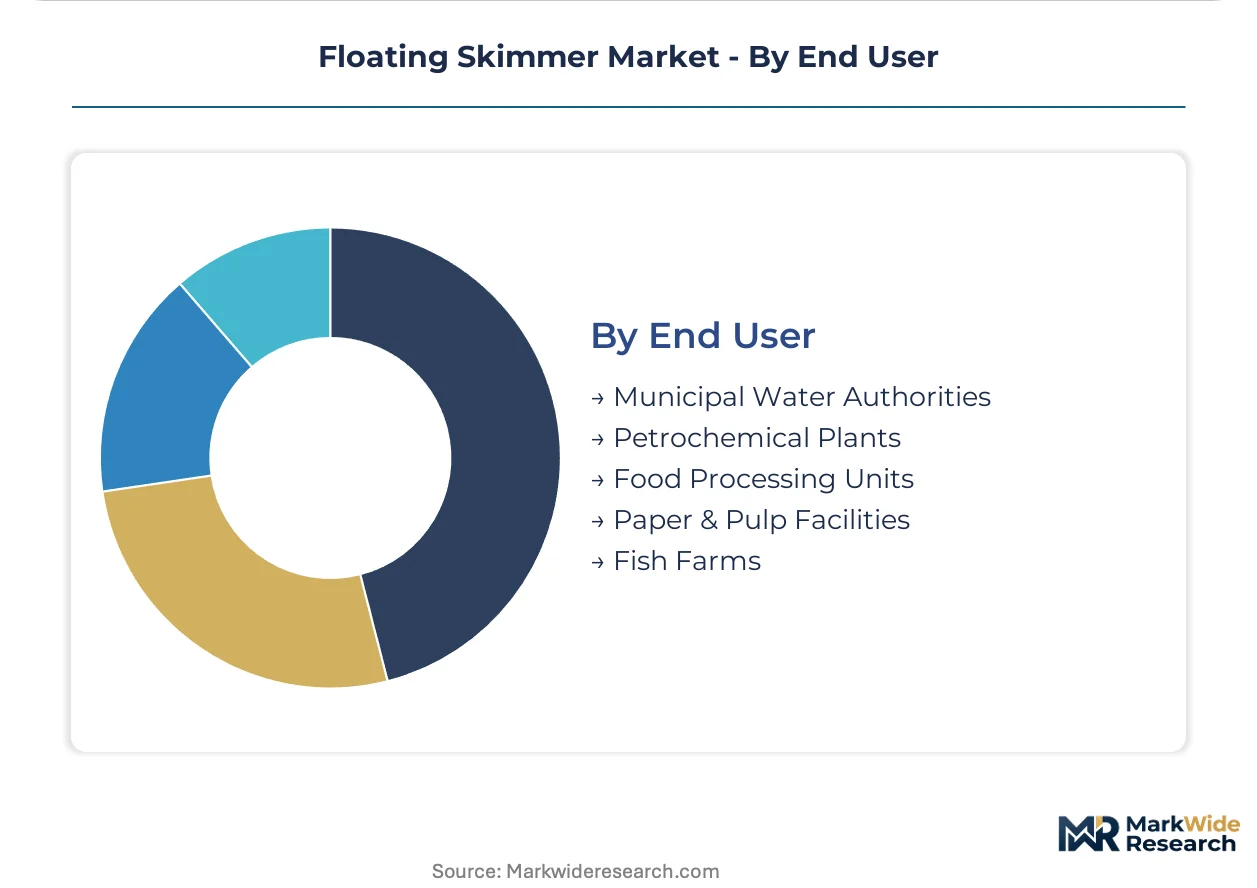
End User:
Customer technical sophistication and procurement authority concentration shape vendor engagement models, with fragmented municipal decision-making contrasting centralized petrochemical engineering specifications.
- Municipal Water Authorities:Aging infrastructure replacement cycles in the United States drive standardization initiatives, with regional purchasing cooperatives consolidating demand to extract volume discounts from manufacturers with broad service networks.
- Petrochemical Plants:Process safety management regulations and insurance underwriting requirements mandate redundant skimmer capacity, with engineering departments specifying corrosion-resistant alloys and automated failover systems that sustain supplier technical relationships.
- Food Processing Units:FOG (fats, oils, grease) separation for sewer discharge compliance in meat and dairy operations.
- Paper & Pulp Facilities:Black liquor and resin acid recovery in kraft mill effluent treatment.
- Fish Farms:Dissolved organic removal in recirculating aquaculture system design.
Municipal water authorities represent the largest addressable base, with petrochemical plants delivering the fastest contract value growth as environmental liability frameworks tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in fluid dynamics and marine corrosion science concentrate in coastal industrial corridors across five nations. These workforce clusters anchor regional skimmer manufacturing capabilities and shape local procurement specifications.
United States
Municipal water authorities in Ohio and Pennsylvania are piloting equipment-as-a-service contracts that transfer operational risk to vendors. The EPA enforces Clean Water Act discharge limits mandating oil-water separation efficiency above 15 parts per million for industrial outfalls. Houston-Galveston petrochemical corridor sustains demand for rapid-deployment containment systems as climate-related incident frequency rises.
Germany
REACH chemical substance restrictions are accelerating fluoropolymer replacement in belt and disc skimmer adhesive surfaces. ECHA timelines compress equipment qualification windows for industrial outfall operators. Ruhr industrial basin water utilities are standardizing on modular weir architectures to reduce spare parts inventory complexity across aging treatment infrastructure.
Canada
Arctic infrastructure expansion drives specification of ice-resistant hydraulic drive systems in northern Alberta and Yukon territories. Health Canada is aligning with emerging PFAS contamination protocols that could redefine skimmer performance benchmarks. Calgary-Edmonton energy corridor maintains year-round containment operations where seasonal ice previously halted activity.
Norway
Offshore oil spill response mandates under OPA 90 liability frameworks require operational status within four hours of incident notification. The country's national environmental regulator enforces strict separation efficiency standards for North Sea containment applications. Stavanger-Bergen subsea engineering cluster dominates premium-tier system integration for harsh marine environments.
Australia
Remote mining tailings pond maintenance is driving fastest adoption of solar-powered skimmer systems with cellular telemetry. The country's environmental protection authority is expanding synthetic foam monitoring scope that threatens existing performance benchmarks. Perth-Kalgoorlie mineral processing corridor represents concentrated demand for unattended reservoir monitoring solutions.
Floating Skimmer Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the floating skimmer market, with foundry-equipped manufacturers maintaining alloy casting capabilities while specialized engineering firms outsource component fabrication. The vendor base organizes around three strategic archetypes: integrated offshore containment specialists, municipal wastewater platform providers, and niche Arctic hydraulic system engineers. Competitive positioning hardens through dual certification portfolio maintenance and predictive maintenance service network expansion rather than pure manufacturing scale.
Within the offshore containment tier, DESMI anchors premium positioning through North Sea engineering heritage, while Elastec occupies a position among inland waterway cleanup specialists with disc skimmer configurations. Lamor exemplifies the Arctic-capable hydraulic drive segment engineered for sub-zero operating conditions. These three entities represent contrasting geographic and technical specializations that fragment procurement authority across incompatible performance hierarchies.
| Leading Market Players |
|---|
| DESMI |
| Elastec |
| Lamor |
| Vikoma |
| Abanaki Corporation |
| Ultraspin |
| SkimOIL |
| Wayne Products |
| Megator |
| Others |
Pricing and Supply Chain Analysis
Marine-grade stainless steel price indices cascade through floating skimmer manufacturing tiers, compressing margins on standard weir systems while preserving premium pricing for Arctic-certified hydraulic configurations. Input cost volatility from concentrated Asian alloy suppliers forces municipal procurement toward longer-term service contracts that transfer material risk to vendors.
Pricing Analysis
Bundled equipment-as-a-service contracts separate from unbundled capital purchases across municipal water authority procurement. Three-tier pricing structure across premium Arctic-hydraulic, standard electric-weir, and economy pneumatic configurations reflects certification grade and after-sales telemetry integration. Cost compression in the standard tier intensifies as regional purchasing cooperatives consolidate demand for volume discounts. Municipal utilities exhibit highest price sensitivity, while petrochemical plant engineering departments prioritize redundancy specifications over unit cost.
Supply Chain Analysis
Fluid dynamics engineering talent scarcity in Denmark, Norway, and Germany constrains production scaling for specialized offshore containment systems. Component sourcing draws from Chinese stainless steel foundries, South Korean corrosion-resistant polymer suppliers, and Finnish hydraulic drive specialists. Single-source vulnerability concentrates in marine-grade alloy supply from concentrated Asian suppliers. Distribution runs through regional water authority purchasing cooperatives in the United States and direct engineering sales for petrochemical facility specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Clean Water Act discharge enforcement and emerging PFAS contamination protocols continuously expand addressable demand through compliance-driven replacement cycles.
For Market Incumbents: Acquire predictive maintenance service networks to defend against asset-light telemetry specialists encroaching on municipal equipment-as-a-service contracts. Deepen backward integration into corrosion-resistant polymer formulation to offset fluoropolymer substitution timelines driven by REACH restrictions. Certification investment in dual ISO 14001 and OPA 90 portfolios remains essential for offshore containment tier access. For New Entrants and Emerging Players: Solar-powered telemetry integration offers a technology-first wedge into western United States water authority procurement where grid connectivity constraints favor autonomous reservoir monitoring. PFAS synthetic foam removal capabilities represent the most penetrable white-space application as Health Canada and EPA expand monitoring scope. Channel partnerships with established municipal service contractors accelerate qualification timelines against incumbent direct sales organizations. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized Arctic hydraulic system engineers possessing ice-resistant drive intellectual property as northern infrastructure expansion accelerates. Long-term viability favors vendors with demonstrated field service density across fragmented municipal decision-making structures. Watch for PFAS protocol finalization as the inflection indicator triggering performance benchmark resets and equipment replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS Remediation Capability Development | EPA protocol expansion positions early movers for synthetic foam removal specifications. |
| Equipment-as-a-Service Model Launch | Ohio and Pennsylvania water authority pilots transfer operational risk to vendors. |
| Arctic Hydraulic System Engineering | Calgary-Edmonton energy corridor demands year-round containment where ice previously halted operations. |
| Solar Telemetry Platform Integration | Perth-Kalgoorlie mining corridor drives fastest adoption of autonomous reservoir monitoring. |
| REACH-Compliant Material Substitution | German chemical manufacturers respond with bio-based surface treatments for disc skimmer adhesion. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with municipal water authority procurement directors, petrochemical plant maintenance engineers, offshore containment system operators, and hydraulic drive component suppliers. Secondary validation draws from EPA enforcement databases, ECHA substance restriction timelines, Health Canada contamination protocols, and customs trade records for marine-grade alloy imports. Bottom-up unit economics triangulate against top-down regulatory mandate sizing.
Rate-of-change decomposition separates volume growth from value mix shift across the projection horizon. Segmentation dimensions modeled include product architecture, power source technology, application context, and end-user procurement authority concentration. CAGRs derive from regulatory mandate implementation schedules and infrastructure replacement cycle analysis. Industry-specific inputs incorporate Clean Water Act enforcement intensity scoring and Arctic infrastructure investment pipeline tracking.
The model holds under stable regulatory enforcement intensity and material supply continuity; deviation in PFAS protocol scope expansion or marine-grade alloy tariff structures would shift replacement demand timing. Forecasts reflect these assumptions without claiming predictive certainty. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.