
 Qatar Oilfield Service Market | 2026-2036
Qatar Oilfield Service Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Oilfield Service Market Analytics
Qatar's local content regulations is decoupling international contractors from turnkey project awards unless they form joint ventures with Qatari firms. SLB leverages its integrated drilling and evaluation portfolio to anchor major North Field contracts. Halliburton competes through cementing and completion specialization tailored to high-pressure sour gas reservoirs. Baker Hughes differentiates via turbomachinery and process solutions for LNG-integrated field developments.
Qatar oilfield services encompass the technical execution of drilling, completion, intervention, and production maintenance activities for hydrocarbon extraction, requiring pressure ratings exceeding 15,000 psi and hydrogen sulfide-resistant metallurgy for sour gas compatibility. Drilling services occupies the largest revenue pool given the scale of horizontal well construction across the North Field expansion. Well completion is recording the fastest trajectory as subsea tiebacks and intelligent completion systems multiply. Reservoir services concentrates margin capture through 4D seismic and advanced analytics integration.
Qatar's Ministry of Commerce and Industry enforces local content thresholds that condition market access on domestic partnership structures. The Qatar Financial Centre Regulatory Authority governs capital deployment rules for foreign service providers establishing operational bases. Qatar Petroleum's technical specifications mandate compliance with API standards and Qatar Construction Specifications for offshore platform integrity. Stakeholders must monitor how QatarEnergy's contractor prequalification criteria evolve as project complexity escalates.
Market Dynamics
Qatar Petroleum's North Field expansion is concentrating service demand around high-pressure sour gas extraction, forcing contractors to reconfigure technical capabilities and partnership structures to meet local content mandates.
Growth Catalysts
- North Field East and South megaprojects:These developments are generating sustained demand for drilling rigs and subsea installation vessels capable of operating in ultra-high-pressure reservoir conditions.
- Local content thresholds:Qatar's Ministry of Commerce and Industry mandates domestic partnership structures that channel foreign investment into joint ventures with Qatari engineering and fabrication firms.
- Sour gas metallurgy advances:Hydrogen sulfide-resistant alloys and premium connections are enabling deeper reservoir access in corrosive high-temperature formations.
Market Restraints
- Specialized alloy supply concentration:Premium sour service steel production concentrates among a limited set of European and Japanese mills, creating input cost volatility and extended lead times.
- Joint venture formation friction:Qatar Financial Centre Regulatory Authority capital deployment rules impose structural delays on foreign service providers establishing operational bases.
- Subsea engineering talent scarcity:The shallow pool of engineers qualified for high-complexity tieback design limits execution velocity across multiple concurrent projects.
Strategic Opportunities
- Intelligent completion systems:Downhole monitoring and autonomous inflow control technology convergence creates white space for integrated service packages in extended-reach horizontal wells.
- Ras Laffan industrial cluster expansion:Proximity to fabrication yards and LNG export infrastructure offers logistics advantages for modular equipment assembly and maintenance.
- 4D seismic analytics integration:Advanced reservoir characterization services capture margin through real-time production optimization and infill drilling targeting.
Industry Challenges
- API Q2 and Q1 certification timelines:Quality management system accreditation for drilling equipment manufacturing creates months-long prequalification bottlenecks.
- Legacy SCADA integration complexity:New digital wellsite systems must interface with existing Qatar Petroleum production control infrastructure, extending commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Oilfield Service Market |
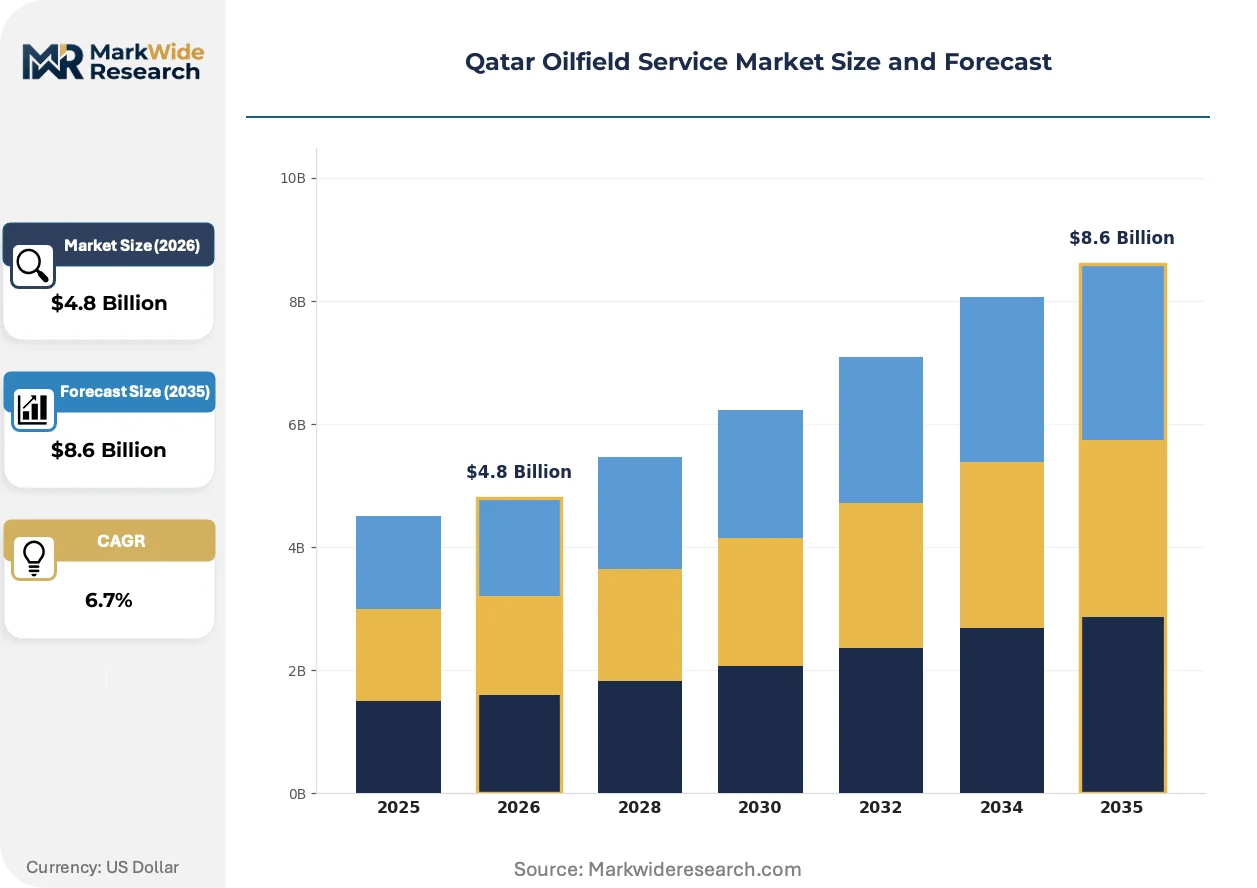
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Drilling Services, Maintenance Services, Well Completion, Reservoir Services Application: Offshore Operations, Onshore Operations, Enhanced Oil Recovery, Production Optimization Technology: Advanced Analytics, Remote Monitoring, Automated Drilling, Robotics End User: National Oil Companies, Independent Operators, Oilfield Contractors, Multinational Corporations |
| Companies Covered | Weatherford, Gulf Drilling International, SLB, Schlumberger Limited, Petrofac Limited, Halliburton, National Energy Services Reunited Corp., SAIPEM SpA, Baker Hughes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Oilfield Service Market Evolving Landscape
Electrification of drilling and production systems is reshaping capital allocation across Qatar's offshore developments, while regulatory pressure on emissions intensifies equipment specification requirements.
High-torque electric top drives and battery-hybrid power modules are electrifying rig operations across North Field jackup and platform drilling campaigns. Qatar Petroleum's contractor technical specifications now prioritize all-electric drawworks and mud pump systems for newbuild rigs. This transition is compressing maintenance intervals and reducing diesel fuel logistics burdens in offshore supply chains.
Qatar Construction Specifications for offshore platform integrity now incorporate stricter fatigue life assessment protocols aligned with API RP 2SIM standards. These mandates require enhanced structural monitoring systems and periodic reassessment of existing jacket installations. Fabrication contractors are responding by embedding fiber-optic strain sensing into new platform builds destined for North Field South development areas.
Integrated service contracting is consolidating previously fragmented drilling, evaluation, and completion procurement under single-source accountability structures. QatarEnergy's prequalification criteria now favor vendors offering bundled technical scopes spanning multiple well construction phases. This behavioral shift is most visible in major offshore lump-sum turnkey awards where interface risk transfer to contractors accelerates project sanctioning timelines.
Qatar Oilfield Service Market Segmentation
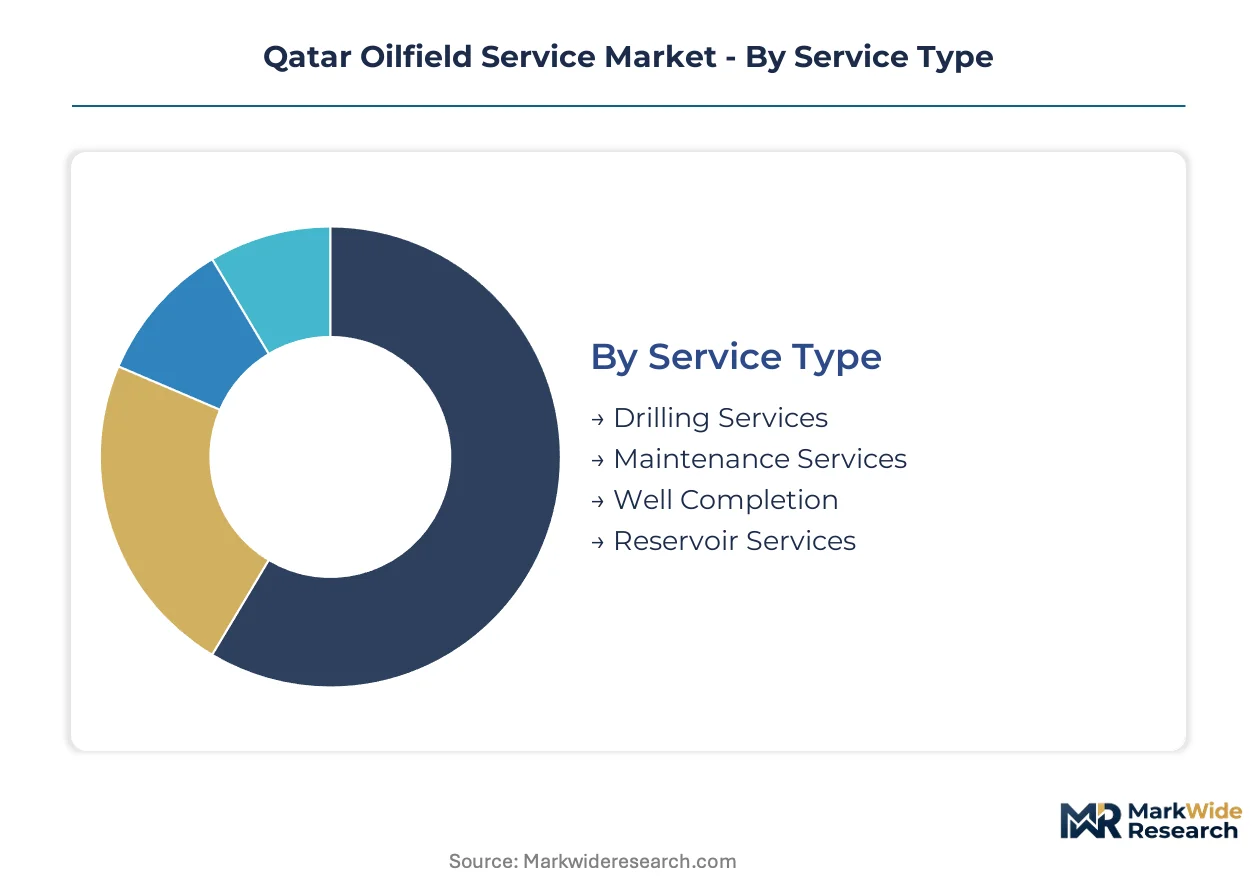
Qatar Oilfield Service Market segmentation reveals how North Field expansion priorities are reshaping procurement patterns across technical service tiers. Contractors must align capabilities with sour gas metallurgy requirements, local content mandates, and integrated project delivery structures to capture contract awards.
Service Type:
Buyers differentiate primarily by capital intensity and technical risk allocation across well lifecycle phases.
- Drilling Services:Horizontal well construction and high-pressure rig operations dominate capital deployment across North Field East and South developments. Qatar Petroleum's lump-sum turnkey awards concentrate here, demanding 15,000+ psi pressure ratings and hydrogen sulfide-resistant metallurgy that only specialized contractors can deliver.
- Well Completion:Subsea tieback installations and intelligent completion systems are multiplying as QatarEnergy prioritizes remote reservoir management. Downhole monitoring convergence with autonomous inflow control creates white space for integrated service packages in extended-reach horizontal wells.
- Maintenance Services:Production uptime contracts and periodic platform integrity assessments sustain recurring revenue streams.
- Reservoir Services:4D seismic interpretation and advanced analytics integration capture margin through real-time optimization and infill targeting.
Drilling Services leads volumes today; Well Completion is gaining share fastest.
Application:
Operational environment dictates equipment specification severity and logistics complexity for contractors.
- Offshore Operations:North Field East and South megaprojects drive demand for jackup rigs, platform drilling modules, and subsea installation vessels capable of ultra-high-pressure reservoir access. Qatar Construction Specifications mandate API RP 2SIM-aligned fatigue life protocols for all new platform builds.
- Onshore Operations:Limited scope remains concentrated around existing onshore facility maintenance and minor workover campaigns.
- Enhanced Oil Recovery:Gas injection and chemical EOR applications are marginal given Qatar's primary gas reservoir characteristics.
- Production Optimization:Real-time well performance monitoring and artificial lift optimization sustain output from maturing well stock.
Offshore Operations commands the dominant revenue pool; Production Optimization shows the steepest expansion trajectory as digital infrastructure penetrates existing assets.
Technology:
Adoption velocity separates early-mover contractors from legacy equipment suppliers in QatarEnergy prequalification rankings.
- Advanced Analytics:Reservoir characterization and predictive maintenance algorithms integrate with Qatar Petroleum's existing production control infrastructure.
- Remote Monitoring:Subsea wellhead sensors and platform-based diagnostics reduce offshore personnel requirements.
- Automated Drilling:High-torque electric top drives and battery-hybrid power modules are electrifying rig operations across jackup and platform campaigns, compressing maintenance intervals and reducing diesel logistics burdens.
- Robotics:Inspection-class ROVs and autonomous underwater vehicles handle subsea infrastructure surveys in high-pressure environments.
Automated Drilling anchors near-term investment; Advanced Analytics is climbing the fastest as QatarEnergy bundles digital services into integrated contracts.
End User:
Contracting authority and local content compliance requirements fragment procurement pathways across buyer categories.
- National Oil Companies:QatarEnergy and Qatar Petroleum drive megaproject sanctioning through prequalified vendor lists that favor joint venture structures with Qatari engineering firms.
- Oilfield Contractors:Tier-1 international service companies and their domestic JV partners execute drilling, completion, and subsea installation scopes under single-source accountability structures.
- Independent Operators:Minor participants in Qatar's concession landscape with limited procurement autonomy.
- Multinational Corporations:Integrated oil companies with equity positions in North Field developments influence technical specifications without direct service contracting authority.
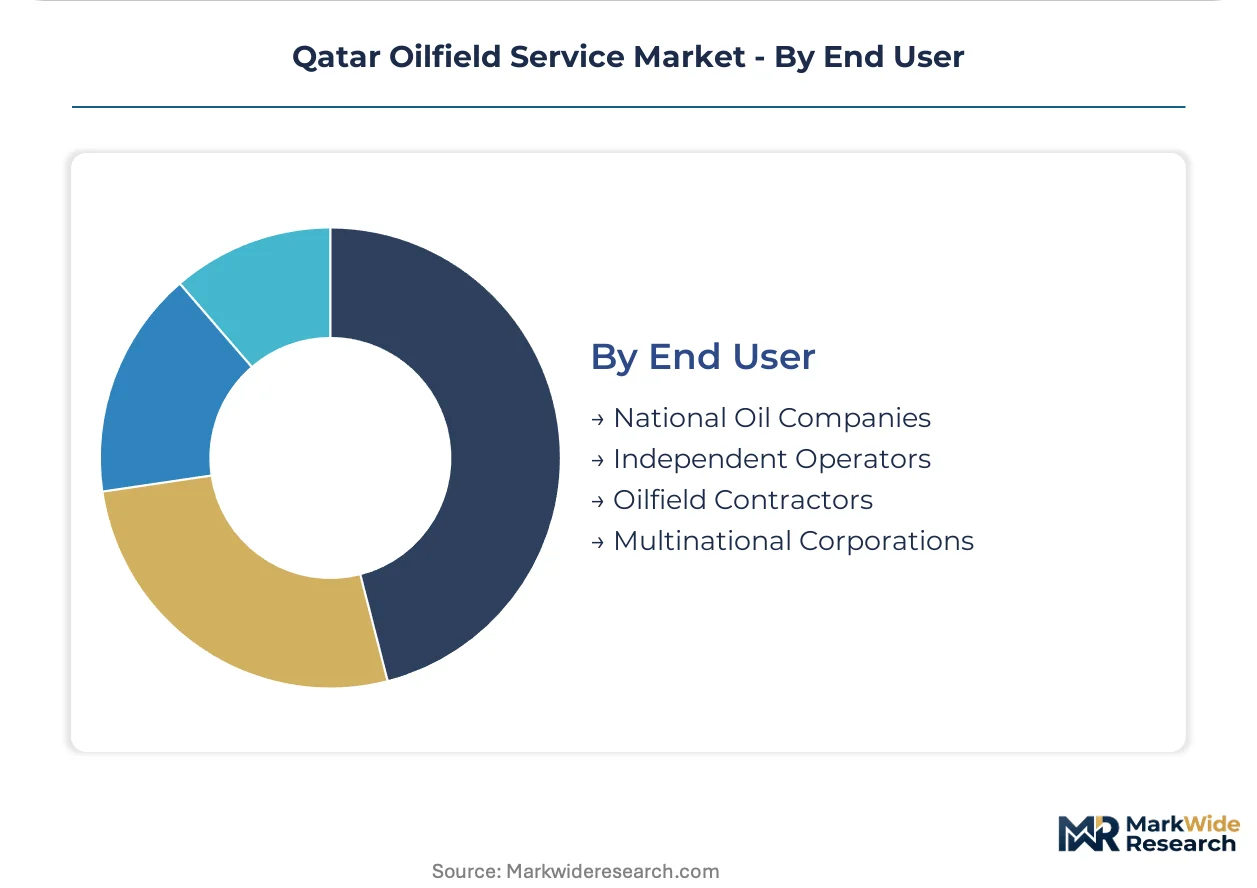
National Oil Companies dominate contract awards today; Oilfield Contractors are expanding their consolidated service scope fastest under integrated contracting trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Doha and Ras Laffan anchor Qatar's oilfield service capabilities, with specialized subsea expertise concentrated around the North Field industrial corridor.
Doha Metropolitan Area
Corporate headquarters and project management functions cluster in Doha's West Bay and Lusail districts, where QatarEnergy and major contractor joint ventures coordinate North Field East and South procurement. Qatar Financial Centre Regulatory Authority capital deployment rules shape foreign firm establishment timelines. The Qatar Science and Technology Park hosts digital oilfield R&D partnerships targeting intelligent completion systems.
Ras Laffan Industrial City
Fabrication yards and modular equipment assembly facilities dominate this northern coastal zone, supplying subsea infrastructure for ultra-high-pressure sour gas developments. Qatar Petroleum's technical specifications mandate API RP 2SIM-aligned fatigue protocols for all platform builds executed here. The Ras Laffan Port handles heavy-lift vessel logistics for jackup rig mobilization and subsea installation campaigns.
Al Khor Region
Workforce accommodation and training centers support offshore rotation schedules for North Field drilling crews. Qatar's Ministry of Commerce and Industry enforces local content thresholds that channel joint venture formation through engineering partnerships based in this municipality. Specialized welding and metallurgy certification programs operate from technical colleges serving the sour gas supply chain.
Mesaieed Industrial Area
Downstream integration with LNG export infrastructure creates maintenance demand for turbomachinery and process equipment. Baker Hughes anchors process solutions capabilities here, leveraging proximity to QatarEnergy's liquefaction trains. The industrial zone's logistics connectivity supports spare parts distribution for offshore production optimization contracts.
Dukhan Onshore Field
Mature oil production sustains workover and artificial lift service demand, though volumes trail offshore North Field expansion priorities. Legacy SCADA integration requirements complicate digital wellsite upgrades across existing well stock. Maintenance service contractors maintain regional bases here for periodic platform integrity assessments.
Qatar Oilfield Service Market Competitive Landscape
The competitive structure tilts toward integrated service bundling, with tier-1 international firms consolidating drilling, completion, and subsea scopes under single-source accountability. Joint venture mandates fragment pure foreign participation, forcing partnership structures with Qatari engineering entities. Three archetypes dominate: full-line integrators anchoring turnkey awards, specialists capturing premium sour gas metallurgy niches, and local-content-compliant JV platforms. Dominant competitive moves include strategic partnerships with domestic fabricators and portfolio diversification into digital reservoir analytics.
Within the full-line integrator tier, SLB and Halliburton exemplify archetypes competing through bundled technical scopes spanning multiple well construction phases. Baker Hughes occupies a position emphasizing turbomachinery and process solutions. Among Qatar-based joint venture structures, Gulf Drilling International represents the local-content-compliant model, while Weatherford and Petrofac Limited sit within specialist tiers targeting completion and maintenance segments respectively.
| Leading Market Players |
|---|
| Weatherford |
| Gulf Drilling International |
| SLB |
| Schlumberger Limited |
| Petrofac Limited |
| Halliburton |
| National Energy Services Reunited Corp. |
| SAIPEM SpA |
| Baker Hughes |
| Others |
Value Network & Pricing Analysis
QatarEnergy's consolidated procurement authority concentrates buyer power among a single national oil company archetype, compressing contractor margins through lump-sum turnkey awards that transfer technical risk to service providers.
Pricing Analysis
Bundled integrated contracts dominate premium awards while unbundled discrete services compete on price in maintenance segments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with API Q2-accredited contractors commanding 40-60% premiums over uncertified competitors. Cost compression in standard-tier drilling services is intensifying because European and Japanese mill concentration for sour service alloys limits supplier alternatives. Exploration-focused operators show highest price sensitivity, while North Field megaproject procurement prioritizes technical compliance over unit cost.
Supply Chain Analysis
API Q2 and Q1 certification gating restricts qualified equipment suppliers to a narrow tier of pre-audited manufacturers. Premium sour service steel draws from Japan, Germany, and Austria, with hydrogen sulfide-resistant alloys, premium threaded connections, and subsea wellhead systems anchoring input dependencies. Single-source vulnerability concentrates around specialized metallurgy mills serving high-pressure reservoir specifications. Distribution runs through Ras Laffan fabrication yards for modular assembly before offshore deployment to North Field platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
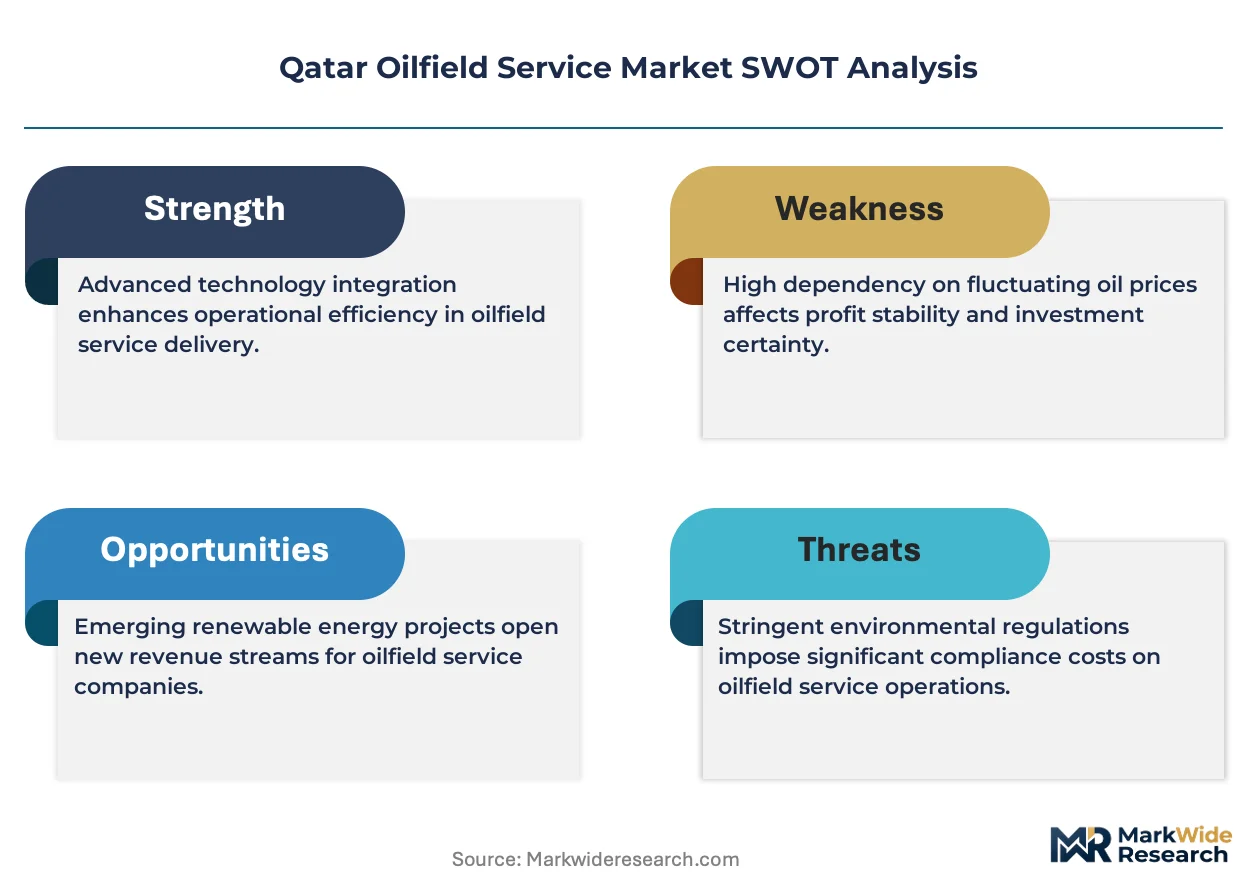
Qatar oilfield services constitute a late-cycle quality story where reservoir complexity and local content mandates favor contractors with proven sour gas execution records over price competitors.
For Market Incumbents: To counter joint venture formation friction from Qatar Financial Centre Regulatory Authority capital deployment rules, anchor market position through backward integration into Ras Laffan fabrication partnerships and accelerate API Q2 certification timelines for drilling equipment manufacturing. Prioritize intelligent completion system R&D to capture margin from autonomous inflow control convergence. For New Entrants and Emerging Players: Launch via specialist subcontracting relationships with established Qatari engineering firms to satisfy Ministry of Commerce and Industry local content thresholds. Target maintenance services and production optimization segments where incumbent bundling is weakest. Penetrate through 4D seismic analytics partnerships that integrate with Qatar Petroleum's existing SCADA infrastructure. For Investors and Strategic Acquirers: National oil companies from adjacent GCC markets are the most active acquirer in this space, seeking sour gas technical capabilities for their own high-pressure developments. Five-to-ten-year viability hinges on exposure to North Field South sanctioning velocity. Monitor QatarEnergy contractor prequalification criteria evolution as the signal for portfolio reallocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation with Qatari Fabricators | Qatar Ministry of Commerce and Industry local content mandates condition market access on domestic partnership structures. |
| API Q2 Quality Management Certification | Qatar Petroleum prequalification criteria favor vendors with accredited drilling equipment manufacturing systems. |
| Intelligent Completion System Development | Downhole monitoring convergence with autonomous inflow control creates white space in extended-reach horizontal wells. |
| Ras Laffan Industrial Cluster Proximity | Proximity to LNG export infrastructure offers logistics advantages for modular equipment assembly and maintenance. |
| 4D Seismic Analytics Integration | Advanced reservoir characterization captures margin through real-time production optimization and infill drilling targeting. |
Research Methodology
Coverage spans Qatar, Saudi Arabia, and UAE, with primary inputs from each market combining structured interviews with drilling contractors, subsea engineers, procurement officers at national oil companies, and regulatory affairs specialists at Qatar Financial Centre with secondary validation from Qatar Petroleum technical specifications, API standards documentation, and Qatar Construction Specifications archives. Bottom-up project sanctioning timelines triangulate against top-down market sizing from contractor fleet deployment data.
Granularity-level modeling disaggregates revenue across service type, application environment, technology adoption tier, and end-user contracting authority throughout the forecast period. CAGRs derive from project pipeline velocity analysis and contractor capacity absorption rates. Modeled inputs include North Field East and South megaproject sanctioning schedules, jackup rig mobilization timelines, and subsea installation vessel day-rate trajectories.
Several conditions sit outside the modeled scope, including geopolitical disruption to European alloy supply chains and unannounced QatarEnergy procurement policy shifts. Forecasts reflect assumptions about local content threshold stability and sour gas metallurgy lead time normalization. A model refresh is warranted upon material change in QatarEnergy contractor prequalification criteria or North Field South project sanctioning velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Asia-Pacific Oilfield Chemicals Market
Oil & Gas
Global Upstream Petrotechnical Training Services Market
Oil & Gas
Global Floating LNG Terminal Market
Oil & Gas
Coiled Tubing System Market
Oil & Gas
Blowout Preventers (BOP) Market
Oil & Gas
SCADA Oil and Gas Market
Oil & Gas
Digital Oilfield Market
Oil & Gas
Saudi Arabia Drilling Rigs Market
Oil & Gas
Tricone Bits Market
Oil & Gas
Oil and Gas Automation Market
Oil & Gas
Iron Ore Mining Market
Oil & Gas
Southeast Asia Oil and Gas Market
Oil & Gas
Oil and Gas EPC Market
Oil & Gas
Drilling Services Market
Oil & Gas
Pipeline Integrity Market
Oil & Gas
Libya Oil and Gas Upstream Market