
 Mobile Servicing Rig Market | 2026-2036
Mobile Servicing Rig Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Servicing Rig Market Analytics
EPA methane performance standards for oil and gas infrastructure is restructuring procurement priorities across the well servicing supply chain. Schlumberger leverages its integrated technology portfolio to anchor positions in automated rig control systems. Ensign competes through geographic density in North American shale basins, while Axis specializes in high-mobility coil tubing and well intervention units engineered for tight wellsite footprints.
A mobile servicing rig is a self-propelled or transportable hoisting and workover unit, typically rated between 150 and 600 horsepower, designed to perform well intervention, completion, and maintenance operations without permanent site installation. Truck-mounted configurations dominate North American land markets due to highway transportability and rapid rig-up times, while skid-mounted units sustain demand in remote mining and utility sectors where road access remains constrained. Trailer-mounted and modular segments are gaining traction in coastal and desert deployments where componentized transport reduces logistics costs.
API 4F and 7K standards govern structural and hoisting equipment design, while OSHA and state-level oil and gas commissions enforce site-specific safety protocols that shape operator purchasing decisions. EPA methane rules and emerging state-level emissions performance programs are forcing equipment upgrades to low-emission powertrains and closed-loop fluid systems. Stakeholders must monitor regulatory divergence between federal and state jurisdictions when configuring fleet deployment strategies.
Market Dynamics
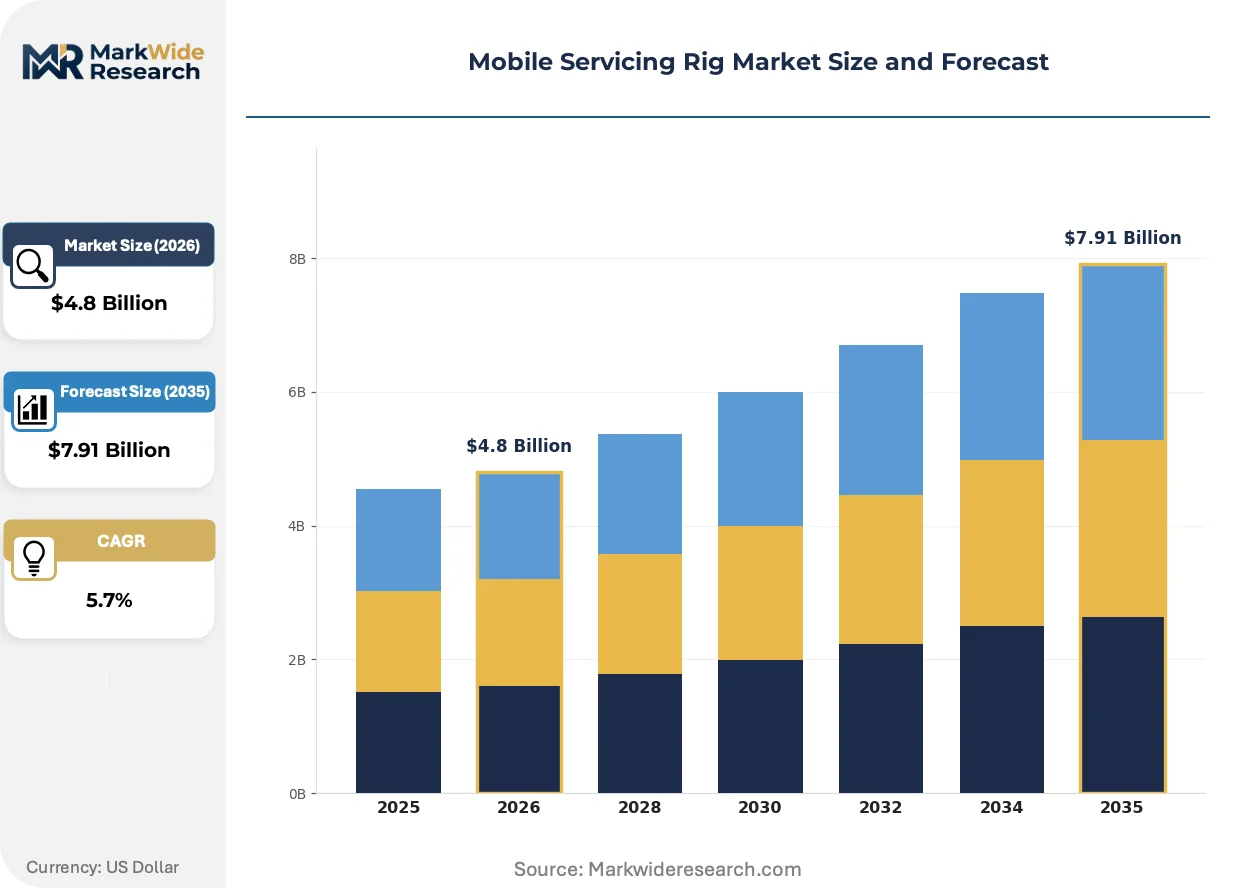
EPA methane performance standards are restructuring capital allocation across the well servicing supply chain, forcing rapid fleet turnover toward low-emission powertrains and closed-loop fluid systems in North American land markets.
Growth Catalysts
- Well intervention intensity:Mature basin decline curves in the Permian Basin of Texas require more frequent workover operations, pulling demand for rapid-deployment truck-mounted units.
- API 4F specification upgrades:Structural and hoisting equipment certification tightening is accelerating replacement cycles among legacy fleet operators seeking highway transportability compliance.
- Pad drilling proliferation:Multi-well site configurations demand rigs capable of rapid redeployment between wellheads without disassembly, favoring self-propelled configurations.
Market Restraints
- Steel and alloy input volatility:Mast and substructure fabrication depends on high-strength steel grades subject to commodity price swings that compress equipment margins.
- Skilled technician scarcity:Certification requirements for API 7K hoisting equipment operation outpace vocational training pipeline output in producing regions.
- Truck chassis supply concentration:Heavy-duty truck manufacturers face production backlogs that extend rig delivery timelines for truck-mounted configurations.
Strategic Opportunities
- Geothermal energy servicing:Closed-loop geothermal systems in the western United States require workover rigs adapted for high-temperature wellbore interventions.
- State-level emissions incentives:California's LCFS and Colorado's methane rules create preferential procurement pathways for dual-fuel and electric powertrain retrofits.
- Modular component standardization:Trailer-mounted segments engineered for componentized transport reduce logistics costs in Middle Eastern desert deployments.
Industry Challenges
- API recertification timelines:Third-party inspection backlogs for 4F and 7K compliance extend equipment downtime and disrupt fleet utilization rates.
- Legacy control system integration:Automated rig control retrofits face compatibility friction with pneumatic and early electronic systems in aging units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Servicing Rig Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skid-Mounted, Trailer-Mounted, Truck-Mounted, Modular Deployment: Onshore, Offshore, Coastal, Desert End User: Oil & Gas, Mining, Energy, Utility Application: Maintenance, Emergency Response, Drilling Support, Repair Services |
| Companies Covered | Schlumberger, LCH Well Servicing, Signal Hill Petroleum, Mesa Well Servicing, Ensign, Axis, Savanna Well Servicing, Guice Engineering, C&J Energy Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Servicing Rig Market Evolving Landscape
Automation and emissions compliance are compressing equipment replacement cycles while reshaping how operators specify powertrain and control architectures for land-based well servicing.
Automated pipe handling systems are converging with real-time torque monitoring to eliminate manual floor operations during workover interventions. Independent operators in the Permian Basin are adopting these packages to reduce crew size requirements and accelerate trip times. The technology is converging with predictive maintenance platforms that compress unplanned downtime intervals and extend mean time between failures.
EPA's methane performance standards for oil and gas infrastructure are mandating closed-loop fluid systems and vapor recovery unit integration on newbuild rigs. Equipment fabricators must now engineer containment specifications that exceed prior API environmental guidelines. Truck-mounted configurations in Texas and New Mexico face the most acute compliance deadlines as state implementation plans accelerate ahead of federal minimums.
Operator procurement patterns now prioritize total cost of ownership metrics over upfront capital expenditure, with fuel efficiency and maintenance interval performance weighted heavily in specification documents. Equipment lessors and integrated service companies are capturing share from independent rig brokers by bundling maintenance and compliance monitoring into long-term contracts. This shift is most visible in the Denver-Julesburg Basin where producer consolidation has concentrated buying power among a handful of supermajors.
Mobile Servicing Rig Market Segmentation
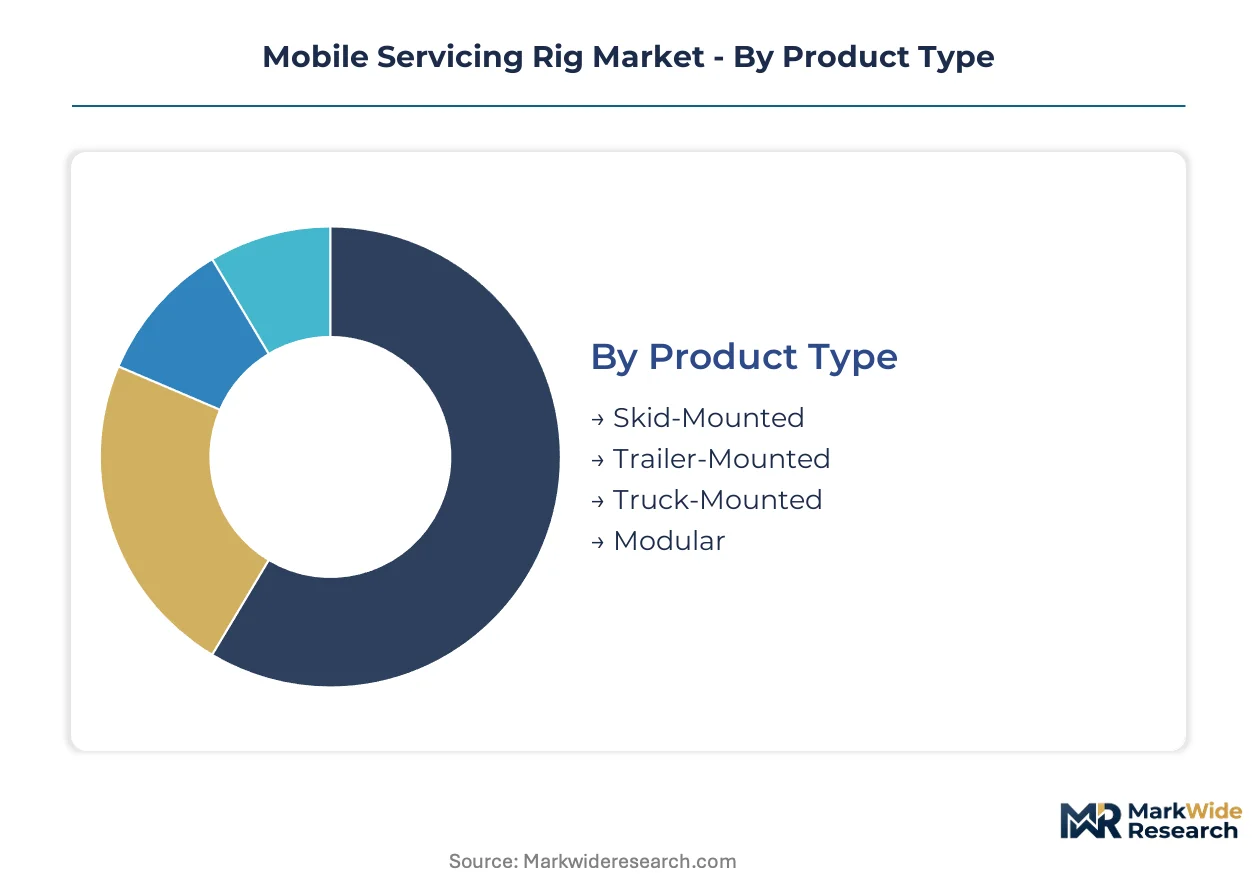
Equipment mobility specifications and powertrain configurations determine procurement patterns across well servicing operations. Segment boundaries reflect divergent capital requirements, regulatory compliance burdens, and logistics constraints that reshape fleet deployment strategies.
Product Type:
Capital intensity varies sharply across mounting configurations, with truck-mounted units demanding the highest upfront investment due to integrated chassis and highway compliance engineering.
- Truck-Mounted:Self-propelled units built on heavy-duty truck chassis deliver highway transportability and sub-24-hour rig-up times. Demand concentrates in the Permian Basin of Texas where pad drilling requires rapid redeployment between wellheads without disassembly. EPA methane performance standards are accelerating fleet turnover toward low-emission powertrains in these configurations.
- Skid-Mounted:Frame-based units without integrated transport require external hauling equipment but offer lower acquisition costs and simpler maintenance access. Mining operations in remote Canadian oil sands and Australian coal seams sustain demand where road infrastructure remains constrained and site permanence reduces mobility requirements.
- Trailer-Mounted:Componentized transport systems reduce logistics costs in coastal and desert deployments where oversized load restrictions apply.
- Modular:Breakdown designs enable helicopter or barge transport to inaccessible wellsites, serving offshore platform maintenance and jungle exploration.
Most installed capacity flows through truck-mounted configurations. Expansion is steepest in modular segments engineered for componentized desert and coastal logistics.
Deployment:
Operating environment dictates structural specifications, with offshore and desert deployments requiring corrosion-resistant materials and extreme-temperature engineering that elevate engineering costs.
- Onshore:Land-based operations dominate unit deployment, with North American shale basins and Middle Eastern oilfields representing the primary demand centers. API 4F structural certification and state-level emissions programs shape equipment specifications across these markets.
- Offshore:Platform-based interventions require compact footprints and explosion-proof electrical systems. North Sea operators and Gulf of Mexico producers drive specification tightening for dynamic positioning compatibility and helicopter transport limits.
- Coastal:Marsh and tidal zone operations in Nigeria's Niger Delta and Louisiana's bayou regions demand amphibious chassis adaptations and saltwater-resistant coatings.
- Desert:High-temperature deployments in Saudi Arabia's Empty Quarter and Algeria's Sahara require enhanced cooling systems and dust filtration engineering.
Onshore environments host the majority of active fleet hours. Coastal applications are gaining share fastest as marginal field development expands in environmentally sensitive shorelines.
End User:
Customer type determines maintenance contract structures and financing arrangements, with oil and gas operators commanding the longest equipment lifecycles and most stringent certification requirements.
- Oil & Gas:Exploration and production companies represent the dominant customer segment, with supermajors and independents specifying API 7K hoisting equipment and closed-loop fluid systems. Well intervention intensity in mature basins is pulling demand for rapid-deployment configurations.
- Mining:Mineral extraction operations require adapted units for dewatering, ventilation shaft maintenance, and exploration drilling. Australian iron ore and Chilean copper belts sustain specialized demand for high-lift capacity and dust-sealed enclosures.
- Energy:Geothermal developers in Nevada and Indonesia are emerging as a distinct customer class, requiring high-temperature wellbore intervention capabilities.
- Utility:Water well drilling and maintenance operations in agricultural regions of India and the US Great Plains utilize lower-horsepower configurations with simplified control systems.
Oil and gas operators account for the largest share of installed base. Energy sector procurement is climbing the fastest as geothermal and carbon capture projects scale.
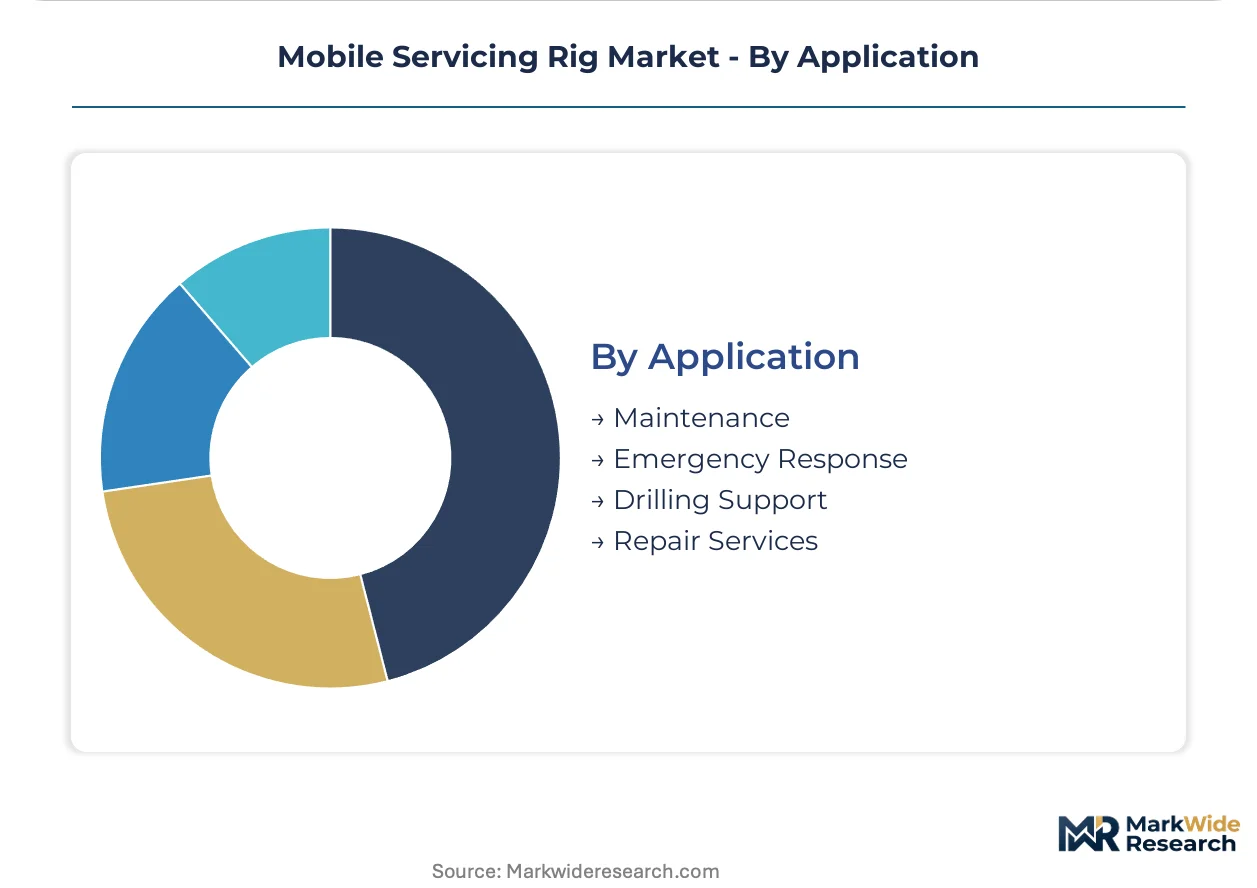
Application:
Service type shapes crew size requirements and equipment utilization rates, with emergency response applications demanding the highest standby availability and fastest mobilization speeds.
- Maintenance:Scheduled workover operations constitute the core revenue stream, requiring predictable mobilization windows and standardized tooling packages. Permian Basin producers are automating pipe handling to compress trip times and reduce crew counts.
- Emergency Response:Blowout control and well kill operations command premium dayrates due to 24-hour standby requirements and specialized safety equipment. Texas Railroad Commission regulations mandate response time commitments that favor locally stationed units.
- Drilling Support:Completion and recompletion activities require integration with fracturing fleets and coiled tubing units.
- Repair Services:Casing repair and fishing operations utilize specialized hoisting configurations and real-time torque monitoring.
Maintenance applications absorb the greatest equipment hours. Emergency response services are expanding most quickly as regulatory pressure intensifies on well control preparedness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The mobile servicing rig industry traces its modern lineage to the Permian Basin of West Texas, where truck-mounted configurations first scaled to meet the demands of intensive well intervention programs across mature oilfields.
United States
Pad drilling proliferation in the Permian Basin and Denver-Julesburg Basin drives demand for rapid-redeployment truck-mounted units. EPA methane performance standards and state implementation plans in Texas and New Mexico accelerate fleet turnover toward low-emission powertrains. Midland-Odessa anchors the densest concentration of active servicing rigs, with producers automating pipe handling to compress crew counts.
Canada
Remote mining operations in the Alberta oil sands and Saskatchewan potash belts sustain demand for skid-mounted configurations where road infrastructure remains constrained. Provincial regulators enforce site-specific safety protocols that exceed federal minimums, shaping operator procurement decisions. Calgary-based equipment lessors capture share through bundled maintenance contracts targeting supermajor consolidation in the Western Canadian Sedimentary Basin.
Saudi Arabia
High-temperature desert deployments in the Empty Quarter require enhanced cooling systems and dust filtration engineering on workover rigs. Saudi Aramco's localization mandates pressure foreign fabricators into joint ventures with domestic partners. Dammam and Khobar industrial zones concentrate rig assembly capacity serving both onshore oilfields and offshore platform maintenance.
China
Shale gas development in Sichuan-Chongqing and tight oil pilot programs in Ordos Basin pull demand for adapted truck-mounted units. MIIT and GB standards govern structural certification, while provincial emissions programs in Beijing-Tianjin-Hebei accelerate dual-fuel retrofits. Chongqing's equipment manufacturing cluster specializes in modular configurations for componentized transport to remote western fields.
Australia
Coal seam gas workover intensity in Queensland's Surat Basin and iron ore dewatering operations in Western Australia sustain specialized demand for high-lift capacity rigs. State-level safety regulators enforce hoisting equipment certification that outpaces vocational training output. Perth-based service companies dominate the offshore platform maintenance segment, integrating vapor recovery systems to meet tightening environmental guidelines.
Mobile Servicing Rig Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology integration and fleet automation capabilities, with integrated service companies commanding longer contract terms and higher asset utilization rates. The vendor base organizes into three tiers: technology-anchored majors with automated control portfolios, geography-focused mid-caps with basin-density strategies, and specialized fabricators serving niche mobility configurations. Consolidation pressure intensifies as equipment lessors bundle compliance monitoring into long-term contracts, displacing independent rig brokers. Dominant competitive moves include strategic partnerships for powertrain electrification and selective capacity expansion in Permian-adjacent service yards.
Within the integrated service tier, Schlumberger anchors positions through technology portfolios spanning automated rig control systems. Ensign and Axis exemplify geography-focused strategies, with the former concentrating fleet density across North American shale basins and the latter specializing in high-mobility configurations engineered for tight wellsite footprints. These three occupy positions that reflect divergent bets on automation capital intensity versus operational flexibility.
| Leading Market Players |
|---|
| Schlumberger |
| LCH Well Servicing |
| Signal Hill Petroleum |
| Mesa Well Servicing |
| Ensign |
| Axis |
| Savanna Well Servicing |
| Guice Engineering |
| C&J Energy Services |
| Others |
Value Network & Pricing Analysis
EPA methane performance standards for oil and gas infrastructure are forcing rapid fleet turnover toward low-emission powertrains, compelling fabricators to absorb engineering cost premiums while buyers demand total cost of ownership transparency over upfront capital expenditure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by automation capability and certification grade. Premium configurations with automated pipe handling and real-time torque monitoring command substantial markups over pneumatic legacy units. Cost compression in standard-tier truck-mounted rigs is intensifying because steel and alloy input volatility squeezes fabrication margins. Independent operators in the Permian Basin exhibit the highest price sensitivity, while supermajors prioritize performance specifications over acquisition cost.
Supply Chain Analysis
Dual-sourcing requirements from major operators mandate qualified suppliers for both heavy-duty truck chassis and high-strength mast steel across the United States, China, and South Korea. Mast and substructure fabrication draws from specialized alloy grades subject to commodity price swings. Single-source vulnerability concentrates in heavy-duty truck chassis manufacturers facing production backlogs. Distribution runs through integrated service companies and equipment lessors capturing share from independent rig brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile servicing rig market functions as a stable compounder anchored by well intervention intensity in mature basins that sustains replacement demand regardless of commodity price cycles.
For Market Incumbents: Deepen backward integration into high-strength steel supply channels to buffer alloy price volatility eroding fabrication margins. Expand automated rig control R&D to defend against technology-anchored majors capturing share through bundled maintenance contracts. Prioritize API 4F and 7K certification investment to accelerate replacement cycles among legacy fleet operators seeking compliance. For New Entrants and Emerging Players: Geothermal developers in Nevada and Indonesia represent an underserved buyer archetype requiring high-temperature wellbore intervention capabilities distinct from oil and gas specifications. Target modular configurations for componentized desert logistics in Middle Eastern markets where oversized load restrictions apply. Pursue joint venture structures with domestic fabricators to satisfy Saudi Aramco localization mandates. For Investors and Strategic Acquirers: Asymmetric upside sits with geography-focused mid-caps concentrating fleet density in Permian-adjacent service yards. The five-to-ten-year viability window favors operators with demonstrated automation integration and compliance monitoring capabilities. Acquisition targets should demonstrate basin-density strategies with embedded maintenance contract revenue. Watch state-level methane implementation plan acceleration as the inflection signal for fleet turnover velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Powertrain Retrofit | California LCFS and Colorado methane rules create preferential procurement pathways for compliant configurations. |
| Automated Pipe Handling Integration | Permian Basin operators adopt packages to reduce crew size requirements and accelerate trip times. |
| Modular Component Standardization | Trailer-mounted segments reduce logistics costs in Saudi Arabia's Empty Quarter desert deployments. |
| Joint Venture Localization | Saudi Aramco mandates pressure foreign fabricators into partnerships with Dammam-based domestic partners. |
| Predictive Maintenance Platform Deployment | Real-time torque monitoring converges with analytics to compress unplanned downtime intervals. |
Research Methodology
Multiple input streams — primary interviews with rig fleet managers, equipment procurement officers, and aftermarket service heads; secondary validation through API certification databases, OSHA enforcement records, and state oil and gas commission filings; plus customs and trade data on steel alloy imports — were reconciled through bottom-up unit deployment counts and top-down market sizing across the analysis window.
Data-stream reconciliation anchored volume and value outputs to modeled segmentation across mounting configuration, powertrain type, deployment environment, and end-user industry. CAGRs were derived from equipment replacement cycle analysis and regulatory compliance deadline mapping. Forecast inputs incorporated well intervention intensity curves in mature basins and state-level emissions program implementation timelines.
Underlying measurement precision varies by segment; truck-mounted configurations carry tighter precision than modular segments due to more transparent fleet registration data. Forecasts reflect assumptions about regulatory enforcement consistency and steel price stabilization. Deviation in EPA methane standard implementation velocity or heavy-duty truck chassis production recovery would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Drones for Oil & Gas Market
Oil & Gas
Global Completion Equipment and Services Market
Oil & Gas
Drilling and Completion Fluids Market
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
Oil & Gas Equipment MRO Market
Oil & Gas
GCC and North Africa Coiled Tubing Market
Oil & Gas
Gabon Oil and Gas Market
Oil & Gas
Open Hole Logging Services Market
Oil & Gas
Oil and Gas Security Services Market
Oil & Gas
Oil Hose Market
Oil & Gas
Venezuela Oil and Gas Market
Oil & Gas
Connected Oil and Gas Market
Oil & Gas
North America Frac Sand Market
Oil & Gas
Digital Oil Rigs Market
Oil & Gas
Africa Natural Gas Market
Oil & Gas
United States Coiled Tubing Market