
 Uk Data Center Cooling Market | 2026-2036
Uk Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Uk Data Center Cooling Market Insights
The UK data center cooling sector is pivoting on a widening split between premium liquid-cooled installations and commodity air-cooled retrofits. Airedale International Air Conditioning leverages its domestic manufacturing base to anchor projects across Greater London and the Midlands. Schneider Electric differentiates through integrated microgrid-to-cooling architectures that sustain margin in hyperscale contracts. Vertiv Group Corp. dominates the retrofit channel with modular thermal units designed for legacy white-space environments.
Data center cooling encompasses the engineered systems—direct expansion refrigerant loops, chiller plants, immersion baths, and thermal energy storage banks—that maintain server inlet temperatures within ASHRAE-specified ranges, typically 18°C to 27°C, while rejecting megawatt-scale heat loads to ambient air, water, or secondary working fluids. Liquid-cooled and immersion cooling segments are capturing the fastest expansion as rack densities exceed 50 kW per cabinet and air-handling reaches physical limits. The chiller systems category retains the largest installed base but faces margin compression from refrigerant phase-down mandates under the F-Gas Regulation. Retrofit installations are emerging as a discrete revenue pool as operators seek to defer capital-intensive new builds.
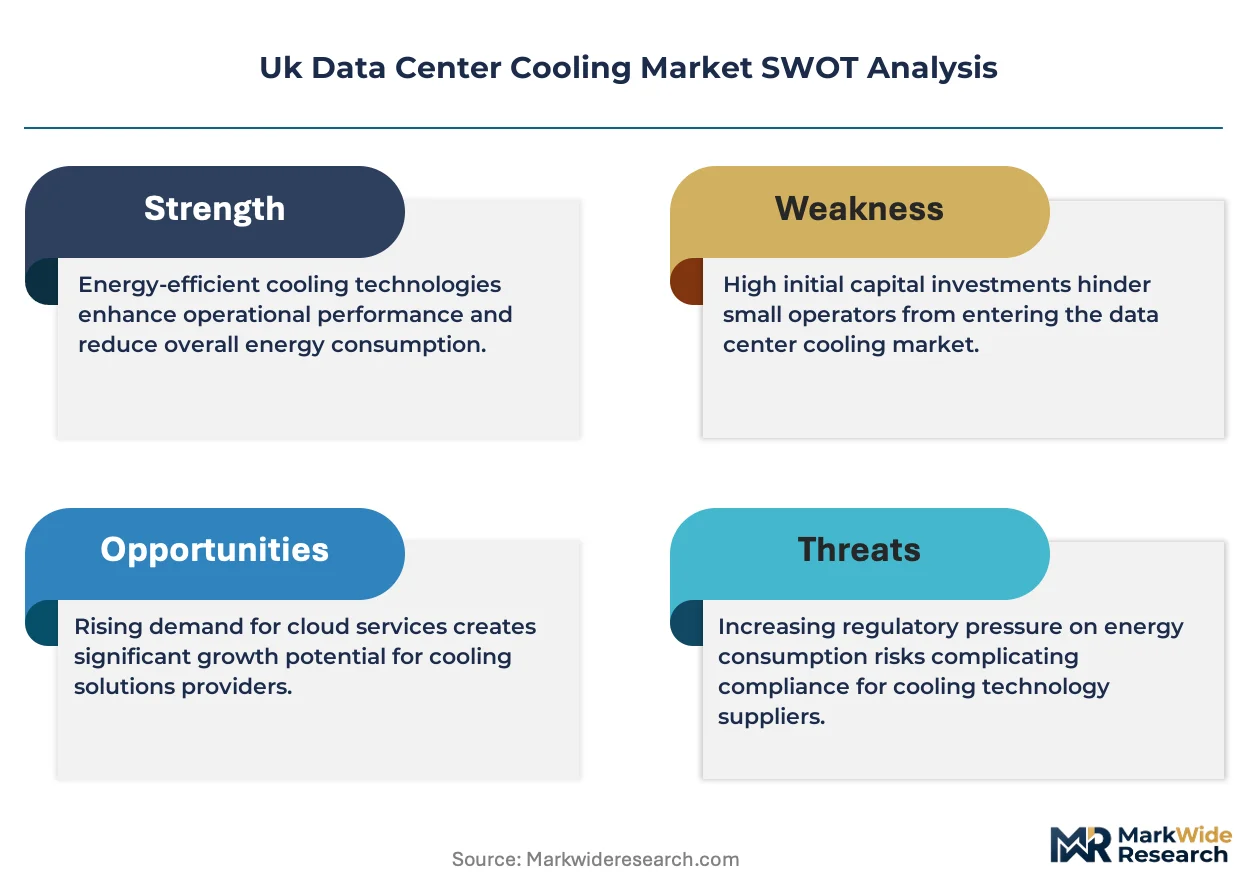
The UK's Building Regulations Part L and the F-Gas Regulation impose efficiency benchmarks and refrigerant containment protocols that reshape equipment procurement specifications. BEIS carbon reporting requirements and emerging CSRD-aligned disclosure rules for data center operators are forcing cooling infrastructure decisions into board-level capital planning. Stakeholders must monitor how Ofgem's grid connection queue reforms and regional water abstraction permits constrain site selection for liquid-cooled facilities.
Market Dynamics
The UK data center cooling market pivots on a structural divergence between legacy air-cooled retrofits and liquid-cooled new builds, with rack power densities above 50 kW per cabinet rendering traditional CRAC units thermally obsolete for hyperscale deployments.
Growth Catalysts
- Building Regulations Part L:Tightening energy efficiency benchmarks under the UK's Part L amendments force operators to specify high-efficiency chillers and heat recovery systems, accelerating equipment replacement cycles.
- Hyperscale expansion:Cloud and colocation operators are commissioning multi-megawatt facilities across the London-Stansted-Cambridge corridor, creating concentrated demand for scalable thermal infrastructure.
- F-Gas Regulation phase-down:The EU F-Gas Regulation's refrigerant quotas are compressing supply of high-GWP working fluids, pushing procurement toward low-GWP alternatives and natural refrigerant systems.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger fabrication depends on base metal prices that have swung 40% in 24-month windows, squeezing margins on fixed-price contracts.
- Grid connection queue congestion:Ofgem's interconnection reforms have lengthened lead times for high-voltage supply to liquid-cooled campuses beyond 36 months in Greater London.
- Water abstraction permitting:Environment Agency restrictions on cooling water withdrawals constrain site selection for direct liquid cooling in southeastern catchments.
Strategic Opportunities
- Manchester and northern clusters:Lower land costs and available grid capacity in Greater Manchester and Leeds are attracting secondary data center developments underserved by incumbent cooling vendors.
- Waste heat recovery integration:District heating network connections allow operators to monetize rejected thermal energy, with BEIS funding streams supporting combined heat-and-power cooling architectures.
- Immersion cooling for AI training:Dielectric fluid baths handling 100+ kW racks are penetrating high-performance computing contracts as GPU densities render air cooling physically impractical.
Industry Challenges
- Refrigerant handling certification:The F-Gas Regulation's mandatory competence requirements for engineers have created a bottleneck, with training capacity lagging deployment timelines by 18-24 months.
- Legacy white-space integration:Retrofitting 15-20 year old facilities with liquid-cooled rear-door heat exchangers requires structural floor loading assessments and containment reconfiguration that extend project durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uk Data Center Cooling Market |
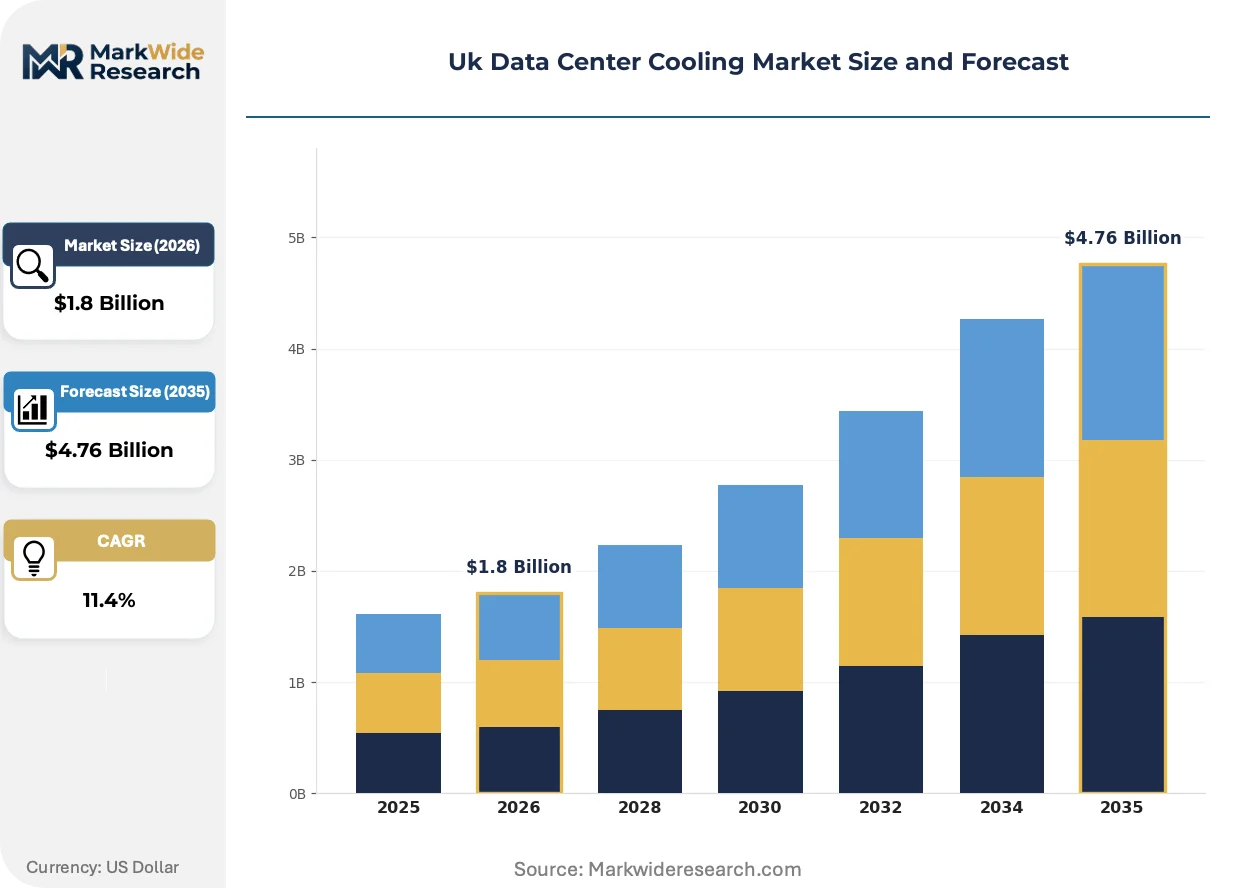
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Type: Air-Cooled, Liquid-Cooled, Evaporative, Heat Exchanger End User: Hyperscale Data Centers, Colocation Providers, Enterprises, Managed Service Providers Technology: Direct Expansion, Chiller Systems, Immersion Cooling, Thermal Energy Storage Installation Type: New Installation, Retrofit, Modular Systems, Custom Solutions |
| Companies Covered | Airedale International Air Conditioning, Vertiv Group Corp., Schneider Electric, Johnson Controls International plc, STULZ GmbH, CoolIT Systems, Carrier, Danfoss, Iceotope Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uk Data Center Cooling Market Trends and Innovations
Liquid cooling architectures are displacing conventional CRAC-based designs across UK hyperscale deployments, with three interconnected shifts reshaping equipment specifications and vendor competitive positioning.
Direct-to-chip cold plates are converging with dielectric immersion systems to form hybrid thermal loops that handle mixed rack densities within single white-space environments. Hyperscale operators in Slough and London are piloting these configurations for AI inference clusters. The convergence is compressing the addressable market for standalone air-cooled chillers below 500 kW capacity.
The F-Gas Regulation's 2024 quota cuts have forced UK distributors to ration high-GWP refrigerant allocations, triggering a specification pivot toward ammonia and CO2-based chillers in new builds. Equipment vendors are re-engineering compressor architectures to accommodate natural refrigerants at the cost of 15-20% capex premiums. Colocation operators with ESG-linked financing are absorbing these premiums to secure supply certainty.
Colocation buyers are unbundling cooling infrastructure from power contracts, negotiating separate thermal service level agreements with specialized engineering firms. This disintermediation fragments the traditional single-source procurement model dominated by integrated electrical-mechanical contractors. The shift is most visible in London's Docklands and City fringe developments where operator sophistication exceeds regional markets.
Uk Data Center Cooling Market Segmentation
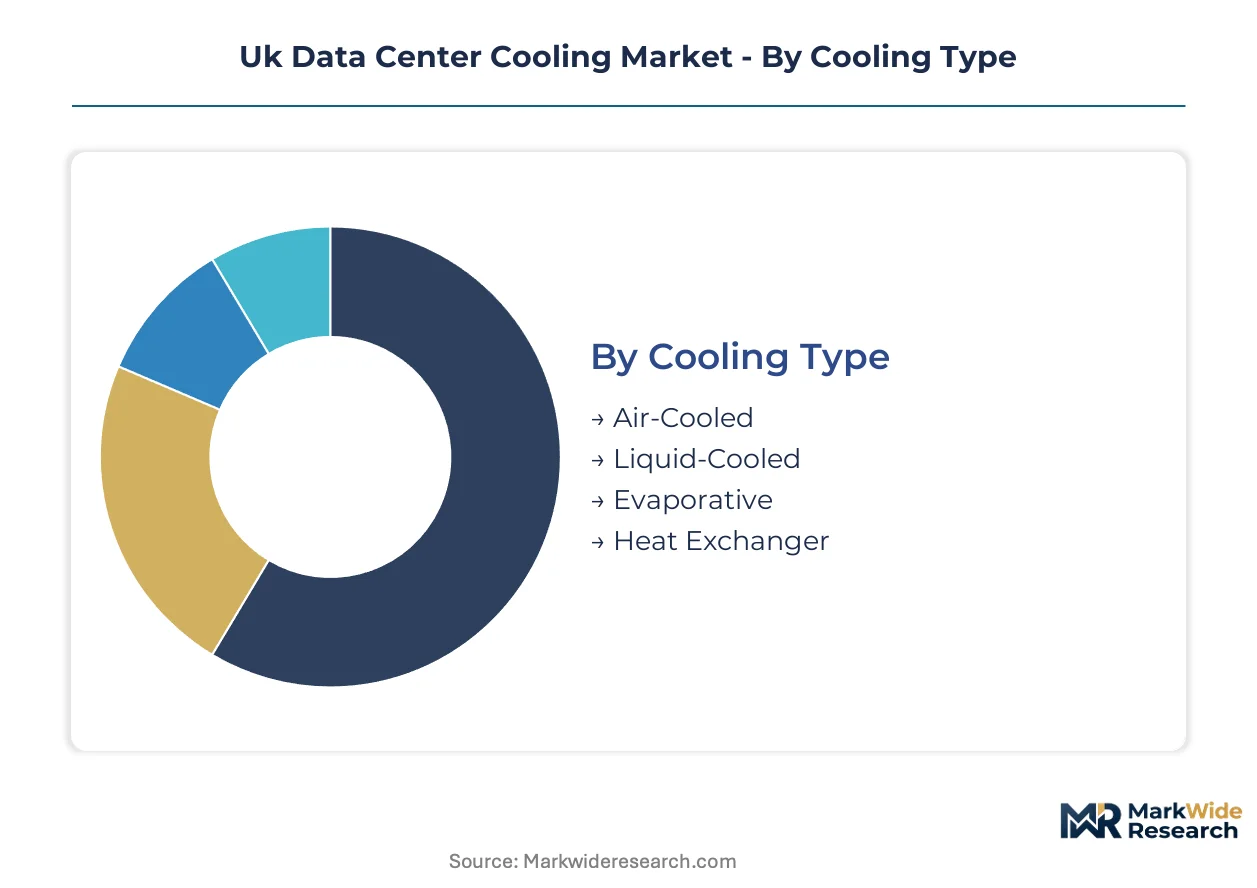
Segmentation in the UK data center cooling market reveals divergent investment priorities across thermal architectures and deployment contexts. Procurement patterns split sharply between legacy facility upgrades and greenfield liquid-cooled campuses, with regulatory pressure and rack density requirements driving category-specific specification shifts.
Cooling Type:
Volume deployment clusters in established air-cooled infrastructure, while premium specifications concentrate in emerging liquid-cooled configurations.
- Liquid-Cooled:Direct-to-chip cold plates and dielectric fluid loops handle rack densities exceeding 50 kW per cabinet. Hyperscale operators in Slough and the London-Stansted-Cambridge corridor specify these systems for AI training clusters where ASHRAE thermal limits exceed air-handling capacity.
- Air-Cooled:Computer room air conditioning units and perimeter CRAC deployments retain the largest installed base across legacy enterprise facilities. Operators defer capital-intensive replacements, sustaining demand for refrigerant-compliant retrofit units under F-Gas Regulation phase-down timelines.
- Evaporative:Adiabatic cooling towers reduce mechanical refrigeration loads in water-permitted locations. Environment Agency abstraction restrictions constrain deployment to northern catchments with available discharge capacity.
- Heat Exchanger:Plate-and-frame and shell-and-tube configurations enable heat recovery integration with district heating networks. BEIS funding streams support deployment in Manchester and Leeds developments.
Mature deployment sits with Air-Cooled. Newer deployment is concentrated in Liquid-Cooled.
End User:
Customer scale determines thermal infrastructure procurement sophistication, with hyperscale operators unbundling cooling from power contracts.
- Hyperscale Data Centers:Cloud operators commission dedicated multi-megawatt facilities with custom thermal loops. Direct engineering relationships with cooling vendors displace traditional contractor intermediation in London fringe developments.
- Colocation Providers:Multi-tenant facilities balance standardized SLAs against heterogeneous tenant density requirements. Docklands operators negotiate separate thermal service level agreements with specialized engineering firms.
- Enterprises:Captive data centers in financial services and telecom verticals prioritize retrofit compatibility over peak efficiency. Building Regulations Part L compliance drives replacement cycles rather than architectural innovation.
- Managed Service Providers:Mid-scale operators seek modular thermal units with rapid deployment profiles. Manchester and northern clusters attract secondary developments underserved by incumbent vendor relationships.
Procurement sophistication peaks with Hyperscale Data Centers. Price-sensitive volume concentrates with Managed Service Providers.
Technology:
Refrigerant chemistry and thermal storage integration are reshaping equipment specifications under regulatory pressure.
- Chiller Systems:Centralized plants using ammonia or CO2 natural refrigerants command specification in new builds. Capex premiums of 15-20% over high-GWP alternatives are absorbed by colocation operators with ESG-linked financing.
- Immersion Cooling:Dielectric fluid baths handle 100+ kW GPU racks for high-performance computing. AI inference pilots in Slough validate hybrid configurations mixing immersion with direct-to-chip loops.
- Direct Expansion:Packaged rooftop and split systems serve sub-500 kW white-space environments. F-Gas Regulation quota cuts compress available refrigerant supply, constraining deployment timelines.
- Thermal Energy Storage:Ice and chilled water banks shift cooling loads off-peak for grid-stressed London facilities. Ofgem connection queue congestion extends payback periods for capital-intensive installations.
Refrigerant transition risk concentrates in Direct Expansion. Steepest expansion trajectory belongs to Immersion Cooling.
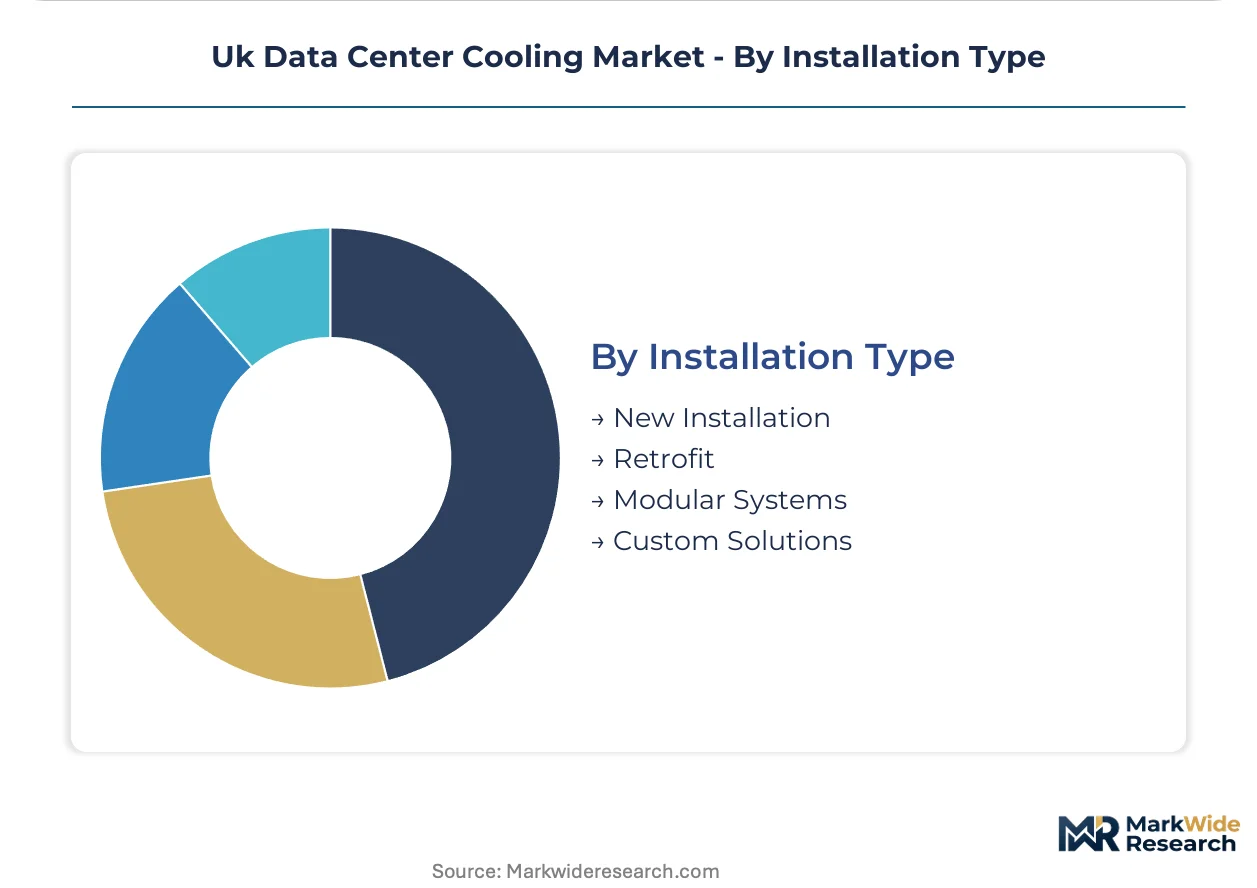
Installation Type:
Deployment context determines project economics, with brownfield constraints extending timelines and fragmenting vendor relationships.
- Retrofit:Rear-door heat exchangers and in-row cooling units upgrade 15-20 year old facilities. Structural floor loading assessments and containment reconfiguration extend project durations in legacy white-space environments.
- New Installation:Greenfield campuses enable optimized thermal loop design from commissioning. Hyperscale developments across the London-Stansted-Cambridge corridor specify integrated microgrid-to-cooling architectures.
- Modular Systems:Factory-integrated thermal units reduce on-site commissioning time for rapid capacity expansion. Vertiv Group Corp. dominates this channel with standardized product platforms.
- Custom Solutions:Bespoke engineering addresses non-standard white-space constraints or extreme density requirements. Airedale International Air Conditioning leverages domestic manufacturing for Greater London and Midlands projects.
Project complexity peaks with Custom Solutions. Volume scaling concentrates with Modular Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The London-Stansted-Cambridge corridor anchors UK data center cooling demand, with hyperscale operators commissioning multi-megawatt facilities across this southeastern concentration. Secondary clusters in Greater Manchester and West Yorkshire are emerging as operators seek lower land costs and available grid capacity outside the congested capital region.
Greater London and the Southeast
Hyperscale cloud operators dominate procurement in Slough and Docklands fringe developments, specifying liquid-cooled architectures for AI training clusters. Building Regulations Part L amendments force replacement of legacy chiller systems in older facilities. The London-Stansted-Cambridge corridor attracts concentrated vendor competition as rack densities exceed 50 kW per cabinet.
West Midlands
Enterprise data centers in Birmingham and Coventry drive retrofit demand for refrigerant-compliant cooling units under F-Gas Regulation timelines. BEIS carbon reporting requirements accelerate equipment replacement cycles in financial services captive facilities. Domestic manufacturing presence in the region supports rapid deployment of modular thermal systems.
Greater Manchester
Colocation operators exploit lower grid connection lead times and available power capacity in Manchester and Salford media city developments. Environment Agency water abstraction permits favor northern catchments for direct liquid cooling deployments. BEIS funding streams support waste heat recovery integration with emerging district heating networks.
Scotland
Cooler ambient temperatures reduce mechanical refrigeration loads in Edinburgh and Glasgow enterprise facilities, favoring free-air cooling configurations. Scottish Government net-zero targets accelerate specifications for natural refrigerant systems. Aberdeen's energy sector data centers pilot immersion cooling for high-performance computing workloads.
Wales
Cardiff and Newport developments attract secondary hyperscale investments seeking alternative locations to saturated English markets. Welsh Government data center investment zones offer streamlined planning permissions for liquid-cooled campuses. Grid capacity constraints in South Wales limit deployment scale compared to northern English alternatives.
Uk Data Center Cooling Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the UK data center cooling sector, creating a tiered competitive structure. Integrated electrical-mechanical contractors dominate new-build hyperscale contracts through single-source procurement relationships. Three strategic archetypes define the vendor base: domestic manufacturers with regional service networks, multinational engineering conglomerates with microgrid integration capabilities, and specialized thermal technology firms with liquid-cooling IP. Competitive moves concentrate on geographic expansion into northern clusters and portfolio diversification toward immersion cooling systems.
Among UK-based engineering specialists, Airedale International Air Conditioning occupies a position exemplifying domestic manufacturing advantage in Greater London and Midlands projects. Vertiv Group Corp. and Schneider Electric represent the multinational tier, with the former anchoring modular retrofit deployments and the latter exemplifying integrated microgrid-to-cooling architectural capabilities. These three firms collectively illustrate the competitive spectrum from regional service depth to global technology integration.
| Leading Market Players |
|---|
| Airedale International Air Conditioning |
| Vertiv Group Corp. |
| Schneider Electric |
| Johnson Controls International plc |
| STULZ GmbH |
| CoolIT Systems |
| Carrier |
| Danfoss |
| Iceotope Technologies |
| Others |
Pricing and Supply Chain Analysis
A performance-efficiency bifurcation between liquid-cooled premium installations and air-cooled commodity retrofits shapes both procurement economics and sourcing configurations across UK data center cooling. F-Gas Regulation quota constraints and Building Regulations Part L compliance costs concentrate margin pressure on refrigerant-dependent tiers while rewarding natural refrigerant architectures with supply certainty.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for hyperscale operators, with thermal service level agreements commanding premiums tied to ASHRAE compliance assurance. Three-tier pricing structure across premium liquid-cooled, standard modular air-cooled, and economy retrofit units reflects certification grade and after-sales bundling differentiation. Cost compression in air-cooled chiller segments is intensifying because copper and aluminum input volatility squeezes fixed-price contract margins. Managed service providers exhibit highest price sensitivity, while hyperscale cloud operators absorb capex premiums for ESG-linked financing access.
Supply Chain Analysis
UK domestic-content preferences under BEIS procurement guidelines are reshaping sourcing toward Greater London and Midlands manufacturing footprints. Heat exchanger fabrication draws from Germany, China, and domestic UK suppliers for base metal inputs. Compressor assemblies and dielectric fluids for immersion systems rest on single-source vulnerability from specialized chemical producers. Distribution runs through integrated electrical-mechanical contractors for new builds and specialized engineering firms for retrofit deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grid connection queue congestion functions as the binding capacity constraint, extending lead times beyond thirty-six months in Greater London and propping pricing power for vendors with available inventory.
For Market Incumbents: Extend service network density into Manchester and Leeds clusters before secondary developers lock in vendor relationships. Defend against modular retrofit specialists by certifying engineering teams under F-Gas Regulation competence requirements faster than training bottlenecks allow. Prioritize backward integration into heat exchanger fabrication to offset base metal price volatility exposure. For New Entrants and Emerging Players: A mid-market price-point gap between premium liquid-cooled installations and economy air-cooled retrofits opens white-space in standardized modular thermal units for rapid-deployment colocation contracts. Target Manchester and northern England developments where incumbent vendor relationships remain underdeveloped. Pursue direct engineering relationships with hyperscale operators seeking to unbundle cooling from power procurement. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational engineering conglomerates seeking liquid-cooling IP and UK service infrastructure. Long-term viability favors vendors with demonstrated F-Gas Regulation compliance architectures and district heating network integration capabilities. Watch Environment Agency water abstraction permit allocations as the inflection signal for direct liquid cooling deployment scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Transition | Ammonia and CO2 compressor architectures secure supply certainty under F-Gas Regulation quota cuts. |
| Waste Heat Recovery Integration | District heating network connections monetize rejected thermal energy in Manchester and Leeds developments. |
| Immersion Cooling Scale-Up | Dielectric fluid bath deployments capture AI training cluster contracts as GPU densities exceed air-handling limits. |
| Modular Retrofit Platform Expansion | Factory-integrated thermal units reduce commissioning timelines for legacy white-space upgrades. |
| Northern Cluster Geographic Expansion | Greater Manchester and West Yorkshire developments exploit lower grid connection lead times versus London. |
Research Methodology
Document review covered Environment Agency permitting databases, Ofgem grid connection queue records, and BEIS funding stream disclosures, complemented by interviews with data center engineering directors, thermal infrastructure procurement leads, and F-Gas Regulation compliance officers. Secondary validation drew from equipment vendor technical specifications, hyperscaler capex disclosures, and Building Regulations Part L amendment tracking. Bottom-up installation unit economics were triangulated against top-down market sizing from regional development pipeline analysis.
Historical deployment patterns were cross-referenced against panel input from cooling system specifiers to anchor growth assumptions across the analysis window. Segmentation modeling incorporated cooling type, end-user scale, refrigerant technology, and installation context dimensions. CAGRs were derived from capacity expansion announcements and regulatory compliance timeline impacts. Forecast inputs included rack density trajectories from GPU server roadmaps and F-Gas Regulation phase-down schedules.
Inputs from Environment Agency abstraction permit registers and Ofgem interconnection reform documentation were available through the study window; gaps in real-time grid connection queue position data introduce uncertainty bands around deployment timing assumptions. Forecasts reflect documented regulatory trajectories and announced hyperscale capacity commitments. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Saudi Arabia Data Center Cooling Market
Data Center Cooling
Data Center Cooling Market
Data Center Cooling
India Data Center Cooling Market
Data Center Cooling
China Study of Data Center Water Consumption Market
Data Center Cooling
Italy Data Center Cooling Market
Data Center Cooling
North America Data Center Cooling Market
Data Center Cooling
Immersion Cooling Market
Data Center Cooling
Indonesia Data Center Cooling Market
Data Center Cooling
Australia Data Center Cooling Market
Data Center Cooling
Saudi Arabia Study of Data Center Water Consumption Market
Data Center Cooling
Adiabatic Dry Cooler Market
Data Center Cooling
Latin America Data Center Cooling Market
Data Center Cooling
CPU Water Cooling Radiator Market
Data Center Cooling
New Zealand Data Center Cooling Market
Data Center Cooling
Brazil Data Center Cooling Market
Data Center Cooling
Philippines Data Center Cooling Market