
 Middle East and Africa Data Center Cooling Market | 2026-2036
Middle East and Africa Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Data Center Cooling Market Foresight
Tier-III and Tier-IV reliability specifications is unwinding legacy cooling architectures across the Middle East and Africa. Schneider Electric SE leverages its integrated power and cooling portfolio to anchor large-scale deployments in the UAE and Saudi Arabia. STULZ GmbH specializes in precision air conditioning systems that dominate financial services and telecom installations. Munters Group AB competes through evaporative cooling expertise suited to the region's arid climate extremes.
Middle East and Africa data center cooling encompasses engineered thermal management systems—chillers, computer room air conditioning units, cooling towers, and rack-level liquid coolers—designed to maintain ambient temperatures between 18°C and 27°C per ASHRAE guidelines for IT equipment reliability. These systems prevent thermal throttling, extend server lifespan, and enable continuous operation of high-density compute infrastructure in ambient conditions exceeding 45°C. Liquid cooling deployments are outpacing air-based alternatives as rack densities surpass 30 kW in AI training clusters. Cloud service providers represent the fastest-growing end user segment, while colocation providers sustain the largest installed base of retrofitted CRAC units across existing facilities.
Saudi Arabia's Communications and Information Technology Commission and South Africa's National Energy Regulator impose efficiency standards that shape equipment procurement and facility design across their jurisdictions. The UAE's MOHAP-aligned green building certifications and adherence to ISO 50001 energy management standards further constrain conventional mechanical cooling approaches. Stakeholders must weigh capital intensity against operational savings as regional regulators tighten carbon disclosure requirements and water usage restrictions intensify site selection constraints.
Market Dynamics
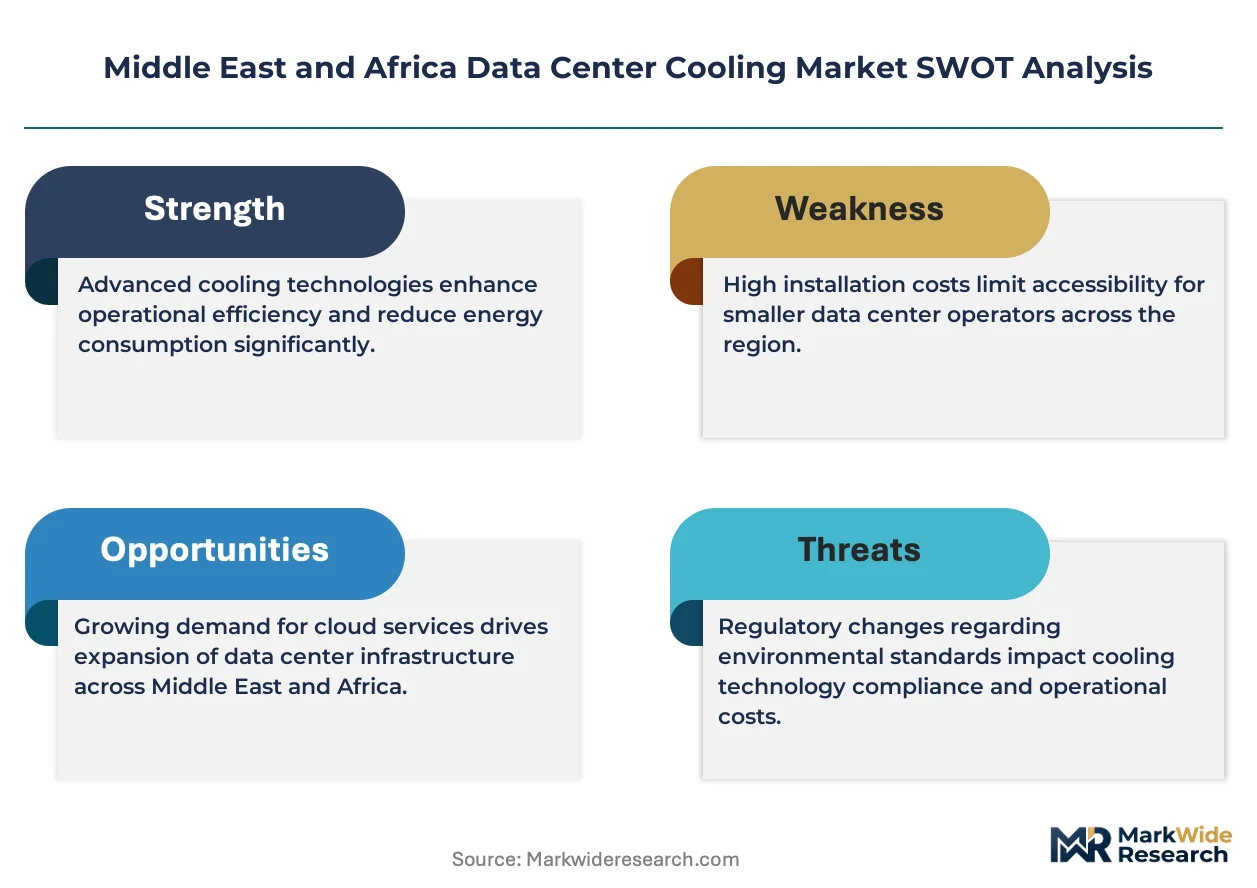
Liquid cooling architectures are displacing legacy air-based systems as hyperscale operators in the Gulf Cooperation Council deploy AI training clusters exceeding 30 kW per rack, forcing infrastructure retrofits across existing facilities.
Growth Catalysts
- Saudi Arabia's data center localization mandates:The Communications and Information Technology Commission requires domestic data sovereignty, compelling international cloud providers to build greenfield facilities with advanced thermal management.
- Evaporative cooling adoption:Arid climate conditions across the UAE and Jordan favor adiabatic systems that reduce mechanical refrigeration loads and water consumption compared to conventional chillers.
- AI workload concentration:Financial services and telecom operators in Johannesburg and Lagos are deploying high-density compute for fraud detection and network optimization, driving precision cooling demand.
Market Restraints
- Capital intensity of liquid cooling retrofits:Existing Tier-II facilities in Egypt and Morocco face prohibitive infrastructure overhaul costs to accommodate direct-to-chip cooling manifolds.
- Skilled technician scarcity:The region lacks sufficient certified personnel for refrigerant handling and leak detection in fluorinated gas systems, extending deployment timelines.
- Water access constraints:Cooling tower operations in water-stressed zones including Qatar and Kuwait confront regulatory restrictions on consumption that limit evaporative system sizing.
Strategic Opportunities
- Nigeria's emerging data center corridor:Lagos and Abuja exhibit underpenetrated colocation capacity with rising enterprise cloud adoption creating first-mover positioning for modular cooling deployments.
- ISO 50001 energy management integration:UAE facilities pursuing MOHAP-aligned green building certifications can capture operational savings through intelligent cooling controls and heat recovery systems.
- Immersion cooling for cryptocurrency mining:Kenya and Ethiopia's renewable energy surpluses attract compute-intensive operations requiring dielectric fluid cooling solutions outside traditional data center standards.
Industry Challenges
- Refrigerant phase-down compliance:South Africa's National Energy Regulator enforcement of F-gas restrictions complicates spare parts sourcing for installed R-410A chiller fleets.
- Legacy CRAC integration complexity:Hybrid air-liquid architectures in Dubai's existing colocation facilities require bespoke control system programming to prevent thermal stratification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Data Center Cooling Market |
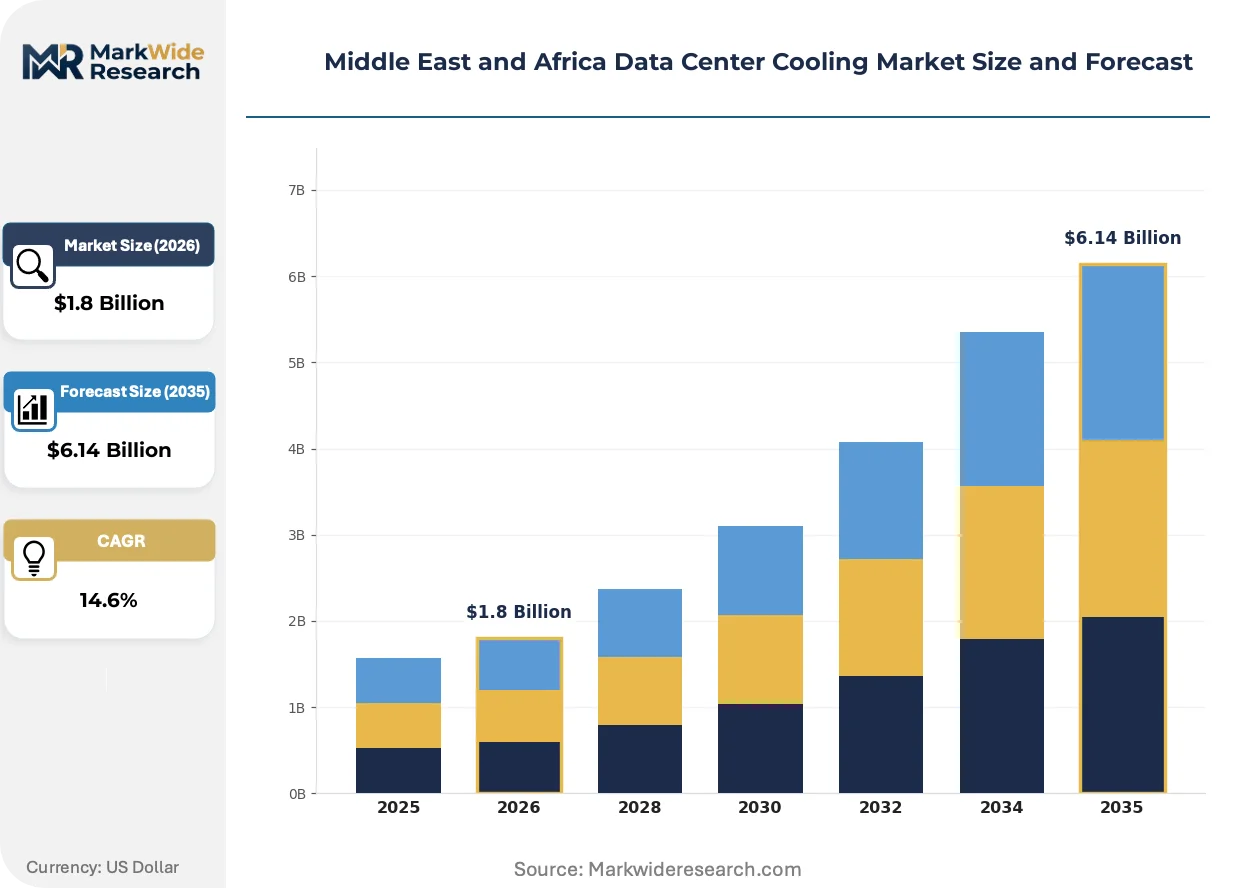
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Technique: Air Cooling, Liquid Cooling, Direct Expansion, Evaporative Cooling End User: Cloud Service Providers, Telecom Operators, Colocation Providers, Enterprises Component: Chillers, CRAC Units, Cooling Towers, Rack Coolers Deployment Model: On-Premises, Hybrid, Managed Services, Hosted Solutions |
| Companies Covered | Schneider Electric SE, Daikin Industries Ltd, Johnson Controls International Plc, Mitsubishi Electric Corporation, Vertiv Group Corp., STULZ GmbH, Munters Group AB, Rittal GmbH & Co. KG, Eaton, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Data Center Cooling Market Shifts & Advancements
Thermal management architectures are converging with power infrastructure as rack densities render traditional compartmentalized design obsolete across Middle Eastern hyperscale builds.
Direct liquid cooling is displacing perimeter CRAC units in Saudi Arabian AI facilities. Cloud operators in Riyadh's King Abdullah Financial District are deploying cold plate manifolds for GPU clusters. This shift is compressing mechanical infrastructure footprints and reallocating floor space to revenue-generating compute.
South Africa's National Energy Regulator has tightened efficiency standards for mechanical cooling systems above 100 kW capacity. Data center operators in Johannesburg must now demonstrate part-load performance metrics to secure operating permits. Colocation providers are responding with variable-speed chiller retrofits and free cooling economizer additions.
Cloud service providers are consolidating vendor relationships for integrated power and thermal packages. Large hyperscale tenders in the UAE now specify single-source accountability for UPS, busway, and cooling distribution. This preference restructuring favors turnkey suppliers over specialized component vendors in Dubai's procurement landscape.
Middle East and Africa Data Center Cooling Market Segmentation
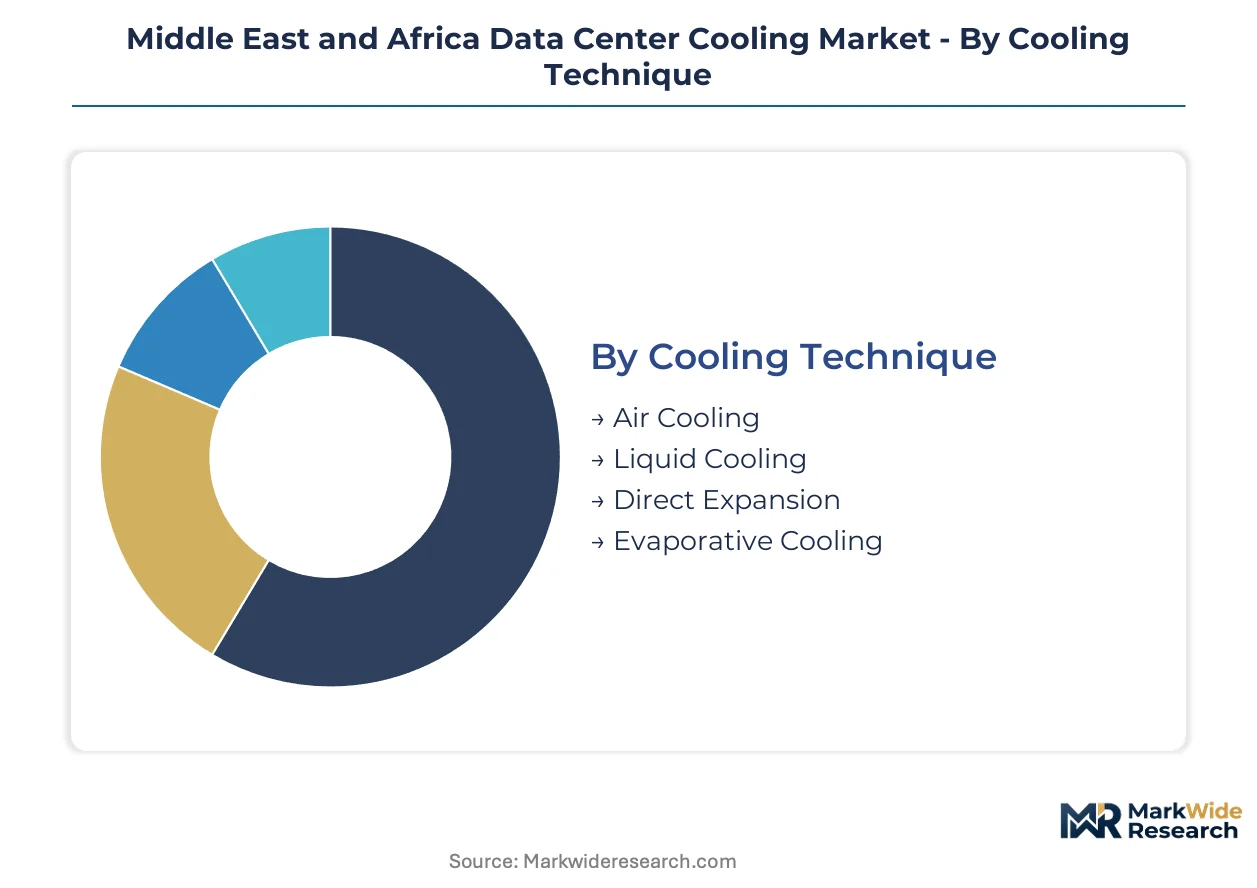
Cooling technique selection in the Middle East and Africa hinges on ambient climate severity and rack density requirements. End-user procurement patterns diverge sharply between hyperscale cloud builds and legacy enterprise retrofits. Component and deployment choices cascade from these upstream decisions, creating distinct channel economics across each segment boundary.
Cooling Technique:
Channel flow splits between direct manufacturer relationships for hyperscale liquid cooling and distributor networks for conventional air systems serving mid-market facilities.
- Liquid Cooling:Direct-to-chip and immersion architectures circulate dielectric fluids or water-glycol mixtures to capture heat at the server level. Cloud service providers in Riyadh and Dubai specify these systems for AI training clusters exceeding 30 kW per rack, driven by Saudi Arabia's data localization mandates and the impossibility of air-cooling such densities.
- Evaporative Cooling:Adiabatic systems exploit the region's arid climate to achieve sub-wet-bulb temperatures without mechanical refrigeration. Colocation providers in Jordan and the UAE favor these installations for their reduced water consumption versus traditional cooling towers and elimination of refrigerant compliance burdens.
- Air Cooling:Perimeter CRAC and in-row units remain prevalent in legacy Tier-II facilities across Egypt and Morocco where retrofit capital is constrained.
- Direct Expansion:Self-contained DX systems serve edge compute nodes and small enterprise server rooms requiring rapid deployment without chilled water infrastructure.
By volume, Air Cooling leads. By growth pace, Liquid Cooling is gaining share fastest.
End User:
Procurement scale and technical sophistication create three distinct customer tiers with diverging vendor engagement models.
- Cloud Service Providers:Hyperscale operators including AWS, Microsoft Azure, and Google Cloud drive specification-setting for the entire market through tenders exceeding 50 MW per facility. These buyers demand integrated power-cooling packages with single-source accountability, compressing margins for component specialists while rewarding turnkey system integrators.
- Colocation Providers:Equinix, Khazna, and regional operators manage the largest installed base of retrofitted cooling infrastructure across Dubai, Johannesburg, and Lagos. Their hybrid upgrade cycles—mixing liquid cooling for high-density suites with retained air systems for legacy clients—create complex maintenance ecosystems.
- Telecom Operators:MTN, Etisalat, and STC deploy precision cooling for central office transformations and 5G edge facilities, prioritizing reliability over efficiency given regulatory uptime requirements.
- Enterprises:Financial services and government entities in Nigeria and Kenya represent fragmented demand served through systems integrators and value-added distributors.
Cloud Service Providers command the highest per-site expenditure. Colocation Providers generate the most recurring maintenance revenue.
Component:
Margin structures vary dramatically between commodity mechanical equipment and precision thermal hardware requiring specialized installation.
- Chillers:Centrifugal and screw compressor units above 500 kW capacity anchor central plant designs in hyperscale facilities. South Africa's National Energy Regulator efficiency standards for mechanical cooling systems above 100 kW are forcing variable-speed retrofits and free cooling economizer additions in Johannesburg.
- Rack Coolers:Rear-door heat exchangers and in-row cooling units bridge air and liquid architectures in hybrid facilities. Demand concentrates in Dubai's existing colocation sites where thermal stratification risks prevent wholesale infrastructure replacement.
- CRAC Units:Computer room air conditioning remains the default for sub-10 kW rack densities across North African enterprise facilities.
- Cooling Towers:Open and closed-circuit designs face sizing constraints in water-stressed Qatar and Kuwait where regulatory restrictions limit evaporative system deployment.
Chillers absorb the largest share of capital budgets. Rack Coolers show the steepest expansion trajectory.
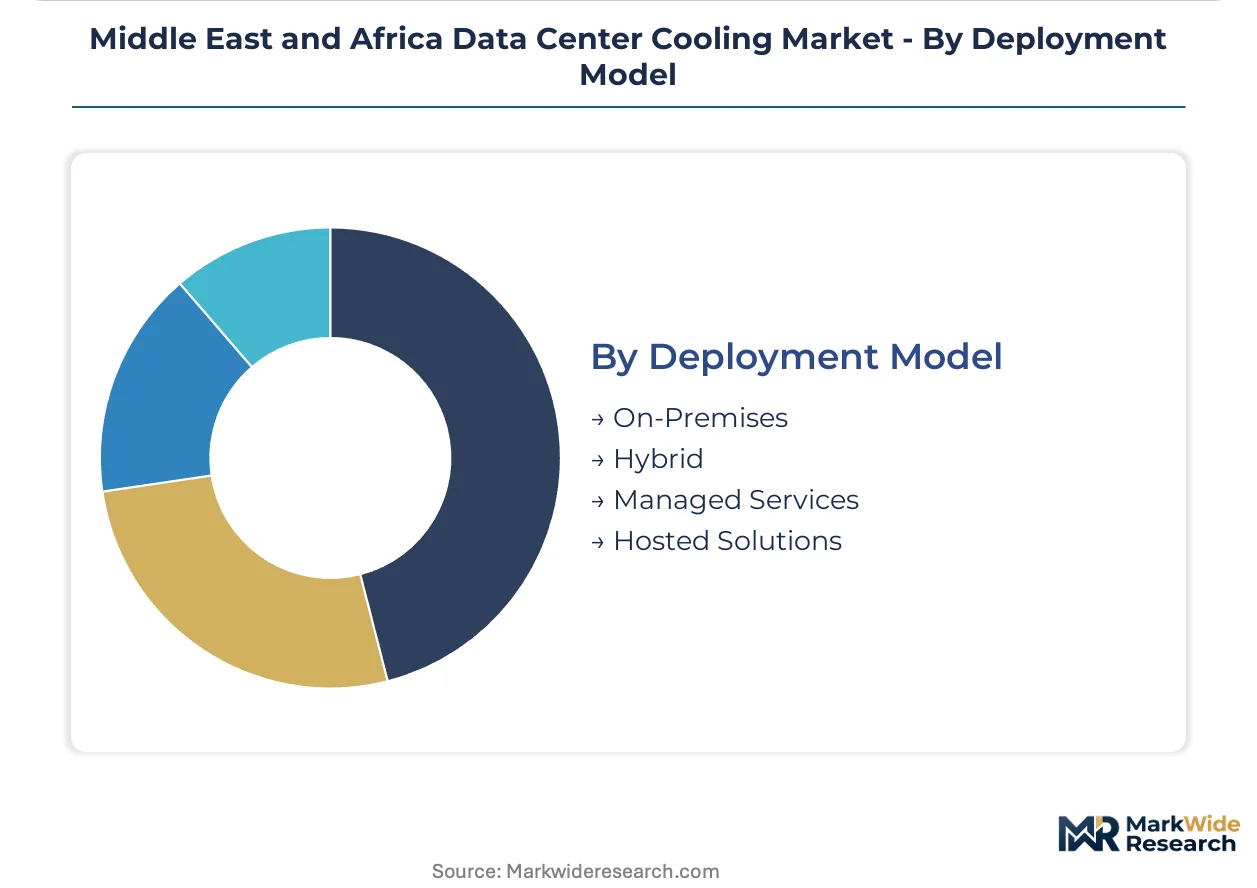
Deployment Model:
Operational risk allocation between customer and vendor determines contract structures and cooling system ownership.
- On-Premises:Customer-owned and operated infrastructure dominates in Saudi Arabia where data sovereignty requirements preclude third-party facility management. CITC licensing conditions effectively mandate direct capital deployment by international cloud providers.
- Managed Services:Outsourced thermal operations appeal to Nigerian and Kenyan enterprises lacking in-house critical facilities expertise. Schneider Electric and STULZ offer performance-contracting arrangements guaranteeing PUE targets.
- Hybrid:Split responsibility models—customer-owned cooling with vendor-managed maintenance—prevail in South African colocation where B-BBEE ownership requirements complicate full outsourcing.
- Hosted Solutions:Pure rental of cooled rack space without infrastructure ownership attracts cryptocurrency miners to Ethiopia and Kenya's renewable energy zones.
On-Premises deployment captures the greatest absolute investment. Managed Services is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale facility construction concentrates in Gulf Cooperation Council member states where energy subsidies and sovereign capital availability lower thermal infrastructure deployment barriers. South Africa anchors sub-Saharan capacity through Johannesburg's financial services concentration. Regulatory divergence between Saudi data sovereignty mandates and South African energy efficiency enforcement shapes divergent equipment procurement patterns.
Saudi Arabia
Riyadh's King Abdullah Financial District hosts GPU-intensive AI training clusters exceeding 30 kW per rack. The Communications and Information Technology Commission mandates domestic data sovereignty, compelling international cloud providers to build greenfield facilities with advanced liquid cooling. STULZ GmbH and Schneider Electric SE anchor large-scale deployments across the capital's emerging hyperscale corridor.
United Arab Emirates
Dubai's colocation providers manage the region's largest installed base of retrofitted CRAC units alongside new liquid-cooled high-density suites. MOHAP-aligned green building certifications and ISO 50001 energy management standards constrain conventional mechanical cooling approaches. Free zone incentives in Dubai Internet City accelerate modular cooling deployments for enterprise cloud adoption.
South Africa
Johannesburg's financial services and telecom operators deploy precision cooling for fraud detection and network optimization workloads. The National Energy Regulator enforces efficiency standards for mechanical cooling systems above 100 kW, forcing variable-speed chiller retrofits and free cooling economizer additions. B-BBEE ownership requirements complicate full outsourcing of thermal operations.
Nigeria
Lagos and Abuja exhibit underpenetrated colocation capacity with rising enterprise cloud adoption creating first-mover positioning for modular cooling deployments. Managed services appeal to enterprises lacking in-house critical facilities expertise. Performance-contracting arrangements guaranteeing PUE targets attract international systems integrators to the emerging corridor.
Egypt
Cairo's existing Tier-II facilities face prohibitive infrastructure overhaul costs to accommodate direct-to-chip cooling manifolds. Legacy CRAC integration complexity in hybrid air-liquid architectures requires bespoke control system programming. Skilled technician scarcity for refrigerant handling and leak detection extends deployment timelines across North African enterprise facilities.
Middle East and Africa Data Center Cooling Market Competitive Landscape
Concentration sits with integrated power and cooling specialists capable of delivering turnkey infrastructure packages to hyperscale operators. The vendor base spans three distinct tiers: diversified industrial conglomerates with broad electromechanical portfolios, precision climate specialists focused on critical facilities, and regional systems integrators serving fragmented enterprise demand. Strategic moves center on consolidated vendor relationships for single-source accountability and geographic expansion through local partnership structures to navigate data sovereignty requirements.
Within the integrated infrastructure tier, Schneider Electric SE and Vertiv Group Corp exemplify the shift toward unified power-thermal procurement specifications. STULZ GmbH occupies a specialist position in precision air conditioning systems, while Munters Group AB anchors evaporative cooling expertise suited to arid climate extremes. Johnson Controls International Plc and Daikin Industries Ltd represent diversified industrial players leveraging scale advantages across mechanical equipment categories. These archetypes reflect the market's bifurcation between hyperscale turnkey demand and legacy retrofit fragmentation.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Daikin Industries Ltd |
| Johnson Controls International Plc |
| Mitsubishi Electric Corporation |
| Vertiv Group Corp. |
| STULZ GmbH |
| Munters Group AB |
| Rittal GmbH & Co. KG |
| Eaton |
| Others |
Supply & Pricing Matrix
ISO 50001 energy management certification gates both supplier qualification and price differentiation across Middle East and Africa data center cooling procurement, compressing margins for uncertified component vendors while rewarding integrated system providers with premium positioning. Buyers in Saudi Arabia and the UAE demand documented efficiency performance as a condition of vendor approval, creating tiered access that separates turnkey specialists from commodity equipment distributors.
Pricing Analysis
South Africa's National Energy Regulator dictates the pricing tier structure for mechanical cooling systems above 100 kW capacity, forcing variable-speed chiller retrofits and free cooling economizer additions that stratify offerings across certified and non-certified equipment tiers. Three-tier pricing structure across premium, standard, and economy levels reflects compliance depth, with hyperscale cloud providers in Riyadh and Dubai showing lowest price sensitivity due to sovereign data localization mandates. Cost compression in mid-market air-cooled segments is intensifying because Egyptian and Moroccan Tier-II facilities lack retrofit capital, squeezing distributor margins.
Supply Chain Analysis
Germany and the United States anchor precision chiller and compressor manufacturing for Middle East and Africa hyperscale deployments, while China supplies heat exchangers and control systems at scale. Supply chains draw from copper tubing, refrigerant gases, and precision electronics as core inputs, with fluorinated gas phase-down regulations in South Africa creating single-source vulnerability for R-410A replacement components. Distribution runs through Dubai's free zone logistics hubs before final-mile deployment to Riyadh, Johannesburg, and Lagos facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Immersion cooling for cryptocurrency mining in East African renewable energy zones threatens to commoditize thermal management expertise outside traditional data center standards, forcing incumbent infrastructure specialists to defend value propositions against unconventional substitute architectures.
For Market Incumbents: Compound defensive positioning by deepening captive supply of dielectric fluids and cold plate manifolds to offset margin erosion from modular cooling entrants targeting Nigeria's underpenetrated colocation corridor. Lock in long-term service contracts with Saudi CITC-licensed facilities before localization mandates mature, as regulatory compliance expertise becomes the primary retention lever against Chinese equipment suppliers. For New Entrants and Emerging Players: Lead with managed services performance contracting in Lagos and Abuja, where enterprise cloud adoption outpaces local critical facilities expertise and PUE guarantees differentiate against capital-sale competitors. Target modular evaporative cooling deployments for Jordanian and UAE colocation providers seeking adiabatic retrofits without full infrastructure replacement, using water consumption benchmarks as the primary technical wedge. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liquid cooling sub-segments as rack densities surpass 30 kW in AI training clusters, compressing payback periods for precision thermal hardware specialists relative to conventional air-conditioning vendors. Acquisition candidates should demonstrate installed base density in Riyadh or Dubai with recurring maintenance revenue streams; the signal to watch is CITC licensing velocity for international cloud providers as a proxy for greenfield capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Power-Cooling Package Consolidation | Single-source accountability for UPS, busway, and cooling distribution compresses vendor margins while rewarding turnkey specialists in UAE hyperscale tenders. |
| Refrigerant Phase-Down Compliance Investment | R-410A replacement capability in South Africa and Saudi Arabia separates qualified suppliers from stranded inventory holders facing spare parts sourcing restrictions. |
| Managed Services Performance Contracting | PUE guarantee structures in Nigeria and Kenya capture enterprise demand lacking in-house critical facilities expertise while locking in recurring revenue. |
| Evaporative Cooling System Expansion | Adiabatic deployment in Jordan and UAE free zones exploits arid climate advantages while sidestepping mechanical refrigeration efficiency standards. |
| Localization Partnership Structuring | B-BBEE ownership compliance in South Africa and CITC data sovereignty requirements in Saudi Arabia mandate joint venture architectures for international vendors. |
Research Methodology
Cross-validation between primary interviews with data center facility managers, thermal infrastructure procurement officers, and cloud provider engineering leads and secondary sources including SEC hyperscaler capex disclosures, CITC licensing registries, and South African National Energy Regulator efficiency filings anchors the qualitative findings. Bottom-up equipment shipment tracking and top-down facility construction pipeline analysis triangulate market sizing across cooling technique, end user, and component segmentation.
Sensitivity analysis around Saudi localization mandate enforcement timelines and UAE green building certification adoption rates stress-tests volume projections across the projection horizon. The analytical framework models cooling technique selection, deployment model ownership structures, and regional regulatory cluster divergence as primary segmentation dimensions, with CAGRs derived from facility construction spend allocation patterns and equipment replacement cycle analysis. Rack density trajectories in AI training clusters and water access constraints in Qatar and Kuwait serve as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained sovereign capital availability in Gulf Cooperation Council member states or accelerated F-gas restriction enforcement in South Africa would require recalibration. Forecasts reflect documented assumptions regarding hyperscale facility commissioning schedules and efficiency standard implementation timelines. Recalibration cycles align with material shifts in CITC licensing velocity, National Energy Regulator enforcement actions, and MOHAP certification adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Data Center Liquid Cooling Market
Data Center Cooling
AI Datacenter Liquid Cooling Market
Data Center Cooling
Malaysia Data Center Cooling Market
Data Center Cooling
North America Data Center Cooling Market
Data Center Cooling
United States Data Center Cooling Market
Data Center Cooling
India Data Center Cooling Market
Data Center Cooling
South Korea Data Center Cooling Market
Data Center Cooling
Mexico Data Center Cooling Market
Data Center Cooling
New Zealand Data Center Cooling Market
Data Center Cooling
Philippines Data Center Cooling Market
Data Center Cooling
Hong Kong Data Center Cooling Market
Data Center Cooling
Germany Data Center Cooling Market
Data Center Cooling
Immersion Cooling Market
Data Center Cooling
Europe Data Center Cooling Market
Data Center Cooling
Taiwan Data Center Cooling Market
Data Center Cooling
Austria Data Center Cooling Market