
 Hong Kong Data Center Cooling Market | 2026-2036
Hong Kong Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Hong Kong Data Center Cooling Market Insights
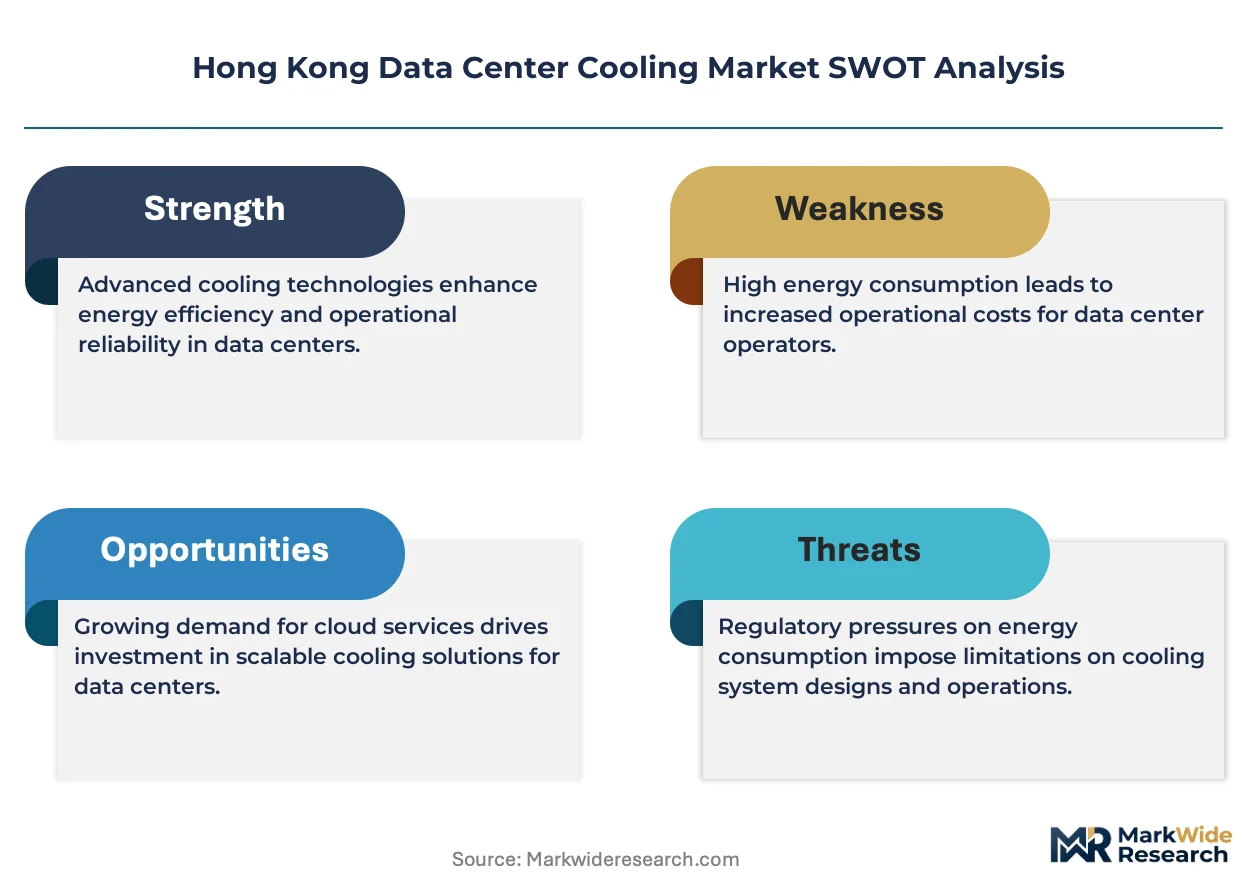
Project finance tied to green bond issuance is rewriting competitive access in Hong Kong's data center cooling sector. Schneider Electric SE leverages its integrated power and cooling portfolio to anchor large-scale deployments across the territory. Vertiv Holdings Co sustains its position through specialized thermal management systems designed for tropical humidity conditions. Huawei Technologies Co Ltd competes by offering end-to-end infrastructure stacks that bundle cooling with server and storage layers.
Hong Kong data center cooling encompasses engineered thermal management systems that maintain IT equipment within operational temperature bands, typically 18°C to 27°C, using chilled water loops, refrigerant-based direct expansion, or dielectric liquid immersion to reject heat generated by high-density server racks. The primary purpose is ensuring compute reliability while minimizing energy consumption in a subtropical climate where ambient temperatures exceed 30°C for extended periods. Chilled water systems dominate existing installed base due to compatibility with Hong Kong's district cooling infrastructure, while liquid cooling represents the fastest-expanding segment as GPU-intensive AI workloads push rack densities beyond 30 kW. Among end users, hyperscale providers command the largest capital allocation for cooling upgrades, though colocation providers concentrate margin pools through multi-tenant service bundling.
Hong Kong's Electrical and Mechanical Services Department enforces the Building Energy Code, which mandates efficiency benchmarks that directly influence cooling system selection and retrofit timelines. The territory also aligns with ISO 50001 energy management standards and references ASHRAE thermal guidelines for equipment certification. These frameworks compel operators to prioritize low-power cooling technologies and document carbon intensity metrics. Stakeholders must monitor how impending revisions to the Buildings Ordinance could mandate liquid cooling readiness in new data center constructions.
Market Dynamics
AI workload densification above 30 kW per rack is forcing Hong Kong operators to abandon conventional chilled water architectures faster than infrastructure depreciation cycles allow.
Growth Catalysts
- Building Energy Code enforcement:The Electrical and Mechanical Services Department mandates efficiency benchmarks that accelerate retrofit timelines for existing facilities.
- Financial services expansion:Banks and asset managers are scaling colocation footprints, creating concentrated demand for precision thermal management.
- Tseung Kwan O clustering:Hyperscale campus development in this industrial estate generates economies of scale for shared cooling infrastructure.
Market Restraints
- Limited land availability:Scarce industrial zoned plots in Hong Kong constrain greenfield construction and expansion options.
- District cooling dependency:Legacy chilled water systems lock operators into centralized utility configurations with limited flexibility.
- Refrigerant phase-down schedules:The F-Gas Regulation alignment pressures operators to accelerate capital-intensive system replacements.
Strategic Opportunities
- Green bond financing:Project finance tied to sustainability certification opens preferential capital access for efficient cooling deployments.
- Edge computing nodes:Distributed micro-data centers across Kowloon and New Territories create demand for modular thermal units.
- Liquid cooling readiness mandates:Impending Buildings Ordinance revisions may require new constructions to accommodate direct-to-chip architectures.
Industry Challenges
- Specialized technician scarcity:Dielectric fluid handling and high-voltage thermal interface expertise remains concentrated among a limited contractor base.
- Legacy system integration:Retrofitting liquid cooling into facilities engineered for air-cooled densities requires structural reinforcement and piping reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hong Kong Data Center Cooling Market |
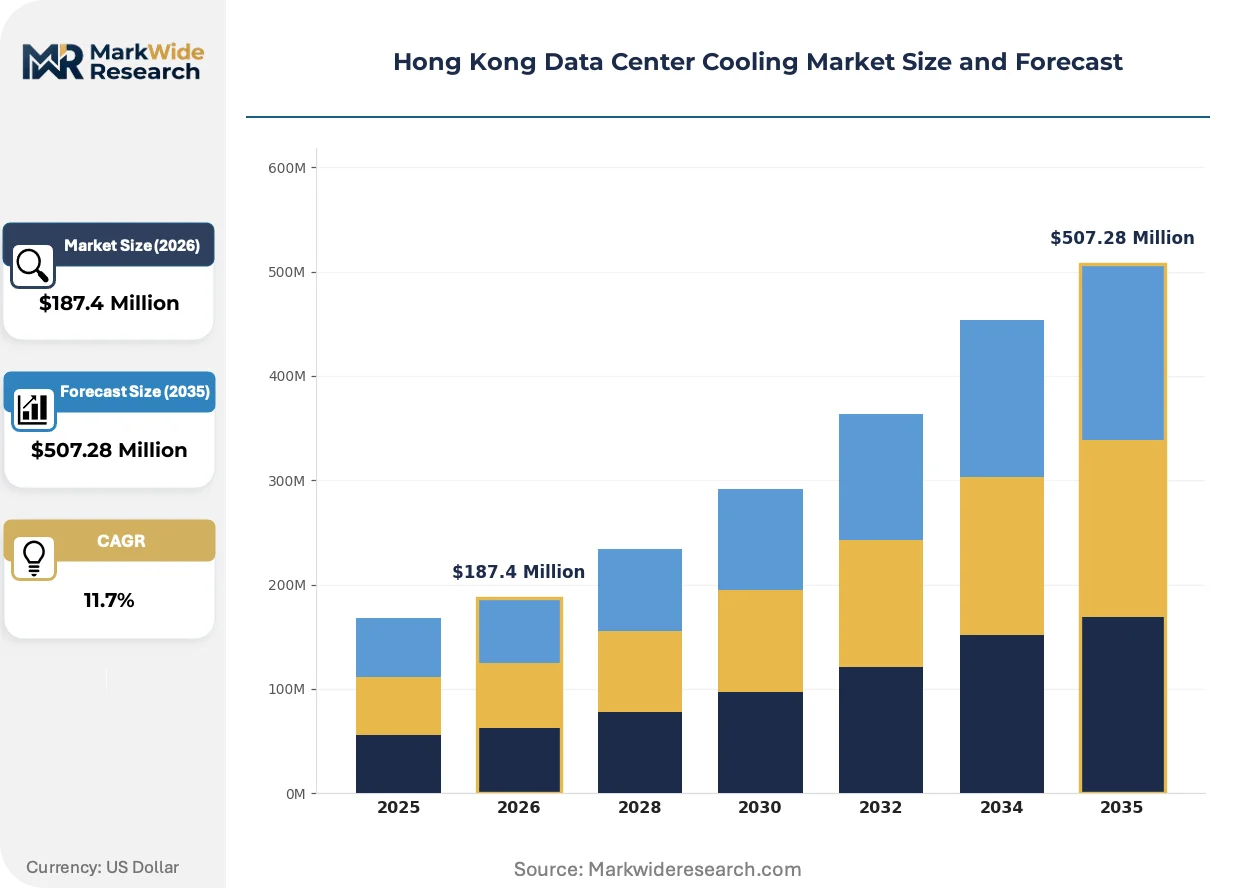
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Type: Chilled Water, Direct Expansion, Evaporative, Liquid Cooling End User: Colocation Providers, Enterprises, Hyperscale Providers, Managed Service Providers Product Type: CRAC Units, In-Row Cooling, Rack-Mounted Units, Immersion Cooling Service Type: Design Services, Installation, Maintenance, Consulting |
| Companies Covered | Johnson Controls International PLC, Stulz GmbH, Schneider Electric SE, Munters Group AB, OneAsia Network Limited, Vertiv Holdings Co, Huawei Technologies Co Ltd, Airedale International Air Conditioning Ltd, LiquidStack Holding BV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hong Kong Data Center Cooling Market Trends and Innovations
Cooling architecture decisions in Hong Kong are decoupling from traditional HVAC engineering disciplines as thermal design merges with semiconductor packaging roadmaps.
Direct-to-chip liquid cooling is migrating from experimental GPU clusters to standard deployment in AI training facilities. Hyperscale operators in Tseung Kwan O are specifying cold plate manifolds as baseline infrastructure rather than upgrade options. This migration from air-dominated to liquid-dominated thermal rejection is compressing equipment refresh cycles and invalidating prior depreciation assumptions.
The Electrical and Mechanical Services Department is tightening Building Energy Code enforcement through mandatory energy audits for facilities above specified consumption thresholds. Operators must now document power usage effectiveness ratios and thermal management efficiency metrics in licensing submissions. Colocation providers face the steepest compliance burden as multi-tenant configurations complicate attribution of cooling loads.
Power purchase agreements bundled with cooling-as-a-service contracts are displacing traditional equipment ownership models. Financial institutions with sustainability mandates prefer operational expenditure structures that transfer efficiency risk to infrastructure vendors. This preference concentrates among hedge funds and private equity firms establishing regional trading infrastructure in Central and Quarry Bay.
Hong Kong Data Center Cooling Market Segmentation
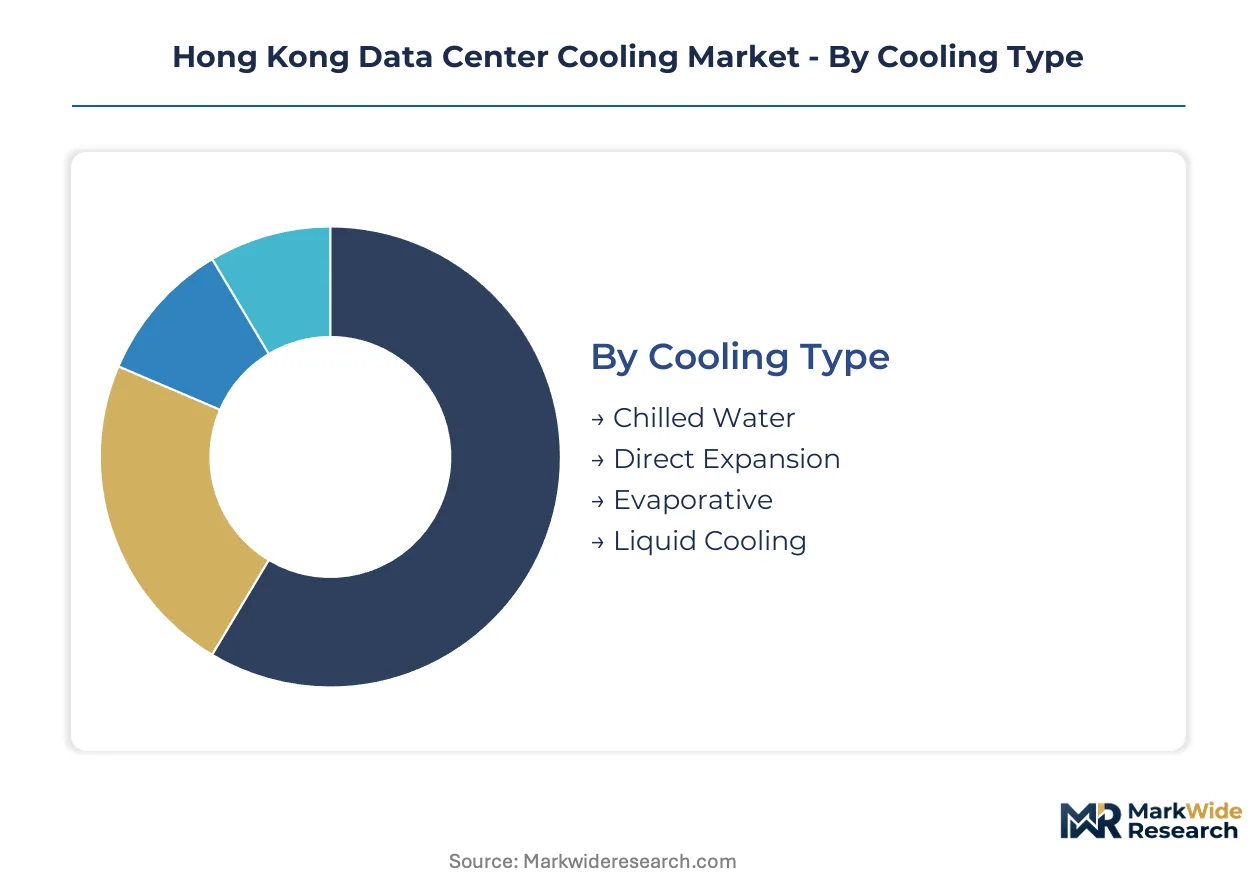
Cooling system selection in Hong Kong hinges on rack density trajectories and regulatory compliance timelines. Segmentation reveals where capital cycles accelerate and which architectures face premature obsolescence.
Cooling Type:
Chilled water systems turn over slowest due to district cooling integration, while liquid cooling refreshes fastest as AI densities outpace depreciation schedules.
- Chilled Water:Centralized chilled water loops distribute cooling through pipe networks connected to district cooling plants. Colocation facilities in Tseung Kwan O Industrial Estate anchor demand here, constrained by Building Energy Code efficiency audits that mandate documented power usage effectiveness ratios.
- Liquid Cooling:Direct-to-chip and immersion architectures reject heat through dielectric fluids or water-glycol mixtures. Hyperscale AI training clusters drive the steepest expansion trajectory, forced by GPU rack densities exceeding 30 kW that overwhelm air-cooled thermal envelopes.
- Direct Expansion:Refrigerant-based split systems provide localized cooling without water infrastructure. Enterprise edge nodes in Kowloon and New Territories deploy these where district cooling connections prove uneconomical.
- Evaporative:Adiabatic cooling towers leverage water evaporation for heat rejection. High ambient humidity in Hong Kong's subtropical climate limits deployment to supplementary roles in hybrid architectures.
Chilled water dominates installed base. Liquid cooling is where expansion concentrates.
End User:
Capital allocation intensity varies sharply across customer types, with procurement patterns reflecting balance sheet capacity and sustainability disclosure obligations.
- Hyperscale Providers:Self-operated campus developments in Tseung Kwan O specify baseline liquid cooling readiness. These operators command the largest absolute capital deployment for thermal infrastructure.
- Colocation Providers:Multi-tenant facilities bundle cooling as a metered service, concentrating margin pools through operational expenditure structures. Financial services firms expanding regional trading infrastructure drive premium-tier demand.
- Enterprises:Corporate captive data centers in Central and Quarry Bay prioritize retrofit compatibility over leading-edge density. Building Energy Code compliance timelines accelerate their refresh decisions.
- Managed Service Providers:Outsourced IT operators serving mid-market clients favor standardized modular units. Cost predictability outweighs thermal performance optimization in procurement criteria.
Hyperscale providers anchor volume leadership. Colocation providers capture the widest margin differentiation.
Product Type:
Equipment form factors are decoupling from traditional HVAC classifications as thermal design merges with semiconductor packaging roadmaps.
- Immersion Cooling:Fully submerged server architectures using dielectric fluids eliminate air handling entirely. Experimental GPU clusters migrate to standard deployment as hyperscale operators specify tank infrastructure as baseline.
- In-Row Cooling:Proximate cooling units positioned between server racks deliver precision thermal management. High-density financial trading floors in Central demand these for latency-sensitive compute environments.
- CRAC Units:Computer room air conditioners remain prevalent in legacy facilities engineered for sub-10 kW densities. Depreciation cycles extend these installations beyond technical obsolescence.
- Rack-Mounted Units:Self-contained cooling integrated at the enclosure level supports distributed edge deployments. Micro-data centers across New Territories specify these for rapid commissioning.
CRAC units dominate installed base. Immersion cooling is where expansion concentrates.
Service Type:
Revenue models shift from equipment ownership toward performance-contracted outcomes, with risk transfer preferences varying by customer sophistication.
- Maintenance:Preventive and corrective service contracts ensure thermal system uptime. Colocation providers with multi-tenant complexity face the steepest compliance burden for documented efficiency metrics.
- Design Services:Engineering consultancies integrate cooling with power distribution and semiconductor roadmaps. Liquid cooling readiness mandates in impending Buildings Ordinance revisions accelerate demand.
- Installation:Mechanical and electrical contracting for new construction and retrofit projects. Specialized technician scarcity for dielectric fluid handling concentrates execution risk.
- Consulting:Advisory services for energy audit preparation and green bond certification documentation. Financial institutions with sustainability mandates drive preference for operational expenditure structures.
Maintenance commands recurring revenue share. Design services is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial institutions with regional trading mandates anchor cooling demand across Asia-Pacific data center clusters, concentrating procurement power in sovereign financial hubs where latency-sensitive infrastructure commands premium thermal specifications.
Singapore
Wealth management firms and commodity trading houses drive precision cooling deployments in Marina Bay and Changi Business Park. The Infocomm Media Development Authority enforces data center sustainability standards that mandate liquid cooling readiness for new approvals. Hyperscale campuses in Tuas anchor the city-state's digital infrastructure expansion.
Japan
Securities exchanges and algorithmic trading platforms in Tokyo's Otemachi district require sub-millisecond latency environments with specialized thermal management. METI's Green Transformation initiative accelerates adoption of energy-efficient cooling architectures through subsidy programs. Osaka's Nanko Waterfront hosts emerging cloud infrastructure clusters with advanced liquid cooling specifications.
South Korea
Memory semiconductor manufacturers and cryptocurrency exchanges generate concentrated demand for high-density thermal solutions in Seoul's Gangnam and Sangam districts. The Ministry of Trade, Industry and Energy enforces building energy codes that mandate documented power usage effectiveness ratios for facilities above consumption thresholds. Busan's expanding fintech corridor attracts modular cooling deployments.
Australia
Superannuation funds and mining sector commodity traders in Sydney's Barangaroo and Melbourne's Docklands specify enterprise-grade colocation with integrated thermal services. The National Australian Built Environment Rating System pressures operators toward low-carbon cooling technologies through certification requirements. Perth's emerging data center precincts leverage evaporative cooling hybrid architectures for arid climate adaptation.
Taiwan
Semiconductor foundries and electronics contract manufacturers drive captive data center cooling investments in Hsinchu Science Park and Taichung's Central Taiwan Science Park. The Bureau of Energy administers mandatory energy efficiency standards for designated consumers that accelerate chiller system retrofits. Taipei City's Neihu Technology Park concentrates financial services data infrastructure with district cooling integration.
Hong Kong Data Center Cooling Market Competitive Landscape
Channel-controlling players compete with product-specialist players for positioning across Hong Kong's data center cooling sector. The vendor base organizes around integrated infrastructure platforms, precision thermal engineering, and dielectric fluid system innovation. Three archetypes dominate: multinational conglomerates with power-cooling integration capabilities, dedicated climate control specialists with tropical humidity expertise, and emerging liquid cooling technology developers. Competitive moves concentrate on strategic partnerships for district cooling integration and technology licensing for direct-to-chip architectures.
Within the integrated infrastructure tier, Schneider Electric SE and Vertiv Holdings Co exemplify channel-controlling positions through bundled power and thermal management portfolios. Stulz GmbH occupies a specialist position representing precision air conditioning engineering for high-density financial trading environments. Huawei Technologies Co Ltd anchors the end-to-end stack archetype, bundling cooling layers with compute and storage infrastructure for hyperscale deployments.
| Leading Market Players |
|---|
| Johnson Controls International PLC |
| Stulz GmbH |
| Schneider Electric SE |
| Munters Group AB |
| OneAsia Network Limited |
| Vertiv Holdings Co |
| Huawei Technologies Co Ltd |
| Airedale International Air Conditioning Ltd |
| LiquidStack Holding BV |
| Others |
Pricing and Supply Chain Analysis
The Pearl River Delta freight corridor channels compressor units and heat exchangers from Guangdong manufacturing clusters into Hong Kong data center construction sites, with logistics costs feeding directly into tiered service pricing across Tseung Kwan O and Central districts. Supply concentration in southern China amplifies procurement leverage for hyperscale operators while compressing margins for modular equipment vendors serving distributed edge deployments.
Pricing Analysis
Cost-plus contracts with copper and aluminum indexation dominate equipment procurement, insulating vendors from commodity volatility while passing through efficiency premiums for low-power cooling architectures. Price differentiation separates liquid-cooling-ready infrastructure from legacy air-cooled systems, with certification tier under the Building Energy Code commanding additional premiums. Pricing pressure stems from hyperscale direct sourcing that bypasses distribution layers, compressing standard-equipment margins. Managed service providers exhibit highest price sensitivity due to standardized procurement criteria, while financial institutions in Central tolerate premium tiering for latency-optimized thermal specifications.
Supply Chain Analysis
Contract manufacturing concentrates in Shenzhen and Dongguan, where specialized sheet-metal fabrication and precision piping assembly feed Hong Kong project timelines. Critical inputs draw from Japanese refrigerant suppliers, German pump manufacturers, and Taiwanese control-system vendors. Single-source vulnerability runs through dielectric fluid formulations held by limited chemical specialists. Distribution runs through electrical and mechanical contractors with Electrical and Mechanical Services Department licensing, concentrating execution risk in technician-scarce installation phases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity justified by maintenance and energy-audit consulting layers expanding faster than capital equipment sales. Recurring revenue from efficiency compliance documentation outpaces hardware depreciation cycles.
For Market Incumbents: Entrench district cooling integration capabilities through exclusive piping infrastructure partnerships with Tseung Kwan O utilities, while accelerating technician certification programs to capture scarce dielectric fluid handling expertise. Liquid cooling readiness mandates in impending Buildings Ordinance revisions threaten legacy air-cooled installed bases. Vertical integration into energy-audit consulting defends margin pools against pure-equipment competitors. For New Entrants and Emerging Players: Edge computing nodes in New Territories industrial zones represent the most penetrable entry point, where district cooling unavailability creates demand for self-contained modular thermal units. Mid-market colocation providers in Kowloon face compliance pressure without internal engineering capacity. A cooling-as-a-service go-to-market angle transfers efficiency risk while opening recurring revenue streams. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate climate-control divisions with tropical humidity expertise but limited AI-density positioning. Long-term viability centers on semiconductor packaging roadmap alignment as thermal design merges with chip-level integration. The signal to watch is hyperscale specification of liquid cooling as baseline rather than upgrade option.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Technology Licensing | Direct-to-chip patent portfolios unlock hyperscale Tseung Kwan O deployments exceeding 30 kW densities. |
| District Cooling Infrastructure Partnership | Exclusive utility agreements in Tseung Kwan O Industrial Estate create captive demand channels. |
| Building Energy Code Compliance Certification | Documented power usage effectiveness ratios differentiate vendors in Electrical and Mechanical Services Department submissions. |
| Technician Training Program Expansion | Dielectric fluid handling expertise scarcity concentrates execution risk with licensed contractor networks. |
| Green Bond Financing Structuring | Sustainability-linked project finance opens preferential capital access for efficiency retrofits. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with data center operators, mechanical contractors, and Electrical and Mechanical Services Department officials, combined with secondary validation against district cooling utility disclosures, Building Energy Code audit filings, and hyperscale capital expenditure reports. Data center engineering directors, facilities procurement managers, and thermal system integration specialists contributed operational perspective. Bottom-up equipment shipment tracking and top-down infrastructure investment flows were triangulated against regulatory compliance timelines.
Forecast inputs incorporated cooling type segmentation by density trajectory, end-user capital allocation patterns across hyperscale and colocation archetypes, and product type evolution from air-cooled to liquid-dominated architectures. CAGRs were derived from installed base turnover rates and regulatory-driven retrofit acceleration. AI workload densification curves and district cooling capacity expansion schedules anchored the projection framework across the analysis window.
Practitioners should monitor Buildings Ordinance revision drafts and hyperscale liquid cooling specification shifts for early signals of architectural inflection. Forecasts reflect assumptions about regulatory enforcement intensity and semiconductor power trajectory continuity. Quarterly review of Electrical and Mechanical Services Department audit disclosure patterns and Tseung Kwan O utility interconnection queues is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Switzerland Data Center Cooling Market
Data Center Cooling
Germany Data Center Cooling Market
Data Center Cooling
Denmark Data Center Cooling Market
Data Center Cooling
New Zealand Data Center Cooling Market
Data Center Cooling
Brazil Data Center Cooling Market
Data Center Cooling
United Arab Emirates Data Center Cooling Market
Data Center Cooling
Middle East and Africa Data Center Cooling Market
Data Center Cooling
United States Data Center Cooling Market
Data Center Cooling
Indonesia Data Center Cooling Market
Data Center Cooling
Thailand Data Center Cooling Market
Data Center Cooling
China Data Center Cooling Market
Data Center Cooling
Netherlands Data Center Cooling Market
Data Center Cooling
Chile Data Center Cooling Market
Data Center Cooling
Middle East District Cooling Market
Data Center Cooling
Data Center Cooling Market
Data Center Cooling
France Data Center Cooling Market