
 High-purity Data Center Thermal Management Fluids Market | 2026-2036
High-purity Data Center Thermal Management Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
High-purity Data Center Thermal Management Fluids Market Insights
Modular fluid-delivery architectures is restructuring procurement patterns across hyperscale campuses. Dow leverages captive silicone supply chains to anchor pricing stability for direct chip cooling contracts. Shell plc competes through synthetic ester portfolios tailored to immersion cooling retrofits. FUCHS specializes in perfluoropolyether formulations that sustain dielectric performance at sub-ambient temperatures.
High-purity data center thermal management fluids are engineered dielectric liquids with moisture content below 10 ppm and particulate contamination controlled to ISO 14644-1 Class 1-equivalent cleanliness, manufactured through multi-stage distillation and molecular filtration to transfer heat from densely packed semiconductor arrays without electrical conductivity. Fluorinated fluids dominate current revenue pools given their unmatched dielectric strength and chemical inertness, while hydrocarbon fluids represent the fastest-expanding category as operators seek lower-global-warming-potential alternatives for non-immersion applications. Synthetic esters concentrate margin capture among boutique compounders serving edge computing facilities with customized thermal profiles.
The EPA's AIM Act phasedown mandates constrain hydrofluorocarbon-based formulations in the United States, while REACH restrictions in Europe limit perfluorinated substance deployment, collectively forcing reformulation investments across the supplier base. ISO 14001 environmental management certification and ASHRAE thermal guidelines increasingly gate market access for fluid vendors serving tier-one colocation operators. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory positions as purity standards tighten and carbon border adjustments reshape competitive cost structures.
Market Dynamics
Liquid cooling infrastructure for AI training clusters is restructuring fluid procurement across hyperscale campuses, compressing qualification timelines from 18 months to under 6 months as thermal densities exceed 100 kW per rack.
Growth Catalysts
- EPA AIM Act phasedown:Hydrofluorocarbon restrictions under the AIM Act force data center operators toward next-generation fluorinated formulations with lower global warming potential, expanding addressable market for reformulated dielectric fluids.
- Hyperscale AI deployment:Training clusters exceeding 50,000 GPUs per facility require direct-to-chip cooling architectures that bypass traditional air-handling constraints, creating dedicated fluid consumption baselines measured in hundreds of thousands of liters per site.
- Synthetic ester chemistry:Biodegradable base stocks derived from vegetable oil feedstocks satisfy corporate sustainability procurement mandates while maintaining dielectric performance for single-phase immersion retrofits.
Market Restraints
- Perfluoropolyether supply concentration:Three Japanese chemical conglomerates control over 80% of virgin PFPE monomer supply, exposing buyers to allocation risk during semiconductor fabrication demand surges.
- Moisture specification tightening:Sub-5 ppm water content requirements demand nitrogen-blanketed logistics chains that add 15-20% to delivered fluid costs versus standard industrial chemical handling.
- Hydrocarbon flash point limitations:Mineral oil and polyalphaolefin formulations face fire code restrictions in jurisdictions adopting NFPA 75 standards for data center protection, constraining deployment in multi-tenant facilities.
Strategic Opportunities
- Edge computing micro-facilities:Distributed AI inference nodes in secondary metros lack on-site fluid engineering expertise, creating demand for pre-mixed, pre-certified thermal management kits with integrated monitoring.
- Two-phase immersion revival:Novec replacement fluids from fluorochemical specialists re-enable vapor chamber cooling for cryptocurrency mining and high-frequency trading co-location sites previously stranded by 3M product discontinuation.
- EU F-Gas Regulation revision:Pending restrictions on perfluorinated substances with global warming potential above 1500 create first-mover advantage for suppliers with hydrofluoroether portfolios already certified to PFOA-free standards.
Industry Challenges
- Thermal-fluid compatibility testing:Server OEMs require 10,000-hour material compatibility studies for each new fluid-server combination, extending sales cycles and straining application engineering teams at mid-size compounders.
- Cross-contamination during retrofits:Facilities transitioning from air cooling to immersion must achieve ISO 14644-1 Class 8 cleanliness in white space environments historically designed to Class 9 specifications, demanding temporary containment infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-purity Data Center Thermal Management Fluids Market |
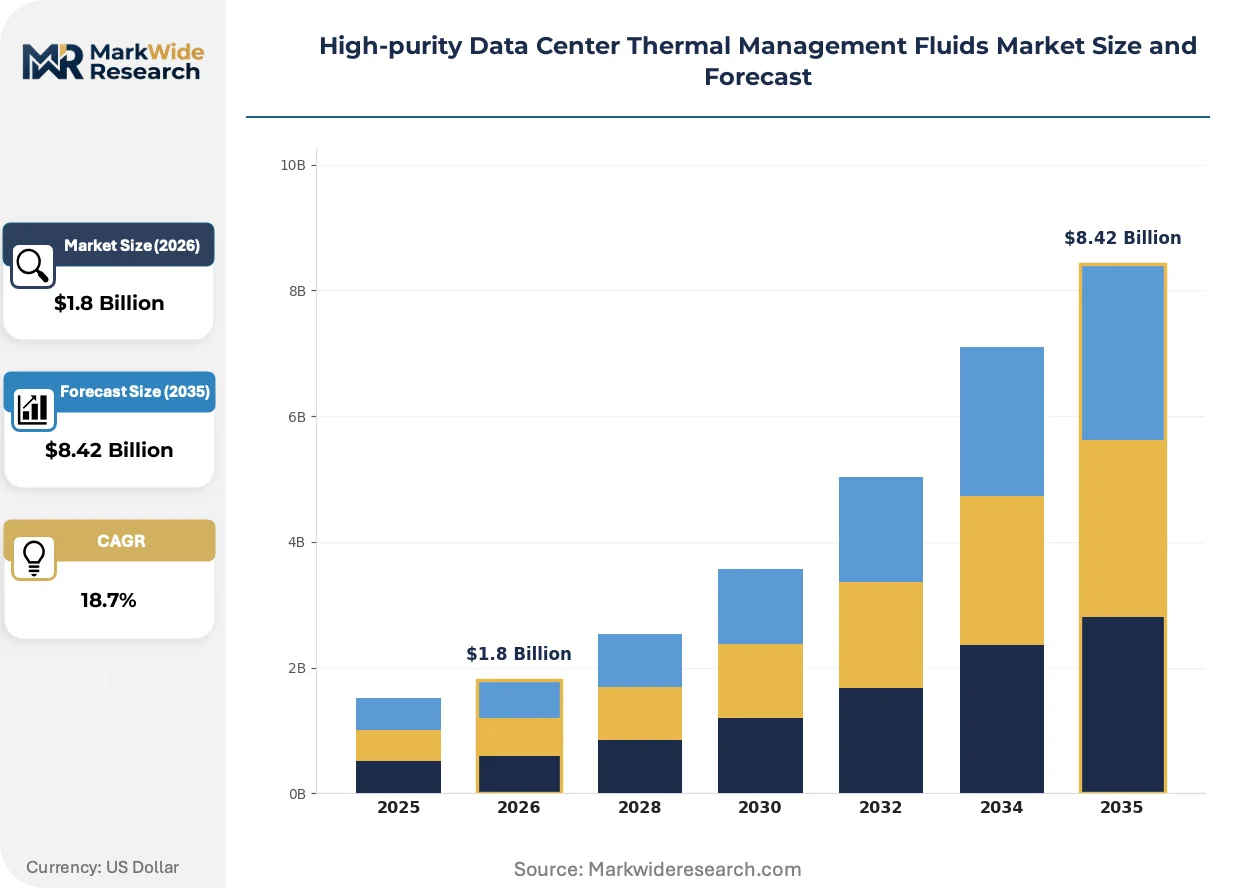
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorinated Fluids, Hydrocarbon Fluids, Silicone Fluids, Synthetic Esters, Perfluoropolyethers Application: Liquid Cooling, Direct Chip Cooling, Immersion Cooling, Heat Exchangers, Rack Cooling Purity Grade: Electronic Grade, Ultra High Purity, Semiconductor Grade, Medical Grade, Research Grade End User: Cloud Service Providers, Colocation Data Centers, Edge Computing Facilities, Hyperscale Operators, Research Institutes |
| Companies Covered | Dow, Shell plc, Exxon Mobil Corporation, The Chemours Company, Valvoline Global Operations, Honeywell International, FUCHS, Castrol, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-purity Data Center Thermal Management Fluids Market Trends and Innovations
Refrigerant chemistry innovation is fragmenting as regional regulatory divergence accelerates formulation specialization, while fluid delivery architectures evolve from centralized bulk storage toward rack-level precision dosing systems.
Single-phase synthetic hydrocarbon blends are decentralizing thermal management infrastructure by enabling air-cooled facility retrofits without vapor compression equipment. Colocation operators in secondary markets adopt these fluids to compete with hyperscale-built campuses on power usage effectiveness metrics. The technology is decentralizing capital deployment patterns, allowing 5-10 MW edge facilities to achieve liquid-cooled power densities without chiller plant investments.
REACH restrictions on perfluorinated substances in Europe are bifurcating product portfolios between continental and Anglo-American markets. Compounders must maintain parallel inventory positions for PFPE-based formulations banned under SVHC candidate listing versus fluorinated fluids permitted under UK REACH continuity. Data center operators in Frankfurt and Amsterdam face 12-18 month fluid qualification delays as they validate hydrofluoroether alternatives to legacy perfluorocarbon coolants.
Direct chip cooling contracts are consolidating procurement authority at the hyperscale engineering level, bypassing traditional distributor channels. Fluid vendors now negotiate multi-year supply agreements with Microsoft, Google, and Amazon Web Services that specify purity certification at the molecular manufacturing stage rather than at point of delivery. This concentration is most visible in Northern Virginia, where fluid suppliers maintain dedicated analytical laboratories within 50 miles of Ashburn-Dulles corridor facilities to support just-in-time drum replacement programs.
High-purity Data Center Thermal Management Fluids Market Segmentation
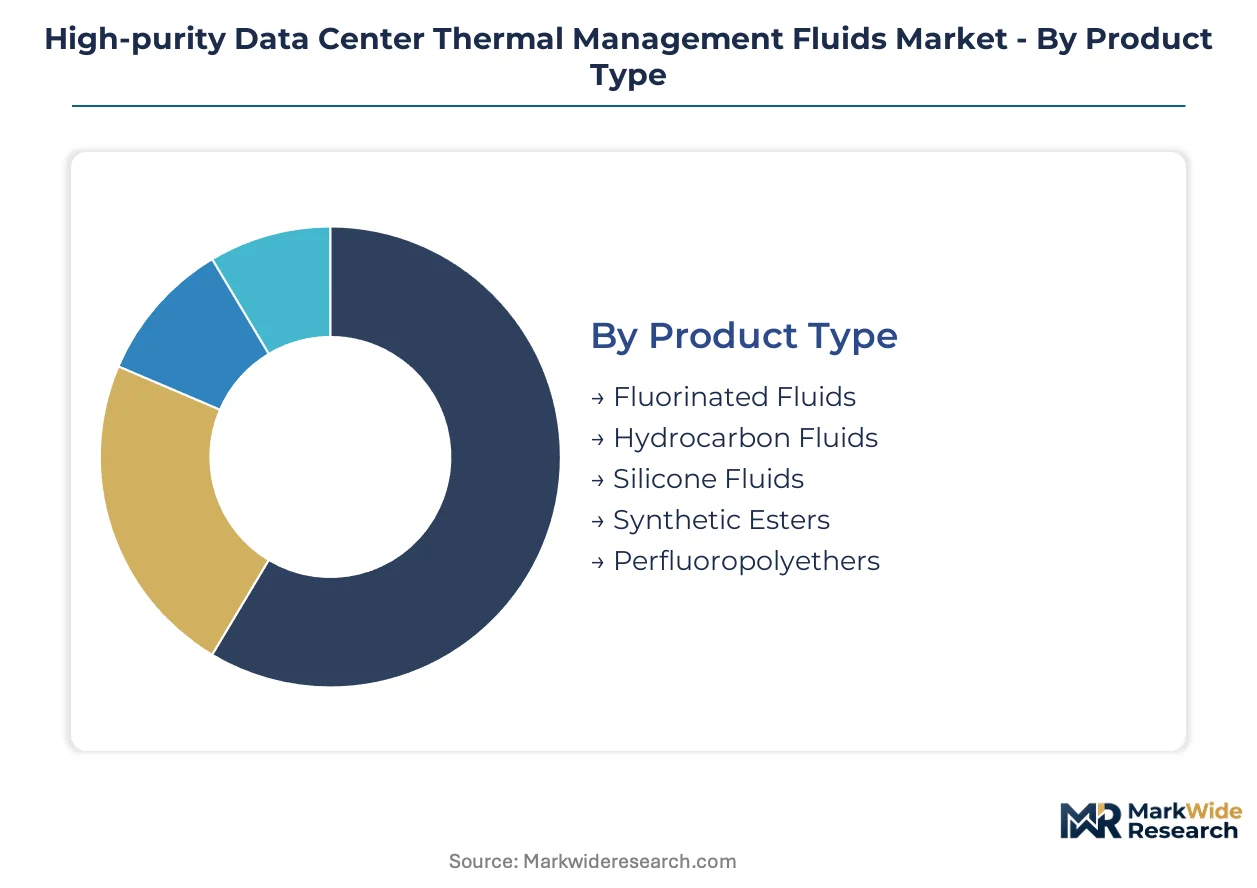
Segmentation in thermal management fluids reveals divergent procurement patterns across cooling architectures and purity specifications. Each dimension exposes distinct technical requirements, regulatory constraints, and margin structures that reshape supplier positioning.
Product Type:
Buyers differentiate primarily by dielectric strength requirements and global warming potential constraints imposed by facility sustainability mandates.
- Fluorinated Fluids:Formulated hydrofluorocarbon and hydrofluoroether chemistries deliver unmatched dielectric strength above 40 kV and chemical inertness for direct chip cooling. Demand concentrates in Northern Virginia's hyperscale corridor where operators face EPA AIM Act compliance deadlines for legacy HFC replacement.
- Hydrocarbon Fluids:Polyalphaolefin and mineral oil base stocks offer lower cost per liter and simplified waste handling, though NFPA 75 fire code restrictions limit multi-tenant deployment. Edge computing retrofits in secondary metros drive fastest uptake as operators bypass vapor compression infrastructure.
- Silicone Fluids:Polydimethylsiloxane formulations maintain thermal stability across -40°C to 200°C operating ranges for heat exchanger applications.
- Synthetic Esters:Vegetable-derived base stocks satisfy corporate renewable procurement mandates with biodegradable end-of-life pathways.
- Perfluoropolyethers:Virgin PFPE monomers from Japanese chemical conglomerates sustain sub-ambient dielectric performance for semiconductor fabrication-adjacent cooling.
Fluorinated fluids lead volumes today; hydrocarbon fluids are gaining share fastest.
Application:
Cooling architecture selection determines fluid consumption intensity, with rack-density thresholds dictating whether air-handling retrofits or liquid-native designs prevail.
- Liquid Cooling:Cold plate and rear-door heat exchanger configurations consume dielectric fluids in closed-loop circulation systems serving 30-80 kW racks. Hyperscale training clusters exceeding 50,000 GPUs per facility anchor demand in the Ashburn-Dulles corridor.
- Direct Chip Cooling:Microchannel cold plates bonded to processor packages enable thermal densities above 100 kW per rack. Microsoft, Google, and Amazon Web Services negotiate multi-year supply agreements specifying purity certification at molecular manufacturing stages.
- Immersion Cooling:Single-phase and two-phase tank architectures submerge entire server assemblies, requiring 10-100x fluid volume per kW versus cold plate designs.
- Heat Exchangers:Secondary loop fluids transfer heat from IT equipment to facility water systems in hybrid cooling configurations.
- Rack Cooling:In-row and overhead cooling distribution units integrate fluid-handling components at the aisle level for incremental density upgrades.
Direct chip cooling commands premium pricing tiers; immersion cooling is climbing the fastest.
Purity Grade:
Specification tightening correlates with semiconductor fabrication proximity and warranty liability exposure from fluid-induced hardware failure.
- Electronic Grade:Moisture content below 10 ppm and particulate filtration to ISO 14644-1 Class 1-equivalent standards serve general IT equipment cooling. Colocation operators in multi-tenant facilities standardize on this tier to balance performance against cross-contamination risk.
- Ultra High Purity:Sub-5 ppm water content and nitrogen-blanketed logistics chains add 15-20% to delivered costs. Hyperscale operators in Northern Virginia require this grade for GPU training clusters where thermal cycling accelerates moisture-induced corrosion.
- Semiconductor Grade:Molecular contamination controls matching wafer fabrication cleanroom standards for advanced packaging facilities.
- Medical Grade:Biocompatibility and sterilization validation for healthcare data infrastructure with patient data processing requirements.
- Research Grade:Batch-certified fluids for experimental cooling architectures in national laboratory and university settings.
Electronic grade dominates procurement volumes; ultra high purity is expanding most quickly.
End User:
Scale and technical capability determine whether buyers self-manage fluid engineering or outsource to integrated service contracts.
- Cloud Service Providers:Microsoft Azure, Google Cloud Platform, and Amazon Web Services operate dedicated fluid engineering teams that negotiate direct supply agreements bypassing distributor channels. These buyers specify purity certification at manufacturing stage rather than point of delivery.
- Hyperscale Operators:Meta, Apple, and Oracle maintain captive data center portfolios with standardized fluid specifications across global facility footprints. Procurement authority concentrates at corporate engineering level with 10,000-hour material compatibility requirements for each server-fluid combination.
- Colocation Data Centers:Equinix, Digital Realty, and CyrusOne serve multi-tenant workloads with conservative fluid selections constrained by NFPA 75 fire codes and cross-liability exposure.
- Edge Computing Facilities:Distributed inference nodes in secondary metros lack on-site fluid expertise, creating demand for pre-mixed thermal management kits.
- Research Institutes:National laboratories and university computing centers validate experimental cooling architectures with small-batch, high-specification procurement.
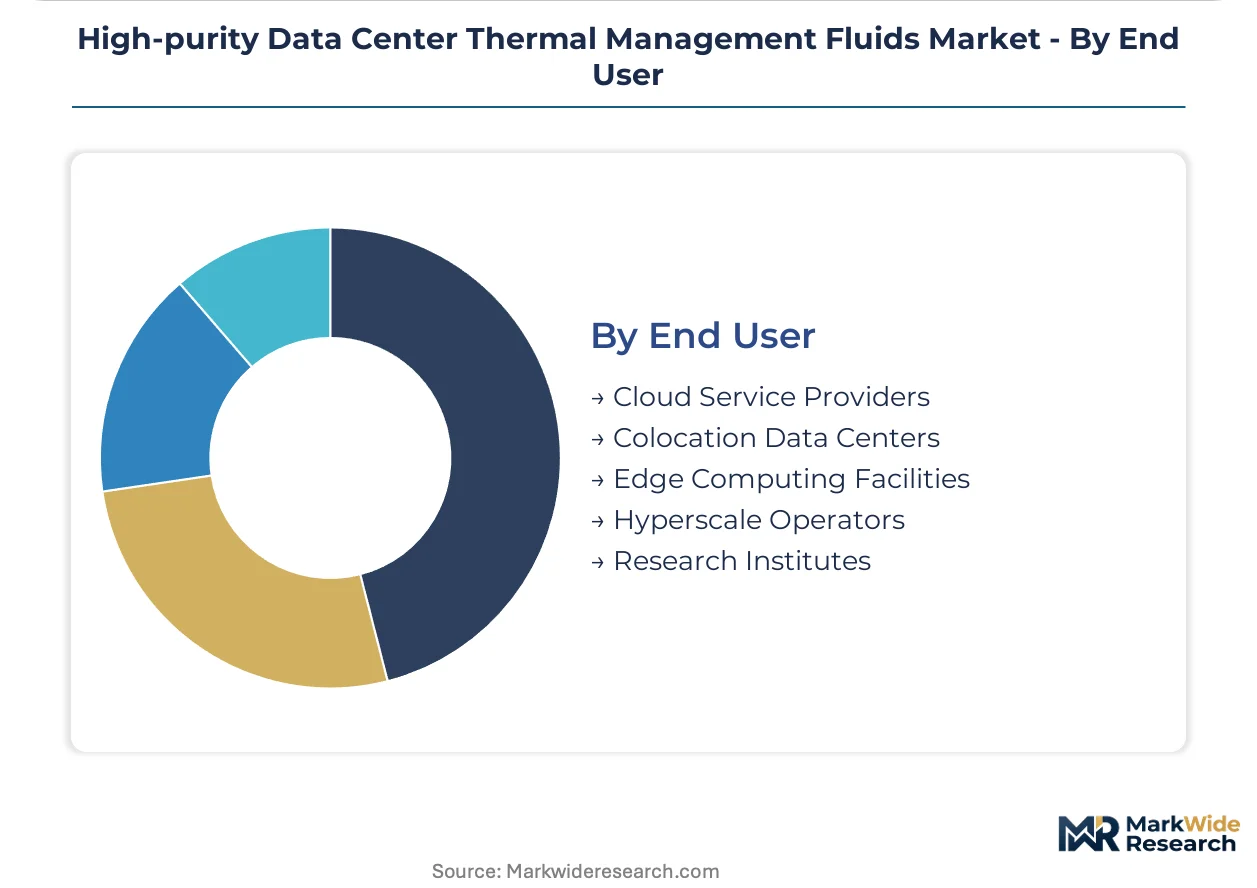
Cloud service providers anchor current demand; edge computing facilities represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The data center thermal management fluids industry traces its commercial origins to the semiconductor fabrication corridors of Japan and the United States, where dielectric coolant chemistry first achieved the purity thresholds required for electronics manufacturing. Demand geography now follows hyperscale facility buildouts rather than feedstock proximity.
United States
EPA AIM Act phasedown mandates are accelerating hydrofluorocarbon reformulation across domestic supply chains. The Northern Virginia data center corridor from Ashburn to Dulles anchors the highest fluid consumption intensity globally, with Microsoft, Google, and Amazon Web Services operating dedicated fluid engineering teams. Virginia's Loudoun County processes more internet traffic than any comparable jurisdiction worldwide.
Japan
Three chemical conglomerates control over 80% of virgin perfluoropolyether monomer supply, exposing global buyers to allocation risk during semiconductor fabrication demand surges. METI industrial policy prioritizes advanced packaging infrastructure, sustaining demand for sub-ambient dielectric fluids. The Osaka-Kobe chemical manufacturing belt concentrates PFPE production capacity.
Germany
REACH restrictions on perfluorinated substances force compounders to maintain parallel inventory positions for formulations banned under SVHC candidate listing versus fluids permitted under continuity arrangements. Frankfurt and Amsterdam data center operators face 12-18 month qualification delays validating hydrofluoroether alternatives. The Rhine-Ruhr industrial region houses Europe's largest synthetic ester compounding capacity.
China
MIIT dual carbon goals and GB standards for data center power usage effectiveness are driving liquid cooling adoption in cloud computing facilities. Domestic hyperscale operators including Alibaba Cloud and Tencent Cloud are qualifying local fluid suppliers for direct chip cooling contracts. The Yangtze River Delta from Shanghai to Hangzhou concentrates the nation's data center construction activity.
Singapore
Tropical ambient temperatures and limited land availability make liquid cooling economically imperative rather than optional for facility expansion. The country's national water agency imposes strict effluent standards that favor closed-loop dielectric systems over water-based alternatives. The Tuas data center precinct represents the densest liquid-cooled facility cluster in Southeast Asia.
High-purity Data Center Thermal Management Fluids Market Competitive Landscape
Premium-margin players sit above commodity-margin players across purity certification tiers, with ultra high purity formulations commanding 15-20% delivered cost premiums over electronic grade equivalents. The supplier base fragments between integrated petrochemical majors, specialty fluorochemical houses, and boutique synthetic ester compounders. Three strategic archetypes dominate: captive silicone supply chain operators, synthetic ester sustainability specialists, and perfluoropolyether purity leaders. Competitive moves concentrate on backward integration into base stock manufacturing and multi-year direct supply agreements with hyperscale engineering teams.
Within the integrated petrochemical tier, Dow and Shell plc exemplify scale-driven positioning through captive raw material access and global distribution infrastructure. Among specialty fluorochemical operators, FUCHS occupies a position representing precision formulation expertise for sub-ambient dielectric applications. These three companies anchor the competitive structure, with each exemplifying distinct strategic archetypes: backward integration for supply security, synthetic portfolio breadth for retrofit flexibility, and molecular purity leadership for advanced cooling architectures.
| Leading Market Players |
|---|
| Dow |
| Shell plc |
| Exxon Mobil Corporation |
| The Chemours Company |
| Valvoline Global Operations |
| Honeywell International |
| FUCHS |
| Castrol |
| Solvay |
| Others |
Pricing and Supply Chain Analysis
Perfluoropolyether monomer spot indices from Japanese chemical conglomerates cascade through three distinct pricing tiers for data center thermal management fluids, with ultra high purity grades commanding 15-20% delivered cost premiums over electronic grade equivalents due to nitrogen-blanketed logistics chains and sub-5 ppm moisture specifications.
Pricing Analysis
Volume-scaled contract pricing with purity-grade differentiation dominates procurement between hyperscale operators and integrated petrochemical suppliers. Price differentiation separates ultra high purity formulations certified at molecular manufacturing stages from standard electronic grade fluids delivered through distributor channels. Cost compression in hydrocarbon fluid tiers is intensifying as synthetic ester compounders compete for edge computing retrofits with biodegradable base stocks. Cloud service providers demonstrate lowest price sensitivity given thermal density requirements, while colocation operators in multi-tenant facilities face NFPA 75 fire code constraints that limit low-cost hydrocarbon adoption.
Supply Chain Analysis
Perfluoropolyether monomer supply rests on three Japanese chemical conglomerates controlling over 80% of virgin PFPE production, exposing global buyers to allocation risk during semiconductor fabrication demand surges. Raw material dependencies center on fluorinated feedstocks from Osaka-Kobe chemical manufacturing belt, silicone precursors from Dow's captive supply chains, and vegetable oil base stocks for synthetic ester formulations. Single-source vulnerability concentrates in sub-ambient dielectric grades required for direct chip cooling architectures. Distribution runs through dedicated analytical laboratories maintained within 50 miles of Northern Virginia's Ashburn-Dulles corridor, bypassing traditional industrial chemical distributors for hyperscale direct supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through reformulation investments that capture EPA AIM Act compliance premiums while displacing legacy hydrofluorocarbon formulations with lower-global-warming-potential alternatives.
For Market Incumbents: Deepen backward integration into fluorinated feedstock manufacturing to secure allocation priority during semiconductor fabrication demand surges. Anchor pricing stability through captive silicone supply chains for direct chip cooling contracts while investing in hydrofluoroether certification ahead of EU F-Gas Regulation revisions. Defend against synthetic ester compounders by accelerating biodegradable formulation R&D for corporate sustainability procurement mandates.
For New Entrants and Emerging Players: Enter via edge computing micro-facilities in secondary metros lacking on-site fluid engineering expertise, offering pre-mixed thermal management kits with integrated monitoring. Target colocation operators constrained by NFPA 75 fire codes with synthetic hydrocarbon blends enabling air-cooled facility retrofits without vapor compression equipment. Pursue two-phase immersion cooling revival opportunities at cryptocurrency mining and high-frequency trading co-location sites previously stranded by 3M product discontinuation.
For Investors and Strategic Acquirers: Asymmetric upside sits with boutique synthetic ester compounders possessing hydrofluoroether portfolios already certified to PFOA-free standards ahead of pending EU restrictions. Long-term viability favors suppliers with demonstrated 10,000-hour material compatibility study completion for server OEM qualification programs. Monitor hyperscale direct supply agreement announcements as inflection indicators for procurement authority consolidation away from distributor channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorinated Feedstocks | Secures allocation priority from Japanese PFPE monomer suppliers during demand surges. |
| Hydrofluoroether Certification Investment | Captures first-mover advantage under pending EU F-Gas Regulation revisions. |
| Long-term Direct Supply Agreement | Bypasses distributor channels with Microsoft, Google, and Amazon Web Services engineering teams. |
| Edge Computing Pre-mixed Kit Launch | Addresses distributed AI inference nodes lacking on-site fluid engineering expertise. |
| Biodegradable Synthetic Ester Scale-Up | Satisfies corporate sustainability procurement mandates with vegetable-derived base stocks. |
Research Methodology
Multiple input streams — primary interviews with data center engineering directors, thermal management procurement leads, and fluid compounding technical directors, combined with secondary validation through EPA AIM Act regulatory filings, SEC 10-K disclosures from integrated petrochemical majors, and customs/trade data on fluorinated chemical imports — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across the projection horizon modeled segmentation dimensions including purity grade tier, cooling architecture application, end-user scale category, and regional regulatory cluster. CAGRs were derived from facility buildout trajectories in Northern Virginia's Ashburn-Dulles corridor, GPU training cluster deployment schedules, and reformulation investment cycles tied to EPA phasedown mandates. Forecast inputs incorporated hyperscale direct supply agreement announcements and ISO 14644-1 cleanliness specification tightening timelines.
Inputs from server OEM material compatibility study disclosures and fluid vendor qualification program updates were available through the study window; gaps in real-time perfluoropolyether monomer allocation data from Japanese chemical conglomerates introduce uncertainty bands around sub-ambient dielectric grade supply assumptions. A small set of named triggers — EU F-Gas Regulation revision finalization, EPA AIM Act phaseout acceleration, and 3M Novec replacement fluid commercialization — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
North America Data Center Cooling Market
Data Center Cooling
Global Laptop Cooling Pads Market
Data Center Cooling
Israel Data Center Cooling Market
Data Center Cooling
United Arab Emirates Data Center Cooling Market
Data Center Cooling
France Data Center Cooling Market
Data Center Cooling
Thailand Data Center Cooling Market
Data Center Cooling
Sweden Data Center Cooling Market
Data Center Cooling
Malaysia Data Center Cooling Market
Data Center Cooling
Middle East District Cooling Market
Data Center Cooling
South Africa Data Center Cooling Market
Data Center Cooling
Japan Data Center Cooling Market
Data Center Cooling
Nigeria Data Center Cooling Market
Data Center Cooling
Germany Data Center Cooling Market
Data Center Cooling
Ireland Data Center Cooling Market
Data Center Cooling
India Data Center Cooling Market
Data Center Cooling
Canada Data Center Cooling Market