
 Netherlands Data Center Cooling Market | 2026-2036
Netherlands Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Data Center Cooling Market Insights
Multi-source equipment procurement is recalibrating how Dutch facility operators balance thermal reliability against supply chain risk. Schneider Electric leverages its integrated power and cooling portfolio to anchor large-scale deployments in the Amsterdam metro area. Vertiv Group Corp competes through precision air conditioning systems designed for high-density server environments. STULZ specializes in customized climate solutions that extend its reach into enterprise colocation facilities.
Netherlands data center cooling encompasses engineered thermal management systems that maintain server inlet temperatures between 18°C and 27°C while dissipating heat loads exceeding 30 kW per rack. These systems employ chilled water loops, refrigerant-based direct expansion, or dielectric fluid immersion to prevent thermal throttling and hardware degradation across continuous operations. Liquid cooling solutions are capturing the fastest expansion trajectory as AI training clusters drive rack densities beyond air-cooling thresholds. Cloud Providers represent the dominant end-user segment, absorbing the majority of new capacity additions across Tier III and Tier IV facilities. Hybrid Systems are gaining share where operators phase liquid loops into legacy air-cooled footprints without full infrastructure replacement.
The Dutch Ministry of Economic Affairs and Climate Policy enforces energy performance standards that restrict power usage effectiveness ratios for new data center builds. BIS certification requirements for imported cooling equipment shape supplier qualification timelines and product adaptation cycles. The EU Green Deal's sectoral carbon budgets are forcing operators to document embodied emissions in cooling infrastructure procurement. Stakeholders must monitor how Amsterdam's moratorium on new data center construction redirects investment toward Rotterdam, Eindhoven, and Groningen satellite markets.
Market Dynamics
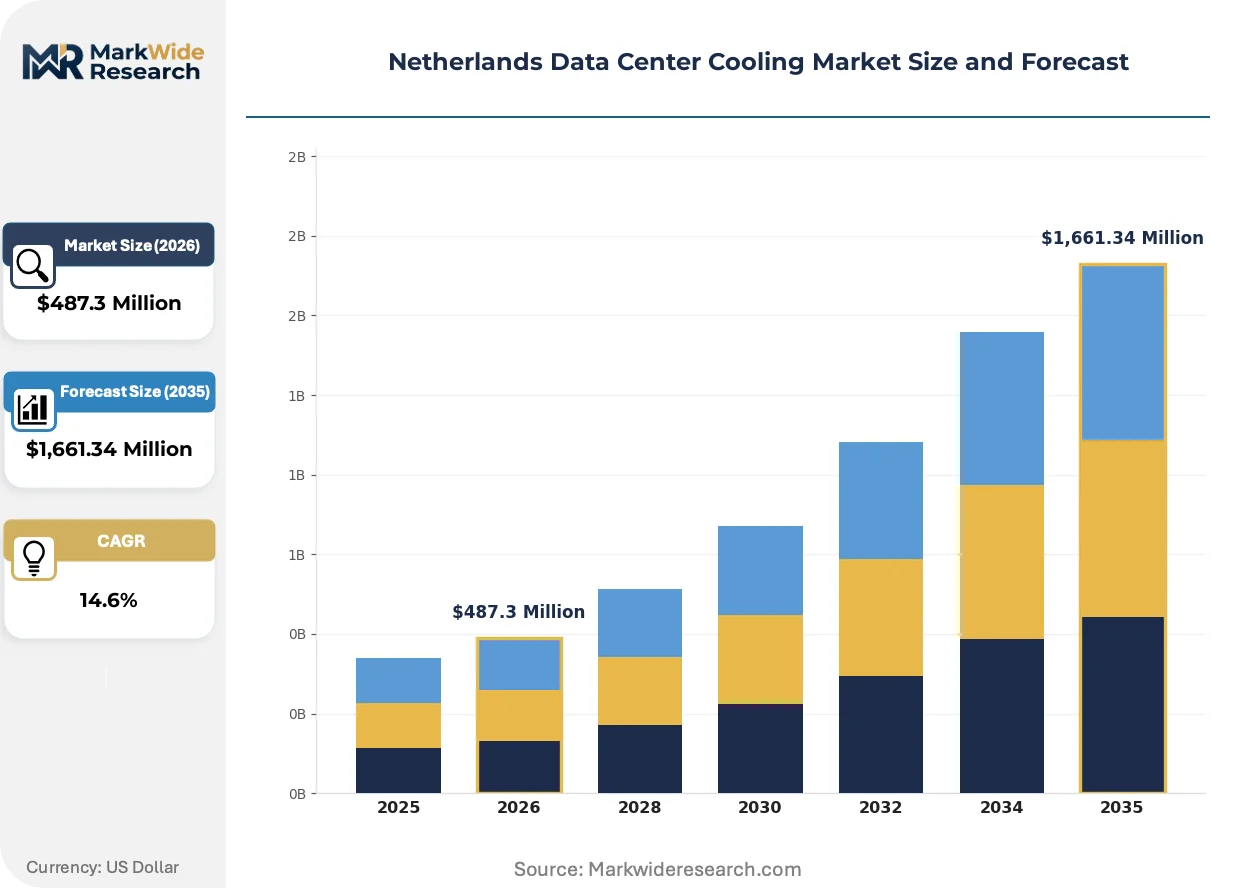
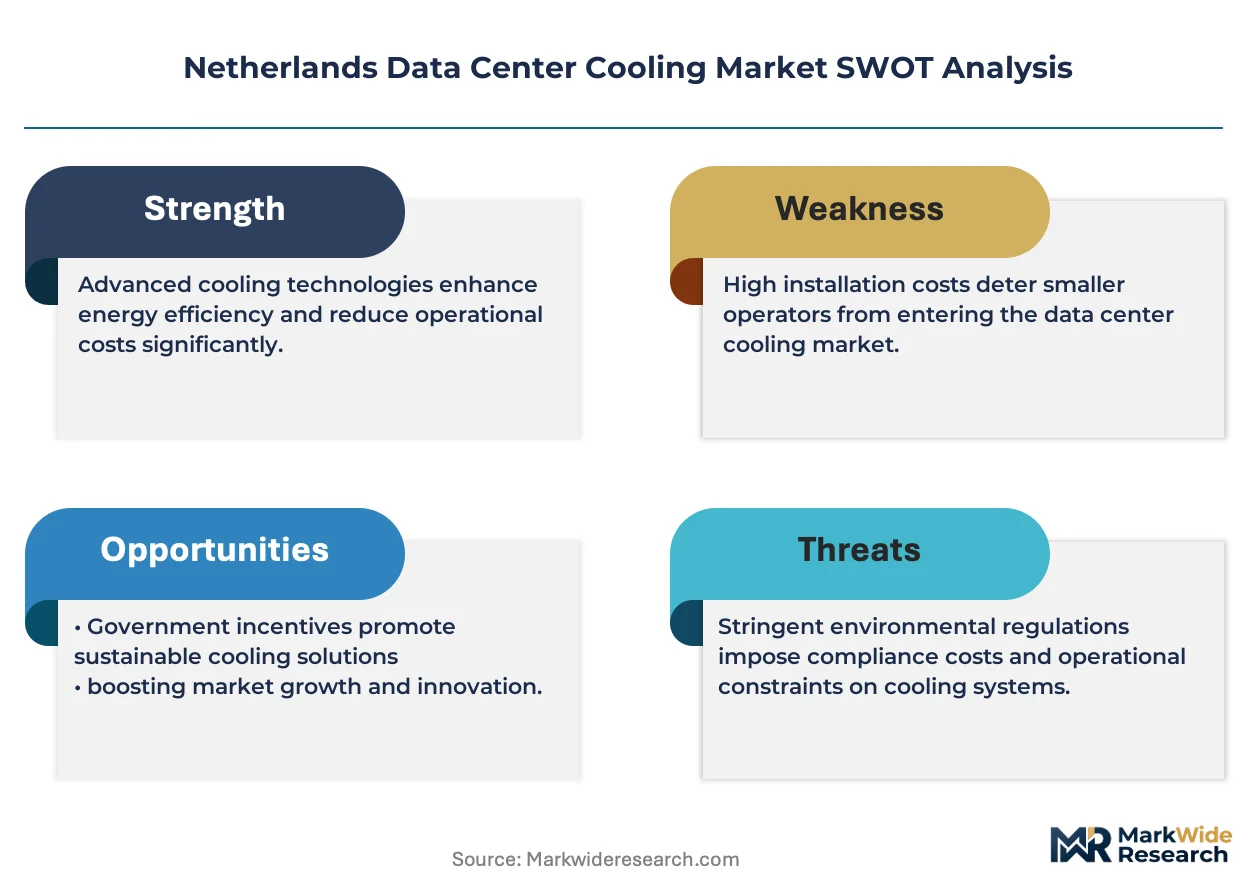
Liquid cooling infrastructure is reshaping capital allocation across Dutch data center portfolios as AI rack densities breach air-cooling thermal thresholds. Operators face simultaneous pressure from the Ministry of Economic Affairs and Climate Policy's energy performance mandates and hyperscale tenants' power density requirements.
Growth Catalysts
- EU Green Deal sectoral carbon budgets:These frameworks compel Dutch operators to document embodied emissions in cooling procurement, accelerating liquid cooling retrofits that reduce power usage effectiveness ratios below legacy air-cooled baselines.
- Hyperscale cloud expansion:Demand concentrates along the Randstad corridor where Tier III and Tier IV facilities absorb capacity additions, pulling precision thermal management systems into Amsterdam's metropolitan cluster and surrounding satellite markets.
- Dielectric fluid immersion:This technology enables direct-to-chip heat extraction for AI training clusters exceeding 30 kW per rack, opening deployment pathways previously blocked by air-cooling physics constraints.
Market Restraints
- Copper and aluminum input volatility:Chilled water loop construction depends on metal commodity markets where price swings compress equipment margins and extend project payback periods for facility operators.
- Amsterdam construction moratorium:This municipal policy redirects investment toward Rotterdam, Eindhoven, and Groningen, fragmenting demand concentration and diluting economies of scale for cooling system deployment.
- BIS certification timelines:Imported cooling equipment faces extended supplier qualification cycles and product adaptation requirements that delay market entry for non-EU manufacturers.
Strategic Opportunities
- Rotterdam-Eindhoven-Groningen satellite corridor:Amsterdam's redirection of data center investment creates greenfield deployment opportunities where liquid-native designs avoid legacy air-cooling retrofit costs entirely.
- Hybrid system architectures:Phased liquid loop integration into existing air-cooled footprints enables operators to defer full infrastructure replacement while capturing partial density gains from AI server deployments.
- CSRD-aligned sustainability reporting:The EU Corporate Sustainability Reporting Directive creates procurement preference for cooling vendors with documented lifecycle carbon inventories, favoring integrated power-and-cooling portfolios over point-product suppliers.
Industry Challenges
- Thermal-fluid engineering talent scarcity:Dielectric coolant chemistry and two-phase heat transfer expertise sits concentrated among semiconductor process engineers, creating recruitment friction for data center operators scaling liquid cooling teams.
- Legacy mechanical infrastructure integration:Retrofitting liquid cooling into facilities engineered for air-cooled loads requires structural reinforcement, plumbing reconfiguration, and containment redesign that extends deployment timelines and capital exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Data Center Cooling Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Type: Air Cooling, Liquid Cooling, Hybrid Systems, Evaporative Cooling End User: Cloud Providers, Telecom Operators, Enterprises, Government Institutions Technology: Indirect Expansion, Direct Expansion, Chilled Beams, Immersion Cooling Building Type: Tier I, Tier II, Tier III, Tier IV |
| Companies Covered | Schneider Electric, Vertiv Group Corp, STULZ, Rittal, Johnson Controls International, Mitsubishi Electric, Danfoss, Carrier Global Corporation, Asperitas, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Data Center Cooling Market Trends and Innovations
Direct liquid cooling architectures are compressing thermal design power ceilings while Dutch regulatory frameworks force operational transparency. Equipment vendors and facility operators must synchronize technology roadmaps with evolving compliance requirements.
Single-phase and two-phase direct liquid cooling systems circulate dielectric fluids through cold plates mounted directly to CPU and GPU packages. Hyperscale cloud providers in the Amsterdam metro area are deploying these systems at rack densities exceeding 50 kW. This technology is overtaking perimeter-based precision air conditioning as the default thermal strategy for AI training infrastructure.
The Dutch Ministry of Economic Affairs and Climate Policy enforces power usage effectiveness ratio ceilings for new data center builds that restrict legacy air-cooled designs. Operators must document energy performance guarantees prior to permitting approval. Cloud providers and enterprise colocation tenants face the steepest compliance burden, driving specification changes in procurement tenders issued across the Randstad corridor.
Facility operators are unbundling cooling infrastructure procurement from bundled mechanical-electrical contracts that dominated legacy construction. Tier III and Tier IV developers now issue separate RFPs for thermal management systems, enabling direct vendor relationships with liquid cooling specialists. This pattern concentrates most visibly in Rotterdam and Eindhoven satellite markets where greenfield designs lack incumbent mechanical contractor relationships.
Netherlands Data Center Cooling Market Segmentation
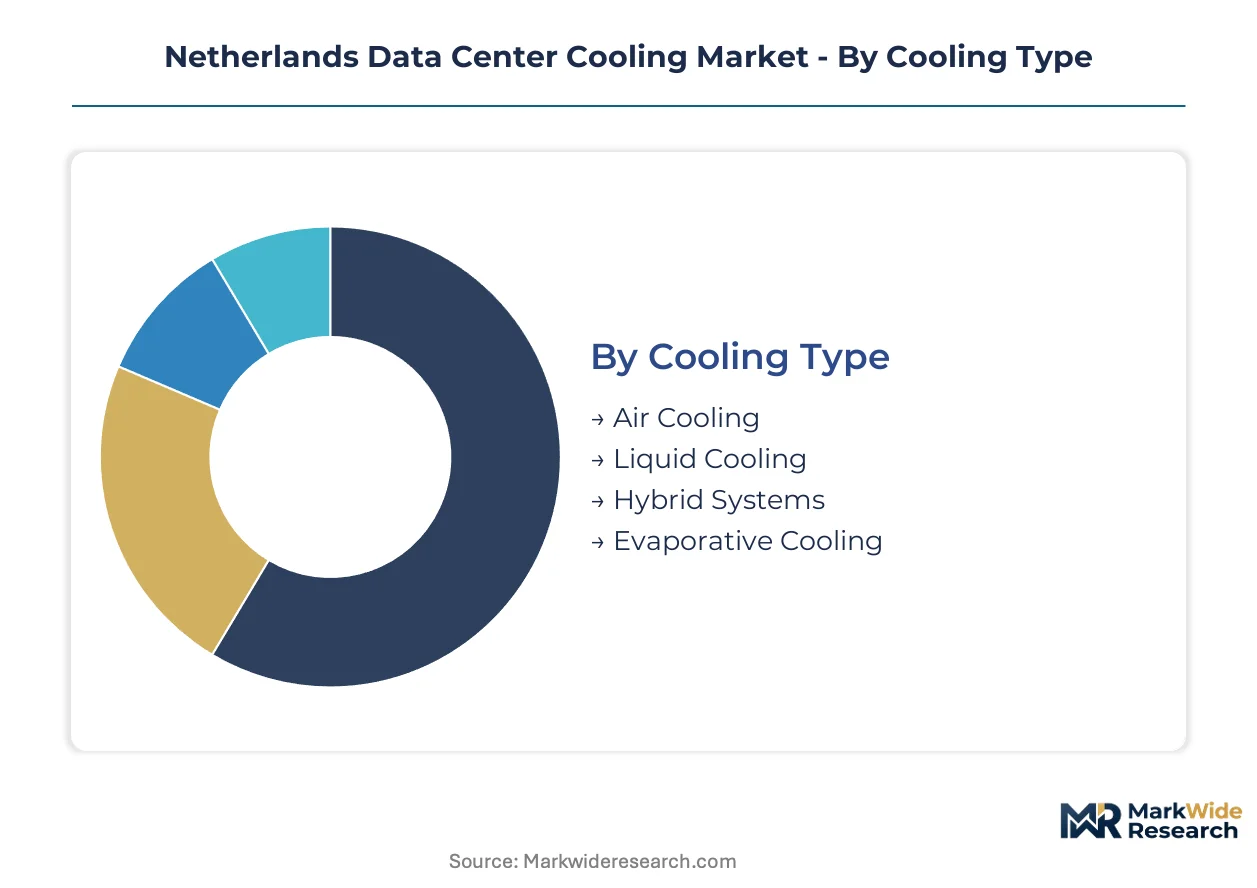
Cooling system selection in Dutch data centers hinges on rack density trajectories and retrofit economics. Facility operators segment procurement by thermal load profile, compliance tier, and integration complexity. Each dimension carries distinct capital intensity and operational trade-offs.
Cooling Type:
Upgrade cycles favor liquid-native designs where legacy air infrastructure imposes replacement costs. Operators weigh retrofit complexity against density gains when phasing cooling technology transitions.
- Liquid Cooling:Dielectric fluid loops and direct-to-chip cold plates extract heat from AI racks exceeding 30 kW. Cloud providers across the Randstad corridor deploy these systems to satisfy Ministry of Economic Affairs and Climate Policy PUE mandates while supporting GPU-intensive training clusters.
- Hybrid Systems:Phased integration of liquid loops into existing air-cooled footprints preserves mechanical infrastructure investment. Enterprise colocation facilities in Rotterdam and Eindhoven favor this approach to defer full capital replacement while capturing partial density gains.
- Air Cooling:Perimeter precision units and raised-floor distribution maintain legacy Tier II installations. These systems face declining specification share as rack densities breach thermal physics thresholds.
- Evaporative Cooling:Adiabatic and water-side economizer configurations exploit the Netherlands' moderate maritime climate. Satellite markets with lower land costs deploy these systems to minimize mechanical refrigeration energy.
Liquid Cooling sits at the top of the volume ranking, with Hybrid Systems climbing the fastest as operators balance retrofit constraints against density requirements.
End User:
Customer type dictates procurement scale, specification stringency, and vendor relationship structure. Contract terms and technical requirements diverge sharply across tenant categories.
- Cloud Providers:Hyperscale operators issue multi-megawatt tenders with custom thermal specifications. These tenants drive liquid cooling adoption across Amsterdam metro facilities and emerging Rotterdam-Eindhoven corridors.
- Enterprises:Corporate data center operators prioritize operational continuity over density optimization. Their procurement emphasizes service-level agreements and redundant mechanical paths rather than cutting-edge thermal performance.
- Telecom Operators:Edge and central office facilities require compact, low-latency cooling solutions. These deployments concentrate in urban aggregation points with constrained footprint availability.
- Government Institutions:Public sector facilities face procurement transparency requirements and national security screening. BIS certification and EU Green Deal compliance documentation carry elevated weight in tender evaluation.
Cloud Providers command the largest capacity share, with Enterprises expanding most quickly as colocation outsourcing accelerates.
Technology:
Heat transfer mechanism selection determines capital cost, maintenance protocol, and refrigerant regulatory exposure. Dutch operators navigate F-Gas Regulation phase-down timelines when specifying thermal systems.
- Immersion Cooling:Dielectric fluid submersion of entire server assemblies enables the highest rack densities. AI training clusters in hyperscale Amsterdam facilities adopt this technology where air-cooling physics fail entirely.
- Direct Expansion:Refrigerant-based split systems offer deployment flexibility for smaller facilities. These systems face regulatory pressure from EU F-Gas Regulation capacity restrictions and global warming potential limits.
- Indirect Expansion:Glycol-water loops separate refrigerant circuits from data hall air streams. This architecture dominates Tier III enterprise colocation where leak containment and maintenance access matter.
- Chilled Beams:Passive or active radiant cooling panels integrate with architectural ceilings. These systems serve low-density office-adjacent server rooms with aesthetic and acoustic constraints.
Direct Expansion retains the widest installed base, though Immersion Cooling gains share fastest among AI infrastructure deployments.
Building Type:
Facility tier classification structures redundancy expectations, cooling architecture complexity, and certification audit requirements. Dutch permitting ties energy performance standards directly to tier designation.
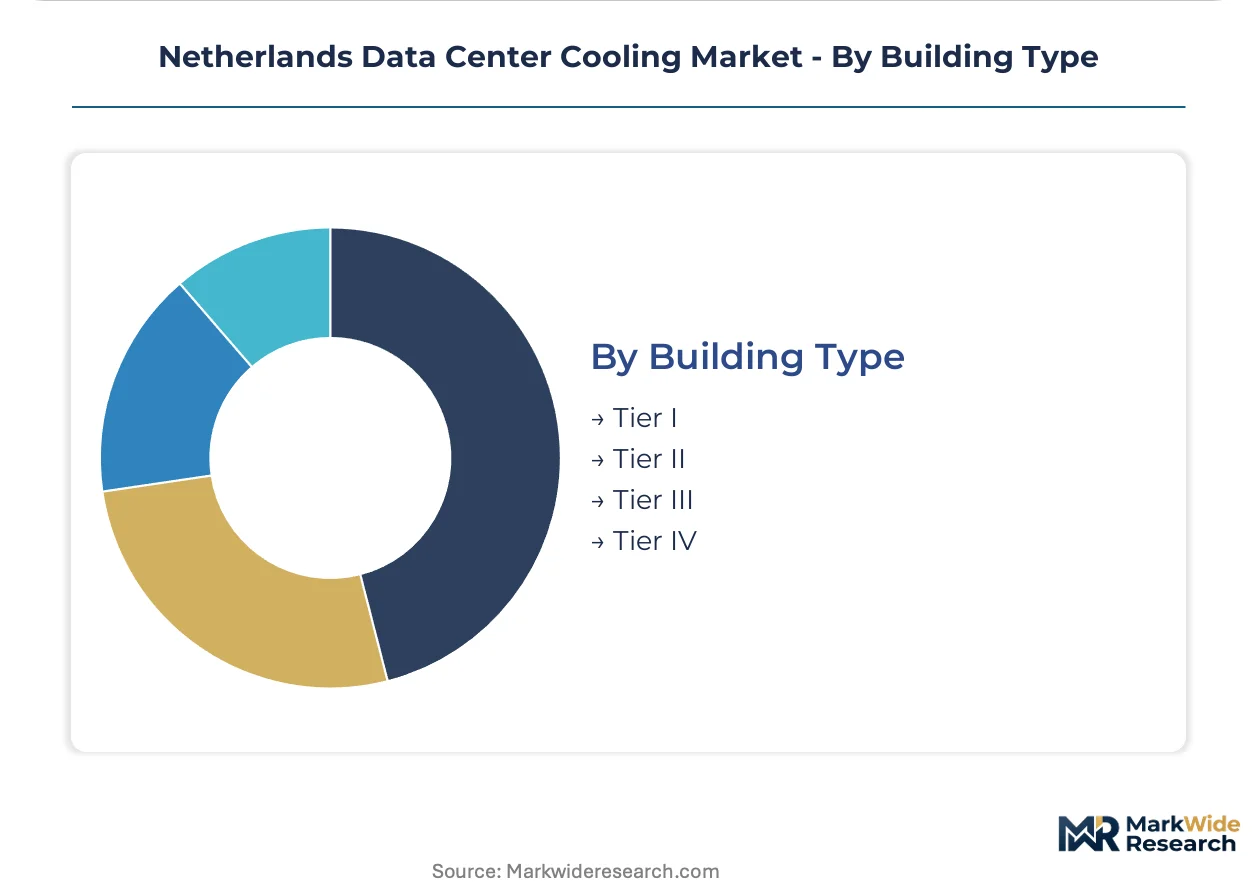
- Tier III:Concurrently maintainable infrastructure with N+1 redundancy on cooling paths. These facilities absorb the majority of new cloud and enterprise capacity across the Netherlands.
- Tier IV:Fault-tolerant architecture with 2N+1 cooling redundancy and compartmentalized infrastructure. Financial services and critical government workloads demand this tier in Amsterdam and Rotterdam financial districts.
- Tier II:Redundant capacity components with single distribution paths. Legacy enterprise facilities and smaller telecom central offices occupy this tier with limited expansion headroom.
- Tier I:Basic capacity with no redundancy requirements. These installations concentrate in edge computing and small business server rooms with minimal cooling sophistication.
Tier III dominates new construction volume, with Tier IV expanding most quickly as critical workload requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Randstad corridor anchors Dutch data center cooling demand, with Amsterdam's metropolitan cluster absorbing hyperscale cloud expansion before municipal restrictions redirected investment toward satellite markets.
Amsterdam Metropolitan Area
Hyperscale cloud providers drive liquid cooling procurement across Tier III and Tier IV facilities exceeding 50 kW per rack. The Ministry of Economic Affairs and Climate Policy enforces power usage effectiveness ratio ceilings that restrict legacy air-cooled designs from new permitting approval. Amsterdam's construction moratorium now redirects cooling system deployment toward Rotterdam, Eindhoven, and Groningen satellite corridors.
Rotterdam
Port-adjacent land availability and submarine cable landing stations attract greenfield data center investment with liquid-native cooling designs. EU Green Deal sectoral carbon budgets compel operators to document embodied emissions in infrastructure procurement. The Rotterdam-Eindhoven corridor now hosts enterprise colocation facilities deploying hybrid systems that phase liquid loops into legacy footprints.
Eindhoven Region
Brainport Eindhoven's high-tech manufacturing ecosystem generates enterprise demand for precision thermal management in R&D data centers. BIS certification requirements for imported cooling equipment shape supplier qualification timelines for non-EU manufacturers. The region's greenfield developments favor direct liquid cooling architectures that avoid air-cooling retrofit costs entirely.
Northern Netherlands
Groningen's renewable energy surplus and lower land costs position the province for sustainable data center expansion with evaporative and adiabatic cooling configurations. The Dutch government's carbon reduction mandates accelerate liquid cooling retrofits across facilities serving AI training clusters. Emerging developments here exploit maritime climate conditions to minimize mechanical refrigeration energy consumption.
Netherlands Data Center Cooling Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue immersion cooling specialization and AI-optimized thermal architectures. The vendor base spans integrated power-and-cooling portfolios, precision air conditioning specialists, and customized climate solution providers. Three archetypes dominate: multinational electrical conglomerates with bundled infrastructure offerings, dedicated thermal management specialists with liquid cooling expertise, and regional climate control fabricators with colocation sector relationships. Competitive moves center on portfolio diversification into integrated sustainability reporting capabilities and geographic expansion toward Rotterdam-Eindhoven-Groningen satellite markets.
Among integrated infrastructure providers, Schneider Electric and Vertiv Group Corp exemplify archetypes occupying positions across the full technology spectrum from precision air conditioning to direct liquid cooling systems. STULZ represents the specialized tier with customized climate solutions extending into enterprise colocation facilities. These three anchors demonstrate how vendor positioning stratifies between bundled electrical-mechanical portfolios and point-product thermal specialization.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv Group Corp |
| STULZ |
| Rittal |
| Johnson Controls International |
| Mitsubishi Electric |
| Danfoss |
| Carrier Global Corporation |
| Asperitas |
| Others |
Pricing and Supply Chain Analysis
Direct liquid cooling retrofits across Dutch Tier III facilities compress project economics while concentrating procurement leverage among integrated power-and-cooling vendors. Dielectric fluid chemistry standardization and cold plate manufacturing scale simultaneously reshape unit cost curves and supplier qualification barriers for non-EU equipment manufacturers.
Pricing Analysis
Copper and aluminum input volatility passes through to chilled water loop construction costs, compressing equipment margins for facility operators. Three-tier pricing structure across premium, standard, and economy levels separates Tier IV fault-tolerant installations from Tier III concurrent maintainability builds and Tier II legacy retrofits. Price differentiation hinges on certification grade and volume scale, with hyperscale cloud tenders commanding steepest discounts. Pricing pressure stems from Amsterdam's construction moratorium redirecting investment toward satellite markets with fragmented demand. Enterprise colocation tenants exhibit highest price sensitivity, while financial services workloads in Rotterdam's port district tolerate premium positioning.
Supply Chain Analysis
Reverse-logistics flows for dielectric coolant reclamation and cold plate refurbishment remain underdeveloped across Dutch liquid cooling deployments. Manufacturing concentration centers on Germany, China, and the Netherlands for precision heat exchangers and pumping systems. Supply chains draw from copper cathode markets in Chile, aluminum smelters in Norway, and fluorinated fluid producers in the United States. Single-source vulnerability sits with specialty dielectric chemistry suppliers facing EU F-Gas Regulation capacity restrictions. Distribution runs through integrated mechanical-electrical contractors in Amsterdam metro and direct vendor relationships emerging across Rotterdam-Eindhoven greenfield corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Netherlands data center cooling market compounds steadily as AI rack density mandates force continuous infrastructure refresh cycles across the Randstad corridor.
For Market Incumbents: Lock in long-term service contracts with hyperscale cloud providers before liquid cooling standardization commoditizes precision thermal expertise. Defend against emerging immersion cooling specialists by anchoring integrated power-and-cooling portfolios in CSRD-aligned sustainability documentation. Prioritize certification investment for BIS compliance to extend qualification timelines for non-EU entrants. Channel control through direct relationships with Tier III developers in Rotterdam satellite markets reinforces pricing power. For New Entrants and Emerging Players: Government institutions with procurement transparency requirements and national security screening represent an underserved buyer archetype with limited incumbent penetration. White-space targets include Groningen's renewable-powered facilities requiring evaporative cooling integration and Brainport Eindhoven R&D data centers demanding precision thermal management. The most penetrable segment sits at Tier IV fault-tolerant builds in financial districts where compliance documentation outweighs brand loyalty. Go-to-market through CSRD reporting partnerships with facility operators lacking in-house lifecycle carbon inventory capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among regional climate control fabricators with colocation sector relationships and liquid cooling retrofit expertise. Long-term viability frames around ten-year infrastructure replacement cycles driven by Ministry of Economic Affairs and Climate Policy energy performance mandates tightening PUE ceilings. Acquisition target archetype: specialized thermal management vendors with dielectric fluid immersion capabilities and existing BIS certification pathways. Monitor Amsterdam municipal policy relaxation signals and hyperscaler capex allocation shifts toward Rotterdam-Eindhoven corridors as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Retrofit Partnership | Schneider Electric anchors large-scale Amsterdam metro deployments through integrated portfolios. |
| CSRD-Aligned Sustainability Reporting | Vertiv Group Corp documents lifecycle carbon inventories to capture procurement preference from cloud providers. |
| BIS Certification Investment | STULZ accelerates supplier qualification timelines for imported precision air conditioning systems. |
| Rotterdam-Eindhoven Geographic Expansion | Asperitas deploys immersion cooling architectures in greenfield facilities avoiding air-cooling retrofit costs. |
| Hybrid System Architecture Development | Danfoss enables phased liquid loop integration preserving legacy mechanical infrastructure investment. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary engagement with data center facility operators, thermal management procurement leads, mechanical contracting executives, and Ministry of Economic Affairs and Climate Policy regulatory affairs specialists alongside secondary validation. Primary sources included structured discussions with Tier III and Tier IV developers across Amsterdam, Rotterdam, and Eindhoven. Secondary data encompassed EU Green Deal sectoral carbon budget documentation, F-Gas Regulation implementation guidance, BIS certification requirement notices, and hyperscaler capex disclosure filings. Bottom-up equipment shipment tracking and top-down facility construction permitting data underwent triangulation against vendor revenue segment disclosures.
Historical reference periods anchored growth trajectory modeling across the projection horizon, with segmentation dimensions spanning cooling type, end user archetype, heat transfer technology, and facility tier classification. CAGRs derived from equipment procurement volume trends and facility power density evolution patterns. Industry-specific forecast inputs incorporated AI training cluster deployment schedules and Ministry energy performance mandate compliance timelines.
Underlying measurement precision varies by segment; liquid cooling and hybrid system categories carry tighter precision than legacy air-cooled installations given concentrated vendor disclosure. Forecasts reflect assumptions regarding hyperscaler expansion continuity, F-Gas Regulation phase-down adherence, and Amsterdam municipal policy stability. Practitioners should monitor Rotterdam-Eindhoven permitting velocity and dielectric fluid chemistry standardization progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Indonesia Data Center Cooling Market
Data Center Cooling
Denmark Data Center Cooling Market
Data Center Cooling
Belgium Data Center Cooling Market
Data Center Cooling
Thailand Data Center Cooling Market
Data Center Cooling
Data Center Liquid Immersion Cooling Market
Data Center Cooling
Singapore Data Center Cooling Market
Data Center Cooling
Japan Data Center Cooling Market
Data Center Cooling
China Study of Data Center Water Consumption Market
Data Center Cooling
Sweden Data Center Cooling Market
Data Center Cooling
Liquid Cooling Racks Market
Data Center Cooling
Data Center Cooling Market
Data Center Cooling
AI Datacenter Liquid Cooling Market
Data Center Cooling
Mexico Data Center Cooling Market
Data Center Cooling
Saudi Arabia Study of Data Center Water Consumption Market
Data Center Cooling
North America Data Center Cooling Market
Data Center Cooling
Global Laptop Cooling Pads Market