
 Switzerland Data Center Cooling Market | 2026-2036
Switzerland Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland Data Center Cooling Market Insights
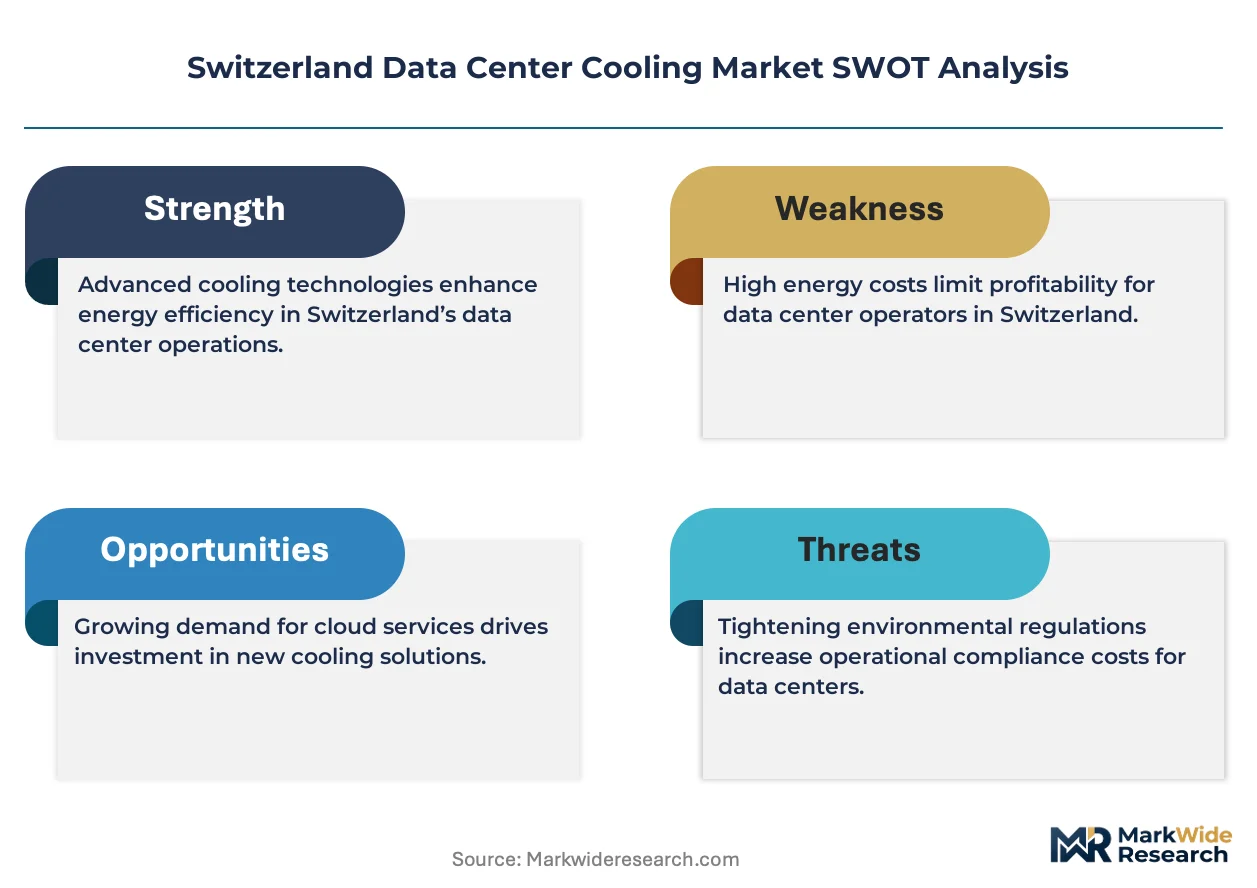
Premium efficiency tier certification is redrawing procurement standards across Swiss data center builds. Schneider Electric SE leverages its integrated power and cooling portfolio to anchor large enterprise deployments in the Alpine region. Rittal GmbH & Co. KG competes through precision enclosure systems that dominate edge computing installations. STULZ GmbH specializes in mission-critical climate control for banking and pharmaceutical facilities.
Switzerland data center cooling encompasses thermal management systems engineered to maintain server inlet temperatures between 18°C and 27°C while minimizing energy use in high-altitude, temperate conditions. These systems employ compressor-based chillers, free cooling heat exchangers, and liquid distribution networks to protect IT infrastructure from thermal-induced downtime. Liquid cooling solutions are capturing the fastest expansion as GPU-intensive AI workloads strain traditional air-based architectures. Colocation providers represent the deepest margin pool among end users, given their multi-tenant density requirements and long-term service contracts. Hybrid cooling configurations are gaining traction as operators phase out legacy systems without full infrastructure replacement.
Swiss Federal Office of Energy efficiency standards, EU F-Gas Regulation transposed into national law, and ISO 50001 energy management certification collectively shape equipment specifications and refrigerant choices. Swissmedic and FINMA oversight of data integrity in pharmaceutical and financial records indirectly mandates cooling redundancy levels that exceed generic commercial standards. Stakeholders must weigh free cooling availability against liquid cooling capital intensity as workload thermal profiles diverge.
Market Dynamics
GPU-intensive AI workloads are compressing thermal design power densities beyond the limits of legacy air-cooled architectures, forcing Swiss operators to reconfigure infrastructure mid-cycle without full facility replacement.
Growth Catalysts
- EU F-Gas Regulation transposition:Swiss federal ordinances are accelerating refrigerant phase-down timelines, pulling demand toward low-GWP alternatives and heat recovery systems in Zurich banking clusters.
- Hyperscale facility expansion:Financial services firms in Geneva are commissioning multi-megawatt deployments with liquid-ready designs, tightening local supply chains for precision cooling hardware.
- Free cooling economics:Alpine elevation and temperate summer peaks enable extended economizer hours, slashing compressor runtime for colocation operators in the Lake Geneva corridor.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger fabrication costs swing with commodity markets, compressing margins on chiller and CRAH unit production.
- German component supplier concentration:Precision pumps and variable-speed drives originate predominantly from Baden-Württemberg facilities, exposing Swiss projects to cross-border logistics friction.
- Refrigerant supply fragmentation:Low-GWP alternatives face limited Swiss distribution channels, extending procurement lead times for retrofit installations.
Strategic Opportunities
- Ticino edge computing corridor:Underpenetrated southern Swiss infrastructure near Milan interconnect points offers first-mover positioning for modular liquid cooling skids.
- ISO 50001 certification mandates:Federal energy management standards are creating service contract pull-through for continuous commissioning and predictive maintenance platforms.
- Pharmaceutical cold chain convergence:Swissmedic oversight of data integrity is extending precision cooling requirements from server rooms into adjacent biologics storage, opening cross-selling vectors.
Industry Challenges
- Thermal-hydraulic engineering scarcity:Liquid cooling system design requires rare fluency in both IT workload profiling and HVAC plant operation, constraining deployment velocity.
- Hybrid architecture integration:Operators blending legacy air handlers with new liquid loops face control system synchronization failures and warranty boundary disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland Data Center Cooling Market |
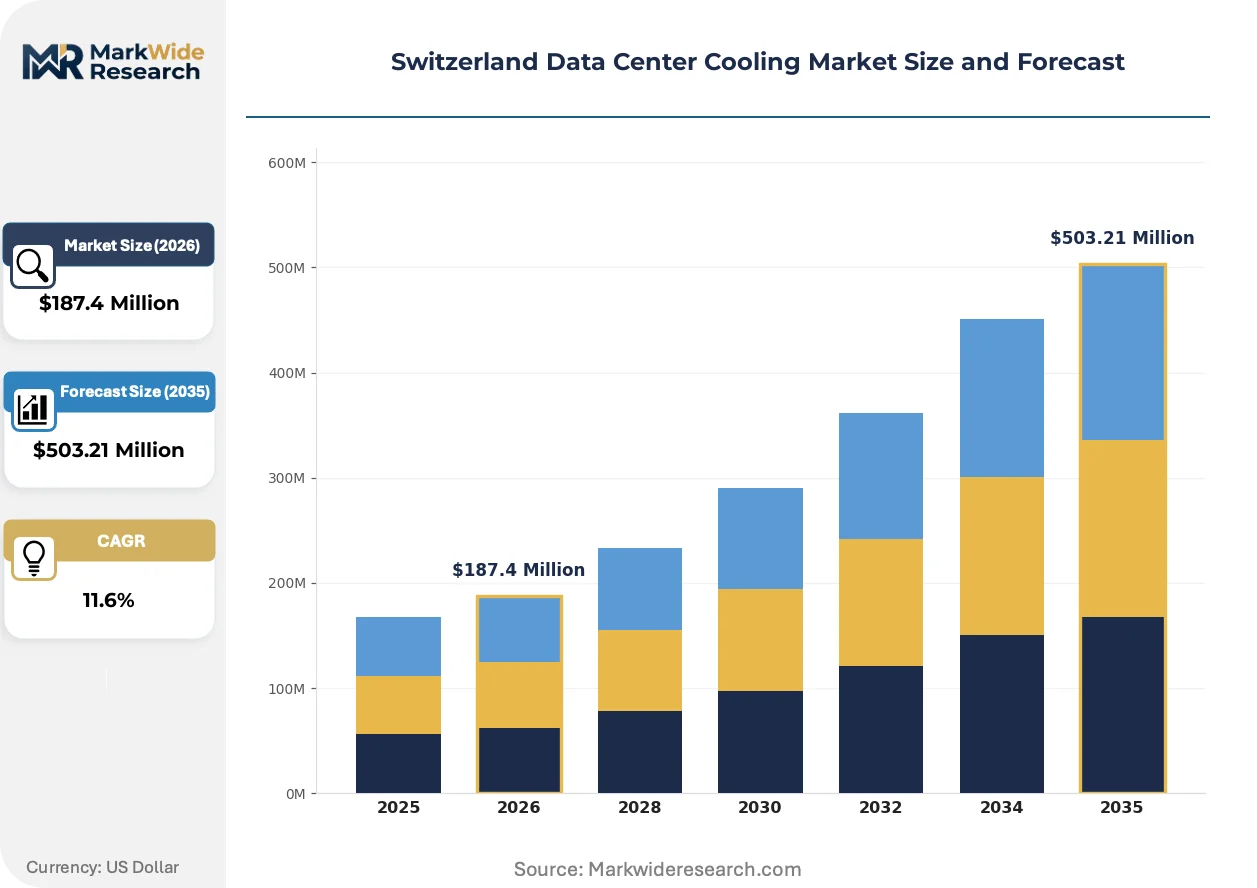
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Technology: Air Cooling, Liquid Cooling, Immersion Cooling, Hybrid Cooling End User: Colocation Providers, Enterprises, Cloud Service Providers, Government Agencies Deployment Model: On-Premises, Off-Premises, Hybrid Environment, Edge Computing Component: Chillers, Cooling Towers, Fans, Condensers |
| Companies Covered | Schneider Electric SE, Vertiv Group Corp, Rittal GmbH & Co. KG, Alfa Laval AB, Munters Group AB, Systemair AB, Mitsubishi Electric Hydronics & IT Cooling Systems SpA, Johnson Controls International PLC, STULZ GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland Data Center Cooling Market Trends and Innovations
Direct-to-chip cooling architectures are compressing facility footprints while Swiss regulators tighten energy accounting transparency, reshaping how operators specify and validate thermal infrastructure.
Immersion cooling dielectric fluids are miniaturizing heat rejection pathways by eliminating air-handling intermediaries entirely. Hyperscale tenants in Zurich are piloting single-phase tanks for 100kW-plus GPU racks, with colocation providers tracking density gains of three-to-fourfold against conventional CRAH rows. This compression is miniaturizing the mechanical plant footprint, freeing white space for revenue-generating compute.
Swiss Federal Office of Energy efficiency ordinances are mandating hourly energy reporting and PUE thresholds for facilities above 500kW. Operators must install sub-metering at rack level and submit annual performance data, with non-compliance triggering permit restrictions. Banking and pharmaceutical verticals are responding fastest, embedding continuous monitoring into FINMA and Swissmedic audit trails.
Buyers are unbundling cooling infrastructure from bundled design-build contracts, sourcing thermal hardware directly and engaging specialist integrators for installation. This disintermediation fragments vendor relationships but captures 12-18% capital savings on large deployments. The pattern is most visible among Geneva-based pharmaceutical firms with in-house engineering competencies and established supplier qualification programs.
Switzerland Data Center Cooling Market Segmentation
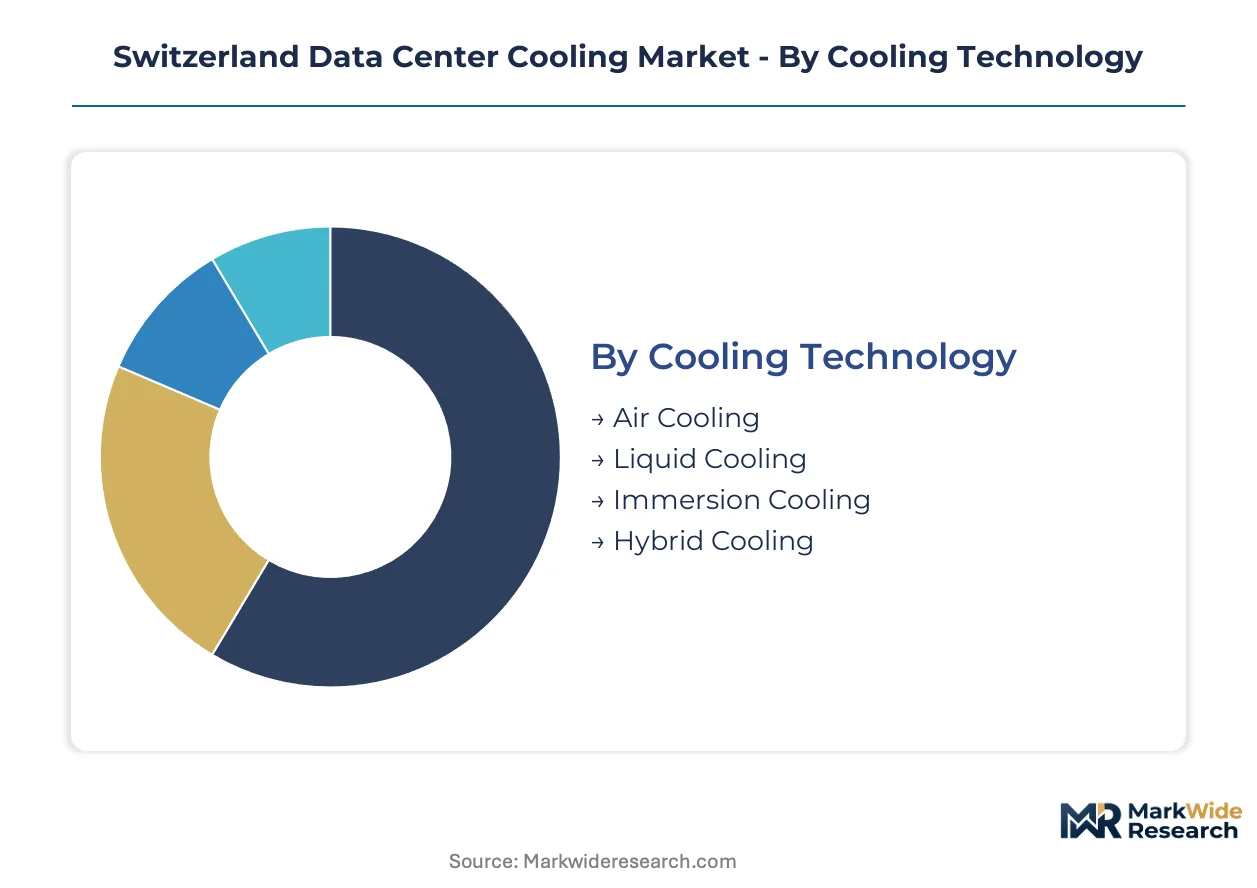
Thermal management procurement in Switzerland fragments across technology readiness, end-use density requirements, and deployment flexibility needs. Each segmentation dimension carries distinct channel economics and regulatory exposure that reshape vendor engagement models.
Cooling Technology:
Technology selection channels through direct OEM relationships for mission-critical installations, while modular retrofits flow via system integrators serving Zurich and Geneva banking clusters.
- Liquid Cooling:Direct-to-chip and cold-plate architectures circulate dielectric fluids to GPU-intensive racks, achieving 100kW-plus densities. Geneva financial services firms are retrofitting legacy white space with liquid-ready manifolds to accommodate AI training workloads without facility expansion.
- Air Cooling:Raised-floor CRAH units and perimeter chillers remain the default for sub-15kW rack densities. Colocation providers in the Lake Geneva corridor extend economizer hours to compress compressor runtime during Alpine summer peaks.
- Immersion Cooling:Single-phase dielectric tanks eliminate air-handling infrastructure entirely. Hyperscale pilots in Zurich test 100kW GPU rack densities with three-to-fourfold space compression against conventional rows.
- Hybrid Cooling:Blended architectures phase liquid loops into existing air-cooled plants. Operators face control synchronization challenges and warranty boundary disputes during mid-cycle infrastructure reconfiguration.
Air Cooling dominates installed base. Liquid Cooling is where expansion concentrates.
End User:
Margin structures vary sharply by tenancy model and compliance exposure, with multi-tenant density requirements commanding premium service contracts.
- Colocation Providers:Multi-tenant facilities require N+1 redundancy and sub-1.3 PUE guarantees to secure long-term contracts. FINMA audit trails mandate continuous thermal monitoring embedded into service level agreements.
- Cloud Service Providers:Hyperscale deployments specify liquid-ready designs from ground-up construction. Geneva-based financial cloud nodes commission multi-megawatt facilities with direct refrigerant distribution networks.
- Enterprises:In-house banking and pharmaceutical data centers face Swissmedic and FINMA oversight extending precision cooling into biologics storage corridors. Zurich pharmaceutical firms unbundle cooling hardware from design-build contracts to capture capital savings.
- Government Agencies:Federal data centers follow Swiss Federal Office of Energy efficiency ordinances mandating hourly energy reporting above 500kW thresholds. Sub-metering at rack level feeds annual performance submissions with permit restrictions for non-compliance.
Colocation Providers anchor revenue concentration. Cloud Service Providers drive capacity expansion.
Deployment Model:
Physical location determines free cooling availability and supply chain access, with southern Swiss infrastructure offering underpenetrated positioning near Milan interconnect points.
- On-Premises:Enterprise-owned facilities in Zurich and Geneva banking districts integrate cooling with building management systems. Swiss federal energy efficiency ordinances tighten operational requirements for captive plants.
- Off-Premises:Third-party colocation and cloud facilities concentrate in the Lake Geneva corridor and Zurich metropolitan cluster. Alpine elevation enables extended economizer hours slashing mechanical refrigeration demand.
- Hybrid Environment:Split workloads across owned and leased capacity require thermal consistency across disparate mechanical plants. Operators synchronize setpoints between on-site chillers and colocation CRAH rows.
- Edge Computing:Distributed nodes in Ticino and southern Swiss corridors demand modular liquid cooling skids for low-latency AI inference. Underpenetrated infrastructure near Milan interconnect points offers first-mover positioning.
On-Premises retains legacy dominance. Edge Computing is climbing the fastest as latency requirements harden.
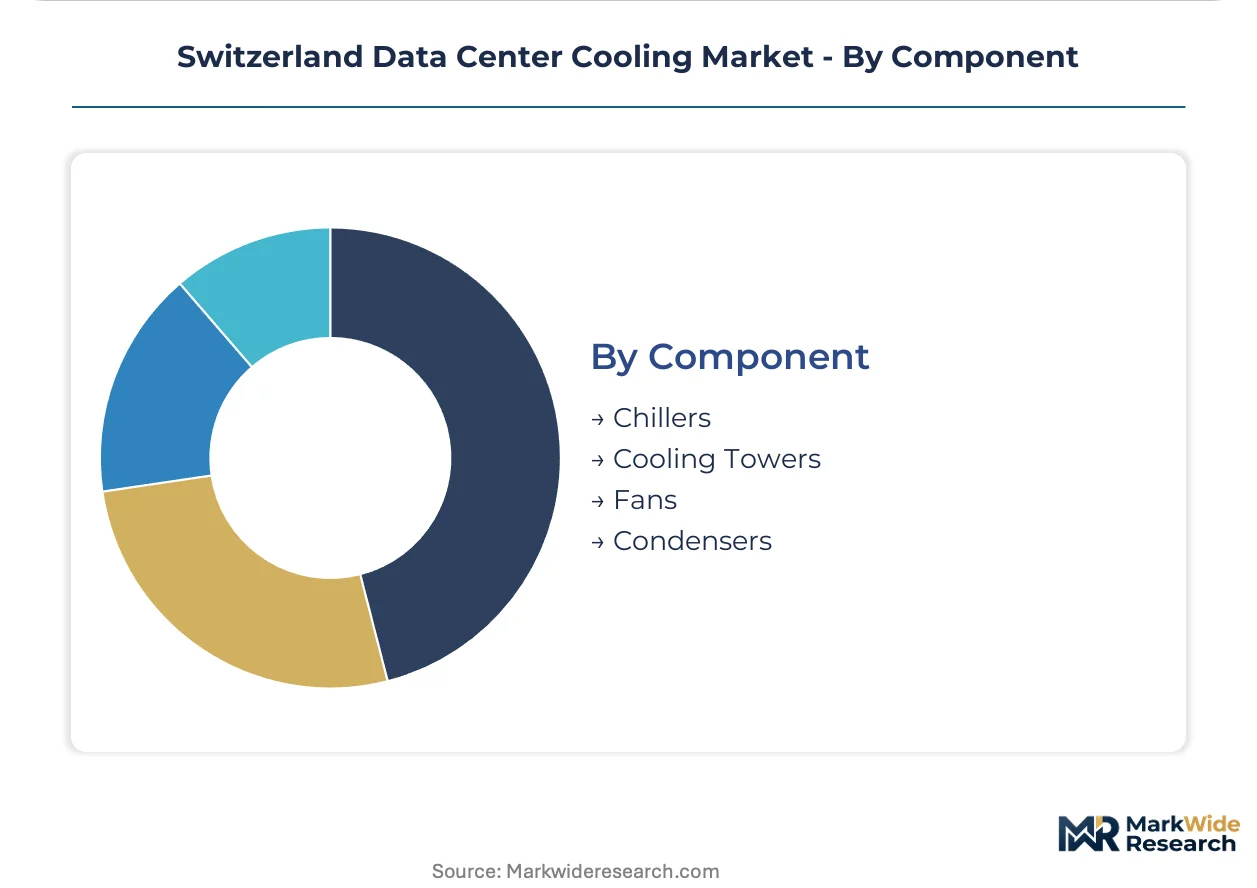
Component:
Hardware procurement concentrates through German component suppliers, exposing Swiss projects to cross-border logistics friction from Baden-Württemberg manufacturing clusters.
- Chillers:Compressor-based units and free cooling heat exchangers protect server inlet temperatures between 18°C and 27°C. Copper and aluminum input volatility swings fabrication costs, compressing margins on large unit production.
- Cooling Towers:Evaporative heat rejection systems exploit Alpine temperate conditions for extended economizer operation. Open-loop designs face water treatment compliance under cantonal environmental regulations.
- Fans:Variable-speed air handlers modulate CRAH and CRAC unit output. Precision pumps and drives originate predominantly from German facilities, creating procurement lead time exposure.
- Condensers:Refrigerant-to-air heat exchangers face EU F-Gas Regulation transposition into Swiss federal law, accelerating low-GWP alternative adoption with limited domestic distribution channels.
Chillers command the largest capital share. Cooling Towers gain share as free cooling economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision component suppliers dominate upstream supply chains serving Swiss data center projects, with Baden-Württemberg manufacturing clusters exporting pumps, drives, and heat exchangers across the Alpine border.
Zurich Metropolitan Cluster
Financial services hyperscale expansion and FINMA compliance requirements are pulling liquid-ready cooling infrastructure into banking district facilities. Swiss Federal Office of Energy efficiency ordinances mandate hourly energy reporting above 500kW thresholds. Colocation providers in Zurich Oerlikon and Schlieren are commissioning multi-megawatt deployments with direct refrigerant distribution networks.
Lake Geneva Corridor
Geneva-based pharmaceutical firms unbundle cooling hardware from design-build contracts to capture capital savings on precision climate systems. EU F-Gas Regulation transposition into Swiss federal law accelerates low-GWP refrigerant adoption. Cloud service providers in Vernier and Meyrin are retrofitting legacy white space with liquid-ready manifolds for AI training workloads.
Ticino Edge Computing Corridor
Underpenetrated southern Swiss infrastructure near Milan interconnect points offers first-mover positioning for modular liquid cooling skids. Cantonal environmental regulations govern open-loop cooling tower water treatment compliance. Distributed AI inference nodes in Lugano and Bellinzona demand low-latency thermal management for GPU-intensive edge deployments.
Swiss Central Plateau
Enterprise-owned captive data centers in Bern and Basel integrate cooling with building management systems under tightening federal energy efficiency standards. ISO 50001 certification mandates create service contract pull-through for continuous commissioning platforms. Pharmaceutical cold chain convergence extends precision cooling requirements from server rooms into adjacent biologics storage corridors.
Alpine Free Cooling Zones
Elevated facilities above 800 meters exploit temperate summer peaks for extended economizer hours, slashing compressor runtime. Cantonal water use regulations constrain evaporative heat rejection system deployment. Research computing installations in Davos and Engadin are piloting hybrid architectures blending free cooling heat exchangers with liquid cooling loops.
Switzerland Data Center Cooling Market Competitive Landscape
Listed leaders compete with private specialists across integrated power and cooling portfolios, creating a tiered structure where scale-driven OEMs anchor enterprise deployments while precision enclosure fabricators capture edge computing installations. The vendor base stratifies into three archetypes: integrated infrastructure conglomerates, precision climate control specialists, and modular enclosure system providers. M&A activity concentrates on liquid cooling technology tuck-ins, while capacity expansion focuses on Alpine-region service networks.
Within the integrated infrastructure tier, Schneider Electric SE and Johnson Controls International PLC exemplify scale-driven OEMs with broad power and thermal portfolios. Rittal GmbH & Co. KG and STULZ GmbH occupy positions as German-based precision specialists, with the former representing modular enclosure system providers and the latter anchoring mission-critical climate control archetypes. Vertiv Group Corp sits within the listed leader category alongside these private specialists, creating competitive tension across Zurich and Geneva banking clusters.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Group Corp |
| Rittal GmbH & Co. KG |
| Alfa Laval AB |
| Munters Group AB |
| Systemair AB |
| Mitsubishi Electric Hydronics & IT Cooling Systems SpA |
| Johnson Controls International PLC |
| STULZ GmbH |
| Others |
Pricing and Supply Chain Analysis
Fourteen-to-eighteen week procurement lead times for precision liquid cooling manifolds concentrate pricing power with German component fabricators serving Zurich and Geneva banking clusters, compressing margins for Swiss system integrators caught between commodity input volatility and fixed-price enterprise contracts.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures across Swiss data center builds, with three-tier pricing stratification separating premium-efficiency certified systems from standard and economy configurations. Price differentiation hinges on ISO 50001 energy management certification tier and after-sales service bundling duration. Cost compression in mid-tier chiller segments is intensifying because copper and aluminum input volatility transfers downstream. Colocation providers exhibit highest price sensitivity due to multi-tenant margin pressure, while pharmaceutical enterprises with Swissmedic compliance mandates show lowest sensitivity.
Supply Chain Analysis
Germany and Austria anchor precision pump and variable-speed drive fabrication for Swiss cooling projects, with Baden-Württemberg facilities exporting heat exchanger subassemblies across Alpine logistics corridors. Raw material dependencies center on copper tubing, aluminum fin stock, and low-GWP refrigerant formulations. Single-source vulnerability runs through Baden-Württemberg precision component concentration, exposing Zurich builds to cross-border transit friction. Distribution feeds from OEM direct sales for hyperscale deployments and system integrator channels for modular retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Switzerland data center cooling operates as a defensive-moat market where regulatory entrenchment creates sticky incumbent positions. FINMA and Swissmedic compliance mandates embed switching costs that protect established supplier relationships across banking and pharmaceutical verticals.
For Market Incumbents: Secure liquid cooling engineering talent pools before thermal-hydraulic scarcity constrains deployment velocity for AI workload retrofits. Deepen backward integration into precision manifold fabrication to offset German supplier concentration risk. Lock long-term service contracts with Geneva pharmaceutical firms unbundling hardware procurement from design-build arrangements.
For New Entrants and Emerging Players: ISO 50001 certification fast-tracks create viable entry pathways into federal agency and enterprise segments facing mandatory energy management compliance. Target Ticino edge computing corridor for modular liquid cooling skid deployments near Milan interconnect points. Lead with predictive maintenance platform bundling to differentiate against established OEM hardware-only offerings.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because Swiss federal energy efficiency ordinances tighten operational requirements above 500kW thresholds, embedding continuous monitoring and predictive service revenue streams. Acquisition focus should center on liquid cooling technology specialists with existing FINMA audit trail integration. Watch hyperscale tenant liquid-ready specification adoption rates as the inflection signal for capacity expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Technology Acquisition | Captures GPU-intensive AI workload retrofit demand across Zurich banking clusters. |
| ISO 50001 Certification Investment | Unlocks federal agency and enterprise segments under mandatory energy management compliance. |
| Ticino Edge Computing Expansion | Positions modular skids near Milan interconnect points for low-latency AI inference workloads. |
| Predictive Maintenance Platform Launch | Captures service contract pull-through from continuous commissioning mandates. |
| Low-GWP Refrigerant Supply Agreement | Secures distribution channels ahead of EU F-Gas Regulation phase-down timelines. |
Research Methodology
A spread of perspectives from data center engineering directors, colocation procurement leads, Swiss Federal Office of Energy policy officers, thermal hardware OEM sales executives, and pharmaceutical facility managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through SEC filings of listed infrastructure OEMs, Swiss federal ordinance registries, EU F-Gas Regulation transposition documents, and customs data tracking cross-border component flows. Bottom-up installation tracking across Zurich and Geneva metropolitan clusters triangulated against top-down energy consumption projections.
Segmentation dimensions modeled span cooling technology type, end-user vertical, deployment model, and component category across the projection horizon. CAGRs derive from installation volume trajectories, efficiency standard adoption curves, and workload thermal density evolution. Industry-specific forecast inputs include GPU rack density specifications from hyperscale tenants and Swissmedic audit trail cooling redundancy requirements.
Decision-makers should treat outputs as directional under assumptions of stable EU-Swiss regulatory alignment and continued Alpine free cooling economics; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in federal energy efficiency ordinance amendments and hyperscale tenant liquid cooling specification adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Hong Kong Data Center Cooling Market
Data Center Cooling
China Study of Data Center Water Consumption Market
Data Center Cooling
Italy Data Center Cooling Market
Data Center Cooling
Middle East District Cooling Market
Data Center Cooling
Europe District Cooling Market
Data Center Cooling
Data Center Liquid Cooling Market
Data Center Cooling
United States Data Center Cooling Market
Data Center Cooling
Liquid Cooling Racks Market
Data Center Cooling
Data Center Cooling Market
Data Center Cooling
Saudi Arabia Study of Data Center Water Consumption Market
Data Center Cooling
Latin America Data Center Cooling Market
Data Center Cooling
APAC Data Center Cooling Market
Data Center Cooling
High-purity Data Center Thermal Management Fluids Market
Data Center Cooling
Taiwan Data Center Cooling Market
Data Center Cooling
Mexico Data Center Cooling Market
Data Center Cooling
Chile Data Center Cooling Market