
 Global Gas Cylinder Market | 2026-2036
Global Gas Cylinder Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gas Cylinder Market Foresight
Carbon-fiber reinforced polymer is repositioning total cost of ownership across high-pressure gas containment. Worthington Industries leverages integrated steelmaking to sustain margin capture in legacy cylinder formats. Hexagon Composites anchors its position through filament-wound Type IV technology leadership. Luxfer Gas Cylinders differentiates via aluminum-lined hybrid designs that navigate weight-sensitive mobility applications.
A gas cylinder is a portable pressure vessel engineered to store and transport compressed, liquefied, or dissolved gases at working pressures typically spanning 150 to 700 bar, constructed from seamless steel, aluminum, or fiber-reinforced composite materials through processes including deep drawing, spin forming, or filament winding. These vessels serve critical functions across medical oxygen therapy, industrial welding, fire suppression systems, and alternative fuel storage where safe containment under pressure is mandatory. Composite cylinders command expanding share in hydrogen and natural gas vehicle applications where weight reduction directly extends vehicle range, while seamless steel retains dominance in welding and fabrication due to cost efficiency and established recycling infrastructure. Medical applications represent a concentrated margin pool as hospitals prioritize lightweight aluminum cylinders for portable oxygen delivery.
ISO 11119 governs composite cylinder design and testing protocols, while the EU F-Gas Regulation and US DOT 49 CFR standards shape material eligibility and transport permissions across jurisdictions. China's GB 17258 and NMPA medical device oversight further segment product certification requirements for market entry. Stakeholders must monitor evolving hydrogen refueling standards and pressure-rating harmonization between regional codes to align R&D pipelines with compliant deployment timelines.
Market Dynamics
Carbon-fiber composite manufacturing is compressing cylinder weight-to-pressure ratios while ISO 11119 compliance requirements force retooling across legacy steel fabrication networks. This material transition redistributes competitive advantage toward filament-winding specialists and away from integrated steel producers.
Growth Catalysts
- EU F-Gas Regulation phase-down:Industrial refrigerant containment is accelerating cylinder replacement cycles across cold-chain logistics in Germany and France.
- Filament-wound Type IV technology:Hydrogen mobility clusters in California and South Korea are specifying all-composite pressure vessels for 700-bar fueling protocols.
- Medical oxygen infrastructure:Japan's METI directives on home healthcare expansion are driving aluminum cylinder procurement for portable therapeutic delivery.
Market Restraints
- Carbon fiber supply concentration:Precursor material sourcing from a limited set of Japanese and US suppliers creates input cost volatility for composite cylinder manufacturers.
- Steel recycling infrastructure lock-in:Established scrap-metal recovery networks in India and Brazil sustain cost advantages for seamless steel formats that resist composite penetration.
- DOT 49 CFR transport restrictions:US Department of Transportation classification protocols limit certain composite cylinder configurations from interstate freight, constraining distribution flexibility.
Strategic Opportunities
- Saudi Arabia hydrogen export hubs:Neom and Jazan industrial zones are commissioning high-pressure storage infrastructure that favors Type III aluminum-lined composite designs.
- India PLI scheme for clean tech:Production-linked incentives for hydrogen equipment manufacturing are attracting cylinder assembly investments in Gujarat and Tamil Nadu.
- Smart cylinder telemetry integration:IoT pressure monitoring and predictive fill-level algorithms are creating aftermarket service revenue streams for fleet operators.
Industry Challenges
- Filament-winding technician scarcity:Composite manufacturing requires specialized aerospace-trained labor pools that remain concentrated in Germany and Japan.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of EU TPED, US DOT, and China GB approvals extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gas Cylinder Market |
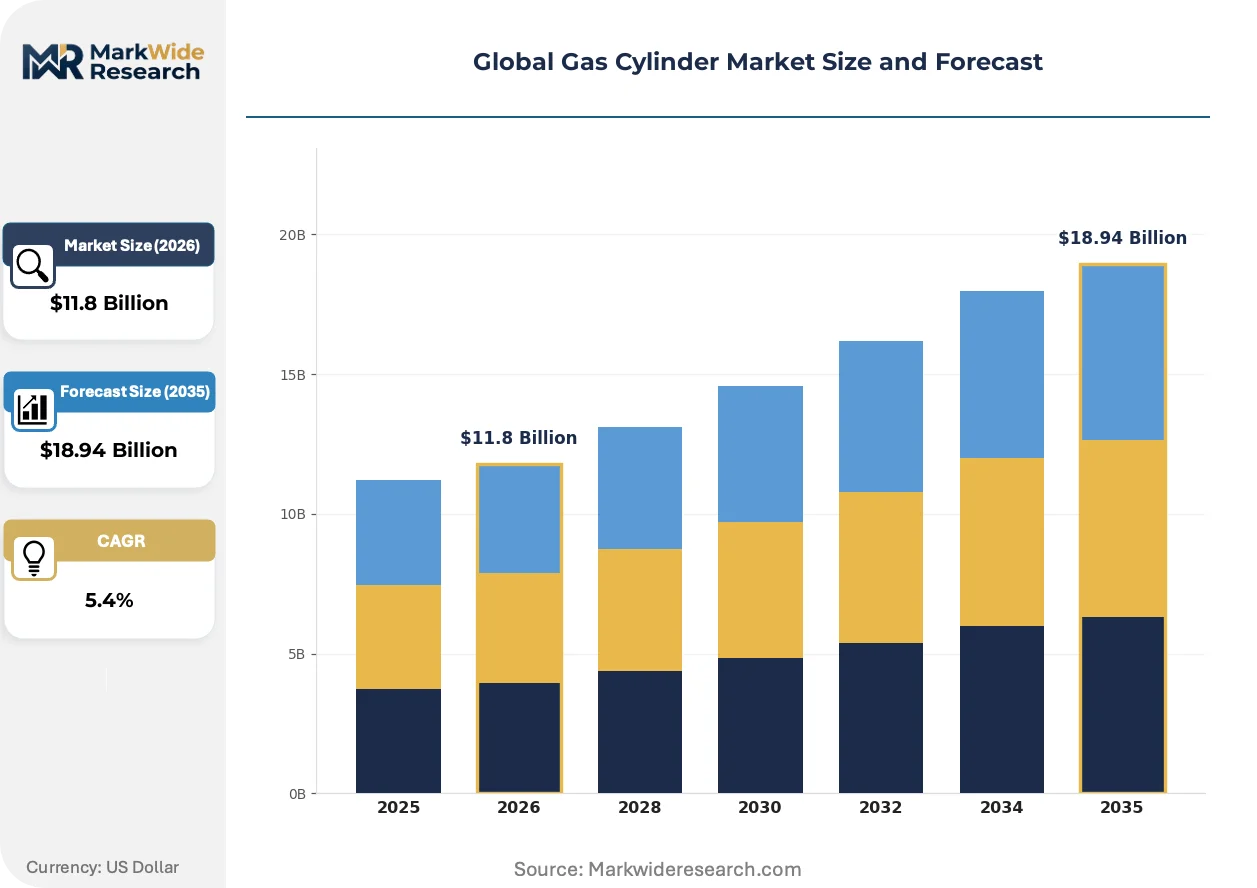
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seamless Steel, Aluminum, Composite, Carbon Steel, Alloy Steel Application: Medical, Welding & Fabrication, Fire Suppression, Food & Beverage, Scuba Diving End User: Hospitals, Construction Sites, Fire Safety Services, Breweries, Diving Centers Valve Type: Standard Valve, High Pressure Valve, Safety Valve, Integrated Valve, Cylinder Valve |
| Companies Covered | Chart Industries, Time Technoplast, Luxfer Gas Cylinders, Drägerwerk AG, Beijing Tianhai Industry, Hexagon Composites, Faber Industrie, CIMC Enric Holdings Limited, Worthington Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gas Cylinder Market Shifts & Advancements
Pressure vessel architecture is fragmenting into application-optimized formats as hydrogen storage, medical portability, and industrial welding each demand divergent weight-pressure-cost tradeoffs. This specialization is forcing manufacturers to abandon universal cylinder platforms.
Filament-wound carbon fiber overwrap is modularizing around liner material selection. Automotive OEMs in South Korea and Germany are specifying swappable Type III and Type IV modules that share common boss geometries and valve interfaces. This standardization is compressing development costs for hydrogen fuel cell vehicle programs while enabling aftermarket retrofit of existing fleet vehicles.
China's GB 17258 revision and NMPA medical device oversight are tightening aluminum alloy purity requirements for therapeutic oxygen cylinders. The industrial consequence is disqualification of secondary-smelter material streams that previously supplied cost-sensitive portable medical units. Hospitals in Shanghai and Beijing are responding by consolidating procurement around certified primary-aluminum suppliers with documented alloy traceability.
After-sales fill-cycle monitoring is unbundling from cylinder hardware sales. Industrial gas distributors in the United States are deploying telemetry-equipped fleets that charge by usable gas delivered rather than cylinder unit rental. This consumption-based model is most visible in Texas and Pennsylvania welding fabrication clusters where contractor customers prioritize cash-flow predictability over asset ownership.
Global Gas Cylinder Market Segmentation
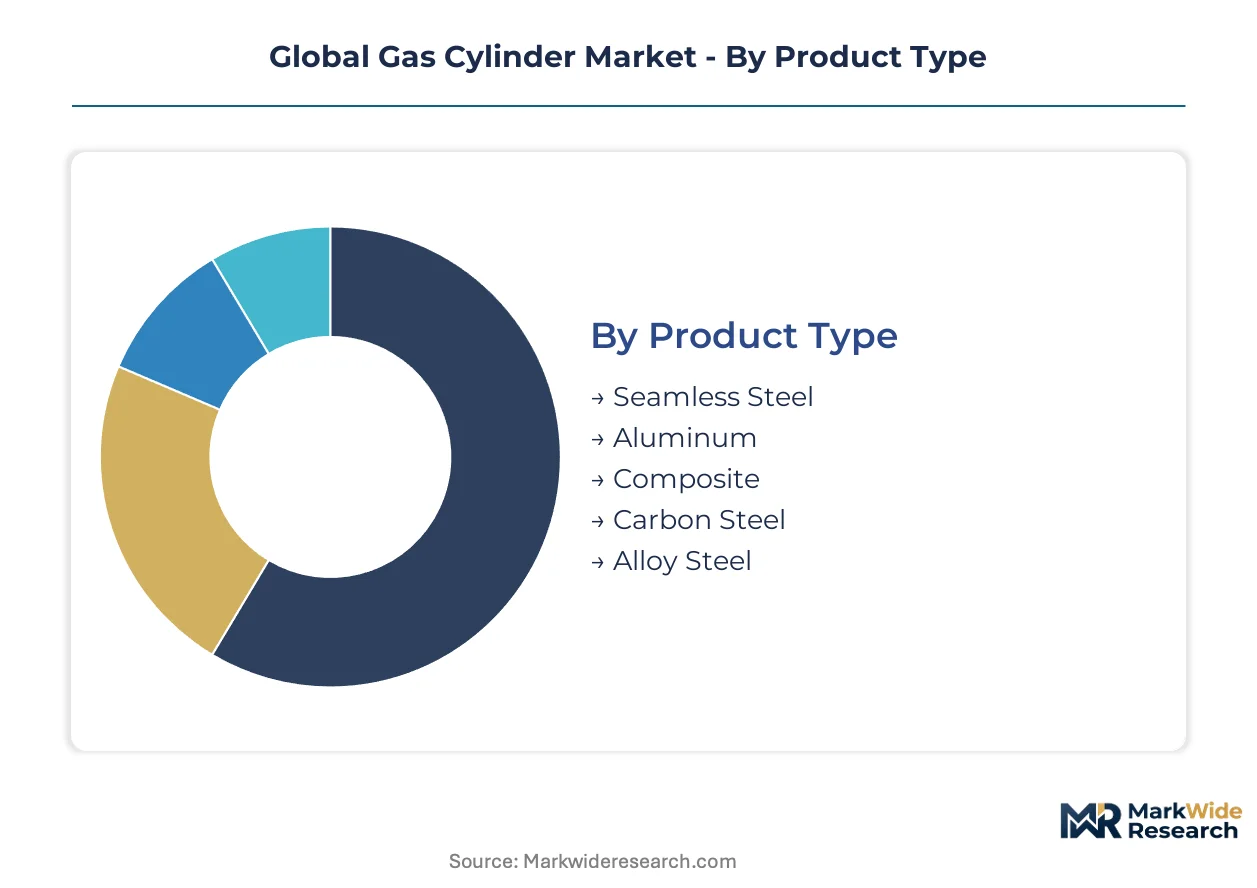
Gas cylinder segmentation reflects divergent pressure requirements, material compatibility, and regulatory pathways across end-use environments. Product architecture and valve configurations determine integration depth with downstream equipment, while application-specific certification creates distinct procurement channels.
Product Type:
Material selection dictates whether cylinders function as standalone transport vessels or embed within complex fuel systems requiring liner compatibility.
- Seamless Steel:Deep-drawn or spin-formed carbon steel construction delivers 150-300 bar working pressure at lowest unit cost. Construction sites in India and Brazil specify seamless steel for oxy-acetylene welding due to established scrap-recovery economics and DOT 49 CFR transport familiarity.
- Composite:Filament-wound carbon fiber overwrap on polymer or aluminum liners achieves 700-bar ratings at 30-40% weight reduction versus steel. Hydrogen mobility clusters in Germany and California mandate Type III/IV composite for fuel cell vehicle integration where range extension justifies premium positioning.
- Aluminum:Extruded and spun 6061-T6 alloy cylinders serve portable medical oxygen where weight reduction enables ambulatory patient mobility. Japan's METI home healthcare directives are accelerating aluminum procurement for therapeutic delivery systems.
- Carbon Steel:Welded construction with protective coatings dominates industrial refrigerant containment. EU F-Gas Regulation phase-down cycles are forcing replacement demand across cold-chain logistics in France and Germany.
- Alloy Steel:Chromium-molybdenum formulations withstand corrosive process gases in specialty chemical applications. Niche demand concentrates in Texas and Louisiana petrochemical corridors where sour gas service requires enhanced metallurgy.
Volume placements concentrate in Seamless Steel; the faster expansion belongs to Composite.
Application:
End-use environments create divergent certification burdens and replacement cadences that segment margin profiles.
- Medical:Therapeutic oxygen delivery demands aluminum or composite construction with NMPA or FDA device oversight. Hospital procurement in Shanghai and Beijing is consolidating around primary-aluminum suppliers with documented alloy traceability under revised GB 17258.
- Welding & Fabrication:Oxy-fuel cutting and shielding gas supply represents the largest installed base. Texas and Pennsylvania fabrication contractors prioritize predictable rental economics over cylinder ownership, driving telemetry-equipped fleet deployment.
- Fire Suppression:High-pressure CO2 and clean agent containment requires corrosion-resistant linings. Data center expansion in Virginia and Nevada is specifying integrated valve systems for automated discharge protocols.
- Food & Beverage:Beverage-grade CO2 and nitrogen service demands sanitary internal finishes. Craft brewery proliferation in Colorado and Oregon is fragmenting procurement toward smaller lot sizes with rapid turnaround.
- Scuba Diving:Aluminum and steel configurations balance buoyancy characteristics against corrosion resistance. Recreational diving centers in Florida and Queensland specify alloy-specific maintenance protocols under ISO 6406 hydrostatic testing.
Revenue concentration sits with Welding & Fabrication; Medical is climbing the fastest on home healthcare infrastructure buildout.
End User:
Customer scale and technical sophistication determine whether procurement emphasizes unit economics or total cost of ownership frameworks.
- Hospitals:Large health systems negotiate multi-year cylinder service contracts bundling equipment, maintenance, and gas supply. Consolidated procurement in Tokyo and Osaka is favoring aluminum lightweighting for porter efficiency.
- Construction Sites:Distributed contractor networks rent cylinders through industrial gas distributors on project-duration terms. Indian construction growth in Gujarat and Tamil Nadu is sustaining steel cylinder demand despite composite alternatives.
- Fire Safety Services:Municipal and commercial suppression system installers require DOT or TPED-certified vessels with documented hydrostatic test histories.
- Breweries:Small-batch craft producers favor flexible rental arrangements over capital-intensive cylinder fleets.
- Diving Centers:Seasonal operators prioritize visual inspection turnaround and valve interchangeability across equipment pools.
Contractor rental volumes dominate Construction Sites; telemetry-enabled service models are gaining share fastest among Hospitals.
Valve Type:
Valve integration depth determines whether cylinders interface with standardized filling infrastructure or require proprietary handling equipment.
- Integrated Valve:Boss-mounted regulator and pressure management systems embed within cylinder architecture. Automotive OEMs in South Korea specify swappable modules with common geometries for hydrogen fuel cell vehicle programs.
- High Pressure Valve:700-bar rated designs with redundant sealing serve hydrogen refueling protocols. California and German mobility clusters are mandating these configurations for 350/700-bar dual-pressure dispensing.
- Standard Valve:Threaded CGA or DIN connections dominate industrial gas interchangeability.
- Safety Valve:Pressure relief devices with fusible plug or burst disc protection serve flammable or toxic gas service.
- Cylinder Valve:Generic term encompassing handwheel-operated shutoff designs across pressure classes.
Shipment volumes cluster around Standard Valve configurations; Integrated Valve designs are expanding most quickly on hydrogen system standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial gas demand concentrates in Germany, China, and the United States where refueling infrastructure investments are accelerating cylinder procurement. Hydrogen mobility clusters and medical oxygen expansion are redistributing regional growth rates away from traditional welding strongholds.
United States
California's hydrogen mobility corridors are mandating 700-bar composite cylinders for fuel cell vehicle integration under NHTSA safety protocols. The DOT 49 CFR framework governs interstate transport permissions, creating certification complexity for new composite formats. Texas welding fabrication clusters are deploying telemetry-equipped rental fleets that charge by gas delivered rather than cylinder ownership.
Germany
EU F-Gas Regulation phase-down cycles are forcing refrigerant cylinder replacement across cold-chain logistics in Bavaria and North Rhine-Westphalia. KBA vehicle-type approval requirements are accelerating Type III and Type IV composite adoption for automotive hydrogen storage. Industrial clusters around Stuttgart and Munich are specifying filament-wound vessels for 350/700-bar dual-pressure dispensing protocols.
China
GB 17258 revision and NMPA medical device oversight are tightening aluminum alloy purity requirements for therapeutic oxygen cylinders in Shanghai and Beijing. NMPA certification is disqualifying secondary-smelter material streams that previously supplied cost-sensitive portable medical units. Yangtze River Delta hydrogen infrastructure investments are attracting Type III aluminum-lined composite manufacturing.
Japan
METI directives on home healthcare expansion are driving aluminum cylinder procurement for portable therapeutic oxygen delivery in Tokyo and Osaka. JIS standards govern medical device traceability requirements that consolidate hospital procurement around certified primary-aluminum suppliers. Kanto region fabrication contractors are transitioning rental fleets toward lightweight formats for porter efficiency.
Saudi Arabia
Neom and Jazan industrial zones are commissioning high-pressure hydrogen storage infrastructure that favors Type III aluminum-lined composite designs. The national hydrogen export strategy is attracting cylinder assembly investments aligned with SFDA industrial equipment oversight. Eastern Province energy corridors are specifying 700-bar vessels for ammonia cracking and hydrogen liquefaction feedstock storage.
Global Gas Cylinder Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated steel producers defending welding markets while filament-winding specialists capture hydrogen mobility premiums. The vendor base organizes around three strategic archetypes: legacy metals fabricators with recycling infrastructure, composite technology licensors with aerospace-trained labor pools, and diversified industrial gas equipment integrators. Capacity expansion and strategic partnerships dominate competitive moves, with players seeking backward integration into carbon fiber precursor supply or downstream control over telemetry-enabled fleet services.
Within the composite technology tier, Hexagon Composites and Luxfer Gas Cylinders exemplify divergent liner strategies for high-pressure containment. Among integrated steel specialists, Worthington Industries occupies a position sustained by captive metallurgy and established scrap-recovery networks. Chinese fabricators including Beijing Tianhai Industry and CIMC Enric Holdings Limited represent scale-driven manufacturing archetypes serving domestic infrastructure buildout and export markets respectively.
| Leading Market Players |
|---|
| Chart Industries |
| Time Technoplast |
| Luxfer Gas Cylinders |
| Drägerwerk AG |
| Beijing Tianhai Industry |
| Hexagon Composites |
| Faber Industrie |
| CIMC Enric Holdings Limited |
| Worthington Industries |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation phase-down mandates gate qualified supply for refrigerant containment cylinders while simultaneously restricting premium-tier pricing access to ISO 11119-certified composite manufacturers. This environmental compliance framework bifurcates the supplier base between legacy steel fabricators serving price-sensitive welding markets and filament-winding specialists capturing hydrogen mobility premiums.
Pricing Analysis
Volume placements concentrate in seamless steel at economy-tier unit economics while composite formats command margin premiums in mobility applications. Three-tier pricing structure across premium, standard, and economy levels separates ISO 11119-certified Type IV vessels from DOT 49 CFR-compliant steel cylinders and welded carbon steel refrigerant units. Cost compression in steel recycling networks is intensifying because established scrap-recovery infrastructure in India and Brazil sustains seamless steel cost advantages. Construction site contractors exhibit highest price sensitivity, while automotive OEMs in Germany and South Korea prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
ISO 11119 and DOT 49 CFR certification requirements gate supply chain participation, disqualifying secondary-smelter aluminum streams and uncertified filament-winding operations. Carbon fiber precursor production concentrates in Japan and the United States, aluminum liner extrusion centers on Germany and China, and steel deep-drawing capacity clusters in India and Brazil. Raw material sourcing draws from Toray and Hexcel carbon fiber supply, Rusal and Chalco primary aluminum, and Nippon Steel and ArcelorMittal carbon steel coil. Single-source vulnerability in Japanese carbon fiber precursor supply creates input cost volatility. Distribution runs through industrial gas distributor rental fleets and direct OEM supply contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where carbon fiber supply concentration and multi-jurisdiction certification timelines are forcing weaker fabricators toward exit or acquisition.
For Market Incumbents: Acquire filament-winding technician capacity and aerospace-trained labor pools in Germany and Japan to defend hydrogen mobility positioning. Secure backward integration into carbon fiber precursor supply through long-term offtake agreements with Toray or Hexcel to mitigate input cost volatility. Counter the threat of Chinese scale-driven manufacturers by accelerating Type III/IV module standardization for swappable hydrogen vehicle platforms. For New Entrants and Emerging Players: Direct-to-fleet telemetry integration offers the lowest barrier entry path for cylinder aftermarket service revenue capture. Target India's PLI scheme for hydrogen equipment manufacturing in Gujarat and Tamil Nadu where production-linked incentives offset certification investment burdens. Pursue white-space in smart cylinder IoT deployment for Texas and Pennsylvania welding fabrication clusters seeking consumption-based rental economics. For Investors and Strategic Acquirers: First-mover SFDA industrial equipment approvals for Saudi Arabia's Neom and Jazan hydrogen export hubs are the leading indicator that Type III aluminum-lined composite manufacturing capacity will achieve premium valuations. Frame long-term viability around 5-10 year hydrogen infrastructure buildout windows rather than cyclical welding demand. Acquire mid-cap filament-winding specialists with existing ISO 11119 certification and aerospace labor relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Precursor | Secures supply from Toray and Hexcel against Japanese precursor concentration risk. |
| Type III/IV Module Standardization | Enables swappable platforms for Hyundai and BMW hydrogen fuel cell vehicle programs. |
| Smart Cylinder Telemetry Deployment | Creates consumption-based revenue streams in Texas welding fabrication clusters. |
| Multi-Jurisdiction Certification Investment | Simultaneous EU TPED, US DOT, and China GB approval compresses launch cycles. |
| PLI-Aligned Manufacturing Scale-Up | Captures India's production-linked incentives for hydrogen equipment in Gujarat. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with filament-winding technicians, industrial gas distributor procurement heads, automotive OEM platform engineers, and hospital biomedical engineers supplied operational validation. Bottom-up cylinder shipment data from EU TPED registration databases, US DOT 49 CFR certification logs, and China GB 17258 compliance records combined with top-down hydrogen infrastructure investment tracking from IEA and national hydrogen council disclosures. Triangulation across primary fieldwork and secondary validation ensured segmentation accuracy across material type, pressure rating, and end-use application.
Granularity-level modeling deployed product-type splits across seamless steel, composite, aluminum, carbon steel, and alloy steel formats with pressure-rating tiers from 150-bar industrial service through 700-bar hydrogen mobility. Application-level modeling captured medical oxygen, welding and fabrication, fire suppression, food and beverage, and scuba diving demand pools with divergent replacement cadences and certification burdens. End-user segmentation distinguished hospital system procurement committees, construction site contractor networks, and fire safety service installers with varying technical sophistication and total cost of ownership frameworks. CAGRs derived from pressure vessel installation rates tied to hydrogen refueling station buildout, EU F-Gas replacement cycles, and METI-directed home healthcare expansion trajectories.
The model holds under sustained hydrogen infrastructure investment and stable carbon fiber precursor supply; deviation in Japanese export restrictions or EU F-Gas phase-down acceleration would shift volume and value trajectories. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
India City Gas Distribution (CGD) Market
Fuels
Petroleum Fuel Dyes Sales Market
Fuels
Global Methane Hydrate Market
Fuels
Diesel As Fuel Market
Fuels
Diesel Fuel Market
Fuels
Global Fuel Ethanol Market
Fuels
United States Coal Market
Fuels
High Octane Racing Fuel Market
Fuels
LNG As a Fuel Market
Fuels
North America Oil and Gas Lubricants Market
Fuels
Fuel Grinder Market
Fuels
Middle-East and Africa Bunker Fuel Market
Fuels
Solid Recovered Fuel Market
Fuels
Global Gas Treatment Market
Fuels
Aerospace Aviation Fuels Market
Fuels
North America Bunker Fuel Market