
 Global Butane Gas Cartridges Market | 2026-2036
Global Butane Gas Cartridges Market Size, Share, and Industry Trends Forecast 2026-2036
Global Butane Gas Cartridges Market Foresight
Food service providers is bifurcating demand away from purely recreational buyers as commercial kitchens adopt portable butane systems for catering and outdoor operations. Iwatani Corporation leverages its integrated gas-to-retail network across East Asian markets. Taeyang Industrial Co., Ltd. anchors production capacity through specialized metal-forming operations for high-pressure cartridges.
Butane gas cartridges are sealed metal containers, typically steel with laminated polymer liners, designed to store liquefied petroleum gas under pressure for controlled release through valved outlets; they serve as portable fuel sources for cooking, heating, and aerosol propulsion where piped gas infrastructure is absent. Disposable cylinders dominate volume shipments due to their convenience in camping and emergency applications, while refillable cartridges capture margin concentration among industrial heating users seeking total cost optimization. Mini canisters represent the fastest-expanding format as ultralight backpacking and solo outdoor travel gain traction.
The EU F-Gas Regulation and China's GB standards enforce pressure-testing protocols and material thickness minimums that raise compliance costs for low-cost exporters. The US DOT and Japan's METI impose distinct transport-classification and labeling requirements that fragment certification pathways. Stakeholders must monitor regulatory divergence between major markets to avoid stranded inventory and redundant testing expenditures.
Market Dynamics
Regulatory fragmentation across the US, EU, and China is forcing cartridge manufacturers to maintain parallel certification tracks, raising fixed costs and compressing margins for mid-scale producers unable to amortize compliance across high volumes.
Growth Catalysts
- EU F-Gas Regulation phase-down:Restrictions on high-GWP refrigerants are redirecting industrial heating demand toward portable butane systems in commercial food preparation across Germany and France.
- Ultralight backpacking equipment:Mini canister formats are capturing share from liquid fuel alternatives as solo outdoor travel expands in South Korea and Japan.
- Emergency preparedness mandates:Japan's METI guidelines for household disaster kits are institutionalizing cartridge stockpiling requirements in municipalities.
Market Restraints
- Steel price volatility:Cold-rolled steel input costs fluctuate with energy markets, squeezing margin predictability for laminated polymer liner production.
- China production concentration:Over 60% of global cartridge metal-forming capacity sits in Zhejiang and Guangdong provinces, creating single-source vulnerability.
- Electric induction substitution:Battery-powered portable cooking systems are displacing butane in basecamp and vanlife segments where grid access exists.
Strategic Opportunities
- India outdoor retail underpenetration:Organized camping equipment distribution remains nascent in tier-2 cities, creating first-mover whitespace for cartridge-camping stove bundling.
- Carbon border adjustment mechanisms:EU CBAM implementation will favor low-carbon steel sourcing, rewarding producers with electric arc furnace supply chains.
- Smart valve integration:Bluetooth-enabled leak detection and consumption tracking are converging with cartridge design, opening premium pricing in institutional catering.
Industry Challenges
- Pressure vessel welder certification:Qualified technicians for high-seam integrity metal forming are scarce in emerging manufacturing locations.
- Multi-jurisdiction labeling:Simultaneous compliance with US DOT hazmat placards, EU CLP pictograms, and China's GB/T markings requires redundant packaging runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Butane Gas Cartridges Market |
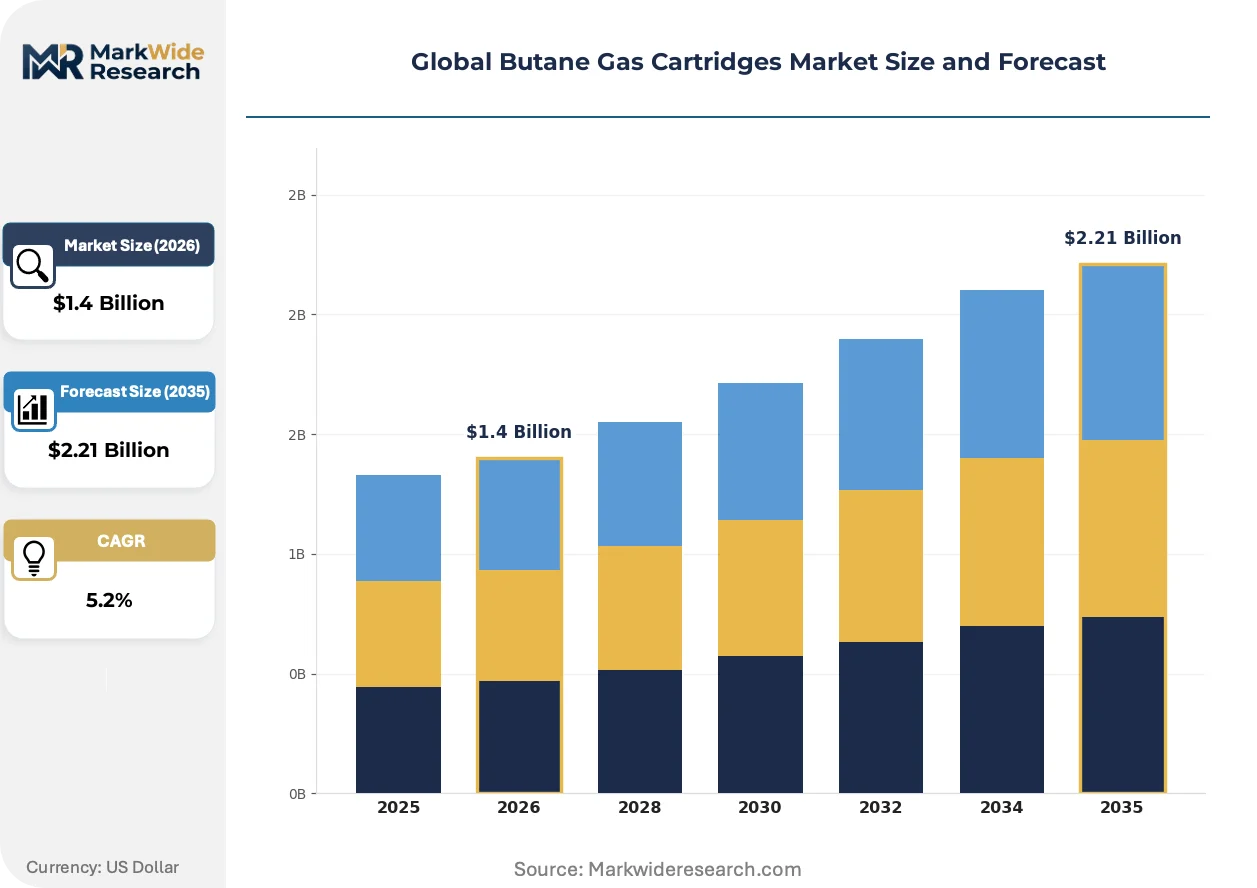
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refillable Cartridges, Disposable Cylinders, Mini Canisters, Bulk Containers Application: Camping Equipment, Portable Stoves, Lighters, Heating Devices, Aerosol Propellants End User: Outdoor Enthusiasts, Food Service Providers, Industrial Heating, Emergency Services Distribution Channel: Direct Sales, Online Retailers, Specialty Stores, Supermarkets, Wholesale Suppliers |
| Companies Covered | Taeyang Industrial Co., Ltd., Iwatani Corporation, Maxsun, Coleman, KOVEA Co., Ltd., Marina Corporation, Foshan Nanhai Lianrun Gas Co., Ltd., Gasmate, Do-Well Aerosols Pvt. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Butane Gas Cartridges Market Shifts & Advancements
Material science advances and regulatory stringency are splitting the market between premium certified products and commodity alternatives, while digital traceability requirements reshape production workflows.
Laminated polymer liner technology is bifurcating the cartridge market by corrosion resistance performance. Commercial kitchens in the EU and Japan are adopting advanced barrier coatings to extend shelf life and reduce flavor contamination. This technology is bifurcating procurement patterns, with institutional buyers demanding certified liner specifications while recreational users accept standard-grade alternatives.
China's GB standards enforcement is tightening pressure-testing protocols and mandating ultrasonic seam inspection for export-bound cartridges. The industrial consequence is accelerated capital expenditure for automated testing lines among mid-tier producers. South Korean exporters to the EU are most affected, responding by consolidating production in facilities pre-certified for both GB and CE marking.
Direct-to-consumer channel expansion is compressing traditional outdoor retail intermediation. Specialty camping brands in the United States and Germany are launching subscription-based cartridge replenishment tied to stove purchases. This shift is most visible in the ultralight backpacking vertical, where route-planning apps now integrate fuel consumption algorithms with one-click resupply ordering.
Global Butane Gas Cartridges Market Segmentation
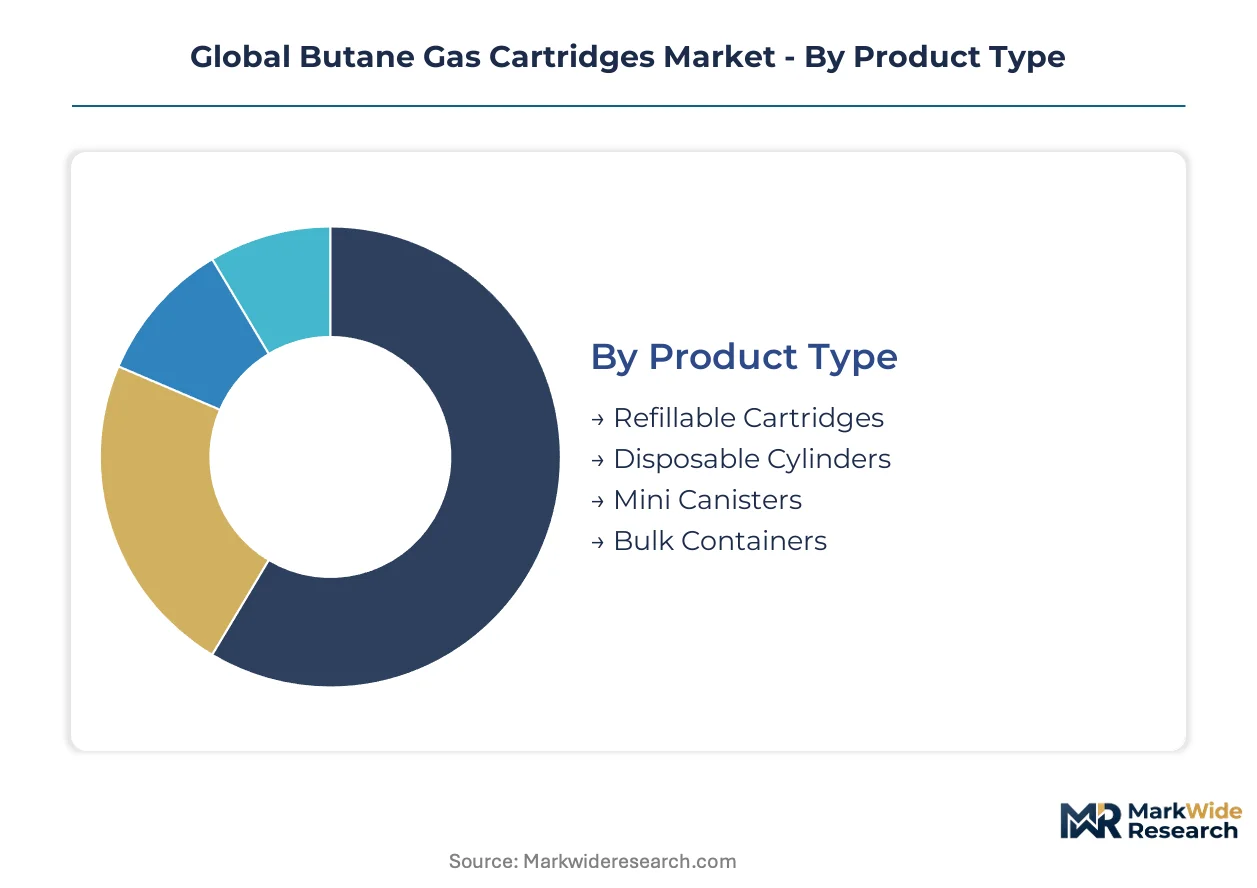
Segmentation in the butane gas cartridges market reveals how regulatory pressure, application specificity, and channel economics fragment procurement patterns across end-use verticals. Each dimension carries distinct margin profiles and compliance burdens that reshape competitive positioning.
Product Type:
EU F-Gas Regulation and China's GB standards enforce divergent pressure-testing protocols that split manufacturing lines by certification tier.
- Refillable Cartridges:Steel shells with replaceable valve systems designed for industrial heating cycles. Food service providers in Germany and France concentrate procurement here to optimize total cost of ownership under refrigerant phase-down mandates. Compliance with repeated pressure cycling requires thicker seam walls.
- Disposable Cylinders:Single-use laminated polymer-lined containers dominate emergency preparedness stockpiling. Japan's METI municipal disaster kit guidelines institutionalize bulk purchases by prefectural governments. Convenience premiums outweigh per-use cost in recreational applications.
- Mini Canisters:Ultralight formats for solo backpacking. South Korean outdoor retailers bundle with stove purchases.
- Bulk Containers:High-volume refill stations for commercial catering operations. Industrial heating users in the United States favor on-site storage.
Established volume favors Disposable Cylinders; emerging adoption favors Mini Canisters.
Application:
End-use differentiation tracks whether piped gas infrastructure exists at the point of consumption.
- Camping Equipment:Integrated stove-cartridge systems for backcountry cooking. Ultralight backpacking demand in South Korea and Japan climbs fastest as route-planning apps enable precise fuel calculation.
- Portable Stoves:Standalone tabletop units for food service catering. Commercial kitchens in France redirect procurement here from fixed LPG installations under F-Gas refrigerant restrictions. Flame control precision matters for sauce preparation.
- Lighters:Small-format cartridges for ignition tools. Convenience store distribution in Japan maintains steady replenishment.
- Heating Devices:Space warming units for construction sites and outdoor events. Cold-weather regions in the United States drive seasonal demand spikes.
- Aerosol Propellants:Industrial spray applications with specialized valve interfaces. EU REACH compliance adds material certification layers.
Commercial substitution favors Portable Stoves; recreational expansion favors Camping Equipment.
End User:
Customer type determines whether procurement emphasizes unit economics or emergency availability.
- Outdoor Enthusiasts:Recreational buyers prioritizing pack weight and burn time predictability. Solo travelers in Japan and South Korea shift toward mini canister formats. Subscription replenishment through direct channels is gaining traction.
- Food Service Providers:Catering operations and mobile kitchens requiring consistent flame output. Germany's commercial kitchen regulations favor certified cartridge systems for outdoor food preparation. Procurement runs through wholesale suppliers with volume pricing.
- Industrial Heating:Construction and warehouse applications demanding extended burn duration. Refillable systems dominate for cost amortization across high-cycle usage.
- Emergency Services:Municipal disaster response agencies stockpiling for grid failure scenarios. Japan's METI guidelines specify minimum household and institutional reserves.
Institutional procurement favors Food Service Providers; preparedness mandates favor Emergency Services.
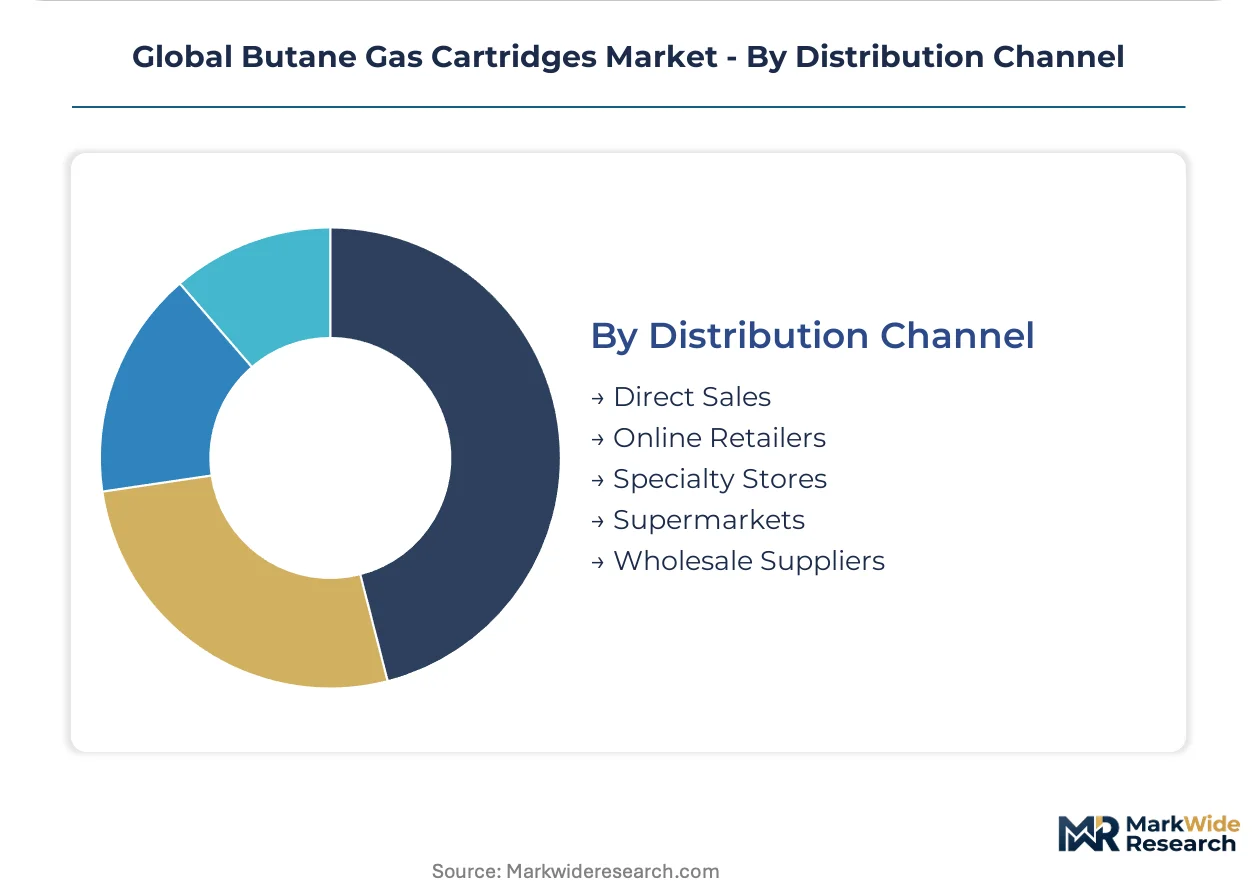
Distribution Channel:
Channel selection reflects whether buyers prioritize immediate availability or cost minimization.
- Direct Sales:Manufacturer-to-institutional contracts for food service and industrial accounts. Large catering chains in the United States negotiate annual volume agreements with specified delivery schedules.
- Online Retailers:E-commerce platforms capturing ultralight backpacking demand. German specialty camping brands integrate fuel consumption algorithms with one-click resupply through route-planning applications.
- Specialty Stores:Outdoor equipment retailers providing technical guidance and compatibility verification. Staff expertise influences cartridge-stove matching decisions.
- Supermarkets:Mass-market convenience placement for emergency preparedness and casual camping. Japan's convenience store density supports impulse replenishment.
- Wholesale Suppliers:Bulk distribution to commercial kitchens and industrial facilities. Zhejiang and Guangdong manufacturing clusters feed regional distribution hubs.
Margin concentration favors Direct Sales; volume expansion favors Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food service providers in Germany and France now match outdoor enthusiasts in South Korea and Japan as dominant buyer archetypes, with procurement patterns diverging between institutional volume contracts and direct-to-consumer replenishment channels.
United States
Industrial heating applications and vanlife culture sustain refillable cartridge demand across the Mountain West and Pacific Northwest. DOT transport-classification requirements for hazmat placarding raise compliance costs for cross-state distributors. Texas and Louisiana host bulk distribution hubs feeding commercial catering operations throughout the Gulf Coast energy corridor.
Germany
Commercial kitchen operators redirect procurement from fixed LPG installations toward portable butane systems under EU F-Gas refrigerant phase-down mandates. The country's national energy regulator enforces strict pressure vessel certification through TÜV inspection protocols. Bavaria and Baden-Württemberg concentrate metal-forming subcontractors serving cartridge manufacturers with CE-marked output.
China
Zhejiang and Guangdong provinces contain over sixty percent of global cartridge metal-forming capacity, with Ningbo and Foshan anchoring laminated polymer liner production. GB standards enforcement through SAMR mandates ultrasonic seam inspection for export-bound units. Domestic demand concentrates in tier-one cities for emergency preparedness stockpiling.
South Korea
Ultralight backpacking culture drives mini canister adoption through Seoul Capital Area outdoor retailers bundling cartridges with stove purchases. The country's national standards body aligns pressure-testing protocols with both GB and CE requirements for dual-market exporters. Busan-Ulsan hosts specialized valve-assembly operations serving Japanese and European buyers.
Japan
METI municipal disaster kit guidelines institutionalize household cartridge stockpiling requirements across prefectural governments. Solo outdoor travel trends in Kanto and Kansai regions accelerate mini canister format expansion. Nagoya-area fabricators supply corrosion-resistant laminated liners for commercial kitchen applications demanding extended shelf life.
Global Butane Gas Cartridges Market Competitive Landscape
Player mix skews toward integrated gas-to-retail networks and specialized metal-forming operations rather than pure-play cartridge fabricators. Market structure reflects moderate consolidation around East Asian manufacturing clusters with fragmented distribution tiers in Western markets. Two strategic archetypes dominate: vertically integrated energy conglomerates controlling cylinder production through captive supply chains, and precision metal-forming specialists concentrating on high-pressure seam integrity. Competitive moves center on dual-certification capacity expansion and direct-to-consumer channel capture through subscription replenishment models.
Among Korean metal-forming specialists, Taeyang Industrial Co., Ltd. exemplifies the precision-fabrication archetype through its specialized operations for high-pressure cartridge applications. Iwatani Corporation represents the integrated-network model with gas-to-retail control across multiple East Asian markets. KOVEA Co., Ltd. occupies a position bridging manufacturing expertise with outdoor equipment brand recognition. These three anchors illustrate how competitive positioning splits between upstream production control and downstream channel access.
| Leading Market Players |
|---|
| Taeyang Industrial Co., Ltd. |
| Iwatani Corporation |
| Maxsun |
| Coleman |
| KOVEA Co., Ltd. |
| Marina Corporation |
| Foshan Nanhai Lianrun Gas Co., Ltd. |
| Gasmate |
| Do-Well Aerosols Pvt. Ltd. |
| Others |
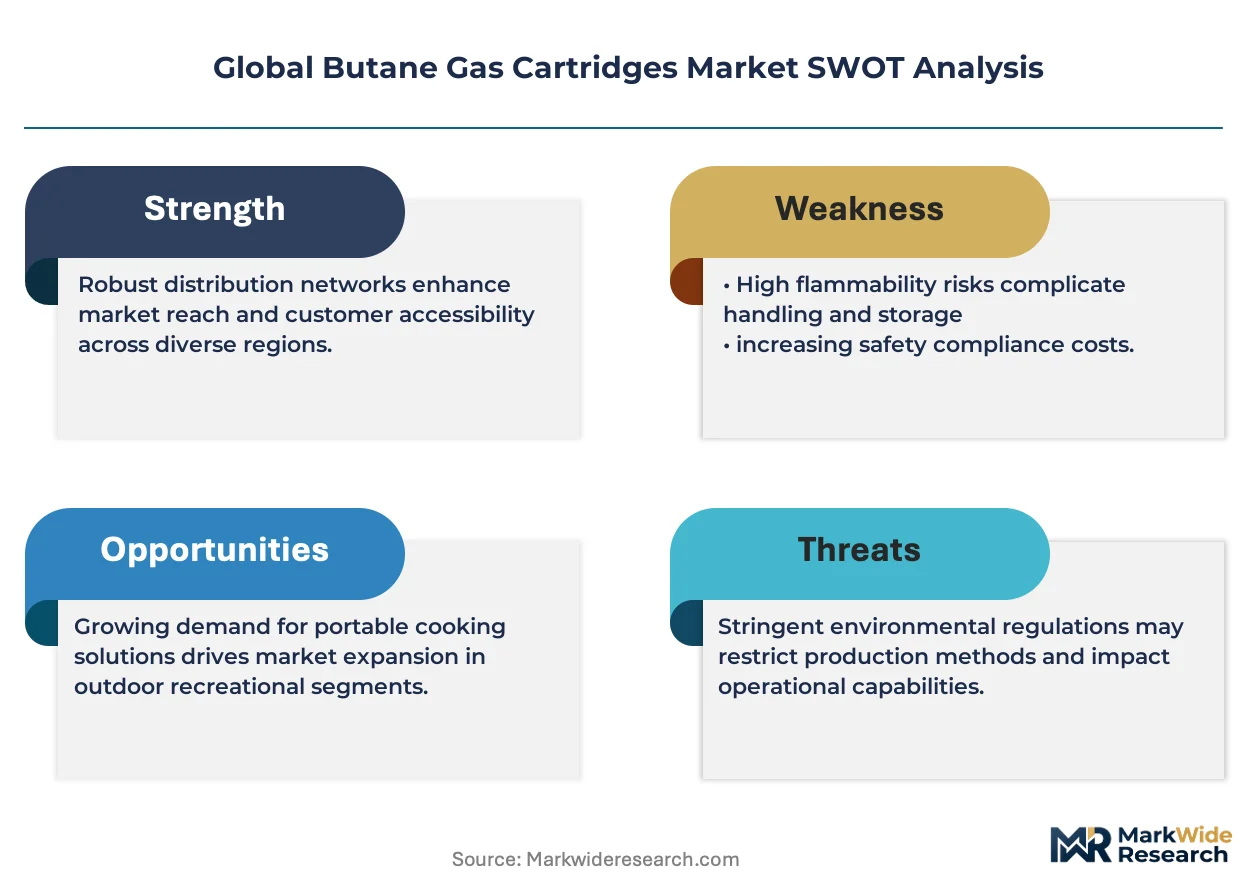
Supply & Pricing Matrix
Long-term offtake contracts with cold-rolled steel indexation lock in laminate liner supply for German and Japanese food service buyers while insulating margin visibility against energy-market volatility. These arrangements concentrate pricing power among integrated producers with captive metal-forming capacity, forcing spot-market dependent distributors into margin compression during input cost spikes.
Pricing Analysis
Cost-plus contracts with London Metal Exchange steel indexation dominate institutional procurement for refillable cartridges, while disposable cylinder spot markets track Zhejiang export prices. Price differentiation rests on CE-marked seam certification and laminated polymer barrier grade, with TÜV-inspected units commanding premium positioning over standard-grade alternatives. Pricing pressure stems from electric induction substitution in vanlife segments, compressing mid-tier portable stove margins. Food service providers exhibit lowest price sensitivity due to total cost-of-ownership framing under F-Gas refrigerant restrictions, whereas recreational backpackers gravitate toward economy mini canisters with subscription bundling discounts.
Supply Chain Analysis
Inventory cycles stretching 8-12 weeks for laminated polymer liners expose downstream fabricators to steel price volatility between order placement and vessel completion. Manufacturing concentrates in China, South Korea, and Japan, with Zhejiang and Guangdong provinces anchoring global metal-forming output. Raw material dependencies center on cold-rolled steel coils, nickel-alloy valve components, and high-density polyethylene barrier films. Single-source vulnerability concentrates in Chinese laminate liner production, where SAMR export certification bottlenecks create allocation risk. Distribution runs through Busan-Ulsan valve-assembly hubs feeding Japanese and European buyers, with direct-to-consumer channels compressing traditional outdoor retail intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cartridge-stove interoperability standardization is creating platform economics dynamics as route-planning applications integrate fuel algorithms with one-click resupply, shifting value capture toward ecosystem orchestrators.
For Market Incumbents: Secure dual-certification capacity expansion across GB and CE marking protocols to preempt stranded inventory from regulatory divergence. Consolidate valve-assembly operations in Busan-Ulsan or Nagoya clusters to reduce multi-jurisdiction labeling redundancy. Backward integration into electric arc furnace steel sourcing will position low-carbon cartridge production ahead of EU CBAM implementation. For New Entrants and Emerging Players: Subscription-based replenishment services for ultralight backpacking segments represent the most penetrable whitespace, as German and South Korean route-planning apps currently under-serve solo travelers with predictive fuel algorithms. Target tier-2 Indian cities through camping stove bundling with organized outdoor retail partners. Deploy direct-to-consumer channel capture with Bluetooth-enabled leak detection as a service-layer differentiator against commodity competitors. For Investors and Strategic Acquirers: Capital is best deployed toward precision metal-forming specialists with pre-certified ultrasonic seam inspection lines and existing Iwatani or Taeyang-tier customer relationships. Long-term viability favors producers with electric arc furnace steel supply chains and smart valve integration roadmaps. Watch for METI disaster kit guideline expansions as the inflection signal for emergency preparedness stockpiling acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Capacity Expansion | GB and CE marking convergence reduces redundant testing expenditures for South Korean exporters. |
| Backward Integration into Low-Carbon Steel | Electric arc furnace sourcing positions ahead of EU CBAM carbon border adjustment mechanisms. |
| Smart Valve Integration | Bluetooth-enabled leak detection opens premium pricing in German institutional catering contracts. |
| Direct-to-Consumer Channel Capture | Subscription replenishment through route-planning apps compresses outdoor retail intermediation. |
| Emergency Preparedness Stockpiling | METI municipal disaster kit guidelines institutionalize bulk cartridge procurement across Japanese prefectures. |
Research Methodology
Desk research of customs trade records, SAMR certification filings, and EU F-Gas Regulation implementation guidance preceded structured interviews with cartridge plant managers, food service procurement leads, outdoor retail category buyers, and valve-assembly technical directors. Primary fieldwork across Zhejiang, Guangdong, and Busan-Ulsan manufacturing clusters combined with secondary validation from METI disaster preparedness documentation and TÜV inspection protocol disclosures. Bottom-up unit economics modeling triangulated against top-down market sizing from steel input consumption and laminated polymer liner trade flows.
Variance decomposition across product type, application vertical, end-user archetype, and distribution channel dimensions shaped the analytical framework throughout the projection horizon. CAGRs derived from segment-level volume trajectories indexed to refrigerant phase-down compliance deadlines and outdoor participation rate shifts. Forecast inputs incorporated F-Gas Regulation enforcement intensity, METI guideline expansion scenarios, and electric induction substitution elasticity in basecamp segments.
Forecasts assume regulatory continuity in EU F-Gas phase-down schedules, China's GB standards enforcement, and Japan's METI disaster kit protocols; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Global Liquid Gas Cylinder (LGC) Market
Fuels
Hydrogen Cylinder Market
Fuels
Alcohol-To-Jet (ATJ) Fuel Market
Fuels
Italy Automotive Engine Oils Market
Fuels
Europe Black and Wood Pellets Market
Fuels
India Liquified Petroleum Gas (LPG) Market
Fuels
Europe Wood Pellet Market
Fuels
Gasoline Market
Fuels
India Coal Market
Fuels
Canada Bunker Fuel Market
Fuels
Global Industrial Burner Market
Fuels
Italy Chemical Logistics Market
Fuels
LPG Cylinder Manufacturing Market
Fuels
Petroleum Fuel Dyes Sales Market
Fuels
Fuel Grinder Market
Fuels
Underground Coal Gasification Market