
 Europe Wood Pellet Market | 2026-2036
Europe Wood Pellet Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wood Pellet Market Foresight
Project finance for combined heat and power retrofits is reconfiguring competitive entry in the Europe wood pellet sector. Drax Group plc leverages its biomass conversion expertise to anchor long-term offtake contracts across Scandinavia and the Baltics. Graanul Invest Group sustains cost leadership through backward integration into Estonian and Latvian forest holdings. Stora Enso Oyj differentiates via integrated pulp-to-pellet streams that control fiber quality from Nordic sawmills.
Wood pellets are densified biomass cylinders, typically six to eight millimeters in diameter and fifteen to thirty millimeters long, manufactured through hammer-milling, drying, and extrusion under high pressure without chemical binders. Their primary purpose is to deliver standardized, high-energy fuel for automated combustion systems in heating and power applications. Premium Pellets command the strongest margin pools where ENplus certification separates certified residential supply from commoditized bulk grades. Industrial Pellets represent the fastest-expanding volume channel as coal-to-biomass conversions at continental power stations accelerate offtake scale. Residential Heating remains the most mature demand segment across Central European markets where stove and boiler penetration already exceeds replacement-cycle thresholds.
The EU Green Deal, the EU AI Act for smart-grid integration, and ECHA REACH compliance for pellet additives collectively shape product standards and market access across member states. EMA guidelines on sustainable biomass sourcing now influence how power utilities structure long-term procurement. Stakeholders must monitor how the EU Green Deal's tightening carbon-border adjustments redirect trade flows from Baltic producers to Western European off-takers.
Market Dynamics
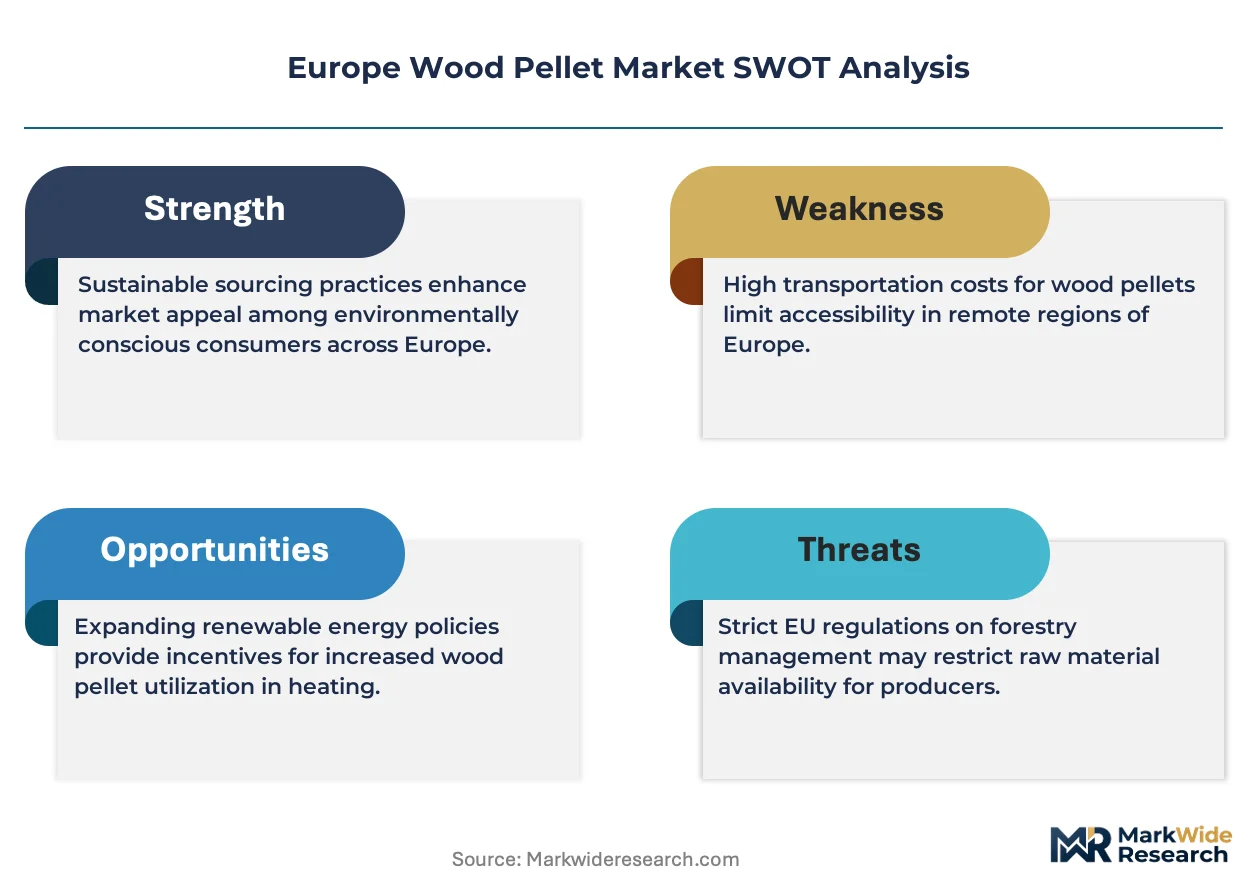
The EU Green Deal's tightening carbon-border adjustments are redirecting Baltic pellet flows toward Western European offtakers, compressing arbitrage margins and forcing producers to certify fiber provenance through ENplus and EMA sustainability frameworks.
Growth Catalysts
- EU Green Deal carbon pricing:The EU's escalating carbon-border adjustment mechanism penalizes fossil heating fuels, tilting household economics toward certified biomass boilers in Germany, Austria, and Italy.
- District heating modernization:Municipal networks across Scandinavia and the Baltics are retrofitting coal plants to biomass, creating anchored demand for industrial-grade pellets with long-term offtake security.
- Hammer-milling automation:Advanced drying and extrusion systems are cutting production energy intensity by fifteen percent, improving unit economics for mid-scale producers competing on delivered cost.
Market Restraints
- Sawmill residue concentration:Nordic fiber supply is controlled by integrated pulp conglomerates, limiting independent pellet producers' feedstock access and pricing leverage.
- ENplus certification backlog:Third-party audit capacity constraints in Eastern Europe are stretching compliance timelines to eight months, blocking market entry for new Baltic suppliers.
- Air-source heat pump substitution:Residential electrification subsidies in Germany and France are diverting household capital from pellet boiler replacements toward heat pump installations.
Strategic Opportunities
- Portuguese and Spanish import penetration:Iberian ports offer underutilized deep-water capacity for North American pellet discharge, bypassing Baltic supply congestion into Italian and French markets.
- Smart-grid integration:The EU AI Act's demand-response protocols enable pellet-fueled combined heat and power plants to bid into frequency regulation markets, stacking revenue streams beyond commodity power sales.
- Industrial carbon capture retrofit:Bioenergy with carbon capture and storage (BECCS) eligibility under EU emissions trading creates negative-emission credit revenue for power utilities burning certified pellets.
Industry Challenges
- Combustion engineering talent scarcity:Automated pellet boiler installation and maintenance requires technicians cross-trained in electronics and solid-fuel systems, a skill combination concentrated in Alpine Austria and Northern Italy.
- Legacy oil tank infrastructure:Residential heating oil storage systems in rural France and Belgium resist cost-effective conversion to pellet silos, trapping households in liquid-fuel dependence despite carbon penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wood Pellet Market |
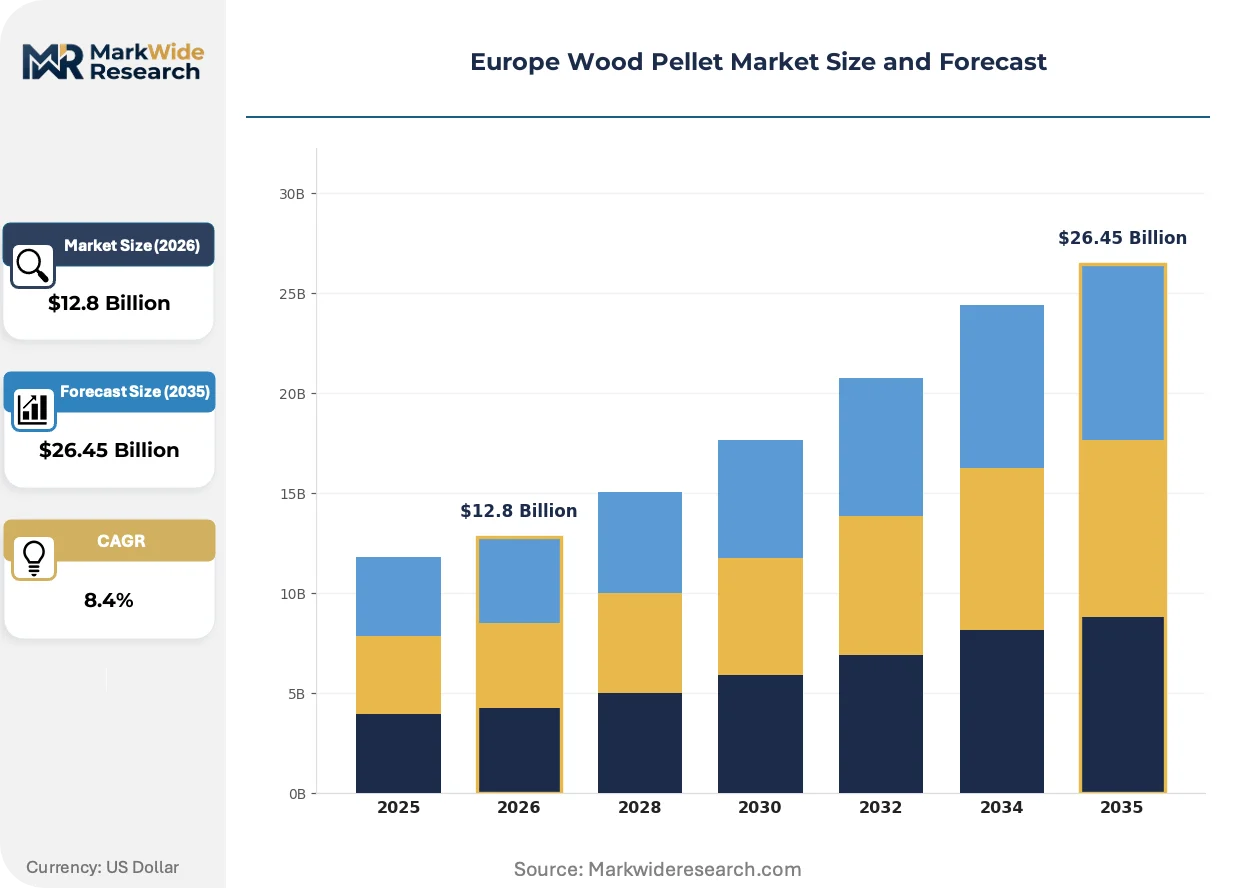
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Premium Pellets, Standard Pellets, Industrial Pellets, Blended Pellets End User: Residential Heating, Commercial Heating, Industrial Heating, Power Generation Material: Pine, Oak, Birch, Mixed Softwood Application: Heating, Cooking, Industrial Use, Biomass Power |
| Companies Covered | Drax Group plc, Graanul Invest Group, Stora Enso Oyj, German Pellets GmbH, Holzindustrie Schweighofer, Scandbio AB, Pinnacle Renewable Energy Group, Vyborgskaya Cellulose, Wood Pellet Energy U.K., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wood Pellet Market Shifts & Advancements
Digital traceability and automated combustion control are converging to transform how pellets are sourced, certified, and consumed across European heating and power markets.
Sensor-embedded pellet delivery systems are digitizing fuel supply chain visibility. District heating operators in Denmark and Sweden are deploying RFID-tagged bulk shipments linked to real-time inventory management platforms. This convergence is digitizing procurement workflows, compressing working capital cycles from thirty days to under seven for integrated utilities.
The EU F-Gas Regulation's phase-down of hydrofluorocarbon refrigerants is indirectly tightening biomass boiler efficiency standards. Installers must now demonstrate seasonal performance factors that favor condensing pellet systems over conventional equipment. German heating contractors are responding by bundling ENplus A1 pellets with modulating burners to secure compliance documentation.
Households are consolidating fuel purchasing through cooperative buying groups. Rural communities in France's Massif Central and Italy's Alpine provinces are forming agricultural syndicates to negotiate direct pellet contracts with Estonian and Latvian producers. This disintermediation is bypassing traditional heating oil distributors who previously controlled last-mile logistics and credit terms.
Europe Wood Pellet Market Segmentation
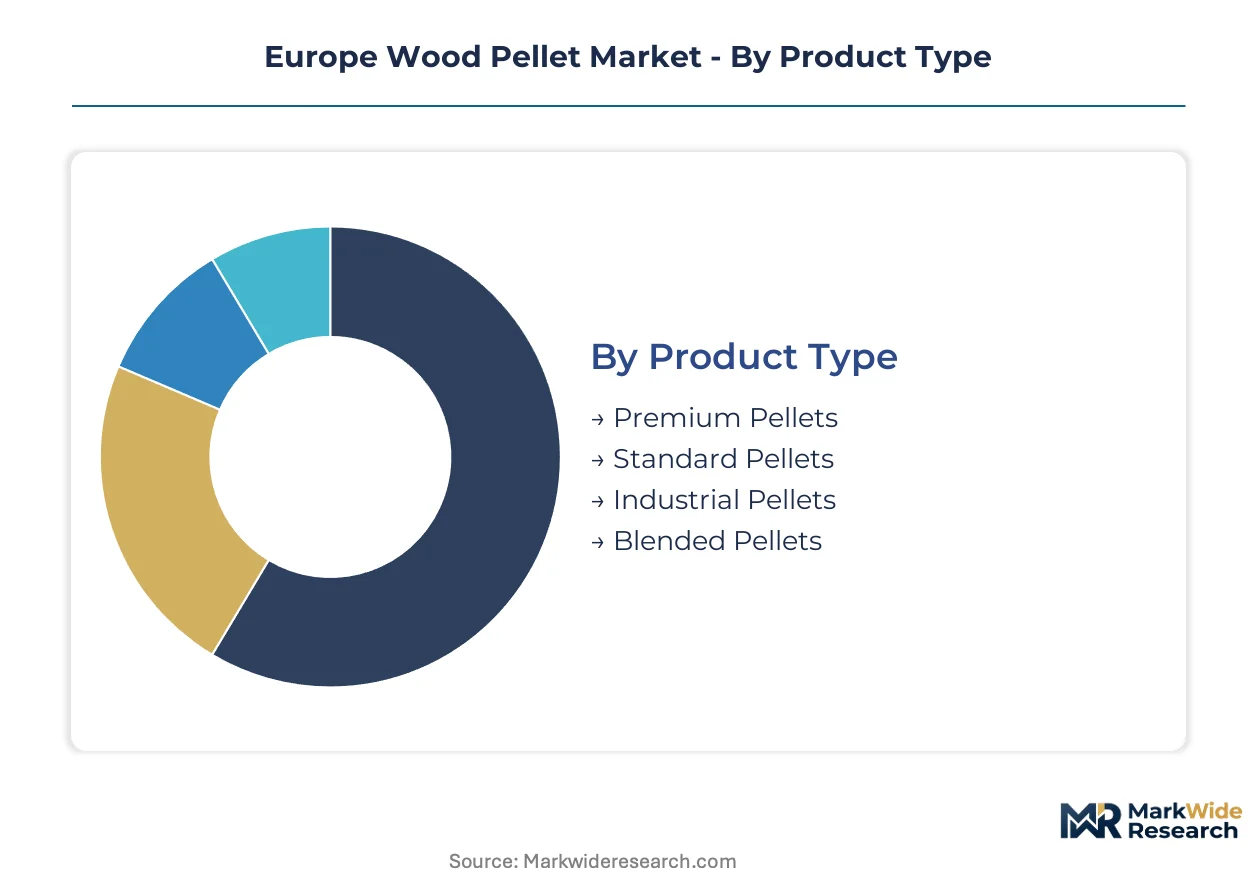
Pellet specification tiers determine combustion system compatibility and certification requirements across European heating and power markets. Segmentation by product grade, end-use intensity, fiber source, and application function reveals how procurement economics diverge between household consumers and industrial offtakers.
Product Type:
After-sales service intensity escalates with certification grade, as ENplus A1 systems require annual burner calibration and ash extraction protocols that lower-tier products avoid.
- Premium Pellets:Manufactured from debarked softwood with moisture content below ten percent and ash residue under 0.7 percent. German and Austrian residential installers specify these grades for condensing boilers in the Alpine corridor, where ENplus A1 certification is mandatory for warranty coverage.
- Standard Pellets:Accept higher bark content and moisture levels up to twelve percent, suitable for non-condensing equipment. Italian consumers in the Po Valley favor this grade for cost-sensitive stove replacements, though ash accumulation demands more frequent maintenance intervals.
- Industrial Pellets:Engineered for utility-scale pulverized fuel systems with bulk density optimized for pneumatic conveying. Drax and Ørsted procurement contracts specify these grades for coal-to-biomass conversions at North Sea power stations.
- Blended Pellets:Combine agricultural residues with wood fiber for cost reduction in district heating networks. Danish operators experiment with straw-wood mixtures to diversify feedstock exposure beyond Nordic sawmill dependence.
Premium Pellets hold the largest share; momentum sits with Industrial Pellets as power utilities accelerate coal displacement timelines.
End User:
Customer scale determines delivery logistics, with bulk pneumatic systems for industrial offtakers contrasting bagged retail channels for household segments.
- Residential Heating:Individual households purchase bagged product through heating contractors and agricultural cooperatives. France's Massif Central and Italy's Alpine provinces concentrate replacement demand as oil boiler depreciation cycles mature.
- Commercial Heating:Hotels, schools, and municipal buildings install mid-scale silo systems with automated feed mechanisms. Austrian commercial operators lead penetration rates due to favorable biomass tariff structures under the national green electricity framework.
- Industrial Heating:Process heat applications in food processing and paper manufacturing require consistent calorific value for kiln and dryer operations. Scandinavian pulp mills integrate pellet combustion into fiber drying stages to reduce natural gas exposure.
- Power Generation:Dedicated biomass plants and converted coal stations consume the highest volumes per offtake point. Baltic producers anchor long-term supply agreements with UK and Dutch utilities seeking carbon-negative credentials under BECCS eligibility rules.
Residential Heating dominates volume; Power Generation is expanding most quickly as carbon-border adjustments penalize fossil generation across EU member states.
Material:
Fiber provenance shapes combustion residue characteristics and supply security, with Nordic sawmill integration controlling access to premium softwood streams.
- Pine:Low ash and high lignin content deliver superior combustion efficiency for residential stoves. Estonian and Latvian forest holdings supply the majority of European pine pellet exports through Graanul Invest's backward-integrated operations.
- Oak:Higher density and calorific value suit commercial boiler applications where heat output stability outweighs ash management complexity. French oak residues from wine barrel cooperages supply niche regional production.
- Birch:Rapid growth cycles enable short-rotation coppice harvesting in Finnish and Swedish forestry models. Birch pellets generate moderate ash requiring weekly cleaning intervals in residential equipment.
- Mixed Softwood:Sawmill residue blends optimize production economics for standard-grade output. Stora Enso's Nordic pulp-to-pellet streams concentrate supply of mixed fiber for industrial power contracts.
Pine commands the greatest volume; Mixed Softwood is gaining share fastest as integrated pulp conglomerates monetize residue streams.
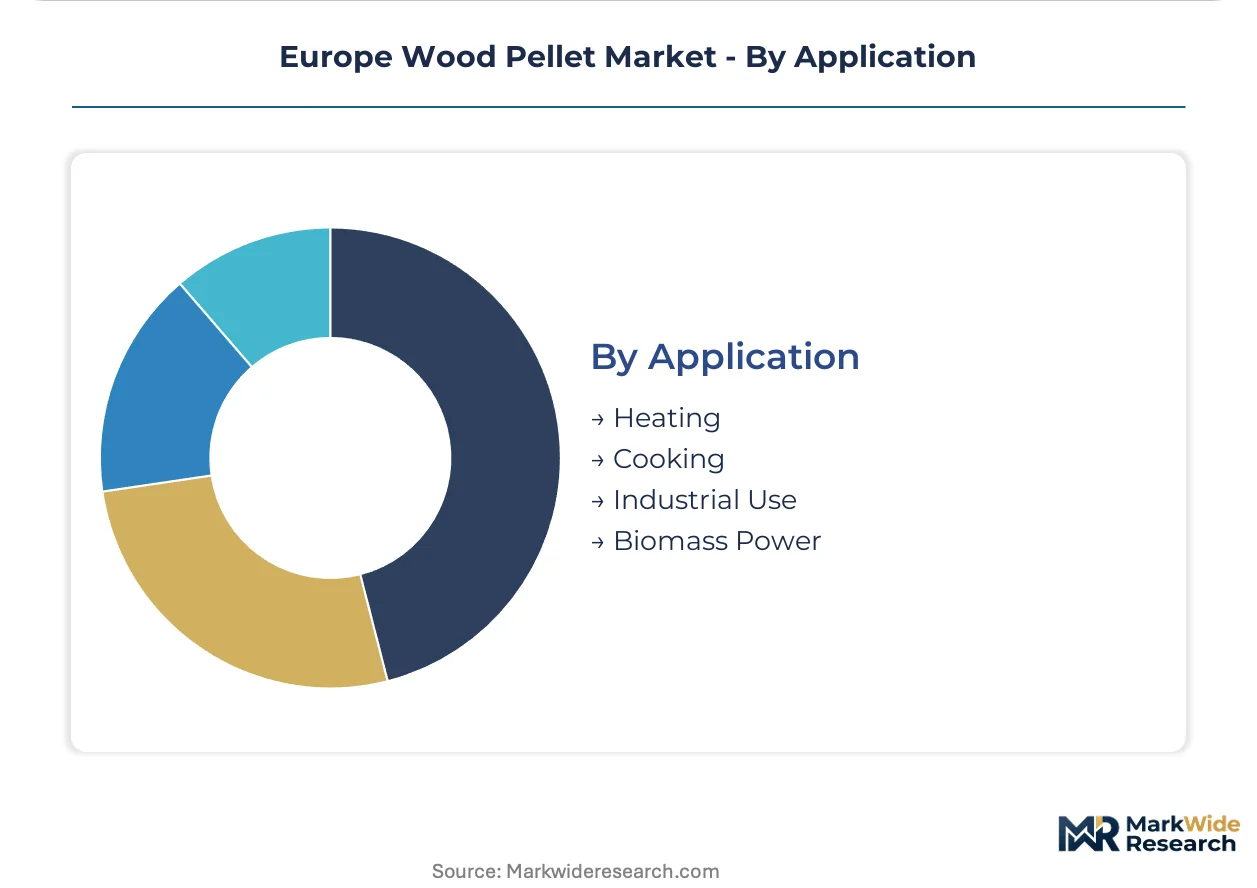
Application:
Functional use case determines equipment specification, with heating applications requiring automated feed systems that cooking and specialized industrial processes do not.
- Heating:Space and water heating applications dominate pellet consumption across Central European markets. German building codes now mandate renewable heat shares that pellet boilers satisfy in retrofitted single-family homes.
- Cooking:Specialized pellet-fired ovens and smokers serve commercial foodservice in Italy and Spain. This niche demands flavor-neutral hardwood grades with controlled moisture for consistent combustion.
- Industrial Use:Process heat for drying, curing, and chemical reactions requires continuous-feed systems with ash removal automation. Portuguese ceramic manufacturers trial pellet substitution for natural gas in kiln operations.
- Biomass Power:Electricity-only and combined heat-and-power generation consume industrial-grade pellets at massive scale. EMA sustainability guidelines now require documented chain-of-custody for utility procurement compliance.
Heating captures the dominant share; Biomass Power shows the steepest expansion trajectory as district heating networks retrofit coal infrastructure across Scandinavia and the Baltics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's carbon-border adjustment mechanism is redistributing pellet procurement economics across member states, with national subsidy frameworks determining household conversion rates from fossil heating systems.
Germany
The Federal Office for Economic Affairs and Export Control administers heating system replacement subsidies that favor ENplus-certified pellet boilers in single-family homes. The Building Energy Act mandates renewable heat shares that biomass systems satisfy. Bavaria's Alpine corridor concentrates installer networks where technician training programs address combustion engineering scarcity.
Italy
Po Valley agricultural cooperatives negotiate direct supply contracts with Baltic producers, disintermediating traditional fuel distributors. The National Recovery and Resilience Plan allocates funds for renewable heating retrofits in rural municipalities. Alpine provinces from Trentino to Friuli-Venezia Giulia host dense concentrations of stove and boiler penetration exceeding replacement-cycle thresholds.
France
The Massif Central's rural communities form syndicates to procure bagged pellets through collective purchasing agreements. Ademe's biomass heating incentive programs compete with electrification subsidies for household capital allocation. Auvergne-Rhône-Alpes clusters installation contractors specializing in oil-to-pellet conversions for legacy tank infrastructure.
Sweden
District heating operators in Stockholm and Malmö retrofit coal infrastructure to biomass with long-term offtake security for industrial-grade pellets. The Swedish Energy Agency's carbon pricing framework accelerates municipal network decarbonization. Nordic sawmill integration around Västerbotten controls fiber supply for premium residential grades.
United Kingdom
Drax Group plc anchors biomass conversion demand through Yorkshire power station procurement that shapes Baltic export flows. The Contracts for Difference scheme supports bioenergy with carbon capture and storage eligibility under emissions trading rules. Scottish pellet distributors leverage deep-water port capacity at Grangemouth for North American import discharge.
Europe Wood Pellet Market Competitive Landscape
On the supply side, the industry is consolidating around integrated pulp conglomerates and specialized biomass converters with captive fiber access. Nordic sawmill residue concentration limits independent producer feedstock leverage. Three archetypes dominate: backward-integrated forest owners, utility-anchored offtake specialists, and regional heating fuel distributors. Capacity expansion and certification compliance constitute the primary competitive vectors as ENplus audit backlogs stretch market entry timelines.
Within the utility-anchored tier, Drax Group plc and Graanul Invest Group occupy positions that exemplify divergent sourcing strategies—UK power station integration versus Estonian-Latvian forest holdings. Stora Enso Oyj represents the integrated pulp-to-pellet archetype controlling fiber quality from Nordic sawmills. These three entities illustrate how supply security and certification depth determine procurement relationships with district heating networks and power utilities seeking long-term offtake certainty.
| Leading Market Players |
|---|
| Drax Group plc |
| Graanul Invest Group |
| Stora Enso Oyj |
| German Pellets GmbH |
| Holzindustrie Schweighofer |
| Scandbio AB |
| Pinnacle Renewable Energy Group |
| Vyborgskaya Cellulose |
| Wood Pellet Energy U.K. |
| Others |
Supply & Pricing Matrix
Overcapacity in Baltic pellet production is compressing spot pricing and forcing Estonian and Latvian suppliers toward long-term offtake contracts with German and Italian utilities. This utilization dynamic rewards backward-integrated forest owners with captive fiber while squeezing independent toll manufacturers on delivered cost.
Pricing Analysis
Certification level creates the primary spread between ENplus A1 residential grades and bulk industrial deliveries. Three-tier pricing structure across premium certified, standard utility, and ungraded spot lots tracks fiber provenance and ash content specifications. Cost compression in standard grades is intensifying because Nordic sawmill residue concentration limits independent producer feedstock leverage. Residential households in France's Massif Central exhibit highest price sensitivity, while UK power utilities under BECCS eligibility show lowest sensitivity due to negative-emission credit stacking.
Supply Chain Analysis
Sawmill residue streams from Estonia, Latvia, and Finland anchor upstream fiber availability for European pellet manufacturing. Production draws from debarked softwood chips, forest thinning harvests, and pulp mill byproduct streams. Single-source vulnerability concentrates in Nordic integrated conglomerates controlling residue allocation. Distribution runs through deep-water Baltic ports for bulk industrial offtake and bagged retail channels via agricultural cooperatives for residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend substitution pressure from air-source heat pumps subsidized under German and French electrification programs.
For Market Incumbents: Insulate core margins by deepening backward integration into Estonian and Latvian forest holdings to secure captive fiber supply. Anchor long-term offtake contracts with Scandinavian district heating operators before ENplus certification backlogs clear and new Baltic entrants achieve compliance. Prioritize burner calibration service bundling to lock in residential replacement cycles. For New Entrants and Emerging Players: Iberian port underpenetration offers white-space access for North American pellet discharge into Italian and French markets bypassing Baltic congestion. Target Portuguese ceramic manufacturers trialing pellet substitution for natural gas kiln operations. Pursue direct procurement relationships with Massif Central agricultural syndicates disintermediating traditional heating oil distributors. For Investors and Strategic Acquirers: Long-term, this sits as a carbon-border arbitrage play because EU Green Deal tightening redirects Baltic flows toward Western European offtakers with premium pricing persistence. Acquire mid-scale producers with ENplus certification progress but stranded without deep-water port access. Monitor German heat pump subsidy renewal decisions as inflection signal for residential pellet demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forest Holdings | Estonian and Latvian timber assets secure fiber supply certainty under EMA sustainability guidelines. |
| ENplus Certification Investment | Third-party audit completion unlocks German and Austrian residential warranty coverage requirements. |
| Long-term Offtake Agreement | UK and Dutch utility procurement under BECCS eligibility creates negative-emission revenue stacking. |
| Iberian Port Capacity Utilization | Spanish and Portuguese deep-water discharge bypasses Baltic supply congestion into Italian markets. |
| Smart-grid Integration Partnership | EU AI Act demand-response protocols enable frequency regulation bidding beyond commodity power sales. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with pellet plant managers, utility procurement officers, district heating operators, and ENplus certification auditors; and secondary validation against EIA biomass statistics, IEA renewable heat reports, EU customs trade data, and EMA sustainability filings. Bottom-up capacity assessments triangulated with top-down demand modeling across residential, commercial, and power generation segments.
Forecast inputs considered fuel switching economics under EU carbon-border adjustments, district heating retrofit timelines, and electrification subsidy competition. Segmentation dimensions modeled include product grade tier, end-use intensity, fiber source provenance, and application function across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating German Building Energy Act compliance mandates and Italian National Recovery and Resilience Plan allocation trajectories.
Practitioners should monitor German heat pump subsidy renewal thresholds and ENplus audit capacity expansion for early signals of residential demand revision. Cross-checking against IEA renewable heat deployment benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Smart Gas Market
Fuels
Underground Coal Gasification Market
Fuels
Coal Gasification Market
Fuels
No.2 Diesel Fuel Market
Fuels
South Africa Bunker Fuel Market
Fuels
Oil Dispensing Stations Market
Fuels
Coal Liquefaction Market
Fuels
Renewable Heating Fuels Market
Fuels
Bituminous Coal Market
Fuels
Europe Renewable Aviation Fuel Market
Fuels
LPG Gas Cylinder Market
Fuels
United Arab Emirates Fuel Station Market
Fuels
China LNG Bunkering Market
Fuels
Collapsible Fuel Tank Market
Fuels
Marine Fuel Optimization Market
Fuels
Aerospace Aviation Fuels Market