
 Tire Derived Fuel Market | 2026-2036
Tire Derived Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Tire Derived Fuel Market Intelligence
Value recovery from end-of-life tires is rewriting the economics of waste management and energy production. Liberty Tire Recycling dominates collection and processing networks across North America, while Ragn-Sells Group leverages its established waste management infrastructure to secure feedstock supply. Scandinavian Enviro Systems AB specializes in advanced pyrolysis technology, creating higher-value outputs from tire waste.
Tire-derived fuel consists of processed scrap tires, typically shredded into uniform pieces with steel and fiber content reduced. It serves as a high-calorific value energy source, often exceeding 13,000 BTUs per pound. Shredded tire formats command the largest market volume due to their compatibility with existing industrial feeders. While cement kilns remain the principal application, the pulp and paper industry represents a key growth area for TDF.
Regulatory frameworks are central to market viability, with the U.S. EPA's rules on non-hazardous secondary materials and the EU's Waste Framework Directive defining TDF's legal status. These policies, alongside China's dual carbon goals, create incentives for industries to substitute fossil fuels. Stakeholders must monitor tightening air emission standards and the policy shift towards higher-value recycling methods over energy recovery.
Market Dynamics
The market is defined by a fundamental tension between its role as a low-cost fossil fuel substitute and mounting regulatory pressure favoring higher-value circular economy outcomes. This dynamic forces stakeholders to navigate between maximizing energy recovery and investing in material recycling technologies.
Growth Catalysts
- Fossil Fuel Substitution Mandates:Demand from energy-intensive sectors, particularly cement manufacturing, is driven by policies like China's dual carbon goals and the EU Green Deal, which incentivize the replacement of coal and petcoke with alternative fuels.
- Waste Management Policy:Landfill diversion mandates and tire disposal regulations across North America and Europe create a consistent, low-cost feedstock supply, making TDF an economically viable waste management solution for end-of-life tires.
- Fuel Specification Advancement:The development of standardized TDF grades with consistent particle size and calorific value improves combustion efficiency and makes it a more reliable fuel source for industrial boilers and kilns.
Market Restraints
- Air Emission Regulations:Tightening standards on emissions, including sulfur oxides, nitrogen oxides, and particulates, enforced by bodies like the U.S. EPA, require significant capital investment in flue-gas treatment systems, increasing the total cost of using TDF.
- Competition from Material Recycling:Government incentives and corporate sustainability goals are increasingly favoring material recovery processes like pyrolysis and devulcanization, which can produce higher-value products like recovered carbon black and oil, diverting feedstock from TDF production.
- Logistical Inefficiencies:The high cost of transporting bulky, low-density shredded tires from processing sites to end-users limits the economically viable radius of supply, creating regional price disparities and supply bottlenecks.
Strategic Opportunities
- Pulp and Paper Industry Penetration:The pulp and paper sector represents a significant growth opportunity, as its industrial boilers are well-suited for co-firing with TDF, offering a new end-market beyond the heavily saturated cement industry.
- Geographic Expansion in Emerging Economies:Markets in Southeast Asia and Latin America with growing industrial bases and nascent waste management regulations offer new frontiers for establishing TDF processing and supply chains.
- Co-processing with Biomass:Combining TDF with biomass in co-firing applications can create a fuel blend with a lower carbon footprint and improved emission profile, aligning with circular economy principles and potentially qualifying for renewable energy credits.
Industry Challenges
- Feedstock Quality Variability:Inconsistent quality of incoming end-of-life tires, including contamination with dirt, water, and non-tire materials, complicates processing and can affect the final fuel characteristics, challenging operational consistency.
- Public and Regulatory Perception:Overcoming the "waste-to-energy" stigma and demonstrating compliance with stringent environmental standards remains a persistent public relations and permitting challenge for TDF facilities and end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tire Derived Fuel Market |
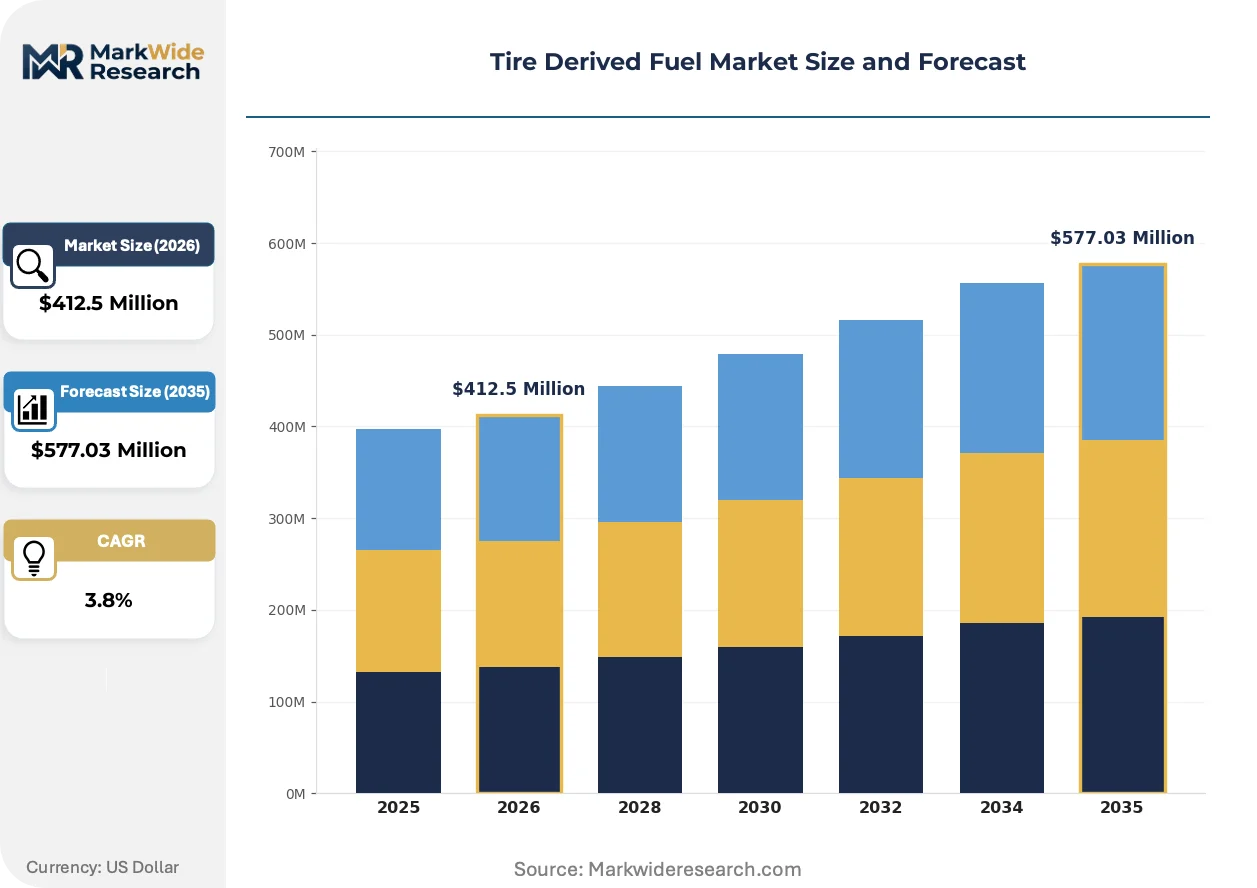
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $577.03 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Tire, Shredded Tire, Tire Chips, Ground Rubber Application: Cement Kilns, Paper Mills, Power Plants, Electric Arc Furnaces, District Heating End User Industry: Cement Manufacturing, Pulp & Paper, Energy Generation, Steel Production Distribution Channel: Direct Sales, Distributors, Online Platforms, Brokers |
| Companies Covered | Ragn-Sells Group, Renelux Cyprus Ltd., Liberty Tire Recycling, Genan Holding A/S, Scandinavian Enviro Systems AB, Lakin Tire, ResourceCo Pty Ltd, Globarket Tire Recycling, Emanuel Tire, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tire Derived Fuel Market Strategic Shifts & Innovations
Technological advancements in processing and a sharpened focus on regulatory compliance are pushing the market toward more refined fuel products. The industry is evolving to meet demands for cleaner combustion and greater material efficiency, positioning TDF as an engineered fuel rather than a simple waste product.
Advanced processing technology is a key focus. This equipment includes sophisticated magnetic and eddy-current separators for near-total metal removal and air classification systems to eliminate textile fibers, creating a purer hydrocarbon product. Cement producers and power plants are the primary adopters, seeking to minimize boiler ash and meet strict emission limits. The market is migrating from selling basic shredded material to supplying engineered, specification-driven fuel pellets and chips.
Regulatory frameworks like the EU's Waste Framework Directive are reshaping the competitive landscape. The directive's waste hierarchy explicitly prioritizes material recycling over energy recovery, placing the onus on TDF producers to prove their environmental benefit compared to landfilling. Industries in countries like Germany and France that use TDF must now invest more heavily in advanced emission control technologies to justify its continued use, impacting their cost structure.
Buying behavior is shifting toward long-term, specification-based supply contracts. This change displaces the traditional spot market purchasing model, favoring large-scale, certified processors who can guarantee consistent fuel quality, reliable volume, and auditable compliance with environmental regulations. This trend is most pronounced in the North American and European cement industries, where fuel stability is critical for kiln operations.
Tire Derived Fuel Market Segmentation
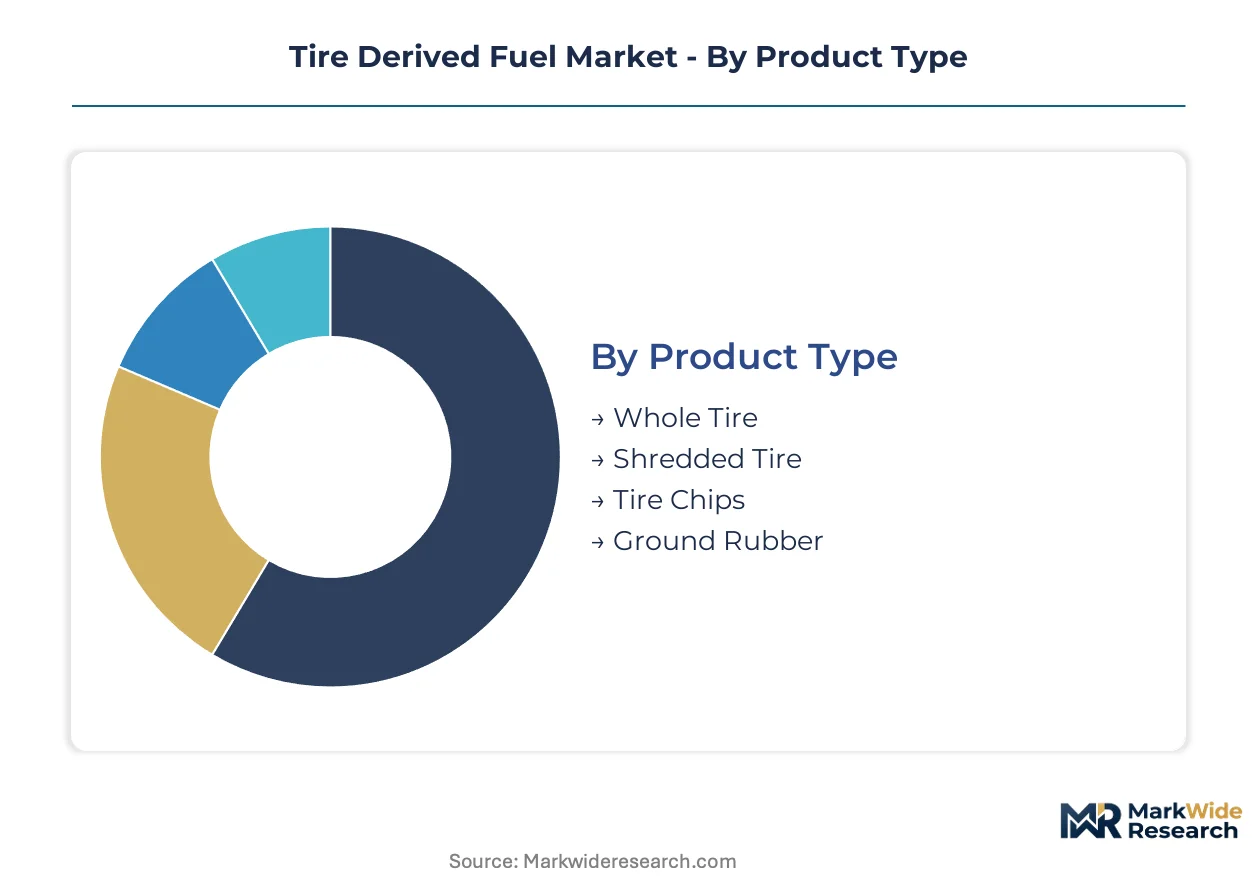
The Tire Derived Fuel market's segmentation provides a granular view of product variations, end-use applications, and supply chain mechanisms. Understanding these distinct categories helps stakeholders identify specific growth pockets and operational efficiencies. This detailed breakdown highlights how different TDF forms cater to varied industrial demands.
Product Type:
The product type segmentation reveals a spectrum of processing maturity, from minimally altered tires to highly refined fuel components.
- Shredded Tire:This form consists of scrap tires mechanically reduced to uniform pieces, with most steel and fiber content removed. Demand concentrates in the North American cement industry, driven by established infrastructure for bulk handling and co-firing.
- Tire Chips:Tire chips are larger, irregularly shaped pieces of tires, often retaining some steel and textile. European power plants increasingly adopt tire chips for their cost-effectiveness as a supplemental fuel, especially under specific emission permits.
- Whole Tire:Whole tires are used as a fuel source primarily in older, less sophisticated industrial boilers, particularly in emerging economies where processing infrastructure is limited.
- Ground Rubber:Ground rubber, while a tire derivative, typically finds applications in asphalt modification or playground surfaces rather than direct fuel, representing a higher-value material recovery path.
Shredded Tire handles the majority of throughput; Tire Chips is the fastest mover on share.
Application:
The application segmentation highlights the diverse industrial sectors leveraging TDF, with varying volume requirements and technical specifications.
- Cement Kilns:These facilities use TDF as a primary or supplementary fuel due to its high calorific value and the ability of the kiln's high temperatures to destroy organic compounds. Demand from the German cement manufacturing sector remains robust, supported by policies encouraging fossil fuel substitution.
- Paper Mills:Industrial boilers in the pulp and paper industry are well-suited for co-firing TDF, offering a reliable energy source for steam generation. The North American pulp and paper sector shows increasing interest as it seeks to reduce reliance on natural gas.
- Power Plants:Large-scale power generation facilities integrate TDF into their fuel mix, often alongside coal, to meet energy demands and manage waste tires, particularly in countries with strong waste-to-energy mandates.
- Electric Arc Furnaces:Steel production using electric arc furnaces can incorporate TDF as a carbon source and fuel, contributing to both energy input and slag formation in a controlled environment.
- District Heating:Urban district heating systems in Europe utilize TDF to generate heat for residential and commercial buildings, aligning with regional circular economy objectives.
Cement Kilns command the largest application volume, while Paper Mills exhibit the steepest expansion trajectory.
End User Industry:
The end user industry segmentation reflects distinct customer types, each with specific operational needs and regulatory compliance requirements for TDF utilization.
- Cement Manufacturing:This industry consumes significant volumes of TDF, benefiting from its high heat content and the ability of cement kilns to neutralize emissions effectively. Chinese cement producers are increasingly adopting TDF to meet national dual carbon goals.
- Pulp & Paper:The pulp and paper sector integrates TDF to reduce operational costs and enhance energy independence, particularly in regions with abundant end-of-life tire supplies.
- Energy Generation:Utilities and independent power producers use TDF to diversify their fuel sources and comply with waste diversion mandates. Facilities in the US leverage TDF for consistent baseload power, supported by EPA guidelines.
- Steel Production:Steel mills employ TDF to supplement traditional fuels, contributing to the energy balance of their operations and managing waste streams.
Cement Manufacturing represents the predominant end-user segment, with Energy Generation showing significant growth in fuel diversification strategies.
Distribution Channel:
The distribution channel segmentation illustrates how TDF feedstock reaches end-users, reflecting varied supply chain concentrations and logistical efficiencies.
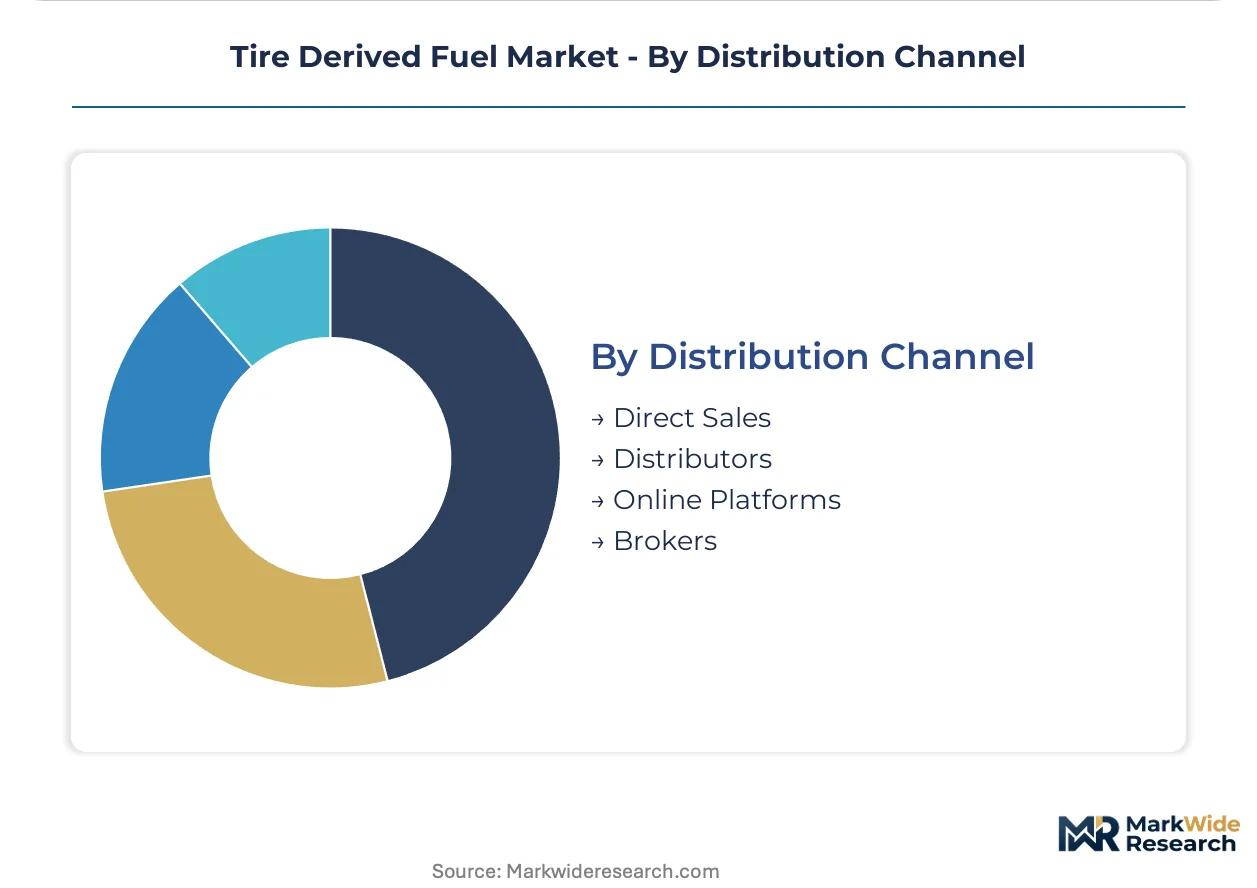
- Direct Sales:Large-volume TDF producers often engage in direct sales with major industrial consumers, facilitating long-term contracts and consistent supply. North American processors prioritize direct relationships with cement manufacturers to ensure steady off-take.
- Distributors:Specialized distributors manage the logistics of TDF, connecting smaller processors with diverse industrial end-users, especially in fragmented regional markets. European distributors play a vital role in aggregating supply for smaller district heating plants.
- Online Platforms:Emerging online platforms facilitate transactions for smaller batches of TDF, connecting buyers and sellers in a more transparent, although less established, marketplace.
- Brokers:Brokers act as intermediaries, matching TDF supply with demand, often handling complex logistical arrangements and compliance requirements for specialized applications.
Direct Sales channels move the majority of TDF volume, while Online Platforms are gaining traction for niche and regional transactions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for tire-derived fuel varies significantly, with some industrial buyers exhibiting high price sensitivity while others prioritize consistent supply and environmental compliance. Emerging economies often seek TDF as a low-cost fossil fuel substitute, contrasting with developed nations where regulatory compliance drives its adoption.
United States
Demand from cement manufacturing drives TDF consumption in the United States. The U.S. EPA's rules on non-hazardous secondary materials define TDF's legal status and use. Industrial clusters in the Great Lakes region leverage TDF for energy recovery in heavy industry.
Germany
European pulp and paper mills seek TDF for steam generation and cost reduction. The EU Green Deal encourages circular economy models for waste tires. German industrial clusters, particularly in North Rhine-Westphalia, show concentrated TDF consumption.
China
Cement producers in China increasingly adopt TDF to meet energy demands. China's dual carbon goals incentivize the replacement of fossil fuels. Industrial zones around the Yangtze River Delta utilize TDF in energy-intensive processes.
India
Growing industrial bases in India require alternative fuels for energy security. The country's waste management policies are evolving to address tire disposal. Cement plants in Rajasthan and Gujarat are exploring TDF as a supplementary fuel source.
Brazil
Latin American industrial sectors are exploring TDF for cost-effective energy. Brazil's national environmental regulations guide waste tire management. Industrial facilities in São Paulo state integrate TDF into their energy mix.
Tire Derived Fuel Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a tiered market structure. This market features large-scale processors, specialized technology providers, and regional waste management entities. Dominant competitive moves include geographic expansion into emerging economies and strategic investments in advanced processing technologies.
Within the large-scale processing and recycling tier, Liberty Tire Recycling exemplifies extensive collection and processing networks across North America. Ragn-Sells Group, a European waste management entity, leverages its established infrastructure to secure feedstock supply. Scandinavian Enviro Systems AB represents a specialized technology provider, focusing on advanced pyrolysis for higher-value outputs from tire waste.
| Leading Market Players |
|---|
| Ragn-Sells Group |
| Renelux Cyprus Ltd. |
| Liberty Tire Recycling |
| Genan Holding A/S |
| Scandinavian Enviro Systems AB |
| Lakin Tire |
| ResourceCo Pty Ltd |
| Globarket Tire Recycling |
| Emanuel Tire |
| Others |
Cost & Logistics Intelligence
Commodity volatility in raw material rubber and steel scrap determines both pricing tier spreads for TDF and the supply chain shape for tire collection. This volatility influences processor margins and end-user fuel costs.
Pricing Analysis
Engineered, high-specification TDF products drive lifetime value for industrial consumers, ensuring consistent energy output and reduced maintenance. Pricing for TDF follows a contract-based long-term offtake model, prioritizing consistent supply over spot market fluctuations. Price differentiation stems from fuel specification consistency and geographic delivery costs. Pricing pressure stems from competition with lower-cost fossil fuels. Cement manufacturers are price-sensitive, while specialized power plants prioritize fuel reliability.
Supply Chain Analysis
Logistical inefficiencies due to high transportation costs dominate the TDF supply chain, creating regional price disparities. Supply concentrates in North America, particularly the US, and Europe, with Germany being a key hub. Raw material dependencies include end-of-life tires from automotive and heavy vehicle sectors. Commodity price volatility for competing fuels represents a structural risk. Distribution runs through direct sales channels for large industrial consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Tire Derived Fuel market reflects a buyer-power shift, driven by increasing consolidation among large industrial consumers like cement manufacturers. This consolidation enables larger, more demanding supply contracts, influencing market dynamics.
For Market Incumbents:
Insulate core TDF supply by securing long-term contracts with cement and pulp & paper industries. Invest in advanced processing technology to meet tightening air emission standards, mitigating regulatory shift threats. Deepen vertical integration into tire collection networks to control feedstock quality and supply. This strategy protects against feedstock quality variability and competition from higher-value material recycling.
For New Entrants and Emerging Players:
Geographic underpenetration in Southeast Asia and Latin America offers significant white-space opportunities for TDF production. Target the nascent industrial bases in these regions, particularly for power generation and cement manufacturing, which seek alternative fuels. A go-to-market angle involves offering integrated waste management and energy solutions, leveraging local waste tire streams.
For Investors and Strategic Acquirers:
The EU Green Deal reshapes the acquisition landscape, favoring TDF providers with strong environmental compliance records and advanced processing capabilities. Long-term viability hinges on companies that can demonstrate a clear pathway to higher-value recycling alongside energy recovery. Target mid-sized processors specializing in pyrolysis or co-processing technologies. Watch for increasing incentives for circular economy solutions as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Pyrolysis Technology | Converts end-of-life tires into higher-value oils and carbon black, aligning with circular economy goals. |
| Establish Long-Term Offtake Agreements | Secures consistent demand and revenue streams from major industrial consumers like cement kilns. |
| Expand Processing Capacity in Emerging Markets | Captures new demand from growing industrial bases in regions like Southeast Asia. |
| Develop TDF-Biomass Co-firing Solutions | Creates a lower-carbon fuel blend, improving emission profiles for industrial boilers. |
| Secure Certifications for Engineered Fuel Pellets | Guarantees consistent quality and compliance, attracting premium buyers in regulated markets. |
Research Approach
Desk research of industry reports, government publications, and academic studies preceded structured interviews with TDF producers, industrial end-users, waste management executives, and environmental regulators. This analysis combined primary insights with secondary validation, employing both bottom-up and top-down triangulation. This approach ensured a comprehensive understanding of market dynamics and supply chain intricacies.
Assumptions on regulatory stability and technological adoption were held fixed, while feedstock availability and industrial demand varied across the analysis window. The analytical framework modeled segmentation dimensions including product type, application, end-user industry, and regional consumption patterns. Compound annual growth rates were derived from historical data and projected shifts in industrial fuel consumption. Key forecast inputs included cement production forecasts and waste tire generation rates.
Practitioners should monitor significant shifts in emission regulations and material recycling incentives for early signals of market redirection. Forecasts reflect current market conditions and known policy trajectories. Material shifts in waste management policy or advanced recycling technology adoption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Gas Hydrates Market
Fuels
LPG Tanker Market
Fuels
India Petrol Station Market
Fuels
Emulsified Fuel Market
Fuels
South America Bunker Fuel Market
Fuels
Oil & Gas Lubricants Market
Fuels
North America Oil and Gas Lubricants Market
Fuels
Brazil Bunker Fuel Market
Fuels
Coal Briquette Box Market
Fuels
No.4 Fuel Oil Market
Fuels
Fuel Quality Testing Market
Fuels
China LNG Market
Fuels
Middle-East and Africa Defense Aircraft Aviation Fuel Market
Fuels
High Octane Racing Fuel Market
Fuels
Compressed Natural Gas (CNG) Dispenser Market
Fuels
Pyrolysis Gas Market