
 Asia-Pacific Coal Market | 2026-2036
Asia-Pacific Coal Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Coal Market Outlook
Aftermarket service revenue around coal handling and preparation plant optimization is rewriting profit expectations across the value chain. China Shenhua Energy Co. Ltd leverages its integrated rail-port-power infrastructure to sustain delivered cost advantages. Coal India Limited anchors domestic supply security through its monopoly over proven reserves in Jharkhand and Odisha. Adaro Energy Indonesia competes on low-sulfur, sub-bituminous export grades to Northeast Asian power buyers.
Asia-Pacific coal encompasses carbon-rich sedimentary rock with calorific values ranging from sub-bituminous grades below 19 MJ/kg to premium metallurgical variants exceeding 30 MJ/kg, extracted through open-cut and underground longwall methods for combustion and reduction processes. Thermal coal dominates volume flows to power plants across the region, while metallurgical grades command premium pricing from steel industry buyers in Japan and South Korea. Direct sales channels from mine mouth to captive generators capture margin pools that distributor networks cannot replicate, particularly for high calorific consignments under annual offtake contracts.
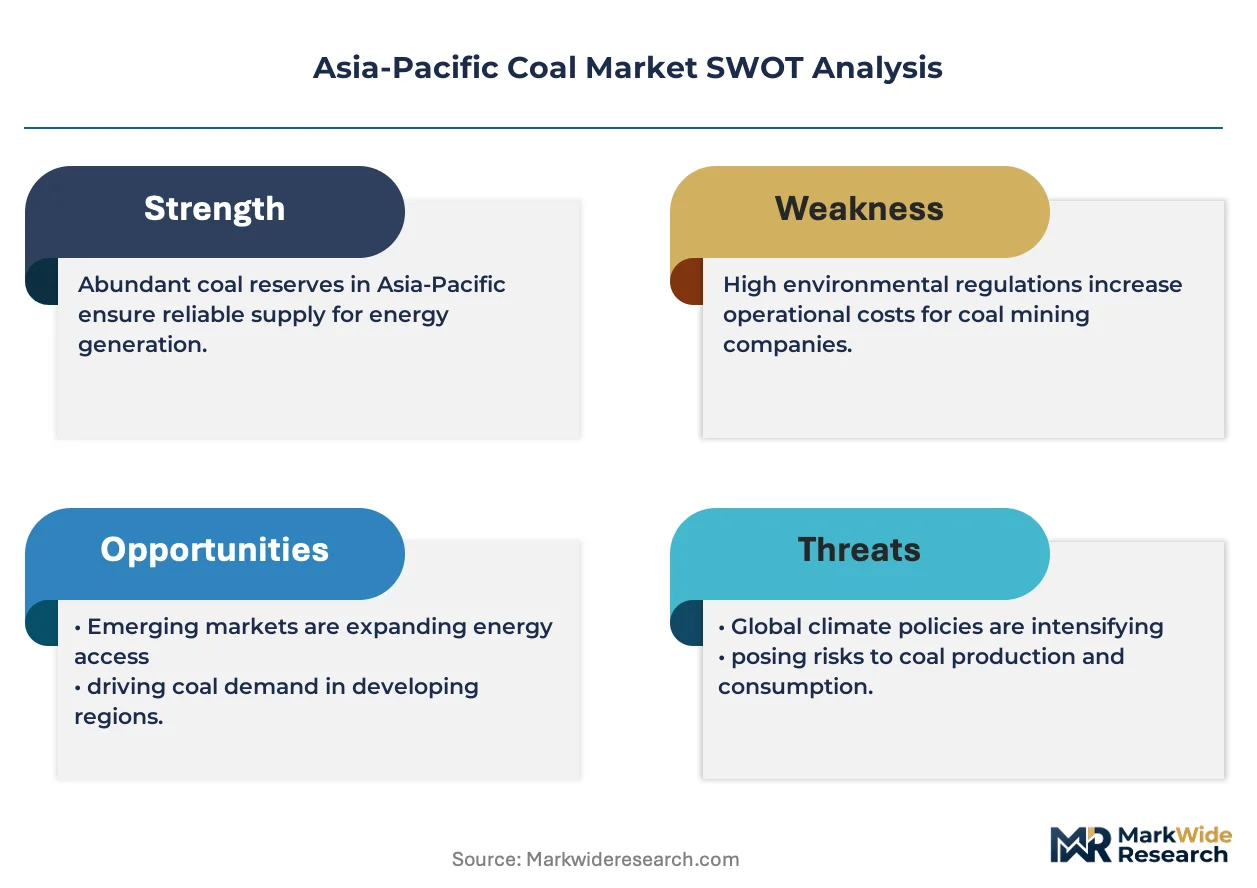
China's MEE enforces emission intensity benchmarks that constrain new mine approvals, while India's CEA mandates flue-gas desulfurization retrofits at existing thermal stations. Indonesia's MEMR regulates export licensing and domestic market obligation quotas that split production between overseas revenue and local power security. Stakeholders must track how carbon border adjustment mechanisms in destination markets reshape competitiveness of unabated coal exports from the region.
Market Dynamics
China's dual carbon goals and India's PLI scheme for clean coal technologies are redirecting capital flows across the Asia-Pacific coal value chain, compressing investment timelines for conventional extraction while accelerating funding toward emission-abated combustion systems.
Growth Catalysts
- Power utility procurement:Thermal coal offtake by state-owned generators in Indonesia and Vietnam sustains volume demand through long-term supply agreements.
- CEA flue-gas mandates:India's Central Electricity Authority requires desulfurization retrofits at existing thermal stations, creating equipment upgrade cycles.
- Bowen Basin infrastructure:Queensland's rail-port corridors enable premium metallurgical coal exports to Northeast Asian steelmakers.
Market Restraints
- MEE emission benchmarks:China's Ministry of Ecology and Environment constrains new mine approvals through intensity thresholds.
- Export licensing quotas:Indonesia's MEMR splits production between domestic market obligations and overseas revenue.
- Renewable substitution:Utility-scale solar and battery storage displace baseload coal dispatch in Australian and Vietnamese grids.
Strategic Opportunities
- Jharkhand coalfield modernization:Mechanized longwall deployment in eastern India unlocks stranded reserves.
- Carbon capture integration:Post-combustion amine scrubbing at ultra-supercritical plants creates low-carbon coal pathways.
- MEMR regulatory tailwinds:Indonesia's domestic market obligation enforcement secures captive supply for local power security.
Industry Challenges
- Longwall automation skills:Shortage of certified operators for remote-controlled shearer systems constrains productivity gains in Australian underground operations.
- FGD retrofit capex:Flue-gas desulfurization installation at legacy Indian thermal stations requires capital allocation competing with renewable buildouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Coal Market |
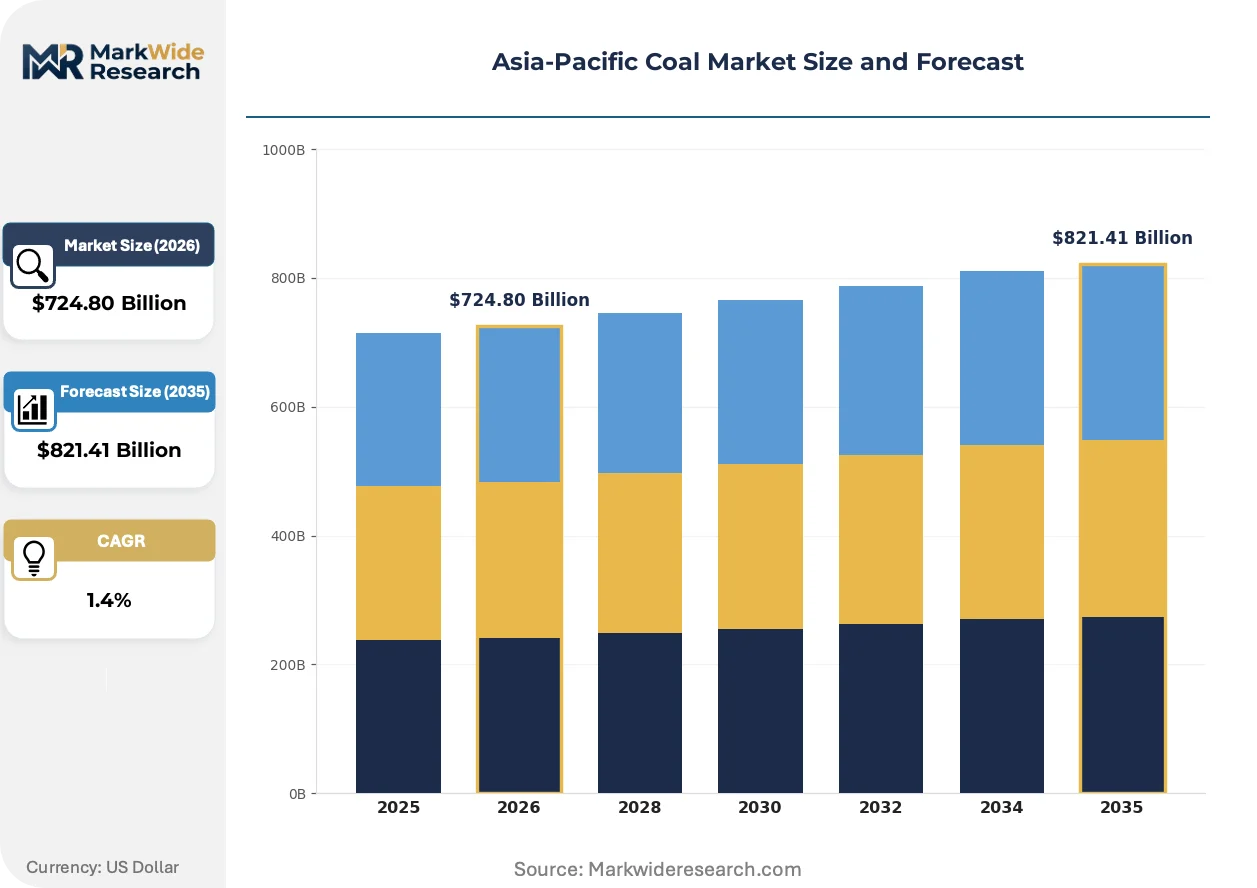
| Market Size in 2026 | $724.80 Billion |
| Market Size in 2035 | $821.41 Billion |
| CAGR (2026 – 2036) | 1.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal, Metallurgical, Anthracite, Lignite End User: Power Plants, Cement Manufacturers, Steel Industry, Chemical Producers Sales Channel: Direct Sales, Distributors, Exports, Brokers Grade: High Calorific, Low Calorific, Coking, Others |
| Companies Covered | China Shenhua Energy Co. Ltd, China Coal Energy Group Co., Ltd., Coal India Limited, NTPC Ltd, Jindal Steel & Power Ltd, Adaro Energy Indonesia, PT Bukit Asam, Bayan Resources, Huadian Power International Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Coal Market Strategic Shifts
Coal handling and preparation plant optimization is rewriting operational economics across the Asia-Pacific value chain, with digital instrumentation and automated beneficiation reshaping how producers extract margin from declining seam qualities.
Ultra-supercritical steam cycles is hybridizing thermal efficiency benchmarks in the Asia-Pacific coal fleet. Japanese power utilities deploy 600°C-plus steam conditions at newbuild plants. This technology is compressing heat-rate differentials between coal and combined-cycle gas generation.
China's MEE enforces emission intensity benchmarks that constrain new mine approvals through carbon-per-ton thresholds. The policy compresses permitting timelines for low-methane, high-efficiency operations. Producers in Shanxi and Inner Mongolia respond by accelerating methane capture and ventilation optimization.
Annual offtake contracting is displacing spot market exposure for premium metallurgical consignments. Northeast Asian steelmakers in Japan and South Korea lock in multi-year supply agreements directly with Queensland and New South Wales exporters. This pattern concentrates procurement leverage with integrated blast furnace operators.
Asia-Pacific Coal Market Segmentation
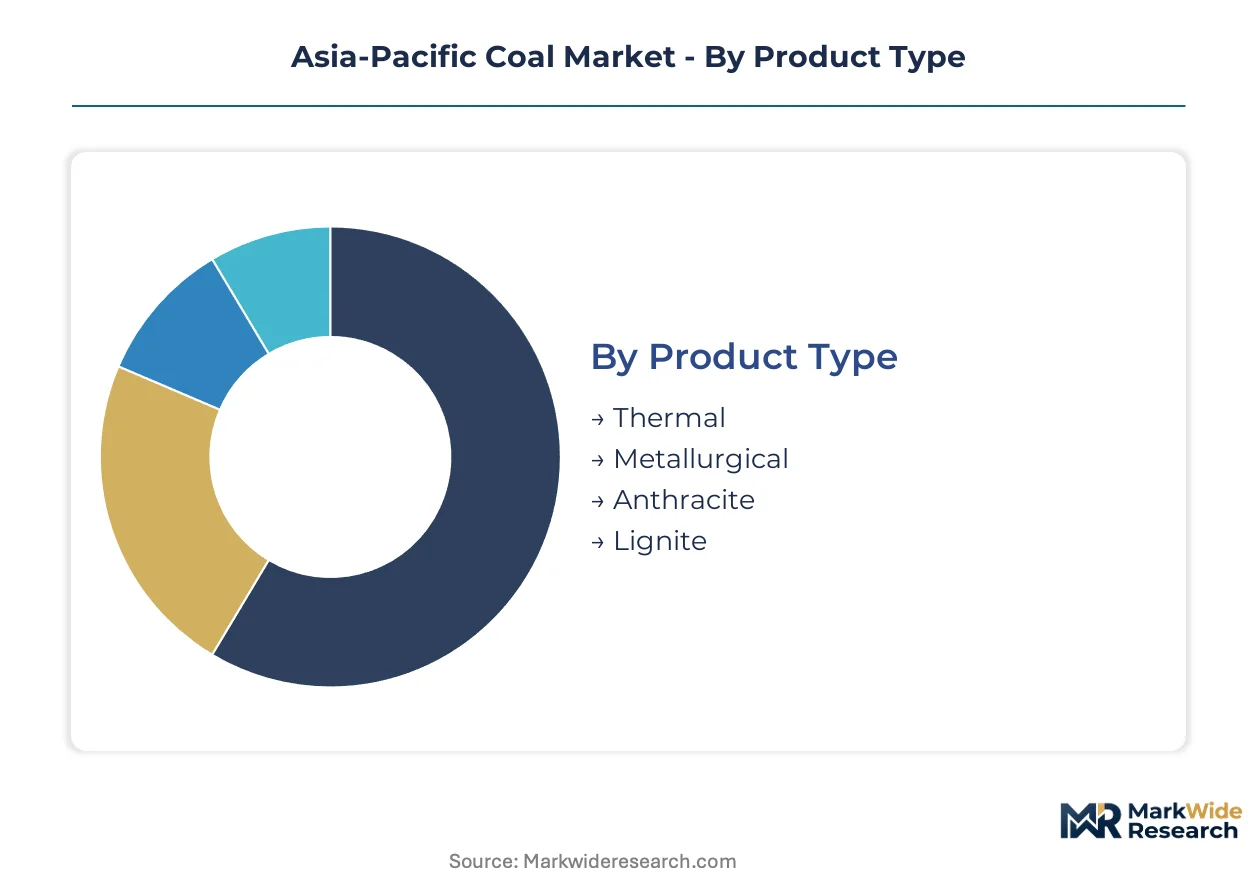
Segmentation in the Asia-Pacific coal market exposes how calorific specifications, combustion requirements, and procurement channels fragment pricing power. Producers optimize plant configurations and logistics investments differently across each slice, with aftermarket service intensity varying sharply by product type and end-use concentration.
Product Type:
After-sales service intensity peaks around coal handling and preparation plant optimization, with thermal and metallurgical grades demanding divergent technical support ecosystems.
- Thermal:Sub-bituminous and bituminous grades with calorific values between 19-27 MJ/kg, combusted primarily for electricity generation. Demand concentrates in Indonesia's mine-mouth power corridors and Vietnam's coastal import terminals, where state-owned generators lock in annual offtake volumes under long-term supply agreements.
- Metallurgical:Premium coking coal with volatile matter below 22% and low phosphorus content, essential for blast furnace reduction. Japanese and South Korean steelmakers in the Keihin and Pohang industrial belts command premium pricing through direct procurement from Queensland's Bowen Basin exporters, with quality consistency driving contract renewals.
- Anthracite:Highest-rank coal with carbon content exceeding 90%, burned for residential heating and specialty metallurgical applications in northern China and South Korea.
- Lignite:Low-rank brown coal with moisture content above 35%, exploited for mine-mouth power generation in Victoria's Latrobe Valley and India's Neyveli basin.
By volume, thermal leads. By growth pace, metallurgical is ahead.
End User:
Customer concentration patterns split procurement leverage between captive mine-mouth arrangements and import-dependent coastal buyers.
- Power Plants:Ultra-supercritical and subcritical thermal stations consuming 80% of regional coal volume. State-owned generators in Indonesia's Java-Bali grid and India's National Thermal Power Corporation anchor demand through 25-year fuel supply agreements.
- Steel Industry:Integrated blast furnace operators and direct reduced iron facilities requiring low-ash, low-sulfur coking coal. Posco's Gwangyang complex and Nippon Steel's East Nippon Works source premium metallurgical consignments through direct Queensland contracts.
- Cement Manufacturers:Rotary kiln operators blending coal with alternative fuels in China's Shandong province and Vietnam's Hon Chong district.
- Chemical Producers:Coal-to-olefins and syngas facilities in China's Ningxia and Inner Mongolia converting low-rank coal into petrochemical feedstocks.
Power plants dominate tonnage. Chemical producers show the steepest expansion trajectory.
Sales Channel:
Channel economics hinge on whether buyers capture margin through direct mine-mouth access or absorb distributor markups for fragmented deliveries.
- Direct Sales:Mine-to-plant contracts eliminating intermediary margins. Coal India Limited supplies Jharkhand and Odisha power stations through dedicated MCL and SECL rail corridors.
- Exports:Seaborne trade through Queensland's Dalrymple Bay and Newcastle's Kooragang terminals serving Northeast Asian steelmakers and Southeast Asian power utilities.
- Distributors:Regional stockists aggregating small-lot deliveries to industrial boilers and brick kilns across India's secondary cities.
- Brokers:Intermediaries facilitating spot market liquidity for speculative arbitrage between Indonesian producers and Chinese import quotas.
Direct sales capture volume leadership. Export channels are climbing fastest.
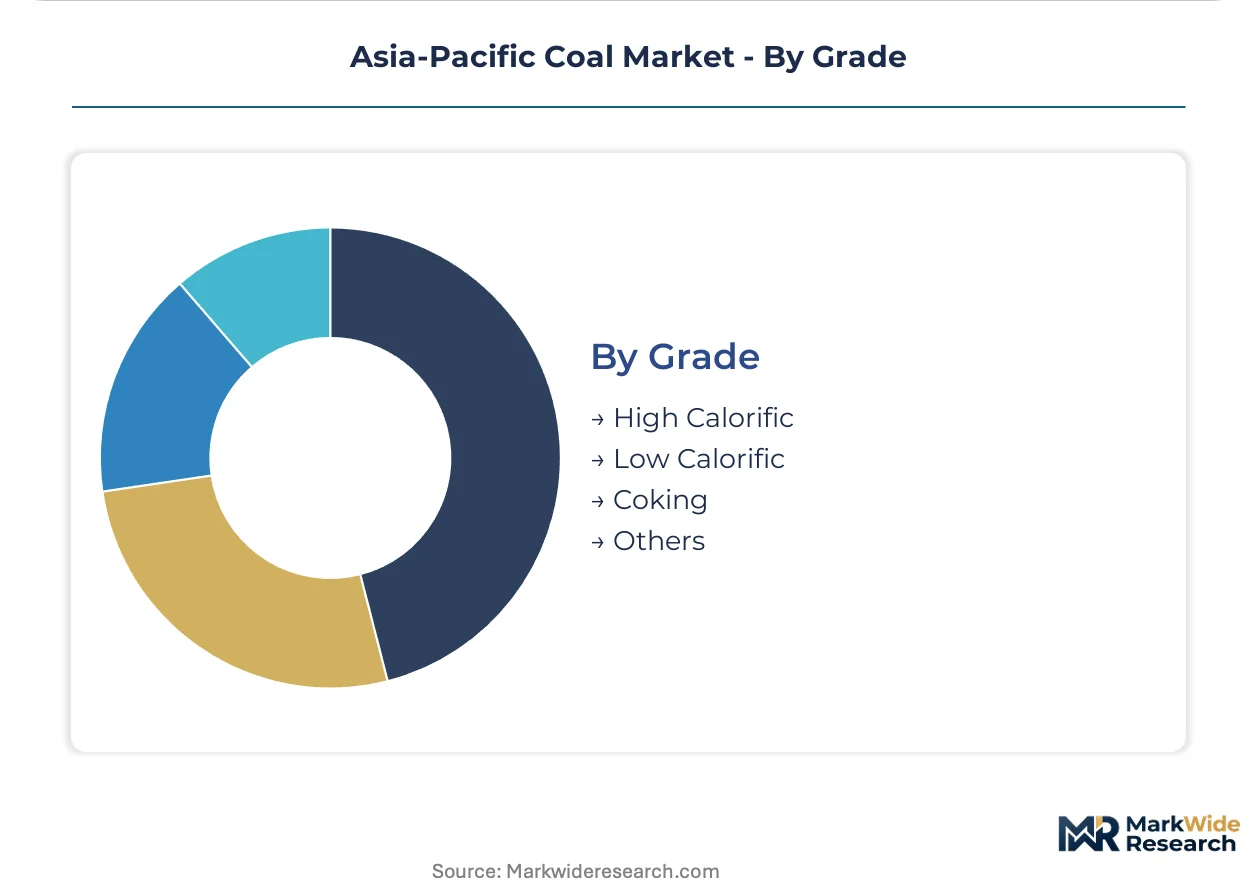
Grade:
Calorific differentiation stratifies pricing tiers, with premium grades commanding scarcity rents from quality-constrained end-users.
- High Calorific:Bituminous coal exceeding 24 MJ/kg, favored by Japanese power utilities for efficiency optimization and coastal plants with limited coal yard capacity.
- Coking:Metallurgical grade with specific caking properties, G-index above 80, and volatile matter between 18-28%, indispensable for coke oven battery operations.
- Low Calorific:Sub-bituminous and lignite grades below 21 MJ/kg, economically viable only at mine-mouth locations with negligible transport costs.
- Others:Blended and beneficiated products meeting custom specifications for industrial boilers and circulating fluidized bed combustion systems.
High calorific grades lead by revenue per ton. Coking grades gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across the Asia-Pacific coal market. Vietnamese and Indonesian power utilities exhibit the highest price sensitivity due to import dependence and currency volatility. Japanese steelmakers show the lowest elasticity, prioritizing metallurgical consistency over cost optimization.
China
Shanxi and Inner Mongolia basins supply roughly two-thirds of domestic thermal coal consumption. The MEE enforces carbon-per-ton emission intensity thresholds that constrain permitting for new underground operations. Producers in Datong and Ordos accelerate methane capture systems to meet these benchmarks.
India
Jharkhand and Odisha coalfields anchor national supply security through the Mahanadi and Damodar valley corridors. The CEA mandates flue-gas desulfurization retrofits at legacy NTPC stations by 2026. Singrauli and Korba industrial clusters absorb the bulk of Coal India Limited's dispatches to captive power units.
Indonesia
Kalimantan and Sumatra export corridors dominate seaborne thermal coal flows to Vietnam and the Philippines. The MEMR regulates domestic market obligation quotas requiring 25% of production for local power security. East Kalimantan's Kutai basin concentrates low-sulfur sub-bituminous output for Northeast Asian buyers.
Australia
Queensland's Bowen Basin and New South Wales' Hunter Valley anchor premium metallurgical coal exports. State environmental regulators impose progressive rehabilitation bonds on open-cut operations. Gladstone and Newcastle port terminals handle the majority of coking coal shipments to Posco and Nippon Steel.
Vietnam
Quang Ninh province's anthracite reserves and coastal import terminals at Cam Pha sustain thermal power expansion. EVN's long-term supply agreements with Indonesian producers lock in base-load fuel security. The Red River Delta industrial corridor drives cement and steel sector coal consumption growth.
Asia-Pacific Coal Market Competitive Environment
Capability concentration sits with integrated rail-port-power operators; scale advantage sits with state-owned reserve holders. The market structures around three tiers: national champions controlling domestic basins, export-oriented miners with seaborne logistics, and captive generators with mine-mouth access. Strategic moves center on infrastructure ownership consolidation and clean technology licensing for emission-abated combustion systems.
Within the national champion tier, China Shenhua Energy Co. Ltd and Coal India Limited exemplify integrated resource-to-power models. Adaro Energy Indonesia occupies a position among export-specialized operators with Kalimantan basin concentration. These anchors illustrate how geographic endowment and regulatory relationships determine competitive positioning across procurement channels.
| Leading Market Players |
|---|
| China Shenhua Energy Co. Ltd |
| China Coal Energy Group Co., Ltd. |
| Coal India Limited |
| NTPC Ltd |
| Jindal Steel & Power Ltd |
| Adaro Energy Indonesia |
| PT Bukit Asam |
| Bayan Resources |
| Huadian Power International Corporation |
| Others |
Value Chain & Pricing Dynamics
Queensland's Dalrymple Bay rail-port corridor compresses delivered cost differentials between Bowen Basin exporters and Northeast Asian steelmakers, concentrating pricing power with integrated operators while fragmenting margins for distributor-dependent buyers. This logistics chokepoint amplifies calorific quality premiums and shapes contract structures across the Asia-Pacific thermal and metallurgical coal tiers.
Pricing Analysis
Aftermarket service revenue around coal handling and preparation plant optimization drives lifetime value capture, with annual offtake contracting dominating premium metallurgical consignments to Japanese and South Korean steelmakers. Price differentiation rests on calorific grade consistency and FGD retrofit bundling for Indian power utilities. Cost compression in sub-bituminous export tiers intensifies because Indonesian MEMR domestic market obligations divert volume from seaborne revenue. State-owned generators in Vietnam exhibit highest price sensitivity due to currency volatility, while integrated blast furnace operators in Japan show lowest elasticity.
Supply Chain Analysis
Upstream coal seam quality and overburden ratios in Australia's Bowen Basin, Indonesia's Kutai basin, and India's Jharkhand coalfields anchor regional supply concentration. Mining operations draw from diesel fuel, explosives, and tire inputs vulnerable to commodity price swings. Single-source vulnerability concentrates around Queensland rail-port infrastructure serving Northeast Asian metallurgical demand. Distribution runs through mine-mouth direct sales for captive Indian power stations and seaborne export terminals for Indonesian thermal grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific coal market fragmentation creates niche opportunities as emission-abated combustion mandates split procurement between ultra-supercritical newbuilds and legacy retrofit cycles. China's dual carbon goals and India's PLI scheme for clean coal technologies redirect capital toward differentiated technology tiers.
For Market Incumbents: Insulate core basin positions through methane capture infrastructure investments in Shanxi and Ordos to satisfy MEE emission intensity benchmarks. Secure rail-port capacity allocation at Dalrymple Bay and Newcastle against renewable substitution threats in Australian grids. Prioritize flue-gas desulfurization licensing partnerships for Indian CEA compliance cycles.
For New Entrants and Emerging Players: Build out mechanized longwall service capabilities targeting Jharkhand coalfield modernization where Coal India Limited faces automation skills gaps. Target carbon capture integration projects at ultra-supercritical plants in China and India as the most penetrable technology tier. Pursue joint development agreements with state-owned generators seeking emission-abated pathways without stranded asset exposure.
For Investors and Strategic Acquirers: Export-specialized miners with Kalimantan basin concentration and locked-in Northeast Asian offtake contracts represent the most defensible acquisition archetype. Long-term viability hinges on successful navigation of carbon border adjustment mechanisms in destination markets. Watch for Indonesia MEMR export licensing quota tightening as the inflection signal for seaborne thermal coal supply availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Longwall Mechanization Deployment | Unlocks stranded reserves in eastern India's Damodar valley corridors against labor productivity constraints. |
| Carbon Capture Integration | Creates low-carbon coal pathways at ultra-supercritical plants serving China's dual carbon compliance. |
| FGD Retrofit Partnerships | Captures equipment upgrade cycles from India's CEA mandates at legacy NTPC thermal stations. |
| Rail-Port Capacity Lock-In | Secures export logistics at Dalrymple Bay against Queensland regulatory rehabilitation bond requirements. |
| Domestic Market Obligation Compliance | Aligns Indonesian production quotas with MEMR enforcement for local power security priority. |
Study Parameters
A standing panel of mine operations managers, utility fuel procurement officers, EPC contractors, and MEMR regulatory specialists provided ongoing calibration against secondary validation from customs trade data, IEA coal market reports, FERC filings, and SEC 10-K disclosures. Bottom-up reserve-to-production modeling triangulated with top-down demand aggregation from national electricity authority forecasts.
Scenario-bracketing around emission intensity compliance trajectories, renewable substitution rates, and carbon border adjustment implementation shaped projections across the analysis window. Segmentation dimensions spanned calorific grade tier, end-use concentration, sales channel structure, and regional regulatory framework. CAGRs derived from production cost curve shifts and offtake contract renewal patterns, with inputs from methane capture technology deployment and flue-gas desulfurization retrofit pipelines.
Stress conditions across Indonesian MEMR quota enforcement, Indian CEA retrofit deadlines, and Chinese MEE permitting thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about technology cost curves and policy implementation timelines. Cross-checking against IEA World Energy Outlook benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
City Gas Distribution Market
Fuels
Australia Coal Market
Fuels
South America Commercial Aircraft Aviation Fuel Market
Fuels
Fuel Analyzer Market
Fuels
Global Methane Hydrate Market
Fuels
Renewable Heating Fuels Market
Fuels
LPG Vaporizer Market
Fuels
Oil Dispensing Stations Market
Fuels
Canada Coal Market
Fuels
Composite Overwrapped Pressure Vessels (Copvs) Market
Fuels
Middle-East and Africa Commercial Aircraft Aviation Fuel Market
Fuels
White Coal Market
Fuels
Fuel Conditioning System Market
Fuels
LPG Gas Cylinder Market
Fuels
Alcohol-To-Jet (ATJ) Fuel Market
Fuels
Aboveground Fuel Storage Market