
 Growlers Market | 2026-2036
Growlers Market Size, Share, and Industry Trends Forecast 2026-2036
Growlers Market Analysis
Germany is fragmenting as new stainless steel fabricators enter the growler supply base alongside established glass producers. Ardagh Group leverages its European glassmaking footprint to serve brewery clients with custom-decorated formats. Berlin Packaging sustains North American distribution density through its multi-material sourcing platform. YETI differentiates via premium thermal insulation technology aimed at outdoor recreation channels.
A growler is a sealed vessel, typically holding 64 fluid ounces, designed to transport draft beverages from production or retail points to end consumers while preserving carbonation and freshness. Glass growlers remain the volume standard due to cost parity and brewery branding compatibility, though stainless steel variants command margin premiums through vacuum-insulated double-wall construction. The 64 oz size anchors commercial throughput for brewery taproom operations, while 32 oz formats gain traction among home users seeking portion flexibility. Swing top closures dominate European refill networks for their reusable gasket systems, whereas screw cap designs prevail in North American retail channels for tamper-evident security.
FDA food-contact substance regulations govern interior coatings and seal materials for growlers distributed in the United States, while EU REACH compliance constrains chemical composition across European imports. Germany's national packaging ordinance and state-level deposit frameworks create divergent compliance obligations for cross-border suppliers. Stakeholders must monitor evolving extended producer responsibility schemes and material-specific recycling quotas that will determine which substrate categories retain cost advantages in key markets.
Market Dynamics
Refillable container mandates across multiple jurisdictions are forcing substrate substitution decisions as breweries weigh glass durability against stainless steel portability in their packaging portfolios.
Growth Catalysts
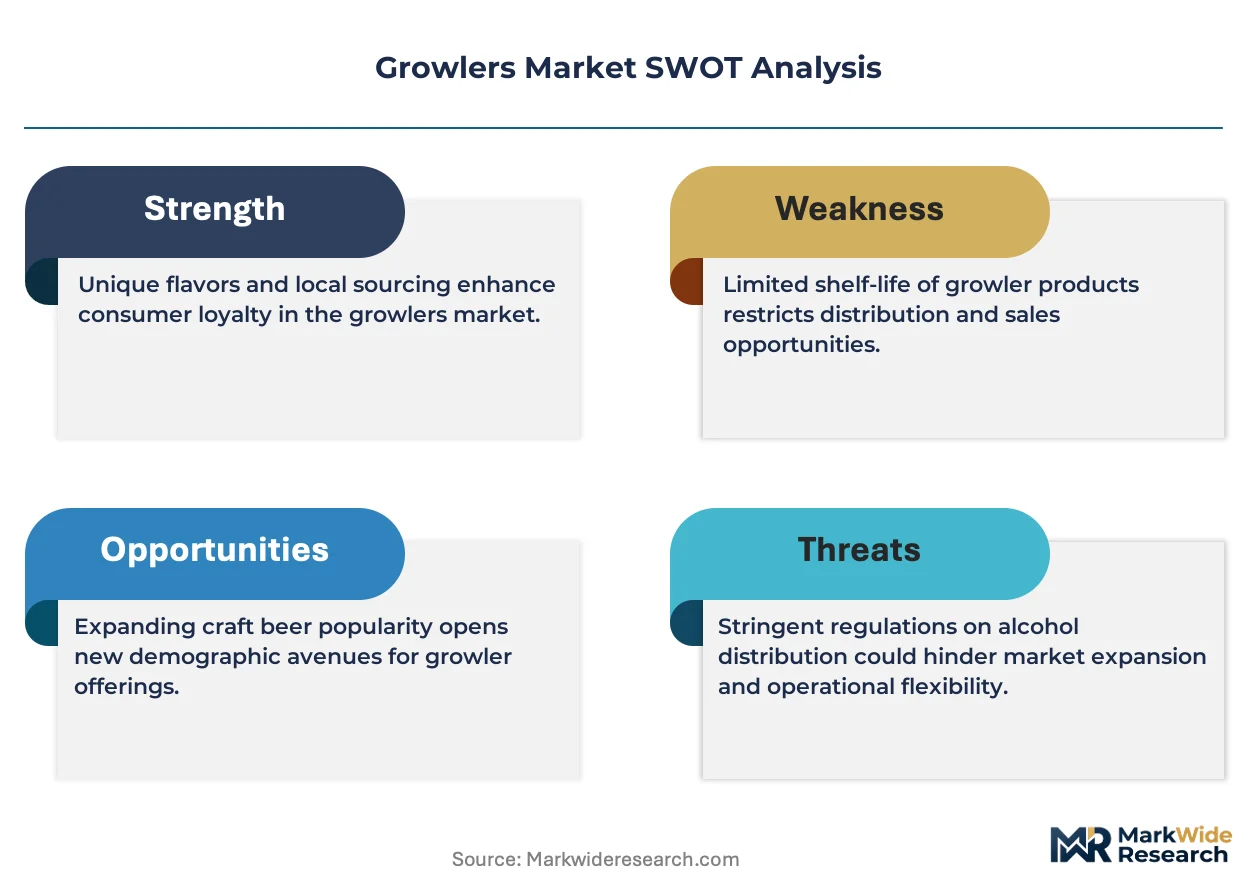
- Extended Producer Responsibility schemes:EU packaging waste directives incentivize breweries to adopt durable formats with higher reuse cycles, directly benefiting stainless steel and thick-walled glass variants.
- Craft brewery taproom density:Urban clusters in Oregon and Washington state generate concentrated demand for branded 64 oz vessels as direct-to-consumer retail channels expand.
- Vacuum insulation technology:Double-wall construction methods preserve carbonation for 24-plus hours, enabling outdoor recreation use cases previously inaccessible to conventional glass formats.
Market Restraints
- Energy cost volatility:Natural gas prices govern borosilicate glass melting furnace economics, compressing margins for European fabricators dependent on continental pipeline supply.
- Deposit system fragmentation:Germany's state-level Pfand variations create compliance complexity for cross-border suppliers shipping into Bavaria versus Berlin-Brandenburg markets.
- Single-use aluminum crowler substitution:Seamless aluminum cans with integrated lids displace glass growlers in brewery to-go operations prioritizing weight reduction and shipping durability.
Strategic Opportunities
- India craft beer emergence:Mumbai and Bangalore microbrewery licensing reforms open untapped demand for imported stainless steel formats as domestic glass supply remains nascent.
- Smart vessel integration:NFC-enabled caps paired with brewery loyalty apps create subscription refill models linking physical container to digital customer identity.
- US state-level refillable container incentives:Oregon's Bottle Bill expansions and California's reusable packaging tax credits reduce total cost of ownership for multi-use formats versus single-use alternatives.
Industry Challenges
- FDA food-contact notification timelines:New interior coating chemistries require 120-day pre-market review cycles, delaying stainless steel product launches for seasonal brewery releases.
- Multi-material recycling infrastructure gaps:Mixed substrate growlers with plastic handles, metal caps, and glass bodies face sortation complexity at municipal materials recovery facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Growlers Market |
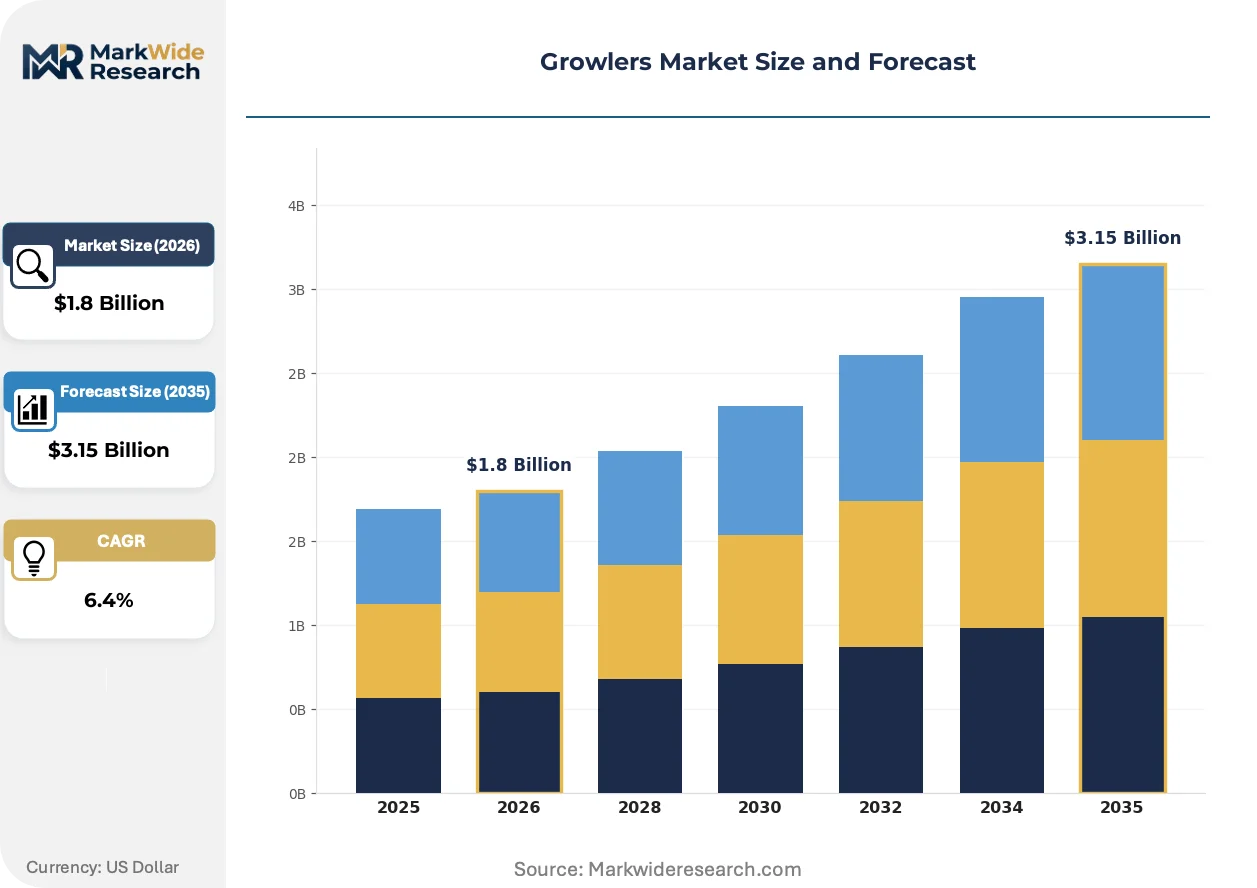
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Stainless Steel, Plastic, Ceramic Size: 32 oz, 64 oz, 128 oz, Others Closure Type: Screw Cap, Swing Top, Flip Top, Others End User: Breweries, Restaurants, Retailers, Home Users |
| Companies Covered | Ardagh Group, Berlin Packaging, Boelter, Croxsons, DrinkTanks, Evans Manufacturing, Global Glass Solutions, GrowlerWerks, YETI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Growlers Market Emerging Trajectories
Material science advances and regulatory pressure on single-use packaging are converging to reshape vessel construction methods and distribution economics across brewery supply chains.
Ceramic-lined stainless steel is hybridizing thermal performance with flavor neutrality previously exclusive to glass. Pacific Northwest craft breweries are piloting these vessels for sour and barrel-aged beer categories where metallic taste transfer posed adoption barriers. The technology is hybridizing price positioning between premium vacuum-insulated steel and mid-tier glass, compressing the traditional three-tier substrate hierarchy.
EU REACH chemical restriction expansions are constraining seal gasket compositions across imported growler shipments. ECHA substance of very high concern listings now cover several phthalate plasticizers common in swing-top closures, forcing reformulation toward silicone alternatives. German fabricators bear the steepest compliance costs given their concentration in refill-network swing-top production.
Brewery direct subscription models are displacing third-party retail channels for vessel acquisition. Consumers in Colorado and Vermont now receive seasonal growler rotations through membership programs, bypassing traditional hospitality equipment distributors. This channel compression is most visible in states with self-distribution privileges for small-batch producers.
Growlers Market Segmentation
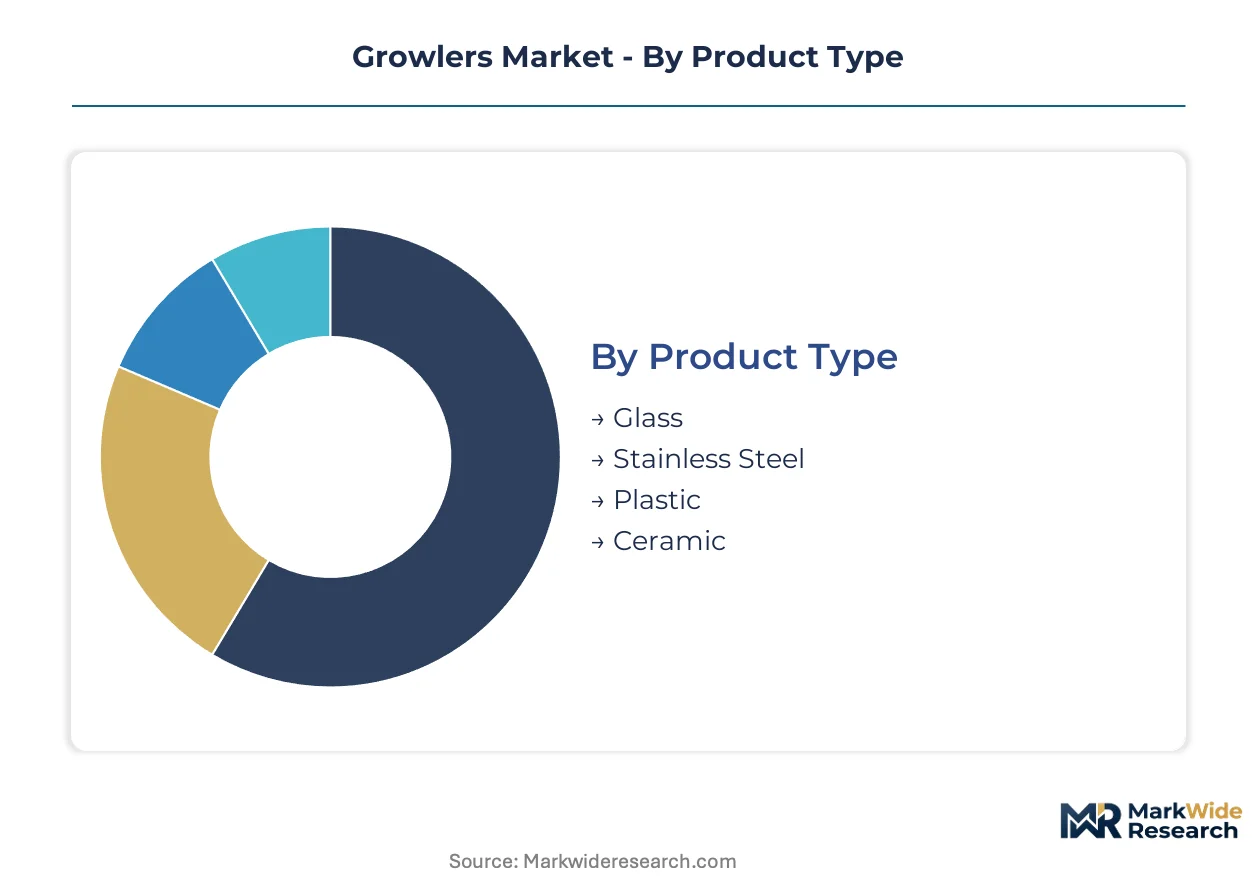
Growler segmentation reveals how substrate choices, capacity formats, and channel economics fragment demand across brewery direct-to-consumer operations. Understanding these divisions exposes where vacuum insulation commands premiums versus where glass retains cost-driven volume.
Product Type:
Mature glass formats coexist with emerging stainless steel thermal technologies as breweries weigh branding flexibility against outdoor portability requirements.
- Glass:Borosilicate and soda-lime compositions dominate brewery taproom branding due to surface decoration compatibility and FDA food-contact compliance clarity. Demand concentrates in Pacific Northwest urban clusters where Oregon's Bottle Bill expansions reduce total cost of ownership for refillable formats versus single-use alternatives.
- Stainless Steel:Vacuum-insulated double-wall construction preserves carbonation for 24-plus hours, enabling outdoor recreation use cases previously inaccessible to conventional vessels. YETI and premium fabricators target this segment where thermal performance justifies margin premiums over glass equivalents.
- Plastic:PET and copolyester variants serve entry-level price points and temporary event deployments where loss tolerance exceeds durability requirements.
- Ceramic:Hybrid ceramic-lined stainless steel formats neutralize metallic taste transfer for sour and barrel-aged beer categories, compressing traditional substrate hierarchies.
Glass retains volume leadership; ceramic-lined stainless steel holds the steepest expansion curve.
Size:
Commercial throughput economics versus home consumption patterns drive divergence across capacity tiers.
- 64 oz:The commercial standard anchors brewery taproom operations through optimal server-to-customer transfer efficiency and transport practicality. Germany's traditional beer culture regions sustain concentrated demand for this format within refill network infrastructures.
- 32 oz:Half-gallon formats gain traction among home users seeking portion flexibility and reduced per-opening oxidation exposure for high-gravity styles.
- 128 oz:Double-gallon vessels serve group consumption occasions and small-batch brewery club memberships where volume efficiency outweighs portability constraints.
- Others:Niche capacities including 16 oz personal formats and custom commemorative sizes address event-specific and gift market applications.
64 oz formats dominate brewery channel revenue; 32 oz variants are climbing the fastest among direct-to-consumer subscription models.
Closure Type:
Regional compliance frameworks and reuse cycle economics dictate sealing mechanism selection across import and domestic supply chains.
- Screw Cap:Tamper-evident threading dominates North American retail channels where FDA notification timelines for new gasket chemistries favor established polymer formulations. Screw closures align with brewery to-go operations prioritizing distribution security over reuse cycle counts.
- Swing Top:Wire-bail gasket systems anchor European refill networks through reusable seal durability, though ECHA substance of very high concern listings now force phthalate-to-silicone reformulation for German fabricators.
- Flip Top:Hinged polymer mechanisms serve mid-tier price positioning with faster opening convenience for outdoor recreation segments.
- Others:Crown cap adapters and proprietary threading systems address specialized brewery branding requirements and keg-style dispensing integration.
Screw cap configurations lead North American volume; swing top formats face steepest regulatory-driven reformulation costs in EU markets.
End User:
Channel concentration versus fragmentation determines vessel specification requirements and procurement scale economics.
- Breweries:Direct-to-consumer taproom operations generate the highest vessel throughput, with craft producers in Colorado and Vermont leveraging self-distribution privileges to bypass traditional hospitality equipment distributors through subscription membership models.
- Restaurants:On-premise beer programs with growler-filling licenses create secondary demand concentrated in states with favorable alcohol-to-go regulations.
- Retailers:Specialty beverage shops and outdoor recreation stores stock premium thermal formats for gift and expedition use cases.
- Home Users:Individual acquisition patterns favor 32 oz formats and ceramic-lined hybrids as sour and wild ale enthusiasm expands beyond traditional IPA-dominant consumption.
Breweries command procurement volume leadership; home users are expanding most quickly through direct subscription channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European growler distribution through its container handling capacity for glass imports from Turkish and Eastern European fabricators. Rail corridors linking the Rhine-Ruhr industrial belt to Bavarian brewery clusters sustain inland logistics for refillable vessel networks. This infrastructure underwrites Germany's role as the continent's primary demand center for swing-top formats.
United States
Craft brewery taproom density in Oregon and Washington generates concentrated demand for 64 oz glass vessels. Oregon's Bottle Bill expansions reduce total cost of ownership for refillable formats versus single-use alternatives. FDA food-contact notification timelines for new interior coating chemistries delay stainless steel product launches for seasonal brewery releases in California and Colorado.
Germany
Traditional beer culture regions sustain refill network infrastructure for swing-top glass formats. ECHA substance of very high concern listings force phthalate-to-silicone reformulation costs on domestic fabricators. Bavaria's state-level Pfand deposit variations create compliance complexity for cross-border suppliers shipping from Berlin-Brandenburg production zones.
India
Mumbai and Bangalore microbrewery licensing reforms open demand for imported stainless steel formats. FSSAI food-contact material standards govern seal gasket compositions for vessels entering through Jawaharlal Nehru Port. Domestic glass supply remains nascent, forcing brewers to source thick-walled borosilicate from Chinese and European exporters.
China
Yangtze River Delta glassworks supply borosilicate blanks to European and North American decorators. GB standards for food-contact materials constrain export-bound production runs versus domestic-market vessels. Ningbo and Shanghai port infrastructure handles outbound containerized shipments to Pacific Northwest brewery clusters.
United Kingdom
London's craft beer scene drives premium thermal format adoption through direct-to-consumer subscription models. REACH compliance obligations apply to EU-sourced swing-top imports post-Brexit customs processing. Scottish brewery cooperatives in Edinburgh and Glasgow pilot ceramic-lined stainless steel for sour beer categories.
Growlers Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in substrate supply and closure fabrication. The vendor base separates into three functional layers: glass container platforms with European melting furnace networks, multi-material distributors with North American logistics density, and premium thermal specialists with vacuum insulation IP. Consolidation pressures concentrate among glass fabricators facing energy cost volatility, while stainless steel entrants fragment the high-margin outdoor recreation segment. Capacity expansion and geographic licensing represent the dominant competitive vectors.
Among North American fabricators, YETI exemplifies the premium thermal archetype through its outdoor recreation channel positioning. Ardagh Group represents the integrated glass platform model with European melting and decorating capabilities. Berlin Packaging occupies the multi-material distribution tier, sourcing across substrate categories to serve brewery clients with consolidated procurement. These three anchors illustrate how substrate specialization, geographic production footprint, and channel access stratify competitive positioning.
| Leading Market Players |
|---|
| Ardagh Group |
| Berlin Packaging |
| Boelter |
| Croxsons |
| DrinkTanks |
| Evans Manufacturing |
| Global Glass Solutions |
| GrowlerWerks |
| YETI |
| Others |
Supply Flow & Price Mechanics
The Port of Hamburg's container handling rates govern landed costs for Turkish and Eastern European glass imports, concentrating pricing power among Rhine-Ruhr distributors while forcing Pacific Northwest brewers to absorb premium freight differentials on stainless steel thermal formats.
Pricing Analysis
Volume-discount tiering separates brewery direct procurement from retail channel acquisition, with 64 oz glass vessels commanding standard rates and vacuum-insulated stainless steel fetching premium positioning through YETI's outdoor recreation branding. Price differentiation rests on thermal performance certification and FDA food-contact compliance tiering, with ceramic-lined hybrids compressing mid-market positioning. Cost compression in borosilicate glass is intensifying because European natural gas furnace economics squeeze fabricator margins. Craft brewery taprooms exhibit lowest price sensitivity; home users through subscription channels show highest elasticity.
Supply Chain Analysis
Contract manufacturing concentration sits with Yangtze River Delta glassworks and Ningbo stainless steel fabricators, with Ardagh Group's European melting networks and Berlin Packaging's North American distribution platform anchoring downstream assembly. Geographic supply concentration centers on China, Germany, and Turkey for substrate production. Raw material dependencies draw from borosilicate sand, nickel-alloy steel stock, and silicone gasket formulations. Single-source vulnerability runs through Yangtze River Delta furnace capacity for North American glass demand. Distribution runs through brewery direct channels, hospitality equipment distributors, and outdoor recreation retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The growlers market is cycling through post-pandemic on-premise consumption recovery, with craft brewery taproom traffic serving as the lead cyclical indicator for vessel procurement velocity.
For Market Incumbents: Harden supply positions by securing captive borosilicate furnace capacity in Turkey or Eastern Europe before energy cost volatility deepens European margin erosion. Lock in multi-year silicone gasket supply contracts ahead of ECHA reformulation deadlines. Single-use aluminum crowler substitution poses the immediate substitution threat; vertical integration into ceramic-lined stainless steel R&D addresses the premium tier defense. For New Entrants and Emerging Players: India's Mumbai-Bangalore microbrewery corridor offers underpenetrated demand for imported stainless steel formats where FSSAI compliance creates barrier-protected pricing. Target ceramic-lined hybrids for sour beer categories where metallic taste transfer has blocked conventional steel adoption. A direct-to-brewery technical sales model bypasses established hospitality distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with dormant growler-specific decorating capabilities and established brewery relationships. Long-term viability hinges on refillable container mandate expansion across OECD jurisdictions. Watch Oregon and California state-level reusable packaging tax credit renewals as policy inflection signals for durable format demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic-Lining Technology Licensing | Pacific Northwest sour breweries pilot ceramic-lined vessels to neutralize metallic taste transfer barriers. |
| Direct-to-Brewery Subscription Platform | Colorado and Vermont producers bypass hospitality distributors through membership-based seasonal vessel rotations. |
| Silicone Gasket Supply Contracting | German fabricators secure reformulated seal materials ahead of ECHA phthalate restriction enforcement. |
| India Market Entry Partnership | Joint ventures with Mumbai microbreweries navigate FSSAI food-contact standards for stainless steel imports. |
| Thermal Performance Certification Program | Vacuum insulation IP holders establish 24-hour carbonation retention standards for outdoor recreation channel positioning. |
Methodological Framework
Desk research of customs trade databases, brewery licensing records, and FDA food-contact notification filings preceded structured interviews with craft brewery operations directors, hospitality equipment procurement managers, glass container plant engineers, and thermal product R&D leads. Secondary validation drew from ECHA substance restriction updates, state-level deposit framework legislation, and EPR scheme implementation timelines. Bottom-up vessel shipment data triangulated against top-down brewery taproom revenue estimates.
Assumptions held fixed include current FDA notification timelines for new coating chemistries and existing EU REACH substance listings; variables tested across scenarios included natural gas price volatility bands and state-level refillable incentive adoption rates. The analytical framework modeled substrate type, capacity format, closure mechanism, and end-user channel dimensions across the projection horizon. CAGRs were derived from segment-level volume build-ups calibrated to brewery taproom density metrics and outdoor recreation participation indices.
Practitioners should monitor ECHA substance of very high concern listing expansions and Oregon Bottle Bill legislative amendments for early signals of regulatory-driven substrate substitution. Forecasts reflect assumptions about craft brewery licensing reform continuity in India and Pacific Northwest urban cluster demand concentration. Quarterly review of natural gas futures, silicone gasket supply availability, and aluminum crowler pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Flavored Powder Drinks Market
Beverages
Cold Pressed Juice Market
Beverages
Solid Beverages Market
Beverages
Relaxation Beverages Market
Beverages
Hydrogen Water Dispenser Market
Beverages
South America Bottled Water Market
Beverages
Rose Floral Water Market
Beverages
Global Bottled Water Market
Beverages
Breakfast Drink Market
Beverages
Vegetable Juice Market
Beverages
Bottled Water Processing Market
Beverages
United Kingdom Energy Drink Market
Beverages
Apple Juice Concentrate Market
Beverages
Fermented Foods and Beverages Market
Beverages
Caffeinated Beverage Market
Beverages
Birch Water Market