
 Fruit Water Market | 2026-2036
Fruit Water Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Water Market Foresight
The capability gap between multinational bottling networks and craft-scale flavor houses is collapsing as co-packing infrastructure democratizes access to aseptic cold-fill lines. The Coca-Cola Company leverages its captive distribution network to secure shelf space in mass retail channels. PepsiCo anchors its position through backward integration into flavor extraction and concentrate supply. Nestlé differentiates via mineral water heritage brands that it extends into fruit-infused line extensions.
Fruit water denotes non-alcoholic beverages combining purified or spring water with natural fruit essences, extracts, or juices, typically containing zero to minimal added sugars and achieving shelf stability through hot-fill, aseptic, or high-pressure processing techniques. The category serves commercial hydration needs positioned between plain bottled water and sugar-laden soft drinks. Sparkling variants capture premium margin pools in health food stores and upscale supermarkets, while infused formats without carbonation dominate volume in convenience retail. Bottles remain the standard packaging substrate, though pouches gain traction in fitness-channel distribution targeting on-the-go consumption.
The FDA governs labeling and health claims under the Federal Food, Drug, and Cosmetic Act, while the EU enforces nutrition and health claims regulation alongside F-Gas rules affecting carbonated production lines. These frameworks elevate compliance costs for new entrants but simultaneously validate clean-label positioning that commands price premiums. Stakeholders must monitor evolving single-use packaging directives in California and the EU that threaten conventional PET economics while creating first-mover advantages for carton and aluminum innovators.
Market Dynamics
Sugar-reduction mandates from FDA and EU regulators are forcing a complete reformulation of flavor extraction methods, collapsing the traditional gap between premium mineral water heritage and mass-market soft drink economics.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of hydrofluorocarbons in carbonated production lines accelerates investment in high-pressure processing alternatives for sparkling variants.
- Fitness-channel demand:Wellness programs and boutique gym chains are creating dedicated cold-case placement for on-the-go hydration formats.
- Aseptic cold-fill infrastructure:Co-packing democratization allows craft-scale flavor houses to access shelf-stable production without captive bottling networks.
Market Restraints
- Natural flavor concentrate supply:Agricultural volatility in citrus and berry harvests creates input cost instability for extraction-dependent formulations.
- Single-use packaging directives:California and EU regulations threaten conventional PET economics while alternative substrates remain at scale disadvantage.
- Clean-label compliance costs:EFSA nutrition and health claims validation requires extensive clinical substantiation that elevates barrier to entry.
Strategic Opportunities
- Aluminum can migration:Premium sparkling sub-segments can bypass PET restrictions entirely through format innovation in health food retail.
- Japan's aging hydration culture:Functional positioning around mineral fortification targets senior consumers underserved by current youth-focused marketing.
- ISO 22000 convergence:Unified food safety certification enables mid-tier producers to enter multiple export markets with single audit compliance.
Industry Challenges
- Flavor chemist scarcity:Formulation expertise in natural extract stabilization commands premium compensation that strains R&D budgets.
- Legacy ERP integration:Track-and-trace requirements for FDA FSMA compliance collide with outdated inventory management systems at regional bottlers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Water Market |
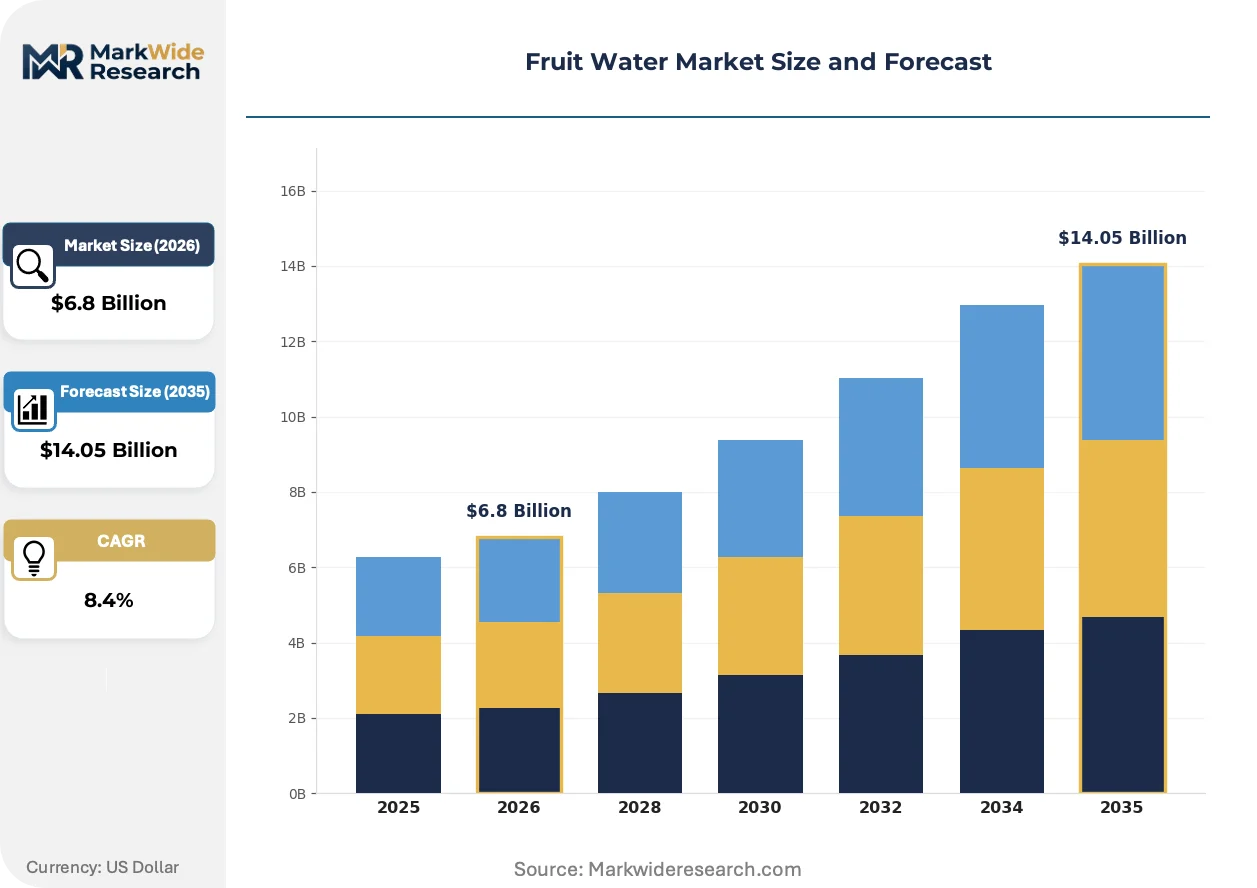
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavored, Infused, Sparkling, Organic Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Health Food Stores Packaging Type: Bottles, Cartons, Pouches, Tetra Packs End User: Health-conscious Consumers, Fitness Enthusiasts, Athletes, Casual Drinkers |
| Companies Covered | The Coca-Cola Company, PepsiCo, Nestlé, Keurig Dr Pepper, Hint Inc., Talking Rain Beverage Company, National Beverage Corp., Danone S.A., Spindrift Beverage Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Water Market Shifts & Advancements
Formulation science is fragmenting the traditional boundary between functional beverages and flavored water, creating new technical requirements for stability without sugar or synthetic preservatives.
High-pressure processing is decomposing the conventional trade-off between shelf life and clean-label positioning. Cold-pressed juice operators and mineral water specialists are adopting HPP systems at accelerating rates. This technology is decomposing the historical advantage of hot-fill bottling networks by enabling ambient distribution of preservative-free formulations.
REACH chemical registration requirements are expanding scrutiny of flavor compound safety dossiers. Manufacturers must now document full toxicological profiles for natural extract constituents previously grandfathered under older frameworks. Carbonated variants face particular exposure given the additional processing aids and packaging interactions under review.
Direct-to-gym distribution is compressing traditional wholesale margins by bypassing conventional retail slotting fees. Boutique fitness chains negotiate exclusive flavor collaborations that displace standard SKU assortment. Germany and Japan show the most advanced development of this channel, with dedicated refrigerated logistics networks serving studio locations.
Fruit Water Market Segmentation
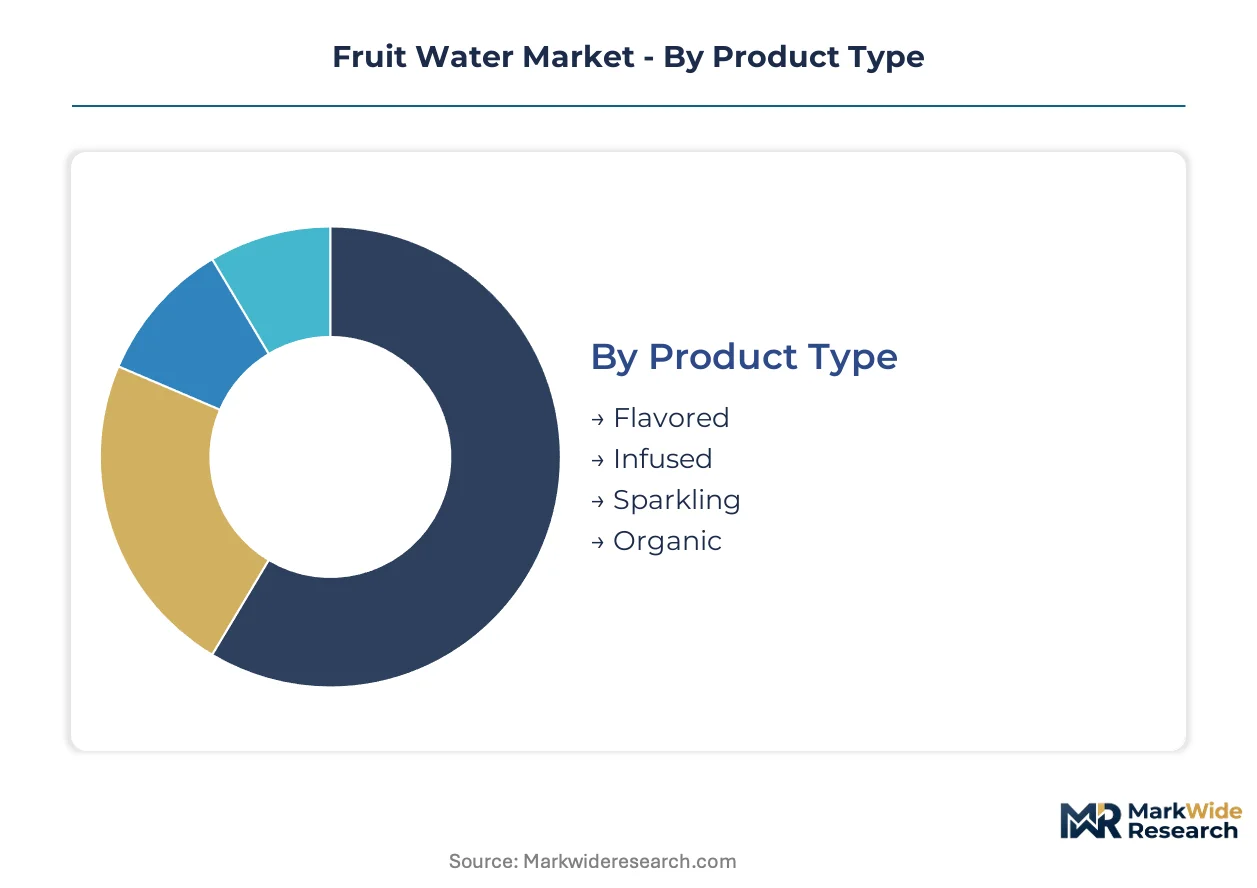
Segmentation in fruit water reveals how regulatory frameworks and channel economics fragment production requirements. Each dimension carries distinct compliance burdens and margin structures that reshape competitive positioning.
Product Type:
FDA nutrition labeling and EU health claims enforcement create divergent formulation pathways across product categories, elevating compliance investment for functional positioning.
- Flavored:These formulations rely on natural and artificial flavor compounds added to purified water bases. Demand concentrates in mass retail channels across the United States where sugar-reduction mandates from the FDA drive zero-calorie positioning. Input cost volatility in citrus and berry concentrates constrains margin stability.
- Sparkling:Carbonated variants achieve premium pricing through high-pressure processing or aseptic cold-fill techniques. Germany's mature hydration culture supports dedicated refrigerated placement in upscale supermarkets, though EU F-Gas Regulation phase-downs force equipment migration away from conventional carbonation systems.
- Infused:Subtle flavor profiles derived from botanical or fruit immersion without extraction concentration. Japan's aging consumer base favors gentle taste profiles in convenience retail formats.
- Organic:Certified organic variants require USDA or EU organic seal compliance across the entire supply chain. Health food stores in California command shelf space premiums for verified sourcing.
Established volume favors Flavored; emerging adoption favors Sparkling.
Distribution Channel:
Channel selection determines cold-chain requirements, slotting fee exposure, and direct-to-consumer data capture capabilities that reshape margin architecture.
- Online Retail:E-commerce platforms enable subscription models and flavor customization with minimal retail intermediary costs. Fitness enthusiasts in urban United States clusters drive repeat purchase velocity through direct delivery.
- Supermarkets:Mass retail placement demands broad SKU assortment and promotional funding commitments. Germany's discount retail density compresses unit economics for premium positioning.
- Convenience Stores:Impulse-driven single-serve formats dominate volume in Japan's dense urban vending infrastructure. Refrigerated shelf scarcity limits flavor variety.
- Health Food Stores:Curated placement validates clean-label credentials and supports aluminum can migration away from PET. California's packaging directive pressures accelerate format innovation here.
Volume concentrates in Supermarkets; margin expansion concentrates in Health Food Stores.
Packaging Type:
Substrate selection now hinges on single-use packaging directives rather than purely cost-driven procurement, reconfiguring capital allocation across production networks.
- Bottles:PET remains the standard substrate for mass-market distribution despite regulatory headwinds. Conventional blow-molding infrastructure at regional bottlers across the United States maintains cost advantages.
- Cartons:Aseptic carton formats bypass California and EU PET restrictions while enabling ambient distribution. Germany's recycling infrastructure supports fiber-based recovery systems.
- Pouches:Flexible formats target fitness-channel on-the-go consumption with reduced shipping weight. Boutique gym chains in Japan negotiate exclusive pouch-based collaborations.
- Tetra Packs:Multi-layer carton systems suit ambient-stable infused variants with extended shelf life. EU packaging waste directives favor renewable substrate sourcing.
Installed base favors Bottles; regulatory compliance favors Cartons.
End User:
User segmentation maps directly to hydration occasion specificity, from performance-oriented electrolyte timing to casual meal accompaniment.
- Health-conscious Consumers:Broad demographic seeking sugar reduction without flavor sacrifice. United States mass retail placement targets this segment with mainstream flavor profiles.
- Fitness Enthusiasts:Boutique gym chains and wellness programs create dedicated cold-case demand. Germany's studio distribution networks serve this segment with specialized logistics.
- Athletes:Performance hydration requires mineral fortification and rapid absorption profiles. Japan's senior athletic communities remain underserved by youth-focused marketing.
- Casual Drinkers:Meal accompaniment and social consumption occasions favor sparkling variants in aluminum formats. Convenience retail in urban Japan captures impulse-driven trial.
Revenue breadth favors Health-conscious Consumers; pricing power favors Athletes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States treats fruit water as a mass-market sugar substitute, while Germany and Japan cultivate premium hydration cultures with distinct channel and format preferences.
United States
FDA sugar-reduction mandates and wellness program proliferation drive demand for zero-calorie flavored formats. The agency's updated nutrition labeling requirements force reformulation transparency. California's single-use packaging directives accelerate aluminum can adoption in Los Angeles and San Francisco health food retail clusters.
Germany
Sparkling variants dominate upscale supermarket placement as mineral water heritage extends into fruit-infused extensions. EU F-Gas Regulation phase-downs compel carbonation equipment migration toward high-pressure processing alternatives. Berlin and Munich studio distribution networks pioneer direct-to-gym cold-case logistics for fitness-channel exclusives.
Japan
Aging demographics favor gentle infused profiles over aggressive carbonation in dense urban vending infrastructure. METI standards for functional food claims enable mineral fortification positioning targeting senior consumers. Tokyo and Osaka convenience retail captures impulse-driven trial through refrigerated shelf scarcity strategies.
United Kingdom
Health-conscious urban clusters in London and Manchester drive subscription e-commerce models with flavor customization. EFSA nutrition and health claims validation elevates compliance costs for clean-label positioning. Carton format adoption accelerates amid EU packaging waste directive alignment pressures post-Brexit transition.
Canada
Health Canada regulations govern natural health product claims for functional hydration variants. Toronto and Vancouver boutique fitness chains negotiate exclusive flavor collaborations bypassing conventional wholesale margins. Aluminum can infrastructure expands as provincial single-use plastic restrictions tighten PET economics.
Fruit Water Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational bottling networks leveraging captive distribution against craft-scale flavor houses accessing democratized co-packing infrastructure. The Coca-Cola Company and PepsiCo anchor the consolidated upper tier through backward integration into concentrate supply and flavor extraction. Nestlé occupies a heritage-mineral position extending established water brands into fruit-infused line extensions. Competitive moves concentrate on format innovation in aluminum and carton substrates alongside direct-to-gym channel bypass strategies.
Among North American beverage conglomerates, The Coca-Cola Company and PepsiCo exemplify scale-driven distribution dominance, while Nestlé S.A. represents European heritage-brand extension strategy. Danone S.A. anchors the premium sparkling sub-segment through mineral water lineage. These three occupy distinct archetype positions: mass-market network leverage, upstream supply control, and premium brand heritage respectively.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo |
| Nestlé |
| Keurig Dr Pepper |
| Hint Inc. |
| Talking Rain Beverage Company |
| National Beverage Corp. |
| Danone S.A. |
| Spindrift Beverage Co. |
| Others |
Supply & Pricing Matrix
Aseptic cold-fill line utilization rates at co-packing facilities determine both minimum viable scale and floor pricing for craft-scale entrants, compressing the historical advantage of multinational bottling networks while elevating price competition in premium sparkling segments.
Pricing Analysis
Subscription revenue from direct-to-gym exclusive flavor collaborations drives lifetime value capture beyond transactional retail. Three-tier pricing structure across premium sparkling, standard infused, and economy flavored levels separates mineral heritage positioning from mass-market sugar substitutes. Cost compression in PET-dependent tiers is intensifying because California and EU single-use packaging directives threaten conventional substrate economics. Health-conscious consumers in mass retail channels exhibit highest price sensitivity, while fitness enthusiasts in boutique studio networks accept premium positioning for exclusive formulations.
Supply Chain Analysis
Citrus and berry harvest volatility in Brazil, Mexico, and Spain creates input cost instability that propagates through natural flavor concentrate markets. Formulation science expertise draws from agricultural extraction specialists in California, flavor compound houses in Switzerland, and high-pressure processing equipment manufacturers in Germany. Single-source vulnerability concentrates in tropical citrus supply exposed to climate-driven harvest disruption. Distribution runs through refrigerated logistics networks serving fitness-channel exclusives in Germany and Japan alongside ambient retail pipelines for mass-market flavored variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Natural extract stabilization expertise commands premium compensation that outstrips supply, creating acquisition premiums for flavor chemist teams and HPP equipment operators with proven shelf-life extension capabilities.
For Market Incumbents: Consolidate backward integration into flavor extraction to secure concentrate supply against agricultural volatility. Capture aseptic cold-fill capacity in Germany and Japan before co-packing democratization erodes scale advantages. Prioritize aluminum can format migration to bypass PET regulatory headwinds in California health food retail clusters. For New Entrants and Emerging Players: Anchor in Japan's aging hydration culture where mineral fortification positioning remains underserved by youth-focused marketing. Target direct-to-gym distribution in Berlin and Munich studio networks for exclusive flavor collaborations. Pursue ISO 22000 certification to enable multi-market export entry with single audit compliance. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among boutique fitness channel operators with exclusive flavor contracts and subscription logistics infrastructure. Five-to-ten year viability favors mid-tier producers with captive HPP capacity and aluminum format flexibility over PET-dependent volume players. Monitor EU F-Gas Regulation enforcement timelines as inflection indicator for carbonated production line equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flavor Extraction | Secures concentrate supply against Brazilian citrus harvest volatility threatening margin stability. |
| High-Pressure Processing Equipment Deployment | Enables ambient distribution of preservative-free formulations competing with hot-fill networks. |
| Aluminum Can Format Migration | Bypasses California PET restrictions while capturing premium placement in health food retail. |
| Direct-to-Gym Distribution Partnership | Compresses wholesale margins through exclusive studio collaborations displacing standard SKUs. |
| ISO 22000 Certification Investment | Unlocks multi-market export access with unified food safety audit compliance across jurisdictions. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers at multinational bottlers, category buyers at German discount retailers, flavor chemists at extraction houses, and supply planners at co-packing facilities and refined through secondary validation against FDA nutrition labeling filings, EU F-Gas Regulation implementation documents, Nielsen retail audit data, and customs records tracking concentrate imports. Bottom-up volume builds across product type, distribution channel, packaging format, and end-user segments were triangulated against top-down market sizing from regulatory framework analysis.
Variance decomposition across the projection horizon isolates volume drivers by sparkling versus still format adoption, refrigerated versus ambient distribution economics, and premium versus mass-market channel positioning. Segmentation dimensions modeled include product type, distribution channel, packaging substrate, and end-user hydration occasion. CAGRs were derived from regression analysis against wellness program penetration rates and sugar-reduction mandate enforcement timelines.
Underlying assumptions cover FDA and EU regulatory stability, co-packing capacity expansion rates, and aluminum substrate cost curves, with deviation risk concentrated in agricultural harvest volatility and single-use packaging directive implementation timing. Practitioners should keep alternative scenarios live as F-Gas Regulation phase-down schedules and California PET restriction enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Rose Floral Water Market
Beverages
Blenders Market
Beverages
North America Ready-To-Drink (RTD) Beverages Market
Beverages
North America Dairy Beverages Market
Beverages
US and Canada Tonic Water Market
Beverages
GCC Juice Market
Beverages
Premium Water Market
Beverages
Plant Based Beverages Market
Beverages
Bottled Deep Ocean Water Market
Beverages
North America Kombucha Market
Beverages
Saudi Arabia Bottled Water Market
Beverages
Italy Bottled Water Market
Beverages
Freezer & Beverage and Wine Cooler Market
Beverages
Maple Water Market
Beverages
North America Sugar Free Energy Drinks Market
Beverages
North America Juices Market