
 Craft Soda Market | 2026-2036
Craft Soda Market Size, Share, and Industry Trends Forecast 2026-2036
Craft Soda Market Intelligence
Clean-label extraction and natural carbonation methods is tilting production economics toward smaller-batch operations with tighter ingredient provenance. Jones Soda Co leverages its customizable label platform to sustain direct consumer engagement. Reed's, Inc. anchors its position through intense ginger-root sourcing specialization. Boylan Bottling Co competes on heritage formulation consistency and glass-bottle nostalgia.
Craft soda denotes small-batch, cane-sugar-sweetened soft drinks produced with natural flavor extracts, botanical infusions, and traditional carbonation at sub-50,000-unit production runs, serving consumers seeking alternatives to high-fructose corn syrup formulations. Cola and root beer variants occupy the deepest consumer recognition pools, while fruit-flavored and herbal segments attract the fastest trial rates among younger demographics. Glass bottle packaging commands premium shelf positioning in specialty stores and gourmet retailers, though aluminum can formats are gaining traction in online retail channels where shipping weight and breakage risk constrain glass adoption.
FDA enforces nutrition-fact panel accuracy and added-sugar disclosure rules that shape craft soda label design and reformulation priorities. State-level sugar taxes and municipal beverage regulations in California, Washington, and Oregon create patchwork compliance costs that favor regional producers with localized distribution footprints. Stakeholders must monitor evolving FDA guidance on natural flavor claims and anticipate which metropolitan markets will extend sugar-tax regimes.
Market Dynamics
Reformulation pressure from FDA added-sugar disclosure rules and municipal sugar-tax debates is compressing margins while forcing botanical ingredient substitution across craft soda portfolios.
Growth Catalysts
- Botanical ingredient provenance:Consumer rejection of high-fructose corn syrup is pulling cane-sugar and natural extract sourcing into premium positioning. Small-batch producers leverage tighter ingredient traceability to differentiate against mass-market alternatives.
- Pacific Northwest urban concentration:Seattle and Portland metropolitan corridors cluster dense demand for glass-bottle heritage formulations. Local distribution footprints minimize compliance costs from Washington and Oregon municipal beverage regulations.
- California sugar-tax momentum:Proposed state-level levy frameworks are accelerating reformulation toward lower-calorie botanical blends ahead of formal enactment. Early movers capture shelf space in Los Angeles and San Francisco gourmet retail channels.
Market Restraints
- Glass packaging cost structure:Weight and breakage risk constrain e-commerce adoption, forcing aluminum can substitution that erodes premium positioning. Shipping economics favor mass-market producers with centralized fulfillment infrastructure.
- Natural flavor claim uncertainty:Evolving FDA guidance on botanical extract classification creates label redesign cycles. Reformulation timelines extend as legal teams interpret ambiguous natural flavor definitions.
- Concentrated ginger-root sourcing:Specialized suppliers in tropical growing regions face climate volatility. Reed's and comparable specialists face input cost spikes during poor harvest seasons.
Strategic Opportunities
- California metropolitan corridor expansion:San Diego and Sacramento sub-markets show underpenetrated craft soda placement relative to Los Angeles density. Regional producers with localized distribution can capture premium foodservice accounts before national brands establish presence.
- Direct-to-consumer subscription channels:Customizable label platforms enable recurring revenue models bypassing traditional retail slotting fees. Jones Soda's engagement infrastructure provides template for scaled digital relationships.
- Botanical-infused functional positioning:Adaptogen and herbal extract convergence with traditional carbonation opens wellness-adjacent positioning. Yerba mate and turmeric variants attract trial from health-conscious younger demographics.
Industry Challenges
- Small-batch carbonation technician scarcity:Traditional carbonation method expertise concentrates among aging workforce. Training pipelines for natural carbonation process control remain underdeveloped.
- Multi-state label compliance:Patchwork sugar-tax disclosure requirements across California, Washington, and Oregon force SKUs with jurisdiction-specific nutrition panels. Packaging complexity multiplies inventory management overhead.
- Glass-to-aluminum format integration:Canning line capex requirements strain sub-50,000-unit producers. Equipment financing access varies sharply by producer credit profile.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Craft Soda Market |
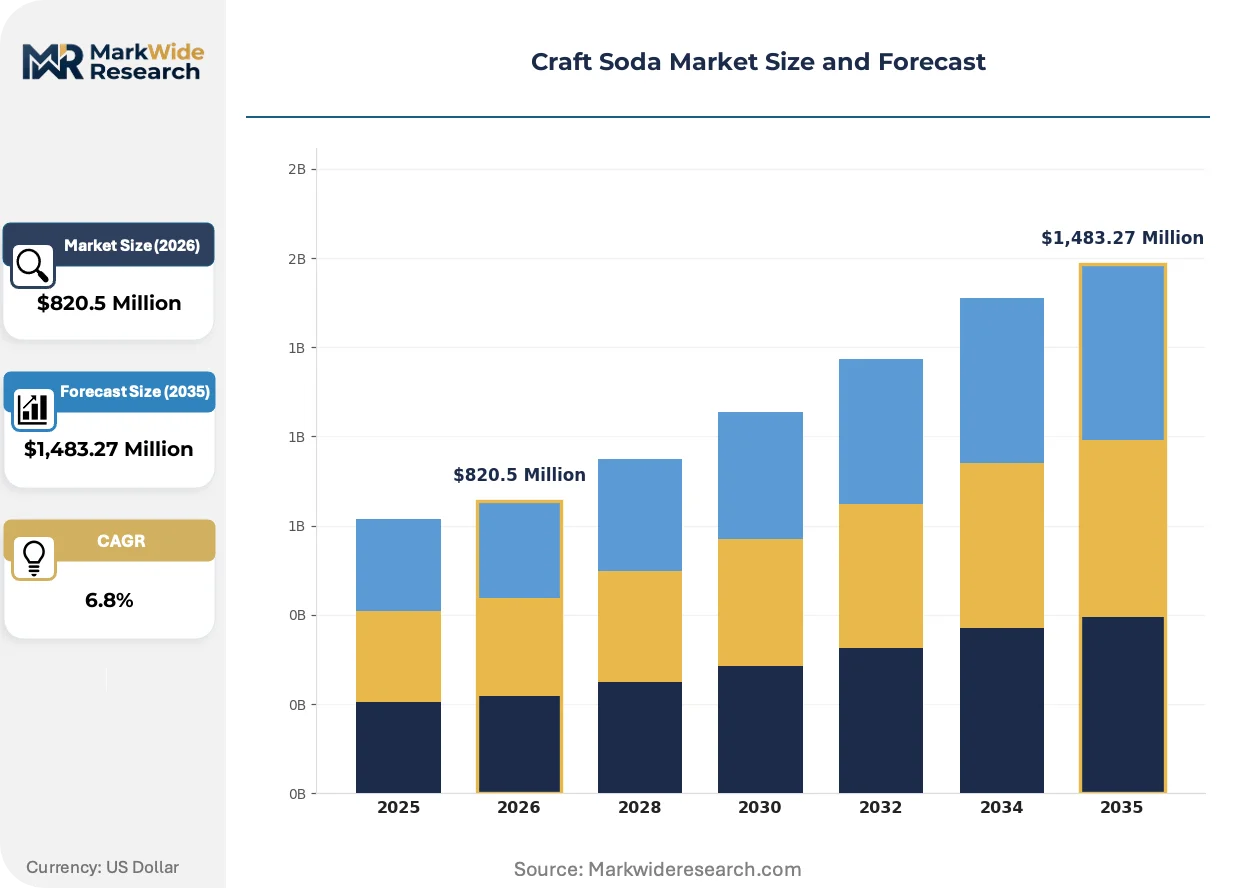
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,483.27 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cola, Ginger Ale, Root Beer, Cream Soda, Fruit Flavored, Herbal Flavor Profile: Spiced, Citrus, Botanical, Sweetened, Unsweetened, Tart Packaging Type: Glass Bottle, Aluminum Can, Plastic Bottle, Carton, Keg, Cask Distribution Channel: Specialty Stores, Online Retailers, Farmers Markets, Cafes, Organic Shops, Gourmet Retailers |
| Companies Covered | SIPP eco beverage co. Inc., Crooked Beverage Co., Jones Soda Co, Q Drinks, Gus, Reed's, Inc., Appalachian Brewing Co, The Original Craft Soda Company, Boylan Bottling Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Craft Soda Market Strategic Shifts & Innovations
Clean-label extraction technology and digital engagement infrastructure are compressing traditional batch-to-retail timelines while fragmenting consumer touchpoints beyond conventional grocery channels.
Supercritical CO2 extraction systems is digitizing botanical oil recovery from citrus peels and ginger roots. Premium craft producers in California and the Pacific Northwest deploy these units to standardize flavor concentration batch-to-batch. The technology is digitizing quality control documentation for FDA natural flavor claim substantiation.
FDA added-sugar disclosure mandates now require line-item reporting of cane sugar versus other caloric sweeteners. Label redesign costs are diverting R&D budgets toward reformulation rather than new product development. Fruit-flavored segments face the steepest compliance burden due to multi-component sweetener blends.
Younger demographic trial behavior now clusters around limited-release drops and seasonal flavor rotations rather than core SKUs. Specialty stores and gourmet retailers are unbundling traditional annual-planogram commitments in favor of flexible 90-day placement cycles. This pattern concentrates in California's metropolitan corridors where consumer novelty-seeking runs highest.
Craft Soda Market Segmentation
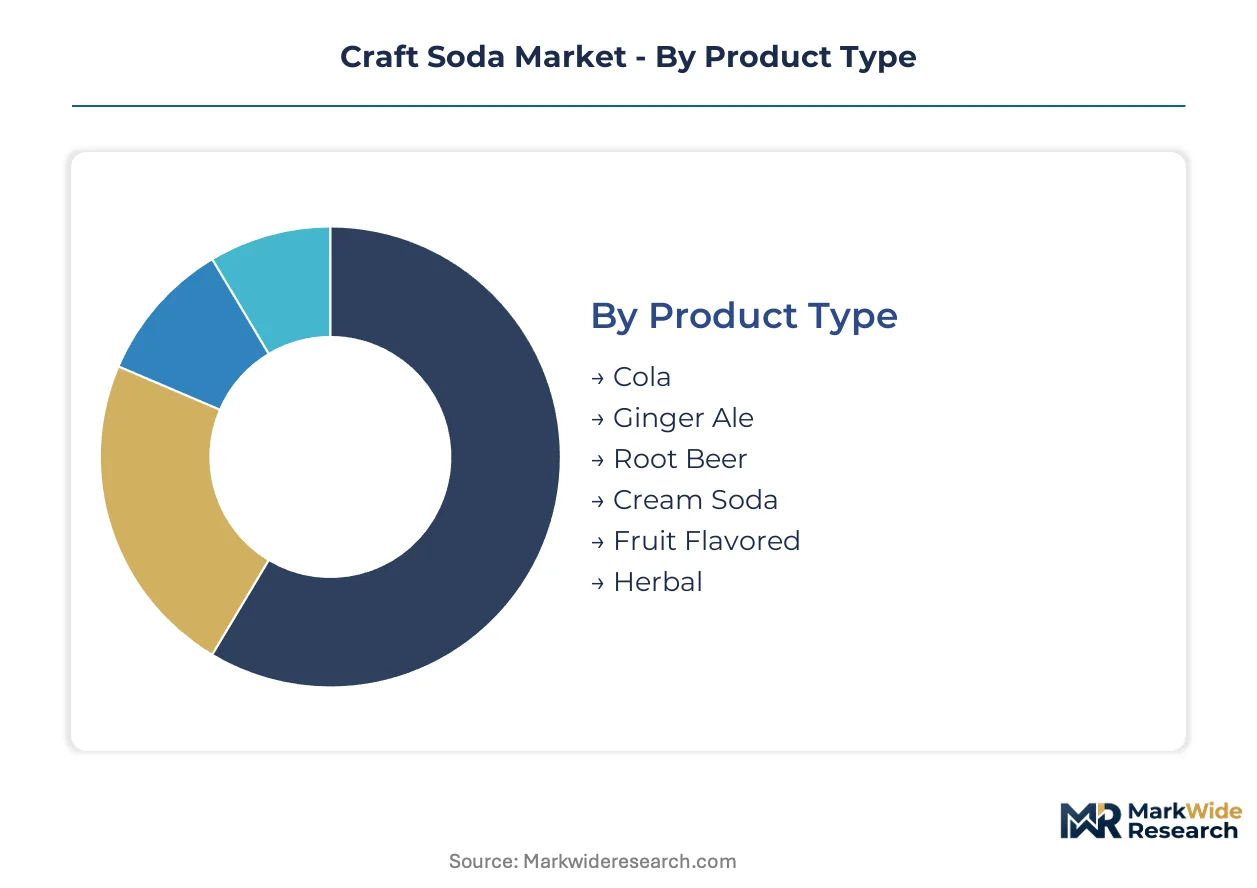
Craft soda segmentation reveals how producers balance heritage authenticity against operational pragmatism. Each dimension—product formulation, sensory positioning, physical format, and route-to-market—carries distinct margin and compliance implications that shape portfolio architecture.
Product Type:
Cost tier differentiation separates heritage-recipe staples from experimental variants with volatile input costs.
- Cola:Caramel-color formulations using kola nut extract and cane sugar define the category's most recognizable profile. Los Angeles and San Francisco gourmet retailers maintain dedicated shelf space for small-batch cola alternatives as consumers reject high-fructose corn syrup mass-market versions.
- Ginger Ale:Fresh ginger-root carbonation demands specialized sourcing relationships with tropical suppliers. Reed's sourcing concentration in this segment exposes producers to climate-driven input volatility during poor harvest cycles.
- Root Beer:Sassafras and wintergreen botanical blends occupy deep consumer nostalgia positioning. Pacific Northwest urban corridors cluster dense demand for heritage glass-bottle presentations.
- Cream Soda:Vanilla-bean and honey formulations target family-oriented consumption occasions. Aluminum can formats gain traction here for outdoor and picnic use cases.
- Fruit Flavored:Citrus and berry extract infusions attract the fastest trial rates among younger demographics. FDA added-sugar disclosure rules impose the steepest label redesign burden due to multi-component sweetener blends.
- Herbal:Adaptogen and botanical extract convergence opens wellness-adjacent positioning. Yerba mate and turmeric variants capture trial from health-conscious consumers in California metropolitan markets.
Cola and root beer command the established base. The steepest expansion runs through herbal variants.
Flavor Profile:
Application context—mixology versus straight consumption—determines which sensory signatures dominate purchase decisions.
- Spiced:Cinnamon, clove, and allspice formulations anchor winter seasonal rotations. Specialty stores in Seattle and Portland prioritize limited-release spiced drops during holiday periods.
- Citrus:Supercritical CO2 extraction from lemon, lime, and grapefruit peels standardizes oil concentration batch-to-batch. California producers deploy this technology to digitize quality control documentation for FDA natural flavor claim substantiation.
- Botanical:Lavender, rose, and elderflower infusions command premium positioning in organic shops. Sourcing traceability requirements compress margins through certified-supplier premiums.
- Sweetened:Cane sugar and honey formulations face reformulation pressure from municipal sugar-tax debates. Proposed California state-level levies accelerate shifts toward lower-calorie alternatives.
- Unsweetened:Carbonated mineral water bases with natural essence extracts attract sugar-avoidant consumers. Online retailers favor this segment for subscription-model replenishment.
- Tart:Cranberry, pomegranate, and hibiscus acidity profiles differentiate cocktail mixers. Cafes and gourmet foodservice accounts specify tart variants for craft beverage programs.
Sweetened variants retain volume leadership. Tart profiles are climbing the fastest among on-premise accounts.
Packaging Type:
Volume scale and breakage risk create divergent economics across physical formats.
- Glass Bottle:Heritage amber and clear glass presentations command premium shelf positioning in specialty stores. Weight and shipping fragility constrain e-commerce adoption, forcing aluminum substitution for direct-to-consumer channels.
- Aluminum Can:Lightweight formats gain traction in online retail where shipping economics favor reduced breakage risk. Canning line capex requirements strain sub-50,000-unit producers with limited equipment financing access.
- Plastic Bottle:PET formats serve price-sensitive convenience store placements. This packaging sacrifices premium positioning for distribution breadth in mainstream retail.
- Carton:Multi-serve paperboard packaging targets family and foodservice bulk purchasing. Farmers markets and organic shops favor cartons for environmental messaging alignment.
- Keg:Stainless steel keg formats supply draft systems in cafes and gourmet retailers. Refillable infrastructure requires localized distribution footprints for return logistics.
- Cask:Small-volume oak cask conditioning enables limited-release positioning. This format concentrates among Pacific Northwest producers emphasizing traditional carbonation methods.
Glass bottles dominate specialty retail valuation. Aluminum cans are gaining share fastest in digital channels.
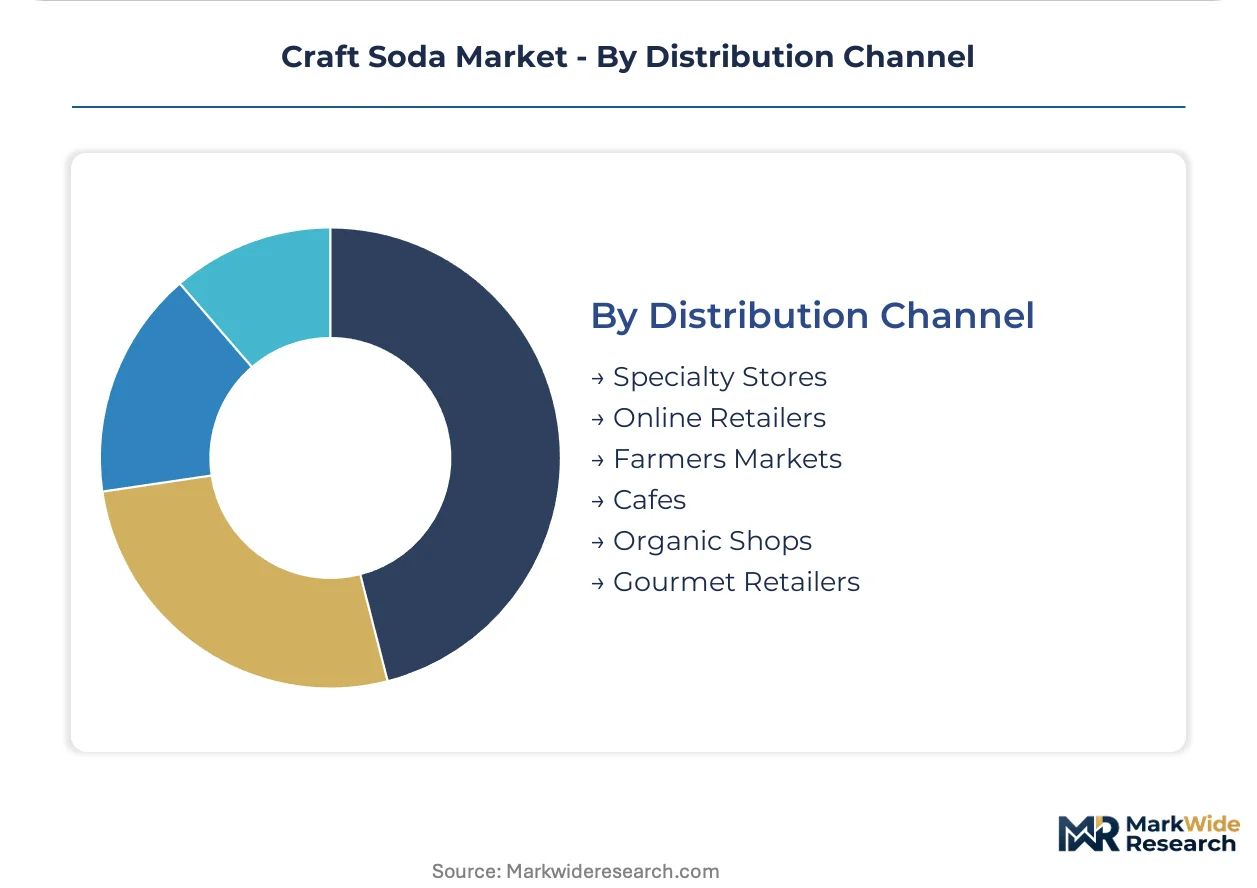
Distribution Channel:
Customer type and purchase occasion fragmentation is forcing producers to maintain parallel channel strategies with distinct margin structures.
- Specialty Stores:Curated shelf sets with 90-day placement cycles replace traditional annual planograms. California metropolitan corridors show the highest concentration of flexible assortment commitments.
- Online Retailers:Subscription and customizable label platforms enable recurring revenue models. Jones Soda's engagement infrastructure provides template for scaled digital relationships bypassing slotting fees.
- Farmers Markets:Direct producer-consumer interaction supports premium pricing and immediate feedback loops. Pacific Northwest urban centers cluster the densest weekend market participation.
- Cafes:On-premise draft and bottle service accounts specify craft soda for beverage program differentiation. Municipal beverage regulations in Washington and Oregon create compliance cost advantages for localized producers.
- Organic Shops:Certification requirements and clean-label standards align with craft soda positioning. FDA natural flavor claim uncertainty extends reformulation timelines for this channel's documentation demands.
- Gourmet Retailers:Whole Foods and comparable banners anchor premium foodservice account expansion. Early movers in San Diego and Sacramento sub-markets capture shelf space before national brand presence solidifies.
Specialty stores anchor current revenue concentration. Online retailers show the steepest expansion trajectory through subscription infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium foodservice buyers and sugar-avoidant consumers cluster in coastal metropolitan corridors where municipal beverage regulations and FDA disclosure mandates shape local competitive dynamics. Regional producers leverage localized distribution footprints to navigate patchwork compliance costs. Demand density tracks urban income concentration and health-conscious demographic weighting.
United States
California's metropolitan corridors anchor the densest craft soda demand clusters, with Los Angeles and San Francisco gourmet retailers maintaining dedicated shelf space for cane-sugar alternatives. FDA added-sugar disclosure rules and proposed state-level sugar-tax frameworks accelerate reformulation toward lower-calorie botanical blends. San Diego and Sacramento sub-markets show underpenetrated placement relative to Los Angeles density, creating first-mover opportunities for regional producers.
Canada
Health-conscious consumers in Toronto and Vancouver metropolitan areas drive trial rates for herbal and adaptogen-infused variants. Health Canada's natural health product regulations intersect with food and beverage labeling standards, creating dual compliance pathways for functional positioning claims. British Columbia's urban centers cluster demand for glass-bottle heritage presentations aligned with environmental messaging priorities.
Mexico
Mexico City metropolitan area consumers exhibit growing rejection of mass-market high-fructose corn syrup formulations in favor of cane-sweetened alternatives. The country's national consumer protection agency enforces front-of-package warning label requirements that pressure reformulation toward reduced-sugar profiles. Guadalajara and Monterrey sub-markets show emerging placement in premium foodservice accounts catering to younger demographic trial behavior.
United Kingdom
London and Southeast England concentrate demand for botanical-infused and heritage-recipe craft sodas in specialty retail channels. The UK's soft drinks industry levy imposes tiered taxation by sugar content, forcing cane-sugar producers toward reduced-calorie reformulation or premium pricing acceptance. Manchester and Birmingham metropolitan areas show expanding farmers market and direct-to-consumer channel participation.
Germany
Bavaria and North Rhine-Westphalia anchor craft soda demand among consumers seeking alternatives to conventional carbonated beverages. Germany's Federal Ministry of Food and Agriculture enforces strict natural flavor claim documentation requirements that extend reformulation timelines. Berlin-Brandenburg metropolitan corridor shows concentrated specialty store placement with flexible 90-day assortment cycles replacing traditional annual planograms.
Craft Soda Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented shelf-space allocation in specialty retail and foodservice accounts. The vendor base spans heritage-formulation specialists, customizable-label platforms, and botanical-sourcing concentrators with divergent margin structures. Three archetypes dominate: direct-engagement digital natives, ginger-root sourcing specialists, and glass-bottle heritage anchors. Competitive moves concentrate on localized distribution footprint expansion and aluminum can format integration to capture e-commerce share.
Within the heritage-formulation tier, Boylan Bottling Co and Appalachian Brewing Co occupy positions emphasizing traditional carbonation methods and nostalgic packaging presentation. Jones Soda Co exemplifies the direct-engagement archetype through customizable label infrastructure that enables recurring revenue models bypassing traditional retail slotting fees. Reed's, Inc. anchors the botanical-sourcing specialist position with concentrated ginger-root supply relationships that expose the archetype to climate-driven input volatility.
| Leading Market Players |
|---|
| SIPP eco beverage co. Inc. |
| Crooked Beverage Co. |
| Jones Soda Co |
| Q Drinks |
| Gus |
| Reed's, Inc. |
| Appalachian Brewing Co |
| The Original Craft Soda Company |
| Boylan Bottling Co |
| Others |
Cost & Logistics Intelligence
Undercapacity in Pacific Northwest ginger-root processing facilities is compressing supplier margins while amplifying pricing power for cane-sugar extractors with secured tropical contracts. This utilization asymmetry forces craft soda producers toward dual-sourcing strategies that reshape both input cost structures and finished-goods pricing tiers.
Pricing Analysis
Cost-plus contracts indexed to ICE cane sugar futures dominate procurement agreements for mid-volume producers. Three-tier pricing structure across premium glass-bottle, standard aluminum-can, and economy PET formats separates heritage positioning from mass-market accessibility. Pricing pressure stems from FDA added-sugar disclosure compliance costs that divert R&D budgets toward label redesign. Foodservice accounts exhibit lowest price sensitivity due to menu-margin absorption, while convenience store channels face acute pressure from high-fructose corn syrup alternatives.
Supply Chain Analysis
Extended payment terms from California specialty retailers are straining working capital for sub-50,000-unit producers dependent on seasonal ginger-root harvests. Supply concentration in Peru, India, and Indonesia for botanical extracts creates vulnerability to El Niño-driven crop failures. Glass bottle sourcing rests on Midwestern sand-to-furnace infrastructure with limited alternative suppliers. Distribution runs through localized cold-chain networks in Seattle, Portland, and Los Angeles metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-consumer subscription infrastructure represents the fastest-expanding service-attach layer, outpacing core product revenue growth as customizable label platforms lock in recurring purchase cycles.
For Market Incumbents: Insulate heritage glass-bottle positioning through exclusive sourcing agreements with Peruvian ginger-root cooperatives before climate volatility disrupts concentrated supply. Secure aluminum can line capacity in California's Central Valley to preempt national brand e-commerce encroachment. FDA natural flavor claim uncertainty demands accelerated legal team investment to compress reformulation timelines.
For New Entrants and Emerging Players: Establish a beachhead in San Diego and Sacramento metropolitan sub-markets where gourmet retailer shelf space remains underpenetrated relative to Los Angeles density. Target herbal-adaptogen variants for wellness-positioned consumers in California's health-conscious corridors. Launch through farmers market direct engagement to bypass slotting fee barriers and capture immediate consumer feedback loops.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across aluminum canning infrastructure as shared-equipment cooperatives emerge in Pacific Northwest urban clusters. Five-to-ten year viability favors producers with backward-integrated botanical extraction capabilities. Watch municipal sugar-tax enactment velocity in California state legislature as the critical demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Botanical Extraction Backward Integration | Supercritical CO2 deployment in California standardizes FDA-compliant natural flavor documentation. |
| Direct-to-Consumer Subscription Launch | Jones Soda's customizable label infrastructure provides template for recurring revenue bypassing retail slotting. |
| Aluminum Can Format Expansion | Lightweight formats capture e-commerce share where glass shipping economics constrain adoption. |
| San Diego-Sacramento Corridor Penetration | Underpenetrated gourmet retail placement offers first-mover shelf space before national brand presence. |
| Adaptogen-Infused Product Line Extension | Yerba mate and turmeric variants attract trial from health-conscious younger demographics in California. |
Research Approach
The analysis maps cola, root beer, ginger ale, cream soda, fruit-flavored, and herbal sub-sectors, each validated through primary interviews with craft soda brand managers, specialty store category buyers, Pacific Northwest distribution channel partners, and botanical extract procurement leads. Secondary sources include FDA guidance documents on natural flavor claims, state-level sugar-tax legislative records, Nielsen retail audit data for California metropolitan corridors, and SEC filings from publicly traded beverage companies. Bottom-up volume triangulation across production run sizes converges with top-down value estimates from gourmet retail channel markups.
Assumptions held fixed across the projection horizon include continued FDA enforcement of added-sugar disclosure rules, no federal preemption of municipal beverage regulations, and stable cane sugar futures volatility within historical bands. Segmentation dimensions modeled encompass product type, flavor profile, packaging format, and distribution channel with regional regulatory cluster overlays. CAGRs derive from logistic growth curve fitting to historical shipment data with elasticity adjustments for sugar-tax incidence. Forecast inputs incorporate Pacific Northwest urban population density trends and specialty store 90-day placement cycle adoption rates.
Stress conditions across El Niño harvest disruption severity, California state sugar-tax enactment timing, and aluminum tariff rate fluctuations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory trajectory and consumer preference evolution. Macroeconomic recession, federal preemption of local beverage taxes, or breakthrough clean-label sweetener technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Caffeinated Beverage Market
Beverages
Europe Bottled Water Processing Market
Beverages
Wellness Water Market
Beverages
Germany Probiotic Drinks Market
Beverages
Europe Coconut Water Market
Beverages
Indonesia Bottled Water Market
Beverages
Water Bottle Market
Beverages
Grab and Go Bottles Market
Beverages
Dairy Based Beverages Market
Beverages
Asia-Pacific Bottled Water Market
Beverages
Whole Grain Drinks Market
Beverages
Drinking Water Market
Beverages
Birch Water Market
Beverages
Cold Pressed Juice Market
Beverages
Latin America Sports and Energy Drinks Market
Beverages
Sparkling Water Machine Market