
 North America Clean Label Ingredient Market | 2026-2036
North America Clean Label Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
North America Clean Label Ingredient Market Analytics
Retail grocery shelf-space allocation is tilting toward transparency-forward brands, forcing reformulation cycles across packaged food portfolios. Cargill, Incorporated leverages its North American agricultural supply base to secure non-GMO raw material streams. Kerry Group plc anchors its position through specialized clean-label taste-modulation technologies. Ingredion Incorporated competes by extending its specialty ingredient portfolio into organic starch derivatives.
Clean label ingredients exclude artificial additives, synthetic preservatives, and genetically modified organisms, typically comprising plant-derived extracts, minimally processed compounds, and certified organic substances with full supply-chain traceability. These inputs serve commercial food manufacturing by enabling transparent ingredient declarations that meet retailer procurement standards and consumer scrutiny. Natural preservatives occupy the largest margin pool among product types due to technical complexity in shelf-life extension without synthetic chemistry. Beverage applications represent the fastest-growing segment as sparkling water and functional drink brands eliminate artificial colorants and flavor carriers. Powder formulations dominate manufacturing workflows for their stability in dry-mix processing and extended distribution logistics.
The FDA governs ingredient safety assessments and labeling accuracy under the Federal Food, Drug, and Cosmetic Act, while USDA administers organic certification standards that restrict synthetic inputs. Health Canada and PMRA coordinate cross-border additive approvals that shape North American supply-chain integration for dual-market suppliers. Stakeholders must monitor evolving enforcement priorities around natural claim substantiation and prepare for tightened substantiation requirements that could disqualify existing product positioning.
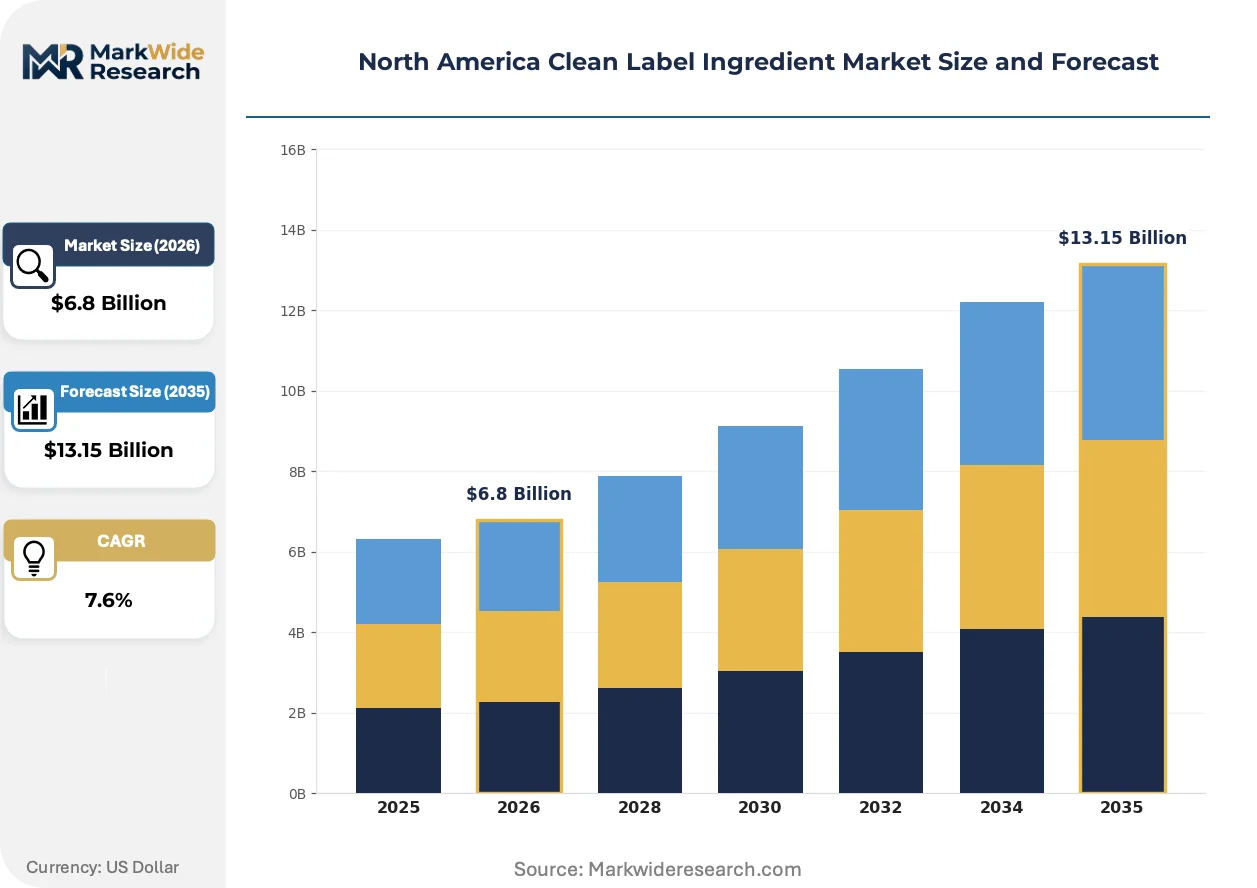
Market Dynamics
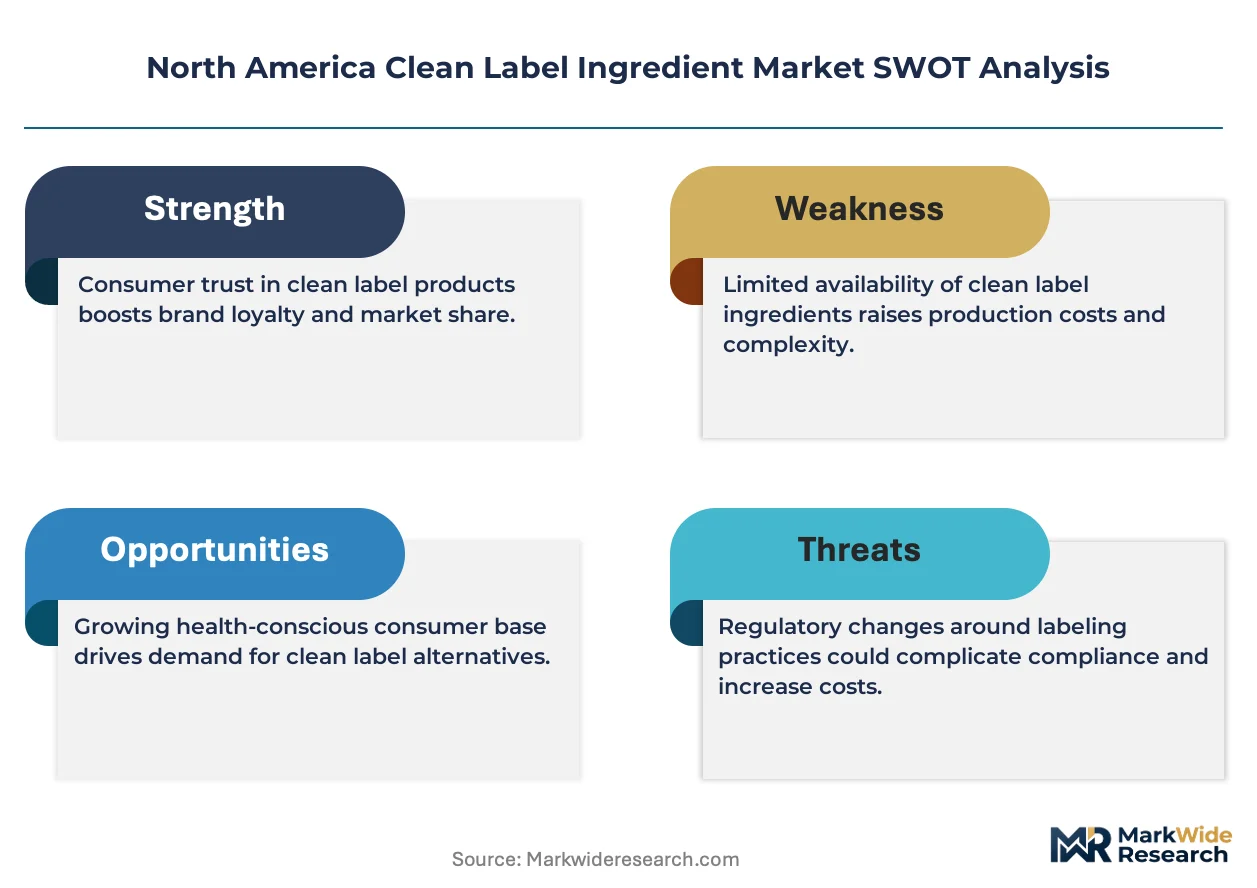
Retail procurement standards and USDA organic certification mandates are compressing formulation timelines across North American packaged food and beverage manufacturing, forcing ingredient suppliers to restructure supply-chain documentation and accelerate clean-label R&D cycles.
Growth Catalysts
- FDA Labeling Transparency Mandates:Updated disclosure requirements under the Federal Food, Drug, and Cosmetic Act compel manufacturers to eliminate artificial additives from ingredient declarations, expanding addressable demand for certified clean-label inputs.
- Carbonated Beverage Reformulation:Sparkling water and functional drink producers are eliminating synthetic colorants and flavor carriers, creating concentrated demand pull for natural alternatives with equivalent stability profiles.
- California Innovation Corridor Concentration:Health food brands and natural product startups clustering near formulation labs and venture capital in the San Francisco-Los Angeles corridor generate accelerated product development cycles and early-adoption revenue streams.
Market Restraints
- Organic Raw Material Cost Volatility:Non-GMO corn and soy supply fluctuations in the US Midwest create input price instability that compresses margin structures for starch derivative and protein ingredient producers.
- Natural Preservative Technical Limitations:Plant-derived antimicrobial compounds demonstrate shorter efficacy windows and narrower pH stability ranges compared to synthetic alternatives, restricting application in ambient-stable packaged goods.
- Cross-Border Regulatory Friction:Divergent Health Canada and FDA approval timelines for novel natural additives create dual-market compliance burdens that delay product launches and increase registration expenditures.
Strategic Opportunities
- USDA Organic Certification Expansion:Tightened federal organic standards are disqualifying incumbent suppliers with incomplete supply-chain documentation, creating white space for fully traceable ingredient providers.
- Powder Formulation Manufacturing Scale-Up:Dry-mix stability advantages in extended distribution logistics position spray-dried and agglomerated clean-label ingredients for penetration into club retail and e-commerce channels.
- Functional Beverage Convergence:The intersection of clean-label requirements with adaptogen and nootropic ingredient demand creates formulation partnerships between natural extract suppliers and beverage innovation labs.
Industry Challenges
- Supply-Chain Documentation Talent Scarcity:Food science professionals with dual expertise in organic certification compliance and blockchain traceability systems command premium compensation that strains mid-tier supplier staffing budgets.
- Legacy Equipment Retrofit Requirements:Transitioning from synthetic to natural preservative systems demands capital-intensive clean-in-place protocol modifications and segregated production line installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Clean Label Ingredient Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Preservatives, Organic Flavorings, Non-GMO Colors, Clean Label Emulsifiers Application: Beverages, Bakery Products, Dairy Alternatives, Snack Foods End User: Food Manufacturers, Beverage Producers, Retailers, Health Food Brands Form: Powder, Liquid, Granule, Concentrate |
| Companies Covered | Ingredion Incorporated, Tate & Lyle PLC, International Flavors & Fragrances Inc. (IFF), Kerry Group plc, Cargill, Incorporated, Archer Daniels Midland Company, DSM-Firmenich AG, Sensient Technologies Corporation, Corbion N.V., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Clean Label Ingredient Market Evolving Landscape
Enzymatic modification processes and fermentation-derived ingredient platforms are restructuring competitive advantage in natural taste modulation and texture enhancement, compressing the performance gap between clean-label and conventional synthetic alternatives.
Precision fermentation for natural flavor compounds is rendering obsolete extraction-dependent supply chains vulnerable to agricultural yield variability and geographic concentration risk. Beverage manufacturers in Texas and Colorado are integrating these bioprocessed inputs at pilot scale, with commercial volumes projected to displace 15-20% of botanical extract procurement within high-margin premium segments.
Health Canada and PMRA coordination on cross-border additive approvals is tightening natural claim substantiation requirements, forcing dual-market suppliers to maintain parallel documentation systems. The harmonization process disadvantages smaller ingredient firms lacking regulatory affairs infrastructure, consolidating procurement relationships toward established North American suppliers with dedicated compliance teams.
Direct supplier-retailer partnerships are replacing traditional distribution intermediaries in clean-label ingredient procurement. Kroger and Whole Foods Market buyers now engage formulation labs and ingredient startups through contracted development agreements, bypassing conventional broker networks. This channel compression concentrates volume with vertically integrated suppliers capable of co-development services, most visible in California and Pacific Northwest retail clusters.
North America Clean Label Ingredient Market Segmentation
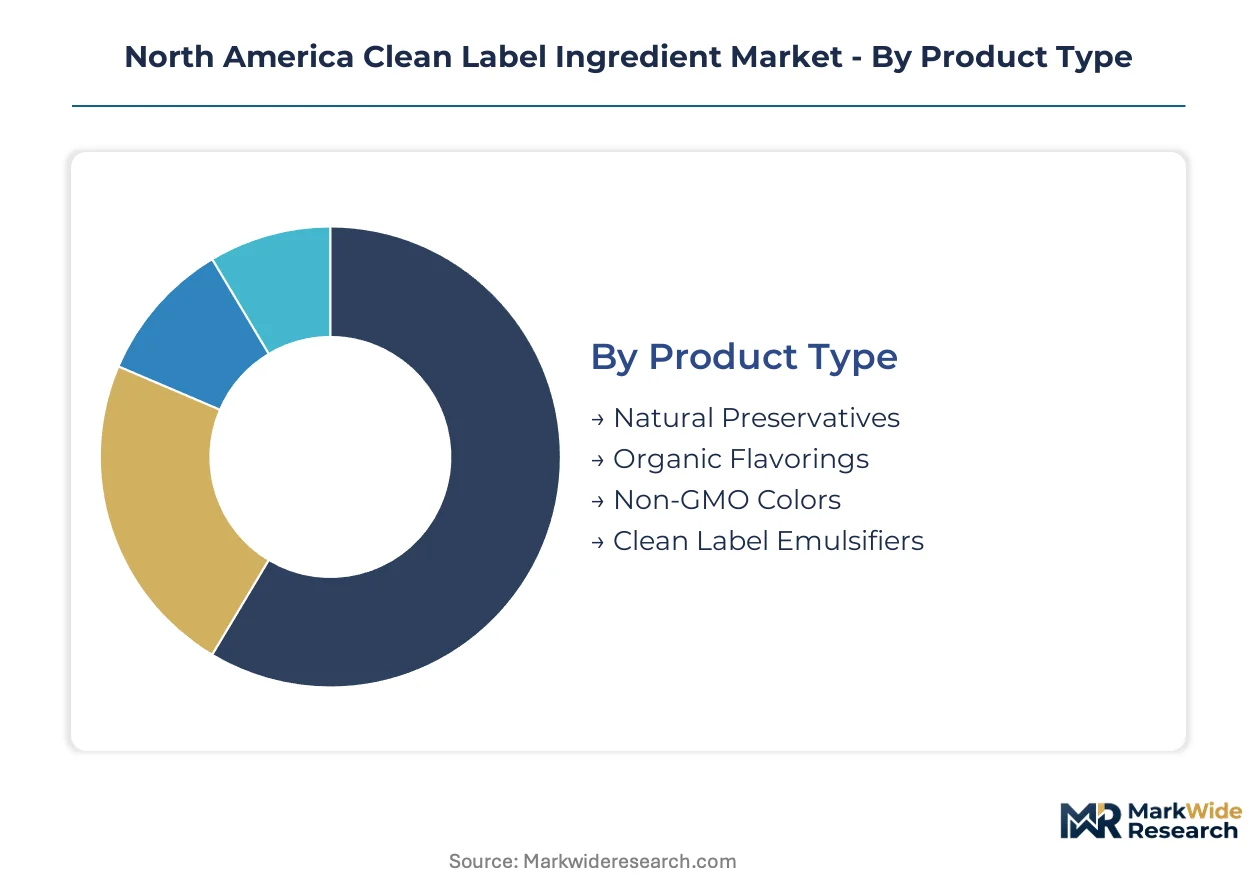
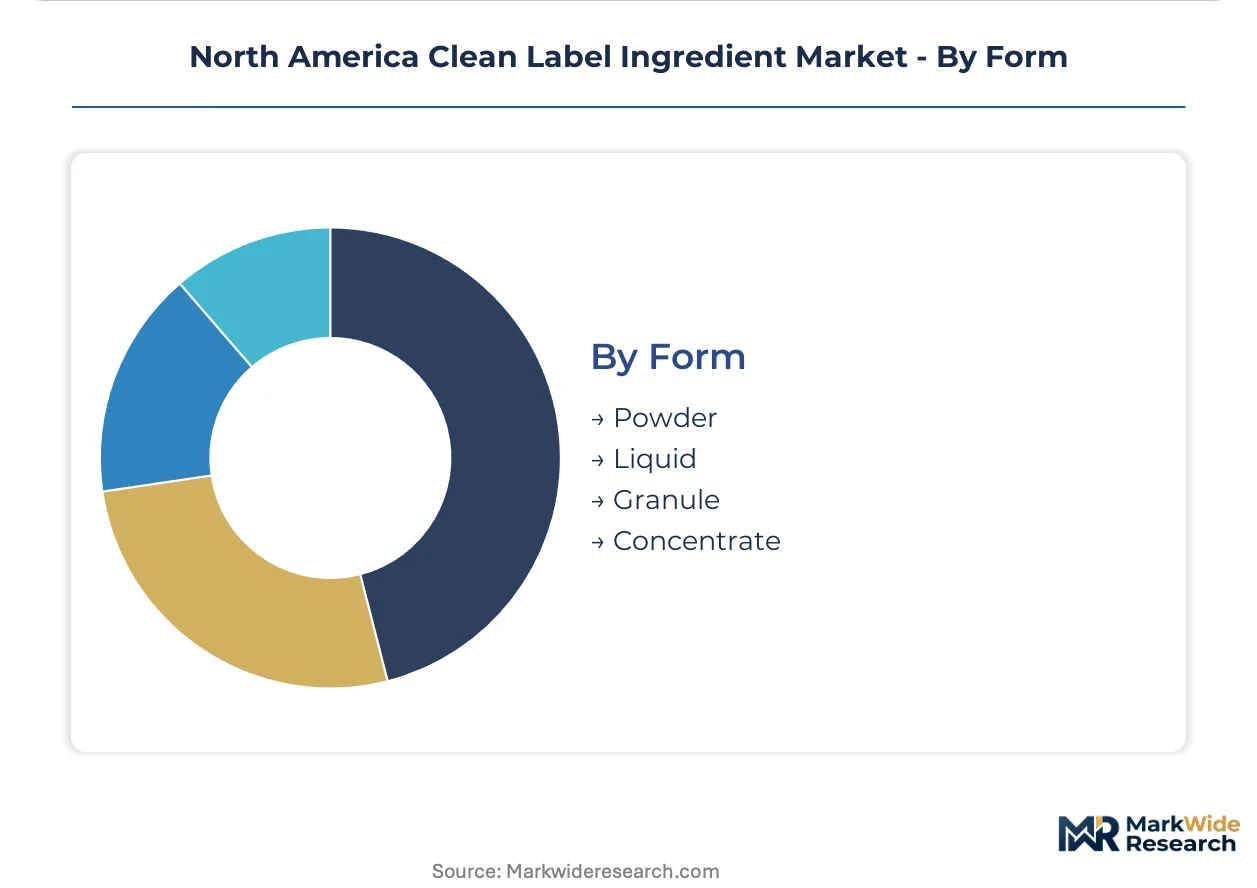
Clean label ingredient procurement varies dramatically across formulation requirements, with powder stability driving long-term contracts while liquid concentrates demand just-in-time logistics. Understanding segment velocity helps suppliers align inventory and R&D investments.
Product Type:
Natural preservatives command the longest development cycles due to efficacy validation requirements, while clean label emulsifiers turn over fastest as beverage brands iterate texture profiles quarterly.
- Natural Preservatives:Plant-derived antimicrobial compounds including rosemary extract, cultured dextrose, and vinegar derivatives replace synthetic benzoates and sorbates. California sparkling water brands and Texas refrigerated beverage facilities drive demand for pH-stable variants that withstand ambient distribution without synthetic chemistry.
- Organic Flavorings:Steam-distilled and cold-pressed botanical extracts certified under USDA organic standards. Pacific Northwest kombucha producers and Colorado functional beverage startups concentrate procurement for adaptogen-infused variants requiring full supply-chain documentation.
- Non-GMO Colors:Anthocyanin, carotenoid, and chlorophyll-based colorants from beet, turmeric, and spirulina sources.
- Clean Label Emulsifiers:Sunflower lecithin and acacia gum alternatives to modified food starch.
Natural preservatives anchor the volume base while clean label emulsifiers gain share at the steepest rate.
Application:
Reformulation intensity separates high-velocity beverage applications from stable bakery procurement patterns.
- Beverages:Sparkling water, functional drinks, and plant-based milks eliminate artificial colorants and flavor carriers. FDA disclosure mandates under the Federal Food, Drug, and Cosmetic Act compress development timelines as brands race to meet retailer transparency standards before shelf resets.
- Bakery Products:Clean label bread, pastry, and cake formulations replace chemical dough conditioners and synthetic preservatives. Midwest commercial bakeries serving Kroger and Albertsons banners drive volume for enzyme-based conditioning systems and cultured wheat starch.
- Dairy Alternatives:Oat, almond, and coconut milk applications requiring emulsion stability without carrageenan.
- Snack Foods:Extruded and popped products replacing artificial flavors and MSG.
Beverages command the steepest expansion trajectory while bakery products provide the stable volume foundation.
End User:
Procurement sophistication tiers separate multinational food manufacturers from agile health food startups.
- Food Manufacturers:Large-scale packaged goods producers with dedicated clean-label R&D facilities and direct supplier relationships. Cargill and Ingredion maintain captive procurement teams that bypass traditional distribution channels.
- Beverage Producers:Sparkling water and functional drink specialists with accelerated formulation cycles. Colorado and Texas facilities pilot precision-fermented ingredients at commercial scale.
- Retailers:Kroger and Whole Foods Market buyers engaging formulation labs through contracted development agreements.
- Health Food Brands:California innovation corridor startups clustering near venture capital and formulation labs.
Food manufacturers anchor procurement volume while health food brands expand most quickly.
Form:
Logistics economics favor powder stability for extended distribution, while liquid concentrates serve regional just-in-time production.
- Powder:Spray-dried and agglomerated ingredients with superior stability in dry-mix processing and extended distribution logistics. Club retail and e-commerce channels concentrate demand for shelf-stable formats that withstand temperature fluctuations.
- Liquid:Ready-to-use concentrates and extracts requiring refrigerated transport. Pacific Northwest beverage co-packers favor liquid formats for rapid batch adjustment and reduced hydration time.
- Granule:Agglomerated particles for controlled dissolution in beverage applications.
- Concentrate:High-potency extracts for premium functional beverage formulations.
Powder formulations dominate volume while liquid concentrates climb fastest in regional production hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach and Los Angeles rail intermodal complex underwrites California's dominance in clean-label ingredient distribution, connecting Midwest agricultural supply basins to Pacific Rim export markets and domestic retail channels.
United States
Midwest corn and soy processing facilities supply non-GMO raw material streams to national formulation networks. FDA labeling transparency mandates under the Federal Food, Drug, and Cosmetic Act compress development timelines for beverage reformulation. California's San Francisco-Los Angeles innovation corridor concentrates venture-backed natural product startups near formulation labs.
Canada
Prairie provinces anchor organic grain and pulse production for cross-border ingredient supply. Health Canada and PMRA coordinate additive approval timelines that shape dual-market compliance strategies. Toronto-Waterloo food tech clusters host precision fermentation pilots serving North American beverage manufacturers.
Mexico
Central highlands agricultural zones expand organic avocado and tropical fruit extract capacity for natural flavoring inputs. Mexico's federal consumer protection agency enforces labeling standards that align with US disclosure requirements. Querétaro and Guanajuato industrial corridors attract co-manufacturing investment from US clean-label brands.
North America Clean Label Ingredient Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain, supplying discrete functional ingredients to formulation houses. The North American market structures around agricultural processors with captive raw material access, specialty ingredient houses with taste-modulation IP, and fermentation technology platforms. Three archetypes dominate: Midwest grain processors with non-GMO supply chain control, European-headquartered taste and texture specialists, and biotech-enabled precision fermentation startups. Capacity expansion and strategic partnerships constitute the primary competitive vectors as players secure organic certification coverage and co-development relationships with retail banners.
Within the agricultural processing tier, Cargill, Incorporated and Archer Daniels Midland Company represent integrated supply chain archetypes with Midwest raw material proximity. Ingredion Incorporated occupies a position among specialty starch and texture ingredient providers. Kerry Group plc exemplifies the taste-modulation specialist model with dedicated clean-label R&D infrastructure.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Tate & Lyle PLC |
| International Flavors & Fragrances Inc. (IFF) |
| Kerry Group plc |
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| DSM-Firmenich AG |
| Sensient Technologies Corporation |
| Corbion N.V. |
| Others |
Value Network & Pricing Analysis
Undercapacity in Midwest non-GMO corn processing facilities drives supplier prioritization toward long-term contract holders, compressing spot-market availability and amplifying price volatility for mid-tier buyers without secured offtake agreements.
Pricing Analysis
Volume-discount tiering structures separate USDA-certified organic inputs from conventional non-GMO grades, with certification premiums widening as FDA disclosure mandates tighten. Price differentiation hinges on supply-chain documentation completeness and organic certification tier, with California beverage producers least price-sensitive due to venture-backed funding structures while Midwest commercial bakeries face acute cost compression. Pricing pressure intensifies in liquid concentrate formats as refrigerated logistics costs escalate.
Supply Chain Analysis
Export-control regimes on precision fermentation equipment constrain technology transfer to Canadian and Mexican facilities, limiting North American capacity expansion for bioprocessed natural flavor compounds. Geographic supply concentrates in the United States Midwest for corn and soy derivatives, California for botanical extraction, and Canada for organic grain and pulse inputs. Raw material dependencies include non-GMO corn streams, organic soy protein isolates, and fermentation feedstocks. Supply chain risk centers on single-source vulnerability for specialized organic certification auditors. Distribution runs through direct supplier-retailer partnerships bypassing traditional broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean label ingredient procurement is evolving into a service-attach opportunity as co-development partnerships and blockchain traceability subscriptions generate recurring revenue streams expanding faster than commodity ingredient sales.
For Market Incumbents: Insulate margin structures by securing captive organic corn processing capacity in Iowa and Illinois, and accelerate investment in fermentation-derived taste modulation platforms to preempt displacement by biotech-enabled startups. Vertical integration into supply-chain documentation software creates defensive moats against emerging traceability specialists.
For New Entrants and Emerging Players: Pursue white-space opportunities in precision-fermented natural preservatives for ambient-stable packaged goods, where technical limitations have kept synthetic alternatives dominant. The Pacific Northwest kombucha and functional beverage corridor offers the most penetrable entry point, with co-manufacturer partnerships providing the optimal go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across precision fermentation platforms as equipment costs decline and yield efficiencies improve, compressing the funding gap between pilot and commercial scale. Long-term viability favors acquisition targets with established USDA organic certification infrastructure and direct retailer relationships. The signal to watch is Health Canada-FDA harmonization progress on novel natural additive approvals.
| Strategic Initiative | Industry Significance |
|---|---|
| USDA Organic Certification Expansion | Tightened federal standards disqualify incumbent suppliers with incomplete documentation, creating white space for fully traceable providers. |
| Precision Fermentation Scale-Up | Bioprocessed natural flavor compounds displace extraction-dependent supply chains vulnerable to agricultural yield variability. |
| Direct Supplier-Retailer Partnerships | Kroger and Whole Foods Market buyers bypass conventional broker networks through contracted development agreements. |
| Supply-Chain Documentation Investment | Blockchain traceability systems command premium talent compensation, consolidating advantage toward well-capitalized players. |
| Powder Formulation Manufacturing Expansion | Spray-dried and agglomerated ingredients penetrate club retail and e-commerce channels through superior stability. |
Research Methodology
A spread of perspectives from ingredient procurement directors at beverage manufacturers, regulatory affairs specialists at agricultural processors, formulation scientists at contract development labs, and category buyers at retail banners converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through FDA labeling guidance documents, USDA organic certification databases, Health Canada additive approval records, and SEC filings from publicly traded ingredient suppliers. Bottom-up segment sizing triangulated against top-down market estimates.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeled by product type, application, end-user sophistication tier, and form factor. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology adoption curves. Forecast inputs incorporated organic acreage expansion rates, precision fermentation yield improvement curves, and retailer procurement standard evolution.
Sensitivities concentrate around FDA enforcement priorities for natural claim substantiation and Health Canada-PMRA harmonization timelines. Forecasts reflect documented assumptions about organic certification adoption rates and fermentation technology cost curves. Material shifts in cross-border regulatory coordination or Midwest organic grain supply would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
South Africa Food Additives Market
Food Additives and Ingredients
Food Grade Magnesium Derivatives Market
Food Additives and Ingredients
Food Clarifiers Market
Food Additives and Ingredients
India Food Colorants Market
Food Additives and Ingredients
North America Food Coating Ingredients Market
Food Additives and Ingredients
PVPP Beer Stabilizer Market
Food Additives and Ingredients
Food Grade Butyric Acid Market
Food Additives and Ingredients
Egypt Food Enzymes Market
Food Additives and Ingredients
Mediterranean Sourdough Starter Cultures Market
Food Additives and Ingredients
Pet Food Emulsifier Market
Food Additives and Ingredients
Noodles Preservatives Market
Food Additives and Ingredients
Food Grade Sodium Hydroxide Market
Food Additives and Ingredients
North America Microencapsulation Market
Food Additives and Ingredients
Global Food Grade Calcium Chloride Market
Food Additives and Ingredients
Transglutaminase Market
Food Additives and Ingredients
United States Food Additives Market