
 Egypt Food Enzymes Market | 2026-2036
Egypt Food Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Food Enzymes Market Insights
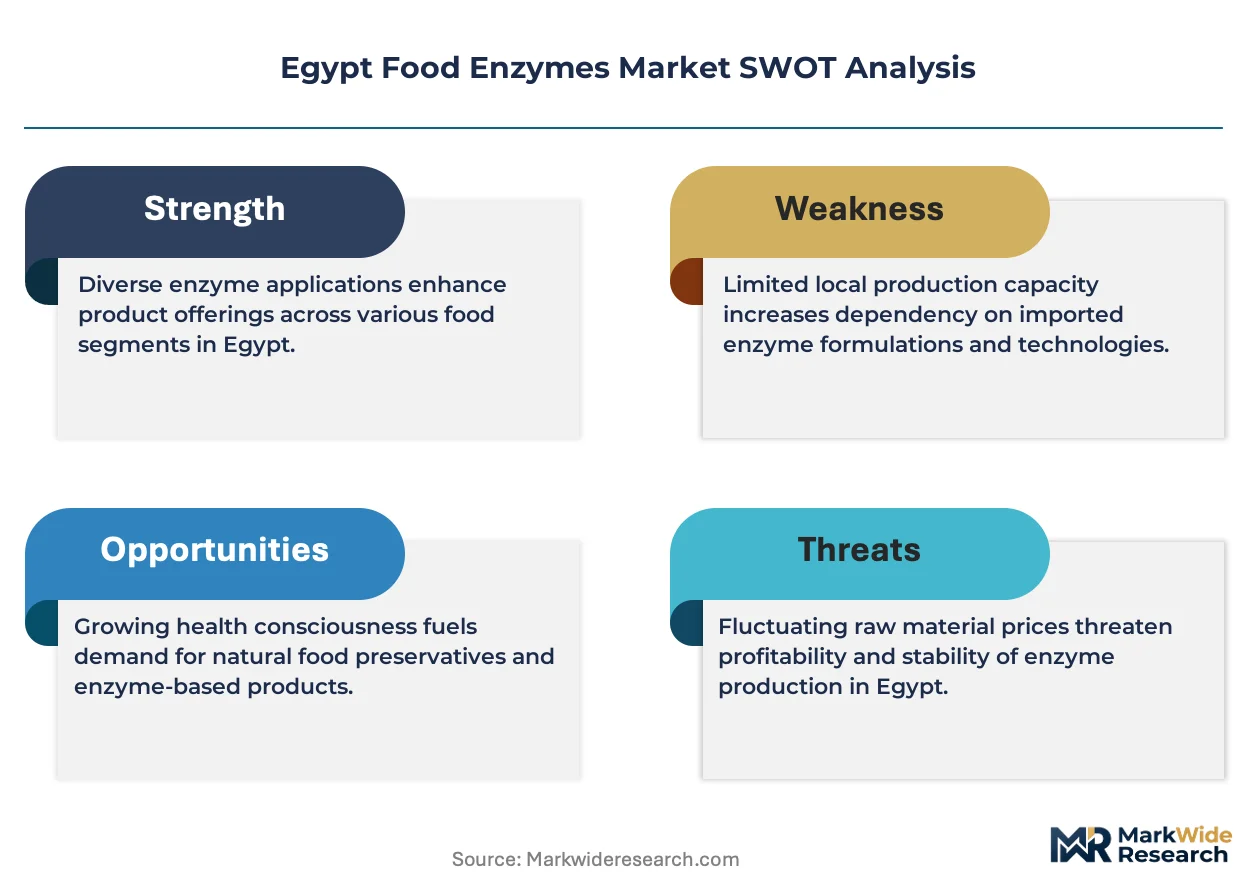
Egypt's National Food Safety Authority (NFSA) alignment with Codex Alimentarius standards is restructuring enzyme approval pathways for imported biotech ingredients. Novozymes A/S leverages its microbial fermentation platform to dominate specialty amylase supply for flatbread producers. Chr. Hansen Holding A/S anchors its position through dairy culture-enzyme bundles tailored to Egyptian white cheese applications. BASF SE competes via lipase formulations optimized for local shortening and margarine processors.
Food enzymes comprise protein-based biocatalysts—typically operating at 30–70°C and pH 4.0–8.0—that accelerate specific biochemical reactions in food matrices without becoming consumed in the process. Their primary commercial purpose spans starch hydrolysis, protein modification, lipid esterification, and cell wall degradation to enhance processing efficiency, sensory profiles, and shelf stability. Amylase commands the largest product type share through widespread deployment in Egyptian baladi bread production, while lipase exhibits the fastest structural growth as confectionery and dairy fat modification applications expand. Microbial source enzymes lead volume flows due to cost-scalable fermentation and consistent batch uniformity, though fungal-derived variants capture premium positioning in clean-label bakery segments.
NFSA oversight intersects with Ministry of Health and Population import licensing requirements, creating dual compliance layers for enzyme formulations entering Egyptian ports. The Egyptian Organization for Standardization and Quality (EOS) mandates label disclosure of enzyme origins, pressuring suppliers toward microbial and plant-sourced certifications. Stakeholders must monitor NFSA's pending biotechnology guidance for genetically modified production strains, as this determination will reshape supplier qualification criteria and local formulation strategies.
Market Dynamics
NFSA's pending biotechnology guidance for genetically modified production strains is forcing enzyme suppliers to requalify formulation strategies before the regulatory window closes. This single policy trajectory concentrates more strategic uncertainty than any demand fluctuation or competitive maneuver currently visible in Egyptian food processing.
Growth Catalysts
- Baladi Bread Modernization:Industrial bakeries in Greater Cairo are replacing chemical conditioners with fungal amylase to meet clean-label export requirements. The shift pulls volume through microbial fermentation supply chains.
- White Cheese Processing Expansion:Dairy culture-enzyme bundles tailored to Egyptian Domiati and Feta variants are penetrating Alexandria's dairy clusters. Lipase-modified fat systems reduce ripening time by half.
- Confectionery Fat Modification:Shortening and margarine processors in 10th of Ramadan City are adopting lipase-catalyzed interesterification to eliminate trans-fat labeling liabilities.
Market Restraints
- Import Licensing Friction:Ministry of Health and Population dual-layer clearance adds 6-12 weeks to enzyme formulation port entry, compressing working capital cycles for distributors.
- Microbial Source Concentration:Bulk fermentation capacity concentrates with Asian contract manufacturers, exposing Egyptian formulators to shipping cost volatility and currency mismatch.
- Thermal Stability Ceiling:Fungal-derived amylase variants lose efficacy above 65°C, limiting deployment in high-temperature extrusion applications for snack manufacturers.
Strategic Opportunities
- Upper Egypt Greenfield Dairy:Sohag and Qena governorates lack localized enzyme blending facilities, creating first-mover advantage for toll-manufacturing partnerships with regional dairy cooperatives.
- NFSA Codex Alignment:The authority's harmonization with Codex Alimentarius enzyme specifications opens pathway for GRAS-status US formulations to bypass redundant safety testing.
- Plant-Sourced Certification:EOS label disclosure mandates are accelerating demand for bromelain and papain alternatives in halal-certified bakery segments.
Industry Challenges
- Fermentation Specialist Scarcity:Industrial microbiology talent pools in Alexandria and Cairo cannot match bioprocess engineering requirements for scaled enzyme production.
- Legacy Dosing Equipment:Small and mid-size bakeries in Delta region operate fixed-speed mixers incompatible with precision enzyme delivery systems, requiring capital retrofit.
- GM Strain Documentation:Suppliers lack batch-level traceability for production organism genetic modification status, blocking NFSA pre-approval submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Food Enzymes Market |
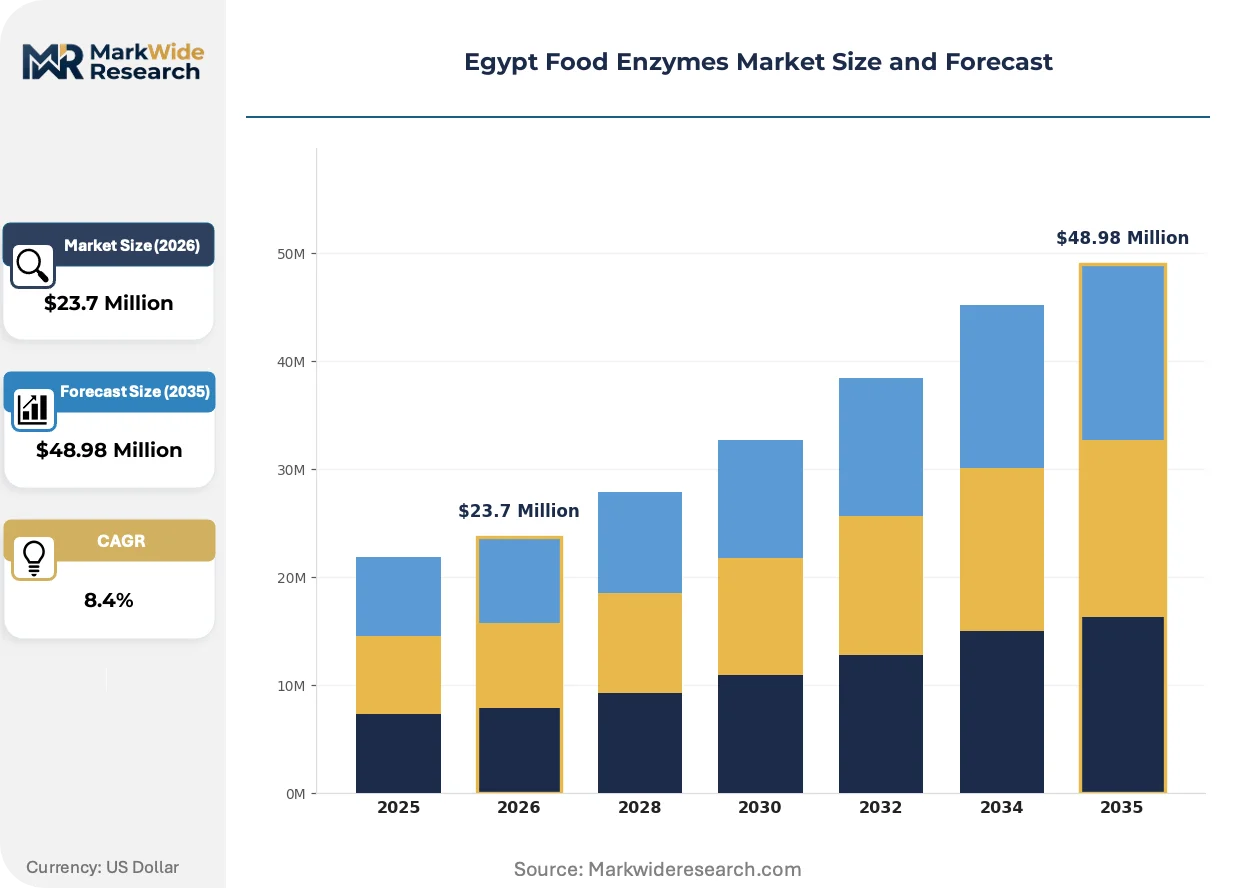
| Market Size in 2026 | $23.7 Million |
| Market Size in 2035 | $48.98 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylase, Protease, Lipase, Cellulase Application: Beverages, Dairy Products, Bakery, Processed Foods Source: Microbial, Animal, Plant, Fungal Distribution Channel: Online, Retail, Distributors, Direct Sales |
| Companies Covered | Novozymes A/S, Chr. Hansen Holding A/S, BASF SE, SUNSON INDUSTRY GROUP CO LTD, AB Enzymes, DuPont de Nemours, Inc., Kerry Group, DSM Nutritional Products, Creative Enzymes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Food Enzymes Market Trends and Innovations
Automation of enzyme dosing and real-time activity monitoring is compressing the technical gap between industrial and artisanal bakery operations. Three convergent developments are restructuring how Egyptian food manufacturers source and deploy biocatalytic systems.
Automated inline enzyme dosing systems are automating the calibration of amylase activity in continuous dough streams. Industrial flatbread producers in Obour City and Badr City are retrofitting existing mixers at pace of 8-12 installations annually. This technology is automating the elimination of over-dosage waste and standardizing crumb structure across multi-shift operations.
NFSA's biotechnology guidance for genetically modified production strains is mandating supplier disclosure of host organism lineage. The policy compresses approval timelines for documented non-GM formulations while extending review periods for undocumented strains. Dairy enzyme bundles face the steepest compliance burden due to recombinant lipase prevalence in global supply.
Clean-label procurement mandates from Egyptian retail chains are rotating volume toward fungal and plant-sourced enzyme certifications. Hypermarket private-label buyers in Cairo and Giza now require EOS-compliant origin disclosure as a condition of supplier qualification. This preference shift is most visible in premium biscuit and wafer segments where export eligibility depends on additive transparency.
Egypt Food Enzymes Market Segmentation
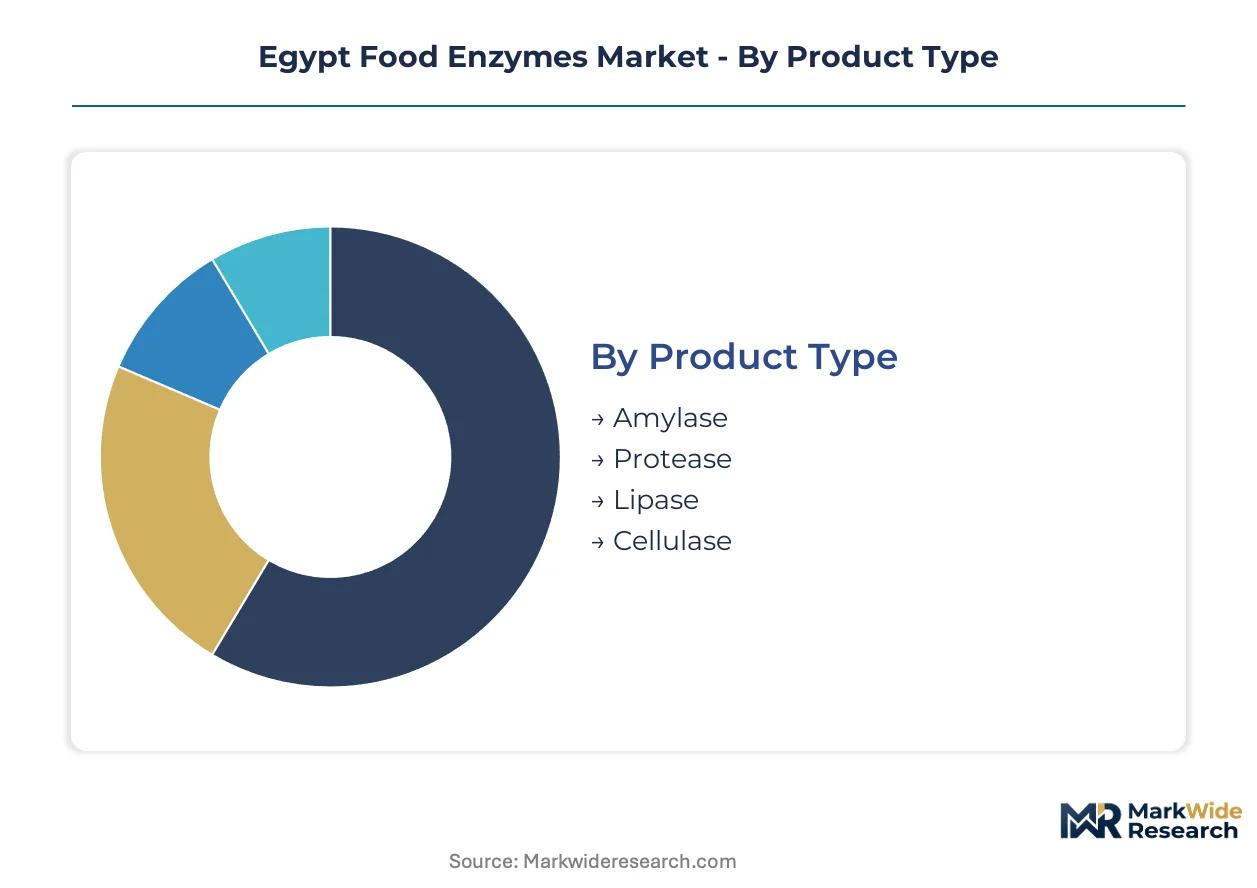
Egypt's food enzyme procurement patterns diverge sharply between industrial-scale processors in Greater Cairo and artisanal producers across the Delta. Segmentation reveals where capital deployment concentrates and which supply channels face regulatory friction under NFSA oversight.
Product Type:
Capital intensity escalates fastest for specialty lipase formulations requiring precision fermentation infrastructure, while commodity amylase runs on depreciated equipment.
- Amylase:Alpha and beta variants hydrolyze starch chains at 60–70°C for dough conditioning. Industrial baladi bread lines in Badr City and Obour City absorb bulk volumes as bakeries retire chemical conditioners. NFSA clean-label alignment accelerates substitution timelines.
- Lipase:Triacylglycerol hydrolases enable interesterification of palm oil fractions for trans-fat elimination. 10th of Ramadan City shortening processors drive demand as export-facing confectionery brands mandate modified-fat certification. Recombinant strain documentation gaps stall some supplier approvals.
- Protease:Endo- and exopeptidases modify protein matrices for texture control in processed meat applications.
- Cellulase:Beta-glucanases degrade plant cell walls for juice clarification and fiber modification in beverage processing.
Amylase absorbs the bulk of installed capacity; lipase is expanding most quickly.
Application:
Customer scale determines enzyme specification tiers, with multinational dairy processors demanding certificate-of-analysis bundles unavailable to small bakeries.
- Bakery:Fungal amylase dominates flatbread production for shelf-life extension and crumb softening. Greater Cairo industrial clusters command bulk procurement through annual tenders tied to NFSA import licensing cycles.
- Dairy Products:Lipase-culture bundles accelerate Domiati and Feta ripening while reducing fat leakage. Alexandria dairy cooperatives drive adoption as white cheese exports to Gulf markets require standardized enzyme documentation.
- Processed Foods:Protease-cellulase blends enhance texture in meat and savory snack matrices.
- Beverages:Pectinase and amylase clarification systems support juice concentration and stability.
Bakery commands the deepest supplier relationships; dairy applications are climbing the fastest as export compliance tightens.
Source:
Certification burden varies dramatically by origin, with microbial strains facing the steepest biotechnology disclosure requirements.
- Microbial:Bacterial and yeast-derived enzymes from submerged fermentation deliver batch consistency at scale. Asian contract manufacturers supply Egyptian formulators, though shipping delays and currency mismatch compress working capital. NFSA GM strain documentation mandates now require host organism lineage disclosure.
- Fungal:Aspergillus and Trichoderma-derived amylase and cellulase capture premium positioning in clean-label bakery segments. Hypermarket private-label buyers in Giza require EOS-compliant origin disclosure as a qualification condition.
- Plant:Bromelain from pineapple and papain from papaya latex serve halal-certified applications where microbial origins face religious scrutiny.
- Animal:Rennet and pepsin extracts persist in traditional cheese-making despite volume erosion to microbial substitutes.
Microbial sources anchor volume flows; fungal certifications are gaining share fastest under clean-label procurement mandates.
Distribution Channel:
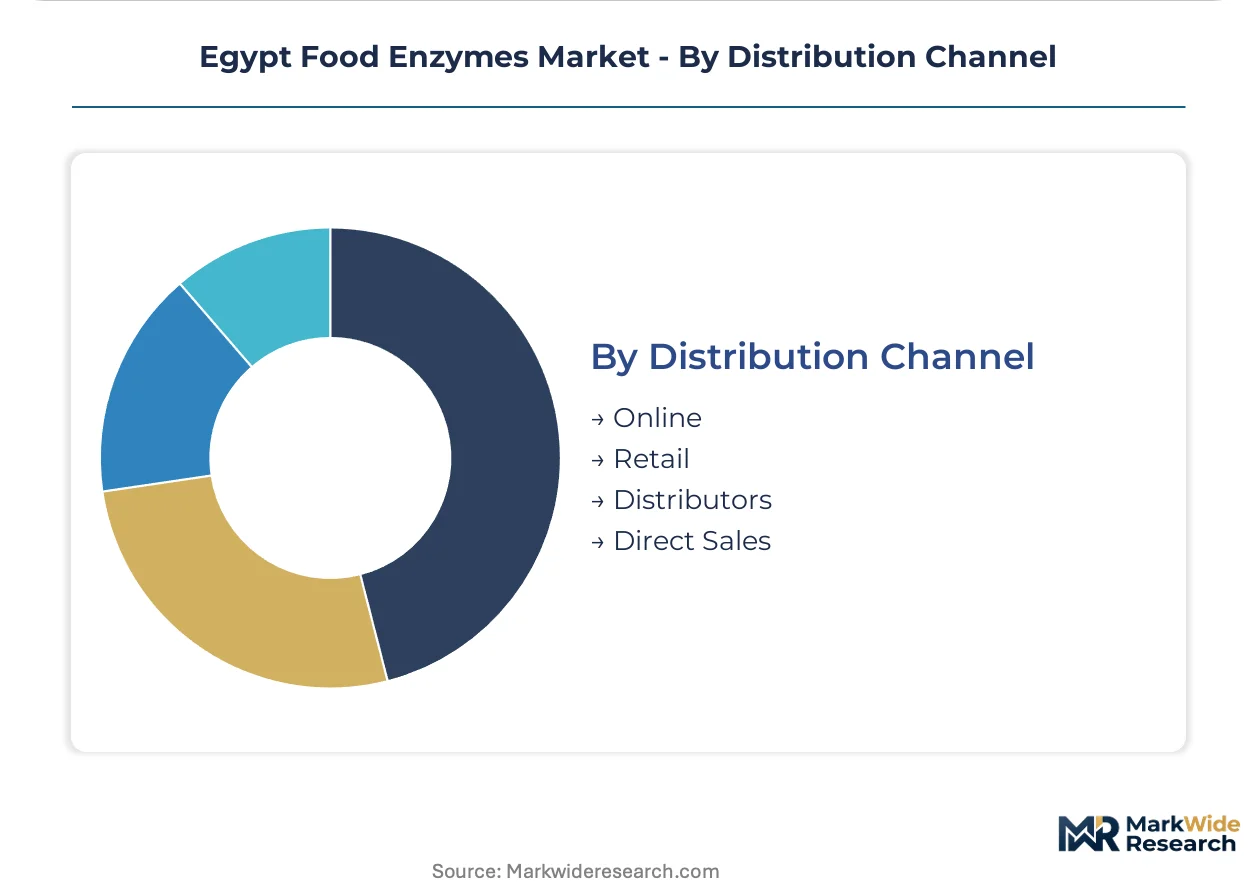
Channel selection correlates with customer technical sophistication and import licensing autonomy.
- Distributors:Local chemical and ingredient houses stock standard amylase and protease grades for mid-size processors. 6-12 week Ministry of Health and Population clearance cycles force distributors to carry 90-day inventory buffers.
- Direct Sales:Novozymes and Chr. Hansen deploy technical service teams for dairy and bakery accounts requiring formulation customization. Direct relationships bypass distributor margins but demand dedicated regulatory affairs staff for NFSA pre-approval.
- Retail:Small-package enzyme blends for artisanal bakers move through Cairo specialty ingredient shops.
- Online:E-procurement platforms serve research institutions and pilot-scale processors with low-volume, high-SKU requirements.
Distributors handle the bulk of tonnage; direct sales channels are expanding most quickly among export-oriented processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt's food enzyme production lags behind consumption, forcing reliance on imported formulations from Asian and European fermentation specialists. Local blending capacity concentrates in Greater Cairo and Alexandria, while Upper Egypt remains entirely import-dependent.
Greater Cairo
Industrial bakeries in Badr City and Obour City absorb bulk amylase volumes for baladi bread modernization. NFSA import licensing cycles synchronize with annual procurement tenders from processing clusters. The 10th of Ramadan City corridor houses shortening manufacturers adopting lipase-catalyzed interesterification for trans-fat elimination.
Alexandria
Dairy cooperatives drive lipase-culture bundle demand for Domiati and Feta cheese exports to Gulf markets. The city's port infrastructure reduces enzyme formulation clearance delays by 2-3 weeks versus Cairo air freight. Local technical service teams from direct-sales suppliers maintain formulation laboratories in the Borg El Arab industrial zone.
Delta Region
Small and mid-size bakeries operate legacy mixing equipment incompatible with precision enzyme dosing systems. Capital retrofit requirements slow fungal amylase adoption despite clean-label procurement pressure from Cairo retail chains. The region's artisanal producers rely on distributor-stocked standard grades with 90-day inventory buffers.
Upper Egypt
Sohag and Qena governorates lack localized enzyme blending facilities, creating toll-manufacturing opportunities for regional dairy cooperatives. Import logistics extend working capital cycles by 4-6 weeks compared to northern governorates. First-mover infrastructure investment would capture unmet demand from greenfield dairy processing expansion.
Suez Canal Zone
Port Said and Ismailia logistics hubs handle transshipment of Asian-sourced microbial enzymes to Red Sea markets. Customs clearance efficiency varies sharply between port authorities, creating arbitrage opportunities for distributors with multi-port licensing. Free zone status attracts regional headquarters for suppliers targeting MENA re-export.
Egypt Food Enzymes Market Competitive Landscape
The competitive structure tilts toward multinational fermentation specialists with established NFSA regulatory affairs capabilities. Market concentration favors players with direct technical service presence over distributor-dependent competitors. Three archetypes dominate: microbial platform specialists, dairy culture-enzyme integrators, and regional toll-blending distributors. Capacity expansion and strategic partnerships represent the primary competitive vectors as suppliers position for biotechnology guidance implementation.
Among microbial platform specialists, Novozymes A/S and DuPont de Nemours, Inc. occupy positions anchored by fermentation scale and enzyme portfolio breadth. Chr. Hansen Holding A/S exemplifies the dairy culture-enzyme integration archetype, while Kerry Group represents the nutrition-ingredient bundling model. SUNSON INDUSTRY GROUP CO LTD and AB Enzymes sit within the cost-optimized supply tier serving price-sensitive bakery and processed food segments. BASF SE, DSM Nutritional Products, and Creative Enzymes each represent distinct specialization vectors spanning lipase formulations, nutritional premix integration, and custom enzyme development respectively.
| Leading Market Players |
|---|
| Novozymes A/S |
| Chr. Hansen Holding A/S |
| BASF SE |
| SUNSON INDUSTRY GROUP CO LTD |
| AB Enzymes |
| DuPont de Nemours, Inc. |
| Kerry Group |
| DSM Nutritional Products |
| Creative Enzymes |
| Others |
Pricing and Supply Chain Analysis
Fungal fermentation platform transitions are compressing unit economics for Egyptian bakery enzyme buyers while concentrating formulation leverage among Asian contract manufacturers with depreciated stainless-steel capacity. This simultaneous cost and supply shift is restructuring how Greater Cairo processors negotiate annual procurement tenders under NFSA import licensing cycles.
Pricing Analysis
Margin tightening in standard-grade microbial amylase reflects bulk fermentation oversupply from Chinese and Indian contract manufacturers competing for Egyptian distributor offtake. Three-tier pricing structure across fungal-certified, standard microbial, and economy bacterial grades separates clean-label export-qualified formulations from commodity baladi bread conditioners. Pricing pressure intensifies in economy tiers as Delta region artisanal bakers delay capital retrofit of legacy dosing equipment. Export-oriented industrial bakeries in Badr City exhibit lowest price sensitivity due to certification compliance requirements; small Delta cooperatives face acute cost-down pressure.
Supply Chain Analysis
Freight cost volatility from Asian fermentation hubs is amplifying working capital compression for Egyptian enzyme distributors managing 90-day Ministry of Health and Population clearance buffers. Supply concentrates in China, India, and Denmark for microbial platform specialists; Egyptian formulators draw from these nodes for amylase and lipase bulk. Raw material dependencies span corn starch feedstock, phosphate buffers, and sterile packaging films. Single-source vulnerability concentrates in recombinant lipase strains lacking GM documentation for NFSA pre-approval. Distribution runs through Alexandria and Port Said port authorities with divergent customs efficiency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's food enzyme market operates under supply-constrained conditions where fermentation specialist scarcity in Alexandria and Cairo props pricing power for established technical service providers. Local blending capacity bottlenecks prevent price normalization even as Asian bulk supply expands.
For Market Incumbents: Lock in distributor exclusivity agreements across Upper Egypt before toll-manufacturing partnerships capture greenfield dairy demand in Sohag and Qena. Defend margin position by accelerating backward integration into sterile packaging film supply currently exposed to currency mismatch. Prioritize NFSA regulatory affairs staffing to pre-position for biotechnology guidance implementation affecting recombinant strain documentation. For New Entrants and Emerging Players: Artisanal bakeries in the Delta region present the most penetrable buyer archetype, operating legacy equipment incompatible with precision dosing but facing clean-label procurement pressure from Cairo retail chains. Target this segment with capital-light retrofit financing bundled with fungal amylase supply. Establish toll-blending presence in Alexandria to bypass distributor margins and capture dairy culture-enzyme bundle demand from Borg El Arab industrial zone. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational fermentation specialists seeking NFSA regulatory affairs capabilities and Egyptian dairy formulation expertise. Long-term viability hinges on biotechnology guidance resolution clarifying GM strain approval timelines. Watch for NFSA publication of final production organism disclosure requirements as inflection indicator for supplier qualification restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Capacity Buildout | NFSA pre-approval expertise accelerates market access for recombinant lipase formulations. |
| Toll-Manufacturing Partnership | Upper Egypt greenfield dairy cooperatives lack localized enzyme blending infrastructure. |
| Clean-Label Certification Investment | EOS-compliant fungal origin disclosure satisfies hypermarket private-label procurement mandates. |
| Backward Integration into Packaging | Sterile film supply control mitigates currency mismatch exposure from Asian converters. |
| Technical Service Team Expansion | Direct sales relationships bypass distributor margins among export-oriented Alexandria dairies. |
Research Methodology
Document review covered Egyptian Organization for Standardization and Quality enzyme labeling mandates, NFSA biotechnology guidance drafts, and Ministry of Health and Population import licensing procedures, complemented by interviews with fermentation plant managers, bakery procurement leads at industrial clusters, dairy cooperative technical directors, and Alexandria distributor channel partners. Secondary validation drew from customs trade data, Codex Alimentarius enzyme specifications, and Egyptian industrial zone development reports. Bottom-up demand modeling from individual processor procurement cycles was cross-referenced against top-down fermentation capacity estimates.
Historical volume trajectories in baladi bread modernization and white cheese processing expansion were cross-referenced against panel input from enzyme supplier technical service teams and distributor inventory managers. The analytical framework segmented by product type, application, source origin, and distribution channel across the analysis window. CAGRs were derived from weighted average of demand elasticity coefficients and supply capacity expansion schedules. Forecast inputs included NFSA regulatory timeline scenarios and clean-label procurement mandate diffusion rates among Cairo-Giza hypermarket chains.
Revisions become necessary when NFSA biotechnology guidance finalization, Codex Alimentarius specification amendments, or Egyptian pound volatility against Asian supplier currencies materialize outside modeled assumptions. Forecasts reflect documented regulatory trajectories and fermentation capacity expansion announcements. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Argentina Food Preservatives Market
Food Additives and Ingredients
United States Feed Additives Market
Food Additives and Ingredients
Vinasse Market
Food Additives and Ingredients
Africa Food Acidulants Market
Food Additives and Ingredients
Salt Substitutes Market
Food Additives and Ingredients
Aluminum-Free Natural Food Color Market
Food Additives and Ingredients
Emulsifiers Market
Food Additives and Ingredients
Microencapsulated Food Ingredient Market
Food Additives and Ingredients
Global Cereal Ingredients Market
Food Additives and Ingredients
Beta Agonist Feed Additive Market
Food Additives and Ingredients
Clean Label Food Ingredient Market
Food Additives and Ingredients
Edible and Soluble Films Market
Food Additives and Ingredients
South Africa Food Emulsifiers Market
Food Additives and Ingredients
Carmine Alternatives Market
Food Additives and Ingredients
Acidity Regulators Market
Food Additives and Ingredients
Food Grade Butyric Acid Market