
 United States Food Additives Market | 2026-2036
United States Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
United States Food Additives Market Analytics
Subscription-based technical service packages for formulation optimization is broadening what ingredient suppliers monetize beyond commodity sales. Cargill, Incorporated leverages its integrated supply chain from farm to formulation lab to sustain pricing power in starches and texturizers. Kerry Group plc anchors its position through sensory science capabilities that differentiate flavor systems for clean-label applications.
United States food additives comprise functional substances incorporated into food matrices at concentrations typically below one percent by weight to achieve preservation, sensory modification, nutritional enhancement, or processing efficiency. These compounds operate through mechanisms including pH reduction, free-radical scavenging, Maillard reaction catalysis, or hydrocolloid network formation to extend shelf stability and standardize consumer experience across production batches. Preservatives and flavor enhancers command the largest share of current revenue, while natural-source colorants represent the fastest-expanding margin pool as beverage brands reformulate away from synthetic dyes. Thickeners maintain mature growth trajectories in dairy applications where texture standardization is non-negotiable.
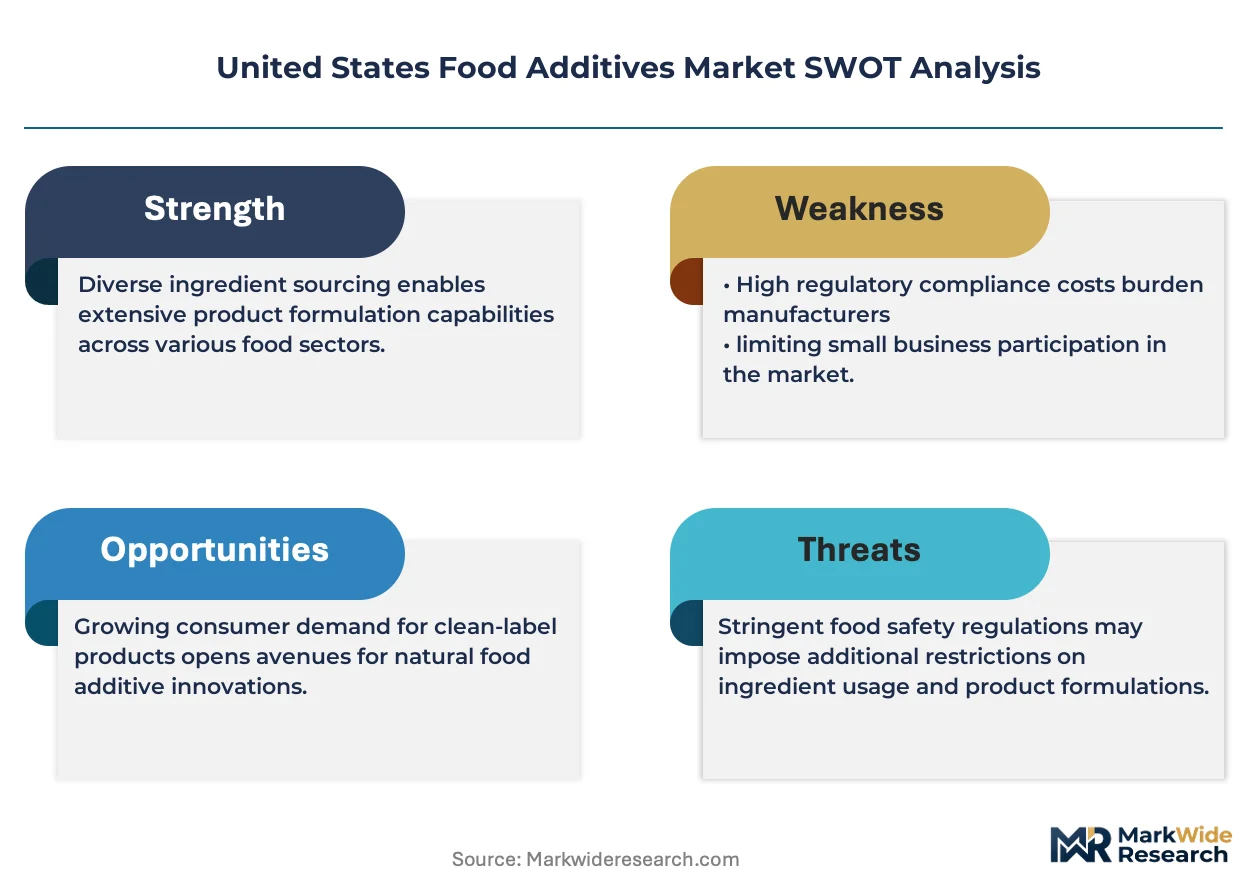
The FDA oversees GRAS determinations and food additive petitions, while USDA regulates additives in meat and poultry products through its Food Safety and Inspection Service, and state-level enforcement by California's Office of Environmental Health Hazard Assessment adds Proposition 65 labeling requirements that reshape formulation decisions. Compliance costs favor suppliers with established regulatory affairs teams capable of navigating parallel federal and state frameworks. Stakeholders must monitor GRAS modernization proposals and emerging state-level restrictions on titanium dioxide and other legacy additives to anticipate reformulation mandates ahead of enforcement timelines.
Market Dynamics
The FDA's GRAS notification modernization is compressing approval timelines while simultaneously elevating evidentiary standards, forcing reformulation cycles that favor suppliers with captive toxicology and regulatory affairs infrastructure.
Growth Catalysts
- California Proposition 65 enforcement:The state's Office of Environmental Health Hazard Assessment mandates warning labels on legacy additives, accelerating demand for exempt natural alternatives in beverage and confectionery manufacturing.
- Precision fermentation-derived proteins:This biotechnology enables clean-label emulsifiers and texturizers that bypass allergen labeling requirements while matching functional performance of synthetic counterparts.
- Midwest dairy processing concentration:Wisconsin and Minnesota's integrated cheese and yogurt manufacturing clusters generate sustained pull for pH control agents and stabilizer systems.
Market Restraints
- Corn and tapioca starch price volatility:Input cost swings for hydrocolloid feedstocks compress margin pools for texturizer suppliers without backward integration into grain origination.
- Single-source dependence on Chinese citric acid:Concentration of fermentation capacity in Shandong province creates supply vulnerability for acidulant-dependent beverage and preserve formulations.
- GRAS self-affirmation liability exposure:FDA's post-market enforcement authority exposes manufacturers to recall risk if novel ingredient safety determinations face subsequent challenge.
Strategic Opportunities
- Texas and Arizona meat processing expansion:USDA-inspected facility growth in these states creates underpenetrated demand for antimicrobial interventions and phosphate alternatives in poultry and beef applications.
- Subscription technical service models:Ingredient suppliers monetize formulation optimization expertise through recurring revenue streams beyond commodity ingredient sales.
- Biomass-derived colorants from agricultural waste:Anthocyanin extraction from grape pomace and beet pulp converges sustainability positioning with cost structures competitive to synthetic dyes.
Industry Challenges
- Cross-functional regulatory talent scarcity:Formulation chemists with parallel expertise in FDA petition procedures and California OEHHA compliance command premium compensation and extended search timelines.
- Legacy ERP integration with traceability systems:Batch record digitization for FSMA compliance encounters friction with decades-old manufacturing execution software in mid-tier processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Food Additives Market |
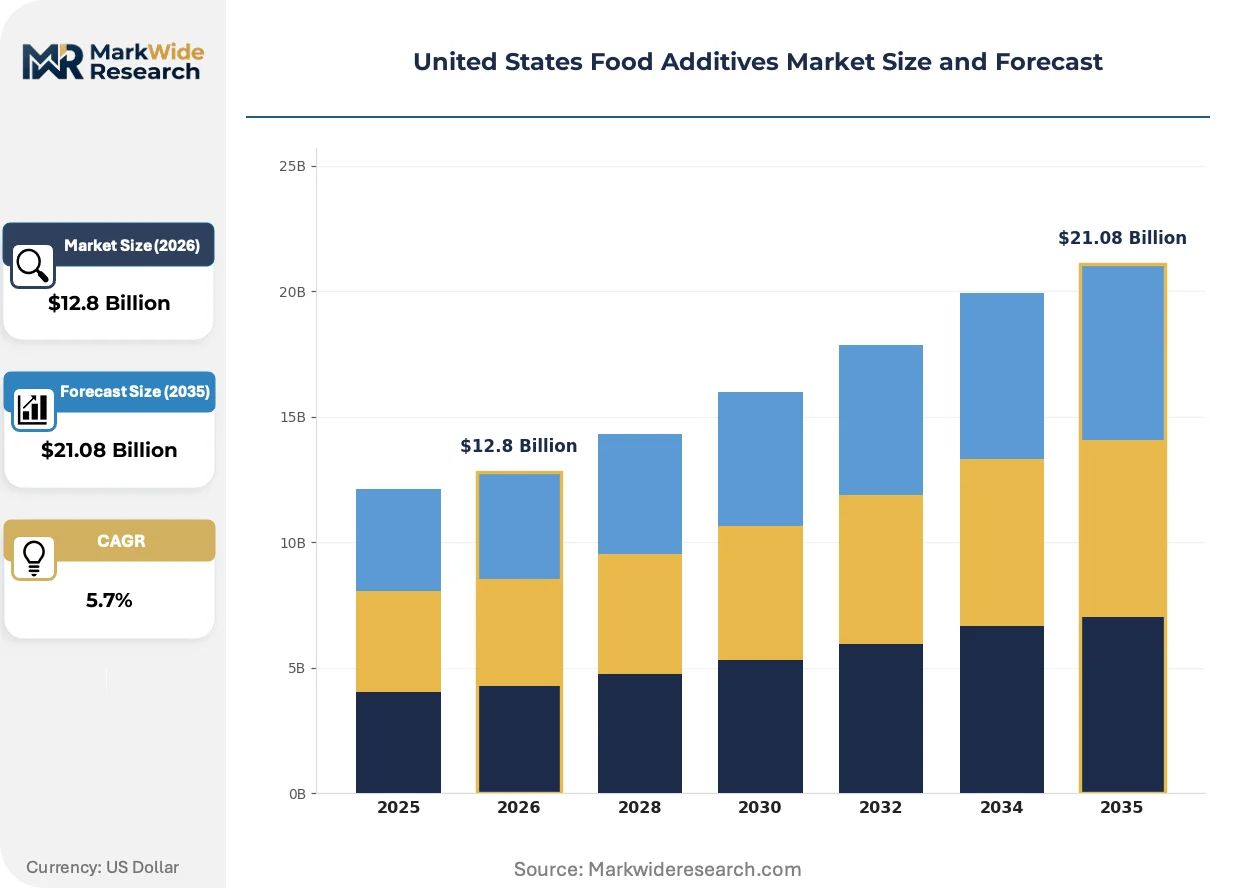
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Preservatives, Colorants, Flavor Enhancers, Thickeners Formulation: Liquid, Powder, Granular, Gel Source: Natural, Synthetic, Organic, Inorganic Application: Beverages, Dairy Products, Baked Goods, Snacks |
| Companies Covered | International Flavors & Fragrances Inc., Tate & Lyle, Cargill, Incorporated, Corbion, Kerry Group plc, Archer Daniels Midland Company, BASF SE, Darling Ingredients Inc., Ingredion Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Food Additives Market Evolving Landscape
Clean-label reformulation is compressing synthetic additive demand while simultaneously expanding the addressable market for functional ingredients derived through biotechnology and upcycled agricultural streams.
Encapsulation technology is unifying flavor stability and controlled-release functionality in a single delivery system. Bakery and ready-meal manufacturers adopt lipid-based and polysaccharide shell structures at accelerated pace to replace artificial preservatives. This convergence is unifying previously separate supplier categories—flavor houses and preservative specialists—into integrated shelf-life solution providers.
California's Office of Environmental Health Hazard Assessment maintains aggressive enforcement of Proposition 65 warning requirements on titanium dioxide and certain artificial colorants. Food manufacturers operating nationwide reformulate to single-state standards rather than maintaining dual SKUs. The confectionery and coated snack segments absorb disproportionate compliance cost as they pivot to fruit and vegetable juice concentrates for color delivery.
Direct procurement relationships between plant-based protein startups and fermentation-derived ingredient developers are displacing traditional distributor intermediaries. These partnerships emphasize co-development agreements with exclusive supply terms and shared regulatory submission costs. The phenomenon concentrates in California's food innovation corridor where venture-backed alternative protein companies cluster near technical service laboratories.
United States Food Additives Market Segmentation
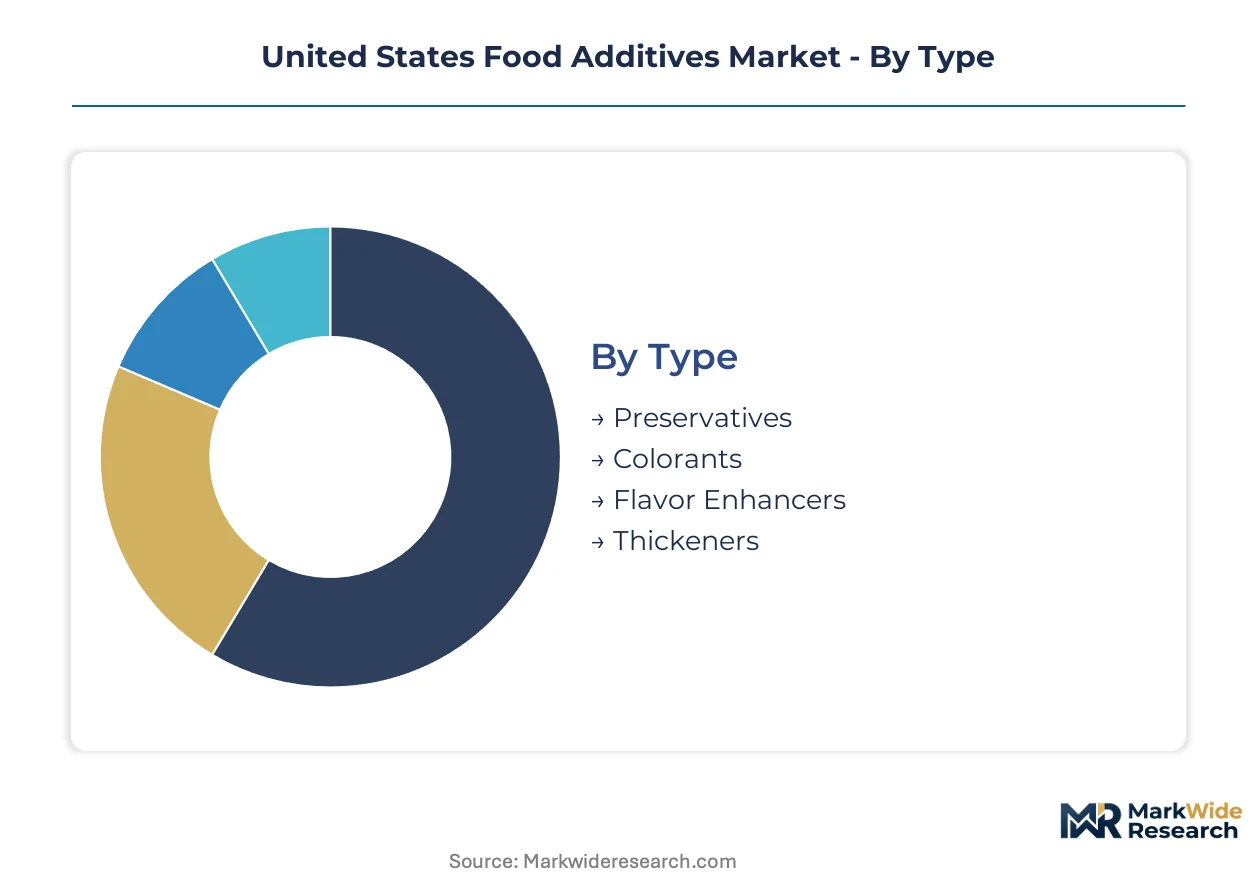
Food additive purchasing decisions cascade through multiple technical and commercial filters. Formulators balance functional performance against regulatory compliance, clean-label positioning, and supply security. Segmentation reveals where specification rigidity gives way to substitution flexibility.
Type:
Customization intensity varies sharply across this category, with commodity preservatives at the standardized end and proprietary flavor systems at the tailored extreme.
- Preservatives:Sorbates, benzoates, and natural alternatives such as cultured dextrose inhibit microbial proliferation through pH modulation and membrane disruption. Demand clusters in California's beverage manufacturing corridor where Proposition 65 compliance accelerates natural-source substitution away from synthetic legacy chemistries.
- Flavor Enhancers:Yeast extracts, hydrolyzed proteins, and nucleotides amplify savory perception while enabling sodium reduction claims. Midwest dairy processors and savory snack manufacturers in Texas drive specification complexity as they pursue clean-label umami delivery without monosodium glutamate labeling triggers.
- Colorants:Anthocyanins, carotenoids, and caramel formulations replace synthetic dyes in confectionery applications.
- Thickeners:Starches, hydrocolloids, and proteins build viscosity networks in dairy and ready-meal matrices.
Leading the category by volume: Preservatives. Expanding most quickly: Colorants.
Formulation:
Physical state selection hinges on processing equipment compatibility, shelf stability requirements, and dissolution kinetics in target food matrices.
- Liquid:Acidulants, liquid smoke, and concentrated flavor systems integrate through direct metering into continuous processing lines. Beverage manufacturers in Georgia and Florida favor liquid acidulants for carbonated and still drink production where rapid dispersion and batch-to-batch consistency are non-negotiable.
- Powder:Spray-dried flavors, encapsulated preservatives, and dry acidulants offer extended stability and reduced transportation costs. Baked goods manufacturers across the Midwest specify powder formats for flour-based systems where moisture control during storage determines ingredient functionality retention.
- Granular:Free-flowing salt replacers and granular citric acid suit mechanical dispensing equipment.
- Gel:Concentrated hydrocolloid suspensions and flavor pastes enable precise viscosity targeting.
Powder formulations dominate procurement tonnage. Liquid formats gain share fastest in beverage and sauce applications.
Source:
Provenance claims now function as primary purchasing criteria, with certification requirements fragmenting what were once commodity categories into premium-tiered alternatives.
- Natural:Plant extracts, fermentation-derived compounds, and minimally processed animal derivatives satisfy clean-label positioning. Snack and confectionery brands operating nationwide reformulate to natural colorants to preempt California warning label requirements, accepting higher per-unit costs for regulatory risk mitigation.
- Synthetic:Petrochemical-derived preservatives, artificial sweeteners, and azo dyes retain cost advantages in private-label and foodservice channels where price positioning supersedes label claims.
- Organic:USDA-certified ingredients command 30-50% premiums in baby food and premium dairy.
- Inorganic:Mineral salts and metallic complexes serve specialized functions in pH control and color stabilization.
Synthetic sources still anchor volume. Natural alternatives climb the fastest as reformulation cycles accelerate.
Application:
End-use concentration shapes regional demand geography, with processing cluster proximity determining supplier technical service deployment.
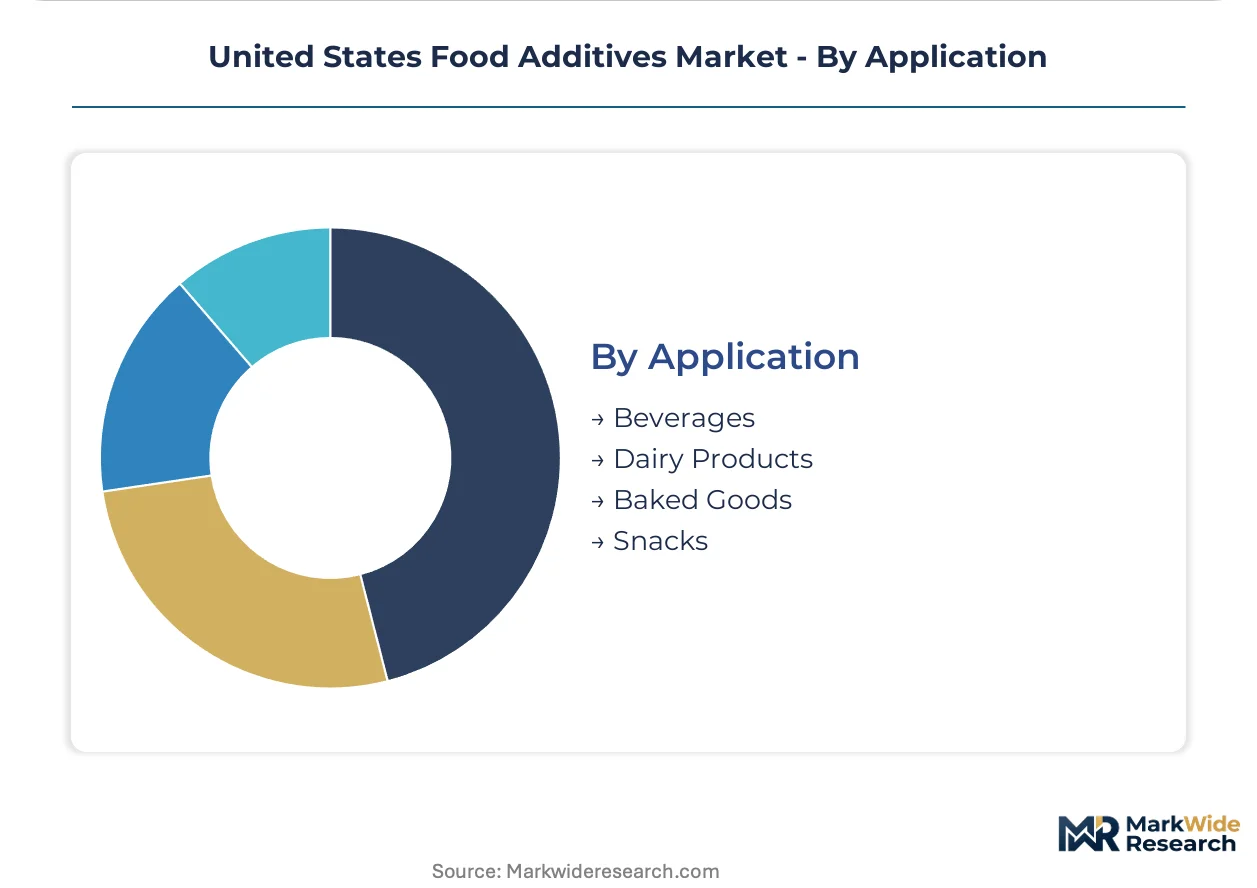
- Beverages:Acidulants, sweeteners, natural colorants, and preservative systems address shelf stability and sensory standardization in high-acid and dairy-based drinks. California's innovation corridor and Florida's citrus processing belt generate concentrated demand for pH control and clouding agents in functional and conventional beverages.
- Dairy Products:Stabilizers, emulsifiers, and cultures manage texture and fermentation in yogurt, cheese, and ice cream. Wisconsin and Minnesota's integrated dairy clusters sustain pull for hydrocolloid systems and phosphate alternatives as processors navigate USDA inspection protocols and clean-label reformulation simultaneously.
- Baked Goods:Emulsifiers, enzymes, and preservatives control staling and mold inhibition.
- Snacks:Seasoning carriers, colorants, and shelf-life extenders address fat oxidation and flavor delivery.
Dairy applications lead procurement volume. Beverage reformulation cycles drive the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic production capacity for fermentation-derived and plant-extracted additives concentrates in the Midwest and California, while formulation demand spreads across dairy belts, beverage corridors, and meat processing expansion zones. This geographic split shapes supplier technical service deployment and inventory positioning strategies.
California
Precision fermentation startups and natural colorant developers cluster in the San Francisco Bay Area and Los Angeles food innovation corridor. The Office of Environmental Health Hazard Assessment enforces Proposition 65 warning requirements that push nationwide reformulation toward exempt natural alternatives. Oakland and South San Francisco host co-development laboratories where plant-based protein companies partner directly with ingredient developers on clean-label emulsifier systems.
Wisconsin
Integrated cheese and yogurt manufacturing generates sustained procurement of stabilizers, phosphate alternatives, and pH control agents. The state's Department of Agriculture, Trade and Consumer Protection administers licensing parallel to USDA Food Safety and Inspection Service oversight. Green Bay and Madison processing corridors anchor hydrocolloid demand as dairy processors navigate simultaneous clean-label and pathogen-control requirements.
Texas
USDA-inspected poultry and beef facility expansion creates underpenetrated demand for antimicrobial interventions and phosphate replacers. The Texas Department of State Health Services coordinates with federal inspectors on additive approval pathways for meat applications. The Dallas-Fort Worth metroplex and Panhandle feedlot zones concentrate new processing capacity that pulls technical service resources southward from Midwest supplier bases.
Minnesota
Specialty dairy and alternative protein manufacturing sustains demand for texturizers and fermentation-derived functional ingredients. The Minnesota Department of Agriculture enforces state-level dairy plant inspections that intersect with FDA food additive jurisdiction. Minneapolis-St. Paul anchors corporate R&D functions for multinational ingredient suppliers serving Upper Midwest dairy cooperatives.
Georgia
Beverage manufacturing and ready-meal production drive acidulant and encapsulated flavor procurement. The Georgia Department of Agriculture administers food safety regulations for processing facilities supplying southeastern distribution networks. Atlanta's logistics hub position attracts inventory staging for suppliers serving Florida citrus processors and Carolinas snack manufacturing.
United States Food Additives Market Competitive Landscape
Top-tier vendors anchor integrated supply chains from agricultural origination through formulation laboratories, while mid-tier specialists compete on sensory science or biotechnology capabilities. Market structure favors suppliers with captive regulatory affairs infrastructure capable of navigating parallel FDA and state-level compliance frameworks. Three archetypes dominate: grain-origination conglomerates with backward integration into starch and protein feedstocks; biotechnology specialists leveraging precision fermentation for clean-label functional ingredients; and sensory-science houses bundling flavor systems with shelf-life extension technologies. Competitive moves concentrate on co-development partnerships with venture-backed alternative protein startups and acquisition of regional distributors to tighten technical service coverage.
Among integrated supply chain operators, Cargill, Incorporated and Archer Daniels Midland Company represent the grain-origination archetype with upstream control over corn and oilseed processing. Kerry Group plc exemplifies the sensory-science specialist model, bundling flavor optimization with clean-label reformulation expertise. Ingredion Incorporated occupies a position between these archetypes, linking modified starch capabilities to texture-standardization demands in dairy and beverage applications.
| Leading Market Players |
|---|
| International Flavors & Fragrances Inc. |
| Tate & Lyle |
| Cargill, Incorporated |
| Corbion |
| Kerry Group plc |
| Archer Daniels Midland Company |
| BASF SE |
| Darling Ingredients Inc. |
| Ingredion Incorporated |
| Others |
Value Network & Pricing Analysis
Regulatory affairs specialists concentrated in California's food innovation corridor command compensation premiums that propagate through tiered supplier pricing, widening spreads between premium clean-label formulations and commodity-grade alternatives as labor-cost differentials compound raw material premiums.
Pricing Analysis
Margin tightening in synthetic preservative tiers reflects California Proposition 65 enforcement accelerating natural-source substitution. Three-tier pricing structure across premium clean-label, standard natural, and economy synthetic levels differentiates on certification grade and regulatory risk exposure. Cost-down pressure on commodity hydrocolloids intensifies because corn and tapioca starch feedstock volatility compresses supplier margins. Private-label beverage manufacturers exhibit highest price sensitivity, while venture-backed alternative protein startups prioritize functional performance over unit economics.
Supply Chain Analysis
Citric acid supply rests on fermentation capacity concentrated in China's Shandong province, with secondary sourcing from Thailand and Belgium providing limited diversification. Corn-derived starches, fermentation feedstocks, and precision fermentation bioreactor components constitute critical input dependencies. Single-source concentration creates tariff exposure and geopolitical disruption vulnerability for acidulant-dependent formulations. Distribution runs through regional technical service laboratories co-located with California and Midwest processing clusters, displacing traditional distributor intermediaries in clean-label segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation capacity scarcity props pricing power for biotechnology-derived clean-label ingredients, constraining supply expansion faster than demand absorption across the analysis window.
For Market Incumbents: Anchor market position through captive toxicology and regulatory affairs infrastructure capable of parallel FDA GRAS navigation and California OEHHA compliance. Defend against precision fermentation startups by acquiring regional distributors to tighten technical service coverage in Texas and Arizona meat processing expansion zones. Prioritize backward integration into grain origination to insulate margin pools from starch feedstock volatility. For New Entrants and Emerging Players: Launch via direct procurement partnerships with venture-backed alternative protein companies in California's food innovation corridor, bypassing established distributor networks. Target underpenetrated antimicrobial intervention demand in Texas and Arizona USDA-inspected poultry and beef facilities. Pursue co-development agreements with exclusive supply terms and shared regulatory submission costs as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors biotechnology specialists with precision fermentation platforms and established GRAS submission track records. Long-term viability hinges on regulatory affairs capabilities that compress approval timelines while elevating evidentiary standards. Watch FDA GRAS modernization implementation pace as the critical inflection signal for reformulation cycle acceleration and incumbent advantage consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Enables clean-label emulsifier production that bypasses allergen labeling requirements for plant-based formulations. |
| Backward Integration into Grain Origination | Captive corn and tapioca starch supply insulates margin pools from input cost volatility in hydrocolloid production. |
| Regulatory Affairs Infrastructure Investment | Parallel FDA petition and California OEHHA compliance capabilities compress reformulation cycle timelines for clients. |
| Co-Development Laboratory Partnerships | Direct technical service relationships with alternative protein startups displace distributor intermediaries in high-growth segments. |
| Biomass-Derived Colorant Extraction Scale-Up | Anthocyanin recovery from agricultural waste converges sustainability positioning with synthetic dye cost competitiveness. |
Research Methodology
Independent corroboration across formulation chemists at Midwest dairy processors, regulatory affairs directors at multinational ingredient suppliers, procurement leads at California beverage manufacturers, and precision fermentation startup executives underwrites the qualitative findings. Secondary validation draws from FDA GRAS notification filings, USDA Food Safety and Inspection Service additive approvals, California OEHHA Proposition 65 regulatory updates, and American Chemical Society technical proceedings. Bottom-up demand modeling across application segments triangulates with top-down supply-side capacity assessments.
Comparable historical reference periods spanning pre- and post-GRAS modernization proposal announcement anchor the forecast window calibration. Segmentation dimensions modeled include additive type, formulation physical state, source provenance, and application end-use across the projection horizon. CAGRs derive from elasticity-adjusted volume projections incorporating clean-label reformulation acceleration rates and biotechnology adoption curves. Industry-specific inputs encompass precision fermentation yield improvement trajectories and California regulatory enforcement intensity indices.
GRAS self-affirmation liability exposure, single-source citric acid supply disruption, and precision fermentation scale-up bottlenecks are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about regulatory timeline stability and feedstock price regime continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Asia-Pacific Malt Ingredient Market
Food Additives and Ingredients
Italy Sodium Reduction Ingredients Market
Food Additives and Ingredients
Global Organic Food Preservatives Market
Food Additives and Ingredients
United Kingdom Food Emulsifier Market
Food Additives and Ingredients
North America Food Starch Market
Food Additives and Ingredients
Neohesperidin Market
Food Additives and Ingredients
Spain Food Additives Market
Food Additives and Ingredients
Beverage Acidulants Market
Food Additives and Ingredients
Food Bleaching Agents Market
Food Additives and Ingredients
Europe Food Emulsifiers Market
Food Additives and Ingredients
Mexico Food Additives Market
Food Additives and Ingredients
Leavening Agents Market
Food Additives and Ingredients
Global Flaked Shortenings Market
Food Additives and Ingredients
Gum Hydrocolloid Market
Food Additives and Ingredients
Potassium Propionate Market
Food Additives and Ingredients
Lactose Monohydrate Market