
 South Africa Food Additives Market | 2026-2036
South Africa Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Food Additives Market Analytics
Technical service subscriptions for enzyme performance optimization is decoupling additive sales from pure ingredient volumes in South Africa. Cargill Incorporated leverages its Johannesburg technical center to anchor formulation partnerships with local millers and bakeries. Kerry Group competes through integrated taste and nutrition platforms that extend beyond commodity supply into recipe co-development.
Food additives comprise functional substances incorporated into food matrices at specified concentrations to enhance stability, sensory properties, or processing efficiency, with typical inclusion rates ranging from parts per million to several percent by weight depending on regulatory maximum limits and technological necessity. Preservatives occupy the largest value pool as shelf-life extension remains critical for South Africa's extended distribution networks to informal retail, while flavor enhancers represent the fastest-growing category as manufacturers reduce sodium and sugar without sacrificing palatability. Emulsifiers sustain margin concentration in dairy and bakery applications where texture standardization commands premium positioning.
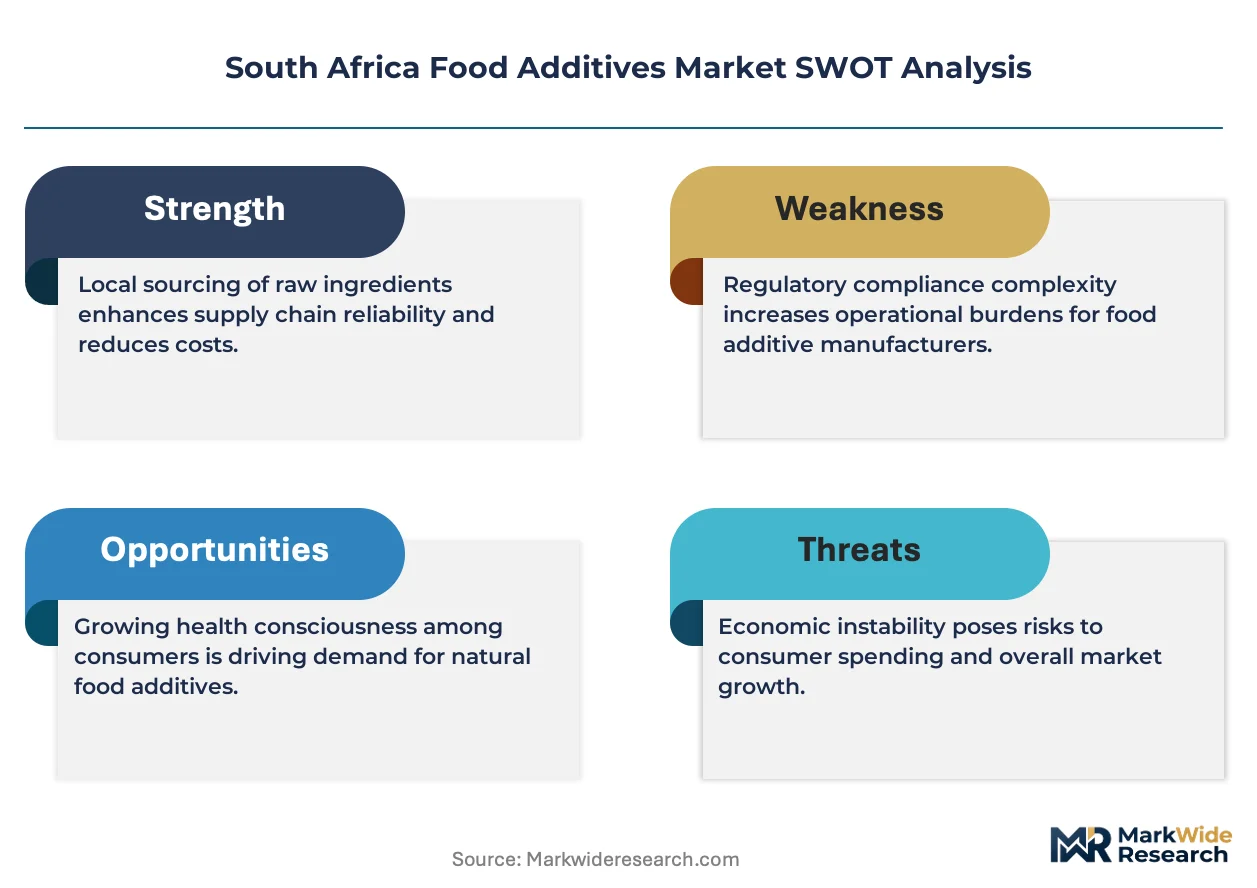
The Department of Health enforces salt reduction targets under its Foodstuffs, Cosmetics and Disinfectants Act, compelling reformulation that expands demand for potassium chloride blends and umami-enhancing yeast extracts. SANS food safety standards and the Consumer Protection Act shape labeling transparency requirements that favor clean-label colorants from botanical sources over synthetic alternatives. Stakeholders must monitor enforcement intensity around sodium limits and the pace of regulatory alignment with Codex Alimentarius standards to anticipate reformulation investment cycles.
Market Dynamics
Reformulation mandates from the Department of Health's salt reduction targets are forcing processed meat and poultry manufacturers to rebuild product matrices around potassium chloride blends and umami-enhancing yeast extracts, creating sustained additive substitution cycles.
Growth Catalysts
- Regulatory pressure:The Department of Health's Foodstuffs, Cosmetics and Disinfectants Act compels sodium reduction across processed foods, expanding demand for clean-label alternatives.
- Enzyme technology:Clean-label enzyme technologies are displacing synthetic preservatives in bakery and dairy applications as manufacturers pursue label simplification.
- Geographic concentration:Gauteng province's Johannesburg-Pretoria food manufacturing corridors concentrate additive demand from national-scale processors.
Market Restraints
- Input cost volatility:Potassium chloride and botanical extract prices fluctuate with agricultural yields and import currency exposure.
- Supply concentration risk:Technical-grade enzymes and specialty emulsifiers depend on concentrated European and Asian supplier bases.
- Regulatory friction:SANS food safety standards create compliance complexity for imported additive formulations lacking local certification.
Strategic Opportunities
- Underpenetrated geography:KwaZulu-Natal's Durban-Richards Bay processing corridor offers expansion potential for technical service partnerships.
- Emerging application:Plant-based meat alternatives require texture-modifying hydrocolloids and flavor-masking systems.
- Regulatory tailwind:Alignment with Codex Alimentarius standards would streamline export qualification for South African additive producers.
Industry Challenges
- Skill scarcity:Food formulation chemists with enzyme optimization expertise remain scarce in local labor markets.
- Certification timelines:Novel additive approvals under the Department of Health's framework extend 18-24 months.
- Integration friction:Legacy production lines require capital retrofitting to handle temperature-sensitive natural colorants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Food Additives Market |
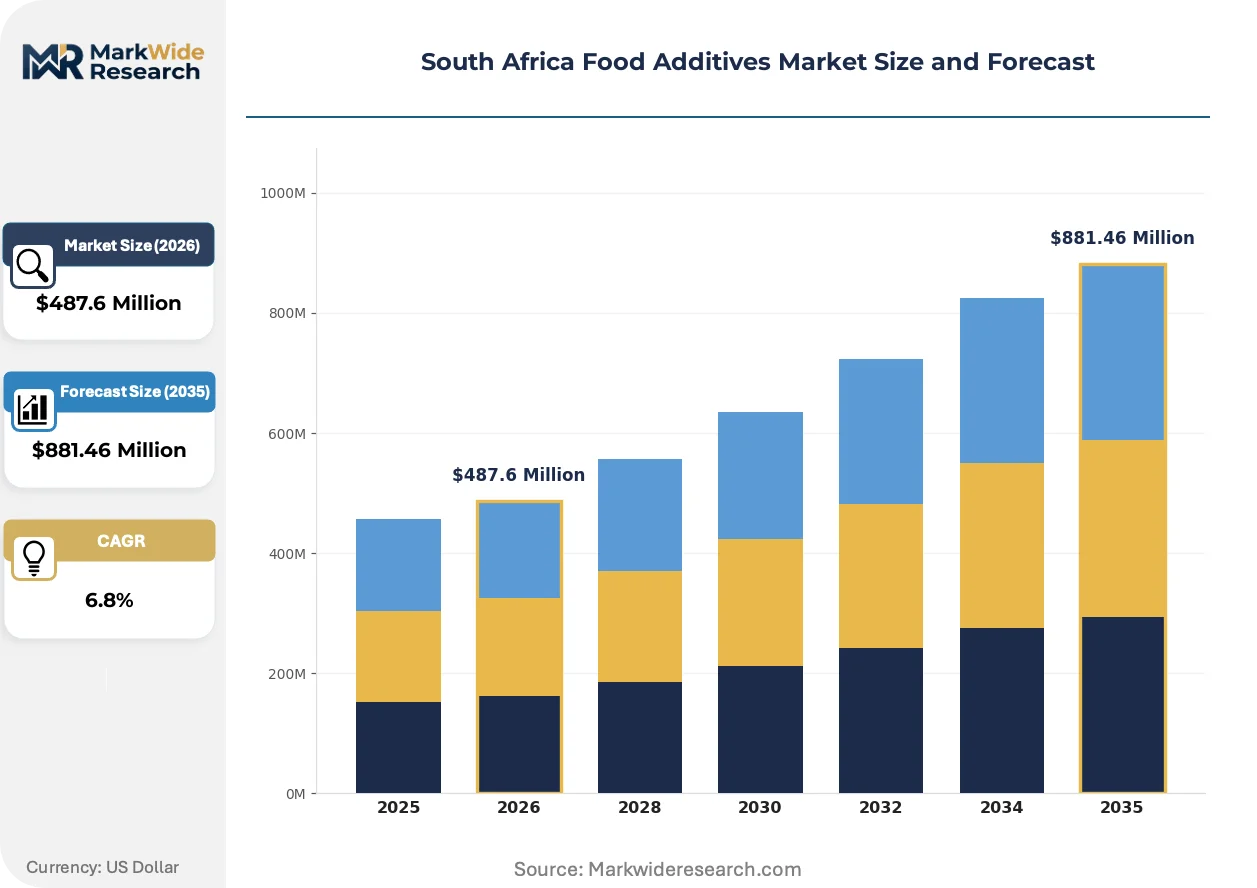
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preservatives, Flavor Enhancers, Colorants, Emulsifiers Application: Beverages, Bakery Products, Dairy Products, Sauces Form: Powder, Liquid, Granular, Gel End User: Food Manufacturers, Food Service Providers, Retailers, Household Consumers |
| Companies Covered | Ingredion Incorporated, Firmenich SA, Cargill Incorporated, DuPont de Nemours Inc, Novozymes, Kerry Group, Corbion, Sensient Technologies, Tate & Lyle, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Food Additives Market Evolving Landscape
Clean-label automation and regulatory alignment pressures are compressing reformulation cycles across South Africa's food manufacturing base, with technical service partnerships replacing commodity supply relationships.
Automated enzyme dosing systems are automating precision addition in commercial bakeries, with large millers retrofitting continuous mixing lines to reduce batch-to-batch variation. This compression of process control is automating quality assurance overhead while enabling real-time formulation adjustments.
The Department of Health's progressive enforcement of sodium targets under its Foodstuffs Act is accelerating potassium chloride blend adoption. Processed meat manufacturers are rebuilding entire product lines around these reformulation requirements, with informal retail distribution networks demanding extended shelf-life solutions that comply.
Technical service subscriptions are displacing transactional additive purchasing among Gauteng-based processors. Large bakeries and meat manufacturers now contract for integrated formulation partnerships rather than commodity procurement, with this model concentrating vendor relationships around Johannesburg technical centers.
South Africa Food Additives Market Segmentation
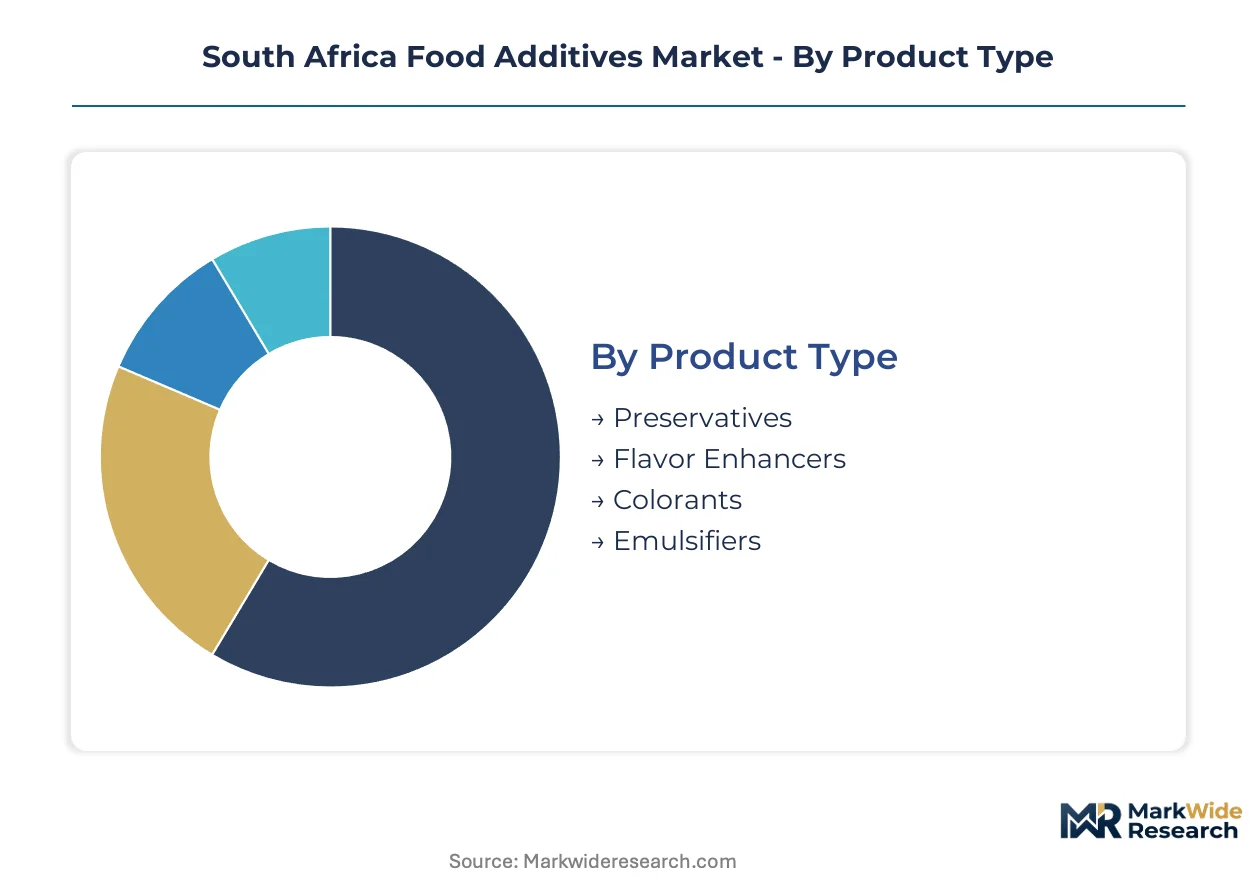
Segmentation in South Africa's food additives market reveals how regulatory mandates and supply chain geography concentrate value across distinct product categories and customer tiers. Understanding these divisions exposes where formulation partnerships command premium positioning versus commodity procurement.
Product Type:
Supply concentration around Johannesburg-Pretoria technical centers favors segments requiring intensive application support over standardized commodity additives.
- Preservatives:Comprise antimicrobial agents, antioxidants, and chelating agents that inhibit microbial growth and oxidative rancidity in processed foods. Demand concentrates in processed meat manufacturers across Gauteng's manufacturing corridors, driven by shelf-life extension requirements for informal retail distribution networks with limited cold chain infrastructure.
- Flavor Enhancers:Include yeast extracts, hydrolyzed vegetable proteins, and nucleotides that amplify umami perception and enable sodium reduction. Adoption accelerates among poultry processors in Johannesburg-Pretoria corridors responding to Department of Health salt reduction targets under the Foodstuffs, Cosmetics and Disinfectants Act.
- Colorants:Span synthetic azo dyes and natural extracts from beetroot, turmeric, and anthocyanin sources. Clean-label migration favors botanical alternatives despite higher input cost volatility tied to agricultural yield fluctuations.
- Emulsifiers:Cover lecithin, mono- and diglycerides, and polysorbates that stabilize oil-water interfaces. Dairy and bakery applications in Gauteng sustain margin concentration where texture standardization commands premium positioning.
Today's leader: Preservatives. Tomorrow's challenger: Flavor enhancers.
Application:
Cost tier differentiation separates high-volume beverage applications requiring precision dosing equipment from artisanal sauce segments tolerating manual addition methods.
- Beverages:Acidulants, sweeteners, and stabilizers maintain pH balance and suspension in carbonated and still drinks. Large-scale bottlers in Johannesburg-Pretoria corridors drive volume procurement with automated dosing integration.
- Bakery Products:Emulsifiers and enzymes condition dough and extend shelf-life in commercial bread production. Technical service partnerships dominate as millers retrofit continuous mixing lines for precision enzyme addition.
- Dairy Products:Stabilizers and preservatives prevent syneresis and spoilage in UHT milk and fermented products. Cold chain limitations in KwaZulu-Natal distribution networks amplify preservative dependency.
- Sauces:Thickeners, acidulants, and preservatives maintain viscosity and safety in condiments. Smaller batch production tolerates semi-manual processes with lower capital barriers.
Volume concentrates in beverages. Margin expansion potential sits with bakery applications.
Form:
Customer type dictates form selection, with large food manufacturers favoring bulk powder and liquid systems while food service operators prioritize handling convenience.
- Powder:Dry-blended concentrates enable precise weighing and extended shelf stability. National-scale manufacturers in Gauteng specify powder forms for high-throughput continuous processing lines.
- Liquid:Pre-dissolved solutions eliminate hydration steps and reduce dust exposure. Automated dosing systems in commercial bakeries favor liquid enzyme preparations for real-time flow adjustment.
- Granular:Free-flowing particles reduce caking in humid storage conditions. Regional distributors specify granular forms for intermediate handling stages.
- Gel:Viscous preparations suit small-batch artisanal producers requiring measured dispensing control. Limited penetration outside specialty sauce and confectionery niches.
Powder dominates procurement volumes. Liquid forms gain share fastest in automated production environments.
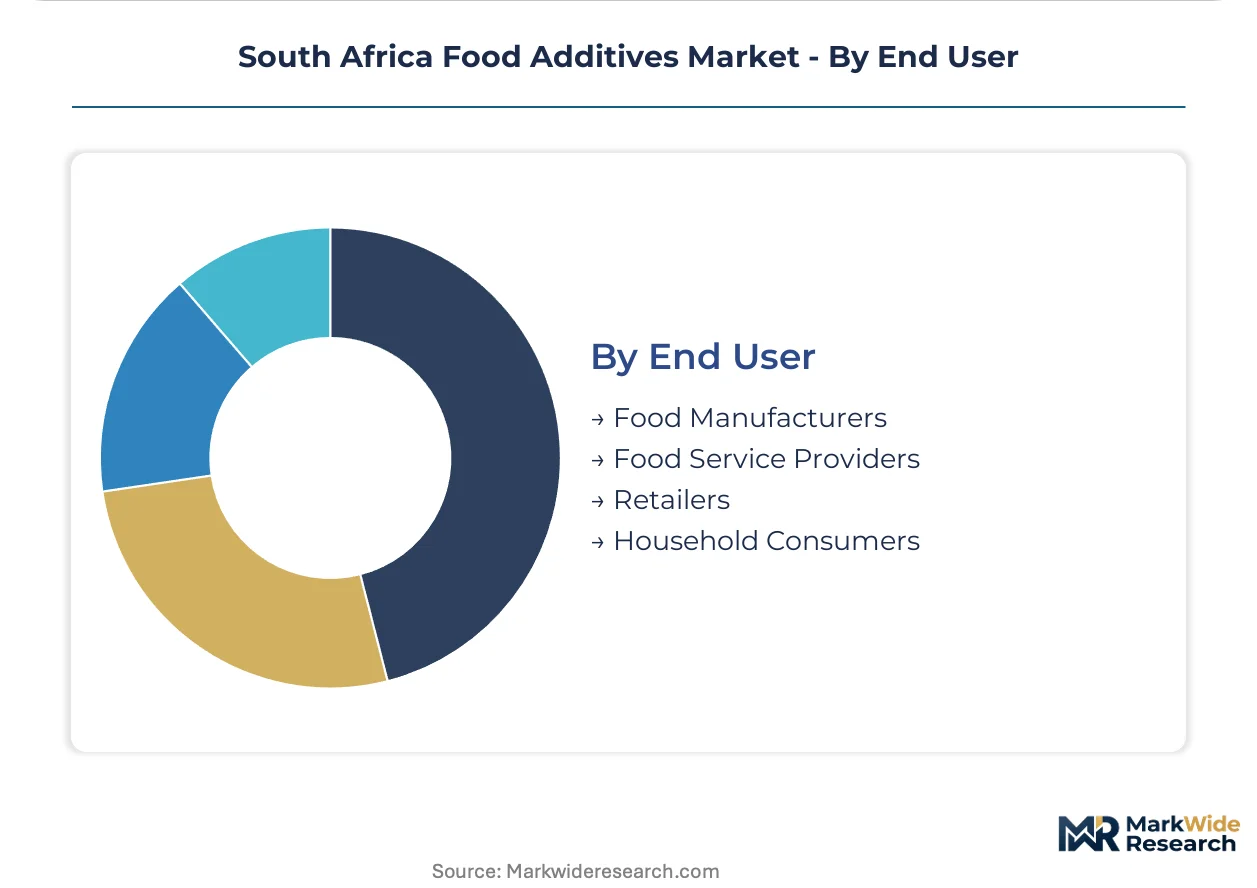
End User:
Maturity gradients separate established technical service relationships with food manufacturers from emerging direct-to-retailer channels bypassing traditional distribution.
- Food Manufacturers:National-scale processors operating Johannesburg-Pretoria and Durban-Richards Bay corridors. Integrated formulation partnerships with Cargill and Kerry technical centers replace transactional purchasing.
- Food Service Providers:Restaurant chains and institutional caterers sourcing pre-blended seasoning systems. Simplified procurement tolerates higher per-unit costs for convenience positioning.
- Retailers:Private-label developers specifying clean-label additive packages for store-brand products. Direct technical engagement with additive suppliers compresses traditional distributor margins.
- Household Consumers:Small-package retail sales of single-function additives. Marginal commercial significance concentrated in specialty baking and preserving enthusiasts.
Food manufacturers anchor value capture. Retailer direct sourcing represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa outpaces neighboring markets in additive sophistication, while smaller economies struggle with cold chain infrastructure that preservatives must compensate for.
Gauteng Province
Johannesburg-Pretoria manufacturing corridors concentrate national-scale meat and poultry processors demanding shelf-life extension solutions. The Department of Health's Foodstuffs, Cosmetics and Disinfectants Act enforces sodium reduction timelines that accelerate potassium chloride blend adoption. Technical service partnerships with Cargill's Johannesburg center anchor formulation relationships for regional millers and bakeries.
KwaZulu-Natal
Durban-Richards Bay processing corridors show underpenetrated potential for enzyme optimization services in dairy applications. SANS food safety standards create compliance complexity for imported specialty emulsifiers lacking local certification. Cold chain limitations across KwaZulu-Natal distribution networks amplify preservative dependency in UHT milk segments.
Western Cape
Cape Town's wine and beverage bottling clusters drive acidulant and stabilizer procurement with precision dosing requirements. The Consumer Protection Act shapes labeling transparency mandates that favor botanical colorants over synthetic alternatives. Artisanal sauce producers in Stellenbosch tolerate semi-manual processes with lower capital barriers than Gauteng-scale operations.
Eastern Cape
Port Elizabeth automotive corridor spillover supports limited food manufacturing scale relative to coastal neighbors. Provincial health departments implement national sodium targets with variable enforcement intensity. Emerging retail distribution networks into informal township markets create demand for extended shelf-life packaging systems.
South Africa Food Additives Market Competitive Landscape
Top-tier vendors anchor integrated formulation partnerships, while commodity suppliers compete on import logistics and distributor relationships. The market structure concentrates around Johannesburg technical centers where enzyme optimization expertise commands premium positioning. Three archetypes dominate: multinational ingredient platforms with local technical infrastructure, regional distributors with SANS certification capabilities, and specialty enzyme houses with clean-label positioning. Competitive moves center on technical service subscription models and backward integration into botanical extract sourcing.
Among multinational platforms, Cargill Incorporated and Kerry Group occupy positions exemplifying the integrated service archetype, while Novozymes represents specialty enzyme expertise. These entities anchor the shift from transactional procurement toward ongoing formulation partnerships. Corbion and Tate & Lyle sit within the preservation and texture-modification tier respectively. Sensient Technologies and Firmenich SA exemplify sensory solution specialists. The competitive dynamic rewards proximity to Gauteng manufacturing corridors over pure price positioning.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Firmenich SA |
| Cargill Incorporated |
| DuPont de Nemours Inc |
| Novozymes |
| Kerry Group |
| Corbion |
| Sensient Technologies |
| Tate & Lyle |
| Others |
Value Network & Pricing Analysis
Processed meat manufacturers' mandated sodium reduction timelines under the Department of Health's Foodstuffs Act are compelling rapid reformulation, forcing suppliers to recalibrate potassium chloride blend availability and compressing margins on legacy preservative portfolios.
Pricing Analysis
Capacity additions in China's specialty enzyme sector are reshaping price floors for clean-label alternatives in South Africa. Three-tier pricing structure across premium, standard, and economy levels separates Cargill's technical service subscriptions from commodity importers and unbranded distributors. Cost compression in botanical colorants is intensifying because agricultural yield volatility in India and Brazil feeds through to extract input costs. Small-scale sauce producers in the Western Cape exhibit highest price sensitivity, while national-scale Gauteng millers prioritize formulation partnership value over per-kilogram procurement economics.
Supply Chain Analysis
Freight cost exposure from Rotterdam and Mumbai ports amplifies landed cost volatility for temperature-sensitive natural colorants and technical-grade enzymes. Supply concentrates in Germany, Denmark, and India for enzyme manufacturing, while potassium chloride draws from Chile and Canada. Single-source vulnerability sits with Novozymes' dominant position in bakery enzyme formulations. Distribution runs through Johannesburg-based technical centers serving Gauteng manufacturing corridors, with secondary logistics nodes in Durban handling KwaZulu-Natal dairy processor demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's food additives market functions as a geographic-arbitrage play where European clean-label technology premiums meet African informal retail shelf-life requirements, with regulatory alignment costs in Pretoria running below equivalent Brussels compliance investment thresholds.
For Market Incumbents: Anchor technical service relationships through expanded Johannesburg center capacity to defend against Kerry Group's integrated taste-nutrition platform encroachment. Deepen backward integration into botanical extract sourcing to offset agricultural yield volatility pressuring colorant margins. Prioritize SANS certification pre-positioning for novel enzyme formulations before Department of Health approval timelines extend competitive windows. For New Entrants and Emerging Players: Artisanal bakery cooperatives in the Western Cape represent an underserved buyer archetype bypassed by multinational technical service models. KwaZulu-Natal's underpenetrated Durban-Richards Bay dairy corridor offers white-space expansion with enzyme optimization services for UHT milk stabilizer applications. Lead with granular form factor convenience and humid-climate storage stability to differentiate from Gauteng-centric liquid system incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with regional distributors possessing SANS certification capabilities and established relationships with informal retail channel networks. Five-to-ten year viability hinges on Codex Alimentarius alignment enabling South African additive export qualification into SADC markets. Monitor Department of Health enforcement intensity around sodium targets as the inflection signal for reformulation investment cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Technical Service Center Expansion | Cargill's Johannesburg facility anchors formulation partnerships displacing commodity procurement relationships. |
| Backward Integration into Botanical Sourcing | Captive supply of turmeric and beetroot extracts reduces agricultural yield exposure for clean-label colorants. |
| SANS Certification Pre-Investment | Early compliance positioning compresses novel additive approval timelines under Department of Health frameworks. |
| Enzyme Dosing System Automation | Precision addition retrofitting in commercial bakeries enables real-time formulation adjustment subscriptions. |
| KwaZulu-Natal Corridor Partnership | Durban-Richards Bay dairy processor engagement captures underpenetrated enzyme optimization demand. |
Research Methodology
Direct dialogue with food formulation chemists, procurement leads at national-scale meat processors, technical R&D directors at enzyme houses, and SANS certification consultants grounded qualitative insights. Secondary validation drew from Department of Health regulatory filings, SANS food safety standards documentation, customs and trade data for potassium chloride and enzyme imports, and SEC 10-K disclosures from listed multinational ingredient platforms. Bottom-up demand modeling across Gauteng and KwaZulu-Natal manufacturing corridors triangulated against top-down market sizing from production volume and inclusion rate assumptions.
Bottom-up segmentation analysis modeled preservatives, flavor enhancers, colorants, and emulsifiers across beverage, bakery, dairy, and sauce applications, with form factor and end-user tier dimensions incorporated throughout the projection horizon. CAGRs were derived from regulatory mandate pacing, reformulation investment cycle timing, and technical service adoption curve analysis. Forecast inputs included Department of Health sodium target enforcement schedules and cold chain infrastructure development trajectories affecting preservative dependency.
Inputs from Department of Health officials and Johannesburg-Pretoria processor technical directors were available through the study window; gaps in KwaZulu-Natal informal retail distribution network data introduce uncertainty bands around preservative demand projections. Forecasts reflect assumptions regarding Codex Alimentarius alignment pacing and enzyme substitution rates for synthetic preservatives. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Nisin for Food Market
Food Additives and Ingredients
India Food Color Industry Market
Food Additives and Ingredients
Anti-Caking Agents Market
Food Additives and Ingredients
Mexico Food Enzymes Market
Food Additives and Ingredients
Argentina Gellan Gum Market
Food Additives and Ingredients
Vietnam Food Additives Market
Food Additives and Ingredients
Lactose Monohydrate Market
Food Additives and Ingredients
Natural Food Color Ingredients Market
Food Additives and Ingredients
AKD Emulsifier Market
Food Additives and Ingredients
Microencapsulated Food Ingredient Market
Food Additives and Ingredients
Europe Leavening Agents Market
Food Additives and Ingredients
Global Baking Powder Market
Food Additives and Ingredients
Japan Food Emulsifiers Market
Food Additives and Ingredients
Clean Label Emulsifiers Market
Food Additives and Ingredients
Europe Food Coating Ingredients Market
Food Additives and Ingredients
Cocoglycerides Market