
 Mediterranean Sourdough Starter Cultures Market | 2026-2036
Mediterranean Sourdough Starter Cultures Market Size, Share, and Industry Trends Forecast 2026-2036
Mediterranean Sourdough Starter Cultures Market Insights
Precision fermentation and cryopreservation advances are reshaping how Mediterranean sourdough starter cultures propagate at commercial scale. Lesaffre leverages decades of strain banking expertise to dominate European distribution networks for heritage cultures. Puratos Group anchors its competitive position through dedicated sourdough institutes in Belgium and Italy that train artisan bakers on live culture management. Lallemand competes via controlled-environment manufacturing that standardizes wild yeast viability across liquid and freeze-dried formats.
Mediterranean sourdough starter cultures comprise symbiotic communities of Saccharomyces cerevisiae and heterofermentative Lactobacillus species, typically maintained at pH 3.8-4.6 and inoculated at 5-20% preferment weight relative to final dough mass. Their primary commercial purpose centers on producing the characteristic acidity, extensibility, and aromatic complexity required for traditional ciabatta, focaccia, and Greek country breads without commercial baker's yeast. Wild yeast and mixed cultures command the deepest margin pools due to strain authentication costs and limited supplier bases, while bakery-specific strains experience the fastest volume growth as industrial bakers retrofit lines for clean-label claims. Freeze-dried packaging leads value contribution because extended shelf stability reduces cold-chain expenditure for export-oriented producers.
EU regulations including the F-Gas Regulation on industrial refrigeration, REACH on fermentation substrate chemicals, and EFSA Novel Food guidance on non-traditional strains collectively elevate compliance costs for culture suppliers entering European markets. Italy's Ministry of Agricultural Policies enforces strict PDO protocols for Pane di Altamura that mandate specific Lactobacillus sanfranciscensis dominance, directly shaping strain selection and documentation requirements. Stakeholders must monitor evolving definitions of "traditional" versus "industrial" fermentation under pending EU-wide harmonization of artisan food standards.
Market Dynamics
EU clean-label mandates and heritage strain authentication requirements are compressing supplier margins while fragmenting procurement channels across Southern European artisan bakeries.
Growth Catalysts
- PDO Certification Mandates:Italy's Ministry of Agricultural Policies enforces strict protocols for Pane di Altamura and other protected designation breads, requiring documented Lactobacillus sanfranciscensis dominance that drives specialized culture procurement.
- Cryopreservation Advances:Commercial-scale liquid nitrogen banking now extends heritage strain viability from months to decades, enabling export-oriented producers to serve distant markets without continuous propagation cycles.
- Clean-Label Retrofitting:Industrial bakeries across Greece and Spain are eliminating commercial baker's yeast from production lines to capture premium positioning, creating surge demand for standardized wild yeast concentrates.
Market Restraints
- Input Cost Volatility:Organic rye and wheat flour prices fluctuate with Black Sea grain flows, directly pressuring propagation substrate costs for culture suppliers maintaining traditional feedstock standards.
- Supply Concentration Risk:Heritage strain banking expertise concentrates among three European biotechnology firms, creating single-source vulnerability for artisan bakeries requiring authenticated Mediterranean lineages.
- Technical Limitation:Heterofermentative Lactobacillus species remain sensitive to temperature excursions above 8°C during transport, constraining distribution radius for live culture formats without cold-chain infrastructure.
Strategic Opportunities
- Underpenetrated Geography:Portuguese artisan bakeries lack established heritage strain suppliers despite growing interest in traditional broa de milho fermentation, presenting first-mover positioning for culture banks with documented regional isolates.
- Regulatory Tailwind:Pending EU-wide harmonization of artisan food standards may elevate "traditional" fermentation definitions, advantaging suppliers with pre-existing strain documentation against industrial competitors.
- Technology Convergence:Precision fermentation platforms are merging with CRISPR-based strain characterization, enabling rapid authentication of wild yeast communities without months-long phenotypic testing.
Industry Challenges
- Skill Gap in Live Culture Management:Artisan bakeries struggle to maintain pH 3.8-4.6 environments during preferment propagation, requiring sustained training investment that strains supplier technical service capacity.
- Certification Timeline Compression:EFSA Novel Food guidance on non-traditional strains demands 18-24 month safety dossier preparation, delaying market entry for innovative culture combinations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mediterranean Sourdough Starter Cultures Market |
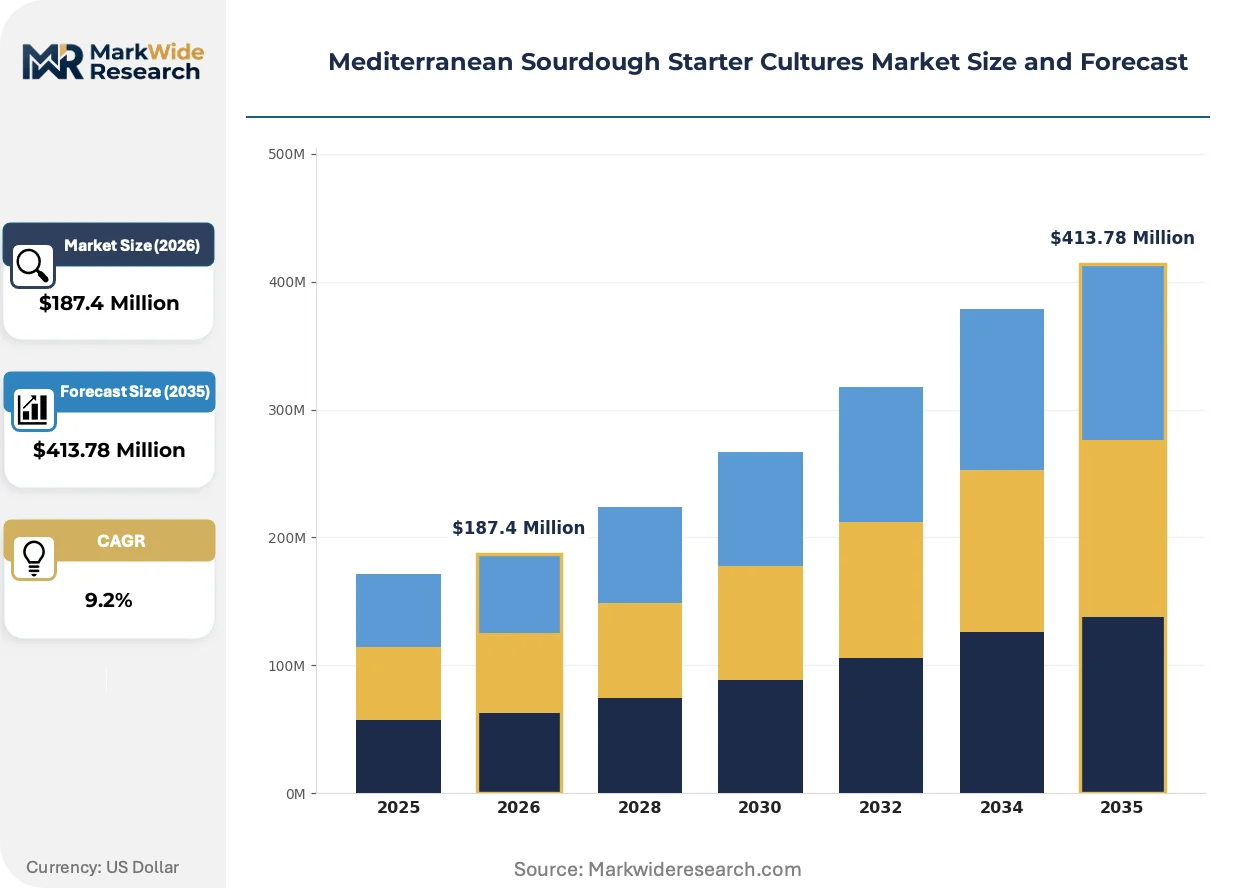
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $413.78 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Culture Type: Lacto-Fermentation, Wild Yeast, Mixed Cultures, Bakery-Specific Strains, Artisan Heritage Application: Bread Baking, Pastry Production, Specialty Food, Culinary Artisanal, Foodservice Industry End User: Bakeries, Artisan Producers, Food Labs, Culinary Schools, Foodservice Providers Packaging Type: Liquid Culture, Freeze-Dried, Frozen, Concentrated Paste, Bulk Containers |
| Companies Covered | Lesaffre, Puratos Group, Lallemand, IREKS, Ernst Böcker, AB Mauri, Pakmaya, Bakels Group, Chr. Hansen, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mediterranean Sourdough Starter Cultures Market Trends and Innovations
Biotechnology integration and regulatory documentation requirements are elevating technical barriers while creating tiered competitive positions based on strain authentication capabilities.
Cryopreservation is hybridizing with traditional propagation methods as biotechnology firms deploy automated liquid nitrogen systems for heritage Saccharomyces cerevisiae repositories. Artisan cooperatives in Tuscany and Provence now contract dedicated strain banking services rather than maintaining in-house cultures. This hybridization compresses the supplier base toward entities with capital-intensive infrastructure while marginalizing small-scale culture maintainers.
REACH compliance on fermentation substrate chemicals now requires full toxicological dossiers for synthetic nutrient media used in commercial propagation. Culture suppliers face reformulation costs or substrate switching to certified organic alternatives. Italian and Greek producers with existing organic supply chains capture cost advantages against competitors dependent on conventional chemical inputs.
Direct procurement from strain banks is displacing distributor intermediaries as large bakery groups seek authenticated documentation for clean-label claims. Consolidated purchasing departments in Spanish industrial baking chains now negotiate exclusive culture supply agreements. Southern France exhibits the most visible channel compression, with three major cooperatives establishing captive propagation facilities.
Mediterranean Sourdough Starter Cultures Market Segmentation
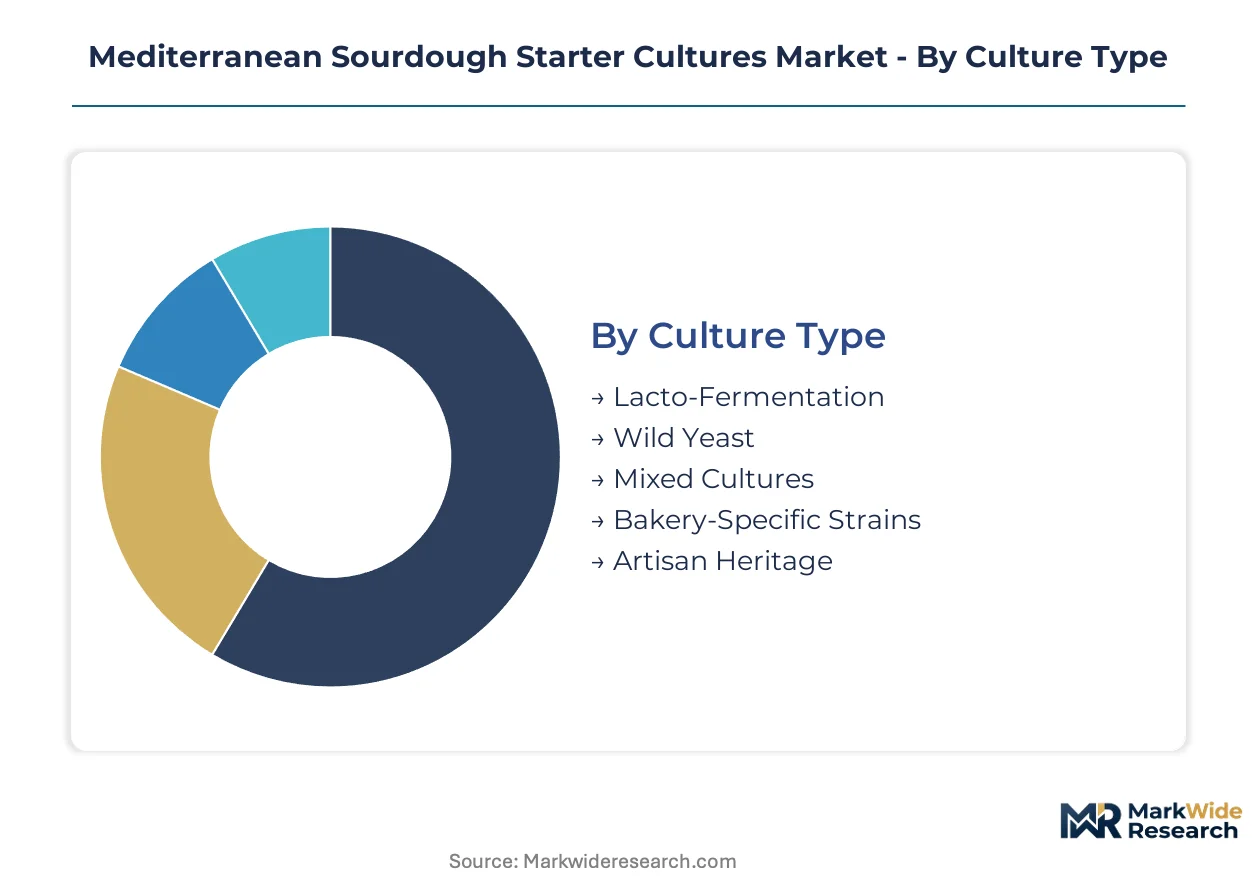
Segmentation in Mediterranean sourdough starter cultures reveals how technical specifications, regulatory requirements, and end-use constraints fragment procurement patterns across Southern European baking operations. Each dimension carries distinct margin profiles and compliance burdens that reshape supplier competitive positioning.
Culture Type:
Use cases span from industrial clean-label retrofits to heritage-authenticated artisan production, creating tiered value pools based on strain documentation depth.
- Wild Yeast:Spontaneously fermented Saccharomyces cerevisiae communities isolated from regional grain ecosystems. Demand concentrates in Tuscan and Provencal cooperatives seeking PDO compliance without commercial yeast declarations, constrained by EFSA Novel Food dossier timelines for non-traditional isolates.
- Mixed Cultures:Symbiotic Lactobacillus sanfranciscensis and wild yeast combinations maintained at controlled pH. Greek industrial bakeries retrofitting lines for clean-label positioning drive fastest volume expansion, though temperature sensitivity above 8°C limits distribution reach.
- Lacto-Fermentation:Heterofermentative bacterial dominance producing sharp acidity profiles.
- Bakery-Specific Strains:Custom-isolated cultures matched to individual facility microbiomes.
- Artisan Heritage:Documented lineages traceable to specific geographic origins and traditional propagation methods.
The dominant share belongs to Mixed Cultures, while Bakery-Specific Strains are closing the gap fastest.
Application:
Cost tiers separate commodity bread operations from premium positioning strategies that command authentication premiums.
- Bread Baking:Traditional ciabatta, focaccia, and Greek country loaves requiring extensibility and aromatic complexity. Italian PDO-certified facilities in Altamura and Matera mandate specific Lactobacillus dominance, directly shaping strain procurement specifications and documentation requirements.
- Specialty Food:Fermented bases for crackers, flatbreads, and savory applications. Spanish producers expanding clean-label portfolios drive demand for standardized concentrates that eliminate commercial yeast from ingredient declarations.
- Pastry Production:Laminated doughs and enriched formulations with controlled acidity.
- Culinary Artisanal:Restaurant and small-batch production emphasizing provenance storytelling.
- Foodservice Industry:High-volume consistent output for hospitality chains.
Bread Baking commands the largest revenue pool, though Specialty Food applications are expanding most quickly.
End User:
Customer type determines technical service intensity and strain authentication depth required for compliance.
- Bakeries:Mid-scale operations requiring standardized cultures with predictable fermentation timelines. Portuguese producers lack established heritage suppliers despite growing interest in traditional broa de milho, creating first-mover opportunities for documented strain banks.
- Artisan Producers:Small-batch operations prioritizing provenance and manual propagation techniques.
- Food Labs:R&D facilities developing novel culture combinations.
- Culinary Schools:Training institutions requiring consistent, reproducible cultures.
- Foodservice Providers:Hospitality and institutional catering operations.
Bakeries absorb the dominant procurement volume, while Artisan Producers are gaining share fastest through PDO certification expansion.
Packaging Type:
Supply concentration and margin structure vary sharply by preservation technology and cold-chain dependency.
- Freeze-Dried:Lyophilized cultures with extended ambient stability. Export-oriented Italian and Greek producers prioritize this format to reduce cold-chain expenditure for distant markets, capturing value through shelf-life extension rather than live-cell density.
- Liquid Culture:Active fermentation states requiring continuous temperature control. Southern France exhibits channel compression as cooperatives establish captive propagation facilities, displacing distributor intermediaries for authenticated documentation.
- Frozen:Cryopreserved concentrates for industrial-scale inoculation.
- Concentrated Paste:High-density formats for direct dough incorporation.
- Bulk Containers:Industrial-scale supply for large bakery groups.
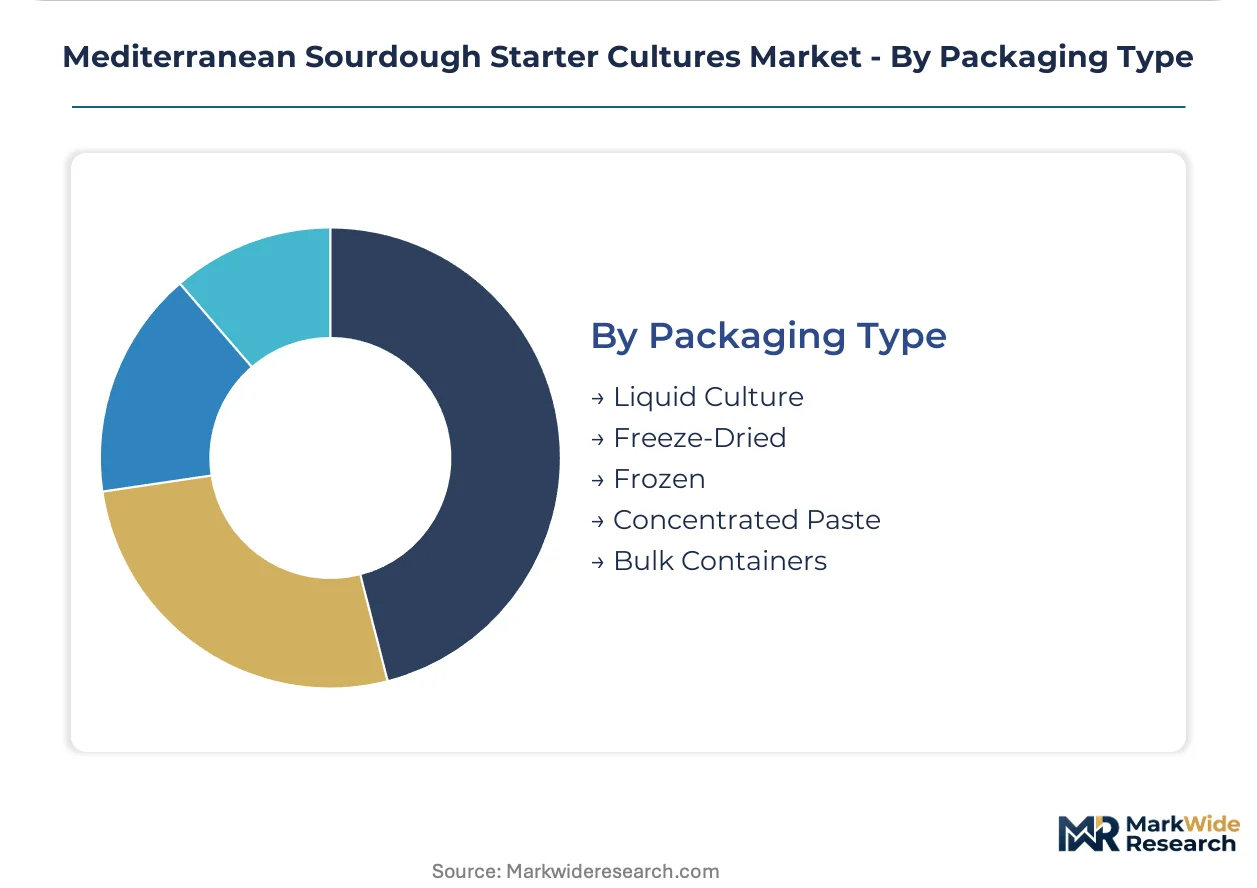
Freeze-Dried holds the leading position, while Liquid Culture is climbing the fastest as on-site propagation capabilities expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian producers export freeze-dried heritage cultures to Greek and Spanish industrial bakeries retrofitting for clean-label positioning. Cryopreservation advances extend distribution reach across Southern European trade corridors.
Italy
PDO certification mandates for Pane di Altamura and Matera drive specialized Lactobacillus sanfranciscensis procurement. The Ministry of Agricultural Policies enforces strict strain documentation protocols. Tuscan cooperatives now contract dedicated strain banking services rather than maintaining in-house cultures.
Greece
Industrial bakeries eliminate commercial baker's yeast to capture premium positioning, creating surge demand for wild yeast concentrates. EFSA Novel Food guidance shapes safety dossier preparation timelines. Athens-based facilities retrofit production lines with standardized culture inoculation systems.
Spain
Consolidated purchasing departments in industrial baking chains negotiate exclusive culture supply agreements. REACH compliance on fermentation substrate chemicals elevates reformulation costs. Catalonian producers expand clean-label portfolios with fermented bases for crackers and flatbreads.
France
Southern France exhibits pronounced channel compression as three major cooperatives establish captive propagation facilities. F-Gas Regulation on industrial refrigeration elevates cold-chain compliance costs. Provencal artisan operations source authenticated cultures directly from strain banks.
Portugal
Artisan bakeries lack established heritage strain suppliers despite growing interest in traditional broa de milho fermentation. EU-wide harmonization of artisan food standards creates regulatory tailwinds. Lisbon-area producers present first-mover positioning opportunities for documented regional isolate banks.
Mediterranean Sourdough Starter Cultures Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered value pools defined by strain authentication depth. Three European biotechnology firms concentrate heritage strain banking expertise, creating supply concentration risk for artisan bakeries. Strategic archetypes include cryopreservation-integrated culture banks, regional propagation specialists, and industrial-scale concentrate suppliers. Dominant competitive moves encompass direct procurement agreements displacing distributor intermediaries and captive propagation facility establishment.
Among the heritage-anchored tier, Lesaffre leverages decades of strain banking expertise to dominate European distribution networks. Puratos Group anchors competitive positioning through dedicated sourdough institutes training artisan bakers. Lallemand occupies the controlled-environment manufacturing segment standardizing wild yeast viability across preservation formats.
| Leading Market Players |
|---|
| Lesaffre |
| Puratos Group |
| Lallemand |
| IREKS |
| Ernst Böcker |
| AB Mauri |
| Pakmaya |
| Bakels Group |
| Chr. Hansen |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on cryopreservation-equipped strain banks compresses both pricing tier spreads and supply chain configuration across Mediterranean sourdough culture markets. Heritage authentication costs widen the gap between documented artisan strains and industrial concentrates while forcing bakeries toward direct procurement from limited supplier bases.
Pricing Analysis
Preservation-technology pricing gaps separate cryopreserved heritage strains from conventional freeze-dried formats and active liquid cultures. Three-tier pricing structure across authenticated heritage, standardized industrial, and generic commercial levels reflects certification depth and strain documentation costs. Price differentiation centers on EFSA Novel Food compliance status and organic substrate verification. Cost compression in the industrial tier intensifies as Greek and Spanish bakeries retrofit lines for clean-label positioning. Artisan producers demonstrate lowest price sensitivity due to PDO mandate requirements, while mid-scale bakeries exhibit highest elasticity to culture concentrate costs.
Supply Chain Analysis
Extended payment terms from consolidated Spanish industrial baking chains now strain propagation facility cash cycles across Southern European suppliers. Heritage strain banking expertise concentrates in Belgium, France, and Italy, with liquid nitrogen infrastructure anchoring high-value repository functions. Raw material dependencies center on organic rye and wheat flour feedstocks, liquid nitrogen for cryopreservation, and certified nutrient media compliant with REACH substrate regulations. Single-source vulnerability persists for Lactobacillus sanfranciscensis lineages authenticated for Italian PDO protocols. Distribution runs through direct procurement agreements displacing traditional distributor networks, particularly in Southern France where cooperatives establish captive propagation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial baker's yeast substitution threatens incumbent positioning as industrial facilities eliminate conventional leavening agents for clean-label claims. Defending heritage strain authentication moats becomes critical for margin preservation across the analysis window.
For Market Incumbents: Build cryopreservation infrastructure moats by expanding liquid nitrogen banking capacity in Tuscany and Provence to capture artisan cooperative outsourcing trends. Defend against precision fermentation entrants by deepening strain documentation archives for EFSA Novel Food pre-submission. Prioritize captive propagation partnerships with consolidated Spanish bakery chains to lock in exclusive supply agreements before channel compression accelerates.
For New Entrants and Emerging Players: Portuguese artisan bakery underpenetration offers first-mover positioning for documented regional isolate banks serving broa de milho fermentation revival. Target Athens-area industrial retrofit projects with standardized wild yeast concentrates compatible with existing inoculation systems. Enter through technical service partnerships that address the skill gap in live culture pH management rather than competing on strain price alone.
For Investors and Strategic Acquirers: Pending EU-wide harmonization of artisan food standards reshapes the acquisition landscape toward suppliers with pre-existing PDO documentation capabilities. Long-term viability centers on strain banking assets with authenticated Mediterranean lineages and cryopreservation infrastructure. Monitor EFSA Novel Food guidance evolution as the inflection signal for regulatory compliance cost escalation that favors scaled incumbents over niche specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryopreservation Infrastructure Expansion | Liquid nitrogen banking extends heritage strain viability from months to decades for export markets. |
| PDO Documentation Investment | Pre-submission dossiers for Italian Ministry protocols accelerate EFSA compliance timelines. |
| Direct Procurement Channel Development | Bypassing distributor intermediaries captures margin from consolidated Spanish bakery chains. |
| Organic Substrate Supply Chain Integration | REACH-compliant feedstock sourcing defends against reformulation cost disadvantages. |
| Technical Service Capacity Buildout | pH management training programs address artisan bakery skill gaps and lock in supplier relationships. |
Research Methodology
Desk research of EFSA guidance documents, EU agricultural policy filings, and fermentation substrate regulatory databases preceded structured interviews with strain banking technical directors, artisan bakery operations managers, industrial baking procurement leads, and clean-label product development specialists. Primary fieldwork combined facility assessments of cryopreservation infrastructure with validation against REACH compliance records and PDO certification protocols. Secondary sources encompassed trade customs data for culture concentrate flows, biotechnology firm SEC disclosures, and Italian Ministry of Agricultural Policies enforcement records. Bottom-up strain volume estimates triangulated against top-down market value projections.
Assumptions held organic rye and wheat flour price volatility within historical bands while varying EFSA Novel Food timeline scenarios across the projection horizon. The analytical framework modeled segmentation dimensions spanning culture preservation format, authentication certification tier, end-use application, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to strain inoculation rates across retrofitting industrial facilities and expanding PDO-certified artisan operations. Forecast inputs incorporated cryopreservation adoption curves and clean-label retrofit penetration patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by precision fermentation platforms or accelerated EU harmonization timelines would shift outcomes. Macroeconomic grain price shocks, regulatory reclassification of traditional strains, or breakthroughs in synthetic biology alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Global Food Anti Caking Agents Market
Food Additives and Ingredients
France Feed Additives Market
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market
Food Additives and Ingredients
DATEM Replacement Market
Food Additives and Ingredients
Egg Wash Substitute Market
Food Additives and Ingredients
South America Feed Additives Market
Food Additives and Ingredients
Food Antimicrobial Additives Market
Food Additives and Ingredients
Food Grade Stearic Acid Market
Food Additives and Ingredients
Egypt Food Preservatives Market
Food Additives and Ingredients
Australia Food Additives Market
Food Additives and Ingredients
Clean Label Food Ingredient Market
Food Additives and Ingredients
Locust Bean Gum Market
Food Additives and Ingredients
Activated Cake Emulsifier Market
Food Additives and Ingredients
Italy Food Enzymes Market
Food Additives and Ingredients
Canada Food Enzymes Market
Food Additives and Ingredients
Powdered Fats Market