
 North America Food Coating Ingredients Market | 2026-2036
North America Food Coating Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
North America Food Coating Ingredients Market Analytics
Buyer concentration among quick-service restaurant chains is pivoting toward dual-sourcing strategies for coating ingredients, fragmenting volume across specialized suppliers rather than consolidating with single vendors. Cargill Incorporated leverages its integrated oilseed processing to secure cost positions on emulsifier-based coatings. Kerry Group anchors its competitive stance through flavor-coating synergies that merge taste delivery with substrate adhesion. Bunge Limited competes on geographic proximity to Midwestern poultry processing corridors.
Food coating ingredients encompass batters, breadings, crumbs, and functional powders applied to proteins and snacks to create texture, retain moisture, and control oil uptake during frying or baking; these systems typically incorporate modified starches, hydrocolloids, and leavening agents engineered to specific viscosity and pickup-rate parameters for industrial fryer lines. The breadcrumb and batter category dominates volume throughput across North American protein processing facilities, while dry-form coatings command premium positioning due to extended shelf stability and reduced freight costs relative to liquid or paste alternatives. Snack applications represent the fastest-expanding demand channel as extruded and popped products adopt seasoned coatings for flavor differentiation.
The U.S. FDA governs ingredient declarations and allergen labeling for coating systems, while USDA FSIS inspects coated meat and poultry products for adherence to species-identity and pathogen-reduction standards; Canada’s CFIA enforces parallel Safe Food for Canadians Regulations that dictate imported coating ingredient compliance. The EPA oversees wastewater discharge from batter-breading operations, particularly in high-volume poultry facilities. Stakeholders must monitor evolving clean-label enforcement thresholds and state-level sodium-reduction mandates that reshape permissible coating formulations.
Market Dynamics
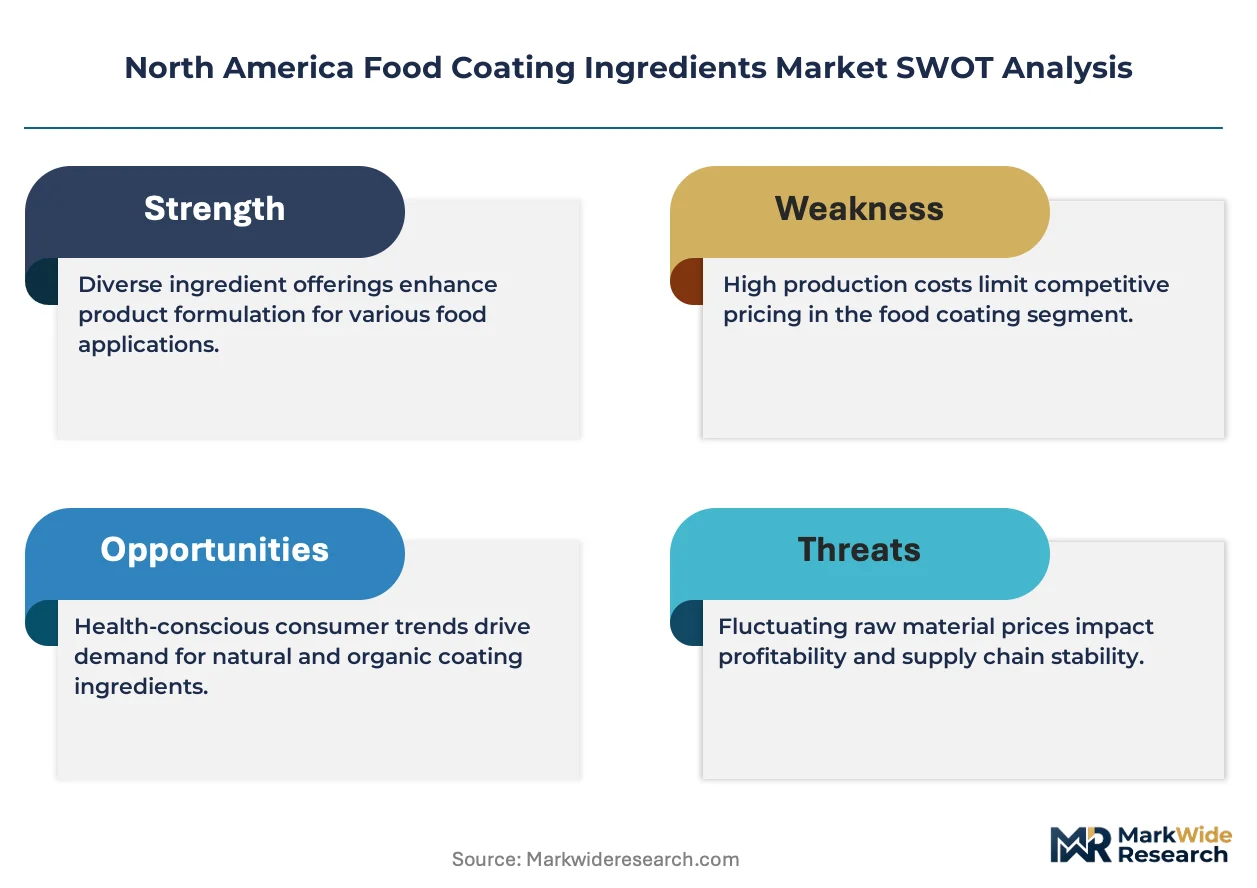
Quick-service restaurant chains are fragmenting procurement across dual-source coating suppliers while FDA clean-label mandates force simultaneous reformulation of legacy batter and breading systems.
Growth Catalysts
- Poultry Processing Cluster Density:The U.S. South and Midwest concentrate protein processing capacity, creating localized demand surges for industrial-scale coating systems.
- FDA Clean-Label Enforcement:Updated ingredient declaration requirements push manufacturers toward simplified, recognizable coating formulations that bypass consumer skepticism.
- Extruded Snack Expansion:Seasoned coatings for popped and extruded products unlock new volume channels beyond traditional protein applications.
Market Restraints
- Modified Starch Input Volatility:Corn and tapioca derivative pricing swings compress margin predictability for hydrocolloid-dependent coating systems.
- Midwest Supply Concentration:Bulk emulsifier and leavening agent production clusters in Illinois and Iowa corridors, exposing buyers to regional weather and logistics disruptions.
- Liquid Coating Substitution:Paste and suspension alternatives threaten dry-form market share where fryer-line retrofit costs deter equipment upgrades.
Strategic Opportunities
- Canadian Import Compliance Services:CFIA Safe Food for Canadians Regulations create advisory and certification revenue streams for U.S.-based coating ingredient exporters.
- Baked Protein Coatings:Oven-compatible batter systems penetrate health-positioned retail and foodservice segments previously dominated by fried applications.
- Direct-to-Processor Digital Channels:E-procurement platforms bypass traditional distributor markups for mid-sized poultry and snack manufacturers.
Industry Challenges
- Fryer-Line Integration Complexity:Viscosity and pickup-rate parameter mismatches between new coating chemistries and legacy industrial equipment delay production ramp-ups.
- Clean-Label Certification Timelines:USDA FSIS species-identity verification for reformulated coatings extends approval cycles, freezing inventory commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Food Coating Ingredients Market |
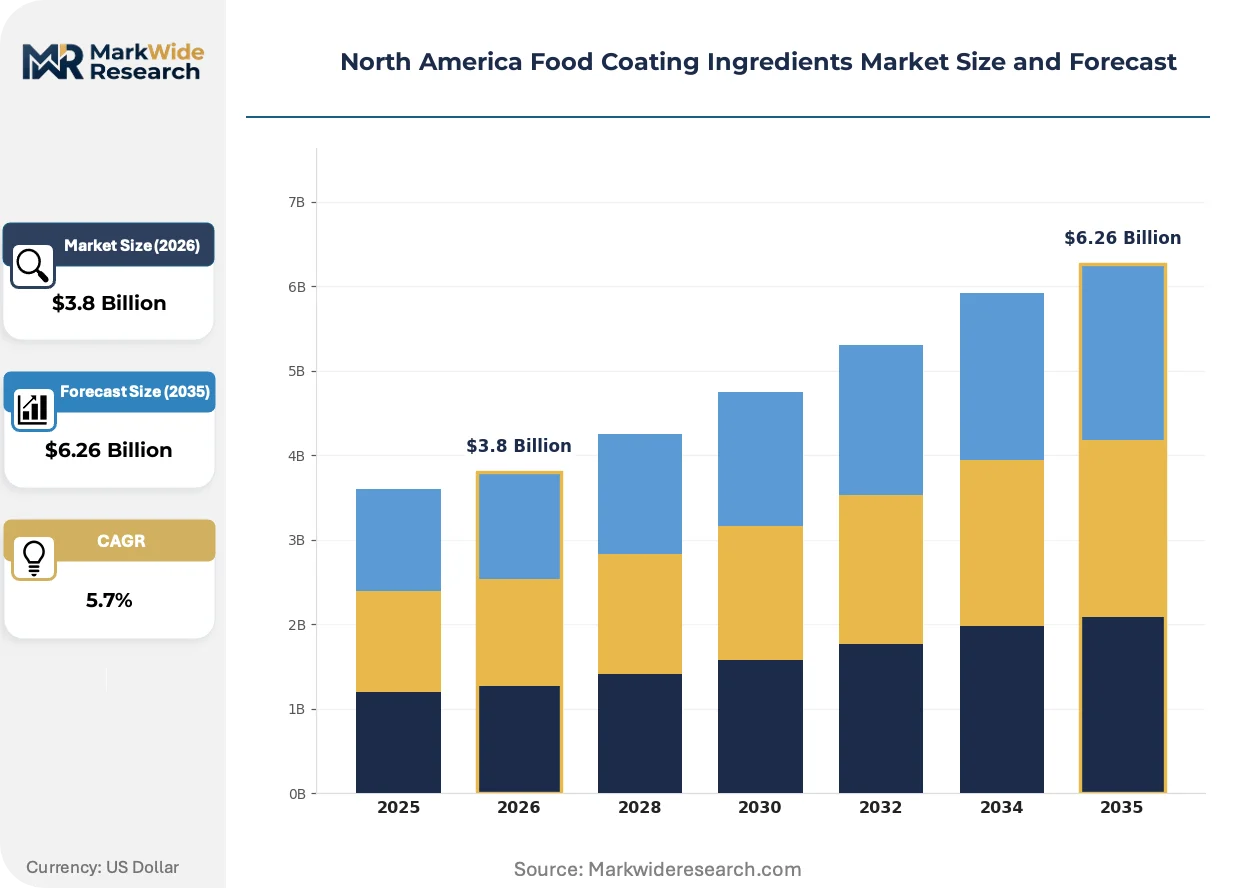
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breadcrumbs, Batters, Crumbs, Flours Application: Snacks, Poultry, Seafood, Meat Form: Dry, Liquid, Powder, Paste End User: Restaurants, Food Processors, Bakeries, Catering Services |
| Companies Covered | Bunge Limited, Kerry Group, Cargill Incorporated, Ingredion Incorporated, Tate & Lyle PLC, Archer Daniels Midland Company, PURATOS GROUP, Ashland Inc., Barry Callebaut, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Food Coating Ingredients Market Evolving Landscape
Coating ingredient innovation now centers on adhesion science and thermal stability rather than flavor delivery alone, as fryer-line efficiency and oil-uptake control become purchasing criteria.
Encapsulated leavening systems are expanding into high-volume poultry processing operations. These microencapsulated acid-base pairs release carbon dioxide on precise thermal triggers rather than hydration contact. Tyson Foods and Pilgrim's Pride trial lines in Arkansas and Georgia report 12-15% batter pickup consistency gains. The technology is expanding into premium retail private-label programs where texture uniformity commands shelf price premiums.
The FDA's updated Nutrition Facts label mandates for added sugars and sodium disclosure reshape coating formulation priorities. Manufacturers now engineer savory taste through yeast extracts and fermented dairy solids rather than sodium-dependent flavor systems. Breaded chicken and fish portions in U.S. retail channels face the steepest sodium-reduction compliance curves, driving accelerated R&D spend on umami-enhancing alternatives.
Quick-service chains are compressing supplier qualification cycles from 18-month windows to 9-month protocols. Dual-source mandates fragment volume commitments across specialized coating houses rather than consolidating with integrated ingredient conglomerates. This behavioral shift concentrates most visibly in Texas and California markets where regional franchisee cooperatives wield procurement autonomy.
North America Food Coating Ingredients Market Segmentation
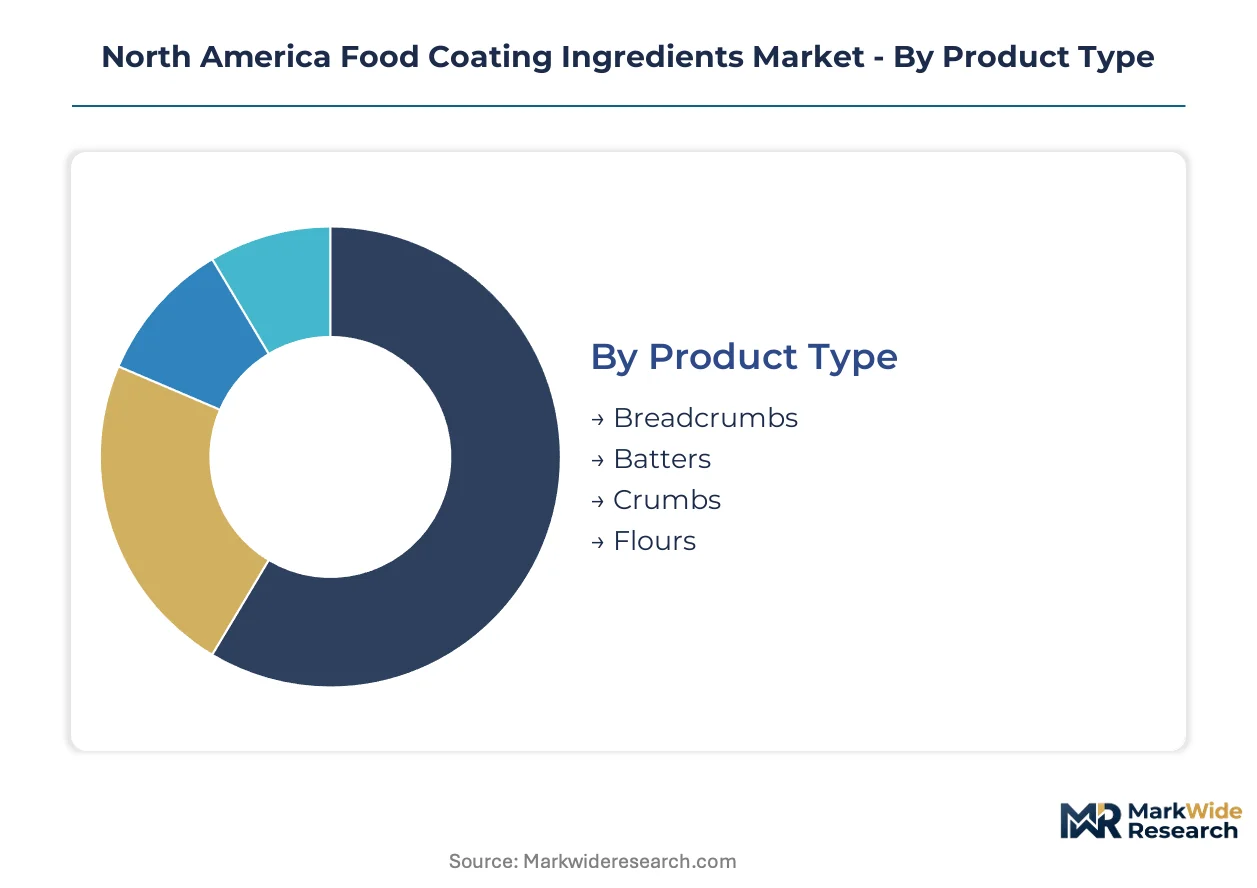
Coating ingredient procurement splits between commodity-scale protein processors demanding standardized viscosity specifications and quick-service chains requiring proprietary adhesion profiles. Segmentation reveals where formulation complexity commands premium positioning versus where bulk throughput drives cost engineering.
Product Type:
Standardized industrial batters dominate volume procurement from poultry processing clusters, while customized breadcrumb blends capture premium positioning through texture differentiation and clean-label certification.
- Breadcrumbs:Wheat-based and gluten-free variants engineered for specific porosity and browning kinetics. Poultry processors in Georgia and Arkansas specify particle-size distributions calibrated to their fryer-line conveyor speeds. Clean-label reformulations substituting modified starches with rice flour and ancient grain bases are climbing fastest as FDA disclosure mandates tighten.
- Batters:Viscosity-calibrated systems incorporating leavening agents, hydrocolloids, and emulsifiers for controlled pickup rates. Midwestern protein facilities standardize on mid-viscosity formulations that balance adhesion with oil-uptake reduction. Dual-sourcing strategies now fragment volume across specialized batter houses rather than consolidating with integrated suppliers.
- Crumbs:Japanese-style panko and extruded American-style fragments with distinct crunch retention profiles. Snack manufacturers specify crumb geometry for extruded product applications.
- Flours:Predust and adhesion layers applied before batter deposition, typically rice or wheat-based with protein content calibrated to substrate moisture.
Most installed capacity flows through Batters. Expansion is steepest in Breadcrumbs.
Application:
Volume concentration tracks protein processing geography, while margin expansion follows snack sector innovation cycles and health-positioned retail formats.
- Poultry:Batter and breading systems for bone-in and boneless segments, with USDA FSIS species-identity verification required for all reformulated coatings. Tennessee and Mississippi processing corridors drive bulk procurement of standardized viscosity systems. Sodium-reduction mandates from state-level health initiatives are forcing accelerated R&D on umami-enhancing yeast extracts.
- Snacks:Seasoned coatings for extruded, popped, and pellet-based products. Texas and California quick-service franchisee cooperatives are compressing supplier qualification cycles from eighteen to nine months. This segment is expanding most quickly as flavor differentiation becomes the primary competitive lever in crowded retail snack aisles.
- Seafood:Delicate adhesion systems for fish portions requiring freeze-thaw stability and minimal oil uptake during frying. Pacific Northwest processors specify lighter batter viscosities than poultry counterparts.
- Meat:Beef and pork coating applications, including value-added retail portions and foodservice patties. Smaller volume channel concentrated in Midwestern beef processing facilities.
Poultry commands the largest share of installed coating capacity. Snack applications are gaining share fastest.
Form:
Freight economics and fryer-line retrofit requirements determine adoption thresholds between dry convenience and liquid performance advantages.
- Dry:Shelf-stable powders and granules with extended storage windows and reduced transportation costs. Dominates procurement from high-volume poultry facilities with established pneumatic handling systems. Shelf stability commands premium positioning in remote Canadian processing locations where supply chain reliability outweighs formulation flexibility.
- Liquid:Suspension and emulsion coatings offering superior substrate adhesion and uniform coverage. Threatens dry-form share where capital expenditure for fryer-line upgrades is justified by throughput gains. Paste alternatives concentrate in artisanal and mid-scale bakery applications.
- Powder:Fine-particle coatings for snack seasoning and predust applications, distinct from granular breadcrumb systems in particle-size distribution.
- Paste:High-viscosity coatings for specialty applications including tempura and premium seafood preparations. Limited volume due to refrigeration requirements and shorter shelf life.
Dry forms absorb the majority of current production capacity. Liquid systems are climbing the fastest as fryer-line modernization accelerates.
End User:
Procurement sophistication varies from commodity-scale volume contracts to specification-driven custom formulation partnerships.
- Food Processors:Integrated poultry and protein facilities with in-house coating operations specifying viscosity, pickup rate, and thermal stability parameters. Arkansas and Georgia Tyson Foods and Pilgrim's Pride facilities trial encapsulated leavening systems for batter consistency gains. Dual-sourcing mandates fragment commitments across specialized suppliers.
- Restaurants:Quick-service chains and regional franchisee cooperatives with compressed nine-month supplier qualification protocols. Texas and California markets exhibit strongest procurement autonomy.
- Bakeries:Mid-scale operations requiring coating systems for value-added bread and pastry applications, typically sourcing through distributor channels.
- Catering Services:Smallest volume channel with fragmented procurement and limited specification requirements.
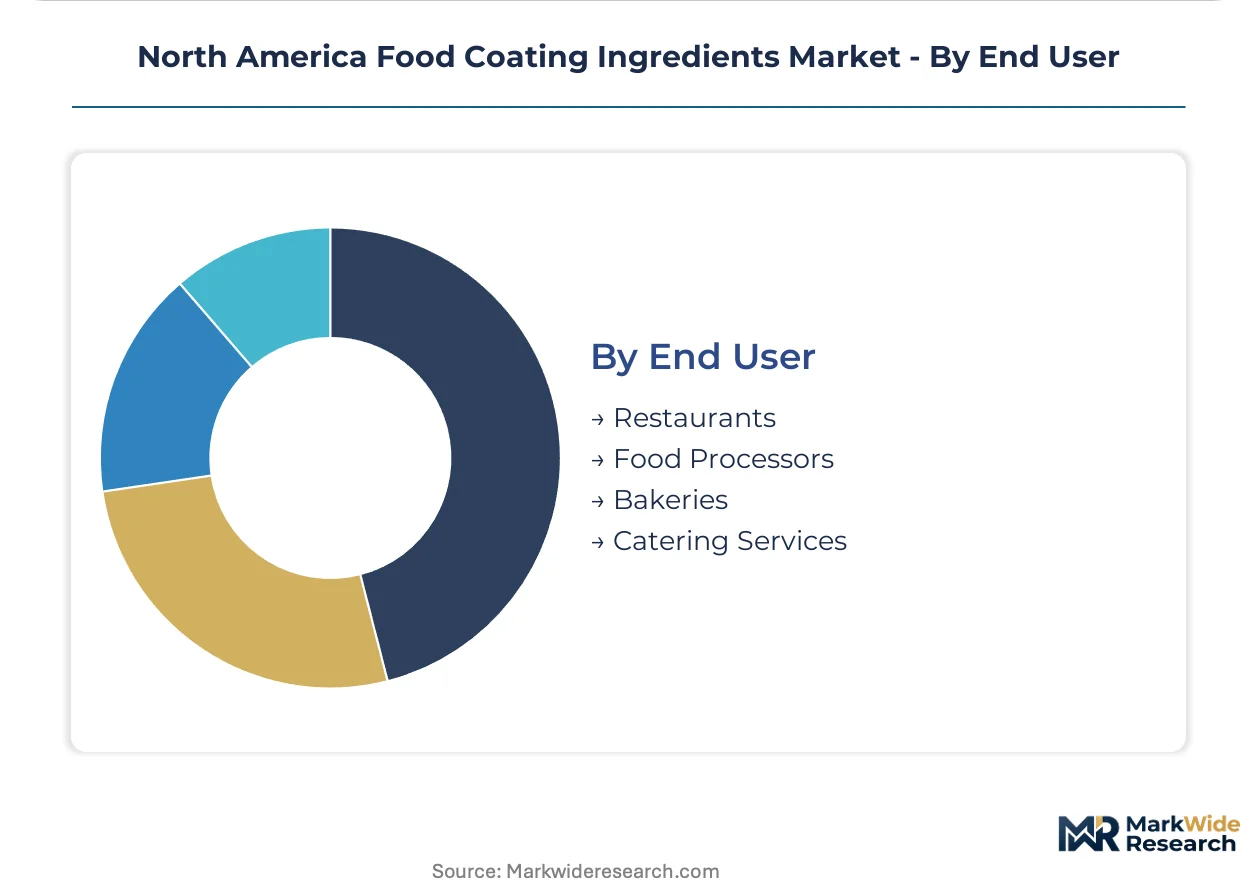
Food Processors channel the largest coating volumes. Restaurants are expanding procurement fastest as quick-service chains proliferate coated menu items.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's coating ingredient procurement trails the United States in absolute volume yet exceeds it in import dependency ratios, while Mexico's quick-service restaurant expansion outpaces both neighbors in percentage terms. Regional dynamics hinge on regulatory divergence, processing cluster density, and cross-border trade flows in batter and breading systems.
United States
Poultry processing corridors in Georgia, Arkansas, and Tennessee drive concentrated demand for industrial-scale batter systems with standardized viscosity parameters. The FDA's updated Nutrition Facts label mandates for sodium disclosure force reformulation toward yeast extract and fermented dairy solids. Tyson Foods and Pilgrim's Pride facilities in Arkansas trial encapsulated leavening technologies for pickup consistency gains.
Canada
CFIA Safe Food for Canadians Regulations impose parallel compliance burdens on U.S. coating ingredient exporters, creating certification service opportunities. Remote processing locations in Alberta and Saskatchewan prioritize dry-form coatings for shelf stability and supply chain reliability. Ontario's snack manufacturing base in the Toronto corridor adopts seasoned coatings for extruded product differentiation.
Mexico
Quick-service franchise expansion in Mexico City and Monterrey accelerates procurement of proprietary adhesion profiles for coated menu items. COFEPRIS labeling requirements for imported food ingredients add regulatory friction to U.S. supplier relationships. Poultry processing growth in Jalisco and Veracruz generates localized demand for breadcrumb and predust systems.
North America Food Coating Ingredients Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure that fragments volume through dual-sourcing mandates rather than consolidating around single vendors. Tiering separates integrated oilseed processors with captive emulsifier supply from specialized coating houses competing on formulation agility. Strategic moves concentrate on geographic proximity to poultry processing corridors and flavor-coating synergy development.
Within the integrated agribusiness tier, Cargill Incorporated and Bunge Limited exemplify scale-driven positions anchored by oilseed processing infrastructure. Kerry Group occupies a specialist position merging taste delivery with substrate adhesion capabilities. These three entities represent contrasting archetypes: upstream-integrated commodity players versus formulation-focused solution providers.
| Leading Market Players |
|---|
| Bunge Limited |
| Kerry Group |
| Cargill Incorporated |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Archer Daniels Midland Company |
| PURATOS GROUP |
| Ashland Inc. |
| Barry Callebaut |
| Others |
Value Network & Pricing Analysis
EPA wastewater discharge mandates for high-volume poultry facilities gate both qualified supply access and premium-tier pricing power, as coating ingredient suppliers must absorb compliance costs or forfeit contracts with major protein processors clustered in the U.S. South and Midwest.
Pricing Analysis
Capacity additions in Illinois and Iowa are reshaping price floors for leavening agents and emulsifiers, compressing margins for legacy suppliers. Pricing stratifies across clean-label certified, standard industrial-grade, and economy bulk tiers. Cost compression in economy batters is intensifying because corn and tapioca derivative volatility erodes hedging effectiveness. Quick-service restaurant chains exhibit highest price sensitivity due to dual-sourcing mandates, while food processors with captive coating operations show lowest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with modified starch suppliers concentrated in the U.S. Corn Belt. Production draws from Iowa, Illinois, and Indiana for corn derivatives, with Canadian prairie provinces contributing wheat-based inputs. Raw material dependencies center on corn starch, tapioca flour, and hydrocolloid gums. Tariff exposure on Canadian wheat imports creates structural risk for breadcrumb manufacturers. Distribution runs through regional ingredient distributors serving poultry processing corridors, with direct-to-processor digital channels emerging for mid-scale buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, justified by quick-service chains compressing supplier qualification cycles from eighteen to nine months and demanding proprietary adhesion profiles that command specification premiums.
For Market Incumbents: Anticipate margin pressure from liquid coating substitution threats by accelerating fryer-line integration partnerships that lock in dry-form volume commitments. Defend position through captive emulsifier supply anchored in Midwestern oilseed processing infrastructure. Prioritize USDA FSIS pre-certification for reformulated clean-label coatings to freeze out smaller competitors during extended approval cycles. For New Entrants and Emerging Players: Direct-to-processor digital procurement platforms offer the most penetrable white-space route, bypassing traditional distributor markups in mid-sized poultry and snack manufacturing segments. Target Canadian import compliance services as the least defended geography, where CFIA Safe Food for Canadians Regulations create advisory revenue streams for U.S.-based exporters. Lead with baked protein coating formulations that penetrate health-positioned retail segments previously dominated by fried applications. For Investors and Strategic Acquirers: Roll-up economics work for specialized coating houses because dual-sourcing mandates fragment volume commitments and create multiple mid-scale acquisition targets with complementary formulation capabilities. Long-term viability centers on five-to-ten year positioning for clean-label certification dominance as FDA enforcement thresholds tighten. The signal to watch is encapsulated leavening adoption rates in Arkansas and Georgia trial facilities as an inflection indicator for premium technology penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | FDA sodium disclosure mandates force yeast extract and fermented dairy substitution in breaded poultry portions. |
| Encapsulated Leavening Scale-Up | Tyson Foods and Pilgrim's Pride trial lines in Arkansas and Georgia validate 12-15% batter consistency gains. |
| Canadian Compliance Certification | CFIA Safe Food for Canadians Regulations create defensible advisory revenue for U.S. coating exporters. |
| Direct-to-Processor Digital Channel | E-procurement platforms bypass distributor markups for mid-sized poultry and snack manufacturers. |
| Baked Protein Coating Development | Oven-compatible batter systems penetrate health-positioned retail segments previously dominated by fried applications. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market combining executive interviews with protein processing plant managers, quick-service chain procurement directors, coating ingredient R&D leads, and distributor channel partners. Secondary validation draws from FDA labeling guidance documents, USDA FSIS inspection protocols, CFIA import compliance bulletins, and customs trade data on starch and hydrocolloid flows. Bottom-up volume modeling triangulates against top-down industry spend estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include coating form, application substrate, end-user procurement sophistication, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to base-year estimates, cross-checked against protein processing capacity expansion timelines and quick-service menu proliferation rates. Forecast inputs incorporate fryer-line modernization cycles and encapsulated leavening adoption trajectories.
Commodity starch price volatility, FDA clean-label enforcement timing, and COFEPRIS import friction are the dominant revision risks for coating ingredient demand projections. Forecasts reflect documented assumptions about poultry processing cluster expansion and quick-service coated menu penetration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Pea Starch Concentrate Market
Food Additives and Ingredients
Liquid Caramel Color Market
Food Additives and Ingredients
Europe Food Acidulants Market
Food Additives and Ingredients
Europe Food Emulsifiers Market
Food Additives and Ingredients
Granulated Tapioca Market
Food Additives and Ingredients
China Food Enzymes Market
Food Additives and Ingredients
PVPP Beer Stabilizer Market
Food Additives and Ingredients
Natural Food Additives Market
Food Additives and Ingredients
Transglutaminase Market
Food Additives and Ingredients
Food Enzymes Market
Food Additives and Ingredients
Latin America Food Enzymes Market
Food Additives and Ingredients
AKD Emulsifier Market
Food Additives and Ingredients
Global Food Texturants Market
Food Additives and Ingredients
Canada Food Acidulants Market
Food Additives and Ingredients
Europe Food Coating Ingredients Market
Food Additives and Ingredients
Brazil Food Preservatives Market