
 Food Grade Butyric Acid Market | 2026-2036
Food Grade Butyric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Butyric Acid Market Foresight
Animal nutrition is recalibrating the demand profile for food grade butyric acid as poultry and swine producers prioritize gut health over antibiotic growth promoters. Perstorp Group leverages its European manufacturing base to supply high-purity sodium butyrate to integrated feed compounders. Eastman Chemical Company anchors North American supply through its specialty additives division. OQ Chemicals GmbH competes on fermentation-derived butyric acid for natural-positioned feed brands.
Food grade butyric acid is a four-carbon short-chain fatty acid (C4H8O2) produced via chemical synthesis or microbial fermentation, typically supplied at minimum 99% purity for food and feed applications. Sodium butyrate dominates volume due to its thermal stability in pelleted feed, while calcium butyrate captures premium positioning in aquaculture and young animal diets. Flavor enhancer applications in processed foods sustain steady offtake, though nutraceuticals targeting gut-brain axis formulations represent the fastest-expanding margin pool.
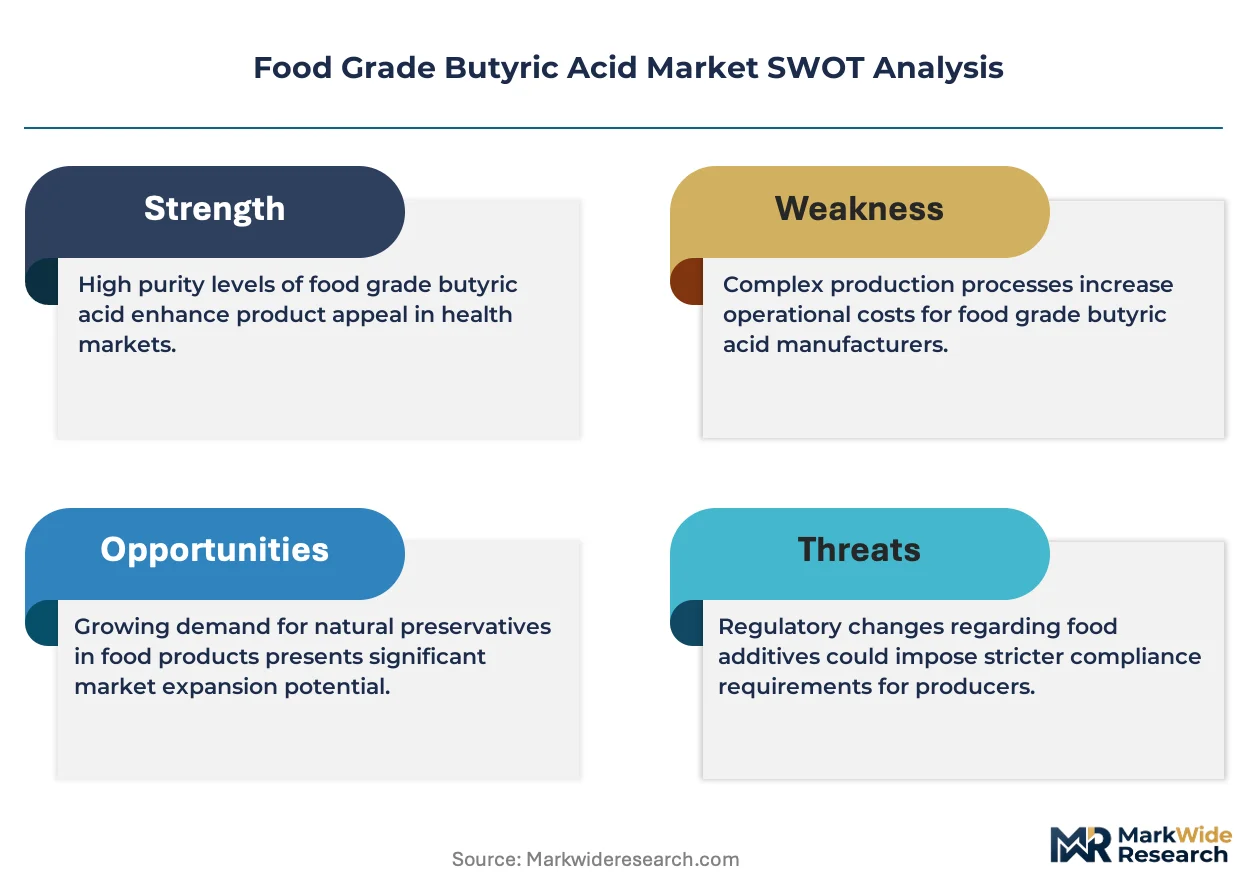
FDA's GRAS self-affirmation pathway and EFSA's feed additive re-evaluation framework shape product registration timelines and purity benchmarks for market access. China's SAMR implements GB standards for food-grade organic acids that constrain import specifications. Stakeholders must monitor regulatory divergence between fermentation-derived and petrochemical-sourced butyric acid classifications as sustainability claims harden into compliance requirements.
Market Dynamics
Feed additive re-registration requirements under EFSA guidelines are compressing supplier timelines and forcing purity upgrades across the sodium butyrate supply base. This regulatory tightening is consolidating procurement relationships around integrated compounders with captive quality assurance infrastructure.
Growth Catalysts
- EFSA Feed Additive Re-evaluation:Mandatory purity threshold upgrades for butyric acid derivatives are locking in long-term contracts between qualified suppliers and European feed compounders.
- Poultry Gut Health Prioritization:Broiler operations across Asia-Pacific are displacing antibiotic growth promoters with sodium butyrate formulations in starter and grower diets.
- Fermentation-Derived Positioning:Microbial production pathways are capturing premium shelf space in natural-positioned feed brands seeking non-petrochemical supply chains.
Market Restraints
- Crude Oil Price Volatility:Petrochemical-sourced butyric acid faces margin compression when naphtha feedstock costs spike, disadvantaging synthetic producers against fermentation alternatives.
- Shandong Supply Concentration:China's integrated feed compounders in this single province control disproportionate blending capacity, creating geographic dependency risk for international buyers.
- Calcium Butyrate Thermal Instability:The salt's decomposition during high-temperature pelleting limits application in standard poultry feed processing, constraining volume expansion.
Strategic Opportunities
- Aquaculture Formulation White Space:Shrimp and marine finfish diets in Southeast Asia remain underpenetrated by butyrate additives, offering first-mover positioning for stable-salt derivatives.
- Gut-Brain Axis Nutraceuticals:Human microbiome supplements targeting cognitive health represent a margin-rich expansion vector beyond traditional feed applications.
- SAMR GB Standard Alignment:Early compliance with China's food-grade organic acid specifications opens direct import channels bypassing third-country transshipment.
Industry Challenges
- Fermentation Scale-Up Expertise:Microbial production requires specialized bioprocess engineering talent scarce among traditional chemical manufacturers pivoting to bio-based routes.
- Dual-Source Certification Complexity:Suppliers maintaining both petrochemical and fermentation lines face duplicated analytical testing burdens under diverging regulatory classification frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Butyric Acid Market |
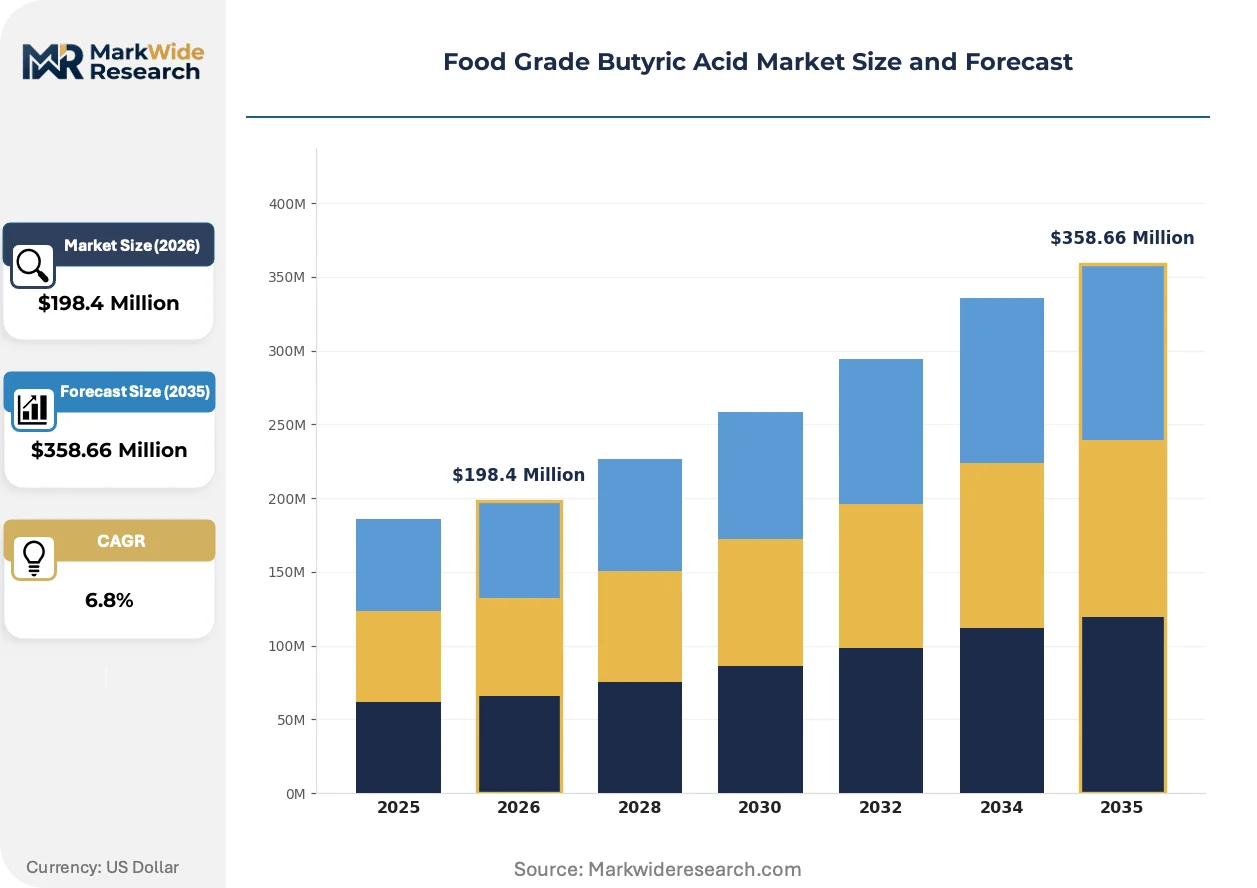
| Market Size in 2026 | $198.4 Million |
| Market Size in 2035 | $358.66 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Butyrate, Calcium Butyrate, Butyric Acid Powder, Butyric Acid Liquid Application: Feed Additives, Food Preservatives, Flavor Enhancers, Nutraceuticals, Animal Nutrition End User Industry: Animal Feed Manufacturers, Food Processing Units, Dietary Supplement Providers, Pharmaceutical Companies Packaging Type: Drums, Bulk Bags, Intermediate Bulk Containers, Bottles |
| Companies Covered | Kemin Industries, Beijing Huamaoyuan Fragrance Flavor Co., Ltd., Eastman Chemical Company, OXEA GmbH, Merck KGaA, Perstorp Group, Blue Marble Biomaterials, Yufeng International Co., Ltd., OQ Chemicals GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Butyric Acid Market Shifts & Advancements
Production technology and regulatory classification frameworks are diverging between synthetic and bio-based supply routes, fragmenting competitive positioning across end-use segments. This bifurcation is reshaping capital allocation and partnership strategies.
Encapsulated butyrate delivery systems using lipid or polymer matrices are modularizing the functional additive landscape. Poultry integrators in Brazil and Thailand are adopting these technologies to protect active ingredients through steam pelleting. The approach is compressing differentiation between commodity sodium butyrate and premium coated alternatives.
EFSA's 2023-2025 feed additive re-evaluation cycle is tightening impurity specifications for short-chain fatty acid salts. European compounders must resubmit dossiers with enhanced toxicological data, extending registration timelines. Sodium butyrate suppliers with existing EFSA approvals are capturing switching volume from delayed competitors.
Integrated feed manufacturers are consolidating procurement around single-source butyrate supply agreements with embedded technical service. This behavior is displacing spot market purchasing in China's Shandong and Guangdong provinces. Compounders with captive quality labs are extracting price concessions in exchange for volume commitments and formulation co-development rights.
Food Grade Butyric Acid Market Segmentation
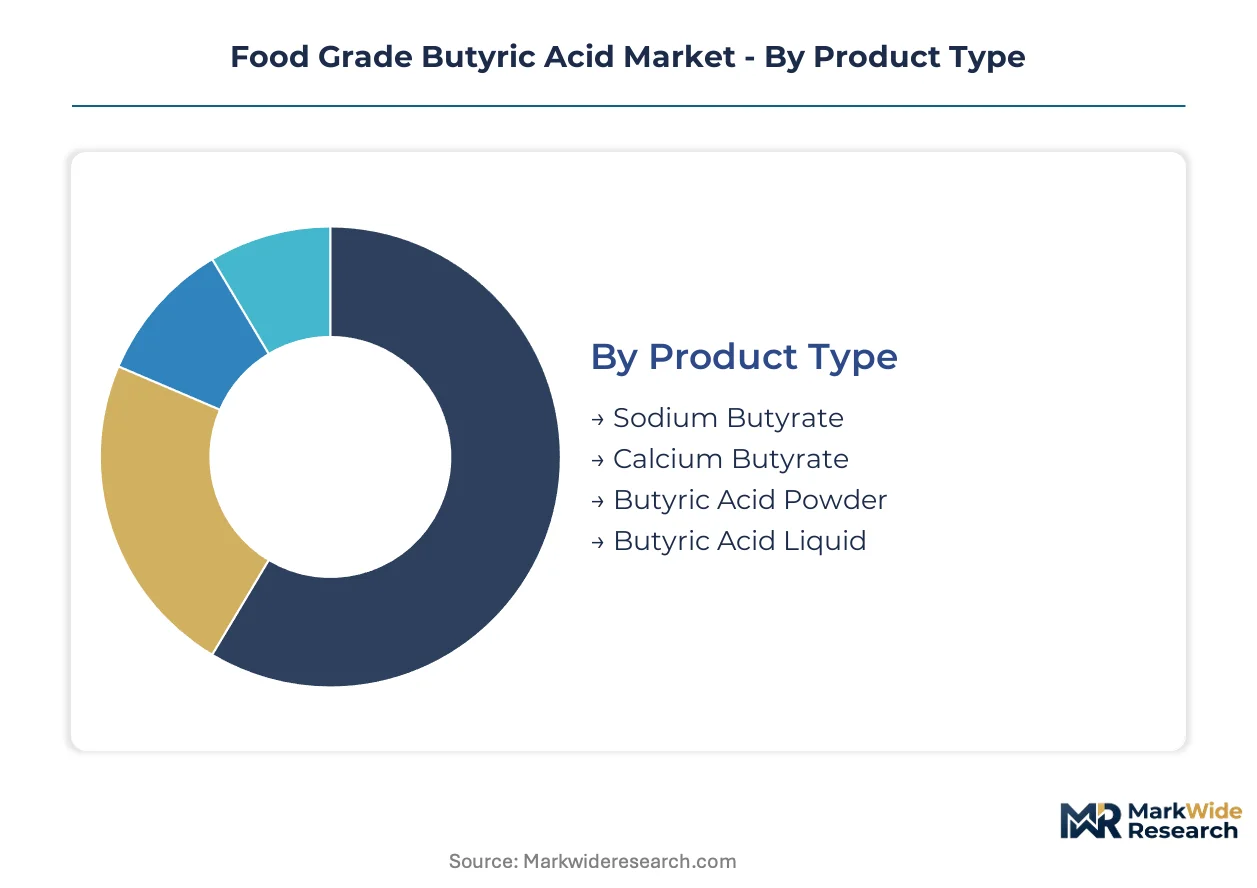
Segmentation in food grade butyric acid reveals how purity specifications, thermal stability requirements, and regulatory compliance burdens fragment procurement patterns across feed, food, and pharmaceutical channels. Buyers prioritize different salt forms and delivery formats based on processing temperatures, shelf-life demands, and geographic regulatory frameworks.
Product Type:
Cost tier separates commodity compounders from premium-positioned formulators seeking thermal resilience or clean-label fermentation sourcing.
- Sodium Butyrate:The sodium salt delivers superior thermal stability during steam pelleting above 85°C, making it indispensable for broiler and swine feed manufacturers in Vietnam and Thailand. Shandong province's integrated compounders consume the majority of Asian sodium butyrate volumes for captive blending operations.
- Calcium Butyrate:Higher calcium content buffers gastric pH more aggressively in young animal diets, though its decomposition threshold near 80°C restricts use to aquaculture feeds and cold-pelleted rations. Premium positioning in shrimp and marine finfish formulations across Indonesia and Malaysia sustains margin premiums over sodium variants.
- Butyric Acid Powder:Spray-dried microencapsulated forms target nutraceutical manufacturers requiring precise dosing in capsule and tablet applications.
- Butyric Acid Liquid:Free acid concentration above 99% serves flavor enhancer applications in processed dairy and baked goods where pH adjustment flexibility matters.
Sodium butyrate leads volumes today; calcium butyrate is gaining share fastest in aquaculture-specialized formulations.
Application:
Application maturity diverges sharply between regulated feed additives with re-registration burdens and emergent gut-brain axis nutraceuticals lacking standardized efficacy frameworks.
- Feed Additives:EFSA's re-evaluation cycle mandates enhanced toxicological dossiers for sodium butyrate approvals, locking in supplier-compounder relationships with existing registrations. European poultry integrators source exclusively from EFSA-qualified producers to avoid formulation disruptions.
- Animal Nutrition:Young animal diets for piglets and calves concentrate demand in Denmark and the Netherlands, where antibiotic growth promoter bans have accelerated butyrate adoption since 2006. Starter feed formulations specify minimum 30% coated butyrate inclusion to ensure ileal release.
- Food Preservatives:GRAS-affirmed applications in cheese and fermented meat products sustain steady offtake from North American dairy processors.
- Flavor Enhancers:Characteristic rancid-butter aroma compounds at low concentrations enhance umami perception in savory snack seasonings.
- Nutraceuticals:Microbiome supplements targeting cognitive health and mood regulation command the steepest price premiums per kilogram, though clinical substantiation requirements constrain mass-market penetration.
Feed additives dominate current procurement volumes; nutraceuticals show the steepest expansion trajectory in margin-adjusted terms.
End User Industry:
Customer scale and quality infrastructure determine whether buyers qualify for direct supply relationships or remain dependent on distributor intermediaries.
- Animal Feed Manufacturers:Integrated compounders with captive analytical laboratories in China's Shandong and Guangdong provinces negotiate multi-year supply agreements embedding technical service and formulation co-development rights.
- Food Processing Units:Mid-sized dairy and savory snack producers purchase through regional chemical distributors due to fragmented volume requirements and limited in-house quality assurance capabilities.
- Dietary Supplement Providers:Contract manufacturers serving the gut-brain axis segment demand fermentation-derived butyric acid with carbon-14 verification to support natural-positioned marketing claims.
- Pharmaceutical Companies:Excipient applications in controlled-release formulations require pharmacopeial-grade documentation and batch-specific impurity profiling that synthetic producers struggle to provide consistently.
Animal feed manufacturers absorb the majority of commodity tonnage; dietary supplement providers are climbing the fastest in value terms.
Packaging Type:
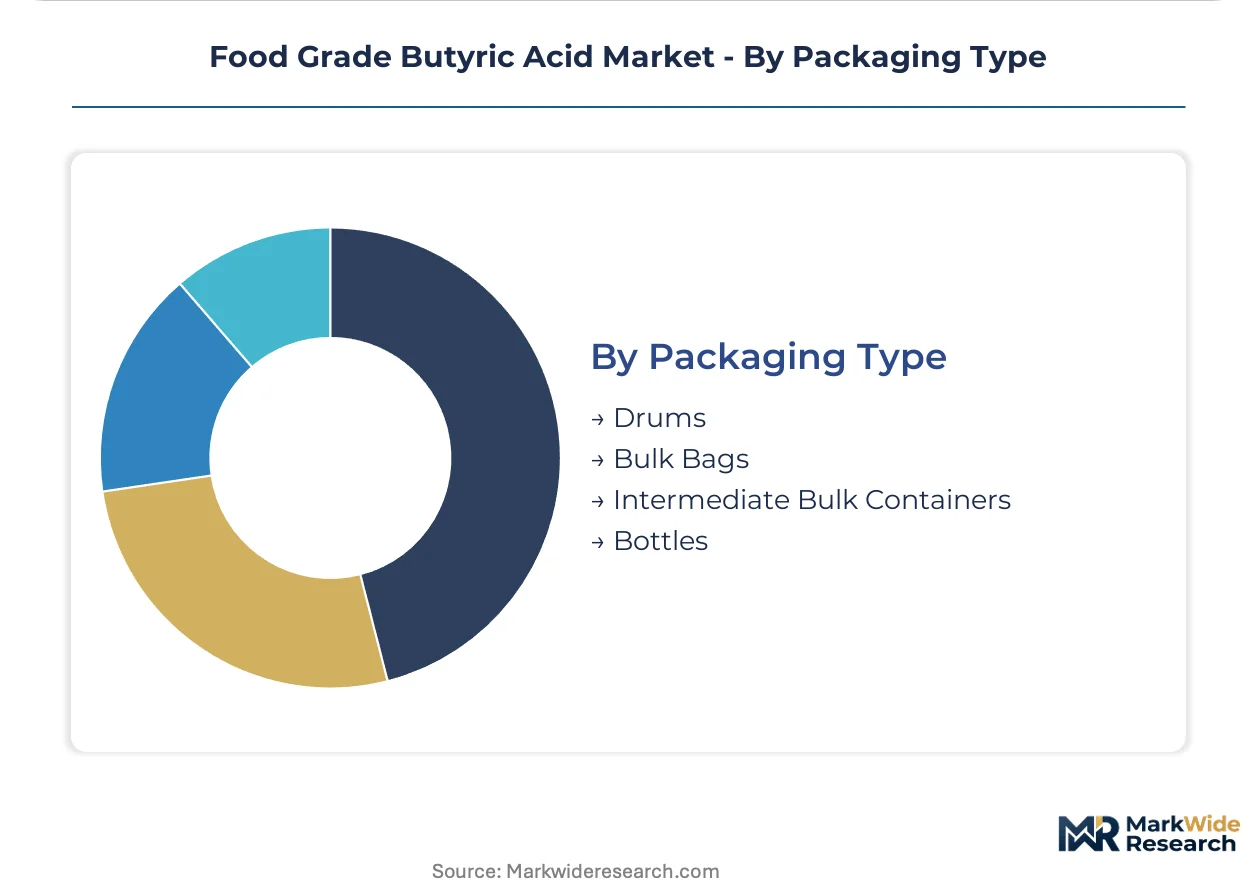
Volume scale and handling automation dictate packaging selection, with bulk formats capturing procurement concentration among integrated compounders and unitized formats serving fragmented food processor demand.
- Bulk Bags:One-tonne flexible intermediate bulk containers dominate sodium butyrate shipments to Shandong feed mills with pneumatic conveying systems and automated weighing infrastructure.
- Intermediate Bulk Containers:Rigid IBC totes suit mid-scale compounders lacking bulk handling equipment but requiring drum-scale efficiency improvements.
- Drums:Steel and fiber drums remain standard for calcium butyrate and liquid butyric acid where moisture sensitivity necessitates sealed unitization.
- Bottles:Laboratory and pilot-scale nutraceutical manufacturers source gram-to-kilogram quantities in amber glass with nitrogen headspace to prevent oxidation.
Bulk bags command the highest shipment volumes today; intermediate bulk containers are expanding most quickly among upgrading mid-scale compounders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing food grade butyric acid production capacity toward jurisdictions with streamlined feed additive approval pathways. Cost-of-compliance gaps between EFSA's re-evaluation requirements and China's SAMR GB standards are accelerating capacity expansion in Shandong and Guangdong provinces.
China
Shandong province's integrated feed compounders are building captive sodium butyrate blending capacity to serve poultry and swine operations across the Yangtze River Delta. SAMR's GB standards for food-grade organic acids constrain import specifications while favoring domestic fermentation-derived production. Qingdao and Weifang host the majority of new butyrate salt manufacturing facilities commissioned since 2022.
United States
GRAS self-affirmation pathways enable faster market entry for butyric acid derivatives targeting nutraceutical and flavor enhancer segments. FDA oversight of feed additive safety maintains rigorous documentation standards that favor established suppliers with dedicated regulatory affairs teams. Iowa and North Carolina poultry integrators source sodium butyrate through long-term contracts with Midwest chemical distributors.
Germany
EFSA's feed additive re-evaluation framework compresses supplier timelines for sodium butyrate dossier resubmission. REACH compliance obligations for petrochemical-sourced butyric acid create differentiation pressure against fermentation-derived alternatives. North Rhine-Westphalia's specialty chemical cluster houses analytical laboratories supporting toxicological data generation for European compounders.
Vietnam
Broiler operations in the Mekong Delta are displacing antibiotic growth promoters with sodium butyrate formulations in starter diets. The Ministry of Agriculture and Rural Development's feed safety regulations align with ASEAN harmonization efforts while permitting faster additive registration than European counterparts. Ho Chi Minh City serves as the distribution hub for imported butyrate salts entering Southeast Asian markets.
Brazil
Poultry integrators in São Paulo state are adopting encapsulated butyrate delivery systems to protect active ingredients through steam pelleting. ANVISA's feed additive registration requirements emphasize Good Manufacturing Practice certification over impurity threshold specifications. Campinas and Sorocaba concentrate formulation R&D activities for Latin American export-oriented broiler operations.
Food Grade Butyric Acid Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with fermentation-derived positioning commanding premium shelf space in natural-positioned feed brands. The supplier base concentrates around integrated chemical conglomerates with captive quality assurance infrastructure and dedicated regulatory affairs capabilities. Three archetypes dominate: petrochemical-sourced volume producers, fermentation-derived premium specialists, and regional compounders with captive blending operations. Competitive intensity centers on EFSA registration maintenance and backward integration into fermentation capacity.
Among European-based suppliers, Perstorp Group and OQ Chemicals GmbH exemplify divergent sourcing strategies within the same regulatory jurisdiction. Eastman Chemical Company anchors North American supply through established specialty additives distribution networks. Beijing Huamaoyuan Fragrance Flavor Co., Ltd. occupies a position serving flavor enhancer applications with proximity to China's processed food manufacturing clusters. These three entities represent the geographic and technological segmentation visible across the competitive set.
| Leading Market Players |
|---|
| Kemin Industries |
| Beijing Huamaoyuan Fragrance Flavor Co., Ltd. |
| Eastman Chemical Company |
| OXEA GmbH |
| Merck KGaA |
| Perstorp Group |
| Blue Marble Biomaterials |
| Yufeng International Co., Ltd. |
| OQ Chemicals GmbH |
| Others |
Supply & Pricing Matrix
Bioprocess engineering talent scarcity in Germany's North Rhine-Westphalia specialty chemical cluster amplifies labor-cost spreads between fermentation-derived premium tiers and petrochemical-sourced standard grades. Shandong province's captive blending workforce commands lower unit conversion costs, compressing distributor margins for international buyers sourcing sodium butyrate through third-party channels.
Pricing Analysis
Distributor margin layers absorb 15-25 point spreads between ex-works fermentation facilities and delivered feed mill pricing in Vietnam and Thailand. Three-tier pricing structure across EFSA-registered premium, SAMR-compliant standard, and unregistered economy grades separates procurement channels by certification burden. Cost compression in synthetic sodium butyrate intensifies when naphtha feedstock volatility spikes, forcing spot-market buyers toward contract-based long-term offtake with qualified suppliers. Mid-scale aquaculture formulators in Indonesia exhibit highest price sensitivity due to fragmented volume requirements, while European poultry integrators prioritize registration compliance over unit cost.
Supply Chain Analysis
Workforce availability constraints in microbial fermentation constrain capacity expansion beyond China's Shandong and Guangdong provinces, where skilled bioprocess technicians concentrate in captive blending operations. Supply draws from China, Germany, and the United States, with raw material dependencies spanning naphtha feedstocks, sodium hydroxide, and calcium carbonate. Single-source vulnerability concentrates in Shandong's integrated compounders, where geographic clustering creates disproportionate procurement risk for international buyers. Distribution runs through regional chemical distributors serving mid-scale food processors, while bulk pneumatic conveying systems at major feed mills enable direct supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EFSA's extended re-evaluation timelines and SAMR's streamlined GB standard compliance, with cost differentials favoring early entrants into China's direct import channels.
For Market Incumbents: To counter fermentation-derived premium positioning by OQ Chemicals and Blue Marble Biomaterials, synthetic producers must backward integration into captive bioprocess capacity or acquire existing microbial production facilities in Qingdao and Weifang. EFSA registration maintenance demands dedicated toxicological data generation capabilities in North Rhine-Westphalia analytical clusters, locking in switching costs for European compounders. For New Entrants and Emerging Players: Begin with aquaculture formulation white space in Southeast Asia, where shrimp and marine finfish diets remain underpenetrated by stable-salt butyrate derivatives. Vietnam's Mekong Delta broiler operations offer fastest additive displacement potential as antibiotic growth promoter bans accelerate. A fermentation-derived positioning with carbon-14 verification serves natural-positioned feed brands seeking non-petrochemical supply chain documentation. For Investors and Strategic Acquirers: Animal nutrition conglomerates with captive quality assurance infrastructure are the most active acquirer in this space, consolidating procurement relationships around integrated compounders with embedded technical service capabilities. Over a five-to-ten year viability window, targets should demonstrate existing EFSA approvals or SAMR GB standard alignment to bypass third-country transshipment. The signal to watch is EFSA's feed additive re-evaluation cycle completion rates, as delayed competitors surrender switching volume to qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive microbial production in Shandong insulates margin compression from naphtha volatility. |
| EFSA Registration Dossier Enhancement | Toxicological data investments in North Rhine-Westphalia laboratories secure European compounder switching volume. |
| SAMR GB Standard Early Compliance | Direct import channel access bypasses third-country transshipment cost layers for Chinese buyers. |
| Encapsulated Delivery System Development | Lipid-matrix technologies protect active ingredients through steam pelleting above 85°C in Brazilian integrators. |
| Aquaculture Formulation Partnership | Shrimp feed specialization in Indonesia and Malaysia commands calcium butyrate premium positioning. |
Research Methodology
Coverage spans China, Germany, the United States, Vietnam, and Brazil, with primary inputs from each market's feed additive procurement specialists and regulatory affairs directors. The analysis combines interviews with plant managers at sodium butyrate manufacturing facilities, procurement leads at integrated feed compounders, distribution channel partners in Ho Chi Minh City and Campinas, and technical R&D directors developing encapsulated delivery systems. Secondary validation draws from SAMR GB standard filings, EFSA feed additive re-evaluation dossiers, customs trade data, and SEC 10-K disclosures from specialty chemical conglomerates. Bottom-up volume modeling and top-down value triangulation cross-validate segment-level outputs.
Granularity extends to salt-form tier, end-use application, packaging format, and regional production hub across the modeling period. The analytical framework models sodium butyrate, calcium butyrate, and liquid acid variants separately, with thermal stability thresholds and certification requirements as industry-specific demand drivers. CAGRs derive from segment-level volume trajectories weighted by purity-adjusted pricing tiers. Forecast inputs include EFSA re-evaluation timeline assumptions, SAMR import specification evolution, and aquaculture feed formulation adoption curves in Southeast Asia.
Several conditions sit outside the modeled scope, including crude oil price volatility beyond historical bands, unanticipated EFSA impurity threshold revisions, and geopolitical disruption to Shandong manufacturing clusters. Forecasts reflect assumptions about regulatory pathway continuity and fermentation scale-up feasibility. Material deviation in EFSA approval timelines, SAMR enforcement intensity, or naphtha-corn feedstock cost spreads warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Fat Replacers Salt Reducers and Replacers Market
Food Additives and Ingredients
Potassium Lactate Market
Food Additives and Ingredients
Sodium Propionate Market
Food Additives and Ingredients
Egypt Food Emulsifiers Market
Food Additives and Ingredients
Oleic Acid Market
Food Additives and Ingredients
Glandular Ingredients Market
Food Additives and Ingredients
Mexico Food Emulsifiers Market
Food Additives and Ingredients
Food Grade Stearic Acid Market
Food Additives and Ingredients
Plant Based Preservatives Market
Food Additives and Ingredients
India Food Additives Market
Food Additives and Ingredients
North America Food Coating Ingredients Market
Food Additives and Ingredients
Beverage Clarifier and Stabilizer Market
Food Additives and Ingredients
Asia-Pacific Fermented Ingredient Market
Food Additives and Ingredients
Alcohol Additives Market
Food Additives and Ingredients
Germany Anticaking Market
Food Additives and Ingredients
Natural Food Preservatives Market