
 Global Food Grade Calcium Chloride Market | 2026-2036
Global Food Grade Calcium Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food Grade Calcium Chloride Market Foresight
Beverage producer demand is hardening as craft brewing and soft drink formulation expand calcium chloride use for water mineralization and pH control. TETRA Technologies Inc. leverages its brine processing infrastructure to serve North American beverage accounts. Solvay S.A. sustains European supply continuity through integrated chlor-alkali operations. Nedmag B.V. anchors North Sea sourcing advantages for dairy and brewing customers seeking low-magnesium grades.
Food grade calcium chloride denotes a purified calcium salt meeting stringent heavy metal and purity thresholds for direct food contact, typically manufactured via limestone-hydrochloric acid reaction or natural brine refinement with subsequent filtration and drying to achieve FCC or E509 compliance. Its primary commercial purpose centers on ionic calcium provision for protein coagulation, moisture binding, and osmotic control across food matrices. The firming agent segment commands premium positioning in cheese and pickle applications where calcium retention governs texture outcomes. Powder and flake forms dominate logistics economics for bulk dairy and meat processors, while liquid concentrate gains traction in automated brewery dosing systems. Dairy Products application leads volume absorption, though Brewing shows the fastest qualification pipeline among mid-sized craft operators.
FDA food additive regulations under 21 CFR 184.1193 establish calcium chloride purity floors for US market access, while EFSA E509 specifications govern European import eligibility and compendial testing protocols. China's SAMR and NMPA alignment with GB standards increasingly conditions Asian supplier qualification for export-oriented food processors. Stakeholders must monitor evolving heavy metal thresholds and certification reciprocity between FDA, EFSA, and Asia-Pacific regulators to preempt supply chain disruption and secure multi-jurisdictional market presence.
Market Dynamics
Calcium chloride supply chains are tightening around brine sourcing concentration in the North Sea and Michigan Basin, forcing dairy processors and breweries to dual-source or accept longer qualification timelines for FCC-grade material.
Growth Catalysts
- Cheese Curd Firming Demand:Artisan and industrial cheesemakers in Wisconsin and the Netherlands are expanding calcium chloride dosing to accelerate coagulation and improve yield recovery rates.
- EFSA E509 Alignment:European brewers seeking export certification are driving demand for low-magnesium flake grades that meet compendial heavy metal thresholds without secondary refining.
- Automated Dosing Systems:Liquid concentrate formats are penetrating craft brewing operations in Colorado and Oregon where precision mineralization controls water profiles for consistent fermentation.
Market Restraints
- Limestone Input Volatility:Feedstock costs for synthetic production routes fluctuate with construction-grade lime demand, compressing margins for FCC-dedicated lines.
- North Sea Supply Concentration:Nedmag B.V. and limited Dutch brine processors control premium low-magnesium reserves, creating single-source vulnerability for European dairy accounts.
- Magnesium Sulfate Substitution:Some pickle and tofu processors are trialing alternative firming agents where calcium retention is less critical to texture outcomes.
Strategic Opportunities
- Indian Dairy Formalization:FSSAI alignment with CODEX standards is opening import pathways for FCC-grade material as organized cheese production expands in Gujarat and Maharashtra.
- Cell-Cultured Protein Applications:Growth medium formulation for cultivated meat startups requires pharmaceutical-grade calcium salts with food-contact approval pathways.
- Direct-to-Brewery Distribution:Regional distributors are bypassing traditional chemical wholesalers to offer just-in-time liquid delivery with on-site storage tanks.
Industry Challenges
- Multi-Jurisdictional Certification Lag:Simultaneous FDA, EFSA, and SAMR qualification requires 18-24 month testing cycles that delay market entry for new production facilities.
- Legacy Equipment Retrofit Costs:Powder-handling systems in mid-sized dairy plants require pneumatic upgrades to safely manage hygroscopic flake material without caking or corrosion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food Grade Calcium Chloride Market |
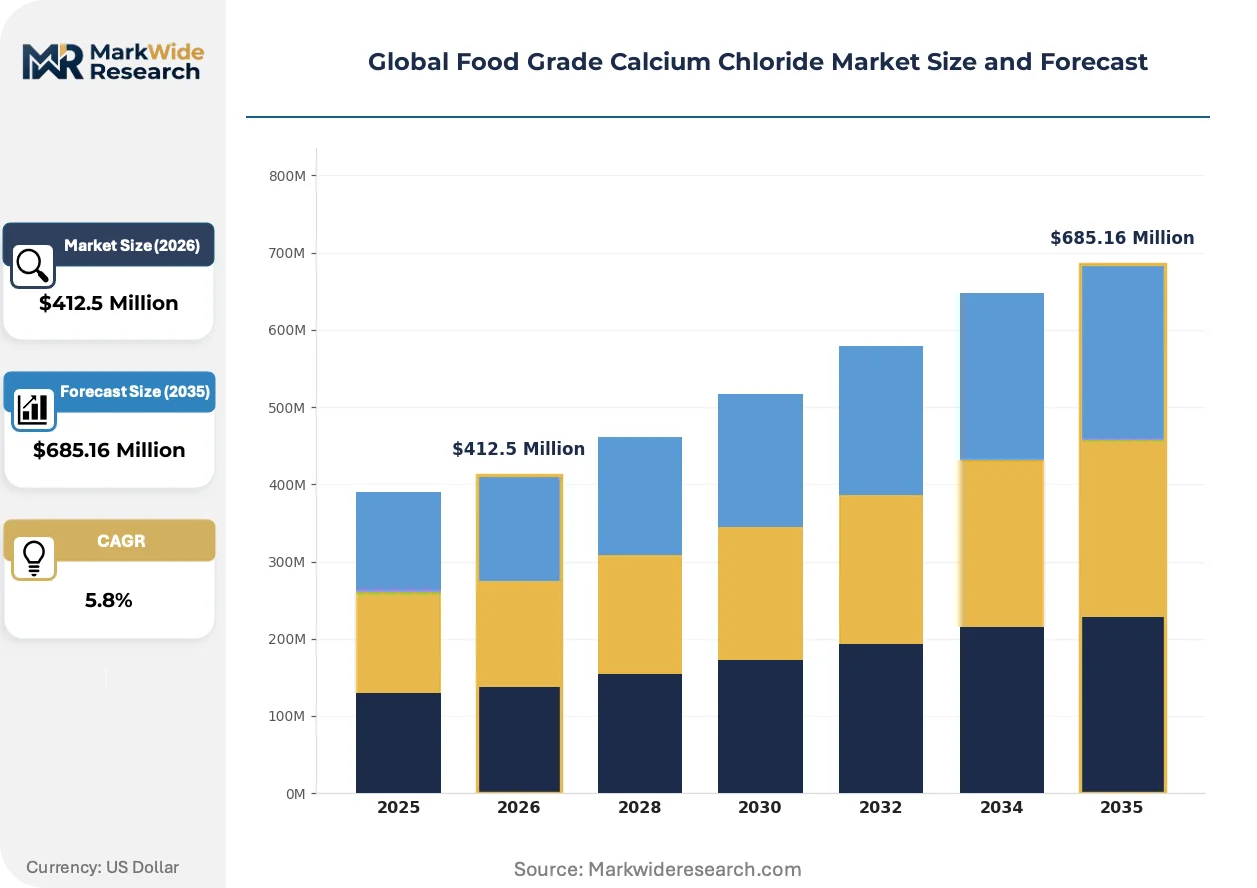
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Additive, Ice Control Agent, Firming Agent, Dehumidifier, Preservative Form: Powder, Flakes, Pellets, Liquid Concentrate, Anhydrous Application: Dairy Products, Meat Processing, Brewing, Pickling, Baking, Soft Drink Production End User: Dairies, Beverage Producers, Food Processors, Meat Packers, Bakeries |
| Companies Covered | Occidental Chemical Corporation, Solvay S.A., TETRA Technologies Inc., Nedmag B.V., Ward Chemical Ltd., Zirax Limited, Weifang Haibin Chemical Co. Ltd., Tokuyama Corporation, Anmol Chemicals Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food Grade Calcium Chloride Market Shifts & Advancements
Mineralization precision is becoming a competitive differentiator in beverage formulation, while regulatory convergence across FDA, EFSA, and Asia-Pacific frameworks is reshaping supplier qualification protocols.
Liquid calcium chloride concentrate is overtaking traditional flake delivery in automated brewery environments. The format enables closed-loop dosing with inline conductivity monitoring. Craft operators in Michigan and Washington are adopting tanker delivery with day-tank systems. This shift is compressing packaging and handling cost structures while demanding new logistics partnerships with food-grade bulk transport specialists.
EFSA's updated heavy metal thresholds for E509 are forcing European importers to reject Chinese material lacking third-party analytical certification. The regulation tightens lead and arsenic floors effective across all member states. German and Czech brewing conglomerates are consolidating supplier lists to pre-qualified Dutch and domestic sources, accelerating documentation requirements for traceability.
Certification-driven procurement is consolidating buyer preferences around suppliers with simultaneous FDA, EFSA, and NMPA registrations. Large dairy processors in California and Wisconsin are embedding compliance documentation into ERP systems for automated lot rejection. This behavioral shift favors incumbent producers with established multi-jurisdictional testing infrastructure over regional specialists lacking global regulatory coverage.
Global Food Grade Calcium Chloride Market Segmentation
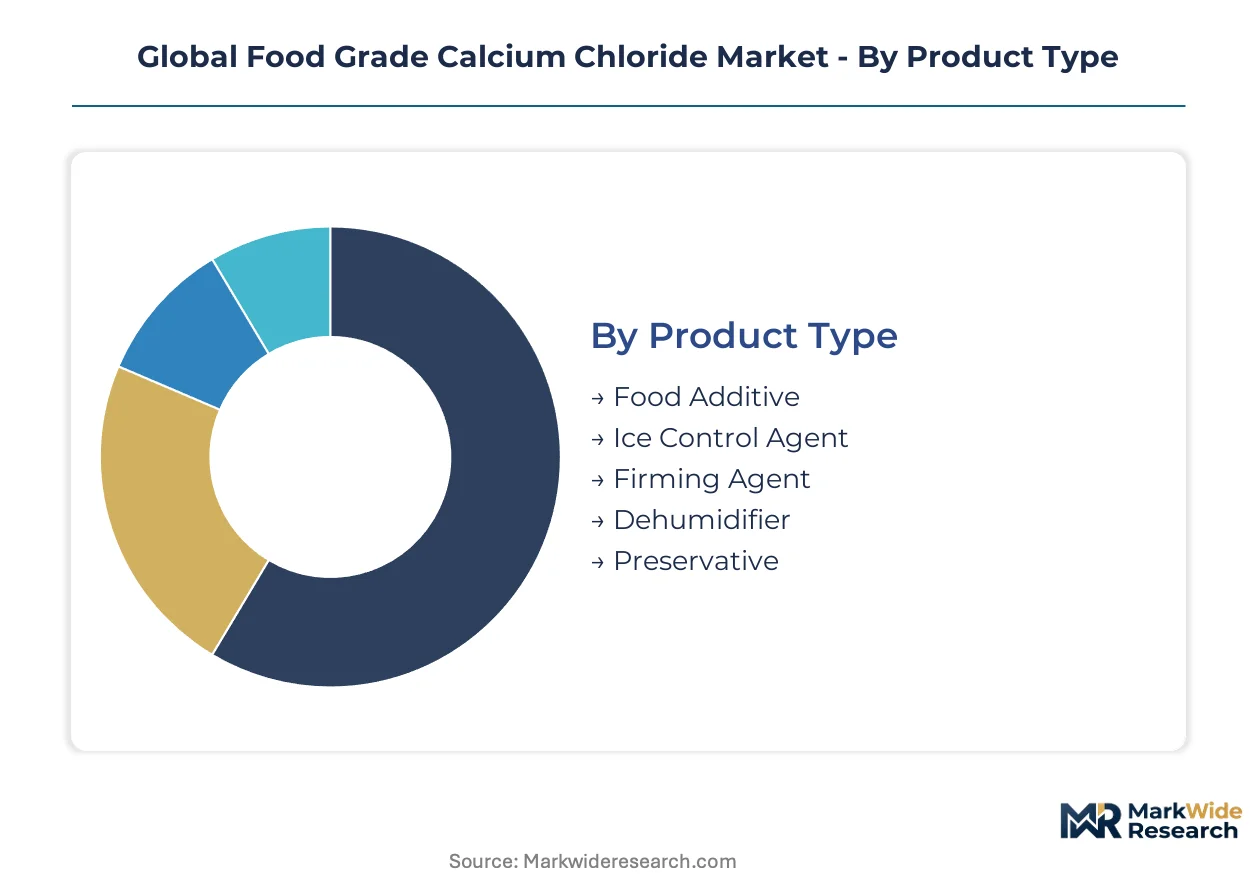
Calcium chloride segmentation reflects divergent purity thresholds and delivery formats across food matrices. Protein coagulation requirements in cheese production differ materially from mineralization needs in brewing water treatment. Each segment carries distinct FCC compliance burdens and logistics economics that reshape supplier selection criteria.
Product Type:
Purity specifications and functional certification separate additive categories across protein systems and moisture control applications.
- Firming Agent:High-purity calcium chloride maintains ionic calcium availability for casein coagulation in cheddar and gouda production. Wisconsin and Dutch cheese corridors absorb premium-grade material where yield recovery rates govern processor economics.
- Food Additive:General-purpose FCC-grade material serves multiple matrices including tofu precipitation and sports drink fortification. Beverage formulators in Germany and the United States specify heavy metal thresholds below baseline FCC floors for export-ready products.
- Ice Control Agent:Lower-purity grades permitted for indirect food contact in cold chain logistics.
- Dehumidifier:Anhydrous formats manage moisture in bulk grain storage and shipping containers.
- Preservative:Osmotic control applications in canned vegetables and brined meats.
Mature deployment sits with Firming Agent specifications in organized dairy sectors. Newer deployment is concentrated in Preservative applications for extended-shelf-life processed foods.
Form:
Physical state determines handling infrastructure requirements and dosing precision across manual and automated production environments.
- Liquid Concentrate:Closed-loop delivery systems enable inline conductivity monitoring for brewery water mineralization. Craft operators in Colorado and Michigan adopt tanker-fed day-tank configurations that eliminate manual handling.
- Flakes:Hygroscopic crystalline material dominates bulk dairy procurement where pneumatic conveyance systems manage moisture absorption risks. Dutch and Michigan Basin processors favor low-magnesium flake grades for EFSA E509 alignment.
- Powder:Fine-ground material for dry-blend beverage premixes and baking applications.
- Pellets:Low-dust format for meat packing brine saturation systems.
- Anhydrous:Maximum calcium content per unit weight for shipping efficiency in dehumidification.
Flake formats retain volume leadership in dairy procurement. Liquid Concentrate gains share fastest where automated dosing infrastructure spreads.
Application:
End-use matrices impose distinct ionic calcium requirements and regulatory documentation burdens.
- Dairy Products:Cheese curd firming and whey processing absorb the largest volume share. Artisan and industrial producers in the Netherlands and Wisconsin expand dosing rates to accelerate coagulation kinetics.
- Brewing:Water profile adjustment for fermentation consistency drives specification intensity. German and Czech brewing conglomerates consolidate supplier lists around pre-qualified Dutch sources with EFSA documentation.
- Meat Processing:Brine injection and moisture retention in cured products.
- Pickling:Firming agent replacement for alum in cucumber and olive processing.
- Baking:Dough conditioning and yeast activation in commercial bread production.
- Soft Drink Production:Mineral fortification and pH stabilization in carbonated formulations.
Dairy Products anchors current volume absorption. Brewing shows the steepest expansion trajectory among mid-sized craft operators building automated systems.
End User:
Procurement scale and compliance sophistication separate buyer categories across the value chain.
- Dairies:Large cooperatives in California and Wisconsin embed FCC documentation into ERP systems for automated lot rejection. Multi-jurisdictional qualification requirements favor incumbent suppliers with simultaneous FDA and EFSA registrations.
- Beverage Producers:Consolidated brewing groups and soft drink manufacturers specify low-magnesium grades with third-party analytical certification. German accounts reject Chinese material lacking EFSA-aligned heavy metal testing.
- Food Processors:Diversified manufacturers managing multiple additive categories.
- Meat Packers:Brine saturation operations with corrosion-resistant equipment requirements.
- Bakeries:Regional and national chains with dry-blend formulation needs.
Consolidated procurement sits with Dairies. Emerging qualification activity concentrates in Beverage Producers retrofitting for automated mineralization control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in North Sea brine corridors and Michigan Basin salt deposits, while consumption clusters in dairy processing belts and craft brewing centers across three continents. Supply geography and demand geography diverge sharply.
United States
Wisconsin and California dairy cooperatives expand calcium chloride dosing for cheddar and mozzarella yield optimization. FDA 21 CFR 184.1193 purity floors govern domestic procurement, with automated ERP lot rejection systems spreading among large processors. Michigan Basin brine operations anchor supply for Great Lakes beverage producers retrofitting for liquid concentrate delivery.
Netherlands
Gouda and Edam cheesemakers in Noord-Holland and Friesland drive premium-grade absorption for curd firming applications. EFSA E509 specifications tighten heavy metal thresholds, rejecting Chinese material lacking third-party certification. Nedmag B.V. and limited Dutch brine processors control low-magnesium reserves, creating single-source dependency for German and Czech brewing accounts.
Germany
Bavarian and North Rhine-Westphalian brewing conglomerates consolidate supplier lists around pre-qualified Dutch sources with EFSA documentation. The country's federal food safety authority enforces E509 compliance across all member state imports. Munich and Hamburg craft operators adopt automated dosing systems for precision water mineralization.
India
Gujarat and Maharashtra organized cheese production expands, driving FSSAI alignment with CODEX standards for FCC-grade import pathways. The national food regulator conditions export-oriented processor qualification on heavy metal testing protocols. Ahmedabad and Mumbai dairy clusters represent the fastest formalization trajectory among emerging markets.
China
Weifang and Shandong Peninsula chemical processors face EFSA rejection for heavy metal non-compliance, compressing export eligibility. SAMR and NMPA GB standard alignment increasingly conditions Asian supplier qualification. Domestic tofu and pickle processors trial magnesium sulfate substitution where calcium retention proves less critical.
Global Food Grade Calcium Chloride Market Competitive Landscape
Top-tier vendors anchor integrated chlor-alkali and brine processing infrastructure, while mid-scale specialists occupy regional distribution niches. The market structures around purification capability and multi-jurisdictional certification breadth. Three archetypes dominate: North Sea brine processors with low-magnesium reserves, integrated chemical conglomerates with FCC-dedicated lines, and regional distributors with direct-to-brewery logistics. Competitive moves concentrate on qualification timeline compression and automated dosing system partnerships.
Among integrated chemical producers, Solvay S.A. and Occidental Chemical Corporation exemplify the certification-heavy tier with simultaneous FDA and EFSA registrations. TETRA Technologies Inc. occupies a position within the North American brine processing archetype, leveraging Michigan Basin infrastructure for beverage account service. These three entities represent the dominant competitive anchors, with specialization in liquid concentrate logistics and heavy metal compliance documentation separating premium positioning from commodity supply.
| Leading Market Players |
|---|
| Occidental Chemical Corporation |
| Solvay S.A. |
| TETRA Technologies Inc. |
| Nedmag B.V. |
| Ward Chemical Ltd. |
| Zirax Limited |
| Weifang Haibin Chemical Co. Ltd. |
| Tokuyama Corporation |
| Anmol Chemicals Group |
| Others |
Supply & Pricing Matrix
Construction-grade lime index volatility cascades through synthetic production routes into three-tier pricing structure across premium, standard, and economy levels for FCC-dedicated lines. Dairy processors in Wisconsin and brewing conglomerates in Germany absorb divergent cost pass-through rates depending on qualification documentation burdens.
Pricing Analysis
Margin tightening in standard-grade flake material reflects limestone input cost pass-through and construction-sector demand competition for lime feedstock. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-registered Dutch brine material from Michigan Basin synthetic output and unqualified Chinese imports. Certification-driven procurement compresses price elasticity among large dairy cooperatives embedding compliance into ERP systems. Mid-sized craft breweries exhibit highest price sensitivity as they retrofit for automated liquid concentrate dosing.
Supply Chain Analysis
EFSA E509 third-party certification requirements gate European market access and consolidate procurement around pre-qualified Dutch and domestic sources. Supply concentrates in the Netherlands, Michigan Basin, and Shandong Peninsula, with brine-derived low-magnesium reserves anchoring premium positioning. Limestone, hydrochloric acid, and natural brine feedstock dependencies expose synthetic producers to construction and chlor-alkali sector demand cycles. Single-source vulnerability around Nedmag B.V. and limited Dutch brine processors creates structural concentration risk for German brewing accounts. Distribution runs through regional chemical wholesalers, though direct-to-brewery tanker delivery partnerships are displacing traditional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid concentrate automation is displacing manual flake handling in craft brewing, compressing packaging economics and demanding new logistics infrastructure partnerships.
For Market Incumbents: Acquire FCC-dedicated brine processing assets in the North Sea corridor to secure low-magnesium reserve access and preempt magnesium sulfate substitution trials in pickle and tofu segments. Deepen backward integration into Michigan Basin salt deposits to insulate beverage account service from construction-grade lime demand cycles. Invest in simultaneous FDA, EFSA, and SAMR testing infrastructure to compress 18-24 month qualification timelines. For New Entrants and Emerging Players: Automated dosing system integration offers entry pathway into Colorado and Oregon craft brewing clusters lacking legacy powder-handling infrastructure. Target Indian dairy formalization in Gujarat and Maharashtra where FSSAI CODEX alignment creates import qualification windows for FCC-grade material. Lead with direct-to-brewery liquid delivery partnerships featuring on-site day-tank storage. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale regional distributors with direct-to-brewery logistics capabilities in underserved craft brewing corridors. Five-to-ten year viability hinges on multi-jurisdictional certification breadth rather than commodity scale. Monitor EFSA heavy metal threshold enforcement as signal for Chinese material exclusion intensity and Dutch source premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Reserves | Secures low-magnesium feedstock access for EFSA E509 compliance in Dutch and German dairy corridors. |
| Multi-Jurisdictional Certification Investment | Compresses FDA, EFSA, and SAMR qualification timelines for new production facility market entry. |
| Automated Dosing System Partnerships | Captures craft brewing shift from flake to liquid concentrate in Colorado and Michigan markets. |
| Direct-to-Brewery Distribution Buildout | Bypasses traditional chemical wholesalers with just-in-time tanker delivery and on-site storage. |
| Cell-Cultured Protein Grade Development | Positions pharmaceutical-grade calcium salts for cultivated meat growth medium formulation demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with dairy plant managers, brewing technical directors, FCC-grade procurement leads, and food additive distribution channel partners cross-validated demand assumptions. FDA 21 CFR 184.1193 documentation, EFSA E509 compendial testing protocols, and SAMR GB standard alignment filings provided regulatory boundary conditions. Bottom-up segment sizing triangulated against top-down industry value estimates.
Data-stream reconciliation across product type, form, application, and end-user dimensions generated volume and value outputs over the projection horizon. CAGRs derived from segment-level growth rate synthesis with input from brine processing capacity expansion timelines and dairy formalization trajectories. Forecast inputs incorporated brewery automation adoption curves and EFSA heavy metal threshold enforcement intensity.
Several conditions sit outside the modeled scope, including geopolitical trade restriction escalations, breakthrough firming agent substitution technologies, and cell-cultured protein regulatory pathway delays. Forecasts reflect documented assumptions about certification reciprocity maintenance and limestone feedstock price correlation stability. A model refresh is warranted upon material change in EFSA third-party testing enforcement or Chinese export eligibility restoration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Russia Anti Caking Market
Food Additives and Ingredients
Lipase Food Enzymes Market
Food Additives and Ingredients
Sugar Reduction Technology Market
Food Additives and Ingredients
Coconut Fatty Acids Market
Food Additives and Ingredients
China Food Additives Market
Food Additives and Ingredients
Monoglyceride Market
Food Additives and Ingredients
France Adjuvants Market
Food Additives and Ingredients
Argentina Gellan Gum Market
Food Additives and Ingredients
Monostarch Phosphate Market
Food Additives and Ingredients
Carrageenan Market
Food Additives and Ingredients
Food Grade Sodium Selenite Market
Food Additives and Ingredients
Spain Food Acidulants Market
Food Additives and Ingredients
Italy Sodium Reduction Ingredients Market
Food Additives and Ingredients
Aluminum-Free Natural Food Color Market
Food Additives and Ingredients
Food Preservatives Market
Food Additives and Ingredients
Beverage Clarifier and Stabilizer Market