
 Food Clarifiers Market | 2026-2036
Food Clarifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Food Clarifiers Market Analytics
Consolidation among multinational beverage producers is restructuring procurement patterns for food clarifiers across Europe and North America. BASF SE leverages its specialty chemicals portfolio to supply high-performance bentonite grades to large-scale wineries. DSM Chemicals sustains leadership in gelatin-based clarifiers through biotech-enabled purification processes. Ashland competes on pectin formulations tailored to acid-stable beverage applications.
Food clarifiers are functional additives and processing aids that remove suspended particles, haze-forming proteins, and unwanted color from liquid food matrices through adsorption, electrostatic interaction, or enzymatic action; typical specifications include particle size distributions below 75 microns and moisture contents under 12% to ensure rapid dispersion and minimal flavor impact. Gelatin and bentonite dominate volume in wine and edible oil processing, where established supplier relationships and proven efficacy create defensive margin pools. Pectin and activated carbon represent faster-growing categories, with pectin gaining traction in vegan beverage formulations and activated carbon expanding in craft brewing and premium water treatment.
The European Food Safety Authority (EFSA) and REACH govern clarifier purity thresholds and chemical safety documentation across EU member states, while the FDA and USDA set parallel residue limits and GRAS standards for products entering the United States. These frameworks elevate compliance costs for smaller suppliers and favor partners with established regulatory dossiers. Stakeholders must weigh certification investments against the narrowing window for preferred-supplier status in consolidating buyer channels.
Market Dynamics
Consolidation among multinational beverage producers is restructuring procurement patterns for food clarifiers across Europe and North America. BASF SE leverages its specialty chemicals portfolio to supply high-performance bentonite grades to large-scale wineries. DSM Chemicals sustains leadership in gelatin-based clarifiers through biotech-enabled purification processes. Ashland competes on pectin formulations tailored to acid-stable beverage applications.
Growth Catalysts
- EU Green Deal compliance:REACH tightening on filtration material purity is accelerating demand for certified plant-derived clarifying agents in German and French wine sectors.
- Craft brewing expansion:Small-batch producers in North America are adopting activated carbon systems for premium water treatment and flavor precision.
- Vegan beverage formulations:Pectin is displacing animal-derived gelatin in juice and plant-milk processing as label-conscious consumers drive formulation shifts.
Market Restraints
- Bentonite supply concentration:Wyoming sodium bentonite deposits dominate global feedstock, exposing processors to single-source geological risk and freight cost volatility.
- Gelatin cold-temperature limitation:Animal protein clarifiers lose efficacy below 10°C, restricting winter processing windows for Northern Hemisphere wineries.
- REACH documentation burden:ECHA chemical safety dossier requirements elevate compliance costs for smaller suppliers seeking EU market access.
Strategic Opportunities
- India FSSAI modernization:India's food safety regulator is expanding clarifier standards for packaged beverages, opening formulation partnerships with domestic dairy and juice processors.
- Enzymatic clarification convergence:Pectinase-chitosan hybrid systems are penetrating premium olive oil extraction where thermal damage must be minimized.
- Direct-to-producer digital channels:Specialty chemical distributors are building e-procurement platforms that bypass traditional beverage industry intermediaries.
Industry Challenges
- Biotech purification talent scarcity:Gelatin processors face acute shortages of fermentation specialists capable of operating DSM-grade enzymatic refinement systems.
- Legacy equipment retrofit costs:Wineries running 1990s-era cross-flow filtration require six-figure capital outlays to integrate modern bentonite dosing automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Clarifiers Market |
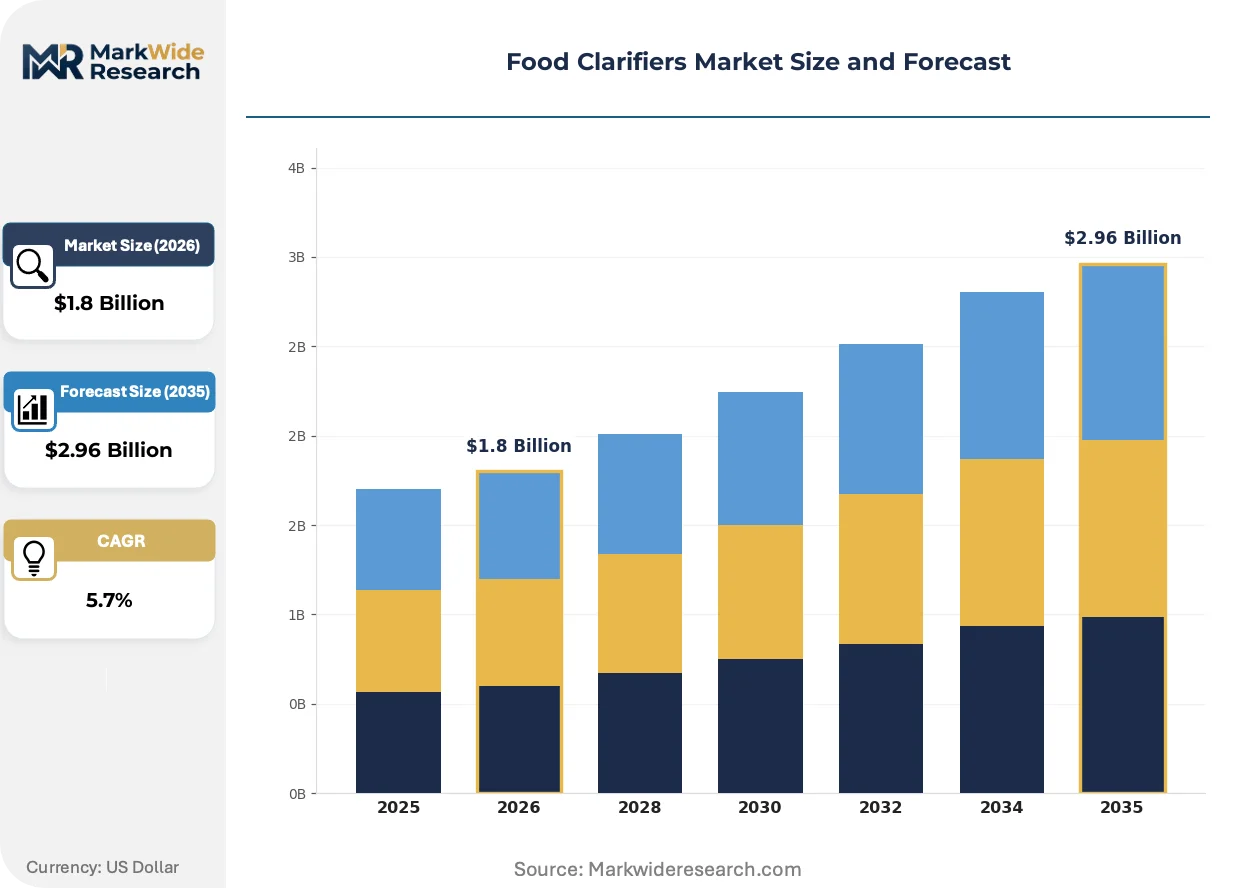
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Pectin, Bentonite, Activated Carbon Application: Beverages, Dairy Products, Wine, Edible Oils End User: Food Manufacturers, Beverage Producers, Restaurants, Breweries Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Ashland, BASF SE, DSM Chemicals, Scott Laboratories, AGROVIN, Tolsa Group, Akzonobel Chemicals, GEA Group, SPX Flow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Clarifiers Market Evolving Landscape
Active filtration technologies and precision enzymatics are displacing conventional settling methods across beverage manufacturing. These shifts are compressing processing timelines while elevating purity thresholds.
Membrane filtration combined with electrostatic particle capture is expanding into high-volume beer and wine clarification where haze stability determines shelf-life premiums. Mid-sized craft breweries in Colorado and Oregon are retrofitting their lines at accelerated rates. This hybrid approach is expanding into markets previously served solely by diatomaceous earth, compressing incumbent mineral supplier margins.
REACH Annex XVII restrictions on microplastic-containing filtration aids are forcing reformulation of synthetic polymer clarifiers across EU member states. ECHA compliance deadlines in 2027 are accelerating R&D spend on biodegradable alternatives. German brewing equipment manufacturers are pre-certifying new systems for cellulose-based media to lock in replacement cycle demand.
Certification-driven supplier selection is consolidating procurement around EFSA-registered and FDA-GRAS dual-qualified vendors. Large beverage conglomerates are narrowing their approved supplier lists to reduce audit burden and liability exposure. This concentration is most visible in California's Central Valley wine cluster, where three major cooperatives have shifted to single-source bentonite contracts with full traceability documentation.
Food Clarifiers Market Segmentation
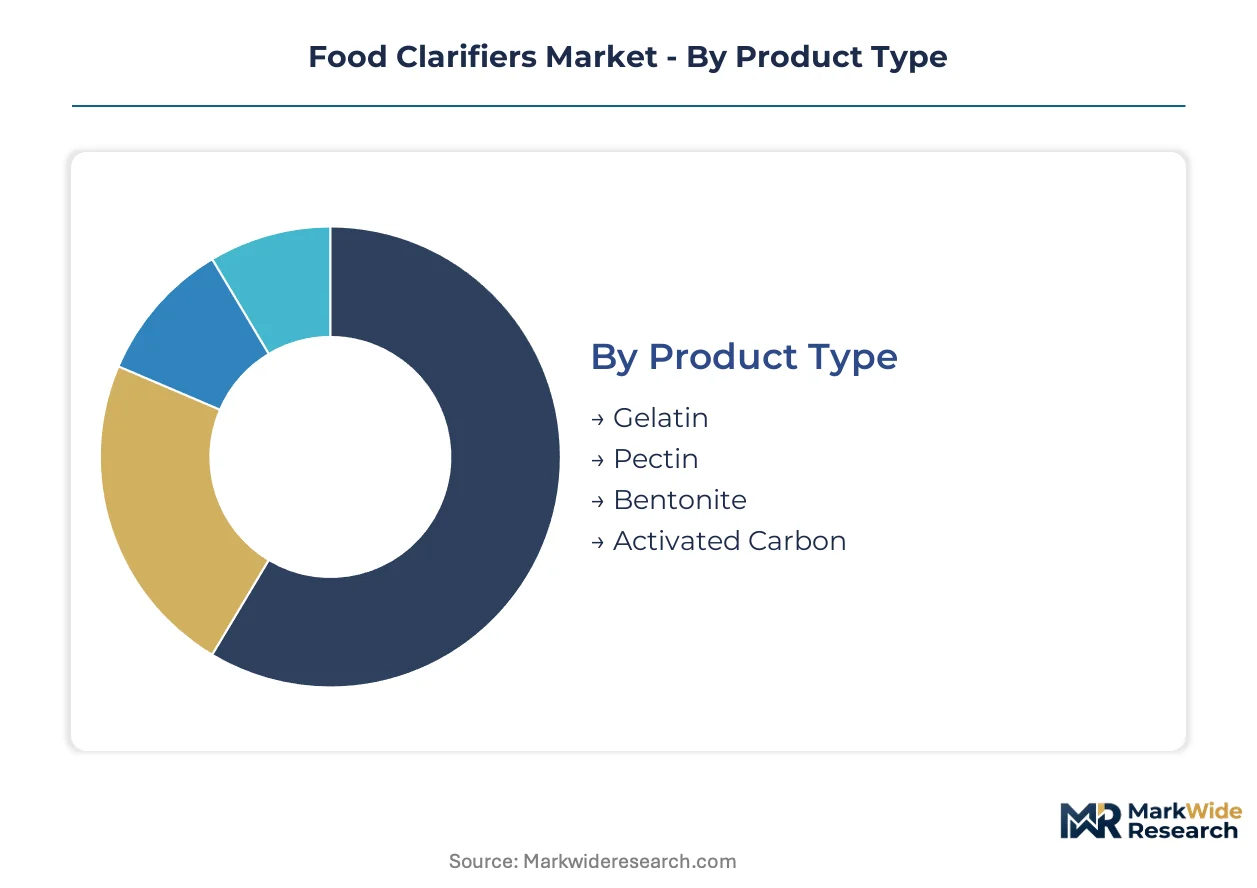
Clarifier selection hinges on matrix compatibility, thermal stability, and regulatory acceptance across divergent processing environments. Procurement patterns split between legacy mineral grades and enzymatic alternatives as beverage formulators rebalance performance against clean-label positioning.
Product Type:
Technical specifications around particle size, charge density, and thermal tolerance define competitive positioning within each clarifier class.
- Gelatin:Collagen-derived protein with isoelectric point optimization for tannin precipitation in red wine matrices. Demand concentrates in traditional French châteaux where established supplier relationships with DSM Chemicals and Rousselot limit switching. Cold-temperature efficacy loss below 10°C restricts Northern Hemisphere winter processing windows.
- Bentonite:Wyoming-sourced sodium montmorillonite with cation exchange capacity exceeding 90 meq/100g for protein adsorption in white wine and juice applications. German Riesling producers in Mosel and Rheingau represent the most volume-concentrated buyer segment. Single-source geological dependence on Powder River Basin deposits exposes processors to freight volatility and supply interruption risk.
- Pectin:Citrus and apple-derived polysaccharide with amidation degree tailoring for acid-stable beverage matrices. German vegan juice processors are displacing gelatin as EFSA clean-label requirements tighten.
- Activated Carbon:Coconut shell and coal-based microporous structures with iodine numbers above 900 mg/g for color and odor stripping. Colorado craft brewers are retrofitting systems for premium water treatment and hop oil precision.
Mature deployment sits with Bentonite. Newer deployment is concentrated in Pectin.
Application:
Processing scale and haze stability requirements create divergent specification thresholds across liquid food matrices.
- Beverages:Fruit juices, plant milks, and functional drinks requiring pectinase-compatible clarification for cloud stability and shelf-life extension. French juice bottlers in Normandy are expanding enzymatic clarification capacity to meet EU Green Deal bioprocessing targets.
- Wine:Red and white vinification demanding sequential fining with gelatin-bentonite protocols or vegan alternatives. Italian Prosecco producers in Veneto represent the fastest-adopting segment for chitosan-pectin hybrid systems.
- Dairy Products:Whey clarification and milk protein stabilization using membrane-compatible polysaccharide grades. Indian FSSAI modernization is expanding standards for packaged dairy clarification.
- Edible Oils:Olive, sunflower, and canola degumming with acid-activated bentonite and enzymatic degumming adjuncts. Spanish Andalusian cooperatives are investing in pectinase-chitosan systems to minimize thermal damage in extra-virgin extraction.
Volume concentration remains in Wine. Specification innovation is accelerating fastest in Beverages.
End User:
Operational scale determines whether procurement flows through distributor networks or direct technical partnerships with clarifier specialists.
- Food Manufacturers:Industrial-scale juice, sauce, and condiment processors with centralized laboratory validation for clarifier efficacy. German private-label bottlers are consolidating approved supplier lists to reduce audit burden.
- Beverage Producers:Multinational conglomerates and regional bottlers with formulation teams specifying clarifier blends. California Central Valley wine cooperatives have shifted to single-source bentonite contracts with full traceability documentation.
- Breweries:Craft and industrial beer producers adopting activated carbon and cellulose-based alternatives to diatomaceous earth. Oregon mid-sized craft breweries are retrofitting membrane-electrostatic hybrid systems at accelerated rates.
- Restaurants:Commercial kitchens and catering operations with small-batch clarification needs for house-made beverages and consommés. Direct-to-producer digital channels are bypassing traditional intermediaries for this segment.
Contract concentration sits with Beverage Producers. Emerging specification development is concentrated in Breweries.
Distribution Channel:
Channel selection reflects order frequency, technical service requirements, and documentation needs for regulatory compliance.
- Distributors:Regional chemical and ingredient distributors with inventory positions in bentonite and gelatin grades. French and German wine regions maintain dense distributor networks for just-in-time harvest supply.
- Direct Sales:Technical account management for large-volume beverage conglomerates requiring customized formulation support. BASF SE and Ashland operate direct channels for high-performance bentonite and pectin grades.
- Online Retail:E-procurement platforms serving craft producers and small-scale wineries with standardized clarifier SKUs. Specialty chemical distributors are building these platforms to capture bypassed intermediary margins.
- Wholesalers:Broad-line food ingredient wholesalers with limited technical service for cost-sensitive processors. Italian and Spanish olive oil processors source commodity bentonite through this channel.
Relationship depth sits with Direct Sales. Channel expansion is climbing fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for food clarifiers concentrates in wine-producing regions and beverage manufacturing clusters where purity standards and processing scale create specification intensity. Regulatory frameworks and procurement consolidation are reshaping supplier access across major producing areas.
Germany
Riesling producers in Mosel and Rheingau drive bentonite procurement for white wine protein stabilization. EFSA purity thresholds and REACH documentation requirements favor established suppliers with dossier-ready grades. Bavarian brewing equipment manufacturers pre-certify cellulose-based filtration systems ahead of 2027 ECHA microplastic restrictions.
France
Traditional châteaux in Bordeaux maintain gelatin-bentonite fining protocols while Normandy juice bottlers expand enzymatic clarification capacity. EU Green Deal bioprocessing targets accelerate plant-derived agent substitution. The Prosecco-style sparkling wine cluster in Champagne trials chitosan-pectin hybrid systems for vegan positioning.
United States
California Central Valley wine cooperatives consolidate around single-source bentonite contracts with full traceability documentation. FDA GRAS standards and TTB labeling rules structure clarifier selection for domestic and export-bound beverages. Colorado and Oregon craft breweries retrofit membrane-electrostatic hybrid systems for premium water treatment.
India
FSSAI modernization expands clarifier standards for packaged dairy and juice processors in Maharashtra and Gujarat. Domestic dairy cooperatives seek formulation partnerships for whey clarification and milk protein stabilization. Karnataka juice bottlers pilot pectin-based vegan clarification to meet emerging label-conscious demand.
Spain
Andalusian olive oil cooperatives invest in pectinase-chitosan systems to minimize thermal damage in extra-virgin extraction. REACH-aligned export requirements shape clarifier selection for EU-bound production. Catalan wine producers balance traditional fining methods against clean-label certification pressures from Northern European buyers.
Food Clarifiers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue enzymatic and plant-derived alternatives. The supplier base organizes around three maturity levels: multinational chemical conglomerates with beverage-specialized divisions, mid-scale regional distributors with harvest-season logistics capabilities, and biotechnology specialists commercializing enzymatic refinement. Dominant competitive moves include certification-driven supplier consolidation by beverage conglomerates and backward integration into raw material sourcing by bentonite processors seeking geological risk mitigation.
Among diversified chemical conglomerates, BASF SE and DSM Chemicals exemplify scale-driven archetypes with integrated regulatory dossier capabilities. Ashland occupies a position within the specialty formulation tier, competing on tailored polysaccharide grades. Regional distributors such as AGROVIN anchor procurement relationships in Mediterranean wine clusters through harvest-timing logistics expertise.
| Leading Market Players |
|---|
| Ashland |
| BASF SE |
| DSM Chemicals |
| Scott Laboratories |
| AGROVIN |
| Tolsa Group |
| Akzonobel Chemicals |
| GEA Group |
| SPX Flow |
| Others |
Value Network & Pricing Analysis
Beverage conglomerate procurement consolidation across Germany and France anchors contract-based long-term offtake pricing for food clarifiers, with volume commitments locking in preferential rates for EFSA-registered suppliers against spot-market volatility.
Pricing Analysis
High-volume bentonite contracts for German Riesling producers trade at compressed margins while specialty pectin grades for vegan beverage formulations capture premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-FDA dual-certified grades from regional single-market qualifications. Pricing pressure stems from REACH documentation cost pass-through to smaller processors. Craft breweries in Colorado exhibit highest price sensitivity; large French cooperatives prioritize certification over unit cost.
Supply Chain Analysis
EFSA-registered supplier qualification gates market access, with certification timelines stretching 18-24 months for new entrants. Wyoming, Turkey, and Greece anchor bentonite feedstock supply; citrus peel for pectin extraction draws from Brazil, Spain, and Florida. Single-source geological dependence on Powder River Basin deposits creates structural vulnerability to freight disruption. Distribution runs through regional chemical distributors with harvest-season inventory positioning and direct technical sales for multinational beverage accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
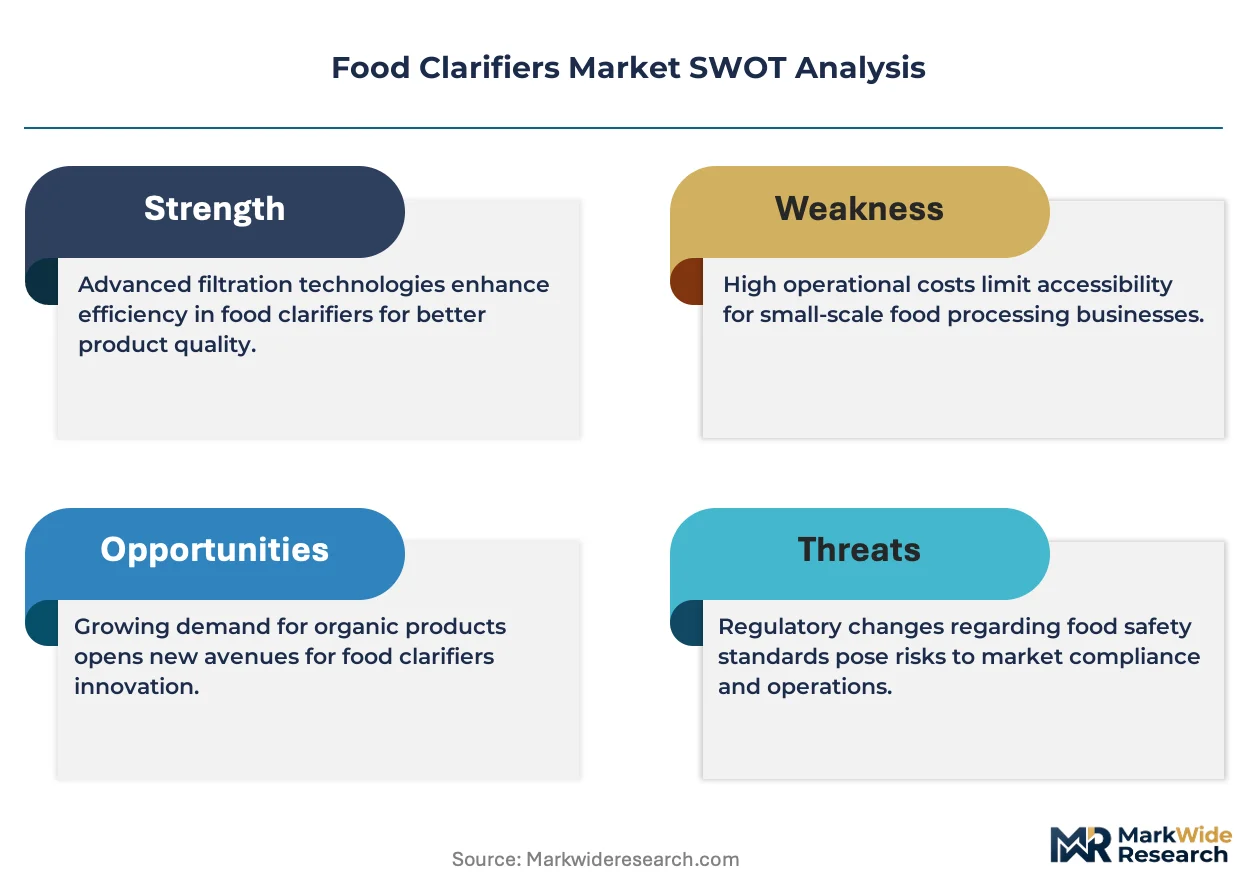
Food clarifier procurement operates as a cost-of-compliance market where REACH dossier investment creates durable barriers against unqualified competitors, entrenching incumbents with established ECHA registrations.
For Market Incumbents: Acquire fermentation technology assets and biotech purification capabilities to offset gelatin cold-temperature efficacy limitations. BASF and DSM Chemicals should extend backward integration into Wyoming bentonite mining partnerships to mitigate single-source geological risk. Certification maintenance in dual EFSA-FDA jurisdictions preserves preferred-supplier status against emerging plant-derived entrants. For New Entrants and Emerging Players: Launch via direct-to-producer digital channels targeting craft breweries and small-batch wineries in Oregon and Colorado with standardized activated carbon SKUs. India's FSSAI modernization opens formulation partnerships for domestic dairy cooperatives in Maharashtra. White-space concentration sits with enzymatic pectinase-chitosan hybrid systems for premium olive oil extraction in Andalusia. For Investors and Strategic Acquirers: The window for entry favors biotechnology specialists with enzymatic refinement capabilities over commodity mineral processors. Long-term viability hinges on clean-label certification positioning as EU Green Deal bioprocessing targets accelerate plant-derived substitution. Watch ECHA microplastic restriction enforcement timing as inflection trigger for cellulose-based filtration system adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bentonite Mining | Captures Wyoming Powder River Basin reserves to secure feedstock against geological supply interruption. |
| EFSA-FDA Dual Certification Investment | Locks in preferred-supplier status with consolidating beverage conglomerates in California and France. |
| Enzymatic Clarification R&D Partnership | Develops pectinase-chitosan systems for thermal-sensitive extra-virgin olive oil extraction in Spain. |
| Direct E-Procurement Platform Launch | Bypasses traditional distributor intermediaries to capture craft brewery segment margins in Colorado. |
| India FSSAI Formulation Partnership | Establishes early-mover position in Maharashtra dairy cooperative whey clarification standards. |
Research Methodology
Multi-period observation of clarifier procurement contract structures, regulatory filing timelines, and harvest-season inventory patterns anchored the trend analysis, supplemented by interviews with beverage formulation directors, chemical distributor procurement leads, winery laboratory managers, and EFSA regulatory affairs specialists. Secondary validation drew from REACH registration databases, ECHA chemical safety dossiers, FSSAI notification records, and customs trade data for bentonite and gelatin imports. Bottom-up segment sizing triangulated against top-down industry value-chain estimates.
Segment-weighting across product type, application matrix, and end-user operational scale drove the analytical framework over the projection horizon. Modeled dimensions included clarifier chemistry class, beverage versus edible oil processing environment, and procurement channel structure. CAGRs derived from volume trajectory analysis calibrated to regulatory deadline impacts and buyer consolidation patterns. Forecast inputs incorporated ECHA microplastic restriction implementation timing and FSSAI standard modernization pace.
Regulatory enforcement delays, raw material freight disruption, and biotechnology talent scarcity are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on certification timeline adherence and buyer procurement consolidation continuity. A model refresh is warranted upon material change in ECHA Annex XVII implementation scheduling or FSSAI clarifier standard finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Cream Emulsifier Market
Food Additives and Ingredients
Carrageenan Gum Market
Food Additives and Ingredients
Lecithin Market
Food Additives and Ingredients
DATEM Replacement Market
Food Additives and Ingredients
South America Food Preservatives Market
Food Additives and Ingredients
Germany Food Acidulants Market
Food Additives and Ingredients
Russia Food Additives Market
Food Additives and Ingredients
Bakery Stabilizers Market
Food Additives and Ingredients
Beverage Encapsulants Market
Food Additives and Ingredients
Brazil Food Enzymes Market
Food Additives and Ingredients
Chymosine Market
Food Additives and Ingredients
Microencapsulation Market
Food Additives and Ingredients
Global Flaked Shortenings Market
Food Additives and Ingredients
Europe Food Coating Ingredients Market
Food Additives and Ingredients
Fermented Chymosin Market
Food Additives and Ingredients
Carob Gum Market