

Pet Food Emulsifier Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Food Emulsifier Market Insights
EU Green Deal sustainability targets and REACH chemical standards are broadening the addressable market for plant-derived and clean-label emulsifiers across European pet food manufacturing. ADM leverages its integrated oilseed processing network to secure lecithin supply chains from North American crush facilities into European compound feed operations. Cargill sustains competitive positioning through backward integration into refined vegetable oil streams that feed emulsifier production. Silverson specializes in high-shear mixing equipment that enables manufacturers to achieve stable emulsions with reduced additive loading.
Pet food emulsifiers comprise surface-active agents that reduce interfacial tension between immiscible lipid and aqueous phases, typically functioning at concentrations of 0.1–2.0% by weight to ensure texture uniformity and shelf stability in processed formulations. Lecithin dominates volume consumption due to its dual hydrophilic-lipophilic character and broad regulatory acceptance, though manufacturers face margin compression from phospholipid supply volatility tied to sunflower and soybean harvest cycles. Mono- and diglycerides occupy the fastest-expanding niche as dry kibble producers reformulate to eliminate synthetic antioxidants while maintaining fat encapsulation through the extrusion process. Polysorbates retain stable demand in wet canned food applications where thermal processing demands robust emulsion integrity through sterilization cycles.
FDA feed ingredient standards in the United States, EFSA additive authorizations under the EU framework, and FSSAI packaging migration limits in India collectively shape product registration pathways and reformulation timelines for emulsifier suppliers seeking multi-territory distribution. ECHA substance evaluation protocols are extending scrutiny to residual solvent levels in lecithin extraction processes, prompting manufacturers to validate alternative supercritical CO2 methods. Stakeholders must monitor divergence between FDA generally recognized as safe determinations and EU novel food catalog requirements, as asynchronous regulatory clocks risk stranding inventory or forcing parallel formulation sets.
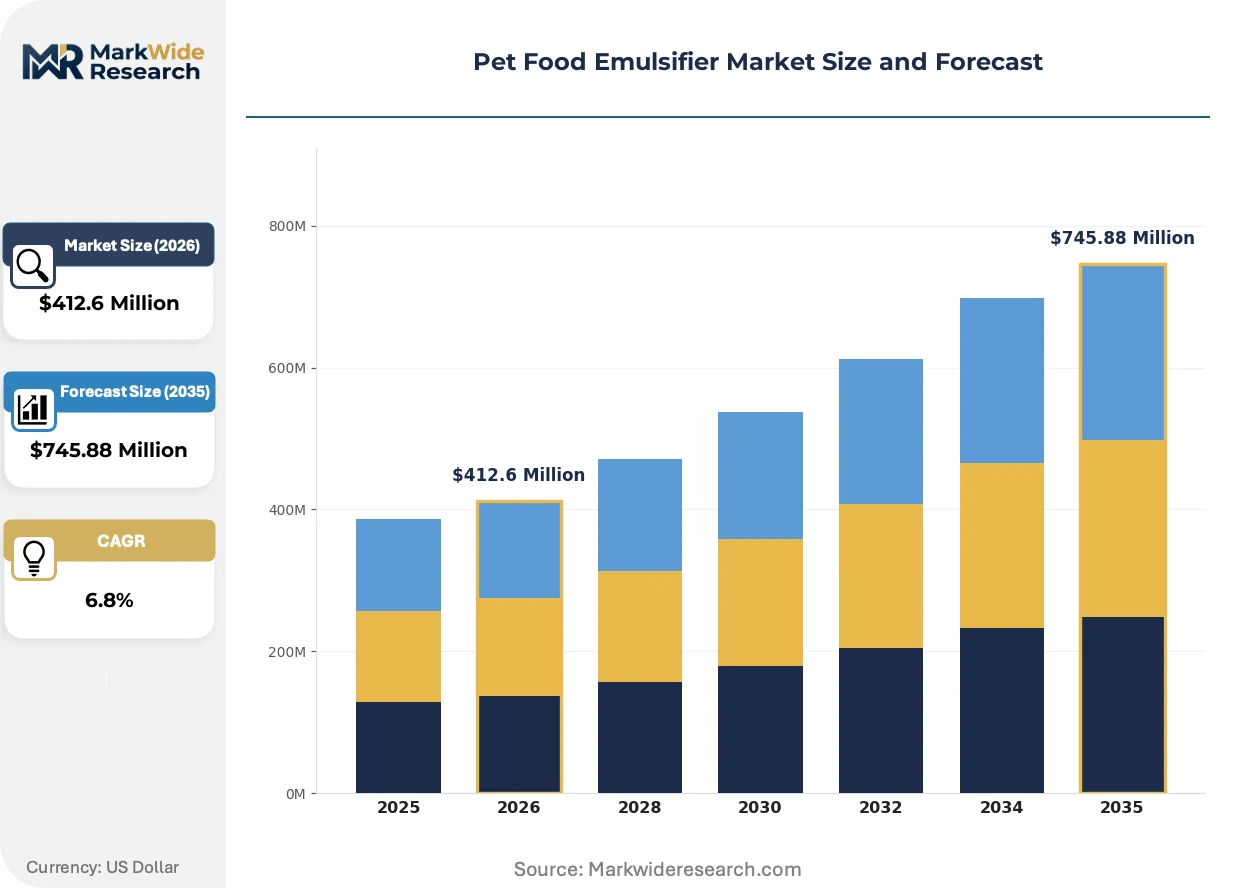
Market Dynamics
Clean-label reformulation mandates from the EU Green Deal and REACH chemical standards are forcing pet food manufacturers to replace synthetic stabilizers with plant-derived alternatives, tightening emulsifier specification windows and concentrating procurement among suppliers with validated sustainable extraction capabilities.
Growth Catalysts
- REACH chemical standard tightening:ECHA substance evaluation protocols are extending scrutiny to residual solvent levels in lecithin extraction, accelerating manufacturer migration toward supercritical CO2 methods that qualify for clean-label positioning.
- Premium wet canned food expansion:Specialty pet food production clusters around Hamburg and Cologne are absorbing higher emulsifier volumes as manufacturers eliminate synthetic antioxidants while maintaining sterilization-stable emulsion integrity.
- Extrusion process reformulation:Dry kibble producers are reformulating to eliminate synthetic antioxidants, creating sustained pull for mono- and diglycerides that encapsulate fats through high-temperature extrusion cycles.
Market Restraints
- Phospholipid supply volatility:Lecithin manufacturers face margin compression from sunflower and soybean harvest cycle fluctuations that destabilize raw material costs without forward-contract hedging.
- Regulatory clock asynchronicity:Divergence between FDA generally recognized as safe determinations and EU novel food catalog requirements risks stranding inventory or forcing parallel formulation sets for multi-territory suppliers.
- Functional performance ceilings:Plant-derived emulsifiers face technical limitations in thermal stability compared to synthetic alternatives, constraining their deployment in retort-processed wet foods requiring sterilization cycle integrity.
Strategic Opportunities
- India FSSAI packaging migration limits:tightening additive authorizations are creating first-mover advantage for suppliers with pre-validated clean-label emulsifier portfolios that preempt domestic reformulation cycles.
- Supercritical CO2 extraction convergence:Combination of green chemistry process innovation with carbon capture utilization is enabling suppliers to position lecithin production as carbon-negative within EU Green Deal accounting frameworks.
- Veterinary therapeutic nutrition:Prescription pet food formulations for renal and gastrointestinal conditions require precision emulsion stability, opening premium pricing tiers for pharmaceutical-grade emulsifier certification.
Industry Challenges
- Formulation chemist scarcity:Pet food manufacturers face talent gaps in lipid chemistry specialization required to balance clean-label ingredient decks with shelf-stability performance specifications.
- Dual certification timeline compression:Simultaneous FDA feed ingredient standard and EFSA additive authorization pathways demand parallel regulatory affairs capacity that strains mid-tier supplier resources.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Food Emulsifier Market Trends and Innovations
Emulsifier technology is bifurcating between high-performance synthetic legacy systems and bio-based alternatives, with regulatory pressure and procurement specification tightening accelerating adoption curves for plant-derived solutions.
Enzymatic interesterification is absorbing capital allocation from chemical glycerolysis in mono- and diglyceride production, yielding positional specificity that improves fat encapsulation efficiency in extruded kibble. European compound feed operations near Rotterdam and Antwerp are adopting these enzymatic routes at commercial scale. The technology is absorbing market share from acid-catalyzed processes by reducing thermal degradation of polyunsaturated fatty acids during emulsifier synthesis.
EU Green Deal sustainability targets are mandating carbon footprint disclosure across pet food supply chains, forcing emulsifier suppliers to validate upstream agricultural emissions from oilseed cultivation through crush facility energy profiles. EFSA additive authorizations now incorporate life-cycle assessment documentation requirements that extend reformulation timelines by 12-18 months. Wet canned food applications face the steepest compliance burden due to higher emulsifier loading rates required for sterilization-stable textures.
Direct procurement relationships between pet food manufacturers and oilseed processors are compressing traditional distribution margins for emulsifier intermediaries. Large compounders in Germany and the Netherlands are establishing captive supply agreements with crush facilities to secure lecithin streams with traceable origin documentation. This channel consolidation is most visible in premium therapeutic nutrition segments where ingredient provenance claims command shelf price premiums.
Pet Food Emulsifier Market Segmentation
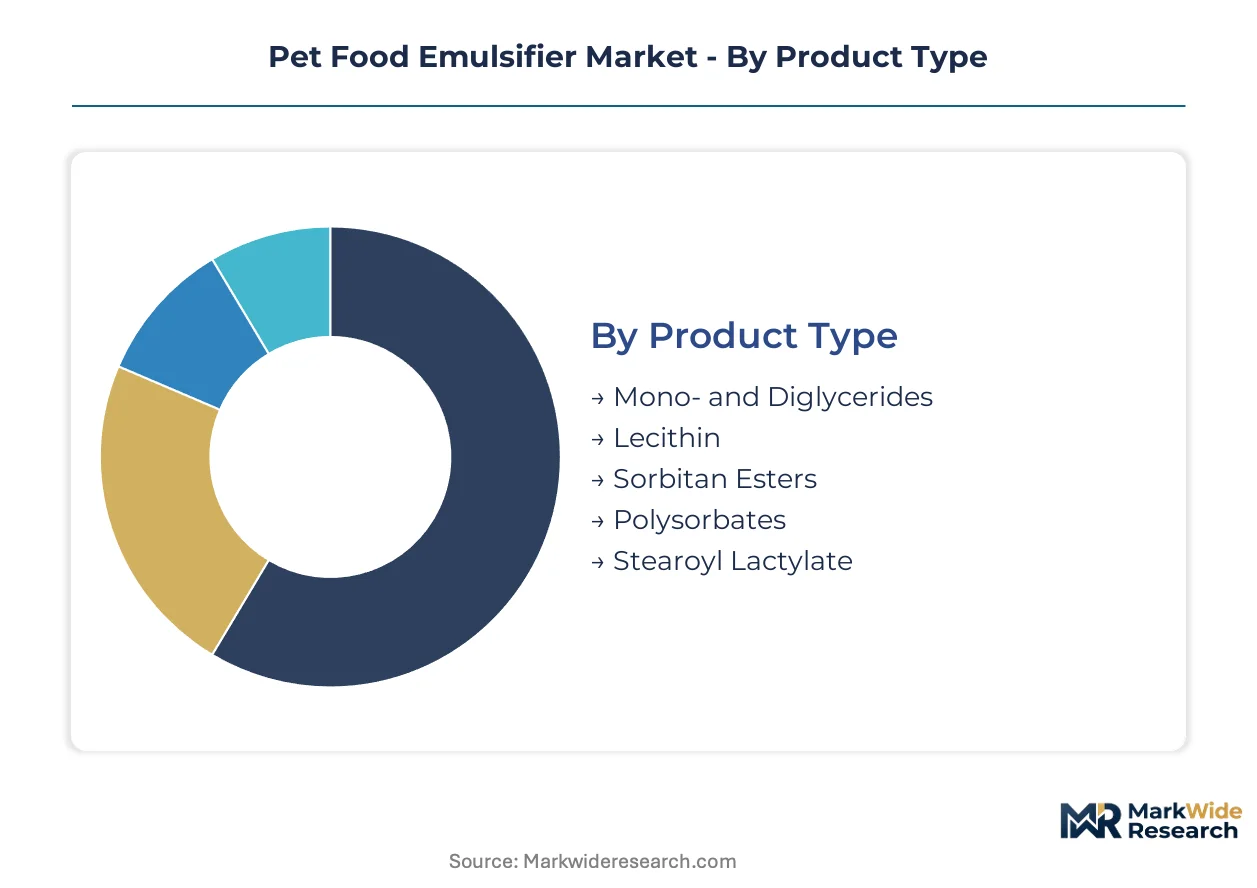
Emulsifier specification varies sharply across pet food formats, with thermal processing demands and clean-label mandates driving divergent procurement patterns. Manufacturers align product type selection with extrusion sterilization requirements, moisture content targets, and distribution channel shelf-life specifications.
Product Type:
Lecithin dominates procurement volumes through its phospholipid functionality, while enzymatic process innovations are reshaping mono- and diglyceride competitiveness.
- Lecithin:Phospholipid-derived emulsifiers with dual hydrophilic-lipophilic balance function at 0.5–1.5% loading in wet canned formulations. Demand concentrates in German specialty production clusters around Hamburg, where sterilization-stable emulsion integrity commands premium specifications. Sunflower and soybean harvest volatility compresses margins without forward-contract hedging.
- Mono- and Diglycerides:Glycerol-based emulsifiers produced through enzymatic interesterification achieve positional specificity for fat encapsulation in extruded kibble. Dry food manufacturers in the Netherlands and Belgium are absorbing higher volumes as they eliminate synthetic antioxidants while maintaining high-temperature process stability. Enzymatic routes displace acid-catalyzed production by reducing polyunsaturated fatty acid degradation.
- Sorbitan Esters:Lipophilic surfactants derived from sorbitol and fatty acids serve intermediate moisture applications where water activity control is critical.
- Polysorbates:Ethoxylated sorbitan esters deliver robust thermal stability for retort-processed wet foods requiring sterilization cycle integrity.
- Stearoyl Lactylate:Lactic acid esters of stearic acid provide dough conditioning functionality in baked treat formulations with extended shelf-life requirements.
Mature deployment sits with Lecithin. Newer deployment is concentrated in Mono- and Diglycerides.
Application:
Moisture content and processing intensity determine emulsifier loading rates, with wet formats absorbing higher additive volumes per ton of finished product.
- Wet Canned Food:High-moisture formulations require 1.0–2.0% emulsifier loading to maintain fat dispersion through 121°C sterilization cycles. Premium lines at Nestlé Purina and Mars Petcare facilities absorb disproportionate volumes as clean-label reformulations replace synthetic stabilizers. REACH chemical standards tighten specification windows for European supply chains.
- Dry Kibble:Low-moisture extruded products utilize 0.1–0.5% emulsifier concentrations for fat encapsulation and dust reduction. Mono- and diglyceride demand is climbing fastest among producers reformulating to eliminate synthetic antioxidants while maintaining extrusion throughput.
- Semi-Moist Food:Intermediate water activity products require humectant-emulsifier synergies for texture stability and mold inhibition.
- Treats:Baked and extruded snack formats prioritize emulsifiers that support machinability and break resistance.
- Supplements:Functional additive formats demand pharmaceutical-grade emulsifier certification for veterinary therapeutic nutrition segments.
Volume concentration centers on Wet Canned Food. Specification tightening is most pronounced in Dry Kibble.
End User:
Procurement scale and technical specification authority fragment across the value chain, with compounders driving bulk volumes and specialty channels demanding traceable provenance.
- Pet Food Manufacturers:Large compounders in Germany and the Netherlands establish captive supply agreements with oilseed crush facilities to secure lecithin streams with validated origin documentation. Direct procurement compresses traditional distribution margins for emulsifier intermediaries.
- Pet Specialty Stores:Private-label and premium branded product lines require clean-label emulsifier portfolios that support shelf positioning claims.
- Veterinary Clinics:Prescription therapeutic nutrition formulations demand pharmaceutical-grade emulsifier certification for renal and gastrointestinal condition management.
- Online Retailers:E-commerce distribution channels prioritize extended shelf-life stability for warehouse fulfillment models with variable temperature exposure.
Procurement consolidation is most advanced among Pet Food Manufacturers. Channel fragmentation persists in Veterinary Clinics.
Packaging Type:
Logistics configuration and handling requirements determine container selection, with bulk formats dominating manufacturing input and unit-dose formats serving specialty distribution.
- Bulk Bags:Flexible intermediate bulk containers handle 500–1000 kg emulsifier deliveries to large compound feed operations near Rotterdam and Antwerp. Carbon footprint disclosure mandates under EU Green Deal targets favor consolidated shipment formats.
- Drums:Steel and fiber containers serve mid-scale manufacturers with validated supercritical CO2 extraction requirements for clean-label positioning.
- Sachets:Unit-dose formats support sampling programs and small-batch formulation development in specialty pet food segments.
- Bottles:Rigid containers accommodate liquid emulsifier concentrates for wet food production lines with automated dosing systems.
- Pouches:Flexible stand-up formats serve treat and supplement manufacturers with space-efficient storage requirements.
Scale concentration favors Bulk Bags. Specification diversity is expanding in Drums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamburg anchors European emulsifier procurement through its concentration of specialty pet food manufacturing and direct supply agreements with oilseed crush facilities serving compound feed operations.
Germany
Specialty pet food production clusters around Hamburg and Cologne absorb disproportionate emulsifier volumes as manufacturers eliminate synthetic stabilizers from premium wet canned formulations. ECHA substance evaluation protocols under REACH mandate residual solvent scrutiny, accelerating migration toward supercritical CO2 extraction methods. North Rhine-Westphalia compounders establish captive supply agreements with regional crush facilities to secure traceable lecithin streams.
United States
FDA feed ingredient standards shape registration pathways for multi-territory suppliers seeking to distribute across North American manufacturing networks. Generally recognized as safe determinations for lecithin and mono-diglycerides enable faster formulation timelines compared to EU novel food catalog requirements. Midwestern pet food production corridors near Kansas City and Omaha concentrate procurement scale for dry kibble extrusion applications.
Netherlands
Rotterdam and Antwerp compound feed operations adopt enzymatic interesterification routes for mono- and diglyceride production at commercial scale. EU Green Deal carbon footprint disclosure mandates extend reformulation timelines by 12-18 months as suppliers validate upstream agricultural emissions. Direct procurement relationships between manufacturers and oilseed processors compress traditional distribution margins for emulsifier intermediaries.
India
FSSAI packaging migration limits and tightening additive authorizations create first-mover positioning for suppliers with pre-validated clean-label portfolios. Domestic reformulation cycles accelerate as premium pet food brands expand distribution through veterinary clinics and online retail channels. Maharashtra and Gujarat manufacturing hubs concentrate formulation development for therapeutic nutrition segments requiring pharmaceutical-grade emulsifier certification.
China
SAMR additive standards and GB food safety requirements shape import registration pathways for foreign emulsifier suppliers seeking access to domestic pet food manufacturing. Yangtze River Delta production zones concentrate wet canned food capacity for both domestic consumption and export markets. Local compounders face technical limitations in thermal stability performance when substituting plant-derived alternatives for synthetic emulsifiers in retort-processed applications.
Pet Food Emulsifier Market Competitive Landscape
The competitive structure tilts toward integrated agricultural processors with captive oilseed supply chains and specialized equipment fabricators with process technology differentiation. Market concentration splits between multinational ingredient suppliers controlling upstream raw material flows and mid-scale mixing equipment specialists capturing value through high-shear emulsion stability solutions. Three archetypes dominate: backward-integrated agricultural processors, enzymatic process technology licensors, and precision mixing equipment fabricators. Capacity expansion and direct procurement relationship formation represent the dominant competitive moves as manufacturers bypass traditional distribution intermediaries.
Among agricultural processing specialists, ADM and Cargill exemplify the backward-integrated archetype through their control of North American oilseed crush networks feeding European compound operations. Silverson occupies a distinct position within high-shear mixing equipment fabrication, representing the process-technology pathway to reduced additive loading. These three anchors illustrate the bifurcation between raw material supply chain control and manufacturing equipment specialization that defines competitive positioning.
| Leading Market Players |
|---|
| Karl Schnell |
| ProXES |
| Seydelmann |
| Scansteel Foodtech A/S |
| LASKA |
| Silverson |
| Handtmann Group |
| ADM |
| Cargill |
| Others |
Pricing and Supply Chain Analysis
Clean-label procurement mandates from EU REACH chemical standards are forcing emulsifier suppliers to validate supercritical CO2 extraction methods, compressing margins for non-compliant producers while concentrating pricing power among certified suppliers with backward-integrated oilseed networks.
Pricing Analysis
Emulsion stability yield in high-temperature sterilization cycles anchors value-based pricing tiers for wet canned food applications. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels segments buyer willingness-to-pay, with veterinary therapeutic nutrition commanding substantial premiums. Cost compression in standard-grade lecithin is intensifying because sunflower and soybean harvest volatility destabilizes raw material costs without forward-contract hedging. Large compounders in Germany exhibit lowest price sensitivity due to captive supply agreements, while mid-tier dry kibble manufacturers face acute margin pressure from enzymatic process technology licensing fees.
Supply Chain Analysis
Ocean freight and inland trucking costs from North American oilseed crush facilities to European compound feed operations constitute a material share of landed lecithin pricing. Supply concentrates in the United States, Germany, and the Netherlands, with crush capacity clustering around Midwestern processing corridors and Hamburg-Antwerp logistics hubs. Raw material flows draw from sunflower and soybean harvest cycles, phospholipid extraction solvents, and enzymatic catalyst inputs. Single-source vulnerability from Black Sea sunflower supply disruptions poses structural risk. Distribution runs through direct procurement relationships between pet food manufacturers and oilseed processors, compressing traditional emulsifier intermediary margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EU Green Deal carbon footprint disclosure mandates and ECHA substance evaluation protocols erect regulatory moats favoring suppliers with pre-validated clean-label extraction capabilities and traceable origin documentation.
For Market Incumbents: Acquire supercritical CO2 extraction assets and enzymatic interesterification technology licenses to defend against substitute synthetic emulsifier producers and emerging plant-derived specialists. Secure captive supply agreements with oilseed crush facilities in Germany and the Netherlands to lock in traceable lecithin streams. Invest in pharmaceutical-grade emulsifier certification capacity to capture premium pricing tiers in veterinary therapeutic nutrition segments.
For New Entrants and Emerging Players: Veterinary clinics and prescription pet food channels represent underserved buyer archetypes with unmet demand for pharmaceutical-grade emulsifier certification and precision emulsion stability. Target India's Maharashtra and Gujarat manufacturing hubs where FSSAI packaging migration limits are accelerating domestic reformulation cycles. Pursue white-label supply partnerships with regional compounders lacking clean-label extraction capabilities as the primary go-to-market angle.
For Investors and Strategic Acquirers: The window for entry favors backward-integrated agricultural processors with captive oilseed networks and validated carbon-negative production positioning under EU Green Deal accounting frameworks. Long-term viability hinges on regulatory compliance capacity rather than commodity scale. Monitor EFSA additive authorization divergence from FDA generally recognized as safe determinations as the critical inflection signal for multi-territory supplier valuation compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crush Capacity | Captive lecithin supply from North American facilities secures traceable origin documentation for EU Green Deal compliance. |
| Supercritical CO2 Extraction Technology Deployment | Carbon-negative process positioning qualifies suppliers for premium clean-label procurement specifications under REACH standards. |
| Pharmaceutical-Grade Emulsifier Certification | Veterinary therapeutic nutrition segments command pricing premiums for renal and gastrointestinal condition formulations. |
| Enzymatic Interesterification Licensing | Positional specificity in mono- and diglyceride production improves fat encapsulation efficiency for dry kibble extrusion. |
| Direct Procurement Relationship Formation | Manufacturer-oilseed processor agreements compress traditional distribution margins and lock in volume commitments. |
Research Methodology
Trade databases, EFSA additive authorization filings, and SEC 10-K disclosures from agricultural processing firms formed the secondary backbone of this analysis. Primary interviews with pet food formulation chemists, oilseed procurement leads at crush facilities, regulatory affairs directors, and veterinary therapeutic nutrition product managers validated demand-side assumptions. Bottom-up emulsifier volume estimates by product type and application were triangulated against top-down pet food production data from compound feed operations near Rotterdam, Hamburg, and Kansas City.
Historical trendline analysis of lecithin and mono-diglyceride consumption patterns informed the projection framework across the analysis window. Segmentation dimensions modeled include emulsifier product type, pet food application format, end-user channel, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating extrusion process reformulation rates, clean-label substitution timelines, and therapeutic nutrition segment expansion. Industry-specific forecast inputs encompassed sunflower and soybean harvest cycle variability, ECHA substance evaluation protocol implementation schedules, and FSSAI packaging migration limit enforcement trajectories.
Revisions become necessary when asynchronous regulatory clock divergence between FDA and EFSA materializes, when phospholipid supply volatility exceeds historical harvest cycle bands, or when enzymatic process technology licensing costs shift competitive economics. Forecasts reflect documented assumptions about clean-label substitution rates and carbon footprint disclosure compliance timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.