

PVPP Beer Stabilizer Market Size, Share, and Industry Trends Forecast 2026-2036
PVPP Beer Stabilizer Market Insights
Asset-light leasing arrangements for stabilization equipment is reconfiguring competitive dynamics among mid-sized brewers seeking to avoid capital-heavy filtration infrastructure. BASF leverages its polymer synthesis expertise to sustain supply security across European malt houses. AEB Group anchors its position through specialized brewing applications support in Italian and Spanish markets. Huangshan Bonsun Pharmaceuticals competes on cost-optimized powder production serving Asian contract brewers.
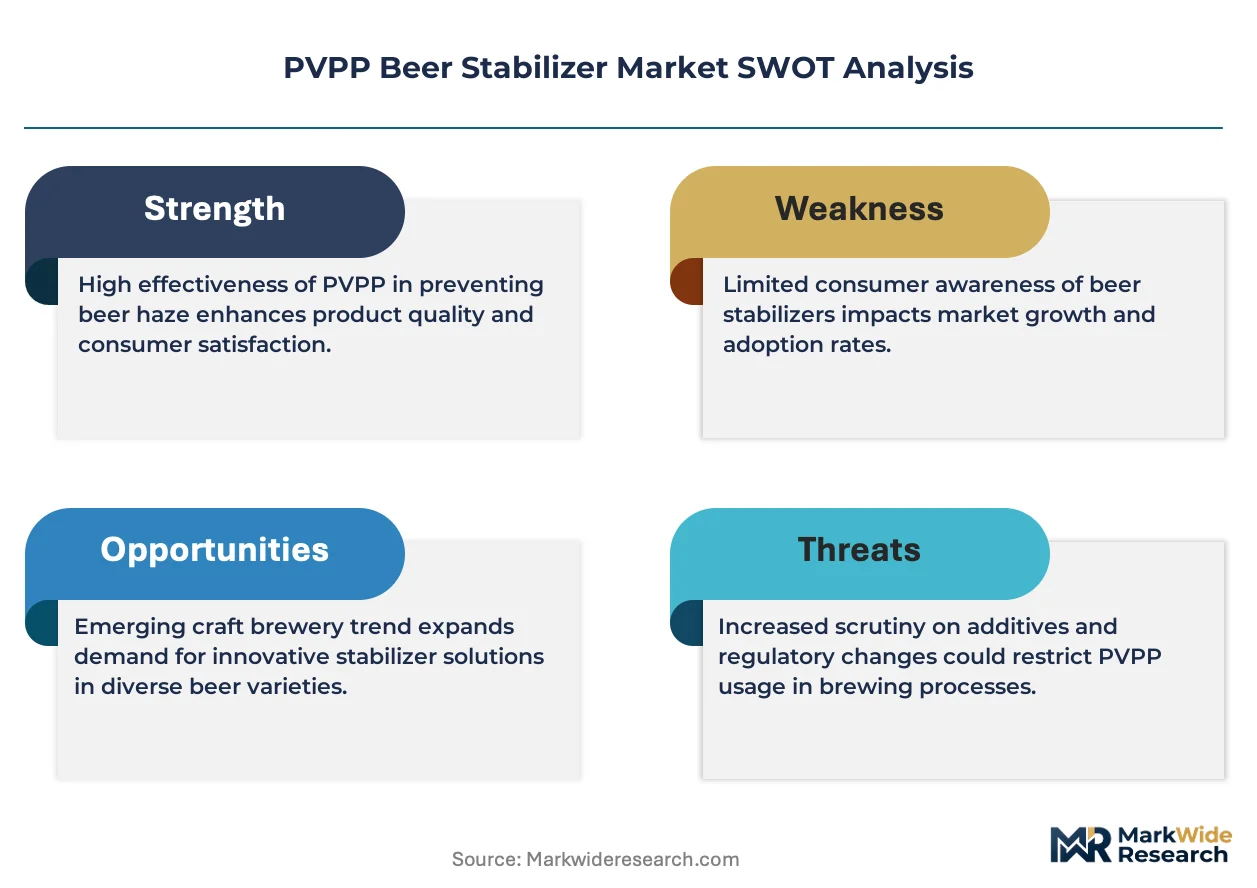
PVPP (polyvinylpolypyrrolidone) beer stabilizer functions as an insoluble, highly cross-linked polymer that selectively adsorbs polyphenols and haze-active proteins through hydrogen bonding at typical dosage rates of 20–50 grams per hectoliter, producing shelf-stable clarity in packaged beer. Powder formulations dominate volume flows due to established handling protocols in automated dosing systems, while liquid concentrate formats are gaining traction among microbreweries prioritizing labor minimization and batch-to-batch consistency. Foam stabilization applications command premium positioning as nitrogenated and specialty beer styles proliferate in North American and European craft segments.
German KBA-adjacent food contact material standards, EU REACH chemical registration requirements, and FDA food additive regulations collectively govern cross-border ingredient acceptance and formulation disclosure protocols. These frameworks elevate compliance costs for new entrants while rewarding incumbent suppliers with validated regulatory dossiers. Stakeholders must monitor evolving single-use plastic restrictions on bulk packaging formats and assess bio-based polymer alternatives before mandates crystallize.
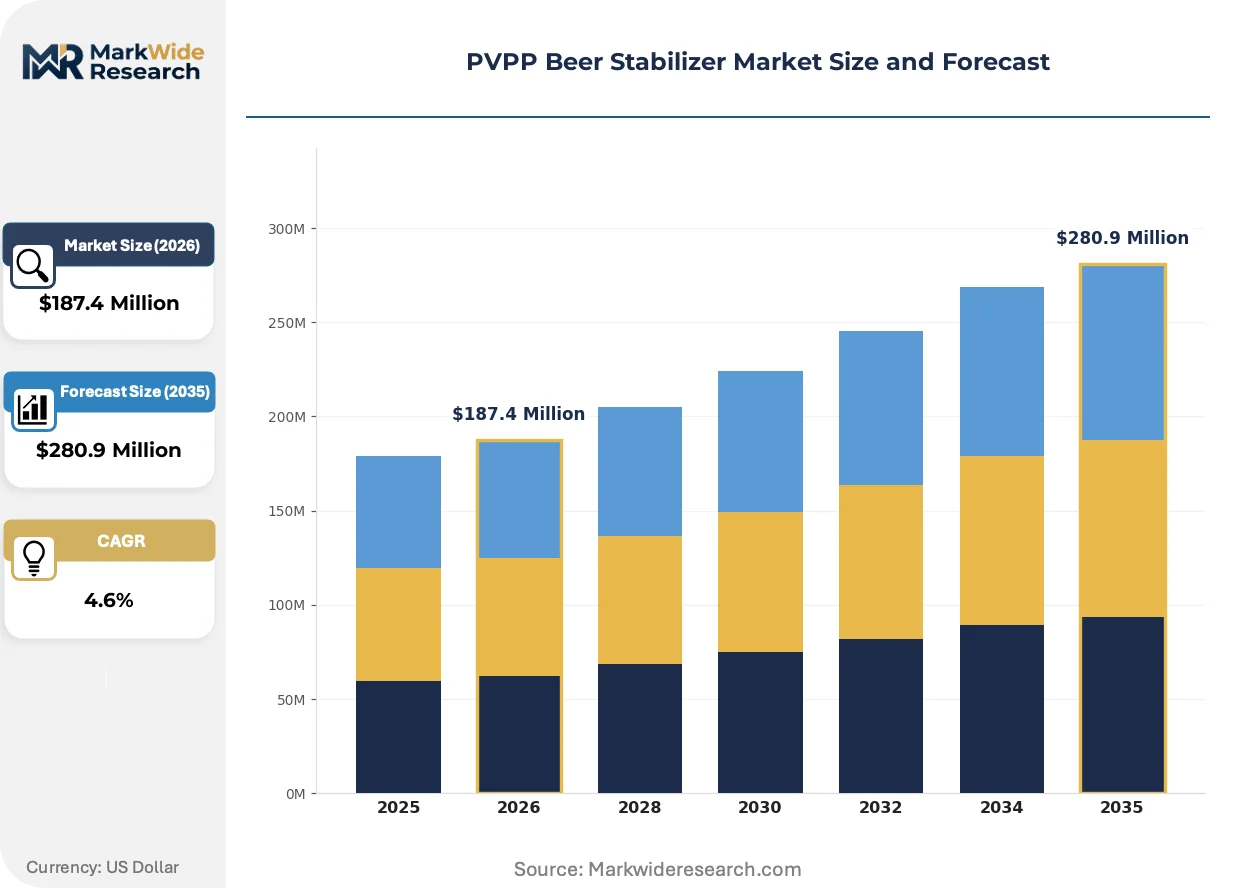
Market Dynamics
EU brewing purity conventions are tightening procurement standards for stabilization agents, forcing malt houses across Germany and the Czech Republic to validate filtration inputs against KBA-adjacent food contact material standards and ECHA registration dossiers.
Growth Catalysts
- REACH Compliance Mandates:ECHA chemical registration requirements compel European brewers to source documented PVPP grades, locking in demand for incumbent suppliers with validated dossiers.
- Craft Brewery Expansion:Microbreweries in Italy and Spain prioritize liquid concentrate formats for labor minimization, creating new volume channels beyond traditional powder procurement.
- Nitrogenated Beer Proliferation:Foam stabilization applications command premium positioning as specialty beer styles expand across North American craft segments.
Market Restraints
- Cross-Linked Polymer Feedstock Volatility:N-vinylpyrrolidone monomer costs fluctuate with acetylene and gamma-butyrolactone availability, compressing margin predictability for powder manufacturers.
- Single-Use Packaging Restrictions:Evolving EU directives on bulk plastic containers threaten established 25-kilogram bag distribution protocols without immediate bio-based alternatives.
- Silica Gel Substitution:Amorphous silica stabilizers compete on unit economics for large-scale lager filtration, particularly among price-sensitive contract brewers.
Strategic Opportunities
- Asset-Light Equipment Leasing:Mid-sized brewers avoid capital-heavy filtration infrastructure through rental arrangements for stabilization skids, reconfiguring competitive dynamics.
- CSRD-Driven Disclosure:Corporate Sustainability Reporting Directive mandates create demand for carbon-footprint-certified PVPP grades among publicly listed beverage groups.
- Automated Dosing Convergence:Integration of powder handling systems with brewery SCADA platforms enables real-time polyphenol adjustment, opening technical service revenue streams.
Industry Challenges
- Polymer Synthesis Talent Scarcity:Cross-linking chemistry expertise concentrates among aging technical workforces in German and Swiss industrial clusters.
- Legacy Filtration Retrofit Complexity:Existing diatomaceous earth lines require mechanical modification to accommodate PVPP dosing without contamination risk.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVPP Beer Stabilizer Market Trends and Innovations
Liquid concentrate formats are compressing established powder workflows as microbreweries prioritize batch-to-batch consistency over legacy handling protocols.
Pre-hydrated PVPP suspensions eliminate dissolution variability in automated dosing systems. Craft breweries across the United States and Canada adopt these concentrates for labor minimization. This format shift is collapsing the traditional powder-dominant procurement model among sub-50,000 hectoliter producers.
F-Gas Regulation phase-down schedules in the European Union accelerate scrutiny of all synthetic polymer inputs in food contact applications. Brewers must now document PVPP grade compliance against evolving per- and polyfluoroalkyl substance contamination thresholds. German malt houses respond by demanding expanded ECHA dossier disclosure from stabilizer suppliers.
Contract brewing arrangements concentrate purchasing authority among third-party production facilities rather than brand owners. Asian contract brewers in Vietnam and Thailand now negotiate direct PVPP supply agreements, bypassing traditional distributor tiers. This channel compression is most visible in export-oriented brewing hubs serving European and North American label markets.
PVPP Beer Stabilizer Market Segmentation
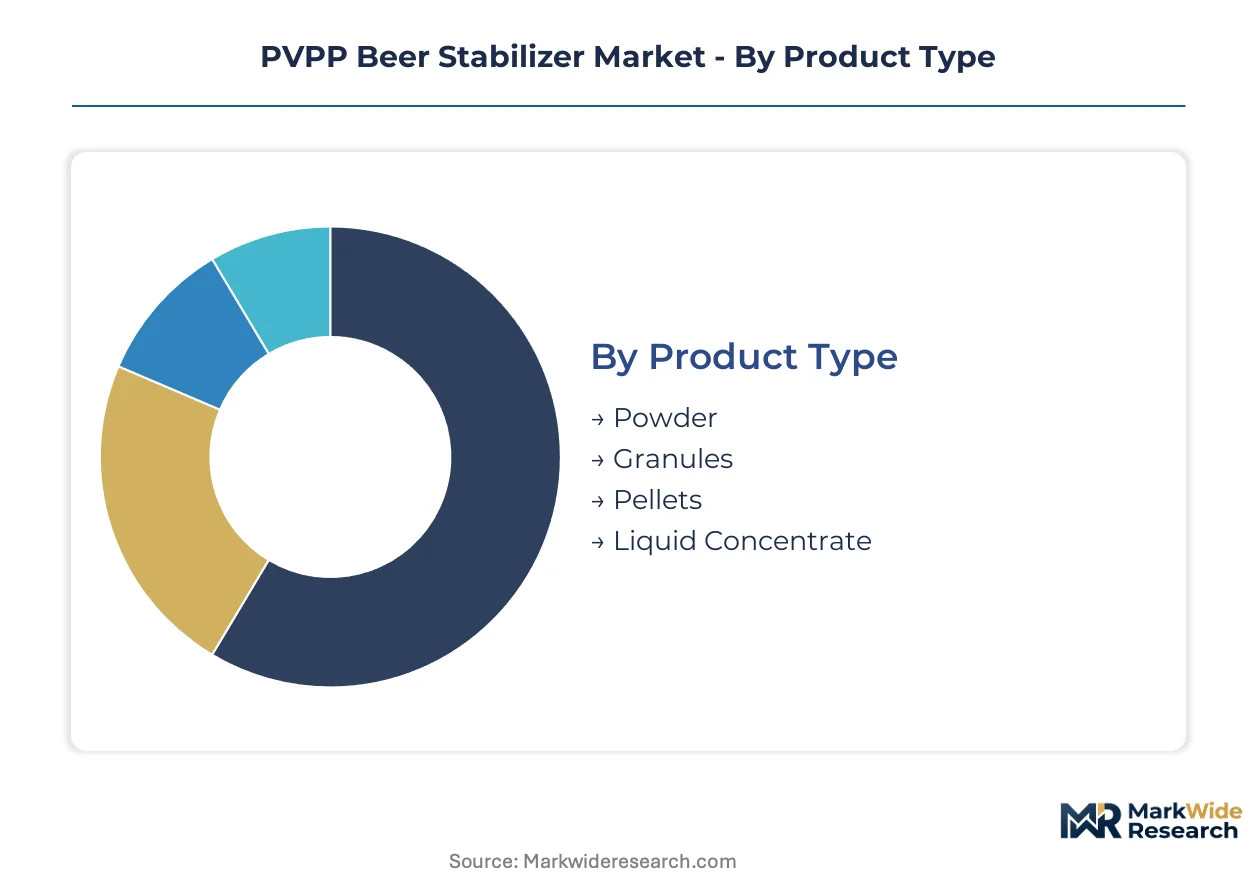
PVPP beer stabilizer procurement splits across four structural dimensions that determine formulation specifications, dosing protocols, and supply chain configurations. Technical requirements vary sharply between automated large-scale filtration and manual microbrewery operations. Understanding these segment boundaries enables suppliers to align production capacity with actual demand concentration.
Product Type:
Mature powder formats coexist with emerging liquid concentrates as breweries recalibrate labor and consistency priorities.
- Powder:Insoluble cross-linked polymer particles with established dissolution kinetics in automated dosing systems. German and Czech malt houses specify powder grades for high-throughput filtration lines where dosing precision and speed dominate operational economics.
- Liquid Concentrate:Pre-hydrated suspensions eliminating dissolution variability and manual handling steps. Italian and Spanish microbreweries drive procurement as batch-to-batch consistency and labor minimization override legacy powder protocols.
- Granules:Intermediate particle size offering controlled release characteristics for specific filtration configurations.
- Pellets:Compressed forms enabling precise tablet-based dosing in smaller-scale brewing operations.
Powder handles the majority of throughput; liquid concentrate is gaining share fastest among sub-50,000 hectoliter producers.
Application:
Cost tier separation distinguishes commodity clarification from premium foam and flavor stabilization services.
- Beer Clarification:Core polyphenol and haze-active protein removal through hydrogen bonding at standard dosage rates. Large-scale lager brewers in Germany specify clarification-grade PVPP as the baseline filtration input under KBA-adjacent food contact standards.
- Foam Stabilization:Nitrogenated and specialty beer styles require premium-grade polymer specifications to maintain head retention and mouthfeel integrity. North American craft segments command price premiums for foam-optimized grades as stout and nitro-ale portfolios expand.
- Flavor Stabilization:Selective adsorption targeting specific phenolic compounds affecting taste stability over shelf life.
- Turbidity Prevention:Preventive dosing against chill haze formation in packaged beer distribution.
Beer clarification absorbs the bulk of volume; foam stabilization commands the steepest expansion trajectory as premium beer formats proliferate.
End User:
Customer type fragmentation creates divergent procurement authority between brand owners and contract production facilities.
- Large-scale Brewers:Automated filtration infrastructure with validated supplier relationships and bulk powder contracts. German industrial brewing clusters anchor demand through multi-year supply agreements with incumbent polymer suppliers.
- Craft Breweries:Mid-sized operations prioritizing technical support and flexible batch sizing over commodity pricing. Spanish and Italian craft segments favor liquid concentrates for labor efficiency in non-automated environments.
- Microbreweries:Sub-10,000 hectoliter producers with minimal dosing automation and high sensitivity to handling simplicity.
- Contract Brewers:Third-party production facilities in Vietnam and Thailand negotiating direct supply agreements, bypassing traditional distributor tiers as export-oriented brewing concentrates purchasing authority.
Large-scale brewers lock in the majority of annual volume; contract brewers are expanding most quickly as production outsourcing accelerates.
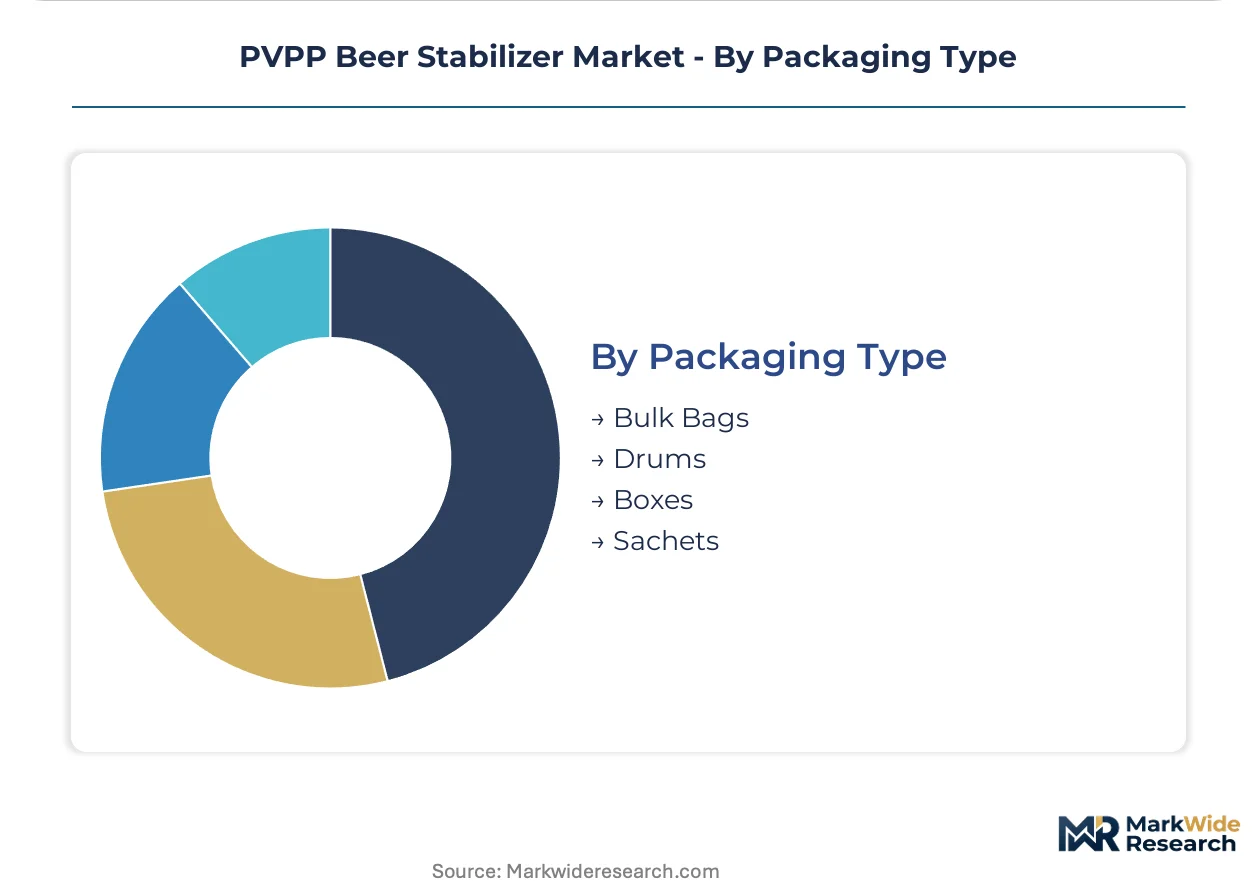
Packaging Type:
Supply concentration in bulk formats faces regulatory pressure from evolving single-use plastic restrictions.
- Bulk Bags:25-kilogram and larger formats dominating automated handling systems at industrial malt houses. German distribution protocols rely on bulk bag logistics, though EU directives on plastic packaging threaten established workflows without immediate bio-based alternatives.
- Drums:Liquid concentrate containment for microbrewery and craft segment delivery. Italian craft breweries specify drum packaging for liquid suspensions to minimize transfer contamination and dosing variability.
- Boxes:Intermediate packaging for regional distributor networks and medium-volume procurement.
- Sachets:Single-use pre-measured units for smallest-scale brewers and trial sampling programs.
Bulk bags carry the majority of tonnage; drums are climbing the fastest as liquid concentrate adoption spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance mandates and tightening EU brewing purity conventions are redirecting procurement flows toward documented PVPP grades, while craft brewery expansion in Southern Europe and contract brewing concentration in Southeast Asia reshape regional demand patterns.
Germany
KBA-adjacent food contact material standards compel malt houses in Bavaria and North Rhine-Westphalia to validate filtration inputs against expanded ECHA dossier requirements. The Krombacher and Bitburger brewing clusters anchor powder-grade procurement through multi-year supply agreements with incumbent polymer suppliers.
Czech Republic
EU brewing purity conventions drive stabilization agent procurement at Pilsner Urquell and Budweiser Budvar production facilities. The Plzeň and České Budějovice brewing districts specify high-throughput powder grades for automated filtration lines serving export markets.
Italy
Craft brewery proliferation across Lombardy and Piedmont prioritizes liquid concentrate formats for labor minimization in non-automated environments. The Milan and Turin metropolitan areas host expanding microbrewery segments that bypass traditional powder-dominant procurement models.
Vietnam
Contract brewing arrangements concentrate purchasing authority among third-party production facilities in Ho Chi Minh City and Hanoi. Export-oriented brewing hubs serving European and North American label markets negotiate direct PVPP supply agreements, bypassing traditional distributor tiers.
United States
FDA food additive regulations govern cross-border ingredient acceptance for nitrogenated and specialty beer styles proliferating across North American craft segments. The Pacific Northwest and Colorado Front Range brewing clusters command premium positioning for foam-optimized PVPP grades.
PVPP Beer Stabilizer Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers distinguished by polymer synthesis depth, regulatory dossier completeness, and technical service proximity. German and Swiss incumbents leverage cross-linking chemistry expertise and validated REACH registrations to lock in European malt house contracts. Asian cost-optimized producers compete on powder production economics for contract brewing segments. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers position for CSRD-driven carbon-footprint certification demand.
Within the European incumbent tier, BASF leverages polymer synthesis expertise to sustain supply security across malt houses requiring documented ECHA dossiers. AEB Group anchors its position through specialized brewing applications support in Italian and Spanish craft segments. Huangshan Bonsun Pharmaceuticals occupies the cost-optimized production archetype, serving Asian contract brewers with powder-grade supply arrangements.
| Leading Market Players |
|---|
| Ashland |
| AEB Group |
| BASF |
| Erbslöh Geisenheim |
| Lallemand |
| Huangshan Bonsun Pharmaceuticals |
| JH Nanhang Life Sciences |
| Synvent Materials Corporation |
| Qingdao Makall Group |
| Others |
Pricing and Supply Chain Analysis
N-vinylpyrrolidone monomer cost volatility compresses margin predictability for powder manufacturers while simultaneously widening spreads between REACH-validated European grades and unregistered Asian supply, forcing procurement officers to recalibrate supplier portfolios against both pricing tier exposure and single-source feedstock dependency.
Pricing Analysis
Certification level creates the primary spread between ECHA-registered European grades and unvalidated Asian alternatives, with foam stabilization applications commanding premium positioning over commodity clarification tiers. Pricing stratifies across premium, standard, and economy levels based on polymer cross-linking density and accompanying technical service bundling. Cost compression in standard-grade powder runs through acetylene and gamma-butyrolactone feedstock fluctuations. Contract brewers in Vietnam and Thailand exhibit highest price sensitivity, while German malt houses prioritize supply security over unit economics.
Supply Chain Analysis
Upstream N-vinylpyrrolidone synthesis concentrates in German and Swiss industrial clusters, with secondary capacity in Chinese pharmaceutical chemical parks. Cross-linked polymer production draws from acetylene derivatives and specialized reactor engineering. Single-source vulnerability pervades REACH-validated grade supply, as ECHA dossier maintenance costs deter multi-source qualification. Distribution runs through bulk bag logistics for powder grades and drum containment for liquid concentrates, with direct supply agreements displacing traditional distributor tiers among Asian contract brewers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PVPP beer stabilizer demand sits in early-cycle expansion as nitrogenated and specialty beer formats penetrate craft segments, with liquid concentrate adoption creating new procurement channels beyond legacy powder workflows.
For Market Incumbents: Harden ECHA dossier completeness against evolving F-Gas Regulation contamination thresholds while embedding technical service teams within Italian and Spanish craft brewery clusters. Silica gel substitution threats and emerging bio-based polymer mandates demand accelerated R&D in sustainable cross-linking chemistry. Capacity addition in Southeast Asian hubs captures contract brewing concentration. For New Entrants and Emerging Players: Southeast Asian contract brewing hubs offer the most penetrable entry point, with Vietnamese and Thai production facilities bypassing traditional distributor tiers. Liquid concentrate formats for sub-50,000 hectoliter microbreweries present white-space opportunity beyond powder-dominated incumbent relationships. Technical partnership with regional brewing equipment lessors enables rapid dosing system integration without capital-heavy infrastructure investment. For Investors and Strategic Acquirers: CSRD-driven carbon-footprint certification reshapes the acquisition landscape, favoring targets with validated polymer synthesis expertise and established ECHA registrations. Long-term viability centers on defensible regulatory dossiers rather than commodity scale. The signal to monitor is accelerated brewer disclosure requirements under Corporate Sustainability Reporting Directive implementation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into N-vinylpyrrolidone Synthesis | Captive acetylene supply secures margin stability against monomer cost volatility for powder manufacturers. |
| Liquid Concentrate Production Scale-Up | Pre-hydrated suspension capacity captures Italian and Spanish craft brewery labor minimization priorities. |
| REACH Dossier Expansion | Enhanced ECHA disclosure meets German KBA-adjacent food contact material standard tightening. |
| Equipment Leasing Partnership | Asset-light filtration skid rental reconfigures competitive dynamics for mid-sized brewer procurement. |
| Bio-Based Polymer R&D Program | Sustainable cross-linking chemistry addresses evolving EU single-use plastic packaging restrictions. |
Research Methodology
Cross-validation between primary interviews with brewing technical directors, procurement leads at malt houses, polymer synthesis engineers, and stabilization equipment OEMs anchors the qualitative findings against secondary validation through customs trade data, ECHA registration databases, SEC chemical sector filings, and Cefic polymer industry reports. Bottom-up volume modeling triangulates against top-down market sizing across powder, liquid concentrate, granule, and pellet format segments.
Calibration against historical procurement patterns and disclosed capacity expansions informs the analytical framework across the analysis window. Segmentation dimensions span product type, application tier, end-user scale, and packaging format. CAGRs derive from installed base growth in automated filtration infrastructure and craft brewery formation rates. Nitrogenated beer portfolio expansion and CSRD disclosure mandates constitute industry-specific forecast inputs.
Practitioners should monitor REACH enforcement intensity, F-Gas Regulation phase-down schedules, and single-use plastic directive implementation for early signals of procurement flow redirection. Forecasts embed assumptions regarding acetylene feedstock availability and ECHA dossier maintenance continuity. Cross-checking against Cefic polymer production statistics and national brewing association capacity surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.