
 North America Cancer Therapy Market | 2026-2036
North America Cancer Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cancer Therapy Market Analytics
Modular therapy bundling is broadening payer and provider choice across the North America cancer therapy landscape. Bristol-Myers Squibb anchors its position through deep immuno-oncology specialization and manufacturing scale. Merck & Co. differentiates via sustained investment in PD-1 pathway leadership. Roche Holding AG leverages its diagnostic-therapeutic integration to control clinical decision workflows.
Cancer therapy encompasses systemic and localized interventions designed to eliminate, control, or palliate malignant disease, utilizing cytotoxic agents, immune modulators, targeted small molecules, and genetic modification platforms that typically require cold-chain distribution, sterile compounding, and biomarker-guided patient selection. Immunotherapy now leads value creation within the product type dimension, while monoclonal antibodies command the dominant margin pool across the technology dimension. Gene therapy represents the fastest-expanding segment, though reimbursement complexity constrains near-term volume scaling.
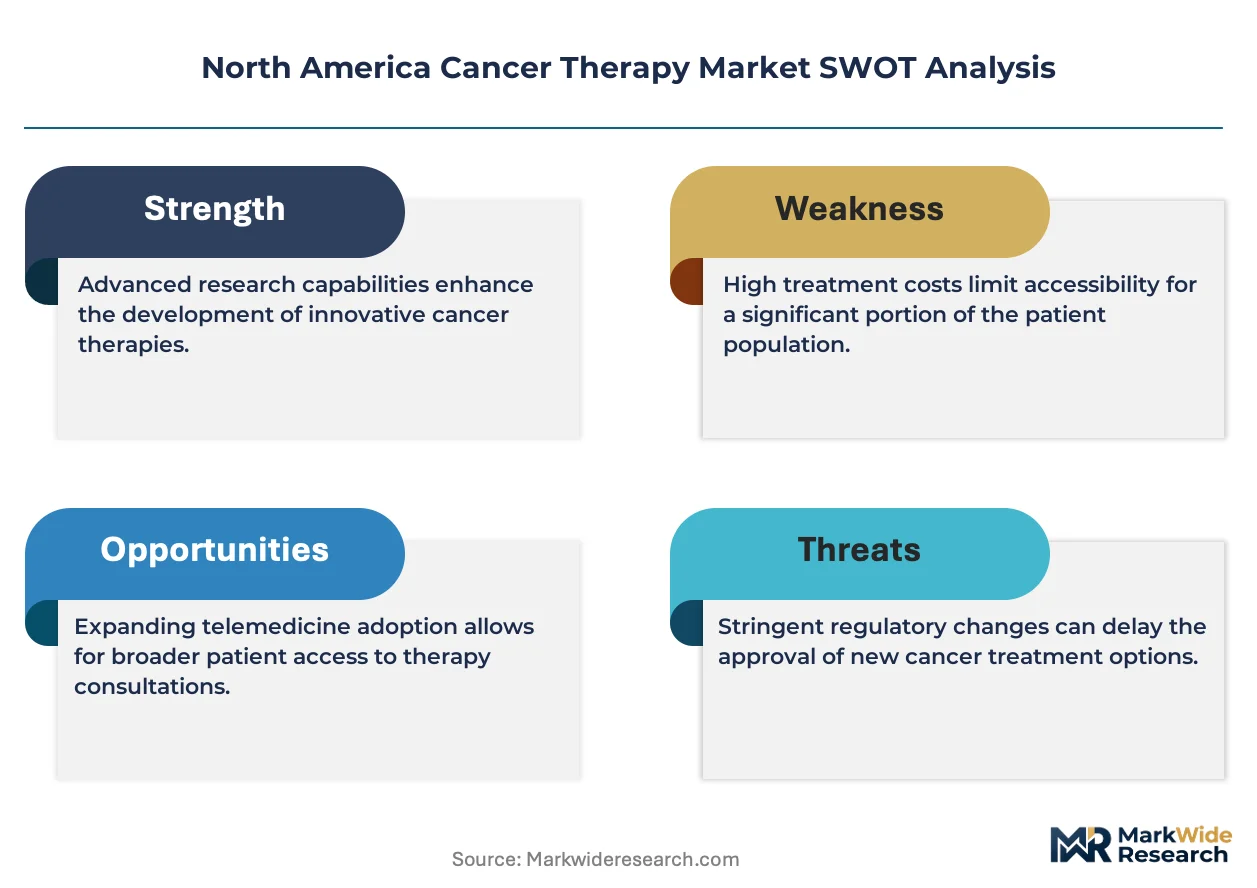
The FDA's accelerated approval framework and the IRA's Medicare price negotiation provisions reshape investment priorities and launch sequencing across the United States. Health Canada's parallel review pathways and Mexico's COFEPRIS regulatory modernization create differentiated market access timelines across the three-country region. Stakeholders must monitor biomarker coverage policy evolution and state-level Medicaid formulary decisions to anticipate reimbursement-driven demand shifts.
Market Dynamics
The IRA's Medicare price negotiation provisions are restructuring commercialization timelines for oncology biologics, forcing manufacturers to front-load value demonstration and accelerate indication expansion before price controls activate.
Growth Catalysts
- FDA Accelerated Approval:The pathway compresses Phase II-to-market timelines for breakthrough-designated immuno-oncology agents, enabling earlier revenue recognition and real-world evidence generation.
- Academic Medical Center Expansion:CAR-T cell therapy protocols are proliferating across major US teaching hospitals, creating captive demand for autologous cell processing infrastructure and specialized nursing labor pools.
- Boston-Cambridge Biopharma Corridor:Concentrated venture deployment and FDA proximity are shortening clinical trial startup intervals and attracting cross-border talent from Canadian and Mexican research institutions.
Market Restraints
- Plasmid DNA Supply Concentration:Viral vector manufacturing depends on a limited base of GMP-certified plasmid suppliers, creating single-source vulnerability for gene therapy developers.
- Cold-Chain Infrastructure Gaps:Ultra-low temperature requirements for cell therapies strain distribution networks in secondary US markets and Mexican border states.
- Biomarker Test Reimbursement Lag:CMS coverage determinations for companion diagnostics trail drug approvals by 12-18 months, delaying precision therapy adoption in community oncology settings.
Strategic Opportunities
- Texas Medical Center Hub:The concentration of proton therapy capacity and phase I trial units creates a gateway for Latin American patient referral networks and investigator-initiated studies.
- Health Canada Parallel Review:Synchronized FDA-Health Canada submissions compress North American launch sequencing, enabling coordinated pricing and access negotiations.
- AI-Driven Trial Matching:Machine learning platforms are converging with electronic health record systems to reduce patient screening failure rates and accelerate enrollment in rare tumor studies.
Industry Challenges
- Cell Therapy Manufacturing Workforce:Shortages of aseptic processing specialists and vector production technicians constrain capacity expansion at contract development organizations.
- Legacy Electronic Health Record Integration:Biomarker-guided treatment selection requires costly interoperability upgrades at community oncology practices, delaying protocol adoption outside academic centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cancer Therapy Market |
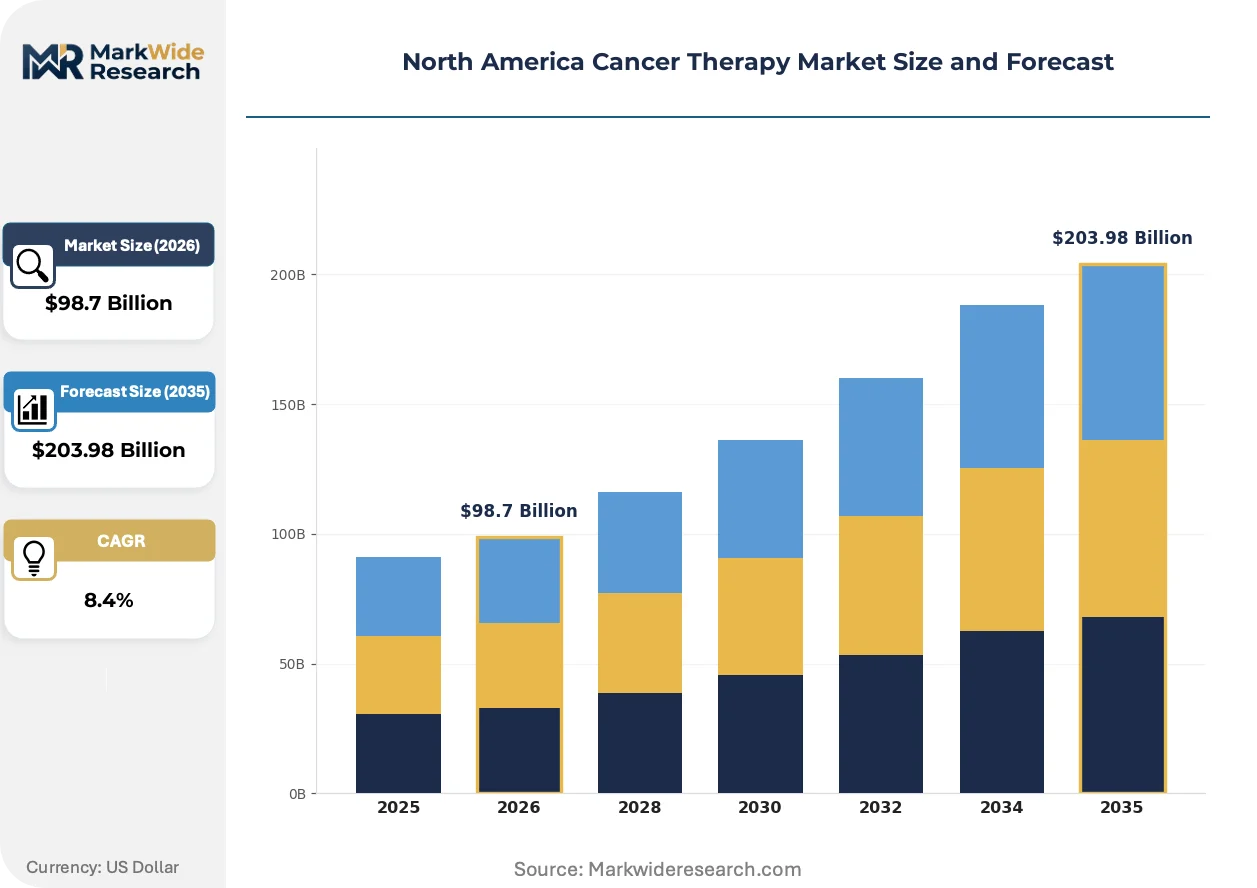
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $203.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Hormonal Therapy End User: Hospitals, Clinics, Research Institutions, Home Care Delivery Mode: Intravenous, Oral, Subcutaneous, Topical Technology: Biologics, Small Molecules, Monoclonal Antibodies, Gene Therapy |
| Companies Covered | Merck & Co., Bristol-Myers Squibb, Roche Holding AG, Johnson & Johnson, Pfizer, AstraZeneca, AbbVie, Amgen, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cancer Therapy Market Evolving Landscape
Bispecific antibody constructs are displacing sequential monotherapy regimens across hematologic malignancies, while real-world evidence platforms are compressing traditional randomized controlled trial dependencies for label expansion.
Next-generation sequencing-based minimal residual disease monitoring is expanding into front-line treatment decision workflows. Community oncology networks in Florida and Arizona are adopting liquid biopsy protocols at twice the rate of 2021 baselines. The technology is expanding into adjuvant therapy duration decisions, enabling earlier treatment cessation and reducing cumulative toxicity exposure.
COFEPRIS regulatory modernization in Mexico is harmonizing good manufacturing practice inspections with FDA mutual recognition agreements. Domestic contract manufacturing organizations are qualifying for US-bound biologic production, shortening supply lead times for Latin American-sourced starting materials. Small and mid-cap developers are prioritizing Mexican facilities for cost-sensitive biosimilar fill-finish operations.
Hospital system procurement consolidation is centralizing oncology formulary decisions at the integrated delivery network level. Independent community practices in the US Midwest are affiliating with regional health systems to access payer contracts and specialty pharmacy networks. This concentration is most visible in Michigan and Ohio, where three systems control 60 percent of infused therapy administration sites.
North America Cancer Therapy Market Segmentation
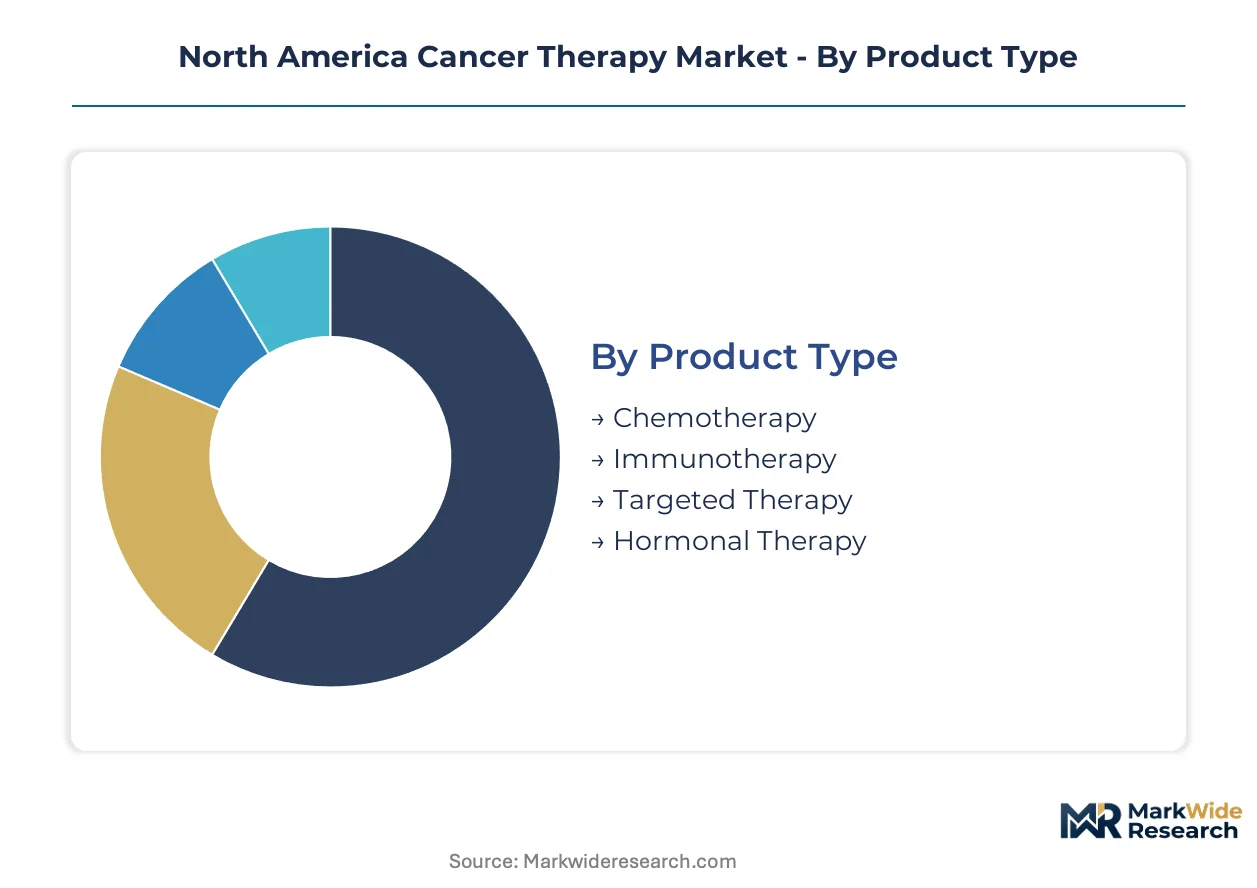
Segmentation reveals how therapeutic modalities, institutional capabilities, and administration pathways intersect to determine commercial access and reimbursement pathways across the North America cancer therapy landscape. Understanding these divisions clarifies where manufacturers must align development priorities with infrastructure constraints.
Product Type:
Standalone systemic therapies dominate outpatient infusion centers, while combination protocols increasingly embed immuno-oncology agents into first-line regimens across academic medical centers.
- Immunotherapy:Checkpoint inhibitors and CAR-T cell platforms activate host immune surveillance against tumor antigens. Demand concentrates at MD Anderson Cancer Center and Memorial Sloan Kettering, where specialized apheresis units and cytokine release syndrome management protocols attract complex case referrals from community networks.
- Targeted Therapy:Small molecule inhibitors and antibody-drug conjugates disrupt oncogenic signaling pathways with biomarker-defined patient selection. UnitedHealth's oncology pathways program and Medicare Advantage prior authorization requirements concentrate prescribing decisions at integrated delivery networks with in-house molecular profiling laboratories.
- Chemotherapy:Cytotoxic alkylating agents and antimetabolites remain embedded in curative-intent combination regimens for solid tumors.
- Hormonal Therapy:Androgen and estrogen pathway modulators address prostate and breast malignancies through long-term oral administration protocols.
Volume placements concentrate in chemotherapy; the faster expansion belongs to immunotherapy.
End User:
Institutional scale determines formulary autonomy, with hospital systems capturing infused therapy margins while home infusion networks compete on oral oncology distribution.
- Hospitals:Academic medical centers and community hospital oncology departments administer complex infusion protocols requiring on-site pharmacy compounding and emergency intervention capabilities. The Cleveland Clinic and Mayo Clinic health systems leverage captive specialty pharmacy networks to retain 340B drug pricing advantages and limit patient leakage to external infusion centers.
- Clinics:Independent and hospital-affiliated outpatient oncology practices deliver routine chemotherapy and supportive care. Florida and Arizona retirement corridor demographics concentrate Medicare fee-for-service volume at physician-owned infusion centers competing on appointment availability and parking accessibility.
- Research Institutions:National Cancer Institute-designated comprehensive cancer centers conduct phase I-III trials with investigational agent access.
- Home Care:Home health nursing and specialty pharmacy services enable oral targeted therapy and subcutaneous immunotherapy administration outside institutional settings.
Revenue concentration sits with hospitals; patient volume is climbing fastest in home care.
Delivery Mode:
Route selection shapes site-of-care economics, with intravenous administration tethered to facility fees and oral formulations enabling pharmacy benefit management leverage.
- Intravenous:Infusion pumps and gravity drip systems deliver cytotoxic and biologic agents requiring vascular access and hypersensitivity monitoring. Texas Medical Center proton therapy complexes and CAR-T cell processing units anchor high-complexity intravenous demand, with specialized nursing labor pools limiting expansion in secondary markets.
- Oral:Tyrosine kinase inhibitors and hormone modulators enable patient self-administration with periodic laboratory monitoring. CVS Caremark and Express Scripts formulary placement decisions determine commercial access, with Medicare Part D catastrophic coverage thresholds influencing patient cost-sharing design.
- Subcutaneous:Prefilled syringe and autoinjector formats reduce infusion chair time for monoclonal antibody maintenance regimens.
- Topical:Cream and gel formulations address localized skin malignancies and radiation dermatitis.
Intravenous captures the highest per-dose revenue; oral formulations are expanding most quickly.
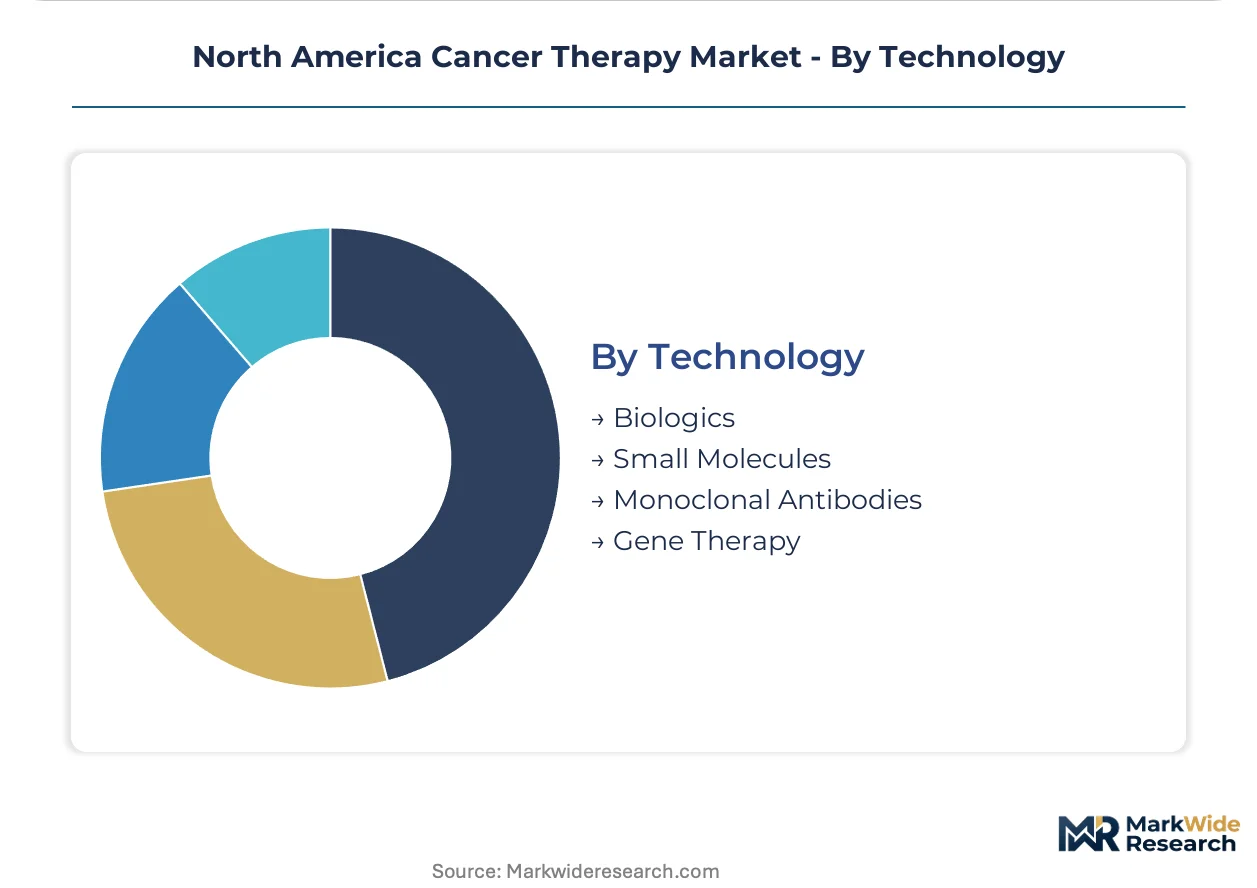
Technology:
Manufacturing complexity and regulatory pathways differentiate technology platforms, with biologics requiring cold-chain infrastructure and gene therapy demanding viral vector production scale.
- Biologics:Recombinant proteins and fusion molecules produced in mammalian cell culture systems target cytokine and growth factor pathways. Amgen's Thousand Oaks manufacturing campus and Bristol-Myers Squibb's Devens biologics facility anchor North American production capacity, with single-use bioreactor adoption reducing batch contamination risk.
- Gene Therapy:Viral vector-delivered genetic modifications and CRISPR-based editing platforms address hematologic and solid tumor indications. Novartis's Morris Plains cell processing center and Kite Pharma's El Segundo viral vector manufacturing site concentrate autologous and allogeneic production expertise, with plasmid DNA supply constraints limiting capacity expansion timelines.
- Monoclonal Antibodies:Humanized and fully human immunoglobulin constructs target tumor antigens and immune checkpoints.
- Small Molecules:Synthetic chemistry-derived kinase inhibitors and epigenetic modulators enable oral bioavailability and blood-brain barrier penetration.
Monoclonal antibodies command the dominant revenue share; gene therapy platforms show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in the United States while Canada and Mexico concentrate on specialized distribution and regulatory gateway functions. The three-country region operates as an integrated demand basin with differentiated infrastructure roles.
United States
FDA accelerated approval pathways and IRA price negotiation provisions compress commercialization timelines for oncology biologics. The Boston-Cambridge corridor attracts Canadian and Mexican research talent through concentrated venture deployment. MD Anderson Cancer Center and Memorial Sloan Kettering anchor CAR-T cell therapy demand through specialized apheresis units and cytokine release syndrome management protocols.
Canada
Health Canada parallel review pathways synchronize submissions with FDA timelines, enabling coordinated North American launch sequencing. The country's national pharmaceutical regulator harmonizes good manufacturing practice inspections with FDA mutual recognition agreements. Ontario and Quebec host clinical trial units that feed into US-based phase III studies through cross-border investigator networks.
Mexico
COFEPRIS regulatory modernization aligns inspection standards with FDA protocols, qualifying domestic contract manufacturing organizations for US-bound biologic production. The Texas Medical Center proton therapy complexes attract Latin American patient referrals through phase I trial access. Northern border states and Mexico City Metro concentrate biosimilar fill-finish operations for cost-sensitive manufacturing.
North America Cancer Therapy Market Competitive Landscape
The competitive structure tilts toward large-cap biopharmaceutical conglomerates with immuno-oncology specialization and diagnostic-therapeutic integration capabilities. Scale advantages in viral vector manufacturing and monoclonal antibody production create barriers for mid-tier entrants. Three archetypes dominate: checkpoint inhibitor specialists, CAR-T cell therapy developers, and diagnostic-therapeutic integrators. Capacity expansion in single-use bioreactor infrastructure and strategic partnerships for plasmid DNA supply security represent the dominant competitive moves.
Within the large-cap integrated tier, Merck & Co., Bristol-Myers Squibb, and Roche Holding AG exemplify divergent strategic positions. Merck & Co. occupies a position defined by sustained PD-1 pathway investment. Bristol-Myers Squibb anchors the immuno-oncology specialization archetype through manufacturing scale advantages. Roche Holding AG represents diagnostic-therapeutic integration, controlling clinical decision workflows through companion diagnostic alignment.
| Leading Market Players |
|---|
| Merck & Co. |
| Bristol-Myers Squibb |
| Roche Holding AG |
| Johnson & Johnson |
| Pfizer |
| AstraZeneca |
| AbbVie |
| Amgen |
| Eli Lilly and Company |
| Others |
Value Network & Pricing Analysis
Aseptic processing specialists in the Boston-Cambridge corridor and viral vector technicians in California's Bay Area command wage premiums that compress margin spreads between premium biologics and standard chemotherapy formulations, with labor-cost differentials widening pricing-tier spreads across the North American cancer therapy landscape.
Pricing Analysis
Margin tightening in gene therapy reflects plasmid DNA supply scarcity and single-use bioreactor capacity constraints. Pricing stratifies across CAR-T cell platforms, monoclonal antibody maintenance regimens, and oral kinase inhibitors based on manufacturing complexity and cold-chain requirements. Cost-down pressure on biosimilars accelerates because Medicare Advantage formulary placement decisions concentrate purchasing power at integrated delivery networks. Community oncology practices exhibit highest price sensitivity due to 340B pricing dependency, while academic medical centers demonstrate lowest sensitivity given captive specialty pharmacy networks and research funding offsets.
Supply Chain Analysis
Dual-sourcing mandates from FDA-qualified contract manufacturers require viral vector developers to qualify plasmid suppliers across the United States, Switzerland, and Germany simultaneously. Gene therapy production draws from GMP-certified plasmid DNA, single-use bioreactor components, and cryopreservation media as critical inputs. Single-source vulnerability in plasmid supply creates systemic risk for autologous cell therapy programs. Distribution runs through captive specialty pharmacy networks at hospital systems, with cold-chain logistics partners handling last-mile delivery to infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America cancer therapy market represents a consolidation play as IRA Medicare price negotiation provisions force subscale developers into strategic exits before price controls activate on their lead assets.
For Market Incumbents: Cement manufacturing scale advantages through captive plasmid DNA production and single-use bioreactor capacity expansion at existing FDA-inspected sites. Lock in cytokine release syndrome nursing labor pools through exclusive staffing contracts at academic medical centers. Defend against emerging allogeneic cell therapy developers by accelerating autologous platform indication expansion.
For New Entrants and Emerging Players: Launch via hospital system specialty pharmacy partnerships rather than independent distribution to bypass formulary access barriers. Target liquid biopsy companion diagnostic bundling as the most penetrable entry point, given biomarker test reimbursement lag creates white-space for integrated test-therapy offerings. Pursue COFEPRIS-registered Mexican manufacturing for cost-sensitive biosimilar fill-finish operations serving US border states.
For Investors and Strategic Acquirers: Re-rating potential sits with diagnostic-therapeutic integrators given FDA accelerated approval pathway expansion and companion diagnostic alignment requirements. Long-term viability favors developers with viral vector manufacturing capabilities and Health Canada parallel review submission experience. Watch biomarker coverage policy evolution at CMS as the inflection signal for precision therapy adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Plasmid DNA Supply Security | Backward integration into GMP-certified plasmid production eliminates single-source vulnerability for gene therapy developers. |
| Health Canada Parallel Review | Synchronized FDA-Health Canada submissions compress North American launch sequencing for coordinated pricing negotiations. |
| AI-Driven Trial Matching | Machine learning integration with EHR systems reduces patient screening failure rates at NCI-designated cancer centers. |
| Community Oncology Affiliation | Hospital system consolidation in Michigan and Ohio captures Medicare fee-for-service volume through 340B pricing advantages. |
| COFEPRIS Manufacturing Qualification | Mexican contract manufacturing organization registration for US-bound biologic production shortens supply lead times. |
Research Methodology
Document review covered FDA accelerated approval filings, Health Canada regulatory submissions, CMS coverage determinations, and ClinicalTrials.gov enrollment data, complemented by interviews with CAR-T cell therapy program directors, oncology formulary managers at integrated delivery networks, payer access specialists at Medicare Advantage plans, and contract manufacturing organization executives. Secondary sources included hospital procurement databases, GPO contract repositories, and 340B pricing disclosure reports. Bottom-up patient volume estimates and top-down manufacturer revenue triangulation anchored market sizing.
Segment-level value outputs across immunotherapy, targeted therapy, chemotherapy, and hormonal therapy modalities were generated through treatment-line penetration modeling, dosing schedule assumptions, and reimbursement pathway mapping across the analysis window. CAGRs were derived from log-linear regression of historical approval velocity and forward pipeline assessment. Patient population segmentation by biomarker status and administration route informed demand projections.
IRA price negotiation implementation timing, biomarker test coverage determination delays, and viral vector manufacturing capacity expansion rates are the dominant revision risks to the forecast outlook. Deviation in CMS companion diagnostic reimbursement policy would shift the precision therapy adoption trajectory materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Nuclear Medicine Therapeutics Market
Specialty Medicine
Short Bowel Syndrome Market
Specialty Medicine
Bronchiectasis Market
Specialty Medicine
Cutaneous Fibrosis Treatment Market
Specialty Medicine
Medical Foods for Orphan Diseases Market
Specialty Medicine
Global Cancer Immunotherapies Market
Specialty Medicine
China Precision Medicine Market
Specialty Medicine
Fibrodysplasia Ossificans Progressiva (FOP) Treatment Market
Specialty Medicine
Global Anal Fistula Treatment Market
Specialty Medicine
Global Interstitial Cystitis Market
Specialty Medicine
Global Pancreatic Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Aldosteronism Treatment Market
Specialty Medicine
Bronchiectasis Therapeutic Market
Specialty Medicine
Asia Pacific Liver Cancer Market
Specialty Medicine
Global Tourette Syndrome Treatment Market
Specialty Medicine
Glaucoma Market