
 Global Cancer Therapy Market | 2026-2036
Global Cancer Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cancer Therapy Market Analysis
Outcome-based pricing for CAR-T cell therapy administration is realigning how pharmaceutical manufacturers contract with hospital systems. F. Hoffmann-La Roche Ltd. anchors its position through companion diagnostic bundling with targeted oncology portfolios. Bristol-Myers Squibb Company leverages extensive immuno-oncology manufacturing scale to sustain supply commitments across multiple continents. Merck & Co., Inc. dominates the PD-1 inhibitor segment through broad label expansions and extensive clinical trial networks.
Cancer therapy encompasses pharmacological, biological, and radiological interventions designed to destroy malignant cells or arrest tumor progression, with monoclonal antibodies typically manufactured via mammalian cell culture in bioreactors exceeding ten thousand liters. Immunotherapy commands the fastest expansion among product types as checkpoint inhibitors demonstrate durable responses in previously refractory solid tumors. Hospitals remain the primary end user segment due to infusion infrastructure requirements and regulatory mandates for supervised administration of cytotoxic agents. Intravenous delivery persists as the dominant administration route despite oral kinase inhibitors gaining traction in maintenance settings.
The FDA accelerates market entry through breakthrough therapy and fast track designations, while the EMA's PRIME scheme offers parallel regulatory support for innovative oncology medicines in Europe. China's NMPA has streamlined oncology drug reviews through priority review pathways aligned with national cancer control objectives. Stakeholders must monitor evolving reimbursement negotiations for cell and gene therapies across Medicare, national health services, and provincial insurance funds.
Market Dynamics
The FDA's accelerated approval pathway is compressing development timelines for breakthrough oncology therapies, forcing manufacturers to build manufacturing capacity ahead of confirmed clinical endpoints.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA's expedited review pathway enables earlier market entry for therapies demonstrating substantial improvement over existing treatments.
- Companion Diagnostic Bundling:Biomarker-driven patient selection is expanding addressable populations for targeted agents while improving response rates.
- China's NMPA Priority Review:Streamlined oncology drug assessments align with national cancer control objectives and accelerate commercialization timelines.
Market Restraints
- Plasmid DNA Supply Concentration:Viral vector manufacturing depends on a limited base of specialized suppliers concentrated in North America and Europe.
- EMA ATMP Complexity:Advanced therapy medicinal product classifications impose extended regulatory timelines and manufacturing inspection requirements.
- Allogeneic Cell Therapy Substitution:Off-the-shelf cellular products threaten autologous manufacturing economics and facility utilization rates.
Strategic Opportunities
- India's CDSCO Biologics Pathway:Emerging biosimilar and originator biologic frameworks create first-mover positioning for oncology portfolios.
- Subcutaneous Formulation Shift:Self-administration devices are displacing infusion center dependency and expanding community oncology access.
- Japan's SAKIGAKE Designation:PMDA's early approval system offers priority review and extended exclusivity for innovative cancer therapies.
Industry Challenges
- Cell Therapy Manufacturing Talent Scarcity:GMP-grade vector production and cryopreservation expertise remains concentrated among limited specialist workforces.
- Legacy EHR Integration Friction:Real-world evidence collection requires interoperability with hospital information systems lacking standardized oncology data models.
- Multi-Region cGMP Certification Burden:Simultaneous FDA, EMA, and NMPA inspections demand redundant quality systems and extended facility qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cancer Therapy Market |
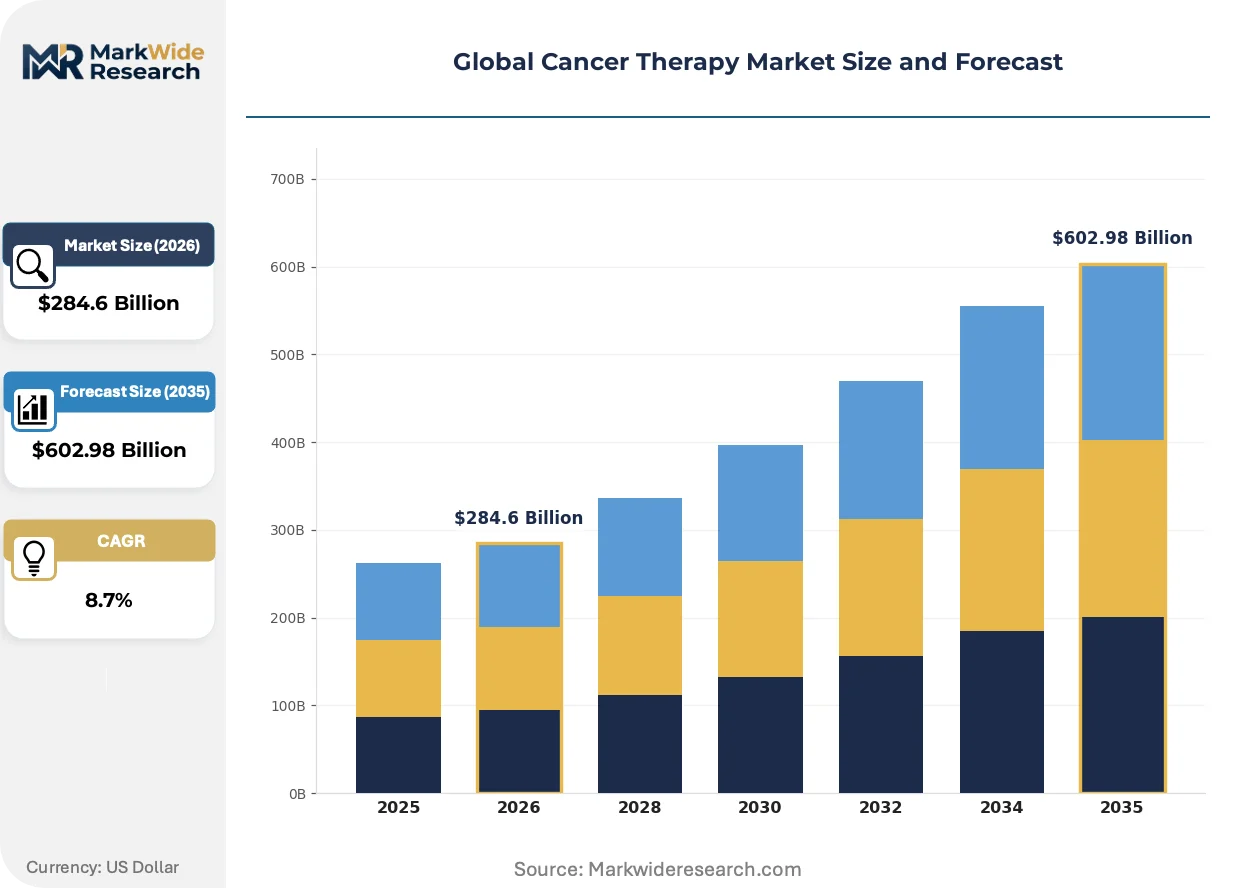
| Market Size in 2026 | $284.6 Billion |
| Market Size in 2035 | $602.98 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Hormonal Therapy End User: Hospitals, Clinics, Research Institutions, Home Care Administration Route: Intravenous, Oral, Subcutaneous, Topical Therapy Area: Breast Cancer, Lung Cancer, Colorectal Cancer, Prostate Cancer |
| Companies Covered | Merck & Co., Inc., F. Hoffmann-La Roche Ltd., AstraZeneca, Bristol-Myers Squibb Company, Pfizer Inc., Johnson & Johnson, Novartis AG, AbbVie Inc., Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cancer Therapy Market Emerging Trajectories
Artificial intelligence is penetrating every stage of oncology drug development, from target identification through clinical trial design and post-market surveillance.
Machine learning platforms are automating biomarker discovery and patient stratification for immuno-oncology trials. Large tertiary hospital systems are deploying these tools to compress enrollment timelines and reduce protocol amendments. The technology is automating previously manual histopathology review processes that bottlenecked diagnostic confirmation.
The EU AI Act's risk-based classification system imposes conformity assessment requirements on clinical decision support algorithms. Developers must now demonstrate algorithmic transparency and bias mitigation for tools supporting treatment selection. European oncology centers are responding by establishing internal AI governance committees ahead of full enforcement.
Hospital systems are consolidating pharmaceutical procurement through centralized specialty pharmacy models. Integrated delivery networks are displacing traditional wholesale relationships for high-cost oncology agents. This pattern is most visible in the United States, where health system-owned specialty pharmacies now handle a majority of oral oncolytic dispensing.
Global Cancer Therapy Market Segmentation
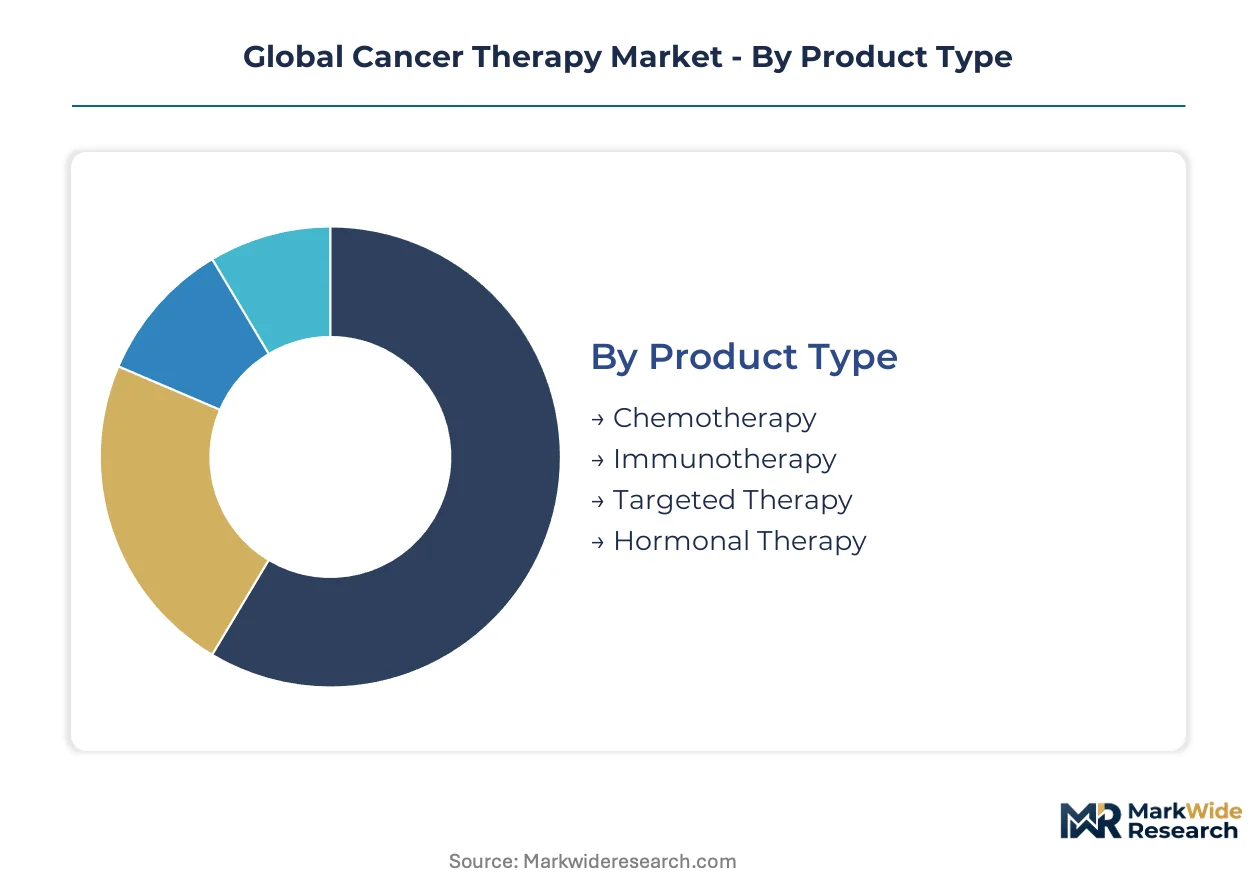
Segmentation in cancer therapy reveals distinct infrastructure requirements and reimbursement pathways that shape commercial strategy. Each dimension—product modality, care setting, delivery mechanism, and tumor indication—carries unique regulatory, manufacturing, and clinical trial implications that determine market access speed and pricing power.
Product Type:
Integration depth varies sharply: immunotherapy and targeted therapy demand companion diagnostic infrastructure and specialized manufacturing, while chemotherapy operates through established distribution networks with minimal biomarker dependencies.
- Immunotherapy:Checkpoint inhibitors and CAR-T cell therapies require GMP-grade bioreactors exceeding ten thousand liters and cryopreservation logistics. Demand concentrates in tertiary oncology centers across the United States, Germany, and China where infusion infrastructure and FDA-NMPA-EMA trial networks align.
- Targeted Therapy:Small molecule inhibitors and monoclonal antibodies are manufactured via mammalian cell culture with biomarker-driven patient selection protocols. Oncology departments in integrated US health systems and China's tier-3 hospitals drive adoption where companion diagnostic bundling with therapy selection is operational.
- Chemotherapy:Cytotoxic agents with established generic competition and standardized administration protocols.
- Hormonal Therapy:Endocrine-targeting agents for prostate and breast malignancies with oral maintenance dosing profiles.
Volume placements concentrate in chemotherapy due to broad tumor applicability; the faster expansion belongs to immunotherapy as durable responses in refractory solid tumors reshape treatment paradigms.
End User:
Cost tier stratification separates high-complexity administration requiring supervised infusion from self-administered maintenance regimens that shift care toward lower-acuity settings.
- Hospitals:Tertiary medical centers with dedicated oncology wards, radiation infrastructure, and multidisciplinary tumor boards. These facilities anchor demand in the United States, China, and Germany where regulatory mandates require cytotoxic supervision and CAR-T administration occurs.
- Clinics:Community oncology practices and ambulatory infusion centers handling stable patients on established protocols. Concentrated in US metropolitan corridors and European urban networks where reimbursement supports outpatient administration.
- Research Institutions:Academic medical centers conducting Phase I-III trials with early access to investigational agents.
- Home Care:Oral oncolytic dispensing and subcutaneous self-administration supported by specialty pharmacy nursing.
Patient volumes flow predominantly through hospital channels; clinics are climbing the fastest as subcutaneous formulations and oral kinase inhibitors displace infusion dependency.
Administration Route:
Supply concentration patterns align with manufacturing complexity: intravenous delivery demands cold-chain logistics and sterile compounding facilities, while oral routes leverage conventional pharmaceutical distribution.
- Intravenous:Infusion-dependent biologics requiring pharmacy compounding, pump administration, and post-infusion monitoring. Hospital systems in the United States and Germany maintain the densest infrastructure, with China's tertiary hospitals expanding capacity rapidly under NMPA priority review pathways.
- Oral:Kinase inhibitors and hormonal agents enabling community dispensing and patient self-management. US health system-owned specialty pharmacies now dominate this channel through centralized procurement models.
- Subcutaneous:Self-injection devices reducing infusion center burden and enabling home administration.
- Topical:Localized dermatologic and mucosal applications with limited systemic exposure.
Intravenous routes still capture the majority of biologic volumes; subcutaneous delivery is gaining share fastest as device-enabled self-administration expands access beyond major medical centers.
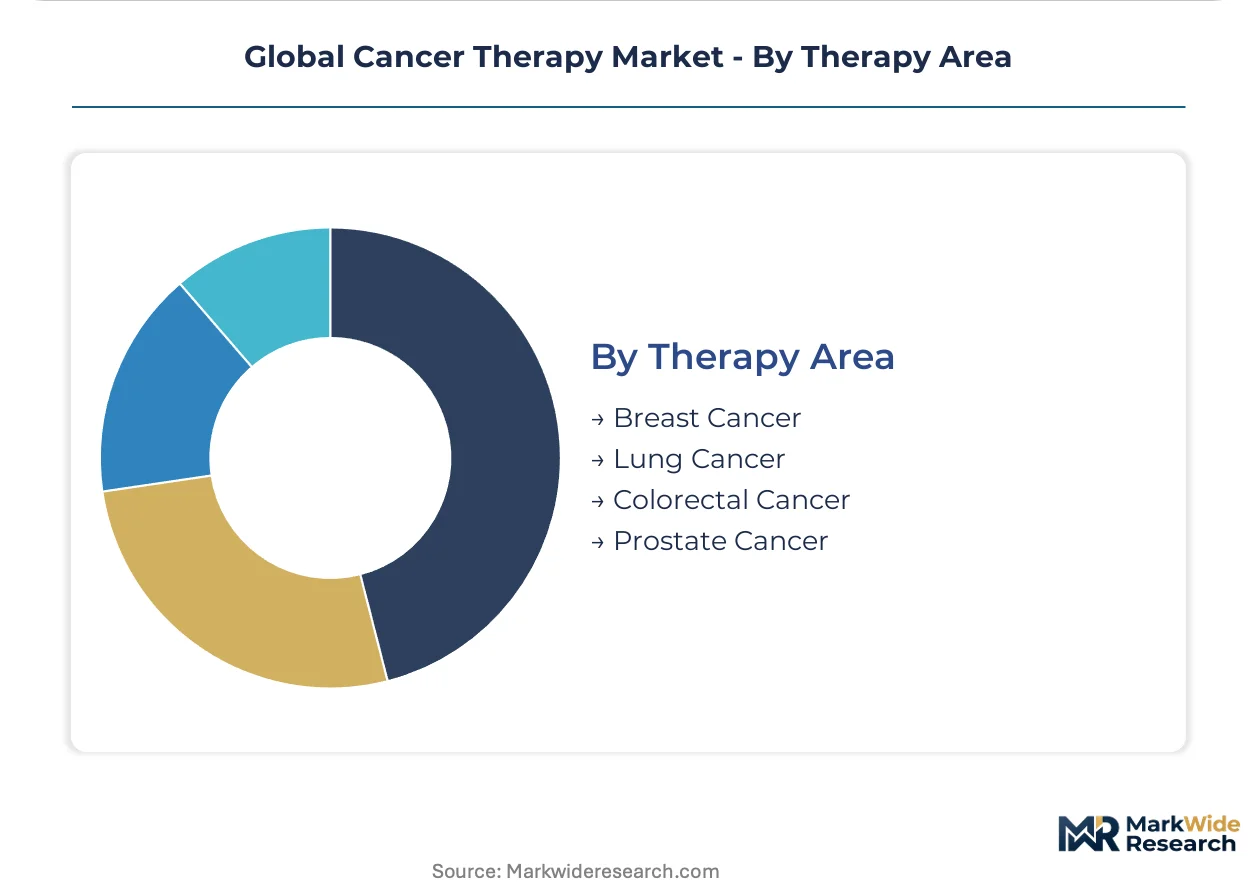
Therapy Area:
Maturity gradients separate well-established screening and treatment protocols from indications where immuno-oncology is displacing earlier standards of care.
- Lung Cancer:The leading oncology indication by mortality burden with extensive PD-1/PD-L1 inhibitor penetration. Non-small cell lung cancer drives protocol adoption across US academic centers and China's tier-3 hospitals where biomarker testing (EGFR, ALK, ROS1) is standard.
- Breast Cancer:Hormone receptor-positive, HER2-positive, and triple-negative subtypes with distinct therapeutic pathways. US integrated delivery networks and German oncology centers concentrate demand for CDK4/6 inhibitors and HER2-directed therapies.
- Colorectal Cancer:MSI-high subpopulations benefiting from checkpoint inhibitor approaches with established surgical and chemotherapeutic backbones.
- Prostate Cancer:Androgen deprivation combinations and PARP inhibitor eligibility in homologous recombination deficient patients.
Commercial activity concentrates in lung and breast indications; colorectal cancer represents the steepest expansion trajectory as MSI-high screening expands checkpoint inhibitor eligibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors the world's densest concentration of oncology clinical trial activity, with Memorial Sloan Kettering Cancer Center in New York and MD Anderson in Texas forming a triangular corridor of tertiary care demand.
United States
FDA's breakthrough therapy designation and Medicare reimbursement for CAR-T administration drive hospital system consolidation around academic medical centers. The National Cancer Institute's Cancer Moonshot initiative accelerates immunotherapy protocol adoption. The Philadelphia-Camden corridor concentrates cell therapy manufacturing facilities serving the Northeast corridor.
China
NMPA priority review pathways and provincial insurance fund expansion for oncology biologics fuel tier-3 hospital infrastructure buildout. The national cancer control program mandates biomarker testing standardization across 31 provincial jurisdictions. Shanghai's Zhangjiang Hi-Tech Park clusters domestic PD-1 developers alongside multinational manufacturing joint ventures.
Germany
EMA centralized marketing authorizations and statutory health insurance coverage for companion diagnostics sustain integrated cancer center networks. The German Cancer Research Center coordinates immuno-oncology trial access across 16 federal states. Heidelberg's National Center for Tumor Diseases anchors Baden-Württemberg's precision oncology corridor.
Japan
PMDA's SAKIGAKE designation offers priority review and extended exclusivity for innovative cancer therapies. The Ministry of Health, Labour and Welfare's reimbursement price premiums for breakthrough drugs sustain domestic pharmaceutical investment. Osaka's Kansai Biocluster concentrates monoclonal antibody manufacturing serving Asia-Pacific distribution.
India
CDSCO's emerging biologics pathway and state-level oncology facility expansion in Maharashtra and Karnataka create biosimilar manufacturing opportunities. The National Cancer Grid standardizes treatment protocols across 250+ member institutions. Hyderabad's Genome Valley anchors contract development and manufacturing for viral vector production.
Global Cancer Therapy Market Vendor Landscape
Capital-heavy biologics manufacturers compete with asset-light precision medicine developers for oncology market position. The structure concentrates among vertically integrated pharmaceutical conglomerates with bioreactor networks exceeding ten thousand liters, mid-scale immuno-oncology specialists, and emerging cell therapy platform companies. Three archetypes dominate: multinational conglomerates bundling companion diagnostics, biotech specialists with single-modality depth, and contract manufacturers capturing viral vector production. Competitive moves center on manufacturing capacity pre-commitment ahead of regulatory approval and strategic partnerships securing plasmid DNA supply.
Among Swiss-headquartered pharmaceutical conglomerates, F. Hoffmann-La Roche Ltd. exemplifies the diagnostic-therapeutic bundling archetype. Bristol-Myers Squibb Company and Merck & Co., Inc. occupy positions within the PD-1/PD-L1 checkpoint inhibitor segment, representing the scale-driven competitive tier where manufacturing network breadth determines supply security across multiple continents.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| F. Hoffmann-La Roche Ltd. |
| AstraZeneca |
| Bristol-Myers Squibb Company |
| Pfizer Inc. |
| Johnson & Johnson |
| Novartis AG |
| AbbVie Inc. |
| Eli Lilly and Company |
| Others |
Supply Flow & Price Mechanics
Integrated US health systems and China's tier-3 hospitals anchor demand concentration, locking in value-based contracting frameworks where reimbursement ties to progression-free survival endpoints. This buyer consolidation enables pharmaceutical manufacturers to command premium pricing for CAR-T and checkpoint inhibitor portfolios while forcing cost transparency in companion diagnostic bundling.
Pricing Analysis
Outcome-based pricing anchors the dominant contracting model, with pharmaceutical manufacturers negotiating risk-sharing agreements tied to patient response rates. Price differentiation separates FDA breakthrough therapy designations from standard-of-care agents, while NMPA priority review pathways in China compress timelines without equivalent price erosion. Pricing pressure stems from Medicare's prospective payment system tightening margins on hospital-administered biologics. Community oncology clinics exhibit highest price sensitivity due to reimbursement lag and cash flow constraints; academic medical centers demonstrate lowest sensitivity given research funding offsets and trial revenue.
Supply Chain Analysis
Regional distribution centers in Indianapolis, Rotterdam, and Singapore anchor hub-and-spoke cold-chain logistics for biologics requiring cryopreservation. Manufacturing concentrates in the United States, Switzerland, and China, with plasmid DNA sourcing anchored in North American and European specialized suppliers. Viral vector production rests on limited GMP-grade facility capacity and concentrated talent pools. Single-source vulnerability in plasmid supply creates bottleneck exposure for cell therapy developers. Distribution runs through health system-owned specialty pharmacies displacing traditional wholesale channels for oral oncolytics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasmid DNA manufacturing scarcity props pricing power for vector producers, constraining cell therapy expansion until capacity catches demand curves.
For Market Incumbents: Hedge against allogeneic cell therapy substitution by securing cryopreservation logistics partnerships and expanding GMP bioreactor capacity in Singapore and Switzerland. Backward integration into plasmid production reduces supplier concentration risk. Defensive patent strategies around subcutaneous formulation delivery protect infusion-center revenue streams from community oncology displacement. For New Entrants and Emerging Players: Begin with India's CDSCO biologics pathway and CDSCO's emerging biosimilar frameworks, where regulatory clarity lags manufacturing capability. Target subcutaneous device-enabled formulations in European ambulatory settings, where EMA centralized approvals create scalable entry points. Partner with contract development organizations in Hyderabad's Genome Valley to bypass capital-heavy facility buildout. For Investors and Strategic Acquirers: The window for entry favors mid-scale immuno-oncology specialists with single-modality depth and established Phase II data packages. Long-term viability hinges on manufacturing network breadth across FDA, EMA, and NMPA jurisdictions. Watch for inflection signals in Medicare reimbursement determinations for cell and gene therapies as capacity constraints ease.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Bundling | Roche's diagnostic-therapeutic integration anchors biomarker-driven patient selection and response monitoring. |
| GMP Bioreactor Scale-Up | Bristol-Myers Squibb's ten-thousand-liter manufacturing networks secure supply commitments across multiple continents. |
| Subcutaneous Formulation Development | Merck's self-administration devices reduce infusion center dependency and expand community oncology access. |
| Plasmid DNA Supply Agreement | Novartis's viral vector manufacturing partnerships mitigate single-source concentration risk in North American suppliers. |
| Regulatory Priority Designation | AstraZeneca's FDA breakthrough therapy and EMA PRIME parallel submissions compress development-to-commercialization timelines. |
Methodological Framework
Independent corroboration across drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers underwrites the qualitative findings. Secondary validation draws from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling triangulates against top-down pharmaceutical revenue disclosures to anchor segmentation splits.
Rate-of-change decomposition separates volume expansion from price mix effects across the analysis window. Segmentation dimensions span treatment line, administration route, regional regulatory cluster, and biomarker-defined patient population. CAGRs derive from fitted growth curves applied to historical approval trajectories and reimbursement expansion schedules. Forecast inputs incorporate NMPA priority review pathway success rates and Medicare CAR-T coverage determination timelines.
Underlying measurement precision varies by segment; immunotherapy and cell therapy carry tighter precision than hormonal therapy due to trial disclosure density. Forecasts reflect assumptions regarding regulatory approval velocity and reimbursement negotiation outcomes. Clinical trial failure rates, plasmid supply disruptions, and allogeneic substitution timelines present specific revision risks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Pneumoconiosis Market
Specialty Medicine
HER2 Positive Gastric Cancer Market
Specialty Medicine
ADHD Therapeutics Market
Specialty Medicine
Primary Ciliary Dyskinesia Market
Specialty Medicine
Endometrial Cancer Treatment Market
Specialty Medicine
Neuroscience Market
Specialty Medicine
Global Myeloproliferative Disorders (MPD) Treatment Market
Specialty Medicine
Global Plasma Protease C1 Inhibitor Treatment Market
Specialty Medicine
Global Chronic Lower Back Pain (CLBP) Market
Specialty Medicine
Idiopathic Thrombocytopenic Purpura Therapeutics Market
Specialty Medicine
Gingivostomatitis Market
Specialty Medicine
Community Acquired Bacterial Pneumonia (CABP) Treatment Market
Specialty Medicine
Acute Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Brugada Syndrome Market
Specialty Medicine
Biliary Atresia Treatment Market
Specialty Medicine
Axial Spondyloarthritis Treatment Market