
 North America Calcium Carbonate Market | 2026-2036
North America Calcium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
North America Calcium Carbonate Market Analysis
The gap between premium precipitated calcium carbonate and commodity ground calcium carbonate is expanding as end-users split between high-purity pharmaceutical and food-grade specifications versus bulk construction filler requirements. Omya AG leverages its vertically integrated quarry-to-delivery network across the United States and Canada to sustain supply security for coated grades. Imerys anchors its position through specialized fine-particle PCC production serving paper and plastics manufacturers. Minerals Technologies Inc. competes via its satellite plant model co-located with paper mills, reducing logistics friction for uncoated product lines.
Calcium carbonate is a naturally occurring mineral compound with the chemical formula CaCO3, typically processed to purities ranging from 95% to 99.7% depending on end-use requirements, and it functions primarily as a functional filler, pH modifier, and cost-reducing extender across industrial formulations. Ground calcium carbonate dominates volume flows into construction and paper applications where lower unit costs outweigh particle-size precision. Precipitated calcium carbonate commands margin pools in plastics and pharmaceuticals where ultrafine particle distribution and surface area control determine performance. The coated calcium carbonate segment occupies a middle tier, bridging opacity demands in premium paper against dispersibility needs in masterbatch compounding.
EPA air quality standards under the Clean Air Act shape limestone mining permits and calcination emissions limits, while FDA 21 CFR regulations govern food-contact and pharmaceutical-grade calcium carbonate purity thresholds. OSHA silica exposure rules additionally influence grinding and milling operations, pushing capital investment toward enclosed processing systems. Stakeholders must monitor how state-level environmental review timelines in Texas, Alabama, and Georgia affect greenfield quarry approvals and subsequent regional supply balances.
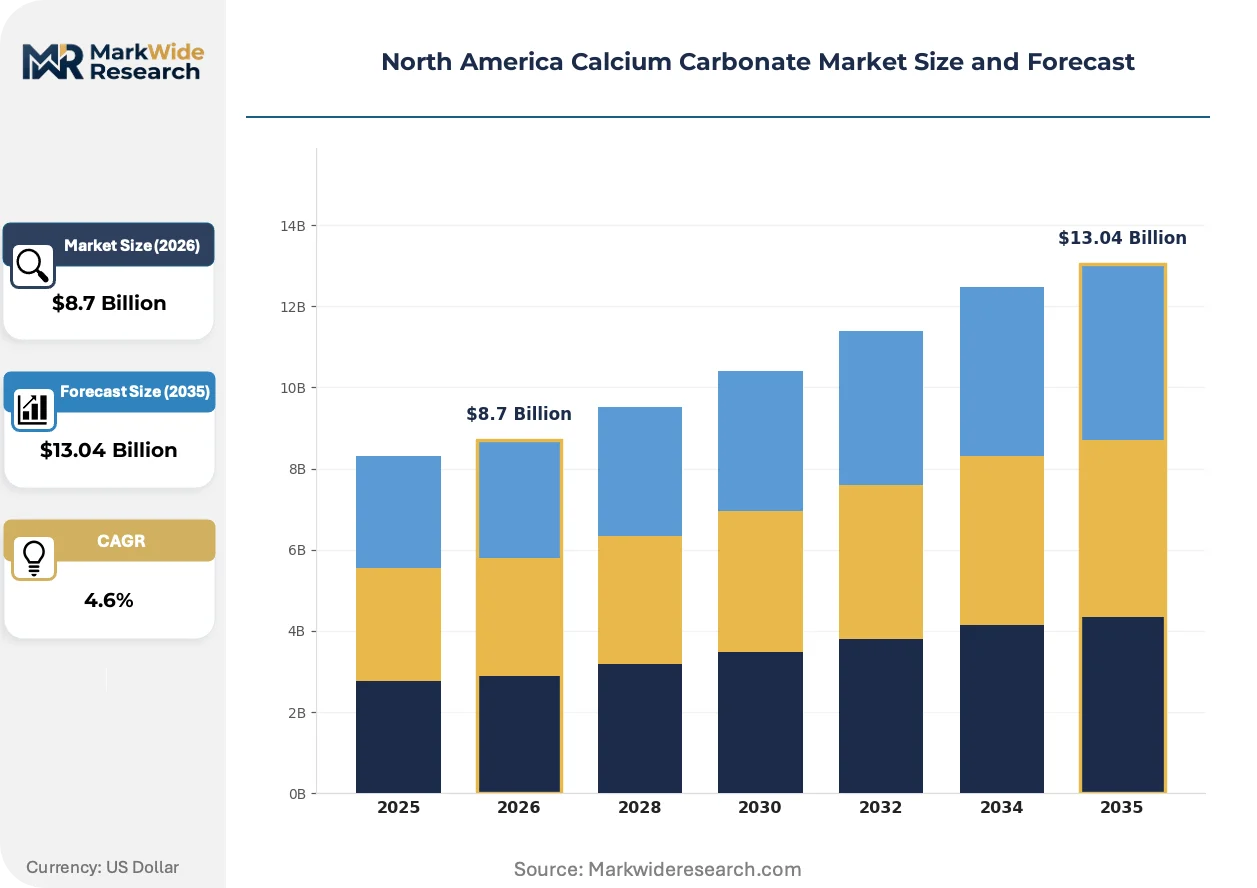
Market Dynamics
Automotive lightweighting mandates and FDA purity tightening are bifurcating demand between high-specification precipitated grades and bulk ground calcium carbonate, forcing processors to choose between margin capture and volume defense.
Growth Catalysts
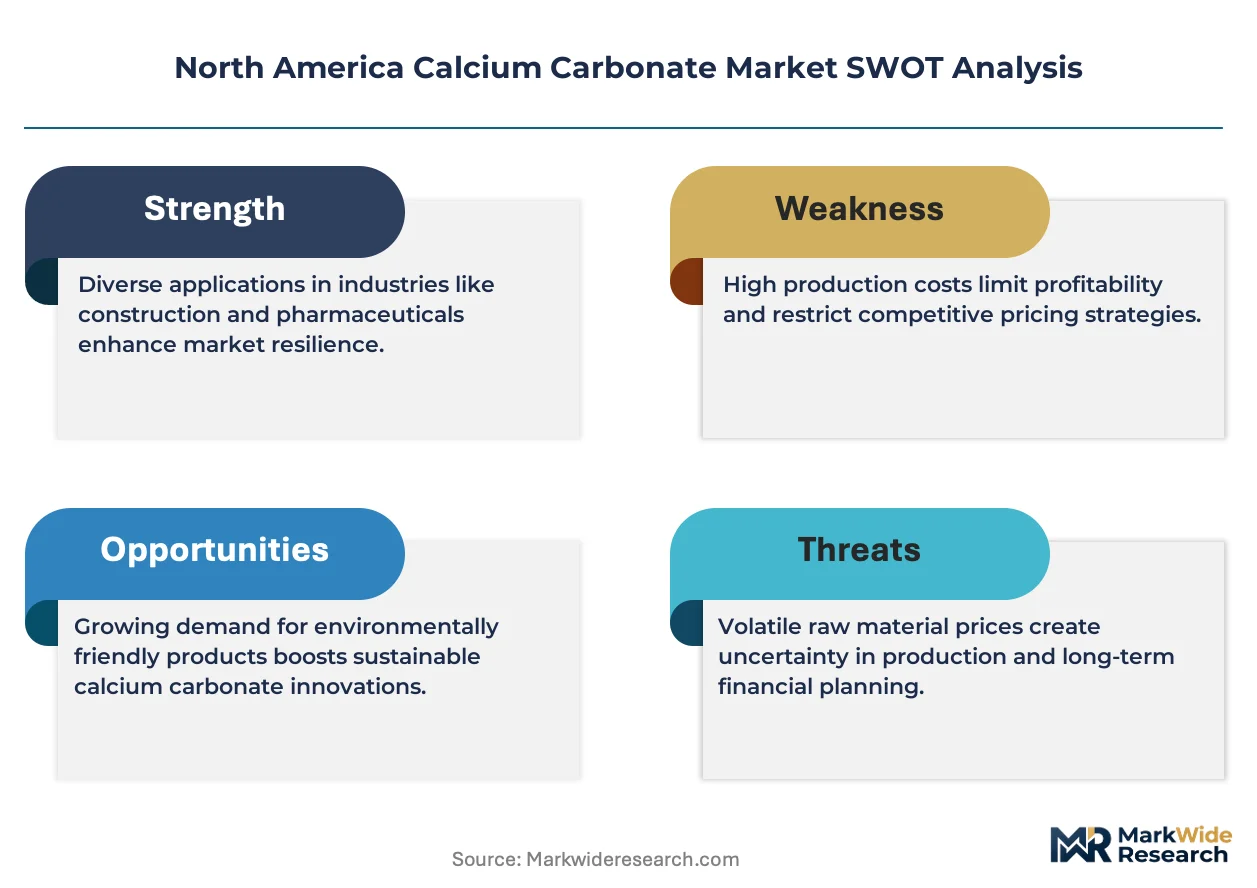
- EPA Emissions Rules:The Clean Air Act's calcination emissions limits are accelerating capital deployment toward enclosed kiln systems, favoring processors with existing environmental compliance infrastructure.
- Plastics Compounding Demand:Polypropylene masterbatch formulations in automotive interior panels are absorbing ultrafine coated grades as OEMs pursue gram-per-part reduction targets.
- Southeastern US Clustering:Limestone reserves in Alabama, Georgia, and Tennessee overlap with paper mill corridors, compressing logistics costs for uncoated product delivery.
Market Restraints
- Natural Gas Price Volatility:Calcination energy costs consume 35-40% of ground calcium carbonate production economics, exposing commodity-grade operators to Henry Hub fluctuations.
- Quarry Approval Timelines:State environmental review processes in Texas and Georgia extend greenfield limestone extraction permits to 4-7 years, constraining regional supply elasticity.
- Silica Substitution in Construction:Ground glass pozzolans and processed fly ash are displacing calcium carbonate in non-structural concrete fillers where color consistency requirements are relaxed.
Strategic Opportunities
- Pharmaceutical-Grade PCC:USP-NF and EP compliance for antacid and excipient applications commands 3-4x commodity pricing, with domestic production capacity underdeveloped relative to import dependence.
- Bio-Based Polymer Integration:Polylactic acid and polyhydroxyalkanoate compounders require surface-modified calcium carbonate to address brittleness and thermal limitations in food packaging.
- IRA Clean Manufacturing Credits:Section 45X advanced manufacturing production credits incentivize domestic precipitated calcium carbonate investment for battery separator and EV component applications.
Industry Challenges
- Particle Size Distribution Expertise:Precipitated grade production requires process engineers capable of controlling nucleation kinetics within 0.1-micron tolerances, a skill set concentrated among retired paper industry specialists.
- OSHA Silica Compliance:Grinding and milling operations face enclosed system retrofit requirements under revised permissible exposure limits, demanding capital deployment without corresponding price recovery mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Calcium Carbonate Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Calcium Carbonate, Precipitated Calcium Carbonate, Coated Calcium Carbonate, Uncoated Calcium Carbonate End User: Paints, Plastics, Rubber, Paper Industry Vertical: Construction, Pharmaceuticals, Cosmetics, Food Form: Powder, Granules, Liquid, Tablets |
| Companies Covered | Omya AG, Imerys, Minerals Technologies Inc., Mississippi Lime Company, J.M. Huber Corporation, GLC Minerals, Parchem Fine & Specialty Chemicals, Carmeuse, Graymont Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Calcium Carbonate Market Emerging Trajectories
Digitization of quality control and surface chemistry engineering are compressing development cycles for application-specific grades, while regulatory fragmentation between EPA air standards and FDA contact limits forces dual-track compliance investment.
Nano-precipitated calcium carbonate production is modularizing across satellite reactor installations co-located with paper mills and plastics compounders. Packaging manufacturers in the Great Lakes corridor are adopting these distributed units to eliminate bulk powder transportation. The technology is modularizing supply chain architecture, converting regional processors from commodity merchants to specification partners.
OSHA's updated respirable crystalline silica standard is forcing grinding operations toward enclosed pneumatic systems and remote monitoring. Capital-intensive retrofitting is consolidating operational control among processors with legacy environmental compliance infrastructure. Surface treatment facilities in Georgia and Alabama are most affected, accelerating partnerships with third-party engineering firms for turnkey enclosure packages.
Buyer consolidation among North American paperboard producers is compressing supplier rosters and extending master service agreements to 5-7 year terms. Tier-one packaging groups are unbundling technical service from material supply, contracting directly with precipitation technology licensors. This pattern is most visible in the Wisconsin and Pennsylvania mill corridors, where coated grade procurement now flows through centralized corporate sourcing functions rather than plant-level purchasing.
North America Calcium Carbonate Market Segmentation
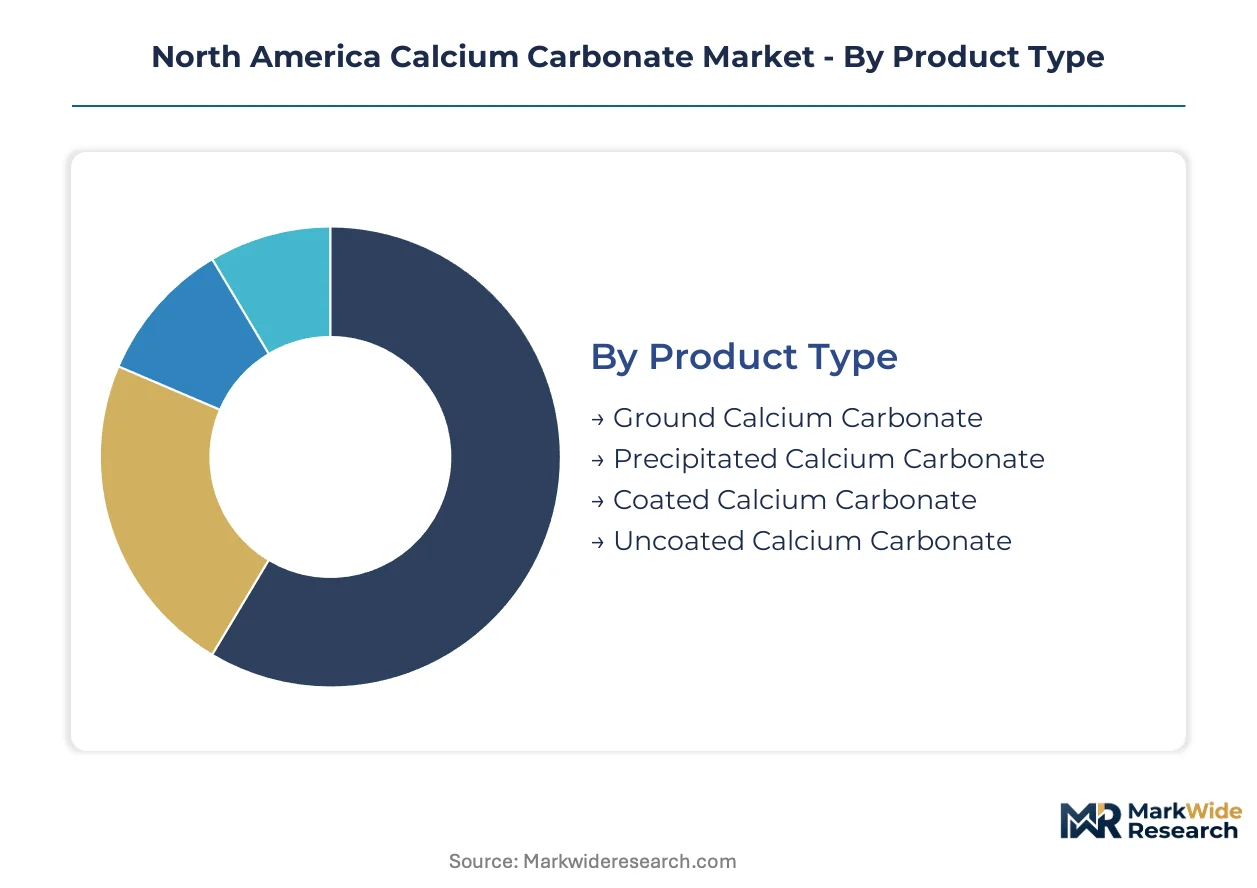
Calcium carbonate processors must align capital deployment with divergent purity and particle-size requirements across end-use specifications. Segmentation reveals where margin pools concentrate versus where volume defense dominates competitive strategy.
Product Type:
Capital intensity escalates sharply from dry grinding operations through controlled precipitation reactors to surface-modification coating lines.
- Ground Calcium Carbonate:Dry milling of limestone to 95-98% purity requires crushing, classification, and grinding circuits. Demand concentrates in southeastern US construction and paper corridors where Alabama and Georgia limestone deposits compress feedstock logistics. Natural gas price exposure in calcination-heavy operations constrains margin flexibility.
- Precipitated Calcium Carbonate:Carbonation reactors controlling nucleation kinetics to 0.1-micron tolerances demand specialized process engineering expertise concentrated among retired paper industry specialists. Automotive lightweighting mandates in polypropylene masterbatch formulations absorb ultrafine grades as OEMs pursue gram-per-part reduction targets.
- Coated Calcium Carbonate:Surface modification with stearic acid or calcium stearate bridges opacity demands in premium paper against dispersibility needs in masterbatch compounding.
- Uncoated Calcium Carbonate:Lower unit cost positioning serves bulk construction filler applications where particle-size precision is secondary to volume throughput.
Most installed capacity flows through Ground Calcium Carbonate. Expansion is steepest in Precipitated Calcium Carbonate.
End User:
Customer concentration varies from fragmented construction contractors to consolidated paperboard producers extending master service agreements.
- Paints:TiO2 extension and opacity control in architectural and industrial coatings.
- Plastics:Polypropylene masterbatch formulations in automotive interior panels absorb ultrafine coated grades driven by OEM lightweighting mandates.
- Rubber:Reinforcing filler applications in tire and industrial rubber compounding.
- Paper:Buyer consolidation among North American paperboard producers compresses supplier rosters and extends master service agreements to 5-7 year terms in Wisconsin and Pennsylvania mill corridors.
Procurement centralization is most advanced in Paper. Technical specification partnerships are deepening fastest in Plastics.
Industry Vertical:
Regulatory burden escalates from construction-grade permissiveness through FDA food-contact and USP-NF pharmaceutical compliance tiers.
- Construction:Ground glass pozzolans and processed fly ash displace calcium carbonate in non-structural concrete fillers where color consistency requirements are relaxed.
- Pharmaceuticals:USP-NF and EP compliance for antacid and excipient applications commands 3-4x commodity pricing, with domestic production capacity underdeveloped relative to import dependence.
- Cosmetics:Surface-modified ultrafine grades for opacity and rheology control in personal care formulations.
- Food:FDA 21 CFR regulations govern food-contact purity thresholds for pH modification and calcium fortification applications.
Volume concentration remains in Construction. Value capture is climbing fastest in Pharmaceuticals.
Form:
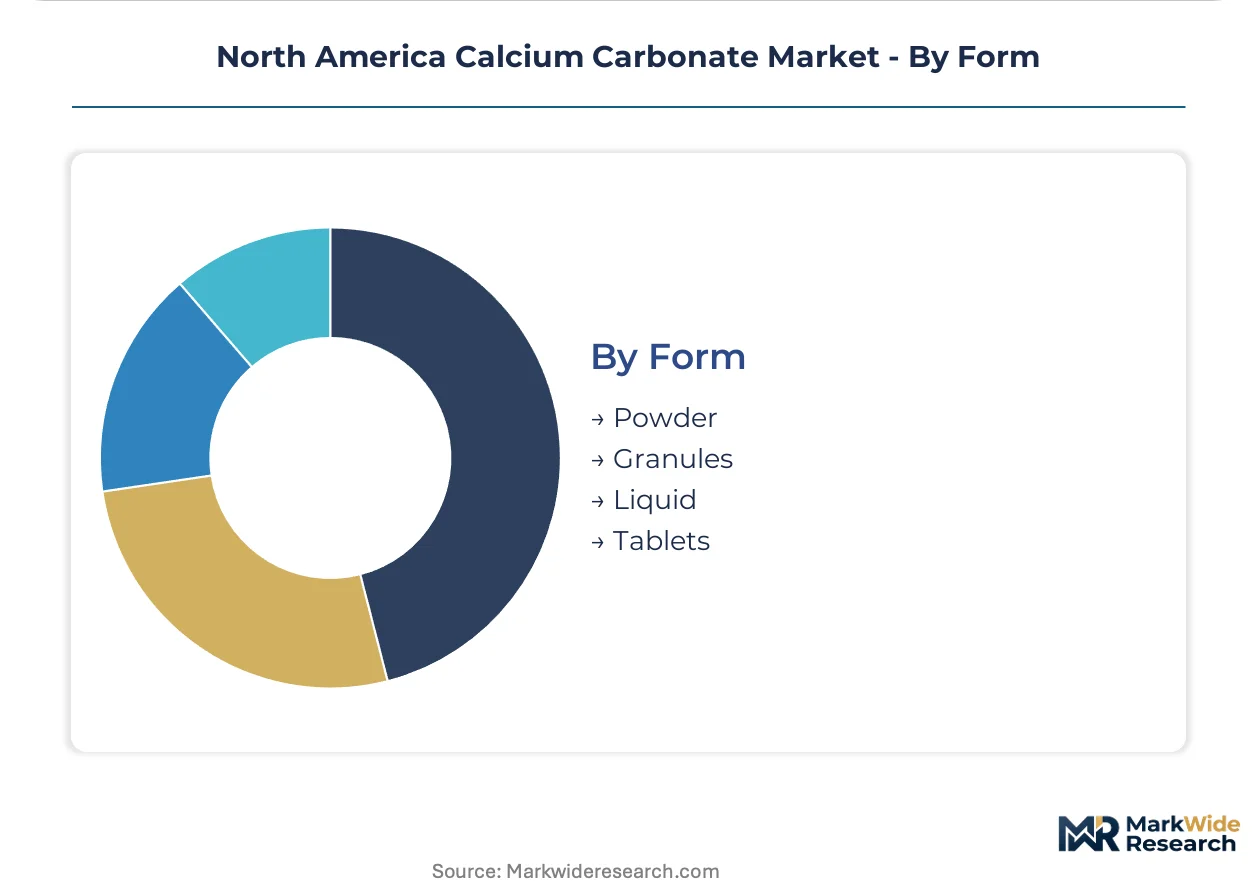
Processing economics and logistics optimization drive form selection across powder bulk handling, granule flowability, liquid dispersion, and tablet compression applications.
- Powder:Bulk pneumatic conveying dominates paper mill and plastics compounder supply chains throughout the Great Lakes and southeastern US corridors.
- Granules:Dust-free handling characteristics serve construction and agricultural lime applications where OSHA silica exposure rules push enclosed system requirements.
- Liquid:Pre-dispersed slurries eliminate powder handling infrastructure for smaller paint and coatings processors.
- Tablets:Direct compression feedstock for pharmaceutical antacid manufacturing requiring USP-NF compliance.
Most tonnage moves as Powder. Conversion investment is accelerating fastest in Liquid dispersions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's pharmaceutical-grade precipitated calcium carbonate capacity lags domestic demand, while the United States concentrates both limestone reserves and paper mill clusters in a tight geographic corridor.
United States
Automotive lightweighting mandates from NHTSA and OEM gram-reduction targets absorb ultrafine coated grades into polypropylene masterbatch formulations. EPA Clean Air Act calcination emissions limits accelerate capital deployment toward enclosed kiln systems in Alabama and Georgia. The southeastern corridor—spanning Birmingham, Atlanta, and Chattanooga—compresses logistics costs through overlapping limestone deposits and paper mill infrastructure.
Canada
Pulp and paperboard producers in Quebec and Ontario drive uncoated calcium carbonate consumption for opacity control and filler applications. Health Canada and PMRA regulations govern pharmaceutical and food-contact grade purity thresholds, tightening import substitution pressure. The Niagara Peninsula and Saguenay regions host limestone processing clusters serving Great Lakes paper mill networks with slurry pipeline delivery systems.
Mexico
Construction sector growth in Mexico City and Monterrey absorbs ground calcium carbonate for cement and concrete filler applications. SEMARNAT environmental review processes extend quarry permitting timelines, constraining greenfield limestone extraction capacity. The Bajío region—Querétaro, Guanajuato, and San Luis Potosí—emerges as a plastics compounding hub demanding coated grades for automotive supplier networks.
North America Calcium Carbonate Market Vendor Landscape
Top-tier vendors anchor the precipitated and coated grade segments, while regional ground calcium carbonate processors defend volume positions through feedstock proximity. Market structure tilts toward consolidation in high-purity applications and fragmentation in construction-grade supply. Three archetypes dominate: vertically integrated quarry-to-delivery networks, satellite plant operators co-located with paper mills, and specialty precipitated grade licensors. Competitive moves concentrate on strategic partnerships with precipitation technology licensors and geographic expansion into southeastern limestone corridors.
Among Swiss and French-based multinationals, Omya AG and Imerys occupy positions exemplifying vertically integrated archetypes with quarry-to-delivery network control. Minerals Technologies Inc. represents the satellite plant model, anchoring co-location strategies with paper mill customers. Mississippi Lime Company and J.M. Huber Corporation sit within the regional ground calcium carbonate tier, defending volume through limestone reserve proximity in the southeastern United States.
| Leading Market Players |
|---|
| Omya AG |
| Imerys |
| Minerals Technologies Inc. |
| Mississippi Lime Company |
| J.M. Huber Corporation |
| GLC Minerals |
| Parchem Fine & Specialty Chemicals |
| Carmeuse |
| Graymont Ltd |
| Others |
Supply Flow & Price Mechanics
EPA Clean Air Act calcination emissions limits gate qualified supply access and premium-tier pricing power for coated and precipitated grades, forcing buyers to pay compliance premiums for processors with enclosed kiln infrastructure while commodity ground calcium carbonate faces margin compression from natural gas cost volatility.
Pricing Analysis
Capacity additions in Alabama and Georgia are reshaping price floors for uncoated ground grades, intensifying competition among regional processors. Three-tier pricing structure across USP-NF pharmaceutical, FDA food-contact, and industrial construction grades differentiates on purity certification and particle-size precision. Cost compression in commodity ground calcium carbonate is intensifying because Henry Hub natural gas fluctuations consume 35-40% of production economics. Construction contractors exhibit highest price sensitivity, while pharmaceutical formulators accept 3-4x premiums for domestic USP-NF compliance.
Supply Chain Analysis
Limestone feedstock supply rests on quarry operations concentrated in Alabama, Georgia, and Tennessee, with calcination energy drawing from regional natural gas distribution networks. Surface-modification coating chemicals and carbonation reactor systems hinge on specialized equipment imports. Single-source vulnerability runs through the southeastern limestone corridor where greenfield quarry permits face 4-7 year state environmental review timelines. Distribution runs through bulk pneumatic conveying networks serving paper mill clusters and plastics compounders throughout the Great Lakes and southeastern corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with automotive lightweighting mandates and FDA purity tightening concentrating margin capture among precipitated and coated grade specialists while commodity ground calcium carbonate defends volume through feedstock proximity.
For Market Incumbents: Deploy satellite plant co-location as the primary lever, anchoring precipitation capacity adjacent to Wisconsin and Pennsylvania paper mill corridors to secure 5-7 year master service agreements. Defend against nano-precipitated calcium carbonate modularization by licensing surface chemistry engineering capabilities to packaging manufacturers. Deepen backward integration into captive limestone reserves in the Birmingham-Atlanta-Chattanooga triangle to offset quarry approval timeline risks. For New Entrants and Emerging Players: Enter via pharmaceutical-grade PCC production targeting USP-NF and EP compliance for antacid and excipient applications, where domestic capacity lags import dependence and commands 3-4x commodity pricing. Target the Niagara Peninsula and Saguenay regions serving Great Lakes paper networks with slurry pipeline delivery systems. Pursue direct technical service contracts with precipitation technology licensors rather than commodity merchant positioning. For Investors and Strategic Acquirers: Valuations sit cheapest among regional ground calcium carbonate processors exposed to natural gas price volatility and silica substitution in construction fillers. Five-to-ten year viability favors vertically integrated quarry-to-delivery networks with existing EPA compliance infrastructure and enclosed processing systems. Watch IRA Section 45X advanced manufacturing production credit uptake as the signal for domestic precipitated calcium carbonate investment inflection into battery separator and EV component applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Limestone Reserves | Quarry ownership in Alabama and Georgia compresses feedstock logistics costs and accelerates greenfield approval timelines. |
| Satellite Plant Co-location with Paper Mills | Minerals Technologies' model eliminates bulk powder transportation through slurry pipeline delivery to Wisconsin and Pennsylvania corridors. |
| Pharmaceutical-Grade PCC Capacity Buildout | USP-NF compliance investment captures 3-4x pricing premiums in antacid and excipient applications with underdeveloped domestic supply. |
| Surface Modification Technology Licensing | Packaging manufacturers in the Great Lakes corridor adopt distributed nano-precipitated reactor installations for specification partnerships. |
| IRA Clean Manufacturing Credit Monetization | Section 45X incentives accelerate domestic precipitated calcium carbonate investment for battery separator and EV component demand. |
Methodological Framework
Bottom-up plastics compounding and paper filler modeling reconciled against top-down limestone quarry capacity tracking forms the analytical core of this study. Primary interviews with paper mill procurement directors, plastics masterbatch formulators, calcium carbonate plant managers, and pharmaceutical excipient sourcing leads combined with secondary validation from EPA Clean Air Act enforcement data, FDA 21 CFR regulatory filings, SEC 10-K disclosures from listed processors, and state environmental permit databases. Top-down and bottom-up triangulation ensures supply-side capacity estimates align with end-use consumption patterns.
Input-output matrices map grade-tier demand across ground, precipitated, and coated calcium carbonate against regional production hub capacity, end-use industry absorption rates, and packaging format specifications throughout the projection horizon. CAGRs derive from segment-level elasticity modeling against automotive lightweighting mandates, FDA purity tightening trajectories, and construction sector substitution dynamics. Forecast inputs incorporate natural gas price scenario modeling and greenfield quarry approval timeline distributions across Texas, Alabama, and Georgia regulatory jurisdictions.
The model holds under stable EPA emissions enforcement and continued automotive lightweighting compliance requirements; deviation in IRA credit uptake velocity or accelerated silica substitution in non-structural concrete would shift precipitated grade investment attractiveness and construction filler demand trajectories. A small set of named triggers—OSHA silica standard enforcement intensity, state-level environmental review timeline compression, and pharmaceutical import substitution policy—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Caprylic Acid Market
Bulk Chemicals
White Charcoal Powder Market
Bulk Chemicals
Middle East Formaldehyde Market
Bulk Chemicals
Europe Castor Oil Market
Bulk Chemicals
Dithiocarbamates Market
Bulk Chemicals
Global Bio Based and Synthetic Dimethyl Ether (DME) Market
Bulk Chemicals
Naphthalene Market
Bulk Chemicals
Monoethylene Glycol (MEG) Market
Bulk Chemicals
Precipitated Barium Sulphate Market
Bulk Chemicals
Gluconic Acid Market
Bulk Chemicals
China Lime Market
Bulk Chemicals
Chlor Alkali Market
Bulk Chemicals
Lactic Acid Market
Bulk Chemicals
Global GABA Market
Bulk Chemicals
Saudi Arabia Sodium Thiosulphate Market
Bulk Chemicals
Oxalic Acid Market