
 China Lime Market | 2026-2036
China Lime Market Size, Share, and Industry Trends Forecast 2026-2036
China Lime Market Outlook
Modular bulk-to-bag repackaging is consolidating buyer choice across the China lime landscape. Anhui Conch Cement leverages captive limestone quarries to sustain cost leadership in quicklime supply. CNBM anchors national distribution through its provincial trading subsidiaries. Tangshan Jidong Cement competes on proximity to Hebei's steel belt, shortening haul distances for metallurgical-grade product.
Lime encompasses calcium oxide (CaO) and calcium hydroxide (Ca(OH)₂) produced by calcining limestone at temperatures exceeding 900°C, with reactivity measured by available lime index and slaking rate. Its primary purpose spans steel fluxing, flue gas treatment, soil stabilization, and chemical synthesis. Quicklime commands the largest volume pool in construction applications, where GB 1594-2017 standards enforce minimum CaO content thresholds. Hydrated lime is gaining share in municipal water treatment as phosphate precipitation regulations tighten across eastern provinces.
China's SAMR enforces GB standards for industrial lime purity and labeling, while MEE provincial branches mandate flue gas desulfurization rates that directly drive hydrated lime consumption. The country's dual carbon goals are pressuring kiln operators toward vertical shaft retrofits and alternative fuel blending. Stakeholders must monitor how carbon intensity benchmarks reshape kiln economics and regional supply balances.
Market Dynamics
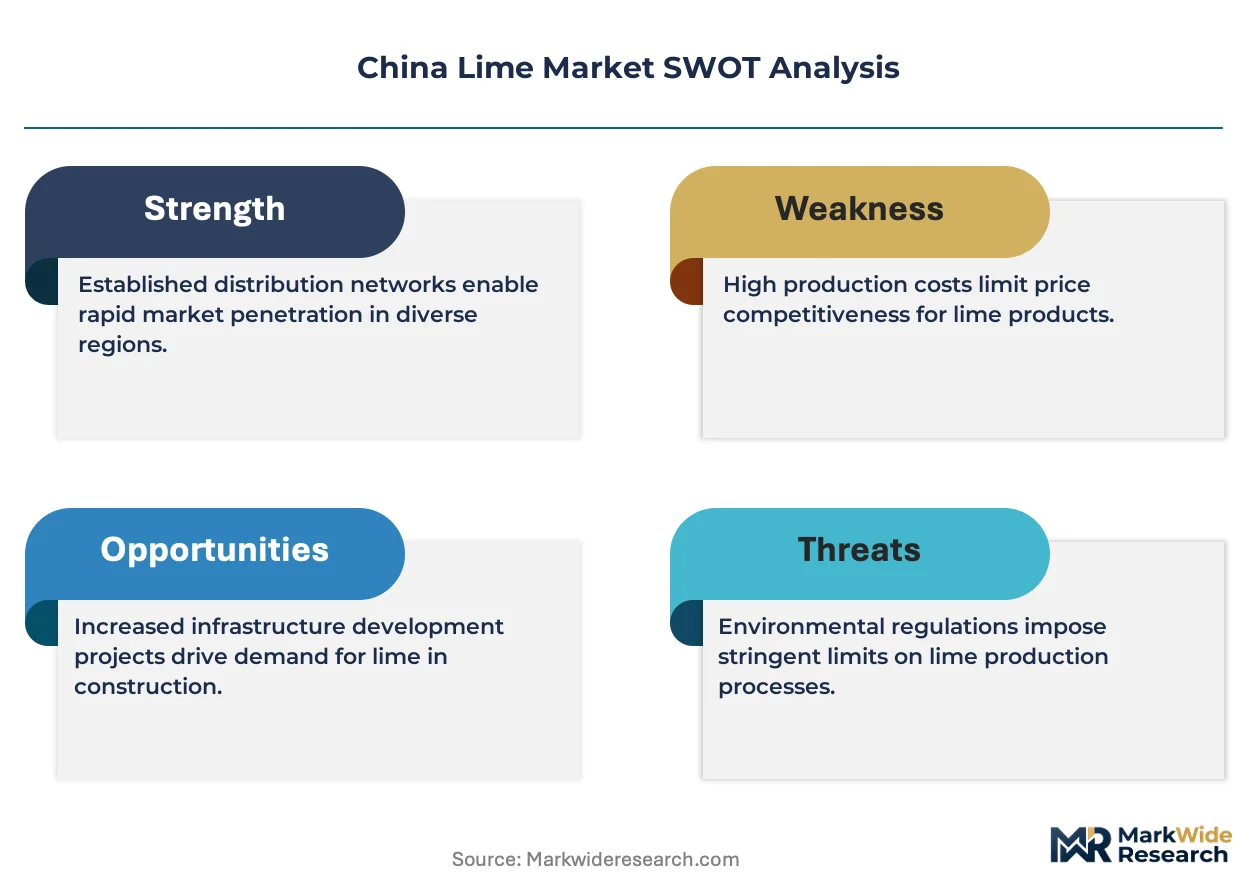
China's dual carbon goals are compressing kiln economics and forcing vertical shaft retrofits across Hebei, Shandong, and Henan provinces. This regulatory pressure is redrawing regional supply balances as smaller operators face carbon intensity benchmarks that favor integrated limestone-to-lime producers with captive quarry access.
Growth Catalysts
- GB 1594-2017 Purity Mandates:Tighter CaO content thresholds for construction-grade quicklime are filtering out substandard producers and concentrating volume among compliant kiln operators in the Yangtze River Delta.
- Flue Gas Desulfurization:MEE provincial branches in Hebei are enforcing desulfurization rates that directly pull hydrated lime into steel mill procurement schedules, tightening metallurgical-grade supply.
- Municipal Water Treatment:Phosphate precipitation regulations across eastern provinces are displacing alum-based treatments with hydrated lime systems in Jiangsu and Zhejiang facilities.
Market Restraints
- Limestone Feedstock Concentration:High-calcium limestone deposits cluster in Anhui and Guangxi, creating haul-cost disadvantages for coastal chemical plants sourcing from distant quarries.
- Energy Cost Volatility:Kiln operations depend on metallurgical coke and pulverized coal, with price swings in Shanxi coal markets directly eroding margin stability for non-integrated producers.
- Substitute Materials:Dolomitic lime and synthetic calcium carbonate are capturing share in lower-specification construction applications where GB standards permit flexibility.
Strategic Opportunities
- Western Corridor Expansion:Sichuan and Chongqing municipal water networks remain underpenetrated by hydrated lime suppliers, offering first-mover positioning as phosphate regulations migrate inland.
- Alternative Fuel Blending:Waste-derived fuels and biomass co-firing in vertical shaft kilns align with provincial carbon quotas and unlock green financing from state development banks.
- Bagged Distribution Innovation:Modular bulk-to-bag repackaging near consumption clusters is shortening lead times for small-batch chemical synthesis customers in the Pearl River Delta.
Industry Challenges
- Kiln Retrofit Capex Burden:Vertical shaft upgrades for emission compliance require 18-24 month payback periods that strain balance sheets of mid-scale operators without state-backed credit lines.
- Refractory Skill Scarcity:Specialized knowledge for lining maintenance in high-temperature kilns is concentrating among aging technician pools in Tangshan and Zibo, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Lime Market |
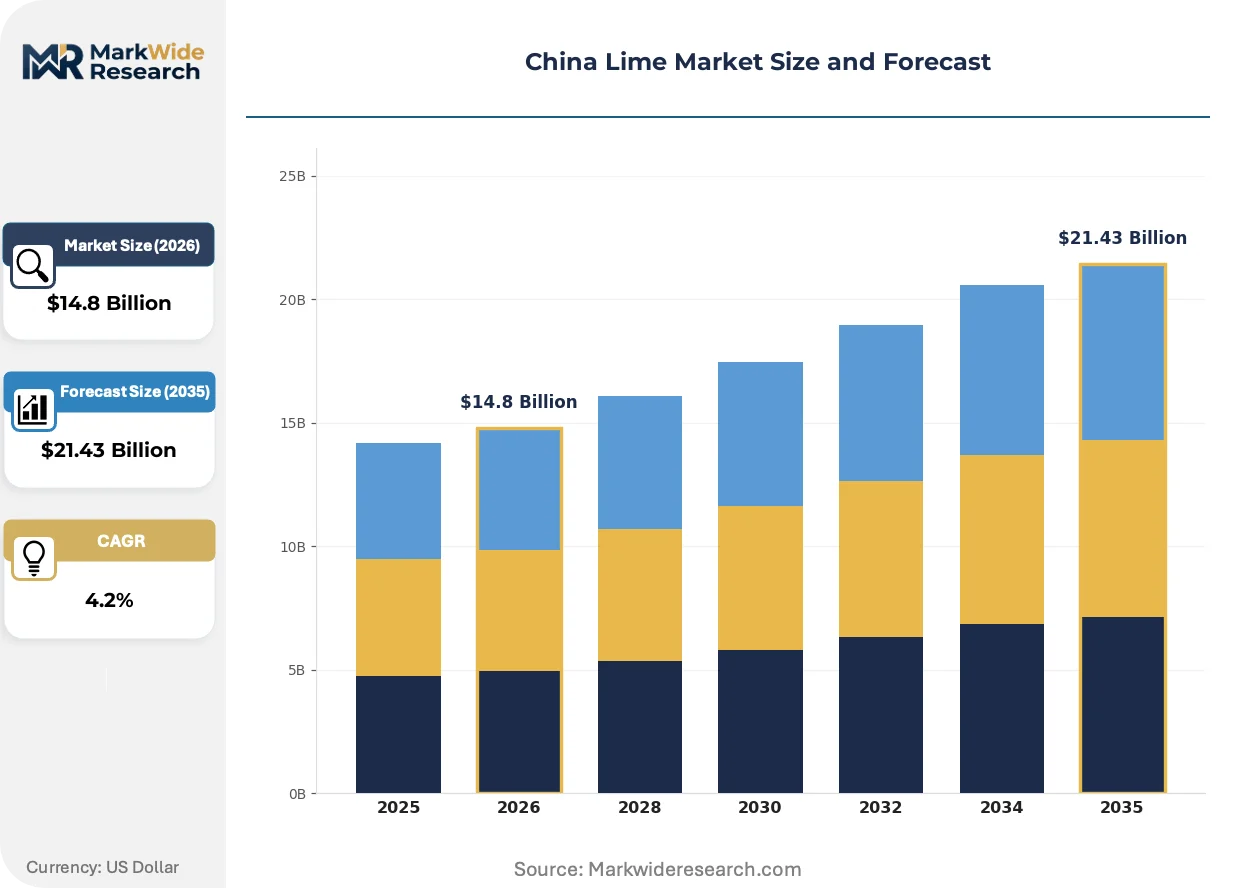
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $21.43 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quicklime, Hydrated Lime, Deadburned Lime, Calcium Carbonate Application: Construction, Water Treatment, Steel Manufacturing, Agriculture End User: Construction Industry, Municipalities, Chemical Plants, Food Processing Packaging Type: Bags, Bulk, Pallets, Drums |
| Companies Covered | Anhui Conch Cement, China National Building Material (CNBM), Tangshan Jidong Cement, Shandong Shanshui Cement Group, Taiheiyo Cement Corporation, Ube Material Industries, Lhoist Group, Carmeuse, Graymont Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Lime Market Strategic Shifts
Carbon intensity benchmarking is rewiring competitive advantage toward integrated producers with upstream quarry control and downstream logistics scale. Three technology and policy vectors are compressing the operational envelope for standalone kiln operators.
Vertical shaft kiln retrofits with waste-heat recovery systems are consolidating operational efficiency gains among early movers. Steel mills in Tangshan and chemical plants in Nanjing are prioritizing suppliers with verified emission profiles. This technology is consolidating procurement decisions around a shrinking pool of certified producers with MEE-audited carbon data.
China's GB standards revision cycle for industrial lime purity is tightening available lime index minimums for construction applications. SAMR enforcement of labeling requirements is raising compliance costs for regional traders. Construction-grade quicklime from Shandong kilns faces the steepest recertification timeline as provincial branches accelerate spot-check protocols.
Long-term offtake agreements are displacing spot-market purchases among Yangtze River Delta chemical plants seeking supply security. Bulk procurement consortia are aggregating volume from smaller water treatment facilities and negotiating directly with Anhui quarry-integrated suppliers. This pattern is most visible in Jiangsu, where municipal procurement platforms are standardizing three-year contracts with price-adjustment clauses tied to energy input costs.
China Lime Market Segmentation
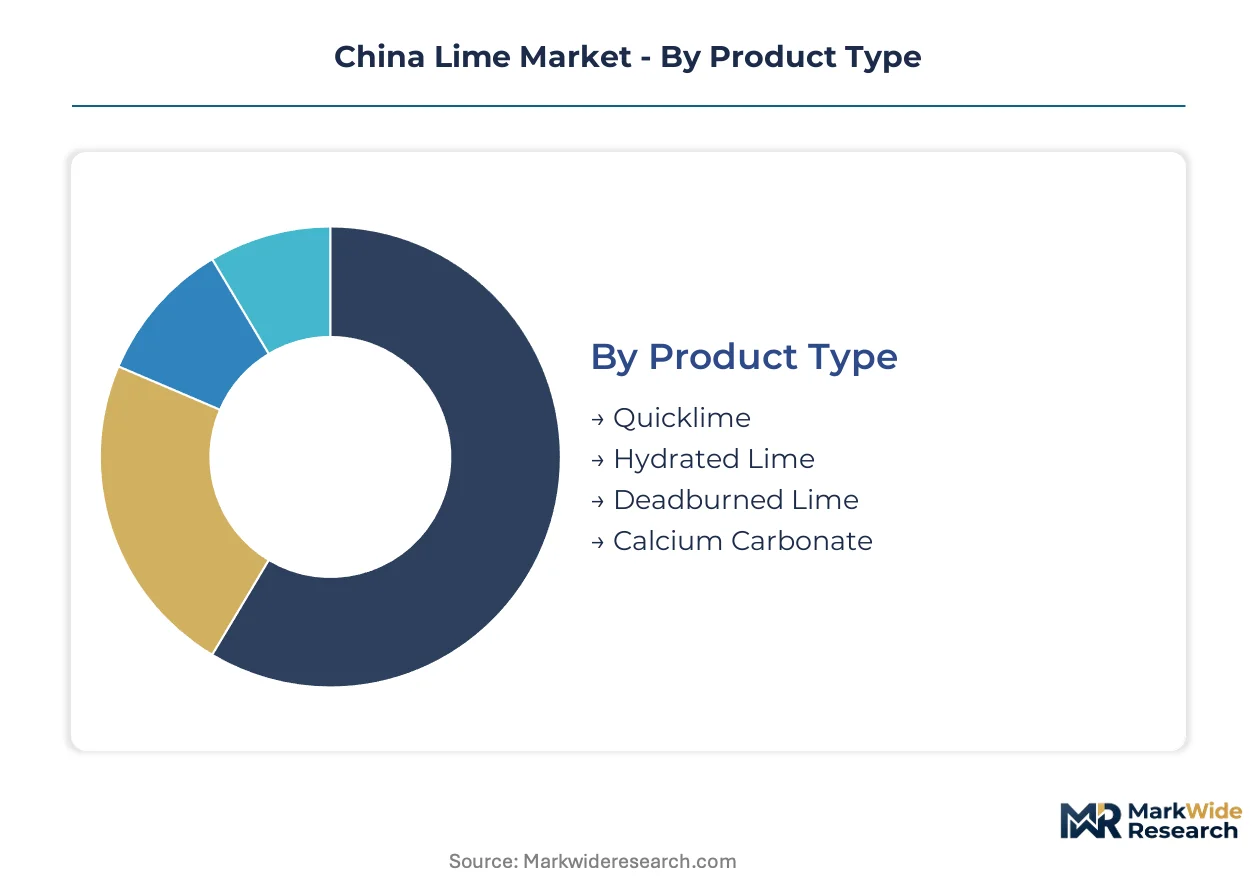
Lime market segmentation in China reveals how product specifications, application requirements, and delivery logistics interlock to shape procurement patterns. Understanding these divisions helps suppliers align kiln output with the diverging purity, reactivity, and packaging demands of steel mills, water treatment facilities, and construction contractors.
Product Type:
Calcination temperature and reactivity index differentiate product grades across China's kiln network.
- Quicklime:Calcium oxide produced at 900-1200°C with high available lime index serves construction soil stabilization and steel fluxing. GB 1594-2017 CaO thresholds are filtering substandard output in Shandong, concentrating compliant supply among Anhui quarry-integrated operators.
- Hydrated Lime:Calcium hydroxide formed through controlled slaking offers superior handling safety and precise pH control. Municipal water treatment plants in Jiangsu and Zhejiang are displacing alum with hydrated lime systems as phosphate precipitation regulations tighten.
- Deadburned Lime:High-density refractory-grade material calcined above 1400°C for extended periods. Steel ladles and cement kilns in Hebei source this for lining durability under thermal shock.
- Calcium Carbonate:Ground limestone and precipitated variants serve filler applications in plastics and paper. Guangxi deposits feed coastal chemical processors with high-purity feedstock.
Mature deployment sits with Quicklime in traditional construction. Newer deployment is concentrated in Hydrated Lime as environmental compliance tightens across eastern provinces.
Application:
End-use specifications drive diverging purity requirements and procurement contract structures.
- Construction:Soil stabilization, masonry mortar, and plaster applications demand consistent slaking rates. Yangtze River Delta infrastructure projects are consolidating supply around GB-certified producers with verified batch consistency.
- Water Treatment:Phosphate precipitation and pH adjustment in municipal plants require low-magnesium hydrated lime. Eastern province facilities are expanding lime procurement as discharge standards tighten.
- Steel Manufacturing:Fluxing and desulfurization operations consume metallurgical-grade quicklime with specified reactivity. Hebei steel mills are prioritizing Tangshan-area suppliers to shorten haul distances.
- Agriculture:Soil pH correction and animal feed supplements utilize lower-specification grades. Anhui and Henan farming cooperatives source from regional kilns with flexible batch sizing.
Volume concentration rests with Construction. Steepest expansion trajectory belongs to Water Treatment as inland municipalities upgrade facilities.
End User:
Customer scale and technical sophistication shape contract terms and delivery modalities.
- Construction Industry:Contractors and ready-mix operators purchase bulk quicklime for soil stabilization. Large state-owned developers in the Pearl River Delta negotiate annual contracts with price-adjustment clauses tied to energy input costs.
- Municipalities:Water treatment departments procure hydrated lime through centralized procurement platforms. Jiangsu municipal networks are standardizing three-year supply agreements with certified suppliers.
- Chemical Plants:Synthesis operations in Nanjing and Ningbo require high-purity grades with documented impurity profiles. These buyers conduct supplier audits and demand MEE-verified carbon data.
- Food Processing:Sugar refining and food-grade applications require SAMR-licensed production with strict heavy metal limits. Guangxi and Yunnan processors source from designated food-grade kilns with dedicated logistics.
Procurement standardization advances fastest among Municipalities. Custom technical requirements remain most pronounced with Chemical Plants.
Packaging Type:
Logistics configuration determines market access for small-batch buyers versus bulk consumers.
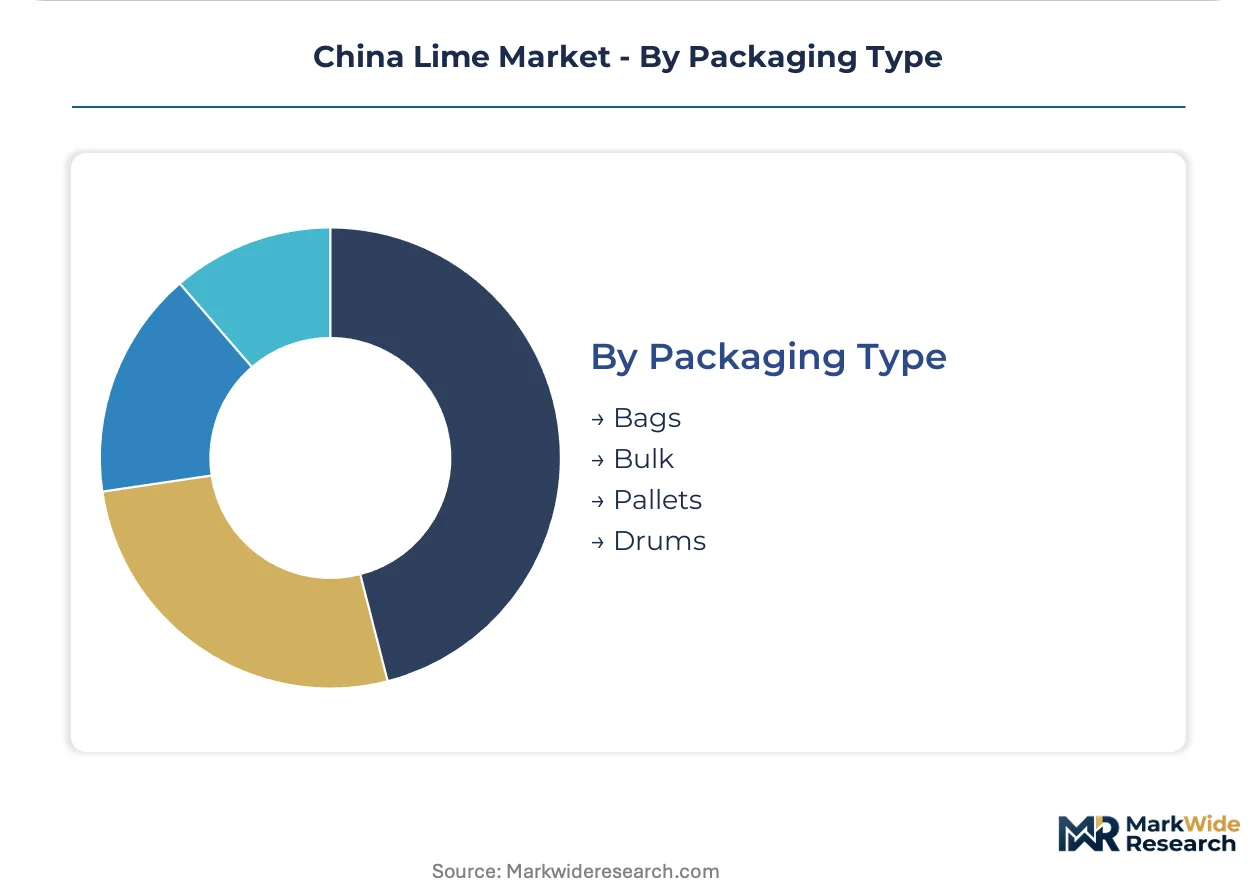
- Bags:25-50kg woven polypropylene units serve small contractors and rural agricultural users. Modular bulk-to-bag repackaging near consumption clusters is shortening lead times in the Pearl River Delta.
- Bulk:Pneumatic tanker delivery dominates steel mill and large water treatment procurement. Hebei steel belt operations receive dedicated bulk shipments from Tangshan-area kilns.
- Pallets:Unitized loads facilitate warehouse handling for mid-scale chemical synthesis customers. Zhejiang specialty chemical plants favor palletized hydrated lime for inventory efficiency.
- Drums:Sealed steel containers protect high-reactivity grades from moisture during extended storage. Food processing and pharmaceutical applications in Jiangsu specify drum packaging for contamination control.
Cost efficiency peaks with Bulk for large consumers. Flexibility premium attaches to Bags for fragmented downstream demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta Economic Zone concentrates China's lime demand through its dense clustering of steel mills, chemical plants, and municipal water treatment facilities. Provincial carbon intensity benchmarks are redrawing supply balances as kiln operators face retrofit pressures across eastern industrial corridors.
Hebei Province
Steel desulfurization operations in Tangshan and Handan consume metallurgical-grade quicklime at scale. MEE provincial branches enforce flue gas treatment rates that pull hydrated lime directly into mill procurement schedules. Tangshan-area kilns compete on haul distance advantages to the steel belt.
Shandong Province
Construction-grade quicklime output faces the steepest GB 1594-2017 recertification timeline as SAMR accelerates spot-check protocols. Zibo's refractory maintenance technician pools are aging, constraining capacity expansion for high-temperature kiln operations. Coastal chemical plants here source limestone from distant Anhui quarries at haul-cost disadvantage.
Anhui Province
High-calcium limestone deposits anchor integrated quarry-to-kiln operations with captive feedstock control. Conch Cement leverages this upstream position to sustain cost leadership in quicklime supply across eastern markets. The province's western corridor remains underpenetrated by hydrated lime suppliers as phosphate regulations migrate inland.
Jiangsu Province
Municipal water treatment networks in Nanjing and Suzhou are standardizing three-year supply agreements through centralized procurement platforms. Phosphate precipitation regulations displace alum-based treatments with hydrated lime systems. Bulk procurement consortia aggregate volume from smaller facilities and negotiate directly with quarry-integrated suppliers.
Sichuan-Chongqing Region
Municipal water networks in Chengdu and Chongqing offer first-mover positioning for hydrated lime suppliers as environmental compliance tightens inland. Provincial carbon quotas pressure kiln operators toward waste-derived fuel blending and biomass co-firing retrofits. Vertical shaft upgrades here unlock green financing from state development banks.
China Lime Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across China's lime landscape. The market structure tilts toward consolidation as carbon intensity benchmarks and GB purity mandates filter out substandard operators. Three archetypes dominate: integrated limestone-to-lime producers with captive quarry access, regional kiln operators competing on proximity to industrial clusters, and cement majors leveraging by-product lime streams. Dominant competitive moves include vertical shaft retrofits for emission compliance and long-term offtake agreements displacing spot-market purchases.
Among cement-sector conglomerates with lime exposure, Anhui Conch Cement and China National Building Material exemplify the integrated archetype through quarry-captive supply structures. Tangshan Jidong Cement occupies a position within the proximity-competitive tier, anchoring supply relationships through haul-distance advantages to Hebei's steel belt. These three entities represent how scale, integration depth, and geographic positioning stratify competitive advantage under tightening environmental enforcement.
| Leading Market Players |
|---|
| Anhui Conch Cement |
| China National Building Material (CNBM) |
| Tangshan Jidong Cement |
| Shandong Shanshui Cement Group |
| Taiheiyo Cement Corporation |
| Ube Material Industries |
| Lhoist Group |
| Carmeuse |
| Graymont Limited |
| Others |
Value Chain & Pricing Dynamics
Refractory maintenance technician pools in Tangshan and Zibo anchor labor-cost differentials that widen pricing-tier spreads between premium kiln operators and mid-scale competitors facing 18-24 month retrofit payback periods.
Pricing Analysis
Short lead-time premiums command pricing power for bagged hydrated lime near Pearl River Delta consumption clusters, while bulk spot inventory trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates GB-certified construction-grade quicklime from metallurgical-grade fluxing material and agricultural lime. Price differentiation hinges on CaO purity thresholds and MEE-verified carbon data. Cost compression in standard-tier construction lime is intensifying because Shandong kilns face accelerated recertification timelines. Small-batch chemical synthesis buyers show highest price sensitivity; steel mills with dedicated bulk contracts show lowest.
Supply Chain Analysis
Returns and refurbishment flows are minimal in lime supply chains, though refractory lining replacement cycles in high-temperature kilns create aftermarket service revenue streams. Geographic supply concentrates in Anhui, Guangxi, and Hebei provinces. Raw material dependencies center on high-calcium limestone deposits, metallurgical coke from Shanxi, and pulverized coal. Single-source vulnerability sits with captive quarry access—coastal chemical plants without backward integration face haul-cost disadvantages. Distribution runs through pneumatic tanker networks for bulk steel mill delivery and modular bulk-to-bag repackaging stations for fragmented downstream demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's lime market functions as a cost-of-compliance story where GB 1594-2017 purity mandates and provincial carbon intensity benchmarks erect barrier-to-entry moats favoring integrated quarry-captive operators with state-backed credit access.
For Market Incumbents: Hedge against refractory skill scarcity by locking long-term technician training partnerships with Zibo vocational institutes before aging pools retire. Secure captive limestone reserves in Anhui and Guangxi to defend margin position against energy cost volatility. Prioritize vertical shaft retrofits with waste-heat recovery systems to meet MEE carbon quotas and unlock green financing. For New Entrants and Emerging Players: Digital procurement platforms for municipal water treatment consortia offer low-friction entry into Jiangsu and Zhejiang three-year contract pipelines. Target Sichuan-Chongqing western corridor for hydrated lime first-mover positioning as phosphate regulations migrate inland. Lead with bagged distribution innovation near mid-scale chemical synthesis clusters to bypass incumbent bulk infrastructure. For Investors and Strategic Acquirers: The window for entry favors integrated limestone-to-lime producers with verified MEE carbon profiles and provincial trading subsidiary networks. Mid-scale operators with state-backed credit lines and pending vertical shaft upgrades represent prime acquisition archetypes. Monitor provincial carbon quota enforcement intensity as inflection indicator for kiln economics compression.| Strategic Initiative | Industry Significance |
|---|---|
| Vertical Shaft Retrofit with Waste-Heat Recovery | MEE carbon quota compliance unlocks green financing from state development banks. |
| Captive Limestone Quarry Acquisition | Anhui and Guangxi deposit control eliminates haul-cost disadvantages for coastal supply. |
| Long-Term Offtake Agreement with Steel Mills | Tangshan-area procurement contracts displace spot-market exposure for metallurgical-grade output. |
| Modular Bulk-to-Bag Repackaging Network | Pearl River Delta stations shorten lead times for small-batch chemical synthesis customers. |
| Alternative Fuel Blending Certification | Waste-derived fuel and biomass co-firing align with provincial dual carbon enforcement. |
Study Parameters
Document review covered customs/trade data, SAMR regulatory filings, and provincial MEE enforcement protocols, complemented by interviews with kiln operations managers, steel mill procurement leads, municipal water treatment directors, and refractory maintenance technicians. Secondary validation drew from China Cement Association statistics, SEC filings of listed building materials conglomerates, and energy input cost indices from Shanxi coal markets. Bottom-up volume modeling triangulated against top-down industry association aggregates.
Cross-referencing historical production data against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type (quicklime, hydrated lime, deadburned lime), application (construction, water treatment, steel manufacturing), and packaging format (bulk, bagged, palletized). CAGRs were derived from regression analysis of input cost trajectories and demand elasticity by end-use sector. Forecast inputs incorporated provincial carbon quota enforcement schedules and GB standards revision timelines.
The model holds under steady dual carbon policy implementation; deviation in MEE enforcement intensity or limestone feedstock cost spikes would shift regional supply balances. Forecasts reflect assumptions about kiln retrofit completion rates and municipal procurement platform standardization. Practitioners should monitor provincial carbon benchmark tightening and phosphate regulation migration inland for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Carbonate Market
Bulk Chemicals
Styrene Market
Bulk Chemicals
Global Butyric Acid Market
Bulk Chemicals
Global Silica Flour Market
Bulk Chemicals
Isovaleryl Chloride Market
Bulk Chemicals
Global Lithium Fluoride Market
Bulk Chemicals
Manganese Sulfate Market
Bulk Chemicals
Mangiferin Market
Bulk Chemicals
Sheet Molding and Bulk Molding Compounds Market
Bulk Chemicals
Potassium Cryolite Market
Bulk Chemicals
Magnesium Lactate Market
Bulk Chemicals
Middle-East and Africa Carbon Black Market
Bulk Chemicals
North America Paraffin Wax and Emulsions Market
Bulk Chemicals
North America Lactic Acid Market
Bulk Chemicals
DL-Methionine Market
Bulk Chemicals
Global Sodium Percarbonate Market