
 Lactic Acid Market | 2026-2036
Lactic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Lactic Acid Market Intelligence
China's fermentation corridor is fragmenting as new biorefinery projects come online across Shandong and Henan provinces. Jungbunzlauer Suisse AG leverages its Swiss fermentation expertise to sustain premium positioning in pharmaceutical-grade supply. Henan Jindan Lactic Acid Technology Co., Ltd. anchors cost-competitive volume production through integrated corn starch processing. Corbion N.V. differentiates via microbial strain optimization and food safety certifications.
Lactic acid is a chiral hydroxycarboxylic acid produced through carbohydrate fermentation or chemical synthesis, existing as L-enantiomer, D-enantiomer, or racemic DL mixtures with purity grades ranging from technical to food and pharmaceutical specifications. The compound functions primarily as a pH regulator, preservative, and chemical building block for polylactic acid biopolymer production. L-Lactic Acid dominates commercial volumes due to metabolic compatibility and established downstream processing infrastructure. Bioplastics applications represent the fastest-expanding demand pool as polylactic acid displaces conventional petroleum-derived packaging materials. Food & Beverage maintains mature, high-margin positions in preservation and flavoring segments where acidulant grade certifications command pricing premiums.
FDA food additive regulations and EPA biobased product standards shape North American market access requirements for fermentation-derived material. REACH registration and EFSA food additive evaluations govern European commercialization pathways, with purity thresholds rising under the EU Green Deal sustainable chemistry framework. China's SAMR food safety standards and GB quality specifications define import and domestic production compliance. Stakeholders must monitor evolving biopolymer feedstock certification schemes and regional carbon accounting rules that will determine cost-competitive positioning across fermentation and synthetic production routes.
Market Dynamics
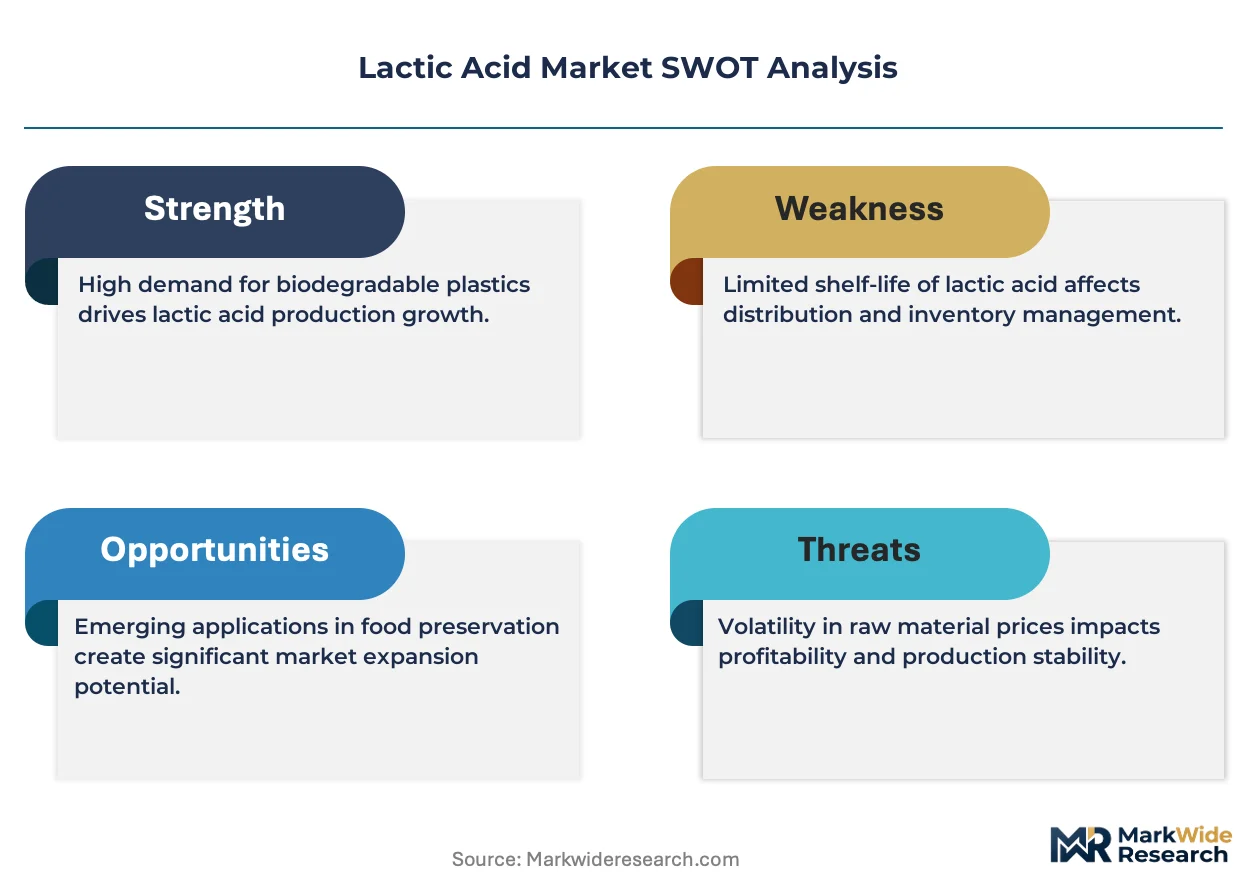
Bioplastics manufacturers are pulling fermentation-grade lactic acid volumes away from traditional food preservative channels, creating supply allocation tension between polymer feedstock and acidulant markets.
Growth Catalysts
- EU Green Deal chemistry mandates:REACH registration requirements for sustainable feedstocks are accelerating polylactic acid adoption across European packaging converters.
- Corn starch processing clusters:Integrated biorefinery corridors in Henan and Shandong provinces are expanding fermentation capacity to serve regional biopolymer demand.
- Food safety certification premiums:SAMR and FDA food additive standards are widening price spreads between technical and pharmaceutical-grade material.
Market Restraints
- Feedstock cost volatility:Corn and sugarcane molasses prices fluctuate with agricultural commodity cycles, squeezing fermentation margins during harvest shortages.
- Pharmaceutical-grade supply concentration:Swiss and Dutch fermentation specialists control high-purity L-enantiomer production, limiting buyer negotiation leverage.
- Petrochemical substitution persistence:Conventional polyethylene terephthalate retains cost advantages in cold-chain packaging applications.
Strategic Opportunities
- India's bioplastic feedstock gap:BIS standards for biodegradable packaging are creating import demand for fermentation-grade material ahead of domestic capacity buildout.
- Carbon accounting integration:EU Green Deal carbon border adjustments will reward fermentation-derived lactic acid with lifecycle certification advantages.
- 3D printing resin formulations:Photopolymerizable lactic acid derivatives are opening additive manufacturing channels for medical device prototyping.
Industry Challenges
- Pharmaceutical-grade validation timelines:EMA and FDA compliance documentation requires 18-24 month approval cycles for new fermentation facilities.
- Microbial strain IP complexity:Proprietary lactobacillus and bacillus coagulans licenses create barriers to process optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactic Acid Market |
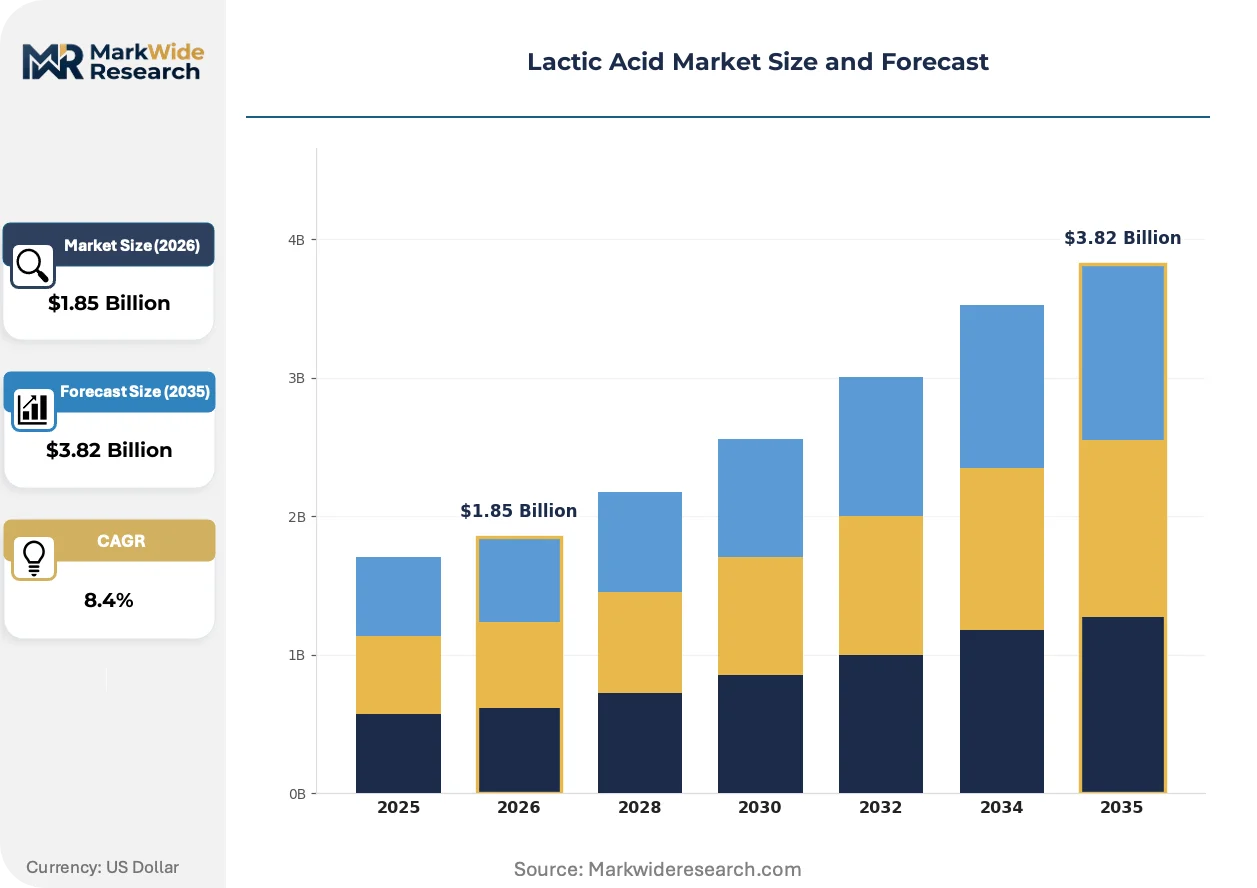
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: L-Lactic Acid, D-Lactic Acid, DL-Lactic Acid, Lactic Acid Derivatives Application: Food & Beverage, Pharmaceuticals, Cosmetics, Bioplastics End User: Food Manufacturers, Pharmaceutical Companies, Personal Care Brands, Plastic Manufacturers Form: Liquid, Powder, Granular, Crystalline |
| Companies Covered | Jungbunzlauer Suisse AG, Henan Jindan Lactic Acid Technology Co., Ltd., Corbion N.V., BASF SE, NatureWorks LLC, Cargill Incorporated, Futerro, Musashino Chemical (China) Co., Ltd., Galactic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactic Acid Market Strategic Shifts & Innovations
Fermentation process intensification and regulatory carbon accounting are compressing the cost gap between biobased and synthetic production routes. These forces are reshaping competitive positioning across purity grades.
Continuous fermentation systems with cell retention technology are rendering obsolete batch-wise stirred-tank operations. Biopolymer producers in China and Thailand are retrofitting plants to reduce downtime and contamination risk. The shift is compressing capital recovery timelines while demanding new bioprocess engineering skill sets.
REACH registration under the EU Green Deal sustainable chemistry framework is tightening purity thresholds for food-contact applications. ECHA documentation requirements now mandate traceability from agricultural feedstock through polymer conversion. European converters are qualifying dual-source supply to mitigate registration renewal risks.
Brand-owner sustainability mandates are consolidating procurement around certified biobased material. Major food retailers are unbundling acidulant purchases from legacy chemical distributors to direct fermentation supplier contracts. The pattern is most visible in German and French private-label supply chains where packaging carbon footprints face consumer scrutiny.
Lactic Acid Market Segmentation
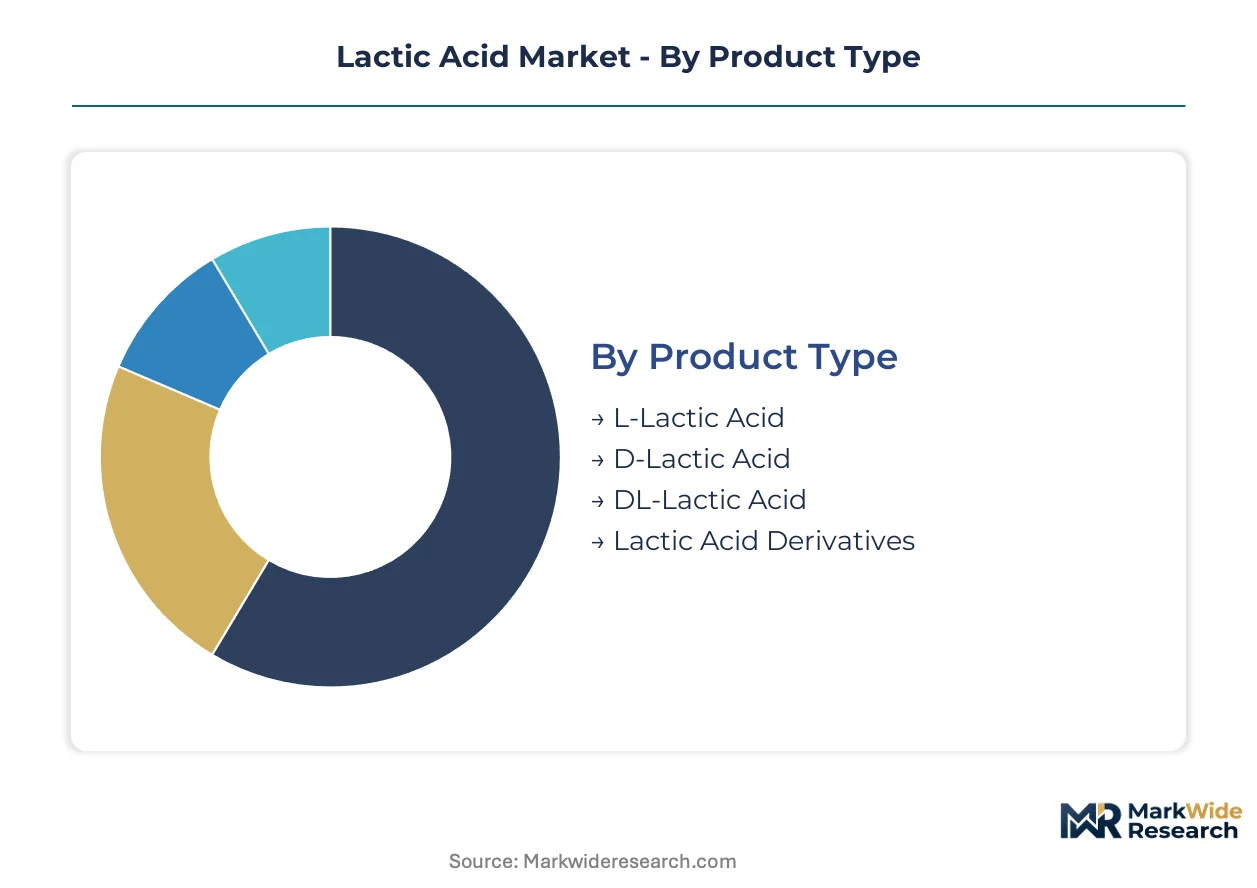
Lactic acid segmentation reflects divergent purity requirements and processing economics across end-use channels. Pharmaceutical and bioplastics applications impose distinct certification burdens that reshape supplier economics. Form and enantiomeric specifications further stratify procurement patterns among industrial buyers.
Product Type:
Mature commodity grades dominate volume flows while specialty enantiomers command premium positioning in regulated applications.
- L-Lactic Acid:The L-enantiomer constitutes the metabolic standard for human and animal physiology, with fermentation processes optimized for optical purity exceeding 99.5%. Bioplastics manufacturers in China and Thailand concentrate procurement around this grade for polylactic acid polymerization, where stereochemical regularity determines crystallinity and mechanical performance. FDA and EFSA food additive approvals lock in this isomer for acidulant applications.
- Lactic Acid Derivatives:Esterified and oligomerized variants including lactate esters and polylactic acid oligomers extend functionality into solvent, plasticizer, and reactive diluent roles. European packaging converters under EU Green Deal mandates are accelerating qualification of ethyl lactate for biodegradable coating formulations, displacing petroleum-derived glycol ethers.
- D-Lactic Acid:The D-enantiomer serves specialized pharmaceutical intermediates and niche polymer blends where controlled crystallinity is desired.
- DL-Lactic Acid:Racemic mixtures find application in technical and industrial cleaning formulations where optical purity carries no performance premium.
L-Lactic Acid handles the majority of throughput; Lactic Acid Derivatives is the fastest mover on share.
Application:
Cost tier stratification separates mature preservation markets from emerging polymer feedstock channels with divergent margin structures.
- Bioplastics:Polylactic acid production consumes fermentation-grade material at scale, with purity requirements tightening as polymer molecular weight specifications advance. Chinese converters in Zhejiang and Guangdong provinces are expanding compounding capacity to serve EU export markets under REACH-registered supply chains. The segment demands consistent lactide precursor quality that batch fermentation struggles to deliver.
- Food & Beverage:Acidulant and preservation applications leverage established GRAS and food additive regulatory pathways, with SAMR compliance in China and FDA clearance in the United States creating dual-qualification burdens for multinational suppliers. German and French retailers are unbundling procurement from chemical distributors to direct fermentation contracts with carbon footprint documentation.
- Pharmaceuticals:Injectable and parenteral formulations require USP and EP-grade material with endotoxin and heavy metal controls that Swiss and Dutch specialists dominate.
- Cosmetics:pH adjustment and humectant functions in personal care absorb technical and food-grade material with moderate purity thresholds.
Food & Beverage handles the majority of throughput; Bioplastics is climbing the fastest on share.
End User:
Customer type determines procurement sophistication, with pharmaceutical and food safety certifications creating vendor stickiness that plastic manufacturers have yet to replicate.
- Food Manufacturers:Global processors of dairy, beverages, and prepared foods specify acidulant grades with batch-level traceability from corn or sugarcane feedstock. Nestlé and Unilever sustainability procurement offices are mandating biobased content verification through ASTM D6866 testing, compressing margins for uncertified suppliers.
- Plastic Manufacturers:PLA resin producers including NatureWorks and TotalEnergies Corbion operate under long-term fermentation supply contracts with volume commitments that strain available capacity. New entrants in Thailand and Indonesia face qualification timelines that delay commercial ramp.
- Pharmaceutical Companies:Parenteral and ophthalmic formulation houses maintain qualified supplier lists with EMA and FDA drug master file dependencies that resist switching.
- Personal Care Brands:L'Oréal and Unilever cosmetic divisions source technical-grade material for pH adjustment with lower certification burdens than food or drug applications.
Food Manufacturers handles the majority of throughput; Plastic Manufacturers is expanding most quickly on share.
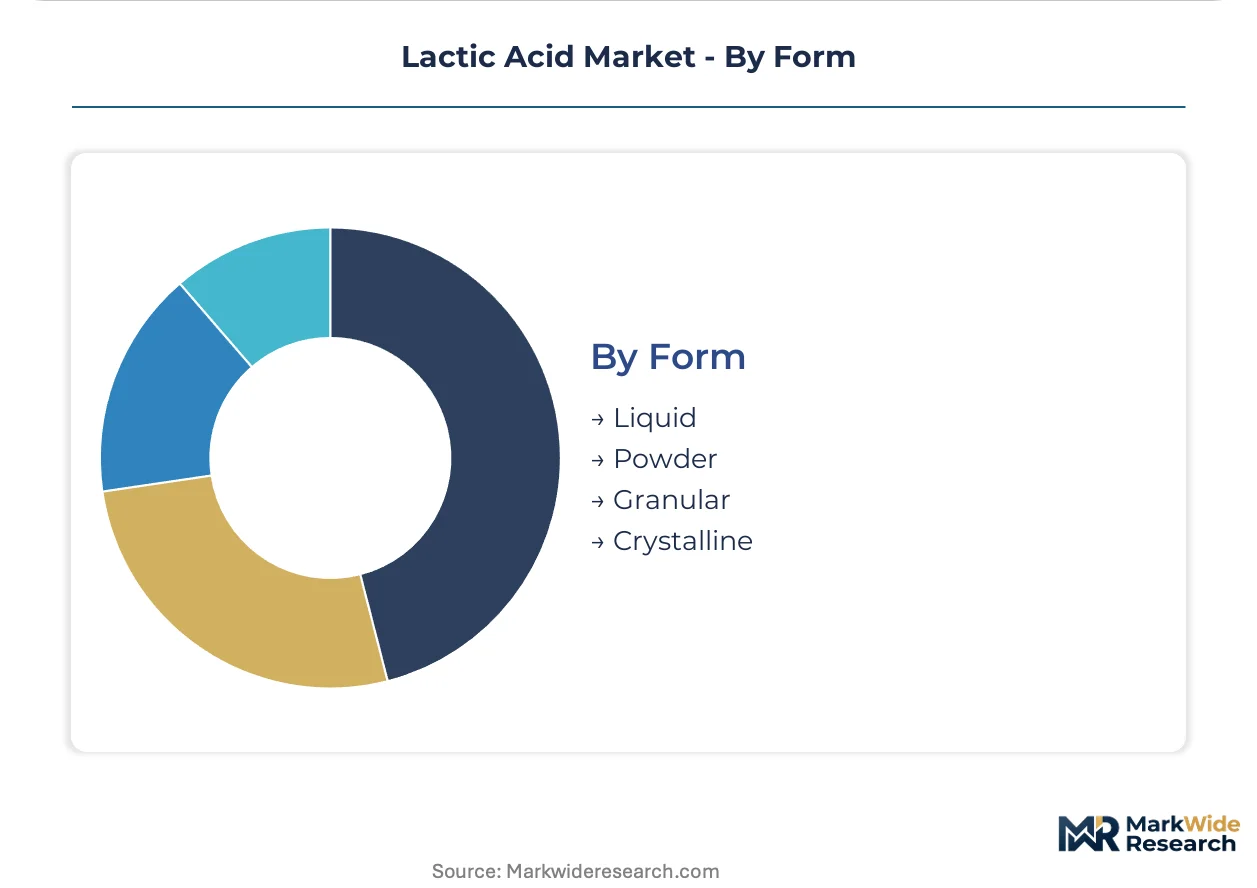
Form:
Volume scale concentrates in liquid delivery, with solid forms capturing premium positioning in logistics-constrained or formulation-specific applications.
- Liquid:Aqueous solutions at 50-88% concentration dominate bulk industrial supply, with tanker truck and ISO container logistics optimized for fermentation plant proximity. Henan and Shandong biorefineries ship liquid product to coastal PLA plants with minimal handling loss.
- Powder:Spray-dried material serves food seasoning blends and dry cosmetic formulations where moisture sensitivity demands anhydrous handling.
- Granular:Agglomerated forms improve flow properties for automated dosing in plastics compounding operations.
- Crystalline:High-purity solid lactic acid isolates serve analytical standards and specialized pharmaceutical synthesis with batch quantities.
Liquid handles the majority of throughput; Powder is gaining share fastest among solid forms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR food safety standards anchor China's dominance in fermentation-grade output, while REACH compliance and EU Green Deal mandates reshape European procurement patterns. National regulations and industrial clustering determine competitive positioning across major production zones.
China
Polylactic acid feedstock demand from Zhejiang and Guangdong converters absorbs expanding Henan and Shandong fermentation capacity. SAMR's GB standards for food additive purity create dual-qualification burdens for export-oriented suppliers. Jungbunzlauer's Swiss fermentation expertise sustains premium positioning in pharmaceutical-grade imports despite domestic volume growth.
Germany
Packaging converters under EU Green Deal chemistry mandates accelerate polylactic acid adoption for retail private-label supply chains. ECHA REACH registration requirements now mandate agricultural feedstock traceability through polymer conversion. BASF SE maintains chemical synthesis capacity for technical-grade material serving industrial cleaning formulations.
United States
FDA GRAS clearance and EPA biobased product standards shape market access for fermentation-derived acidulant grades. NatureWorks LLC's Nebraska polylactic acid complex consumes contracted fermentation volumes under long-term supply agreements. Corn belt starch processing clusters in Iowa and Illinois anchor cost-competitive feedstock integration.
Thailand
Cassava-based fermentation corridors serve regional biopolymer demand from Indonesian and Vietnamese converters. Continuous fermentation retrofits reduce downtime for plants supplying NatureWorks and TotalEnergies Corbion regional affiliates. BIS-equivalent import demand from India creates export channel opportunities ahead of domestic Indian capacity buildout.
Netherlands
Corbion N.V.'s microbial strain optimization and food safety certifications sustain pharmaceutical-grade supply dominance. EMA compliance documentation and FDA drug master file dependencies resist supplier switching for parenteral formulation houses. Rotterdam logistics hubs facilitate REACH-registered material distribution across European packaging converter networks.
Lactic Acid Market Key Industry Players
Capability concentration sits with Swiss and Dutch fermentation specialists controlling high-purity L-enantiomer production; scale advantage sits with Chinese integrated biorefineries exploiting corn starch processing clusters. The market structures around three archetypes: premium-grade pharmaceutical suppliers, cost-optimized fermentation volume producers, and chemical synthesis incumbents serving technical applications. Dominant competitive moves include capacity expansion in Shandong and Henan provinces and strategic partnerships between PLA resin producers and fermentation suppliers.
Within the premium-grade tier, Jungbunzlauer Suisse AG exemplifies Swiss fermentation expertise sustaining pharmaceutical-grade positioning. Henan Jindan Lactic Acid Technology Co., Ltd. anchors Chinese cost-competitive volume production through integrated corn starch processing. Corbion N.V. occupies a position emphasizing microbial strain optimization and food safety certifications for regulated applications.
| Leading Market Players |
|---|
| Jungbunzlauer Suisse AG |
| Henan Jindan Lactic Acid Technology Co., Ltd. |
| Corbion N.V. |
| BASF SE |
| NatureWorks LLC |
| Cargill Incorporated |
| Futerro |
| Musashino Chemical (China) Co., Ltd. |
| Galactic |
| Others |
Cost & Logistics Intelligence
Undercapacity in European pharmaceutical-grade fermentation is compressing buyer leverage while Chinese corn-starch corridors run at higher utilization, creating divergent pricing power across purity tiers and reshaping procurement geography for bioplastics feedstock.
Pricing Analysis
Price spreads between Swiss pharmaceutical-grade and Chinese technical-grade material exceed threefold, with EMA documentation and FDA drug master file dependencies sustaining premium tiers. Three-tier pricing structure across pharmaceutical, food-grade, and technical levels reflects certification burden and optical purity thresholds. Cost compression in technical grades is intensifying because Henan and Shandong biorefineries are expanding fermentation volume. Food manufacturers exhibit highest price sensitivity due to unbundled procurement and carbon-footprint documentation demands, while pharmaceutical formulators accept premiums for qualified supplier lists.
Supply Chain Analysis
Corn starch and sugarcane molasses feedstock sourcing draws from agricultural commodity markets in China, Thailand, and Brazil, tethering fermentation economics to harvest cycles and biofuel policy competition. Lactobacillus and bacillus coagulans microbial strains, plus specialized bioreactor equipment, constitute critical input dependencies. Single-source vulnerability concentrates in Swiss and Dutch high-purity L-enantiomer production, where EMA compliance documentation resists supplier switching. Distribution runs through tanker truck and ISO container logistics optimized for fermentation plant proximity, with Rotterdam and Shanghai hubs serving regional converter networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward bioplastics manufacturers as PLA resin producers consolidate procurement around long-term fermentation supply contracts with volume commitments that strain available capacity.
For Market Incumbents: Entrench pharmaceutical-grade positioning by deepening EMA and FDA drug master file portfolios before Chinese biorefineries complete pharmaceutical-grade validation timelines. Add fermentation capacity in Henan or Shandong provinces to defend cost-competitive volume share against emerging Thai and Indonesian entrants. Certification investment represents the critical lever for margin defense. For New Entrants and Emerging Players: Build out India's bioplastic feedstock supply channel ahead of domestic BIS-standard capacity buildout, targeting import demand from packaging converters under biodegradable packaging mandates. Thailand's cassava-based fermentation corridors offer the most penetrable white space for regional biopolymer supply. A go-to-market angle anchored in REACH-registered material with agricultural feedstock traceability documentation opens European converter networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Swiss and Dutch fermentation specialists with pharmaceutical-grade supply dominance and long-term qualified supplier relationships. Over the medium-term horizon, acquisition targets should display microbial strain IP portfolios and food safety certification infrastructure that resist commoditization. The signal to watch is EU Green Deal carbon border adjustment implementation timing, which would revalue fermentation-derived material with lifecycle certification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Starch Processing | Henan and Shandong biorefineries exploit integrated agricultural processing to compress fermentation feedstock costs. |
| Continuous Fermentation Retrofit | Thai and Chinese plants reduce downtime and contamination risk through cell retention technology upgrades. |
| REACH Registration Investment | European packaging converters qualify dual-source supply to mitigate ECHA documentation renewal risks. |
| Long-term Supply Agreement with PLA Producers | NatureWorks and TotalEnergies Corbion affiliates lock in fermentation volumes under volume-commitment contracts. |
| Pharmaceutical-Grade Validation Timeline Acceleration | New fermentation facilities compress EMA and FDA compliance documentation cycles to challenge Swiss-Dutch dominance. |
Research Approach
Operator-level perspectives from fermentation plant managers, bioplastics procurement leads at PLA resin producers, pharmaceutical formulation supply chain directors, and food manufacturer sustainability officers anchored the qualitative base. Primary interview insights combined with secondary validation from customs and trade data, SEC filings of listed fermentation specialists, ECHA REACH registration databases, and SAMR food additive approval records. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates across purity grades and end-use channels.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity testing around corn price volatility and EU carbon border adjustment implementation timing. Segmentation dimensions modeled include enantiomeric purity tier, application channel, end-user procurement sophistication, and regional production hub clustering. CAGRs derived from capacity expansion pipelines, qualified against historical utilization rates and polymer feedstock demand elasticity. Industry-specific forecast inputs incorporated polylactic acid resin capacity buildout schedules and pharmaceutical-grade validation timeline distributions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-backed biorefineries or accelerated pharmaceutical-grade qualification campaigns would shift outcomes beyond modeled bounds. Cross-checking against ECHA REACH registration renewal schedules and NatureWorks supply contract disclosure patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Ferrous Sulfate Market
Bulk Chemicals
ASEAN Sulfur Market
Bulk Chemicals
Caproic Acid Market
Bulk Chemicals
Malathion Market
Bulk Chemicals
Chemical Warehousing Market
Bulk Chemicals
Global Acrylate Monomers Market
Bulk Chemicals
Acetate Salt Market
Bulk Chemicals
Global Bitumen Market
Bulk Chemicals
Potassium Chloride Market
Bulk Chemicals
Europic Chloride Market
Bulk Chemicals
Precipitated Fine Hydrate Market
Bulk Chemicals
Sodium Dicyanamide Market
Bulk Chemicals
Nahcolite Market
Bulk Chemicals
Zinc Carbonate Market
Bulk Chemicals
Ammonium Thiosulfate Market
Bulk Chemicals
China Lime Market