
 Naphthalene Market | 2026-2036
Naphthalene Market Size, Share, and Industry Trends Forecast 2026-2036
Naphthalene Market Outlook
Coal tar pitch is pivoting toward higher-value naphthalene extraction as steel industry byproduct economics tighten. Rain Carbon Inc. leverages vertical integration across carbon materials and distillation assets to sustain feedstock security. JFE Chemical Corporation anchors Asian supply through captive coke oven gas processing in Japan. Koppers Inc. competes in North American refining and tar distillation, while Himadri Specialty Chemical Ltd. dominates Indian coal chemical derivatives through backward integration into carbon black and specialty oils.
Naphthalene is a bicyclic aromatic hydrocarbon (C₁₀H₈) with a melting point near 80°C, produced primarily via coal tar distillation or petroleum catalytic reforming, serving as a critical intermediate for phthalic anhydride, naphthalene sulfonates, and insecticide synthesis. Industrial grade naphthalene occupies the largest volume share due to phthalic anhydride demand for polyester and alkyd resins, while pharmaceutical grade commands premium pricing through stringent purity thresholds for sulfonamide and anthelmintic production. Powder and flake product forms lead solid handling logistics, whereas liquid naphthalene concentrates in continuous process integration at integrated chemical complexes.
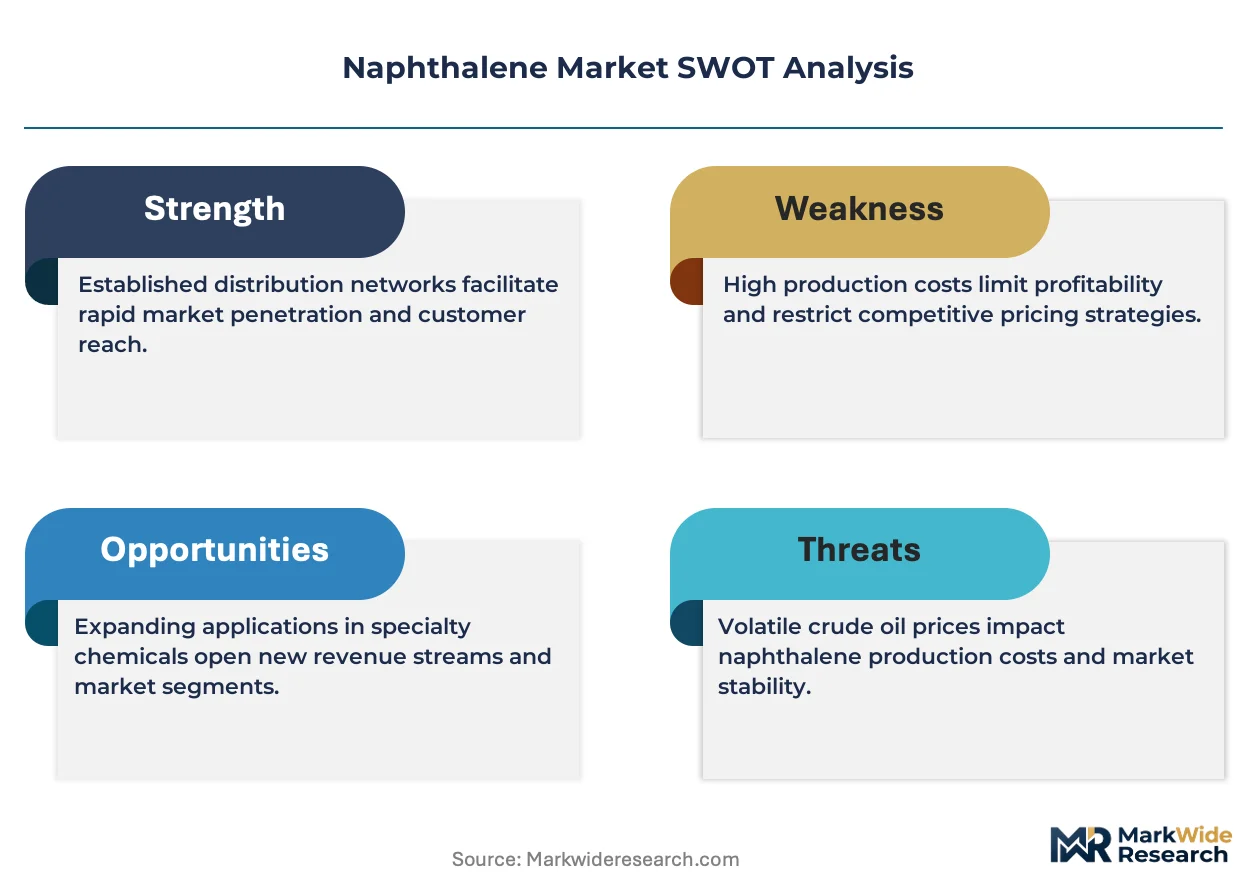
EPA hazardous air pollutant standards under the Clean Air Act and REACH Annex XVII PAH restrictions constrain emissions from tar distillation facilities, pushing producers toward closed-system recovery and refined grade certification. OSHA permissible exposure limits and EU CLPA classification requirements shape workplace handling protocols and downstream product labeling across chemicals and coatings end users. Stakeholders must monitor regulatory tightening on PAH content in consumer goods and construction materials, as this will determine which grade specifications and geographic production bases retain market access.
Market Dynamics
Coal tar distillation economics are tightening as steel industry rationalization reduces feedstock availability, forcing naphthalene producers to prioritize refined-grade output and captive coke oven gas integration over merchant market sales.
Growth Catalysts
- Phthalic anhydride demand:Polyester resin and plasticizer production in China's construction chemicals sector sustains volume offtake for industrial-grade material.
- REACH Annex XVII enforcement:European restrictions on polycyclic aromatic hydrocarbons redirect refinery-sourced naphthalene toward higher-purity grades with certified low-PAH content.
- Coal chemical clustering:Shanxi and Hebei provinces concentrate integrated carbon black, specialty oil, and naphthalene derivative capacity that lowers logistics costs.
Market Restraints
- Feedstock concentration risk:Over half of merchant naphthalene originates from Chinese coal tar distillation, creating geographic supply vulnerability.
- Petroleum-based substitution:Ortho-xylene routes to phthalic anhydride compete on price volatility during crude oil downturns.
- EPA MACT standards:Hazardous air pollutant limits on tar distillation emissions raise compliance capital intensity for US facilities.
Strategic Opportunities
- Pharmaceutical-grade certification:Sulfonamide and anthelmintic API production demands ultra-high purity thresholds that command premium pricing.
- Construction chemical additives:Naphthalene sulfonate superplasticizers penetrate Southeast Asian ready-mix concrete markets with urban infrastructure buildouts.
- Closed-system recovery technology:Vacuum distillation and solvent crystallization methods reduce yield loss and emissions simultaneously.
Industry Challenges
- Specialized process engineering talent:Coal tar fractionation and continuous naphthalene recovery require expertise scarce outside legacy steel-chemical hubs.
- Grade certification timelines:Pharmaceutical and food-grade registrations demand multi-year stability data and GMP audits that delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Naphthalene Market |
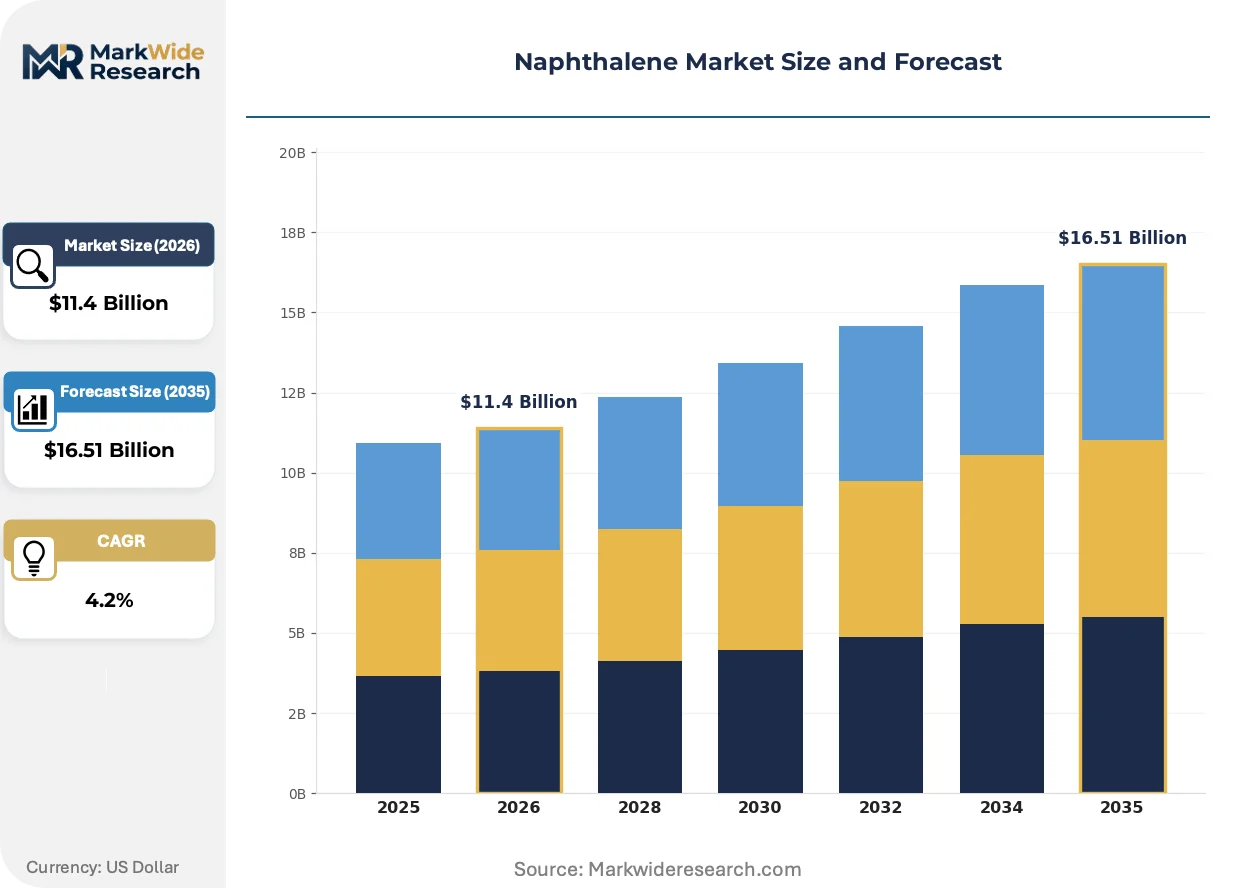
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flakes, Liquid, Granules, Powder Grade: Industrial, Reagent, Food Grade, Pharmaceutical Application: Solvent, Dye, Plastics, Coatings End User: Chemicals, Textiles, Pharmaceuticals, Paints |
| Companies Covered | Rain Carbon Inc., JFE Chemical Corporation, Koppers Inc., ExxonMobil Corporation, Himadri Specialty Chemical Ltd., China Steel Chemical, DEZA a.s., Epsilon Carbon Private Limited, PCC Rokita SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Naphthalene Market Strategic Shifts
Process intensification and regulatory stringency are compressing the viable technology set, favoring producers with integrated distillation assets and automated quality control systems over merchant traders.
Continuous catalytic hydrogenation of naphthalene to tetralin and decalin is modularizing downstream integration for specialty solvent and fuel additive producers. Japanese petrochemical complexes adopt these units to diversify from commodity phthalic anhydride exposure. The technology is modularizing what were previously batch-reactor operations into streamlined, heat-integrated process trains.
EPA's revised National Emission Standards for Hazardous Air Pollutants impose stricter benzene and naphthalene emission limits on tar storage and handling. US refiners and tar distillers must retrofit vapor recovery systems and closed-loop sampling infrastructure. The regulatory pressure is accelerating consolidation toward facilities with existing emissions control capital.
Long-term offtake contracting is displacing spot-market purchasing among European construction chemical formulators. Buyers seek supply security amid feedstock volatility and REACH compliance documentation requirements. German and Dutch distributors now structure three-year minimum-volume agreements with certified low-PAH suppliers rather than sourcing through trading houses.
Naphthalene Market Segmentation
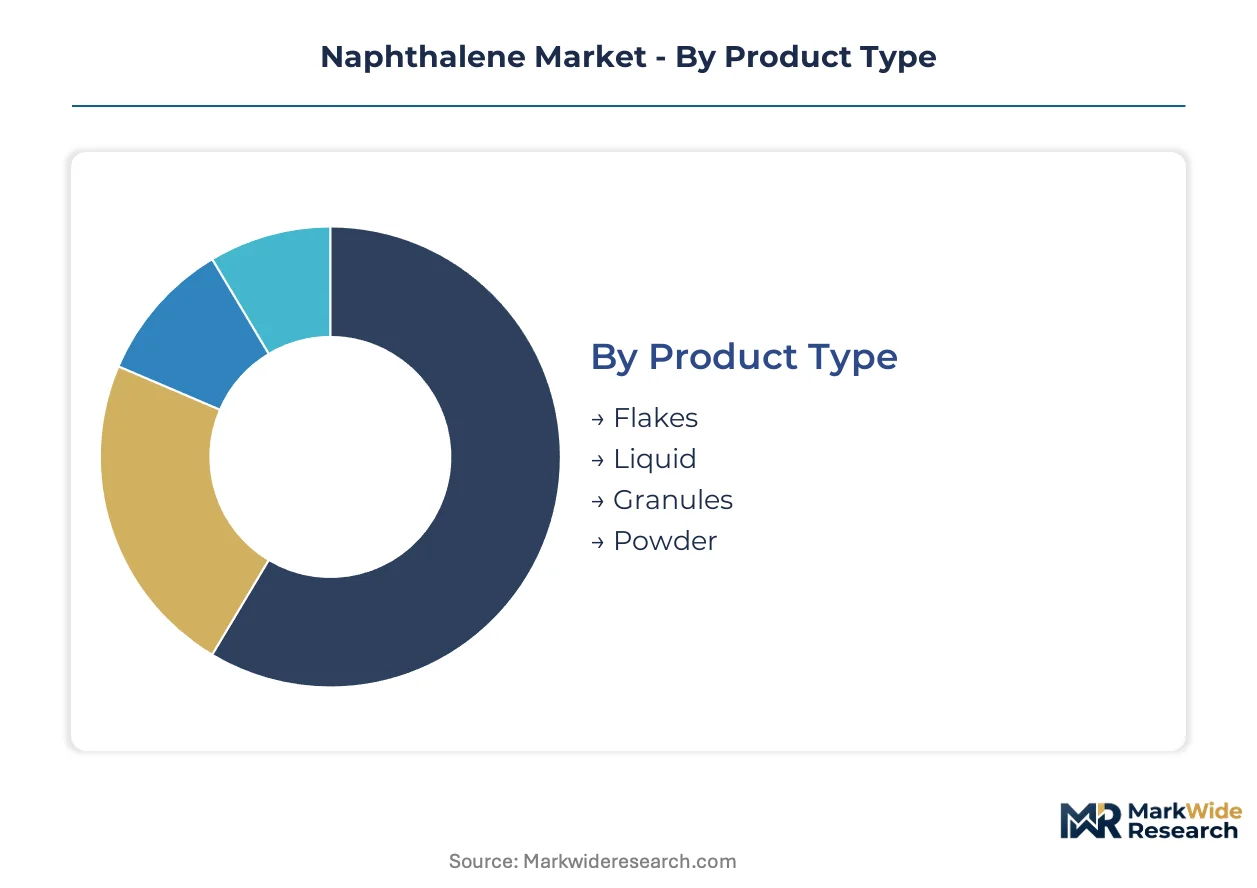
Naphthalene market segmentation reflects divergent purity requirements and handling economics across derivative chains. Grade certification and physical form selection directly determine addressable end-use markets and margin capture potential.
Product Type:
Physical form selection traces a customization-vs-standardization spectrum from bulk liquid handling to precision flake packaging for specialty applications.
- Flakes:Solidified naphthalene formed through controlled cooling and flaking drums, packaged in moisture-resistant bags for regional chemical distributors. Demand concentrates in European construction chemical formulators seeking precise dosing control for sulfonate superplasticizer synthesis, constrained by REACH documentation requirements for each batch.
- Liquid:Molten naphthalene maintained above 80°C melting point, delivered via heated tanker trucks to integrated phthalic anhydride plants. Demand concentrates in China's Shanxi and Hebei province chemical clusters where continuous process integration eliminates solidification costs, though thermal maintenance raises logistics complexity.
- Granules:Spherical particles produced through prilling or pastillation, offering reduced dust generation versus powder. Preferred by Japanese textile dye manufacturers for automated feeding systems.
- Powder:Finely milled crystalline form with high surface area, serving laboratory reagent and specialty pesticide formulation markets where rapid dissolution matters.
Leading the category by volume: Liquid. Growing fastest: Flakes.
Grade:
Margin structure follows a cost tier from commodity industrial material to certified pharmaceutical purity with multi-year registration timelines.
- Industrial:Technical-grade material with 95-98% purity, containing acceptable levels of methylnaphthalenes and sulfur compounds for phthalic anhydride catalytic oxidation. Demand concentrates in China's polyester resin sector where coal tar distillation economics favor volume over refinement, though EPA MACT compliance costs pressure US-based industrial-grade producers.
- Pharmaceutical:Ultra-high purity naphthalene meeting USP/EP monographs with stringent limits on polycyclic aromatic hydrocarbons and heavy metals. Demand concentrates in Indian API manufacturing hubs for sulfonamide and anthelmintic production, where CDSCO registration requirements and GMP certification create 18-24 month market entry barriers.
- Reagent:ACS-grade material for analytical chemistry and research applications, produced in limited batches with full traceability documentation.
- Food Grade:Refined naphthalene derivatives permitted for specific food packaging applications under FDA 21 CFR indirect food additive regulations, representing a narrow specialty niche.
Industrial grade dominates tonnage. Pharmaceutical commands the steepest expansion trajectory.
Application:
Application segmentation maps to maturity stages across naphthalene's derivative chemistry evolution.
- Plastics:Phthalic anhydride precursor for polyester resins, plasticizers, and alkyd coatings, representing the foundational demand anchor. Concentrated in Chinese construction chemicals and automotive coatings sectors.
- Solvent:Direct use as dye carrier and chemical synthesis medium, particularly in Japanese textile processing. Facing substitution pressure from less regulated alternatives.
- Dye:Intermediate for azo and vat dye synthesis, with demand tied to Indian and Bangladeshi textile export markets.
- Coatings:Alkyd resin component for architectural and industrial paints, tracking construction activity cycles in Southeast Asian urbanization corridors.
Plastics application leads volume. Coatings shows strongest momentum.
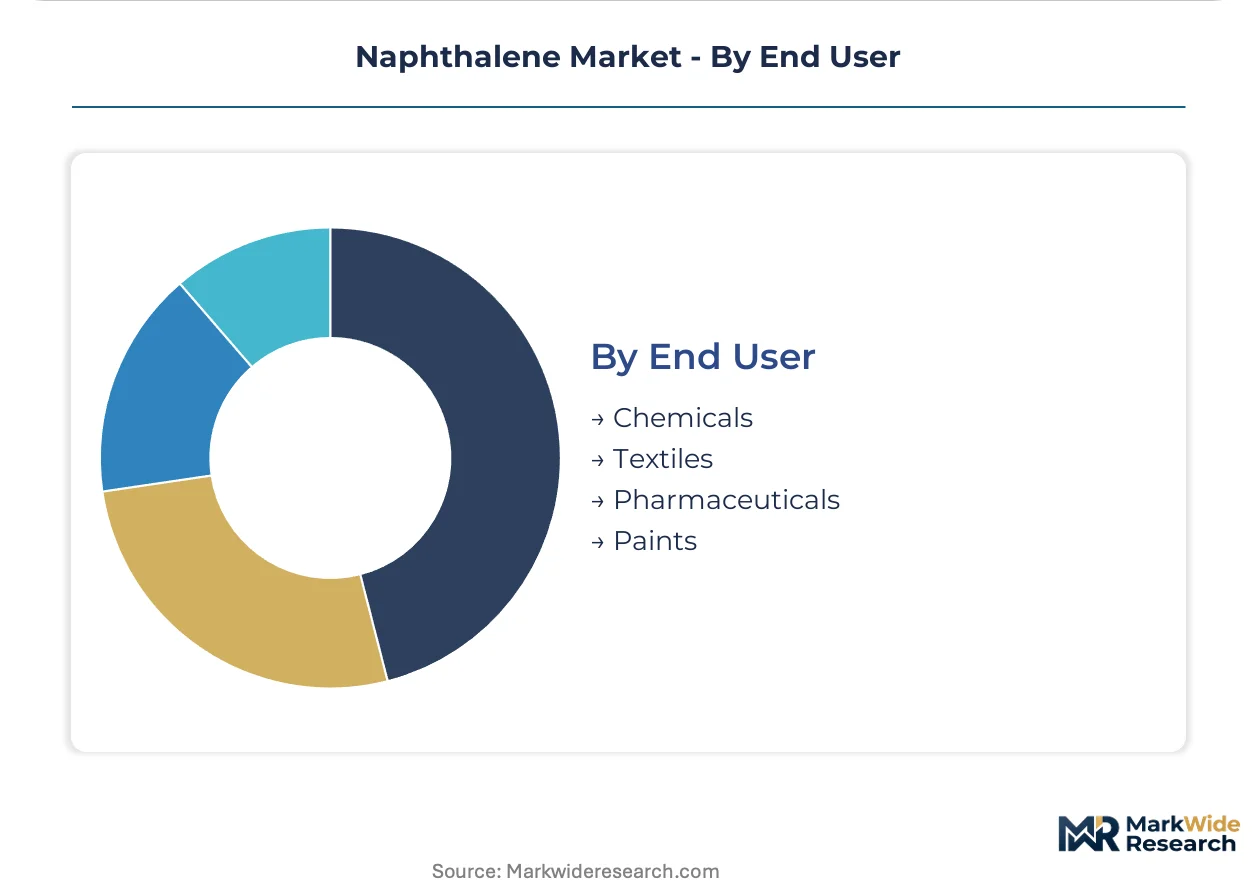
End User:
End-user concentration reflects supply chain proximity to coal tar distillation assets versus refined chemical processing capabilities.
- Chemicals:Integrated producers of phthalic anhydride, naphthalene sulfonates, and specialty derivatives, absorbing majority of merchant naphthalene supply. Clustered near coke oven operations in China, Japan, and India.
- Pharmaceuticals:API manufacturers requiring certified low-PAH material with full regulatory documentation. European EMA and US FDA inspection regimes favor established suppliers with validated quality systems.
- Textiles:Dye houses and finishing operations, primarily in South Asian export manufacturing zones.
- Paints:Coating formulators purchasing naphthalene-derived alkyd resins rather than direct naphthalene, representing indirect offtake.
Chemical sector consumes the largest share. Pharmaceutical end-use climbs fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanxi and Hebei provinces operate as China's coal chemical special economic zones, concentrating integrated carbon black, specialty oil, and naphthalene derivative capacity that lowers logistics costs and anchors regional supply security.
China
Coal tar distillation capacity in Shanxi and Hebei provinces supplies dominant phthalic anhydride and naphthalene sulfonate output for construction chemicals. MEE emissions standards under dual carbon goals constrain new coke oven investments. Tianjin and Tangshan chemical clusters concentrate backward-integrated producers with captive coke oven gas processing.
United States
Refinery-sourced naphthalene faces EPA MACT standards for hazardous air pollutants that raise compliance capital intensity. OSHA permissible exposure limits shape workplace handling protocols across Gulf Coast chemical complexes. Texas and Louisiana refining corridors retrofit vapor recovery systems to meet revised benzene and naphthalene emission limits.
Germany
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons redirect naphthalene toward higher-purity grades with certified low-PAH content. ECHA classification requirements drive downstream product labeling across chemicals and coatings end users. Leverkusen and Ludwigshafen chemical parks concentrate phthalic anhydride producers with integrated emissions control infrastructure.
India
API manufacturing hubs in Maharashtra and Gujarat demand pharmaceutical-grade naphthalene for sulfonamide and anthelmintic production. CDSCO registration requirements and GMP certification create 18-24 month market entry barriers for new suppliers. Himadri Specialty Chemical anchors supply through backward integration into carbon black and specialty oils from West Bengal operations.
Japan
PETROCHEMICAL complexes adopt continuous catalytic hydrogenation to diversify from commodity phthalic anhydride exposure. METI industrial policy supports modular process intensification for tetralin and decalin specialty solvents. Chiba and Yokkaichi refining corridors concentrate JFE Chemical Corporation's captive coke oven gas processing capacity.
Naphthalene Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated coal tar distillers commanding feedstock security while merchant traders face margin compression from regulatory compliance costs. The vendor base concentrates around steel-chemical legacy hubs where coke oven gas access creates natural moats. Three archetypes dominate: captive coke oven operators with upstream control, refinery-integrated petrochemical producers, and specialty chemical pure-plays with pharmaceutical-grade certification. Capacity consolidation and emissions control retrofitting represent the dominant competitive moves as EPA and MEE standards tighten.
Among North American refining and tar distillation operators, Koppers Inc. occupies a position exemplifying integrated carbon materials capability, while Rain Carbon Inc. represents vertical integration across distillation assets and feedstock security. JFE Chemical Corporation anchors Asian supply archetypes through Japanese coke oven gas processing. Himadri Specialty Chemical Ltd. exemplifies Indian backward integration into carbon black and specialty oils. DEZA a.s. and PCC Rokita SA represent European specialist positions within Central European chemical corridors.
| Leading Market Players |
|---|
| Rain Carbon Inc. |
| JFE Chemical Corporation |
| Koppers Inc. |
| ExxonMobil Corporation |
| Himadri Specialty Chemical Ltd. |
| China Steel Chemical |
| DEZA a.s. |
| Epsilon Carbon Private Limited |
| PCC Rokita SA |
| Others |
Value Chain & Pricing Dynamics
REACH Annex XVII enforcement on polycyclic aromatic hydrocarbons compels European construction chemical formulators to demand certified low-PAH naphthalene with full batch documentation, forcing suppliers to invest in closed-system recovery and solvent crystallization capacity that compresses margins on industrial-grade material.
Pricing Analysis
Short lead-time premiums dominate spot transactions as German and Dutch distributors abandon trading-house sourcing for three-year minimum-volume agreements with certified suppliers. Three-tier pricing structure across pharmaceutical, industrial, and reagent grades separates margin capture potential, with pharmaceutical-grade commanding substantial premia due to 18-24 month CDSCO and FDA registration timelines. Cost compression in industrial-grade material is intensifying because ortho-xylene substitution routes to phthalic anhydride compete aggressively during crude oil downturns. Chinese polyester resin producers exhibit highest price sensitivity, while Indian API manufacturers demonstrate lowest sensitivity due to regulatory lock-in with validated suppliers.
Supply Chain Analysis
Returns and off-specification material flows from pharmaceutical-grade production are reprocessed into industrial-grade feedstock, minimizing yield loss at integrated Shanxi and Hebei chemical clusters. Raw material sourcing draws from Chinese coal tar distillation, Japanese coke oven gas processing, and US refinery catalytic reforming streams. Feedstock dependency rests on methylnaphthalene separation efficiency and sulfur compound removal capacity. Single-source vulnerability concentrates in Chinese merchant supply, which provides over half of globally traded volume. Distribution runs through heated tanker logistics for molten material and moisture-resistant bagging for flaked product to regional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA MACT standards and REACH Annex XVII compliance costs function as structural moats, elevating capital requirements for tar distillation emissions control and pharmaceutical-grade certification that deter undercapitalized entrants.
For Market Incumbents: Hedge against ortho-xylene substitution threats by deepening captive coke oven gas integration in Shanxi and Hebei provinces, while accelerating vacuum distillation retrofitting to defend margin position under tightening EPA benzene emission limits. Prioritize pharmaceutical-grade certification investments to capture sulfonamide API demand premia. For New Entrants and Emerging Players: European construction chemical distributors represent the most accessible channel partners for certified low-PAH flake supply, given their displacement of spot-market purchasing with long-term contracting. Target Southeast Asian ready-mix concrete markets for naphthalene sulfonate superplasticizer penetration, leveraging urban infrastructure buildouts as the go-to-market anchor. For Investors and Strategic Acquirers: The window for entry favors integrated coal tar distillers with existing emissions control infrastructure and validated quality systems. Five-to-ten year viability hinges on feedstock security through steel-chemical legacy hub proximity. Monitor EPA MACT enforcement intensity as the inflection signal for US facility consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Shanxi province chemical clusters add closed-system recovery units to meet MEE emissions standards. |
| Backward Integration | Captive coke oven gas processing secures feedstock against steel industry rationalization. |
| Green Manufacturing Transition | Solvent crystallization methods reduce PAH emissions while improving pharmaceutical-grade yields. |
| Long-term Supply Agreement | German distributors structure three-year contracts to secure REACH-compliant documentation. |
| Joint Venture | Japanese petrochemical complexes partner for modular tetralin and decalin hydrogenation units. |
Study Parameters
Document review covered EPA enforcement actions, ECHA classification updates, CDSCO registration databases, and ACC trade statistics, complemented by interviews with coal tar distillation plant managers, phthalic anhydride procurement leads at Chinese construction chemical producers, REACH compliance officers at European distributors, and pharmaceutical API manufacturing quality directors. Secondary validation drew from customs/trade data, SEC 10-K filings of listed carbon material producers, and MEE emissions disclosure reports. Bottom-up capacity modeling and top-down demand triangulation anchored volume and value estimates.
Segment-level projections across grade tier, physical form, end-use industry, and regional production hub were generated through the analytical framework. CAGRs were derived from elasticity-adjusted demand curves and capacity utilization trajectories. Key forecast inputs included coke oven investment cycles under China's dual carbon goals and ortho-xylene price volatility coefficients.
Caveats apply where MEE enforcement intensity, EPA MACT retrofitting timelines, or REACH Annex XVII scope expansion could materially shift the outlook. Forecasts reflect assumptions on steel industry byproduct economics and coal tar distillation capacity persistence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sodium Permanganate Market
Bulk Chemicals
Magnesium Carbonate Market
Bulk Chemicals
Lignin Waste Market
Bulk Chemicals
Global Bitumen Market
Bulk Chemicals
Bromacil Market
Bulk Chemicals
Global Quinine Sulphate Market
Bulk Chemicals
India Iodine Market
Bulk Chemicals
Sodium Metasilicate Pentahydrate Market
Bulk Chemicals
Dithiocarbamates Market
Bulk Chemicals
Caproic Acid Market
Bulk Chemicals
Potassium Sulphate Market
Bulk Chemicals
India Chlorine Market
Bulk Chemicals
Muconic Acid Market
Bulk Chemicals
Global Chlorinated Paraffin Wax Market
Bulk Chemicals
Activated Bleaching Earth Market
Bulk Chemicals
Iodine Market