
 Precipitated Barium Sulphate Market | 2026-2036
Precipitated Barium Sulphate Market Size, Share, and Industry Trends Forecast 2026-2036
Precipitated Barium Sulphate Market Outlook
The premium-commodity split in precipitated barium sulphate is consolidating around particle size distribution and surface treatment chemistry, with coated and ultra-fine grades commanding sustained price premiums over uncoated commodity volumes. Solvay leverages its European manufacturing base to dominate specialty coated grades for pharmaceutical and electronics end users. Cimbar Resources, Inc. anchors North American supply through its barite-to-sulphate vertical integration. Shaanxi Fuhua Chemical Co., Ltd. competes on scale from its Shaanxi production complex, shipping standard grades across Asian plastics and rubber channels.
Precipitated barium sulphate is a synthetic barium salt produced through controlled precipitation of barium sulfide with sodium sulfate, yielding particles with purity exceeding 98.5% and median diameters tunable between 0.3 and 10 micrometers for specific optical density and rheological performance. Its primary commercial purpose centers on delivering chemical inertness, high refractive index compatibility, and X-ray opacity across filled polymer systems and protective coatings. Ultra-fine grades lead margin pools in electronics and pharmaceutical end users where dispersion quality governs performance, while plastics and paints applications sustain volume throughput across coated and uncoated product types. The automotive application segment shows structural momentum as OEMs specify lighter radiation-shielding compounds for battery housings and interior panels.
REACH registration requirements in Europe and GB standard compliance protocols under China's SAMR shape product specifications for export-oriented manufacturers, with ECHA substance evaluation driving substitution away from less pure natural barite derivatives. FDA indirect food contact rulings and USP monograph standards for pharmaceutical-grade barium sulphate create dual compliance tracks that filter market access for non-specialist producers. Stakeholders must monitor evolving battery enclosure standards in automotive and tightening heavy metal thresholds in Asian coatings regulations to align R&D and certification investments with the next wave of specification divergence.
Market Dynamics
Automotive OEMs in Germany and China are driving specification upgrades for high-purity precipitated barium sulphate as battery enclosure standards tighten and REACH and GB heavy metal thresholds harden, compressing tolerance for lower-grade fillers across export-oriented supply chains.
Growth Catalysts
- Radiation shielding mandates:EV battery housing regulations in Germany and China now specify X-ray opacity fillers, pulling ultra-fine grades into automotive polymer compounds.
- REACH substance evaluation:ECHA's ongoing barium compound assessments are accelerating substitution away from natural barite derivatives toward synthetic precipitated grades with certified purity.
- East Asian chemical clustering:Manufacturing concentration in Shandong and Jiangsu provinces creates dense downstream demand for pigment extension and plastics compounding applications.
Market Restraints
- Barite ore supply concentration:Captive mining rights in select geographies limit feedstock access for non-integrated sulphate producers, concentrating upstream leverage.
- Energy cost volatility:Precipitation and calcination processes are electricity-intensive, exposing margin structures to industrial power tariff fluctuations in China and Europe.
- Silica and calcium sulphate substitution:Lower-cost mineral fillers threaten commodity-grade volumes in paints and rubber where optical density requirements permit.
Strategic Opportunities
- Pharmaceutical-grade certification:USP monograph compliance opens premium positioning for producers able to meet FDA indirect food contact and medical imaging standards.
- India plastics compounding:Underpenetrated masterbatch production in Gujarat and Maharashtra offers volume expansion as BIS standards align with international purity benchmarks.
- Coated grade surface chemistry:Organosilane and stearate treatments enable dispersion in high-performance thermoplastics, commanding price premiums over uncoated commodity volumes.
Industry Challenges
- Particle size distribution control:Achieving sub-micron consistency with narrow span requires precision precipitation engineering and real-time process analytics that strain technical capabilities.
- Dual-track certification timelines:Simultaneous REACH registration and GB standard compliance create extended approval cycles that delay market entry for new production capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precipitated Barium Sulphate Market |
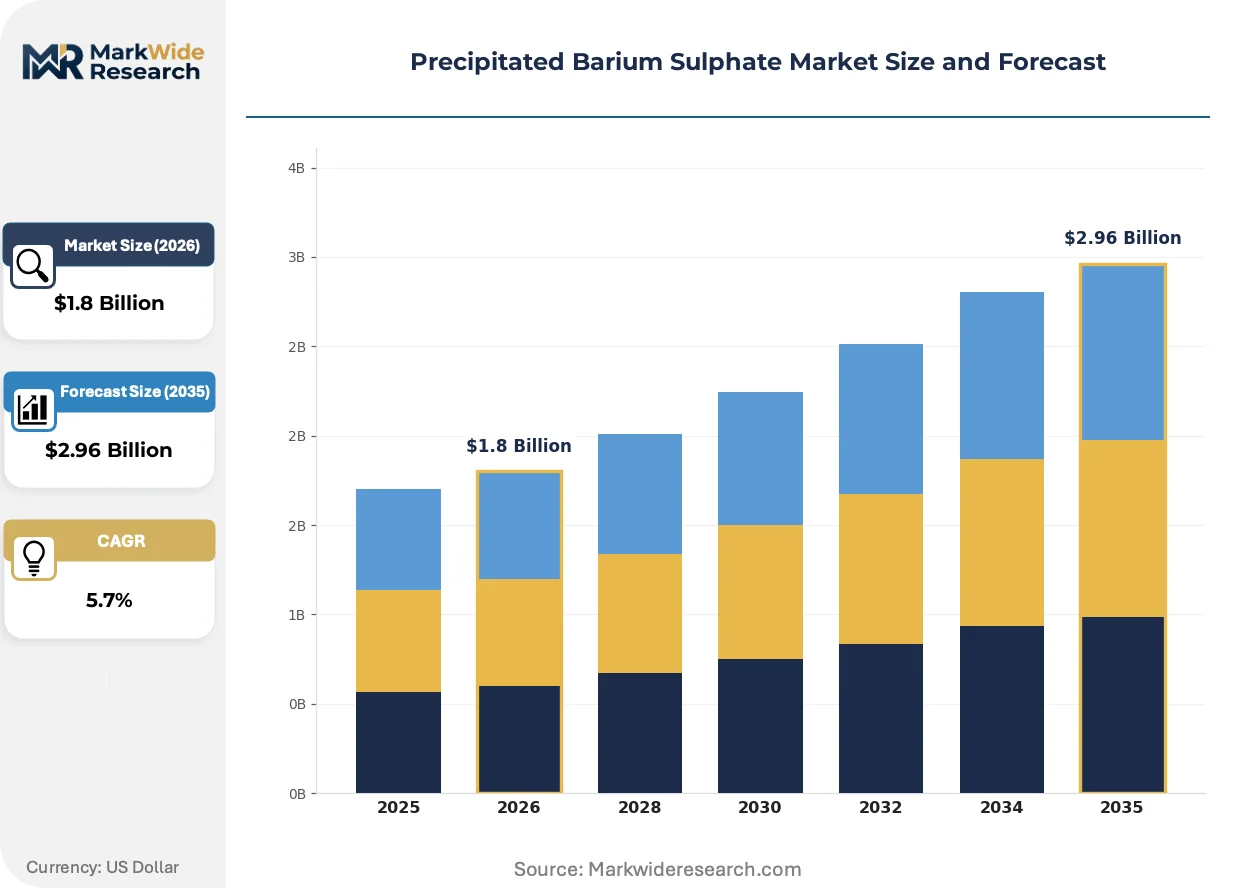
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated, Uncoated, High Specific Surface Area, Ultra-Fine Application: Plastics, Paints, Coatings, Rubber End User: Automotive, Construction, Electronics, Pharmaceutical Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | Solvay, Venator Materials PLC, Fengchen Group Co., Ltd., Cimbar Resources, Inc., SAKAI CHEMICAL INDUSTRY CO., LTD., Huntsman International LLC, Barium & Chemicals, Inc., SHENZHOU JIAXIN CHEMICAL CO.,LTD., Shaanxi Fuhua Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precipitated Barium Sulphate Market Strategic Shifts
Surface modification chemistry and digital process control are compressing the performance gap between commodity and specialty grades, while regulatory divergence between Europe and Asia forces parallel certification investments.
Coated precipitated barium sulphate with tailored organosilane surface treatments is unifying dispersion performance across polar and non-polar polymer matrices. Automotive compounders in Germany are adopting these grades for battery housing applications at accelerated qualification timelines. The technology is unifying previously separate product lines into single-platform offerings that reduce SKU complexity for multinational polymer suppliers.
China's SAMR has tightened GB standards on heavy metal content in coatings and plastics, forcing export-oriented manufacturers to source certified synthetic grades over natural barite alternatives. The industrial consequence is a bifurcation between domestic-market commodity production and export-grade specialty lines. Electronics and automotive end users in East Asia are responding by consolidating supplier bases around vertically integrated producers with in-house analytical certification.
Specification-driven procurement now dominates automotive and pharmaceutical channels, displacing volume-based tendering with technical scorecard evaluations. Distributors in Europe are losing share to direct mill relationships as OEMs require batch-level traceability and custom surface chemistry. This pattern is most visible in Germany's automotive supply chain, where Tier 1 compounders now specify particle morphology and surface area metrics in binding supply agreements.
Precipitated Barium Sulphate Market Segmentation
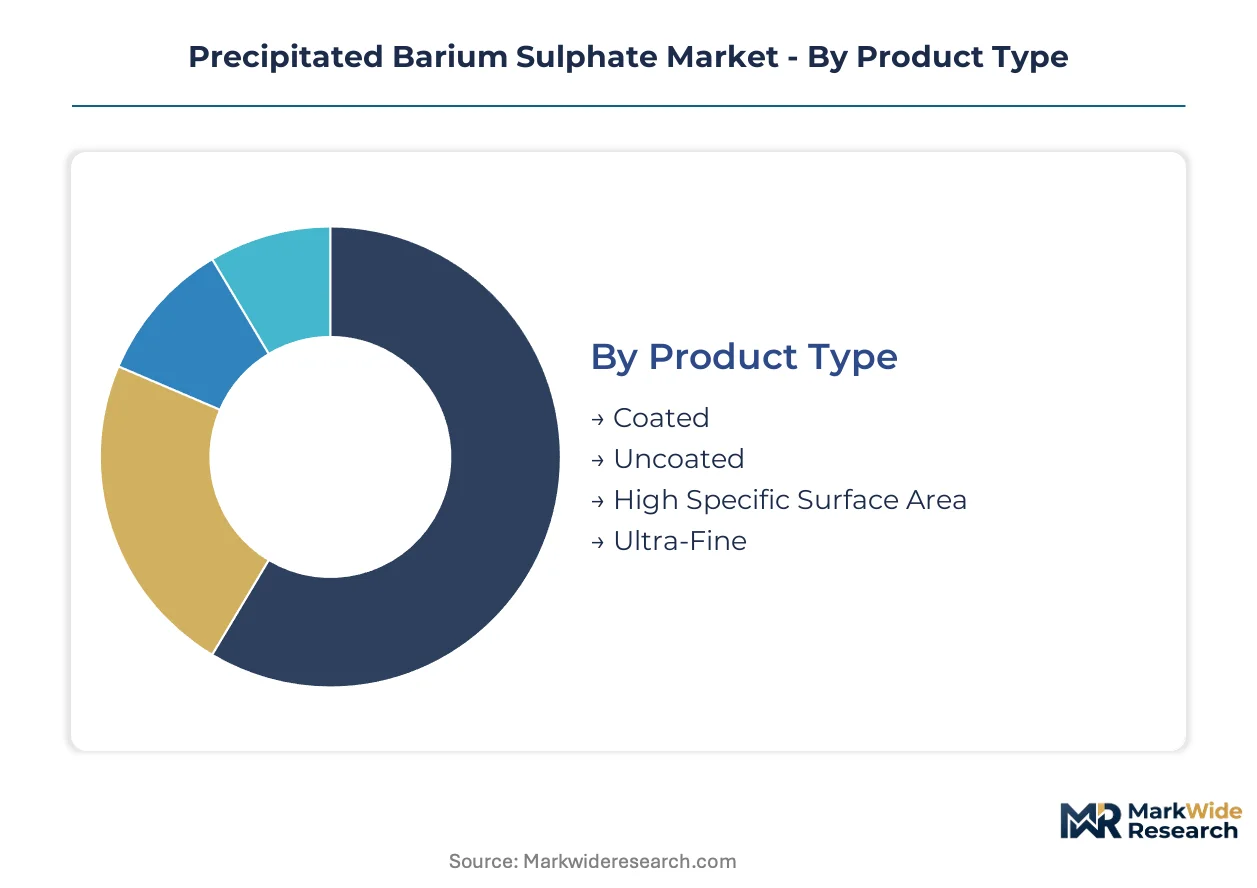
Precipitated barium sulphate markets stratify sharply across purity grades and surface chemistries, with capital allocation decisions favoring integrated producers capable of spanning multiple specification tiers from shared precipitation assets.
Product Type:
Capital intensity peaks in ultra-fine and coated grades, where sub-micron particle engineering and organosilane surface treatments demand continuous precipitation reactors and closed-loop solvent recovery systems that commodity producers cannot replicate.
- Ultra-Fine:Median diameters below 0.5 micrometers deliver X-ray opacity and dispersion stability for EV battery housings and medical imaging compounds. German automotive OEMs specify these grades under tightening battery enclosure standards, pulling capacity expansion toward REACH-certified European producers.
- Coated:Organosilane and stearate surface treatments enable compatibility across polar and non-polar polymer matrices, unifying previously separate product lines. East Asian electronics manufacturers are consolidating procurement around coated grades that reduce masterbatch complexity.
- High Specific Surface Area:Engineered porosity above 15 m²/g targets pharmaceutical and specialty coating applications where adsorption performance governs formulation stability.
- Uncoated:Standard precipitation yields commodity volumes for paints and rubber where optical density requirements permit lower specification thresholds.
Uncoated grades absorb the bulk of installed capacity; ultra-fine is expanding most quickly.
Application:
Application mix reflects diverging margin structures, with coatings commanding premium pricing for REACH and GB-compliant grades while plastics sustains volume throughput across standard specifications.
- Coatings:Automotive and industrial formulations require heavy metal certification under ECHA substance evaluation and SAMR protocols. German and Chinese coatings manufacturers are phasing out natural barite derivatives in favor of synthetic precipitated grades with certified purity.
- Plastics:Masterbatch compounding in Shandong and Jiangsu provinces drives bulk consumption of standard and coated grades for pigment extension and polymer weighting.
- Paints:Architectural and decorative applications face substitution pressure from calcium sulphate and silica fillers where opacity requirements are less stringent.
- Rubber:Tire and industrial rubber formulations utilize commodity grades for density modification and processability enhancement.
Plastics absorbs the bulk of installed capacity; coatings is climbing the fastest.
End User:
End user concentration is tilting toward specification-intensive sectors where batch traceability and custom surface chemistry displace volume-based procurement.
- Automotive:Battery housing regulations in Germany and China now mandate X-ray opacity fillers, pulling ultra-fine grades into polymer compounds for EV platforms. Tier 1 compounders specify particle morphology and surface area metrics in binding supply agreements.
- Pharmaceutical:USP monograph compliance and FDA indirect food contact rulings create dual certification tracks that filter market access to specialty producers with analytical capabilities.
- Electronics:High-performance thermoplastics for device housings demand coated grades with narrow particle size distribution and dispersion stability.
- Construction:Cement and concrete applications utilize standard grades for density and radiation shielding in medical and industrial facilities.
Construction absorbs the bulk of installed capacity; automotive is gaining share fastest.
Distribution Channel:
Channel structure is compressing as specification-driven procurement displaces distributor intermediaries in automotive and pharmaceutical segments.
- Direct Sales:OEM relationships dominate automotive and electronics channels where batch-level traceability and custom surface chemistry are mandatory. German Tier 1 compounders now bypass distributors for mill-direct agreements.
- Distributors:Regional chemical distributors retain position in paints and rubber where standard grades and price transparency favor intermediary stocking.
- Online:Digital procurement platforms are penetrating commodity-grade segments with standardized specifications and volume pricing.
- Retail:Limited to small-volume specialty applications and laboratory reagent markets.
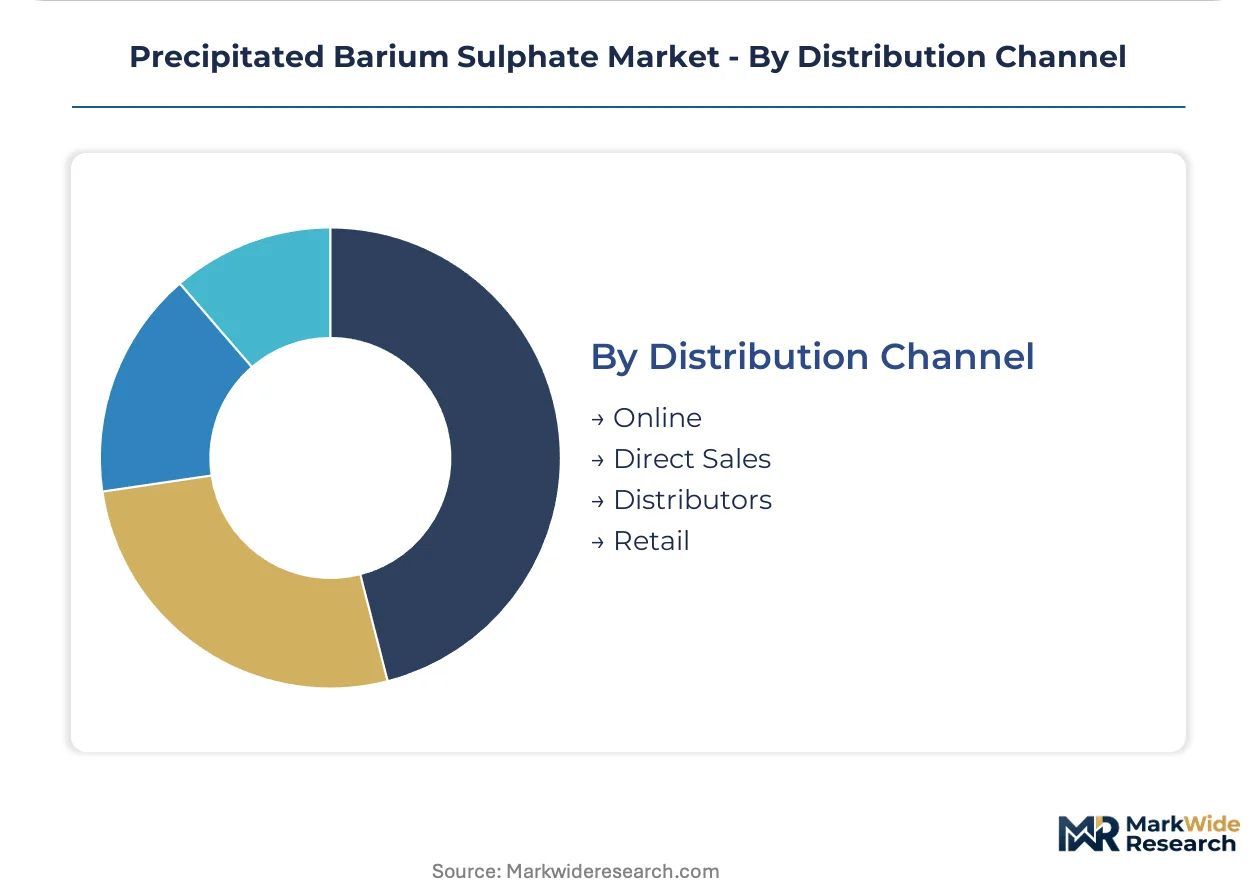
Distributors absorb the bulk of channel volume; direct sales is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong and Jiangsu provinces anchor production capacity for precipitated barium sulphate, with chemical manufacturing clusters in Qingdao and Nantong driving global supply of standard and coated grades for plastics compounding and coatings applications.
China
Automotive OEMs in Shanghai and Beijing specify ultra-fine grades for EV battery housings under tightening GB standards from SAMR. MIIT's dual carbon goals push producers toward energy-efficient precipitation processes. Shaanxi province hosts integrated barite-to-sulphate operations serving export markets with certified purity documentation.
Germany
Tier 1 compounders in Bavaria and Baden-Württemberg mandate REACH-certified grades with batch-level traceability for radiation shielding compounds. ECHA substance evaluation accelerates substitution away from natural barite derivatives. The Rhine-Ruhr industrial corridor concentrates specialty coated grade production for pharmaceutical and electronics end users.
United States
Coatings manufacturers in Ohio and Texas procure high-purity grades to meet EPA heavy metal thresholds in architectural formulations. FDA indirect food contact rulings filter market access for pharmaceutical-grade suppliers. The Gulf Coast petrochemical corridor sustains demand for masterbatch compounding in plastics applications.
India
Masterbatch producers in Gujarat and Maharashtra expand precipitated barium sulphate consumption as BIS standards align with international purity benchmarks. CDSCO pharmaceutical regulations create compliance pathways for USP-grade imports. The Delhi-Mumbai Industrial Corridor attracts specialty chemical investments targeting underpenetrated plastics compounding channels.
Japan
Electronics manufacturers in Kanto and Kansai regions specify coated grades with narrow particle size distribution for high-performance thermoplastics. METI industrial standards govern surface treatment chemistry for device housing applications. The Nagoya automotive cluster qualifies ultra-fine grades for next-generation battery enclosure designs.
Precipitated Barium Sulphate Market Competitive Environment
Capital-heavy producers compete with asset-light distributors across a tiered structure where integrated barite miners and specialty chemical houses occupy distinct margin bands. The vendor base stratifies around purity certification capabilities, with REACH-registered European operators commanding premium positioning against scale-driven Asian commodity suppliers. Three archetypes dominate: vertically integrated miners with captive feedstock, specialty chemical houses with surface modification expertise, and regional distributors with logistics networks. Competitive moves center on dual-track certification investments and direct mill relationships displacing intermediary channels.
Among European specialty chemical houses, Solvay anchors the coated-grade segment for pharmaceutical and electronics applications. Chinese producers Shaanxi Fuhua Chemical Co., Ltd. and SHENZHOU JIAXIN CHEMICAL CO.,LTD. exemplify the scale-driven archetype, shipping standard grades across Asian plastics and rubber channels from integrated production complexes. Cimbar Resources, Inc. represents North American vertical integration, controlling barite mining through sulphate conversion for regional coatings and industrial markets.
| Leading Market Players |
|---|
| Solvay |
| Venator Materials PLC |
| Fengchen Group Co., Ltd. |
| Cimbar Resources, Inc. |
| SAKAI CHEMICAL INDUSTRY CO., LTD. |
| Huntsman International LLC |
| Barium & Chemicals, Inc. |
| SHENZHOU JIAXIN CHEMICAL CO.,LTD. |
| Shaanxi Fuhua Chemical Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Barite ore procurement costs cascade through three distinct pricing tiers, with captive mining rights in China and India anchoring upstream leverage while REACH-certified European producers capture premium spreads downstream. Energy-intensive precipitation and calcination processes expose margin structures to industrial power tariff volatility, compressing returns at commodity-grade producers faster than specialty-coated operations.
Pricing Analysis
Yield-based pricing anchors the precipitated barium sulphate market, with pharmaceutical-grade USP monograph compliance and automotive battery enclosure certification commanding substantial premiums over uncoated commodity volumes. Price differentiation separates ultra-fine grades with sub-micron particle engineering from standard precipitation outputs, while surface treatment chemistry with organosilane or stearate compounds enables further tier separation. Cost compression in commodity grades is intensifying because silica and calcium sulphate substitutes threaten volume applications where optical density requirements permit. Plastics compounding buyers in East Asian manufacturing clusters exhibit highest price sensitivity, whereas German automotive OEMs prioritize specification compliance over unit economics.
Supply Chain Analysis
Feedstock security rests on concentrated barite mining rights across China, India, and Morocco, with integrated producers controlling upstream access while non-integrated sulphate converters face raw material bottlenecks. Synthetic production draws from barium sulfide and sodium sulfate chemical inputs, with precipitation reactor engineering and closed-loop solvent recovery systems creating technical moats at specialty-grade operations. Single-source vulnerability concentrates in Shandong province chemical clusters, where downstream plastics and coatings manufacturers depend on localized precipitation capacity. Distribution runs through direct mill relationships displacing regional distributors in automotive and pharmaceutical channels, while commodity grades flow through traditional chemical distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The precipitated barium sulphate market sits at a coating-chemistry transition, with organosilane surface treatments replacing legacy uncoated commodity specifications across automotive and electronics applications.
For Market Incumbents: Extend certified production capacity in REACH-registered European facilities to capture specification upgrades from German automotive OEMs tightening battery enclosure standards. Deepen backward integration into captive barite mining or secure long-term offtake agreements with Indian and Moroccan ore suppliers to defend against feedstock concentration risks. Organosilane surface modification R&D represents the critical lever for unifying previously separate product lines and reducing SKU complexity. For New Entrants and Emerging Players: Launch via direct technical partnerships with Gujarat and Maharashtra masterbatch producers targeting underpenetrated Indian plastics compounding channels as BIS standards align with international purity benchmarks. White-space concentration sits in pharmaceutical-grade USP monograph compliance, where analytical certification capabilities filter market access. A certification-first go-to-market angle, emphasizing batch-level traceability and custom surface chemistry, bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: ECHA substance evaluation acceleration is the leading indicator that synthetic precipitated grade substitution away from natural barite derivatives will concentrate margin capture among vertically integrated producers with in-house analytical capabilities. Five-to-ten-year viability favors specialty chemical houses with surface modification expertise over pure-play mining operations. Watch for SAMR enforcement actions on heavy metal content in Chinese export-grade production as the signal for accelerated supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barite Mining | Captive ore supply secures feedstock access against upstream concentration in China and India. |
| Organosilane Surface Treatment Scale-Up | Coated grade expansion captures automotive battery housing specification upgrades from German OEMs. |
| Dual-Track Certification Investment | Simultaneous REACH registration and GB standard compliance accelerates market entry timelines. |
| Direct Mill Relationship Development | Bypassing distributors meets Tier 1 compounder demands for batch-level traceability in Bavaria. |
| Pharmaceutical-Grade Analytical Capability Buildout | USP monograph compliance opens premium positioning for FDA indirect food contact applications. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews spanning plant managers at precipitation facilities, procurement leads at German automotive Tier 1 compounders, distribution channel partners in East Asian chemical clusters, and technical R&D directors at specialty coating operations. Bottom-up capacity modeling triangulated against top-down demand segmentation across purity grades and surface chemistries. ECHA substance evaluation databases, SAMR GB standard protocols, FDA indirect food contact rulings, and USP monograph documentation provided regulatory validation layers.
Granularity-level modeling operated at product-type tier (ultra-fine, coated, high specific surface area, uncoated), application segment (coatings, plastics, paints, rubber), and end-user industry (automotive, pharmaceutical, electronics, construction) across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by price realization patterns, with automotive battery enclosure regulation timing and pharmaceutical certification penetration curves serving as industry-specific forecast inputs.
Feedstock price volatility, regulatory enforcement acceleration, and substitute filler technology advancement are the dominant revision risks to modeled outputs. Forecasts embed assumptions on ECHA evaluation timelines, SAMR standard implementation pacing, and energy cost normalization patterns. A small set of named triggers—ECHA substance evaluation conclusions, SAMR heavy metal enforcement actions, and German automotive OEM qualification timelines—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Plastics Market
Bulk Chemicals
Global Bio Based Platform Chemicals Market
Bulk Chemicals
Global Sodium Borohydride Market
Bulk Chemicals
Ammonia Storage Tanks Market
Bulk Chemicals
Glacial Acrylic Acid (GAA) Market
Bulk Chemicals
Global Molten Sulfur Market
Bulk Chemicals
Glyceryl Triacetate (Triacetin) Market
Bulk Chemicals
Metallurgical Coke Market
Bulk Chemicals
Asia-Pacific Formic Acid Market
Bulk Chemicals
2-Nitrothiophene Market
Bulk Chemicals
Picric Acid Market
Bulk Chemicals
Global Sodium Phosphate Market
Bulk Chemicals
Diisopropylbenzene Market
Bulk Chemicals
Europe Lipids Market
Bulk Chemicals
Global Silica Flour Market
Bulk Chemicals
Benzotrifluoride Market