
 North America Bovine Lactoferrin Market | 2026-2036
North America Bovine Lactoferrin Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bovine Lactoferrin Market Insights
Asset-light toll manufacturing and third-party extraction leasing is tilting competitive dynamics toward firms that avoid capital-heavy fractionation infrastructure. FrieslandCampina leverages its Dutch dairy science heritage to sustain premium positioning in North American ingredient supply. Glanbia Nutritionals anchors its presence through whey protein co-location that reduces lactoferrin isolation costs. Synlait Milk differentiates via integrated spray-drying capacity that controls powder quality from farm to finished ingredient.
Bovine lactoferrin is an iron-binding glycoprotein comprising approximately 703 amino acids, typically extracted from cheese whey or skim milk through cation exchange chromatography and employed as a bioactive ingredient for immune modulation and iron absorption enhancement. The powder segment dominates current volume flows due to superior stability in bulk ingredient handling and extended shelf life under controlled humidity conditions. Pharmaceutical applications represent the fastest-growing demand pool as compounding pharmacies and drug developers explore lactoferrin's antimicrobial and anti-inflammatory properties for novel delivery formats. Dietary supplements occupy the mature volume tier where brand proliferation has compressed differentiation and shifted margin capture toward contract manufacturers with scale efficiencies.
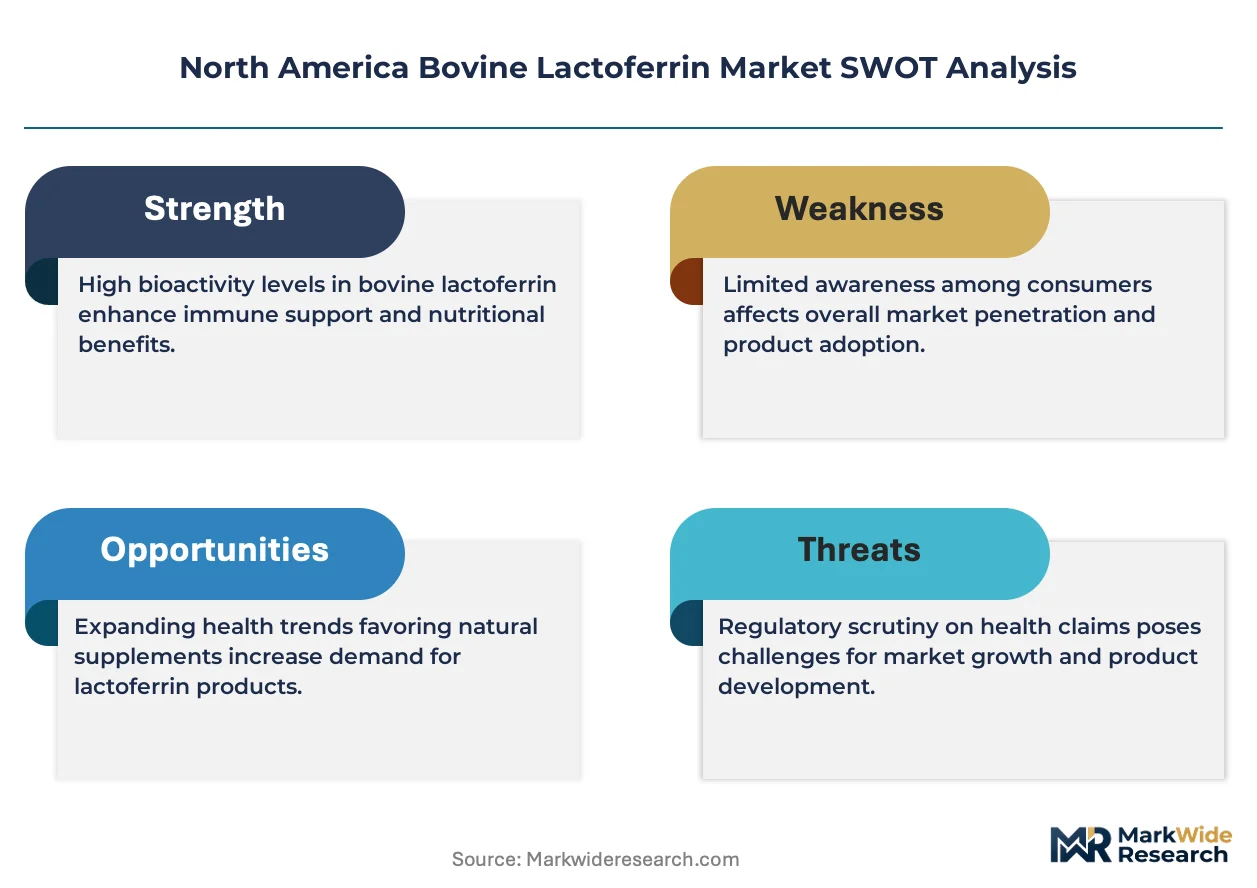
The FDA oversees lactoferrin through its GRAS self-affirmation and notification programs, while Health Canada regulates the ingredient under its Natural Health Products framework, creating a dual compliance burden for cross-border suppliers. USDA organic certification and state-level dairy quality standards in Wisconsin and California further fragment the qualification landscape for raw material sourcing. Stakeholders must monitor evolving infant formula nutrient specifications from the American Academy of Pediatrics and Health Canada, as these clinical guidance documents increasingly influence procurement criteria for bioactive protein fortification.
Market Dynamics
Asset-light toll manufacturing and third-party extraction leasing is tilting competitive dynamics toward firms that avoid capital-heavy fractionation infrastructure. The FDA's GRAS notification pathway for dairy-derived ingredients accelerates product clearance timelines.
Growth Catalysts
- GRAS Notification Streamlining:The FDA's GRAS self-affirmation pathway compresses ingredient approval timelines for dairy-derived bioactives entering infant formula and dietary supplement channels.
- Infant Formula Reformulation:Manufacturers are fortifying with bioactive proteins as clinical guidance from the American Academy of Pediatrics elevates procurement criteria for immune-modulating ingredients.
- California Nutraceutical Corridor Concentration:Demand clusters in this processing hub where dairy fractionation expertise and finished goods manufacturing co-locate.
Market Restraints
- Whey Supply Concentration:Raw material sourcing concentrates in Wisconsin and California dairy belts, creating geographic vulnerability to regional climate disruptions.
- Dual Compliance Burden:Health Canada's Natural Health Products framework and FDA GRAS programs impose parallel qualification requirements for cross-border suppliers.
- Plant Protein Substitution:Fermentation-derived and legume-based iron-binding proteins are emerging as functional alternatives in dietary supplement applications.
Strategic Opportunities
- Pharmaceutical Compounding Expansion:Drug developers are exploring lactoferrin's antimicrobial properties for novel delivery formats targeting antimicrobial and anti-inflammatory indications.
- USDA Organic Certification Premium:State-level organic dairy quality standards in California and Wisconsin enable ingredient tiering for premium nutraceutical positioning.
- Integrated Spray-Drying Control:Farm-to-finished-ingredient powder quality management is capturing margin from buyers seeking batch traceability.
Industry Challenges
- Cation Exchange Chromatography Skill Scarcity:Fractionation expertise for whey and skim milk extraction remains concentrated among legacy dairy scientists.
- Capital-Heavy Isolation Infrastructure:Whey protein co-location investments required for cost-competitive lactoferrin separation strain mid-scale entrants.
- Guideline-Driven Procurement Volatility:Shifting nutrient specifications from pediatric clinical bodies force rapid formulation adjustments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bovine Lactoferrin Market |
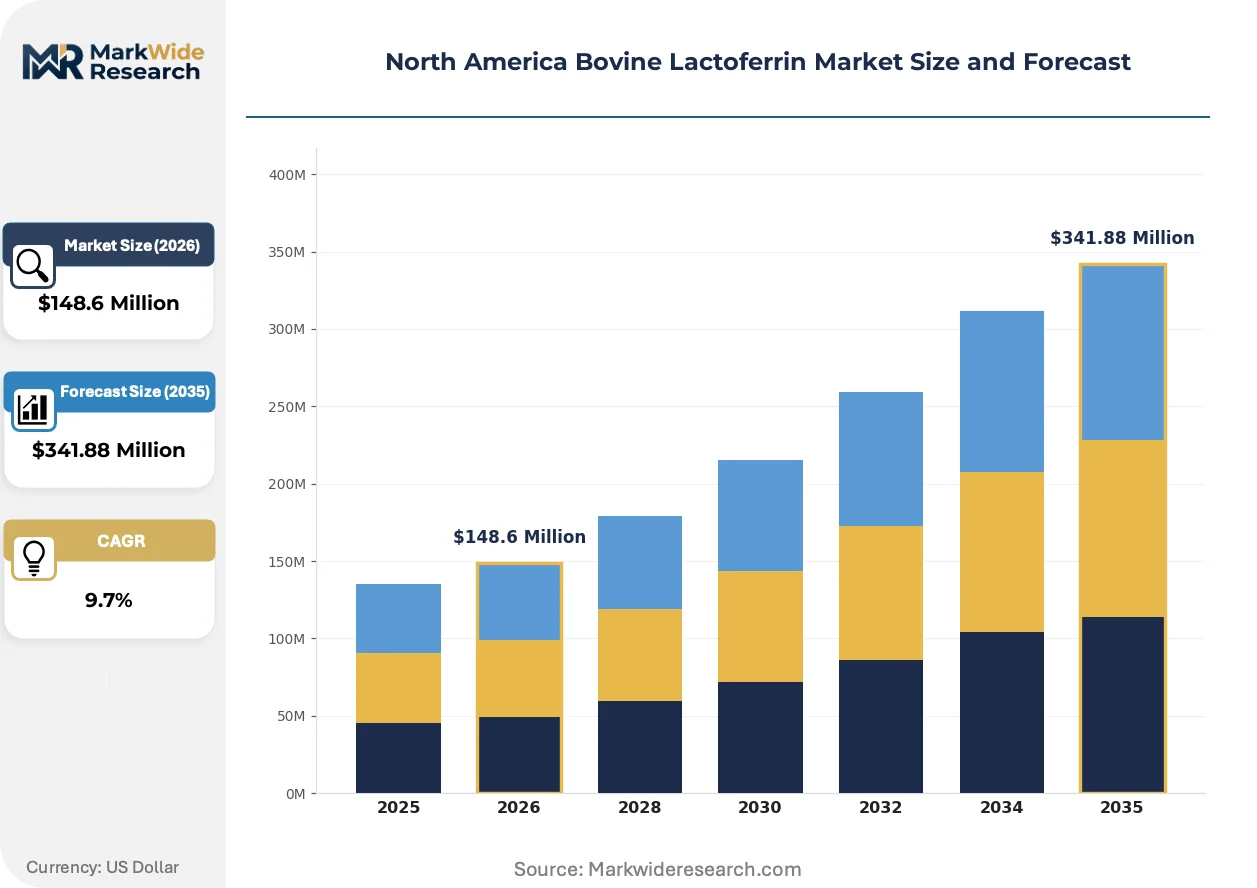
| Market Size in 2026 | $148.6 Million |
| Market Size in 2035 | $341.88 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsules, Tablets Application: Dietary Supplements, Functional Foods, Infant Formula, Pharmaceuticals End User: Healthcare Providers, Nutraceutical Companies, Food Manufacturers, Consumers Distribution Channel: Online Retail, Supermarkets, Pharmacies, Direct Sales |
| Companies Covered | FrieslandCampina, Synlait Milk, Fonterra Co-operative Group, Glanbia Nutritionals, Bega Cheese, Saputo, Nutriscience Innovations, Lactoferrin International, Tatua Co-Operative Dairy Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bovine Lactoferrin Market Trends and Innovations
Process intensification and regulatory harmonization are compressing development cycles for bioactive dairy ingredients. Three converging forces are restructuring how value flows through the North American supply base.
Membrane filtration technology is hybridizing with traditional cation exchange chromatography to reduce solvent use and improve yield rates in whey processing. Pharmaceutical-grade ingredient manufacturers are adopting these hybrid systems fastest, driven by compounding pharmacy demand for high-purity inputs. This convergence is compressing the cost gap between food-grade and pharmaceutical-grade lactoferrin specifications.
The FDA's GRAS notification program and Health Canada's Natural Health Products framework are creating divergent compliance pathways for cross-border suppliers. Dual-track qualification requirements are fragmenting supplier bases into region-specialized operators. Infant formula manufacturers with integrated US-Canada supply chains face the steepest documentation burdens.
Ingredient buyers are consolidating procurement around contract manufacturers with captive fractionation capacity. Brand proliferation in dietary supplements has compressed differentiation, shifting margin capture toward toll processors with scale efficiencies. This concentration is most visible in California's nutraceutical corridor where spray-drying and isolation capabilities co-locate.
North America Bovine Lactoferrin Market Segmentation
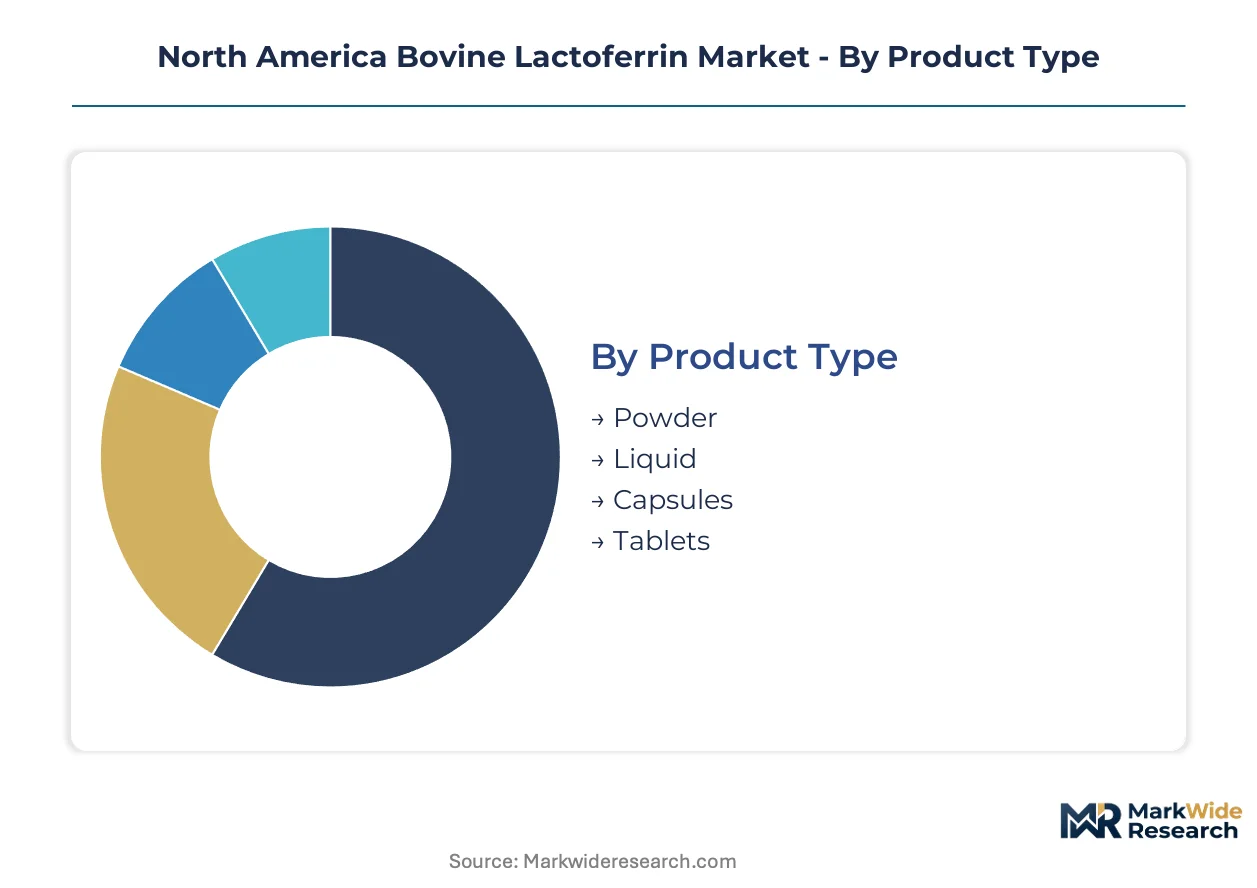
Segmentation in bovine lactoferrin markets reveals how bioactive protein specifications diverge across regulatory pathways and end-use requirements. Powder stability versus liquid bioavailability, pharmaceutical purity versus food-grade cost efficiency, and direct procurement versus retail distribution each create distinct competitive arenas with separate margin structures.
Product Type:
Use-case spectrum spans bulk ingredient handling through precision-dosed delivery formats, with stability requirements and bioavailability claims driving format selection.
- Powder:Spray-dried lactoferrin delivers superior shelf stability under controlled humidity, dominating California's nutraceutical corridor where bulk handling infrastructure concentrates. Infant formula manufacturers in the upper Midwest dairy belt source powder for its compatibility with dry-blending operations and extended storage logistics.
- Liquid:Aqueous suspensions preserve native protein conformation for enhanced iron-binding kinetics, finding uptake in pharmaceutical compounding where bioactivity metrics determine procurement. Compounding pharmacies in Texas and Florida are adopting liquid formats for novel antimicrobial delivery systems requiring rapid dissolution profiles.
- Capsules:Encapsulation protects gastric degradation for targeted intestinal release, serving nutraceutical brands with differentiated absorption claims.
- Tablets:Compressed formats enable precise dosing in multivitamin matrices, occupying mass-market supplement shelves where cost-per-unit drives selection.
The dominant share belongs to Powder, while Liquid is closing the gap fastest.
Application:
Regulatory classification tiers separate food-grade fortification from pharmaceutical-grade therapeutic claims, with compliance burden determining market entry sequencing.
- Dietary Supplements:Mature volume tier where brand proliferation has compressed differentiation and shifted margin capture toward contract manufacturers with scale efficiencies. California and Utah-based supplement brands dominate procurement, though FDA GRAS documentation requirements increasingly favor established suppliers with notification history.
- Pharmaceuticals:Drug developers are exploring lactoferrin's antimicrobial and anti-inflammatory properties for novel delivery formats targeting compounding pharmacy channels. FDA's drug substance qualification pathway imposes steepest purity specifications, creating margin premiums for manufacturers with pharmaceutical-grade isolation capabilities.
- Functional Foods:Beverage and dairy fortification applications leverage GRAS status for immune positioning claims, with beverage manufacturers in the Pacific Northwest testing heat-stable formulations.
- Infant Formula:Manufacturers are fortifying with bioactive proteins as clinical guidance from the American Academy of Pediatrics elevates procurement criteria for immune-modulating ingredients. Abbott and Mead Johnson sourcing specifications drive purity standards across the supply base.
Pharmaceuticals command the steepest expansion trajectory, though Dietary Supplements retain volume leadership through established retail distribution.
End User:
Procurement sophistication varies from institutional specification-setting to consumer self-selection, with technical capability determining ingredient grade access.
- Nutraceutical Companies:Contract manufacturers and branded marketers with formulation expertise source across purity grades based on positioning strategy, concentrating procurement decisions in California's Orange County and Utah's Wasatch Front clusters.
- Food Manufacturers:Dairy processors and beverage formulators integrate lactoferrin into functional product lines, with Wisconsin cheese makers leveraging captive whey streams for cost-advantaged sourcing.
- Healthcare Providers:Compounding pharmacies and integrative medicine clinics specify pharmaceutical-grade inputs for patient-specific formulations, driving demand for lot-traceable documentation.
- Consumers:Direct purchasers through e-commerce channels exhibit price sensitivity and limited specification literacy, creating arbitrage opportunities for lower-tier suppliers.
Nutraceutical Companies anchor procurement volume, while Healthcare Providers are gaining share fastest through compounding pharmacy expansion.
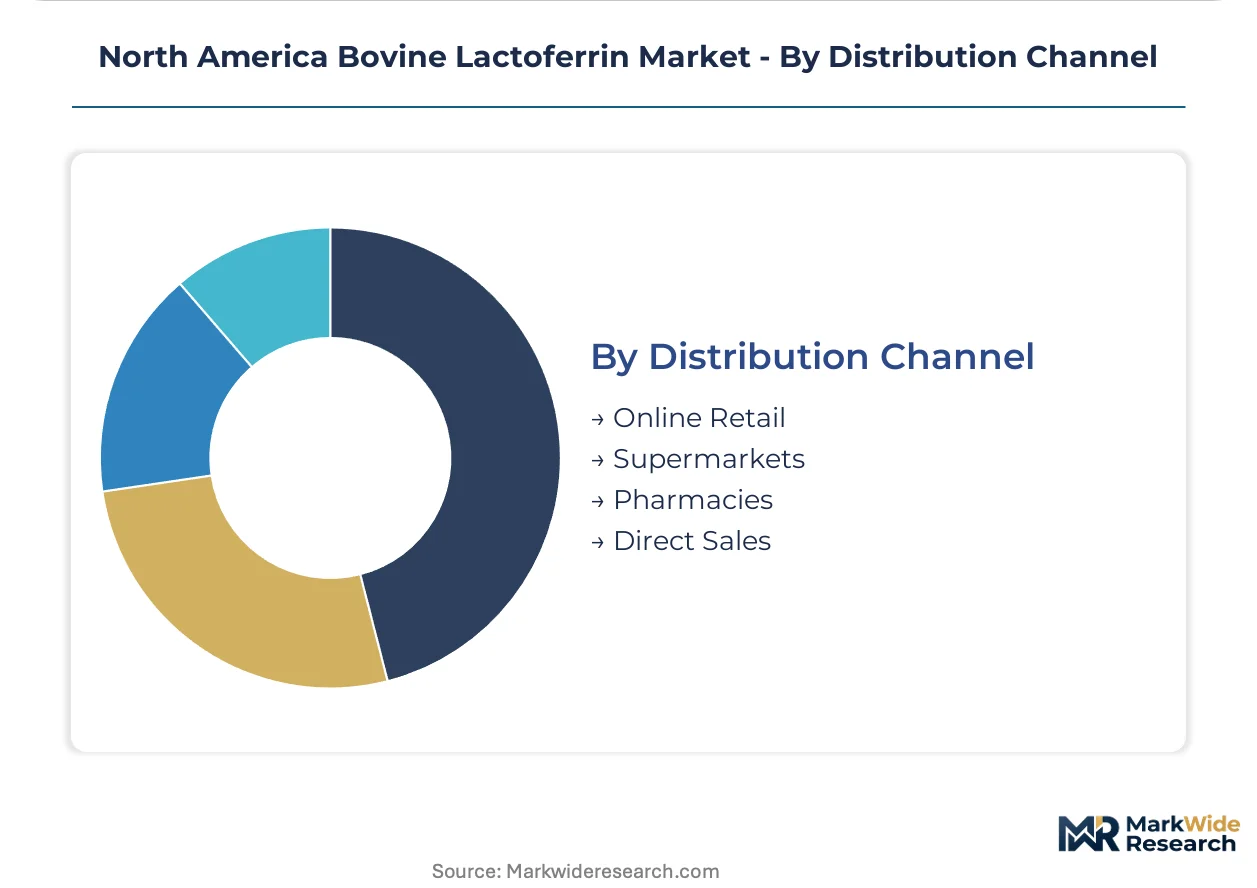
Distribution Channel:
Channel selection reflects buyer technical sophistication and urgency requirements, with specification complexity favoring direct relationships over retail intermediation.
- Direct Sales:Long-term supply agreements between fractionators and infant formula or pharmaceutical manufacturers bypass intermediaries, enabling batch customization and joint regulatory filing support. FrieslandCampina and Glanbia Nutritionals anchor this channel through technical service capabilities.
- Pharmacies:Hospital and retail pharmacy chains source pharmaceutical-grade inventory for compounding operations, with USP-grade documentation requirements filtering supplier bases.
- Online Retail:Amazon and specialized supplement platforms serve consumer self-selection with commoditized powder and capsule offerings, where review velocity and price positioning determine visibility.
- Supermarkets:Mass-market retail placement remains limited given ingredient cost structures and consumer education requirements, though functional food integration is testing select Whole Foods and Sprouts locations.
Direct Sales captures the dominant procurement value, while Online Retail is expanding most quickly through direct-to-consumer brand proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's GRAS notification pathway accelerates product clearance timelines for dairy-derived bioactives entering US and Canadian markets. Infant formula reformulation drives demand concentration across California's nutraceutical corridor and the upper Midwest dairy belt.
United States
California's nutraceutical corridor anchors ingredient demand as spray-drying and isolation capabilities co-locate with finished goods manufacturing. Wisconsin's dairy processing belt supplies captive whey streams to fractionators seeking cost-advantaged raw material access. FDA GRAS self-affirmation compresses approval timelines for bioactives entering dietary supplement and infant formula channels.
Canada
Health Canada's Natural Health Products framework imposes parallel qualification requirements alongside FDA programs, creating documentation burdens for cross-border suppliers. Quebec and Ontario dairy processors leverage proximity to US infant formula manufacturers for integrated North American supply chains. Provincial organic certification standards enable premium ingredient tiering for nutraceutical positioning.
Mexico
Jalisco's dairy cluster supplies whey feedstock to fractionators serving both domestic supplement brands and export markets. COFEPRIS regulatory alignment with FDA standards facilitates ingredient transit into US pharmaceutical compounding channels. Northern border states concentrate toll manufacturing investments targeting California nutraceutical demand.
North America Bovine Lactoferrin Market Competitive Landscape
On the supply side, the industry is consolidating around fractionators with captive whey processing infrastructure and integrated spray-drying capabilities. The competitive terrain splits between Dutch dairy science heritage players, Australasian co-operative structures, and North American nutritionals specialists. Three archetypes dominate: legacy dairy cooperatives with backward integration into milk supply, ingredient specialists with pharmaceutical-grade isolation capabilities, and asset-light toll manufacturers leasing third-party extraction capacity. Capacity expansion and regulatory filing partnerships constitute the dominant competitive moves as firms race to secure GRAS notification precedence.
Within the heritage dairy cooperative tier, FrieslandCampina and Fonterra Co-operative Group exemplify players leveraging century-old fractionation expertise for premium North American positioning. Glanbia Nutritionals occupies a distinct slot among nutritionals-focused operators, anchoring its presence through whey protein co-location strategies that reduce isolation costs. Synlait Milk represents the integrated manufacturing archetype, controlling powder quality from farm through finished ingredient via captive spray-drying infrastructure.
| Leading Market Players |
|---|
| FrieslandCampina |
| Synlait Milk |
| Fonterra Co-operative Group |
| Glanbia Nutritionals |
| Bega Cheese |
| Saputo |
| Nutriscience Innovations |
| Lactoferrin International |
| Tatua Co-Operative Dairy Company |
| Others |
Pricing and Supply Chain Analysis
The I-5 freight corridor linking California's nutraceutical corridor to the upper Midwest dairy belt concentrates logistics costs that amplify both supply-side pricing power and downstream grade-based price differentiation. Whey supply concentration in Wisconsin and California creates regional bottlenecks where fractionators extract premiums from captive raw material access, while infant formula manufacturers absorb cost pass-throughs driven by clinical specification tightening.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and food-grade lactoferrin, with FDA drug substance qualification commanding substantial premiums over GRAS-notified food-grade material. Three-tier pricing structure across premium, standard, and economy levels stratifies by purity specification and lot traceability depth. Cost compression in the dietary supplement tier is intensifying because brand proliferation has shifted margin capture toward contract manufacturers with captive spray-drying infrastructure. Consumer direct purchasers through Amazon and specialized platforms exhibit the highest price sensitivity, while pharmaceutical compounding pharmacies demonstrate the lowest sensitivity due to bioactivity metric requirements.
Supply Chain Analysis
Tariff exposure between the United States and Canada dominates supply chain risk planning as cross-border suppliers navigate parallel FDA GRAS and Health Canada Natural Health Products qualification burdens. Raw material sourcing concentrates in Wisconsin, California, and Quebec dairy belts, with whey feedstock availability tethered to cheese production cycles and seasonal milk flow variation. Cation exchange chromatography resin supply and specialized membrane filtration equipment constitute critical component dependencies with limited qualified vendors. Distribution runs through direct long-term supply agreements for pharmaceutical and infant formula tiers, while dietary supplement channels fragment across online retail and contract manufacturing intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among infant formula manufacturers as Abbott and Mead Johnson procurement specifications increasingly dictate purity standards across the entire North American supply base. This consolidation forces suppliers into technical service partnerships that favor fractionators with integrated regulatory filing capabilities.
For Market Incumbents: Pre-empt fermentation-derived iron-binding protein substitution by securing pharmaceutical-grade isolation certifications ahead of compounding pharmacy demand expansion. Lock in backward integration into Wisconsin and California whey streams before climate volatility disrupts regional supply. Anchor presence through joint GRAS notification filings with major infant formula manufacturers to create switching costs. For New Entrants and Emerging Players: Mexico's Jalisco dairy cluster offers underpenetrated toll manufacturing capacity with COFEPRIS-FDA regulatory alignment enabling cost-advantaged export positioning. Target pharmaceutical compounding channels in Texas and Florida where liquid format bioavailability claims command premium positioning. Enter through asset-light extraction leasing arrangements that avoid capital-heavy fractionation infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy dairy cooperatives seeking to monetize captive fractionation expertise without full vertical integration commitment. Frame long-term viability around pharmaceutical-grade capacity expansion as antimicrobial and anti-inflammatory therapeutic applications mature. Monitor Health Canada-FDA regulatory harmonization progress as the primary inflection signal for cross-border supply chain rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Isolation Certification | FDA drug substance qualification unlocks compounding pharmacy margin premiums unavailable to food-grade suppliers. |
| Backward Integration into Whey Supply | Wisconsin cheese maker partnerships secure captive raw material streams insulated from spot market volatility. |
| Joint GRAS Notification Partnerships | Collaborative filings with Abbott and Mead Johnson create specification lock-in and technical service revenue. |
| Integrated Spray-Drying Capacity Expansion | Farm-to-finished-ingredient quality control captures batch traceability premiums from nutraceutical buyers. |
| Asset-Light Toll Manufacturing Network | Third-party extraction leasing reduces capital intensity for mid-scale entrants targeting dietary supplement volume. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA GRAS notification databases, USDA organic certification records, and American Academy of Pediatrics clinical guidance documents. Interviews with infant formula procurement directors, dairy cooperative fractionation engineers, and compounding pharmacy formulation specialists informed supply-side and demand-side validation. Health Canada Natural Health Products framework documentation and state-level Wisconsin dairy quality standards provided regulatory boundary conditions. Bottom-up volume modeling from whey supply estimates and top-down value triangulation against ingredient pricing benchmarks ensured cross-verification.
Forecast inputs span product type segmentation across powder and liquid formats, application tiers from dietary supplements through pharmaceuticals, and end-user categories including nutraceutical companies and healthcare providers. CAGRs derive from regression analysis against infant formula fortification intensity trends and pharmaceutical compounding channel expansion rates across the analysis window. Whey protein co-location economics and cation exchange chromatography yield improvement trajectories constitute industry-specific forecast inputs.
Practitioners should monitor Health Canada-FDA regulatory harmonization negotiations, fermentation-derived protein substitution rates, and pediatric clinical guideline revision cycles for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Austria Protein Supplements Market
Nutritional Supplements
Algae Supplements Market
Nutritional Supplements
Whey Basic Protein Isolates Market
Nutritional Supplements
Microencapsulated Fish Oil Market
Nutritional Supplements
Europe Botanical Supplements Market
Nutritional Supplements
Marine Collagen Market
Nutritional Supplements
Immunity Boosting Food Market
Nutritional Supplements
Asia-Pacific Digestive Enzymes Market
Nutritional Supplements
Energy Supplements Market
Nutritional Supplements
India Whey Protein Market
Nutritional Supplements
Natural Immune Booster Market
Nutritional Supplements
High-Selenium Yeast Market
Nutritional Supplements
Nutrition Therapy Market
Nutritional Supplements
Global Digestive Enzymes Market
Nutritional Supplements
Lipid Nutrition Market
Nutritional Supplements
Africa Beta Glucan Market