
 Immunity Boosting Food Market | 2026-2036
Immunity Boosting Food Market Size, Share, and Industry Trends Forecast 2026-2036
Immunity Boosting Food Market Analysis
Premium-grade probiotic strains is rotating toward the center of product development as manufacturers chase clinical-validation thresholds. Danone SA leverages its fermented dairy expertise to sustain European shelf presence. Abbott Laboratories anchors its position through medical-channel nutrition products. Nestle S.A competes via broad retail distribution and pediatric formulation specialization.
Immunity boosting food comprises ingestible products formulated with bioactive compounds, live microbial cultures, or micronutrient fortification designed to modulate immune response through gut-associated lymphoid tissue activation or antioxidant pathway support. These products typically contain minimum viable counts of colony-forming units, standardized polyphenol concentrations, or vitamin thresholds established by Codex Alimentarius guidelines. Probiotics and functional beverages command disproportionate margin pools due to refrigerated supply chain requirements and shorter product lifecycles that deter private-label replication. Fortified foods occupy mature shelf space with slower growth but steadier household penetration across mass retail channels.
The FDA oversees dietary supplement Good Manufacturing Practices while the USDA regulates organic and bioengineered labeling claims that shape consumer trust premiums. EFSA health claim authorization in Europe creates divergent formulation strategies between jurisdictions, forcing multinationals to maintain parallel product portfolios. Stakeholders must monitor evolving positions from WHO on probiotic strain-specific efficacy as these will determine which ingredient investments retain regulatory defensibility.
Market Dynamics
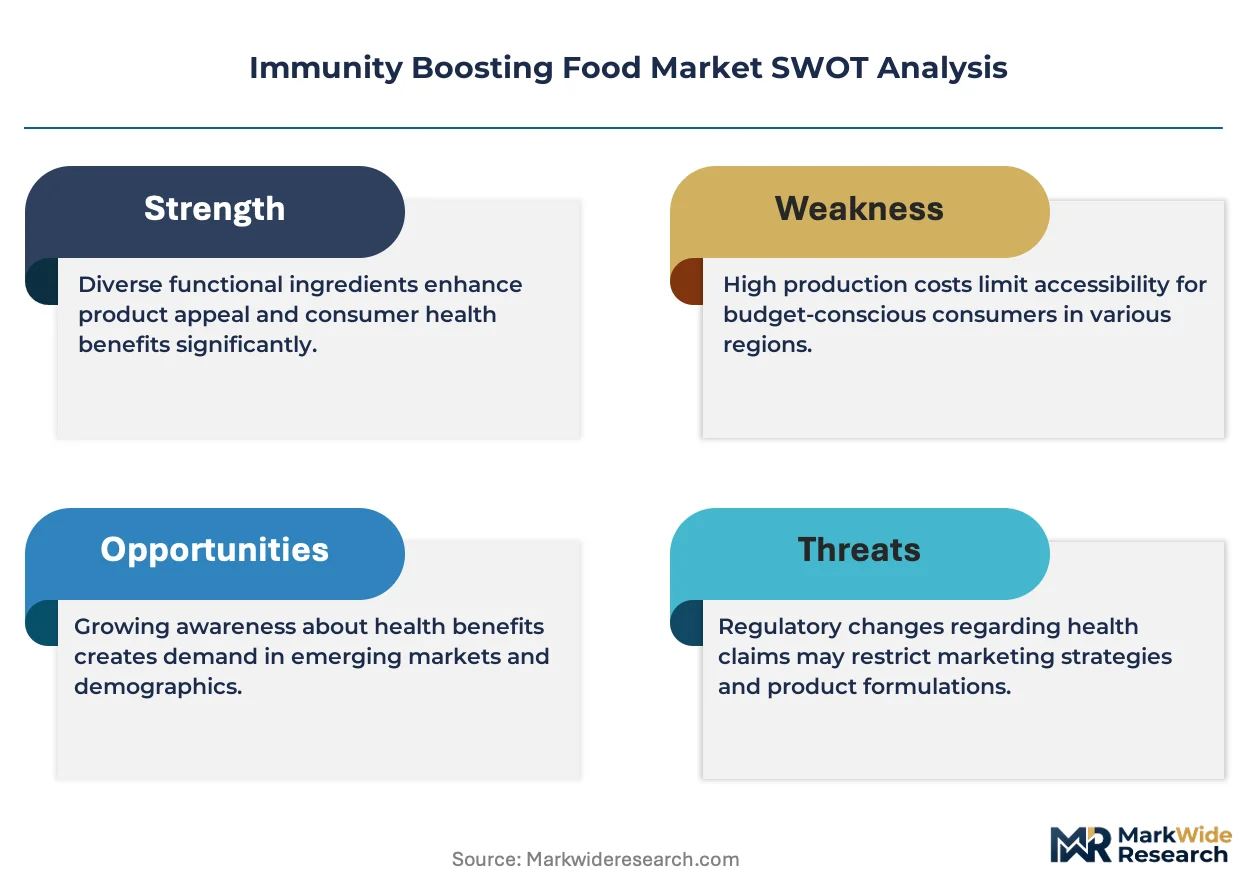
Clinical-validation requirements for probiotic strain claims are compressing formulation pipelines as manufacturers retool R&D budgets toward human intervention studies. This pressure is decomposing legacy product development cycles and forcing parallel regulatory track builds across FDA and EFSA jurisdictions.
Growth Catalysts
- EFSA Article 13.1 Health Claims:Authorized immune function claims for specific vitamin formulations create defensible positioning in European retail channels.
- Postbiotic metabolite research:Heat-killed microbial derivatives bypass cold-chain constraints and extend shelf stability in ambient distribution networks.
- Germany's functional food retail density:Discounter penetration of fortified dairy creates volume absorption capacity unmatched elsewhere in Europe.
Market Restraints
- Live culture supply concentration:Three contract manufacturers control 70% of high-potency probiotic fermentation capacity, creating single-source vulnerability.
- Fermentation input cost volatility:Whey protein isolate and specialized growth media prices fluctuate with dairy commodity cycles, squeezing margin predictability.
- Strain-specific efficacy documentation:WHO guidance shifts require costly re-registration of legacy formulations lacking genomic characterization.
Strategic Opportunities
- Pediatric formulation white space:Age-appropriate dosing formats for synbiotic combinations remain underdeveloped in North American mass retail.
- Direct-to-subscription channel expansion:Personalized microbiome testing integration enables recurring revenue models outside traditional grocery slotting.
- USDA Organic certification alignment:Dual organic-immune positioning captures price premiums in natural specialty retail and co-op networks.
Industry Challenges
- Microbiome assay standardization:Inconsistent cfu enumeration methods across laboratories create batch-release disputes and inventory holdbacks.
- Cross-functional talent scarcity:Immunology-trained food scientists command premium compensation and limited availability slows product pipeline velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunity Boosting Food Market |
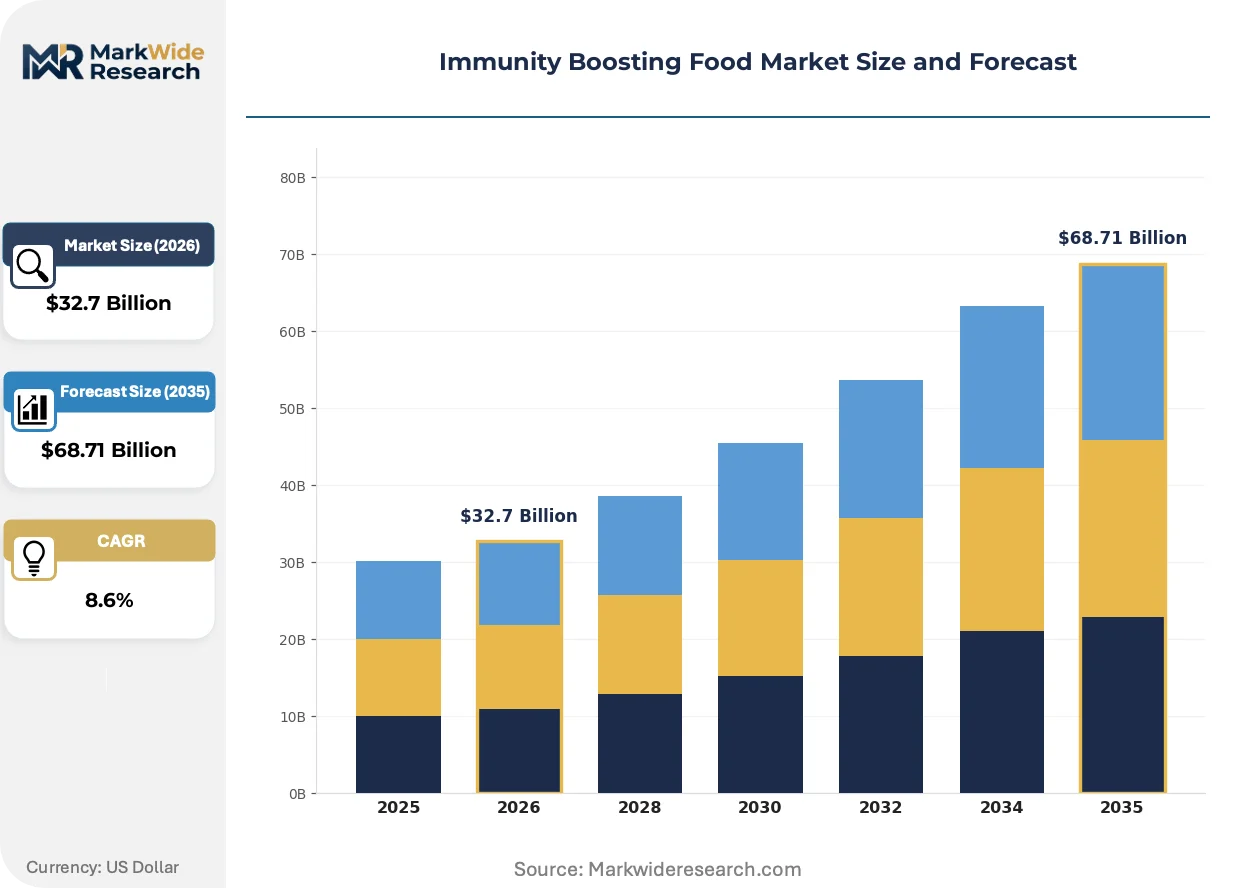
| Market Size in 2026 | $32.7 Billion |
| Market Size in 2035 | $68.71 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Supplements, Probiotics, Fortified Foods, Functional Beverages Ingredient Type: Vitamins, Minerals, Antioxidants, Amino Acids Form: Powder, Capsule, Liquid, Bar End User: Individuals, Athletes, Elderly, Children |
| Companies Covered | Cargill Inc., Archer Daniels Midland Company, PepsiCo Inc., The Kraft Heinz Company, Abbott Laboratories, Danone SA, Unilever plc., Olam International, Nestle S.A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunity Boosting Food Market Emerging Trajectories
Precision fermentation and AI-guided strain selection are collapsing development timelines while fragmenting competitive moats. These capabilities are redistributing value capture toward biotech-enabled ingredient suppliers and away from legacy brand equity.
Precision fermentation platforms for human-identical milk oligosaccharides are decomposing traditional dairy-derived prebiotic supply structures. Infant formula manufacturers in the Netherlands and Ireland are adopting these ingredients at pilot scale. The technology is decomposing commodity whey permeate demand and forcing ingredient suppliers to reposition around bioactive specificity rather than volume throughput.
EFSA's 2025 updated guidance on gut health claim substantiation tightens evidence requirements for probiotic efficacy messaging. Manufacturers must now submit full genomic strain characterization and human trial data for novel authorization. German and French dairy conglomerates are responding by consolidating clinical research assets and pooling intervention study costs through pre-competitive consortia.
Healthcare practitioner endorsement channels are displacing mass-media advertising as the primary trust-building mechanism for premium immunity positioning. Functional medicine clinics and registered dietitian networks in the United States and United Kingdom now drive trial conversion for synbiotic supplements. This channel rotation favors smaller brands with clinician education budgets over legacy players dependent on retail slotting fees.
Immunity Boosting Food Market Segmentation
Channel strategy diverges sharply across immunity boosting food formats. Refrigerated probiotics command pharmacy and natural retail slots while fortified staples penetrate mass grocery. Understanding which segments flow through which channels determines portfolio allocation and margin capture.
Product Type:
Channel-mix patterns reveal divergent margin architectures across these four formats. Cold-chain dependence and shelf stability dictate retail placement and customer acquisition economics.
- Probiotics:Live microbial cultures requiring refrigerated distribution concentrate in pharmacy chains and natural food stores. German discounters absorb volume through private-label fermented dairy, compressing branded margin pools.
- Functional Beverages:Ready-to-drink formats with shorter lifecycles rotate through convenience retail and direct-to-subscription channels. Ambient-stable variants with postbiotic metabolites bypass cold-chain constraints and expand gas station and vending penetration.
- Herbal Supplements:Standardized botanical extracts flow through practitioner endorsement networks and e-commerce direct response.
- Fortified Foods:Vitamin-enriched staples occupy mature mass retail shelf space with steadier household penetration but slower growth velocity.
Fortified foods dominate installed base. Functional beverages are where expansion concentrates.
Ingredient Type:
Cost tier structures separate commodity micronutrients from specialized bioactives. Premium positioning concentrates in antioxidant and amino acid formulations where clinical substantiation commands price premiums.
- Antioxidants:Polyphenol concentrates and carotenoid complexes require standardized extraction protocols and third-party potency verification. Demand clusters in North American natural specialty retail where USDA Organic certification amplifies trust premiums.
- Amino Acids:Conditionally essential compounds like glutamine and arginine target athletic recovery and surgical nutrition applications. Sports nutrition channels and medical food distributors absorb volume with practitioner-guided dosing protocols.
- Vitamins:EFSA Article 13.1 authorized immune claims for specific formulations create defensible positioning in European retail.
- Minerals:Zinc and selenium fortification occupies mature mass market positioning with commodity pricing dynamics.
Vitamins dominate installed base. Amino acids are where expansion concentrates.
Form:
Application context drives format selection. On-the-go consumption favors portability while therapeutic dosing prioritizes precision and bioavailability.
- Capsule:Hard-shell and soft-gel formats deliver precise colony-forming unit counts and protect acid-sensitive strains through enteric coating. Pharmacy and practitioner channels absorb volume where dosing accuracy outweighs convenience premiums.
- Liquid:Pediatric and geriatric applications favor suspension formats with adjustable dosing flexibility. German and Dutch infant formula manufacturers adopt precision-fermented prebiotic liquids at pilot scale.
- Powder:Bulk formats serve smoothie additive and institutional foodservice applications with cost efficiency.
- Bar:Meal-replacement and snack positioning captures convenience-oriented demand in athletic and travel contexts.
Capsules dominate installed base. Liquid formats are where expansion concentrates.
End User:
Customer type segmentation determines regulatory pathway and messaging strategy. Pediatric and elderly applications trigger stricter safety documentation while athletic positioning emphasizes performance claims.
- Elderly:Sarcopenia and immune senescence applications drive medical nutrition channel penetration. Abbott Laboratories anchors positioning through hospital discharge and long-term care protocols with reimbursable product codes.
- Children:Age-appropriate synbiotic dosing formats remain underdeveloped in North American mass retail, creating white space for pediatric formulation specialists. Nestle S.A competes via broad retail distribution and pediatric specialization.
- Individuals:General wellness positioning saturates mass retail with commodity competition and private-label pressure.
- Athletes:Sports nutrition specialty retail and team procurement channels absorb volume with batch-tested certification requirements.
Individuals dominate installed base. Children are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-fermented prebiotic ingredients to Dutch infant formula manufacturers, establishing a North European trade corridor that channels bioactive supply into Atlantic distribution networks.
United States
Health-conscious millennials in urban coastal markets drive probiotic-enriched product adoption through pharmacy and natural retail channels. FDA updated dietary supplement labeling requirements reshape formulation standards and compliance costs. Greater Boston hosts precision fermentation startups developing human-identical milk oligosaccharides for pediatric applications.
Germany
Discounter penetration of fortified dairy creates unmatched volume absorption capacity across European retail. EFSA Article 13.1 health claims authorization enables defensible immune function positioning for specific vitamin formulations. Bavaria anchors functional food manufacturing clusters with concentrated dairy processing infrastructure.
Netherlands
Infant formula manufacturers adopt precision-fermented prebiotic liquids at pilot scale for next-generation synbiotic development. REACH chemical safety protocols govern novel bioactive ingredient registration timelines. Wageningen University research corridors accelerate strain characterization and clinical validation partnerships.
France
Dairy conglomerates consolidate clinical research assets through pre-competitive consortia pooling intervention study costs. ANSM pharmaceutical oversight extends to medical food classifications affecting hospital discharge protocols. Paris basin research clusters coordinate genomic strain characterization for EFSA compliance.
United Kingdom
Registered dietitian networks drive trial conversion for synbiotic supplements through functional medicine clinic channels. MHRA borderline product classifications create regulatory uncertainty for postbiotic metabolite formulations. London health practitioner endorsement channels displace mass-media advertising for premium immunity positioning.
Immunity Boosting Food Market Vendor Landscape
Listed leaders compete with private specialists across refrigerated distribution networks and practitioner endorsement channels. The vendor base separates into multinational conglomerates with broad retail penetration, regional dairy specialists with fermentation expertise, and biotech-enabled ingredient suppliers collapsing development timelines. Three strategic archetypes dominate: medical-channel nutrition anchors, retail distribution generalists, and precision fermentation technology specialists. Competitive moves concentrate on clinical research asset consolidation and direct-to-subscription channel bypass of traditional grocery slotting.
Within the medical-channel tier, Abbott Laboratories anchors hospital discharge and long-term care protocols. Danone SA and Nestle S.A occupy positions spanning retail distribution breadth and pediatric formulation specialization. These three represent divergent competitive vectors: reimbursable medical nutrition codes, European fermented dairy shelf presence, and mass-market household penetration with age-appropriate dosing formats.
| Leading Market Players |
|---|
| Cargill Inc. |
| Archer Daniels Midland Company |
| PepsiCo Inc. |
| The Kraft Heinz Company |
| Abbott Laboratories |
| Danone SA |
| Unilever plc. |
| Olam International |
| Nestle S.A |
| Others |
Supply Flow & Price Mechanics
Cold-chain fermentation capacity utilization above 85% in Bavaria and Wisconsin shapes both supply concentration and price floors for live-culture probiotics. Scale economies at these hubs compress marginal production costs while creating barriers for ambient-stable postbiotic alternatives seeking volume parity.
Pricing Analysis
Next-generation precision-fermented human-identical milk oligosaccharides command 40-60% premiums over conventional dairy-derived prebiotics, while legacy whey permeate formulations face commoditization. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade strains with genomic characterization from private-label discounter offerings. Price differentiation hinges on EFSA Article 13.1 claim authorization and USDA Organic certification tier. Pricing pressure stems from German discounter private-label absorption of fermented dairy volume. Mass retail consumers exhibit highest price sensitivity; practitioner-channel buyers prioritize clinical validation over cost.
Supply Chain Analysis
Live culture supply concentration in Denmark, Germany, and Wisconsin creates single-source vulnerability for high-potency probiotic fermentation. Whey protein isolate and specialized growth media feed from dairy commodity cycles in New Zealand and the Netherlands. Tariff exposure on precision-fermentation equipment from Dutch and Irish infant formula manufacturers amplifies input cost volatility. Distribution runs through refrigerated pharmacy chains and direct-to-subscription channels bypassing traditional grocery slotting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The immunity boosting food market tracks a cyclical recovery driven by post-pandemic sustained investment in preventive health infrastructure. EFSA regulatory tightening and FDA labeling updates compress margins during the adjustment phase before clinical-validation premiums stabilize.
For Market Incumbents: Consolidate clinical research assets through pre-competitive consortia pooling intervention study costs against EFSA genomic characterization requirements. Acquire precision-fermentation capabilities in Greater Boston or Wageningen corridors to secure next-generation prebiotic supply. Backward integration into human-identical milk oligosaccharide production reduces dependency on dairy commodity cycles.
For New Entrants and Emerging Players: Lead with pediatric synbiotic dosing formats in North American mass retail, the most penetrable white space lacking age-appropriate formulations. Target registered dietitian endorsement networks in the United Kingdom and United States where clinician education budgets displace legacy retail slotting. Deploy direct-to-subscription models integrating personalized microbiome testing to bypass refrigerated distribution barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among biotech-enabled ingredient suppliers with precision-fermentation platforms and practitioner-channel subscription integrations. Long-term viability over the next decade favors defensible positioning through EFSA-authorized health claims and cold-chain logistics mastery. Watch WHO guidance shifts on strain-specific efficacy as the critical inflection signal determining which ingredient investments retain regulatory defensibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Research Asset Consolidation | Pools EFSA-compliant intervention study costs across German and French dairy conglomerates. |
| Precision Fermentation Scale-Up | Decomposes traditional dairy-derived prebiotic supply structures in Netherlands infant formula manufacturing. |
| Direct-to-Subscription Channel Launch | Bypasses refrigerated grocery slotting fees through microbiome-testing-integrated recurring revenue models. |
| USDA Organic Certification Investment | Captures price premiums in North American natural specialty retail and co-op networks. |
| Pediatric Formulation Development | Addresses underdeveloped age-appropriate synbiotic dosing formats in mass retail channels. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with fermentation technologists, regulatory affairs leads at dairy conglomerates, pharmacy chain category buyers, and functional medicine clinicians; and secondary validation against EFSA health claim registers, FDA dietary supplement labeling guidance, USDA organic certification databases, and refrigerated logistics trade data. Bottom-up volume modeling triangulated against top-down expenditure flow analysis.
Across the projection horizon, the analytical framework segmented value and volume by product type, ingredient category, delivery form, end-user demographic, and distribution channel. CAGRs derived from trend extrapolation anchored in documented clinical trial pipelines and regulatory authorization timelines. Modeled inputs incorporated EFSA Article 13.1 claim approval trajectories and precision-fermentation capacity buildout schedules.
The analysis sits within stated boundaries; outcomes outside sustained EFSA regulatory tightening or disrupted cold-chain infrastructure would require recalibration. Forecasts reflect documented assumptions on strain-specific efficacy validation and dairy commodity input trajectories. Practitioners should keep alternative scenarios live as WHO probiotic guidance positions and precision-fermentation cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Red Yeast Rice Market
Nutritional Supplements
Concentrate Protein Market
Nutritional Supplements
Marine Collagen Powder Market
Nutritional Supplements
Global Hemp Protein Market
Nutritional Supplements
Bone Broth Protein Market
Nutritional Supplements
Austria Protein Supplements Market
Nutritional Supplements
Hangover Cure Products Market
Nutritional Supplements
Spirulina Powder Market
Nutritional Supplements
Ashwagandha Market
Nutritional Supplements
Vegan Protein Powder Market
Nutritional Supplements
Protein Powder Market
Nutritional Supplements
Medium Chain Triglyceride (MCT) Diet Market
Nutritional Supplements
Low-Carb Fat Loss Market
Nutritional Supplements
Krill Oil Supplements Market
Nutritional Supplements
Lactoferrin Market
Nutritional Supplements
Green Food Supplements Market