
 India Whey Protein Market | 2026-2036
India Whey Protein Market Size, Share, and Industry Trends Forecast 2026-2036
India Whey Protein Market Foresight
India is reconfiguring whey protein supply dynamics through expanding domestic dairy processing capacity in Gujarat and Punjab. Glanbia PLC leverages its Irish dairy heritage to sustain premium isolate imports into Indian metro markets. Parag Milk Foods Ltd anchors its position through backward integration into cheese manufacturing, yielding captive whey streams. MuscleBlaze competes aggressively on channel control, dominating online storefronts with direct-to-consumer subscription models.
Whey protein comprises the globular protein fraction isolated from milk during cheese production, typically containing beta-lactoglobulin, alpha-lactalbumin, and immunoglobulins with protein concentrations ranging from 35% to 90% depending on processing grade; its primary commercial purpose centers on delivering complete amino acid profiles for muscle protein synthesis and recovery applications. Concentrate variants occupy the volume-heavy entry tier due to lower production costs and broader accessibility, while isolate segments command margin pools among lactose-intolerant consumers seeking higher purity. Sports nutrition applications lead absolute consumption, though clinical nutrition channels for post-surgical recovery and geriatric care represent the fastest-growing demand vector.
FSSAI standards govern protein content claims and contaminant thresholds for all domestic whey products, while BIS certification requirements shape import quality benchmarks for foreign suppliers seeking Indian market access. The PLI scheme for food processing infrastructure indirectly subsidizes domestic whey fractionation capacity expansion, altering cost structures for local manufacturers. Stakeholders must monitor evolving FSSAI draft regulations on novel protein blends and adapt formulation pipelines accordingly.
Market Dynamics
FSSAI's tightened nutritional labeling norms are compressing formulation cycles across India's whey protein landscape, forcing manufacturers to recertify product lines and accelerate purity testing protocols.
Growth Catalysts
- FSSAI Labeling Mandates:Stricter protein content verification requirements are elevating quality thresholds and filtering out substandard imports from unregulated suppliers.
- Tier-2 City Gym Penetration:Fitness infrastructure expansion in Pune, Jaipur, and Lucknow is creating first-time whey consumers outside traditional metro strongholds.
- PLI Scheme Subsidies:Food processing infrastructure incentives are lowering capital barriers for domestic whey fractionation facilities in Gujarat and Punjab.
Market Restraints
- Skim Milk Powder Price Volatility:Input cost swings in dairy commodities squeeze margin pools for concentrate-grade producers dependent on spot market sourcing.
- Import Concentration Risk:Premium isolate supply chains remain tethered to Irish and American processing facilities, exposing buyers to currency fluctuation and shipping disruption.
- Lactose Intolerance Prevalence:Digestive sensitivity among Indian consumers limits addressable market for concentrate variants and pushes demand toward higher-cost isolate grades.
Strategic Opportunities
- Clinical Nutrition Channels:Post-surgical recovery and geriatric care applications represent underdeveloped demand vectors with limited specialized competition.
- Direct-to-Consumer Subscription Models:Online storefronts with automated replenishment are capturing repeat purchase behavior among urban fitness enthusiasts.
- Backward Integration into Cheese Manufacturing:Captive whey stream generation through in-house dairy processing insulates against raw material price cycles.
Industry Challenges
- FSSAI Certification Timelines:Extended approval windows for novel protein blends delay product launches and compress revenue recognition cycles.
- Cold Chain Infrastructure Gaps:Temperature-controlled logistics deficiencies in tier-3 cities limit distribution reach for moisture-sensitive isolate products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Whey Protein Market |
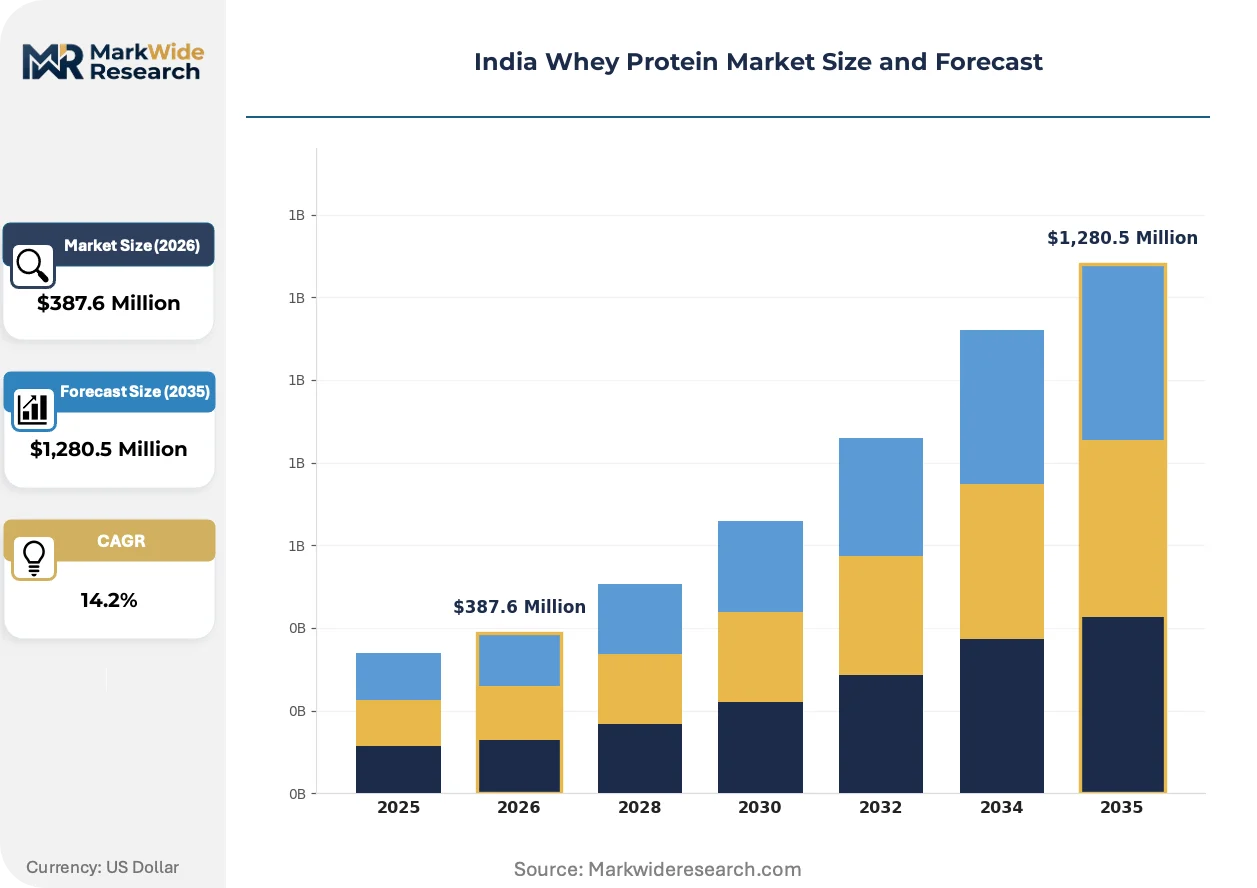
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Isolate, Hydrolysate, Blends Application: Sports Nutrition, Dietary Supplements, Food and Beverages, Clinical Nutrition End User: Athletes, Bodybuilders, Health Conscious Consumers, Fitness Enthusiasts Distribution Channel: Online Stores, Supermarkets, Health Food Stores, Specialty Stores |
| Companies Covered | Optimum Nutrition (Glanbia Performance Nutrition), Nestlé India Limited, Parag Milk Foods Ltd, Amway India Enterprises Pvt. Ltd, Herbalife Nutrition Ltd, Gujarat Cooperative Milk Marketing Federation, MuscleBlaze, MyFitFuel, Glanbia PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Whey Protein Market Shifts & Advancements
Cross-flow microfiltration and ion-exchange processing are redefining purity benchmarks across India's whey protein supply base. These technical advances compress production costs while elevating protein concentration ratios.
Membrane-based fractionation systems are rendering obsolete traditional heat-based denaturation methods that degraded bioactive protein fractions. Premium sports nutrition brands in Mumbai and Bangalore are adopting these systems at accelerating rates. The shift is compressing price premiums between concentrate and isolate grades while forcing legacy thermal processors into commodity positioning.
FSSAI draft regulations on novel protein blends are mandating expanded contaminant testing panels and traceability documentation for all domestic manufacturers. The industrial consequence is a bifurcation between compliant facilities with in-house laboratories and import-dependent brands facing extended clearance delays. Maharashtra-based processors with existing BIS certification infrastructure are adapting fastest, while smaller Gujarat facilities face consolidation pressure.
Subscription-based replenishment models are displacing traditional retail pharmacy and gym counter distribution among metropolitan consumers. Direct-to-consumer channels with AI-driven consumption forecasting are capturing loyalty through personalized dosage recommendations. This behavioral pivot is most visible in Karnataka's Bangalore cluster, where digital-native fitness platforms bundle protein with training protocols.
India Whey Protein Market Segmentation
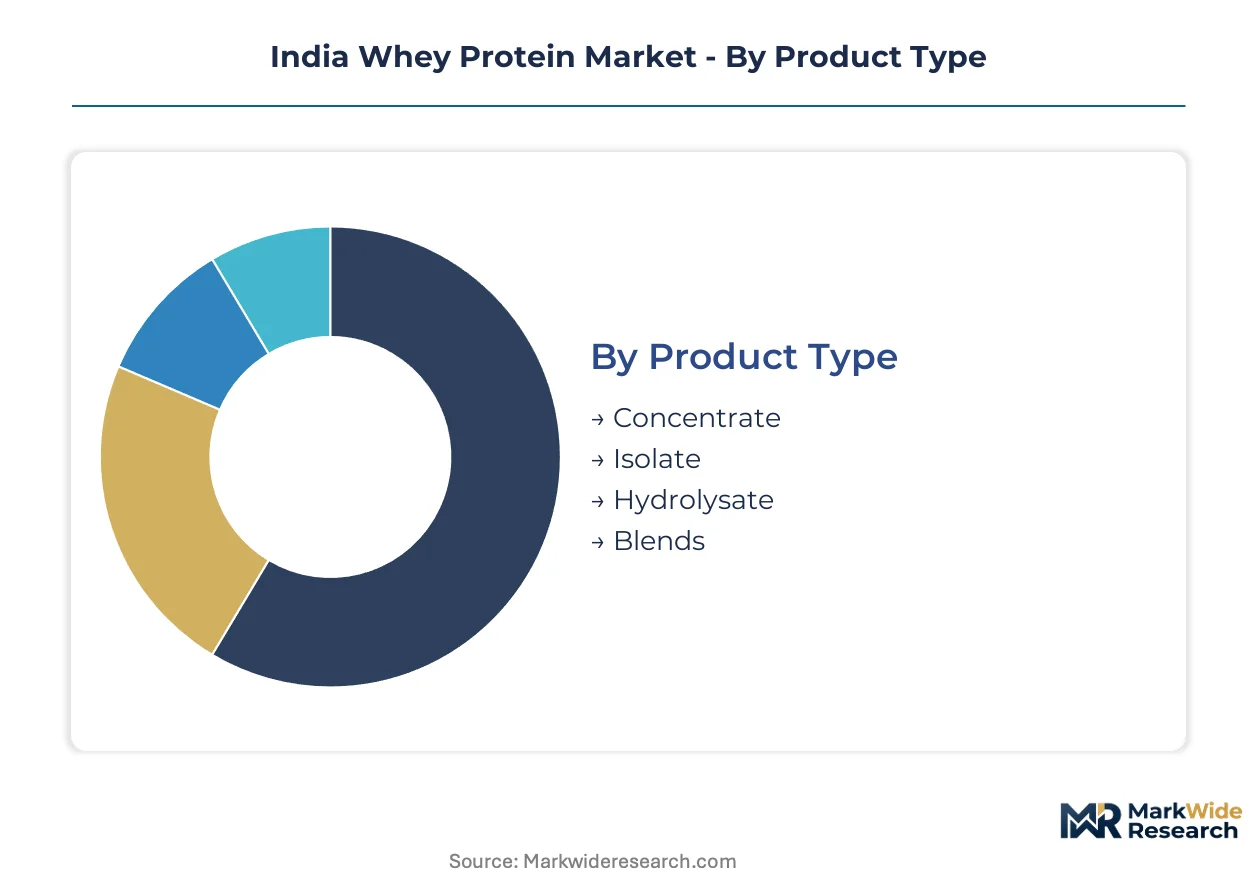
Segmentation in India's whey protein market reveals distinct demand physics across purity grades, use cases, and channel economics. Each dimension carries unique regulatory exposure and margin architecture that shapes competitive positioning.
Product Type:
Use-case spectrum spans from cost-sensitive mass-market formulations to precision nutrition for metabolic constraints.
- Concentrate:Contains 35-80% protein with retained lactose and milk fats, making it the entry-grade workhorse for price-conscious gym-goers in tier-2 cities. Demand concentrates in Maharashtra's fitness infrastructure where volume purchasing by gym chains drives procurement.
- Isolate:Achieves 90%+ protein purity through cross-flow microfiltration, eliminating lactose for consumers with digestive sensitivity. Adoption is climbing fastest among Bangalore's tech workforce seeking premium recovery solutions without gastrointestinal compromise.
- Hydrolysate:Pre-digested protein fragments enable rapid absorption for post-surgical clinical protocols.
- Blends:Custom ratios of concentrate and isolate balance cost-performance for hybrid positioning.
Established volume favors Concentrate; emerging adoption favors Isolate.
Application:
Channel economics diverge sharply between performance-driven consumption and medical-grade requirements.
- Sports Nutrition:Dominates absolute consumption through protein powders, bars, and ready-to-drink formats targeting resistance training protocols. Maharashtra and Karnataka absorb the majority of volume through metropolitan gym networks and e-commerce fulfillment centers.
- Dietary Supplements:General wellness positioning captures occasional users seeking meal replacement or weight management support.
- Food and Beverages:Functional fortification in dairy alternatives and baked goods expands addressable occasions beyond dedicated supplement use.
- Clinical Nutrition:Post-surgical recovery and geriatric sarcopenia management represent the steepest expansion trajectory, with limited specialized competition creating margin pools for FSSAI-certified medical nutrition suppliers.
Volume leadership sits with Sports Nutrition; margin expansion concentrates in Clinical Nutrition.
End User:
User sophistication determines willingness to pay for certification transparency and sourcing traceability.
- Fitness Enthusiasts:The fastest-expanding cohort as gym penetration deepens in Pune, Jaipur, and Lucknow beyond traditional metro strongholds. Subscription-based replenishment models capture loyalty through personalized dosage algorithms.
- Athletes:Competitive and semi-professional performers demand batch-tested products with contaminant documentation for anti-doping compliance.
- Bodybuilders:High-volume consumers prioritize protein-per-rupee efficiency and flavor palatability over purity premiums.
- Health Conscious Consumers:Occasional users with limited category knowledge depend on FSSAI labeling for purchase confidence.
Frequency economics favor Fitness Enthusiasts; per-unit spend peaks with Athletes.
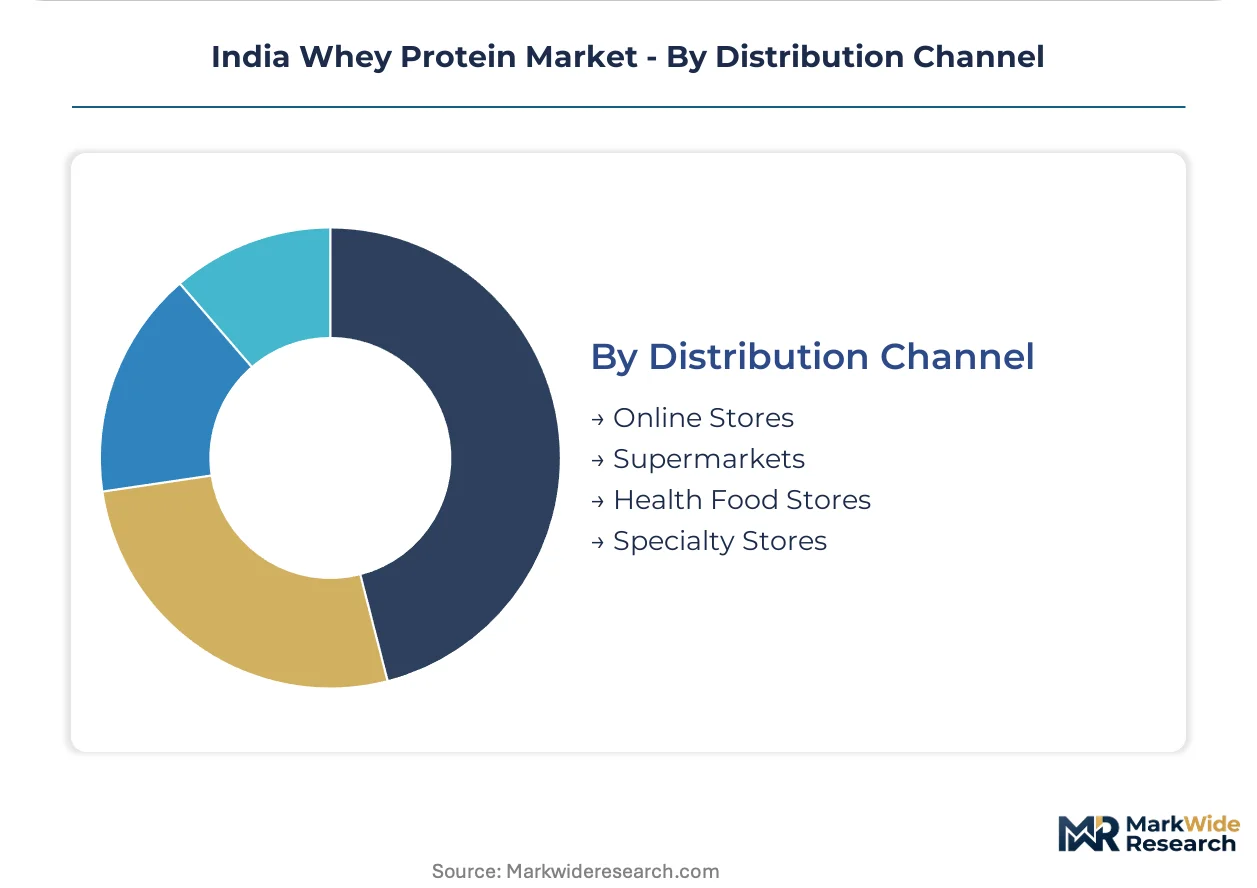
Distribution Channel:
Channel control determines customer data access and margin retention in a market shifting toward direct relationships.
- Online Stores:Direct-to-consumer platforms with automated replenishment are displacing traditional retail among urban consumers. Karnataka's Bangalore cluster leads this behavioral pivot through digital-native fitness platforms bundling protein with training protocols.
- Supermarkets:Mass-market visibility drives trial among first-time purchasers with limited category knowledge.
- Health Food Stores:Staff consultation supports premium isolate sales to lactose-intolerant consumers seeking guidance.
- Specialty Stores:Gym-affiliated counters retain relevance for immediate post-workout consumption occasions.
Customer acquisition efficiency favors Online Stores; conversion assistance concentrates in Health Food Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic whey fractionation capacity clusters in Gujarat and Punjab, where dairy cooperative infrastructure and PLI scheme subsidies converge. Maharashtra and Karnataka absorb the majority of finished product demand through metropolitan fitness networks and e-commerce fulfillment density.
Maharashtra
Mumbai and Pune gym chains drive concentrate-grade volume through institutional procurement contracts. FSSAI certification requirements filter substandard imports at Nhava Sheva port, elevating compliance costs for foreign suppliers. The Mumbai metropolitan cluster hosts premium isolate distribution hubs serving lactose-intolerant consumers in western India.
Gujarat
Amul's cooperative dairy network generates captive whey streams from cheese manufacturing operations in Anand and surrounding districts. State-level food processing incentives under the PLI scheme subsidize fractionation facility expansion in the Sabarkantha and Mehsana belts. Domestic concentrate production from these facilities undercuts imported alternatives on landed cost.
Karnataka
Bangalore's tech workforce sustains premium isolate adoption through direct-to-consumer subscription platforms. BIS certification requirements shape import quality benchmarks for Irish and American suppliers accessing the market. The city's digital-native fitness ecosystem bundles protein products with personalized training protocols, capturing repeat purchase loyalty.
Punjab
Verka and other cooperative dairy processors leverage surplus milk availability to expand whey recovery operations in Ludhiana and Jalandhar districts. FSSAI labeling mandates compel domestic manufacturers to accelerate purity testing protocol implementation. These facilities supply concentrate-grade material to northern Indian gym networks and supplement brands.
Delhi-NCR
The National Capital Region concentrates clinical nutrition demand from post-surgical recovery centers and geriatric care facilities. CDSCO medical nutrition regulations intersect with FSSAI supplement standards, creating dual compliance requirements for specialized whey formulations. Gurugram-based health food retailers curate premium isolate selections for affluent consumers seeking digestive tolerance.
India Whey Protein Market Competitive Landscape
International dairy conglomerates and domestic dairy cooperatives split the market into premium import-dependent and cost-optimized local supply tiers. Concentration remains moderate, with no single entity commanding decisive share across all purity grades and distribution channels. Three strategic archetypes dominate: Irish-American multinationals leveraging heritage positioning, Indian dairy cooperatives exploiting backward integration into cheese manufacturing, and digital-native brands capturing direct-to-consumer subscription economics. Competitive moves center on certification speed under tightening FSSAI norms and cold chain infrastructure expansion into tier-2 cities.
Among Irish-domiciled dairy processors, Glanbia PLC exemplifies the heritage-import archetype through sustained premium isolate positioning. Parag Milk Foods Ltd occupies the integrated domestic tier, anchoring supply security through captive whey generation from in-house cheese operations. MuscleBlaze represents the digital-native vector, dominating online storefronts with automated replenishment models that capture metropolitan fitness enthusiast loyalty.
| Leading Market Players |
|---|
| Optimum Nutrition (Glanbia Performance Nutrition) |
| Nestlé India Limited |
| Parag Milk Foods Ltd |
| Amway India Enterprises Pvt. Ltd |
| Herbalife Nutrition Ltd |
| Gujarat Cooperative Milk Marketing Federation |
| MuscleBlaze |
| MyFitFuel |
| Glanbia PLC |
| Others |
Supply & Pricing Matrix
Import concentration risk from Irish and American processing facilities determines both the premium-to-concentrate price spread and the three-tier supply chain configuration spanning captive domestic streams, contracted imports, and spot-market sourcing. FSSAI certification timelines compress margin pools for brands dependent on foreign isolate while rewarding backward-integrated domestic cheese manufacturers with cost insulation.
Pricing Analysis
FSSAI labeling mandates dictate the pricing tier structure across India's whey protein landscape. Three-tier pricing structure across premium isolate, standard concentrate, and economy-grade blends separates certified medical nutrition suppliers from gym-chain commodity suppliers. Price differentiation rests on purity grade and BIS certification level, with lactose-free isolate commanding substantial premiums over concentrate. Cost compression in the concentrate tier is intensifying because skim milk powder spot market volatility squeezes margin pools for non-integrated producers. First-time gym consumers in tier-2 cities exhibit highest price sensitivity, while Bangalore's tech workforce demonstrates lowest elasticity for certified isolate.
Supply Chain Analysis
Cheese manufacturing operations in Ireland and the United States feed premium isolate streams into Indian metro markets. Raw material dependencies center on skim milk powder spot markets, cross-flow microfiltration membrane systems, and cold chain logistics capacity. Supply chain risk concentrates in single-source vulnerability for isolate-grade imports exposed to currency fluctuation and shipping disruption. Distribution runs through direct-to-consumer subscription platforms, gym-affiliated specialty counters, and health food retail consultation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's whey protein market sits in an early-cycle expansion phase as clinical nutrition applications penetrate post-surgical recovery protocols and geriatric care facilities beyond traditional sports nutrition dominance.
For Market Incumbents: Pre-empt FSSAI regulatory tightening by accelerating in-house laboratory investments and BIS certification infrastructure ahead of draft novel protein blend requirements. Captive whey stream generation through backward integration into cheese manufacturing insulates margin position against skim milk powder volatility. Channel control through direct-to-consumer subscription models with AI-driven replenishment locks in metropolitan fitness enthusiast loyalty before digital-native competitors scale.
For New Entrants and Emerging Players: Build out clinical nutrition specialization targeting post-surgical recovery and geriatric sarcopenia management where limited competition creates margin pools for FSSAI-certified medical nutrition suppliers. Pune and Jaipur gym networks represent the most penetrable geography as fitness infrastructure expands beyond saturated Bangalore and Mumbai clusters. Partner with digital-native fitness platforms bundling protein with personalized training protocols to bypass established retail pharmacy distribution.
For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors vertically integrated dairy cooperatives with captive whey streams and existing BIS certification infrastructure. Long-term viability over the next decade hinges on regulatory compliance speed and cold chain reach into tier-2 cities. Watch FSSAI finalization timelines on novel protein blend regulations as the signal for accelerated consolidation among import-dependent brands facing extended clearance delays.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cheese Manufacturing | Captive whey stream generation insulates Parag Milk Foods and GCMMF against raw material price cycles. |
| FSSAI Certification Infrastructure Investment | In-house laboratory capacity accelerates product launch timelines for Maharashtra-based processors ahead of draft regulations. |
| Direct-to-Consumer Subscription Launch | Automated replenishment with AI-driven dosing captures repeat purchase behavior among Bangalore's tech workforce. |
| Clinical Nutrition Channel Expansion | Post-surgical recovery specialization opens margin pools in Delhi-NCR geriatric care facilities with limited competition. |
| Cold Chain Infrastructure Partnership | Temperature-controlled logistics into tier-2 cities extends isolate distribution reach beyond moisture-sensitive constraints. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with dairy processing executives, FSSAI regulatory affairs leads, gym chain procurement managers, and clinical nutrition specialists; and secondary validation through FSSAI filings, BIS certification databases, PLI scheme disclosures, and customs import records. Bottom-up triangulation against top-down market sizing cross-checked volume estimates from domestic fractionation capacity in Gujarat and Punjab against metropolitan demand clusters in Maharashtra and Karnataka.
Forecast inputs span product type segmentation across concentrate, isolate, hydrolysate, and blend grades; application channels from sports nutrition through clinical protocols; and end-user sophistication tiers from first-time gym consumers to competitive athletes. CAGRs were derived from trajectory analysis of gym penetration rates in tier-2 cities, PLI subsidy uptake curves, and FSSAI compliance cost modeling. Dairy commodity price cycle assumptions and membrane technology adoption curves shaped isolate-to-concentrate mix projections.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Irish multinationals or accelerated PLI scheme uptake by domestic cooperatives would shift outcomes. Cross-checking against Amul's cooperative production disclosures and Glanbia's regional import volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Canada Whey Protein Market
Nutritional Supplements
Global Adaptogens Market
Nutritional Supplements
North America Prenatal Supplements Market
Nutritional Supplements
Vitamin B3 Market
Nutritional Supplements
Spirulina Purple Blend Market
Nutritional Supplements
North America Digestive Health Supplements Market
Nutritional Supplements
Asia-Pacific Arachidonic Acid Market
Nutritional Supplements
Algae Omega Market
Nutritional Supplements
Nutritional Food and Drink Market
Nutritional Supplements
Microencapsulated Omega-3 Powders Market
Nutritional Supplements
South America Omega-3 Products Market
Nutritional Supplements
Algae Omega 3 Market
Nutritional Supplements
Japan Dietary Supplements Market
Nutritional Supplements
L Carnitine Market
Nutritional Supplements
Africa Beta Glucan Market
Nutritional Supplements
Andro Supplements Market