
 Marine Collagen Market | 2026-2036
Marine Collagen Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Collagen Market Intelligence
Asset-light contract manufacturing and toll-processing arrangements is tilting competitive dynamics toward brands without extraction infrastructure. Vital Proteins LLC leverages its direct-to-consumer channel strength to control premium positioning. Nitta Gelatin Inc. anchors Japanese supply through integrated marine sourcing and hydrolysis capabilities. Rousselot competes across European nutraceutical and pharmaceutical grades with specialized cod-skin processing.
Marine collagen denotes protein extracted from fish skin, scales, and bones, comprising primarily Type I collagen with glycine-proline-hydroxyproline amino acid sequences; manufacturers employ enzymatic hydrolysis at controlled temperature and pH to yield peptides with molecular weights below 10 kDa for enhanced bioavailability in dietary supplements and dermal formulations. Hydrolyzed collagen leads volume output due to its solubility and neutral sensory profile, while collagen peptides command premium pricing in sports nutrition and anti-aging cosmetics where bioactive signaling claims justify higher formulation costs. Gelatin retains stable demand in food applications though growth decelerates relative to peptide fractions.
EFSA novel food evaluations, FDA GRAS self-affirmation pathways, and MFDS functional ingredient registrations collectively determine market access timelines and label claim permissibility for marine-derived collagen products. REACH compliance for processing chemicals and EU Green Deal sourcing traceability requirements add compliance layers that favor vertically integrated extractors with documented supply chain custody. Stakeholders must monitor evolving marine stewardship certifications and fishery quota restrictions that could constrain raw material availability faster than demand normalization.
Market Dynamics
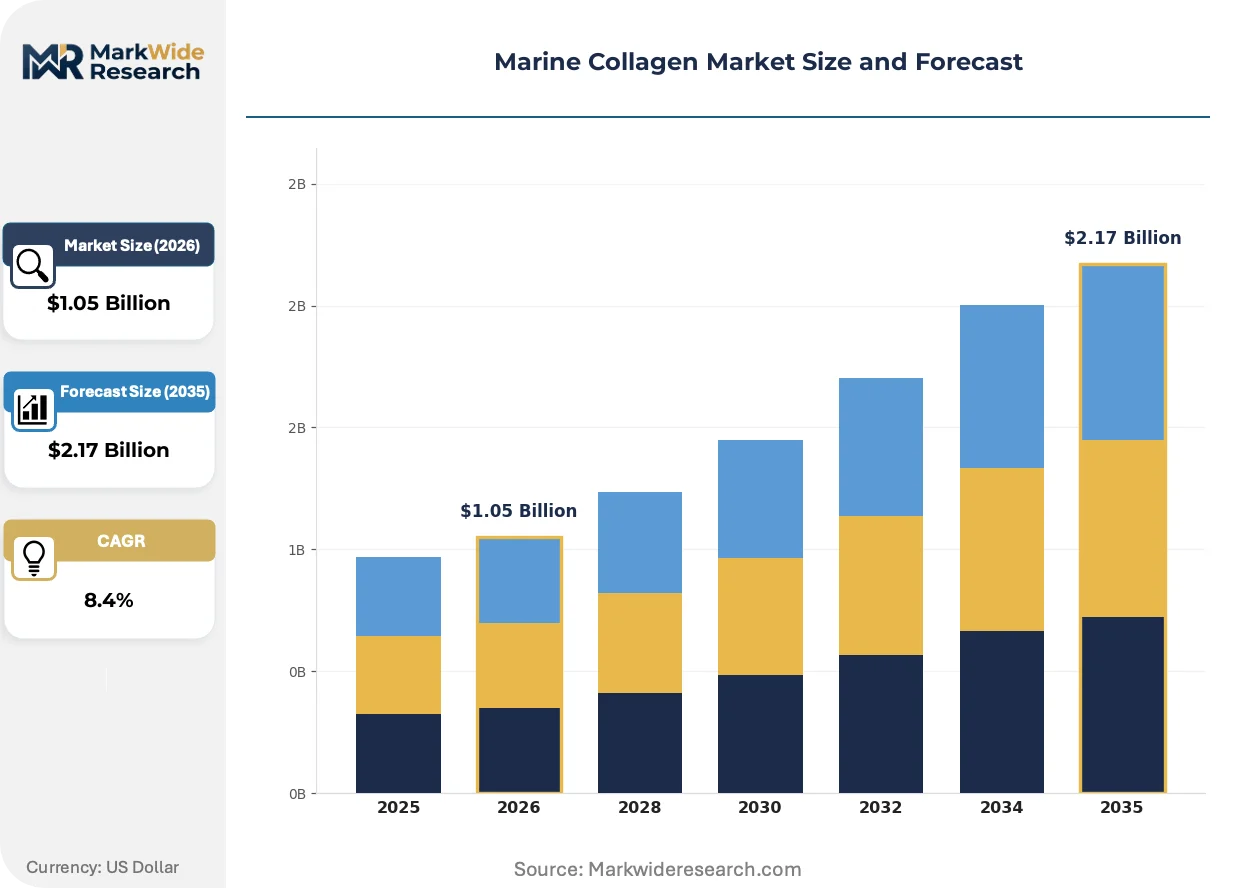
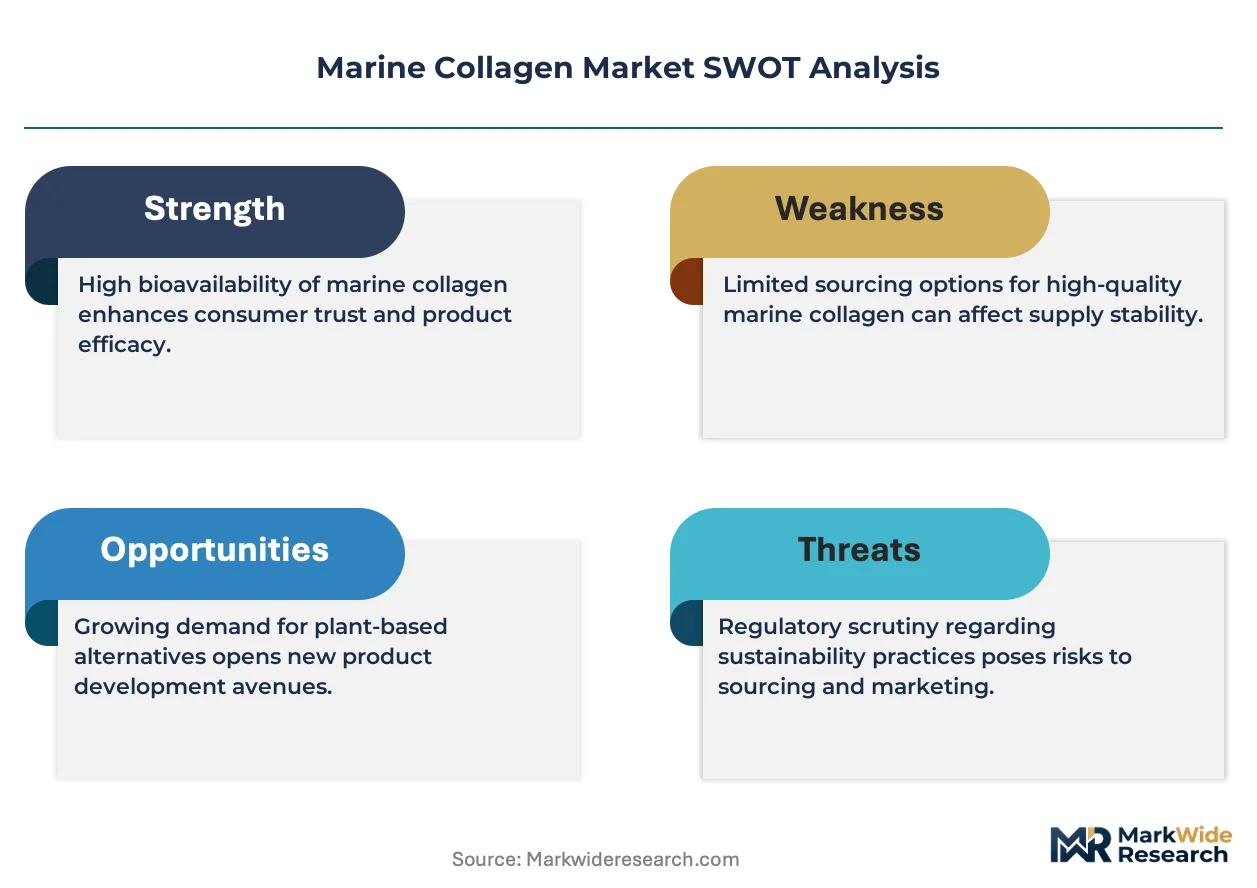
Asset-light contract manufacturing is tilting competitive dynamics toward brands without extraction infrastructure, while EFSA novel food evaluations and MFDS functional ingredient registrations determine which hydrolyzed collagen suppliers capture premium positioning in nutraceutical and cosmetic channels.
Growth Catalysts
- EFSA Novel Food Pathways:German and French nutraceutical manufacturers scale marine collagen procurement under streamlined safety evaluations, accelerating product launches across European functional food categories.
- South Korea's Functional Food Sector:MFDS approval requirements shape import access for hydrolyzed collagen peptides, concentrating demand among domestic formulators with established regulatory relationships.
- Enzymatic Hydrolysis Refinement:Controlled temperature and pH processing yields peptides below 10 kDa molecular weight, unlocking enhanced bioavailability claims in dermal and dietary supplement applications.
Market Restraints
- Fishery Quota Constraints:Marine stewardship certifications and raw material availability restrictions in North Atlantic cod fisheries threaten supply normalization faster than demand softening.
- REACH Compliance Burden:Processing chemical documentation and EU Green Deal traceability requirements add compliance layers that disadvantage non-integrated extractors lacking documented supply chain custody.
- Bovine-Porcine Substitution:Lower-cost mammalian collagen alternatives retain cost-sensitive food and pharmaceutical applications, compressing marine collagen penetration in price-driven segments.
Strategic Opportunities
- Cosmeceutical Bioactive Signaling:Collagen peptide premium positioning in anti-aging formulations justifies higher formulation costs where clinical substantiation supports dermal remodeling claims.
- Sports Nutrition Functionalization:Recovery and joint health applications represent underdeveloped white space for hydrolyzed marine collagen beyond traditional beauty positioning.
- Integrated Marine Sourcing:Japanese and Nordic extractors with captive fishery relationships and in-house hydrolysis capabilities capture margin expansion unavailable to toll-dependent competitors.
Industry Challenges
- Extraction Infrastructure Capex:Enzymatic processing equipment and cold-chain logistics require substantial capital deployment that strains mid-scale entrants without contract manufacturing partnerships.
- Cross-Border Certification Timelines:Divergent FDA GRAS self-affirmation, EFSA novel food, and MFDS registration pathways create fragmented market access timelines that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Collagen Market |
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Gelatin, Collagen Peptides, Marine Collagen Powder Application: Nutraceuticals, Cosmetics, Food & Beverage, Pharmaceuticals Customer Type: Health-Conscious Consumers, Athletes, Elderly, Beauty Enthusiasts Form: Liquid, Powder, Capsules, Gummies |
| Companies Covered | Vital Proteins LLC, Nitta Gelatin Inc., Ashland Inc., Rousselot, Norland Products Inc., Certified Nutraceuticals Inc., COBIOSA, Seagarden AS, Weishardt Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Collagen Market Strategic Shifts & Innovations
Digital traceability systems and precision fermentation alternatives are actively reshaping how marine collagen suppliers demonstrate provenance and sustainability credentials to institutional buyers.
Blockchain-enabled supply chain verification is digitizing custody documentation from fishery catch to finished peptide. European cosmetic and pharmaceutical manufacturers now require batch-level traceability as a procurement prerequisite. This technology is compressing supplier qualification cycles while raising barriers for extractors lacking real-time data infrastructure.
REACH compliance extensions under EU Green Deal sourcing mandates now require documented carbon intensity metrics for marine raw materials. German and French formulators face downstream liability exposure from undocumented supply chains. Cod-skin processors with integrated Nordic fishery relationships capture preferential supplier status under these disclosure requirements.
Direct-to-consumer subscription models are displacing traditional ingredient distributor relationships in premium collagen peptide segments. South Korean functional food brands and US wellness startups now prioritize channel control over wholesale margin preservation. This shift concentrates marketing investment in digital acquisition rather than trade promotion, favoring brands with proprietary consumer data capabilities.
Marine Collagen Market Segmentation
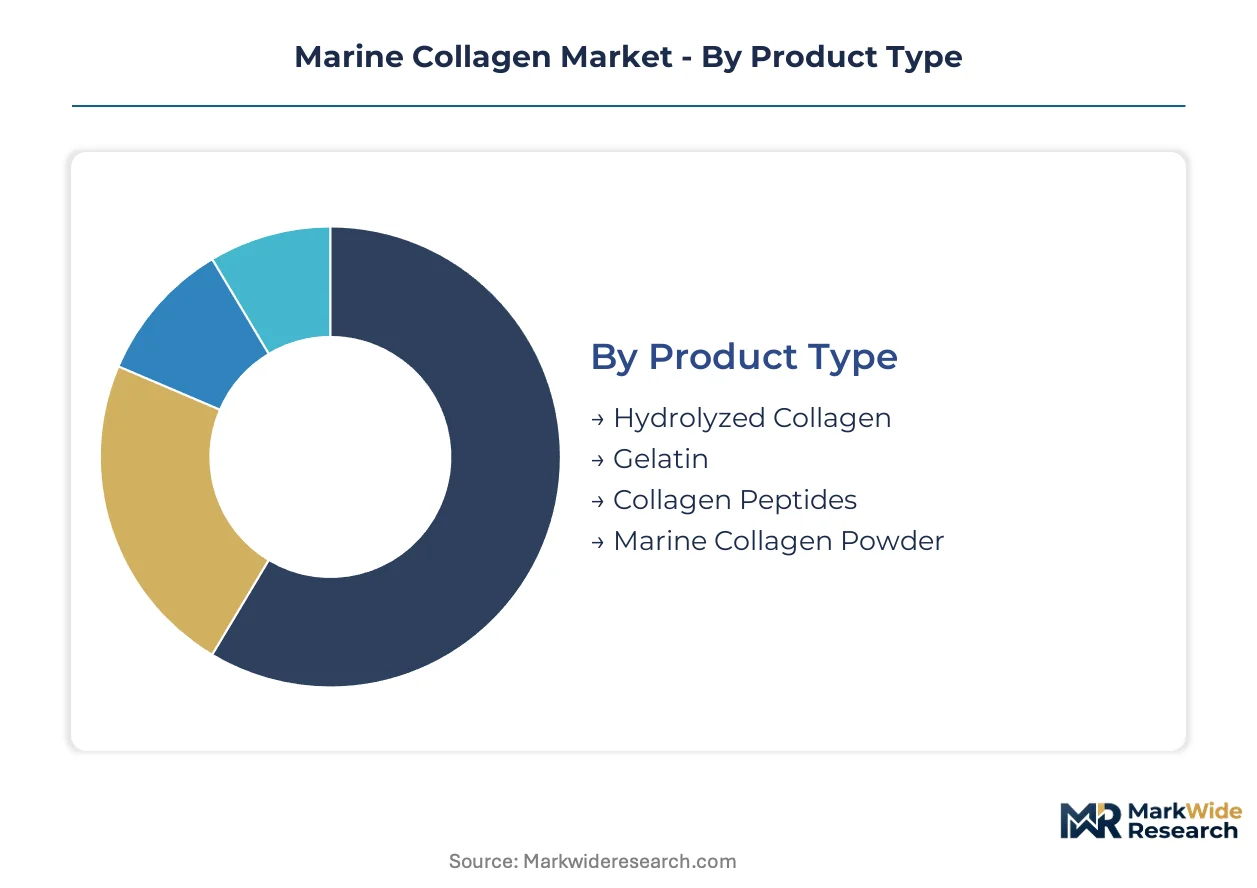
Segmentation in the marine collagen market determines procurement cycles, formulation costs, and regulatory pathways. Manufacturers align enzymatic processing capabilities with specific product tiers while distributors prioritize form factors that match channel velocity requirements.
Product Type:
Hydrolyzed collagen turns inventory fastest due to bulk nutraceutical contracts, while gelatin moves slowest through food-sector procurement cycles with longer tender timelines.
- Hydrolyzed Collagen:Enzymatic hydrolysis yields peptides below 10 kDa molecular weight with neutral taste and complete cold-water solubility. South Korean functional food manufacturers under MFDS registration requirements drive procurement concentration for bioavailability-focused formulations.
- Collagen Peptides:Bioactive signaling fractions command premium positioning in cosmeceutical applications where clinical substantiation supports dermal remodeling claims. German and French nutraceutical brands under EFSA novel food guidance scale peptide procurement for anti-aging positioning.
- Gelatin:Retains stable demand in confectionery and encapsulation applications with established food-grade specifications.
- Marine Collagen Powder:Bulk ingredient format serves contract manufacturers and private-label brands with formulation flexibility.
Hydrolyzed collagen anchors the volume base while collagen peptides gain share at the steepest rate.
Application:
Cost tiers separate premium-positioned channels from commodity food applications, with certification requirements and clinical substantiation costs determining margin capture.
- Nutraceuticals:Dietary supplements and functional foods represent the highest-margin application with peptide-grade specifications and bioavailability claims driving procurement decisions.
- Cosmetics:Dermal formulations require cosmetic-grade hydrolysis with documented molecular weight distribution and heavy metal testing protocols.
- Food & Beverage:Gelatin and lower-specification hydrolyzed fractions serve cost-sensitive applications with reduced purity requirements and higher volume throughput.
- Pharmaceuticals:Injectable and wound-care applications demand pharmaceutical-grade collagen with full batch documentation and GMP compliance.
Nutraceuticals command the steepest margin expansion while food and beverage applications provide the volume foundation.
Customer Type:
Demographic targeting shapes product development cycles, with athlete and beauty enthusiast segments driving innovation velocity compared to slower-turning elderly formulations.
- Beauty Enthusiasts:Anti-aging and skin hydration positioning commands premium pricing with peptide-grade products and subscription-based replenishment models.
- Athletes:Joint recovery and connective tissue support applications represent underdeveloped white space with sports nutrition brands expanding marine collagen SKUs.
- Health-Conscious Consumers:General wellness positioning targets clean-label preferences and sustainable sourcing credentials.
- Elderly:Bone density and mobility support applications require clinical substantiation for therapeutic claims with longer development timelines.
Beauty enthusiasts anchor current revenue concentration while athletes represent the expansion trajectory with steepest growth potential.
Form:
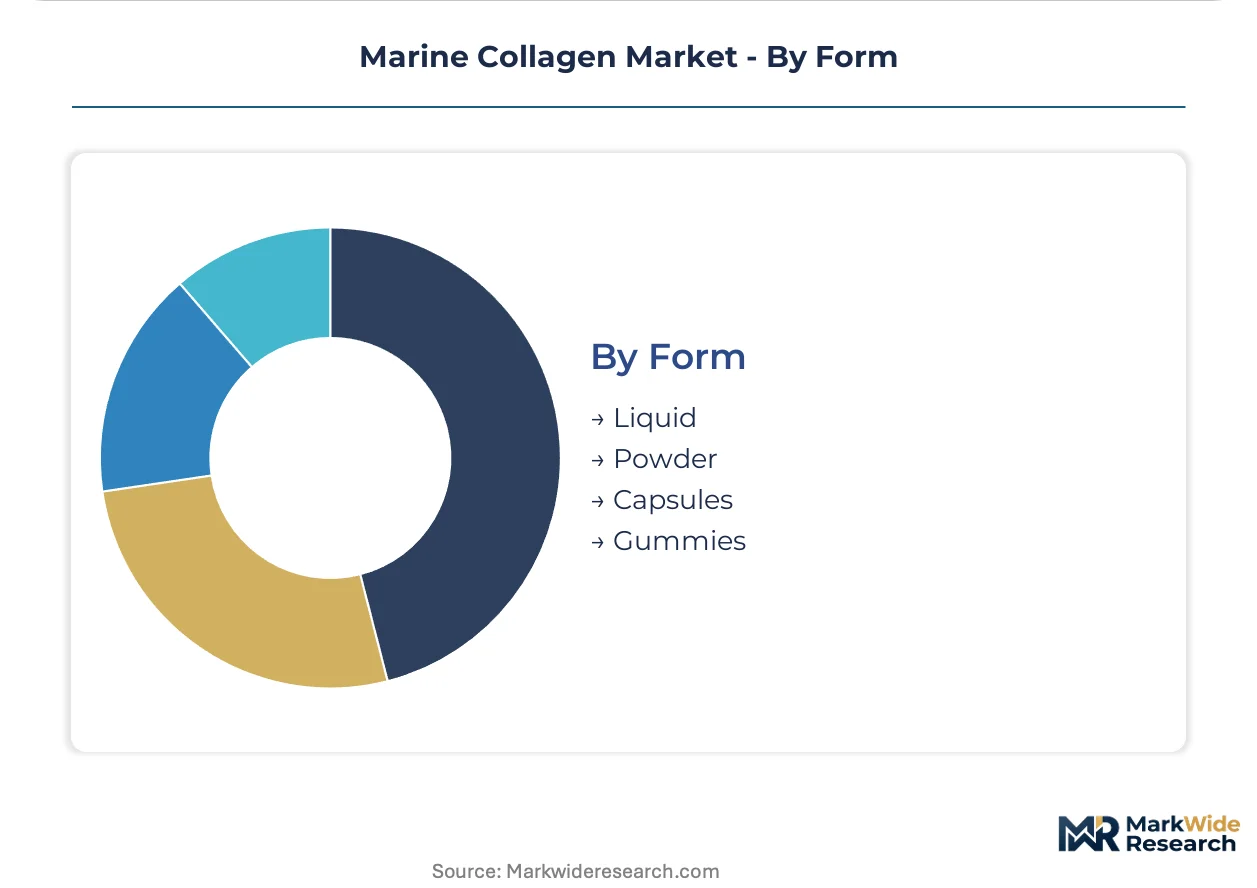
Supply concentration favors powder formats with established toll-processing infrastructure, while gummies and liquids require specialized manufacturing partnerships.
- Powder:Bulk format dominates B2B ingredient sales with flexible dosing and neutral sensory profile enabling diverse formulation applications.
- Capsules:Standardized dosing format serves pharmaceutical and premium nutraceutical channels with convenience positioning.
- Liquid:Ready-to-drink formulations require stability testing and preservative systems with shorter shelf life constraints.
- Gummies:Confectionery format demands specialized molding equipment and sugar-alternative formulations for clean-label positioning.
Powder formats anchor manufacturing scale while gummies climb the fastest as brands target convenience-driven consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine collagen trade flows concentrate in net-importing nutraceutical markets where domestic extraction capacity lags formulation demand. Export-oriented Nordic and Japanese processors supply hydrolyzed peptides to European and North American brands under divergent regulatory clearance timelines.
Germany
Nutraceutical manufacturers in Hamburg and Frankfurt scale marine collagen procurement for functional food launches under EFSA novel food guidance. The country's Federal Office of Consumer Protection and Food Safety enforces strict documentation requirements for imported hydrolyzed peptides. Bavarian contract manufacturers now dominate toll-processing arrangements for brands lacking in-house enzymatic hydrolysis infrastructure.
South Korea
Seoul-based functional food brands drive concentrated demand for low-molecular-weight collagen peptides under MFDS registration pathways. The Ministry of Food and Drug Safety maintains stringent import access protocols that favor established suppliers with documented bioavailability data. Busan-Ulsan industrial clusters host specialized hydrolysis facilities serving both domestic formulators and re-export markets.
United States
Direct-to-consumer wellness brands in California and New York source marine collagen peptides through FDA GRAS self-affirmation channels. The FDA's Center for Food Safety and Applied Nutrition oversees novel ingredient notifications without pre-market approval requirements. Pacific Northwest coastal processors extract from Alaskan pollock and Pacific cod fisheries with Marine Stewardship Council chain-of-custody certification.
France
Paris and Lyon cosmetic laboratories command premium peptide grades for anti-aging dermal formulations under ANSM cosmetic ingredient oversight. The French National Agency for Food, Environmental and Occupational Health Safety coordinates with EFSA on novel food safety evaluations. Brittany fishing ports supply raw cod skins to integrated extractors with documented carbon intensity metrics under EU Green Deal traceability mandates.
Japan
Tokyo-Osaka nutraceutical corridors sustain captive demand for domestically sourced marine collagen from coastal fishery cooperatives. The Ministry of Health, Labour and Welfare regulates functional food claims through Foods with Function Claims registration. Nagoya-based gelatin specialists maintain backward integration into Pacific saury and tuna processing byproduct streams.
Marine Collagen Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with enzymatic hydrolysis and fishery sourcing capabilities. The vendor base separates between asset-light brands dependent on toll-processing and vertically integrated extractors with captive raw material access. Three archetypes dominate: direct-to-consumer wellness platforms, integrated marine processors with Nordic or Japanese fishery relationships, and European pharmaceutical-grade specialists. Capacity expansion and supply chain custody documentation represent the dominant competitive moves as regulatory traceability requirements harden.
Within the integrated processor tier, Nitta Gelatin Inc. and Rousselot exemplify archetypes of geographic sourcing concentration and specialized cod-skin processing respectively. Vital Proteins LLC occupies a position as the direct-to-consumer platform archetype with channel control over premium positioning. These three companies represent the structural fault lines between extraction infrastructure ownership and brand-mediated market access.
| Leading Market Players |
|---|
| Vital Proteins LLC |
| Nitta Gelatin Inc. |
| Ashland Inc. |
| Rousselot |
| Norland Products Inc. |
| Certified Nutraceuticals Inc. |
| COBIOSA |
| Seagarden AS |
| Weishardt Group |
| Others |
Cost & Logistics Intelligence
Busan-Ulsan industrial clusters anchor Northeast Asian hydrolysis capacity, concentrating enzymatic processing expertise that translates into asymmetric pricing power for peptide-grade marine collagen over toll-dependent European brands.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, where pharmaceutical-grade certification and documented molecular weight distribution command substantial premiums over food-grade gelatin. Price differentiation rests on MFDS registration status and EFSA novel food clearance, with South Korean functional food manufacturers showing lowest price sensitivity due to regulatory compliance requirements. Cost compression in standard-grade hydrolyzed fractions is intensifying as Baltic and Vietnamese processors expand enzymatic capacity. Contract manufacturers serving private-label nutraceutical brands exhibit highest price sensitivity, squeezing margins on undifferentiated powder formats.
Supply Chain Analysis
Bavarian and Nagoya-based contract manufacturers hold dominant toll-processing capacity for brands lacking in-house enzymatic infrastructure. Raw material supply concentrates in Norway, Japan, and Vietnam, drawing from North Atlantic cod fisheries and Pacific tuna processing byproduct streams. The chain rests on fishery quota volatility under Marine Stewardship Council protocols and seasonal catch restrictions. Single-source vulnerability runs through Nordic cod-skin processors with captive fleet relationships. Distribution runs through direct-to-consumer subscription platforms displacing traditional ingredient distributors in premium peptide segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine collagen represents a high-growth disruption as precision fermentation alternatives and blockchain traceability systems simultaneously threaten incumbent extraction models while opening premium positioning for verified sustainable sourcing.
For Market Incumbents: Harden supply chain custody documentation through backward integration into certified fisheries or exclusive quota arrangements, as EU Green Deal traceability mandates and REACH compliance extensions threaten non-integrated extractors with downstream liability exposure. Invest in enzymatic hydrolysis capacity expansion at Busan-Ulsan or Nagoya clusters to capture margin expansion unavailable to toll-dependent competitors facing capacity constraints.
For New Entrants and Emerging Players: Pursue sports nutrition white space where marine collagen penetration remains underdeveloped relative to saturated beauty positioning, targeting athlete recovery and joint health applications with clinical substantiation partnerships. Enter through direct-to-consumer subscription models that displace wholesale distributor relationships, prioritizing proprietary consumer data capabilities over trade promotion investment.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated processors with captive fishery relationships and in-house hydrolysis capabilities over asset-light brands dependent on contract manufacturing. Long-term viability centers on documented supply chain custody and regulatory clearance portfolios rather than marketing spend efficiency. Monitor Marine Stewardship Council certification revocation patterns and EFSA novel food evaluation backlogs as inflection indicators for raw material access constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Fisheries | Captive raw material access secures margin expansion under EU Green Deal traceability mandates. |
| MFDS Novel Food Registration | Regulatory clearance unlocks premium positioning in South Korea's functional food procurement concentration. |
| Blockchain Supply Chain Verification | Batch-level traceability meets European cosmetic manufacturer procurement prerequisites. |
| Sports Nutrition SKU Expansion | Athlete recovery applications represent underdeveloped white space beyond traditional beauty positioning. |
| Direct-to-Consumer Platform Launch | Subscription models concentrate marketing investment in digital acquisition over trade promotion. |
Research Approach
Cross-validation between primary interviews with nutraceutical formulators, fishery cooperative managers, and cosmetic R&D directors and secondary validation through EFSA novel food filings, MFDS registration databases, and Marine Stewardship Council chain-of-custody records anchors the qualitative findings. Bottom-up demand modeling triangulates against top-down trade flow analysis from customs documentation and integrated processor capacity disclosures.
Calibration against historical volume trajectories and regulatory clearance timelines shapes the analytical framework across the projection horizon. Segmentation dimensions include product type tier, application grade specification, customer demographic target, and regional regulatory cluster. CAGRs derive from normalized growth rate convergence across enzymatic processing capacity expansion and functional food launch pipelines. Forecast inputs incorporate fishery quota allocation patterns and EFSA evaluation backlog durations.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending on premium wellness products and marine raw material commodity indices would shift the trajectory. Forecasts reflect assumptions around regulatory pathway efficiency and fishery stock sustainability. Quarterly review of EFSA novel food evaluation throughput and North Atlantic cod catch volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Nutrient Dense Food Products Market
Nutritional Supplements
Europe Collagen Supplements Market
Nutritional Supplements
Australia Protein Market
Nutritional Supplements
Australia Collagen Peptides Market
Nutritional Supplements
Europe Amino Acid in Dietary Supplements Market
Nutritional Supplements
Forskolin Market
Nutritional Supplements
Austria Protein Supplements Market
Nutritional Supplements
Asia-Pacific Amino Acid in Dietary Supplements Market
Nutritional Supplements
Nutraceutical Supplements Market
Nutritional Supplements
Lactoferrin Market
Nutritional Supplements
Mushroom Powders Market
Nutritional Supplements
Lutein Market
Nutritional Supplements
Algae Omega Market
Nutritional Supplements
Liquid Dietary Supplements Market
Nutritional Supplements
Cognition Supplements Market
Nutritional Supplements
Europe Moringa Supplement Market