
 High-Selenium Yeast Market | 2026-2036
High-Selenium Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
High-Selenium Yeast Market Insights
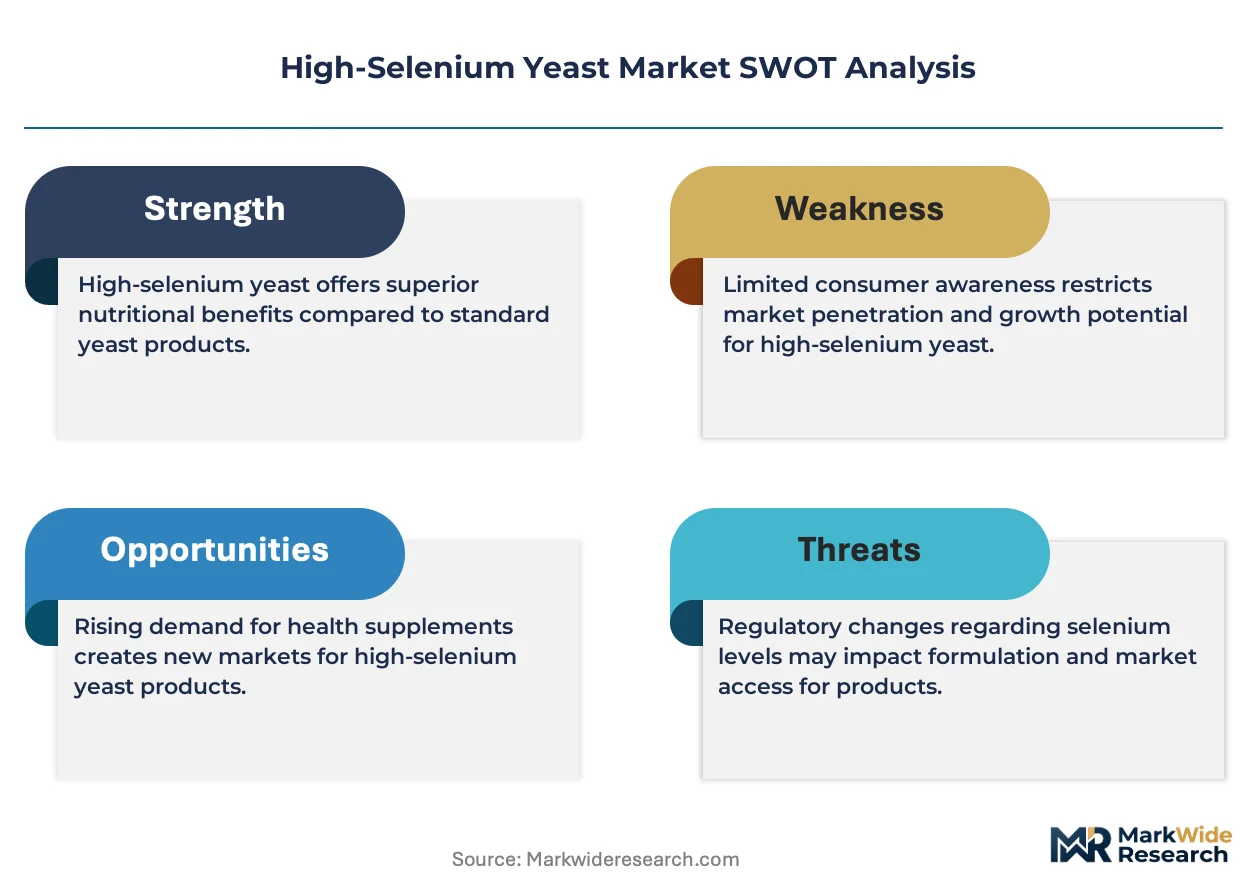
Specialized fermentation technologists is rotating toward high-selenium yeast strains as standard baker's yeast expertise proves insufficient for selenium bioaccumulation at commercial scale. Alltech Inc leverages its Kentucky-based research campus to sustain proprietary strain development programs. Lallemand Inc anchors North American supply through vertically integrated fermentation and drying assets. Lesaffre Group competes across European feed and human nutrition channels with differentiated organic selenium positioning.
High-selenium yeast comprises Saccharomyces cerevisiae cultivated in selenium-enriched media, typically achieving 1000–3000 ppm selenium content with 90%+ organic selenomethionine bioavailability for animal and human metabolic pathways. The product serves primarily as a bioavailable selenium source replacing sodium selenite in premix formulations where absorption efficiency determines nutritional outcome. Organic selenium products command premium positioning in nutraceutical and pharmaceutical applications where selenomethionine purity drives formulation value. Animal feed applications dominate volume throughput as livestock producers substitute inorganic sources under tightening residue regulations. Distribution through direct sales channels captures the largest margin pools by bypassing intermediaries in bulk feed additive procurement.
FDA GRAS status and USDA organic certification govern human-grade selenium yeast entry into United States dietary supplement channels, while EFSA feed additive evaluations shape European import and formulation standards. China's NMPA and GB standards enforce selenium content labeling and purity thresholds for domestic nutraceutical production. Stakeholders must monitor evolving organic certification requirements across multiple jurisdictions as traceability demands tighten raw material sourcing protocols.
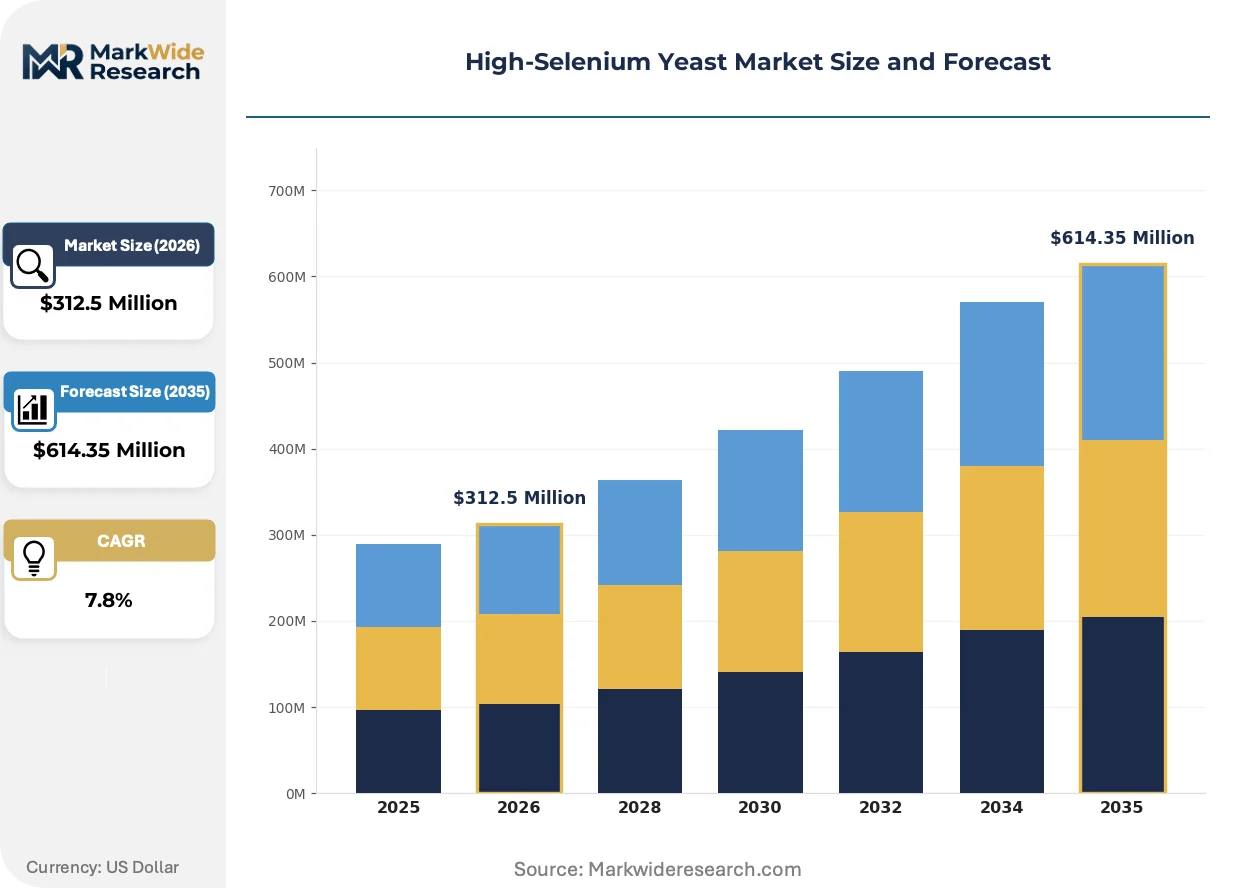
Market Dynamics
Fermentation capacity scarcity is compressing supply timelines as animal feed formulators accelerate organic selenium substitution ahead of EU Green Deal traceability deadlines.
Growth Catalysts
- EU Green Deal traceability mandates:Livestock supplement documentation requirements are pulling forward procurement cycles for certified organic selenium sources across European feed supply chains.
- Sodium selenite displacement in poultry nutrition:Hatchery operators are reformulating premixes to improve selenium retention rates in broiler and layer operations under tightening residue monitoring protocols.
- China nutraceutical channel expansion:Domestic selenium yeast production is scaling to serve aging-population dietary supplement demand through direct-to-consumer e-commerce platforms.
Market Restraints
- Strain development cost structure:Proprietary Saccharomyces cerevisiae selection programs require sustained R&D expenditure with multi-year gestation periods before commercial viability.
- Fermentation capacity concentration:Commercial-scale selenium yeast production clusters in select temperate-climate regions with established brewing and biotechnology infrastructure.
- Selenomethionine standardization limits:Batch-to-batch organic selenium content variation complicates premix formulation precision for pharmaceutical-grade applications.
Strategic Opportunities
- India pharmaceutical excipient channel:CDSCO regulatory pathways for selenium yeast in tablet and capsule formulations remain underdeveloped relative to mature nutraceutical markets.
- Precision livestock farming integration:Real-time mineral monitoring systems are creating demand for standardized organic selenium inputs with verified bioavailability metrics.
- USDA organic certification tailwinds:Premium livestock product labeling requirements are expanding addressable market for certified organic selenium yeast in organic meat and dairy supply chains.
Industry Challenges
- Fermentation specialist scarcity:Industrial microbiology talent pools with selenium bioaccumulation expertise remain shallow relative to standard yeast production skill bases.
- Multi-jurisdiction certification timelines:Synchronous FDA GRAS, EFSA feed additive, and NMPA nutraceutical approvals extend product launch cycles across major markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Selenium Yeast Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $614.35 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Selenium, Inorganic Selenium, Natural Selenium, Synthetic Selenium Application: Nutraceuticals, Animal Feed, Dietary Supplements, Pharmaceuticals End User: Agriculture, Food Industry, Health & Wellness, Pharmaceutical Companies Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Direct Sales |
| Companies Covered | Alltech Inc, Lesaffre Group, Lallemand Inc, Angel Yeast Co Ltd, Novus International Inc, Archer Daniels Midland Company, Cypress Systems Inc, Pharma Nord Inc, Biorigin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Selenium Yeast Market Trends and Innovations
Bioprocess intensification is compressing production economics while regulatory convergence across feed and food-grade specifications is reshaping quality assurance protocols.
Continuous fermentation systems with real-time selenium monitoring are miniaturizing capital requirements for mid-scale producers. Regional feed compounders in Brazil and Southeast Asia are piloting modular bioreactor installations to reduce import dependency. This distributed production architecture is compressing logistics costs and customs clearance timelines for time-sensitive premix formulations.
EFSA's revised feed additive evaluation frameworks are tightening purity thresholds for selenium yeast imports into European Union member states. Third-party laboratory certification requirements are proliferating as national feed safety authorities harmonize testing protocols. Premix formulators are responding by consolidating supplier relationships around vertically integrated producers with captive analytical capabilities.
Direct procurement relationships between livestock integrators and selenium yeast producers are displacing traditional distributor intermediaries in North American and European markets. Large poultry and swine operations are negotiating volume commitments with fermentation specialists to secure supply priority during capacity constraints. This channel compression is most visible in vertically integrated protein production systems spanning genetics, nutrition, and processing operations.
High-Selenium Yeast Market Segmentation
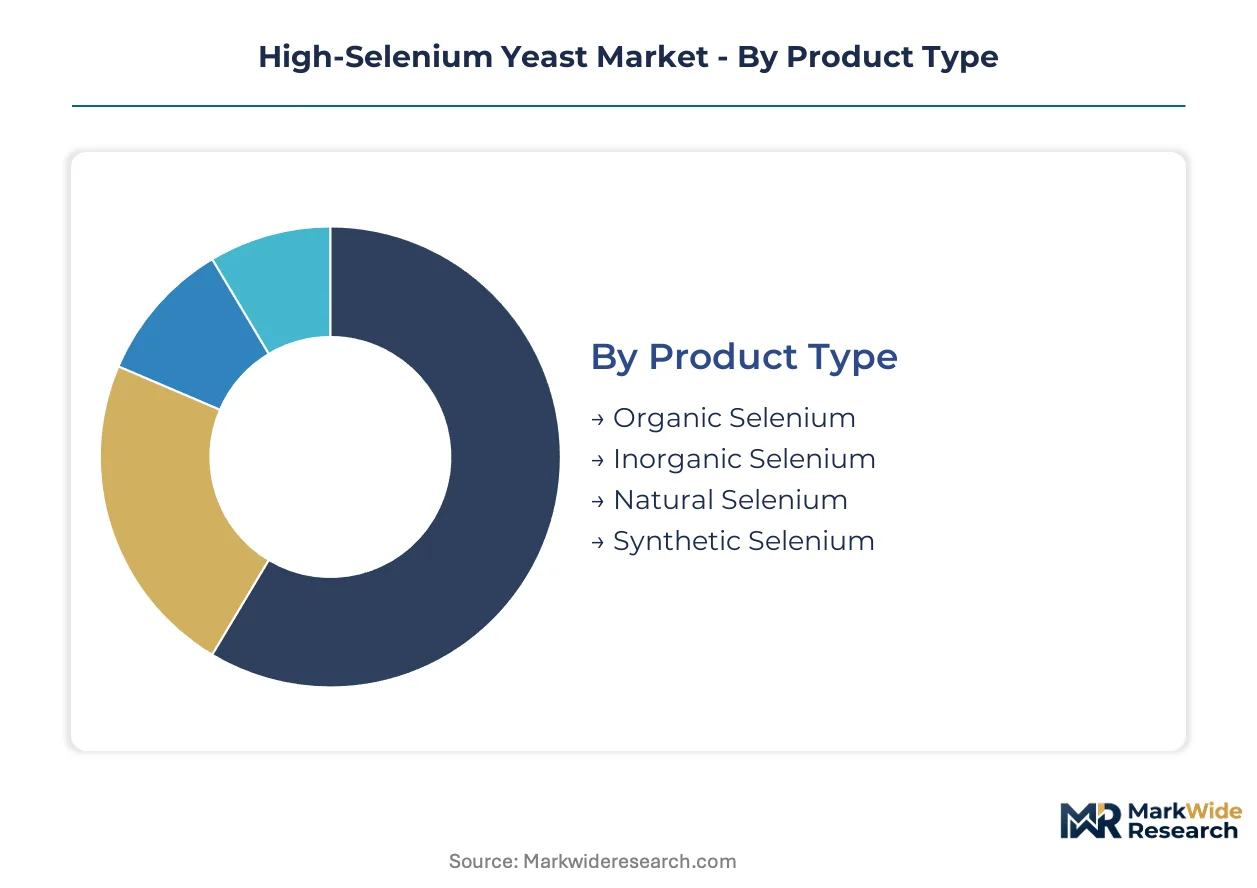
Selenium bioavailability specifications vary sharply across end-use categories, forcing suppliers to maintain parallel production lines with distinct certification protocols. Segmentation clarity determines which procurement channels absorb capacity constraints during EU Green Deal traceability transitions.
Product Type:
Inorganic selenium faces acute displacement pressure as feed formulators and nutraceutical brands accelerate organic source substitution under tightening residue regulations.
- Organic Selenium:Saccharomyces cerevisiae biomass with selenomethionine incorporation exceeding 90% of total selenium content. Poultry integrators in the United States are consolidating procurement around certified organic sources to satisfy USDA organic meat labeling requirements while reducing environmental selenium discharge.
- Inorganic Selenium:Sodium selenite and selenate salts with immediate ionic bioavailability but inferior retention in animal tissues. Price-sensitive layer operations in India continue sourcing inorganic forms where regulatory enforcement remains fragmented, though this segment contracts as export-oriented producers upgrade specifications.
- Natural Selenium:Plant-derived selenium from accumulator species such as Astragalus and Brassica. Limited commercial scale restricts availability to premium human nutrition applications where clean-label positioning justifies supply instability.
- Synthetic Selenium:Chemically synthesized selenomethionine produced through non-biological pathways. Pharmaceutical excipient applications in Japan favor synthetic purity where batch consistency outweighs organic certification value.
Organic selenium retains volume leadership; synthetic selenium holds the steepest expansion curve in pharmaceutical-grade specifications.
Application:
Margin structures diverge dramatically between bulk feed additive procurement and pharmaceutical excipient qualification, with certification costs consuming disproportionate value in smaller-volume channels.
- Nutraceuticals:Capsule and tablet formulations targeting antioxidant and thyroid support positioning. China's aging population is absorbing domestic yeast-derived selenium through direct-to-consumer e-commerce platforms, with NMPA registration requirements filtering out unqualified suppliers.
- Animal Feed:Premix incorporation for broiler, layer, swine, and ruminant nutrition. EU feed compounders are pulling forward organic selenium procurement timelines to meet Green Deal traceability documentation deadlines ahead of implementation phases.
- Dietary Supplements:Standalone selenium products and multivitamin complexes. FDA GRAS self-affirmation pathways dominate US market entry, though NSF and USP verification programs command retail shelf placement premiums.
- Pharmaceuticals:Active pharmaceutical ingredient and excipient applications with documented bioequivalence. CDSCO regulatory pathways in India remain underdeveloped relative to mature markets, creating first-mover advantages for qualified suppliers.
Animal feed commands absolute volume; pharmaceuticals generate the highest unit margins despite qualification barriers.
End User:
Customer technical capabilities determine whether selenium yeast procurement flows through distributor intermediaries or direct manufacturer relationships.
- Agriculture:Livestock integrators and independent feed mills with varying analytical sophistication. Vertically integrated protein producers in Brazil are negotiating direct supply agreements to bypass import distributor markups during currency volatility.
- Food Industry:Functional food and beverage fortification applications. Selenium yeast incorporation into bakery and dairy products concentrates in European markets where EFSA health claim approvals support marketing investment.
- Health & Wellness:Consumer-facing brands with emphasis on traceability storytelling. Subscription wellness platforms in the United States are demanding batch-level selenium speciation data for customer transparency portals.
- Pharmaceutical Companies:Multinational and generic manufacturers with exacting impurity profiles. ICH Q3D elemental impurity guidelines are elevating analytical requirements beyond standard feed-grade specifications.
Agriculture absorbs the largest tonnage; health and wellness segments are climbing fastest as direct-to-consumer channels expand.
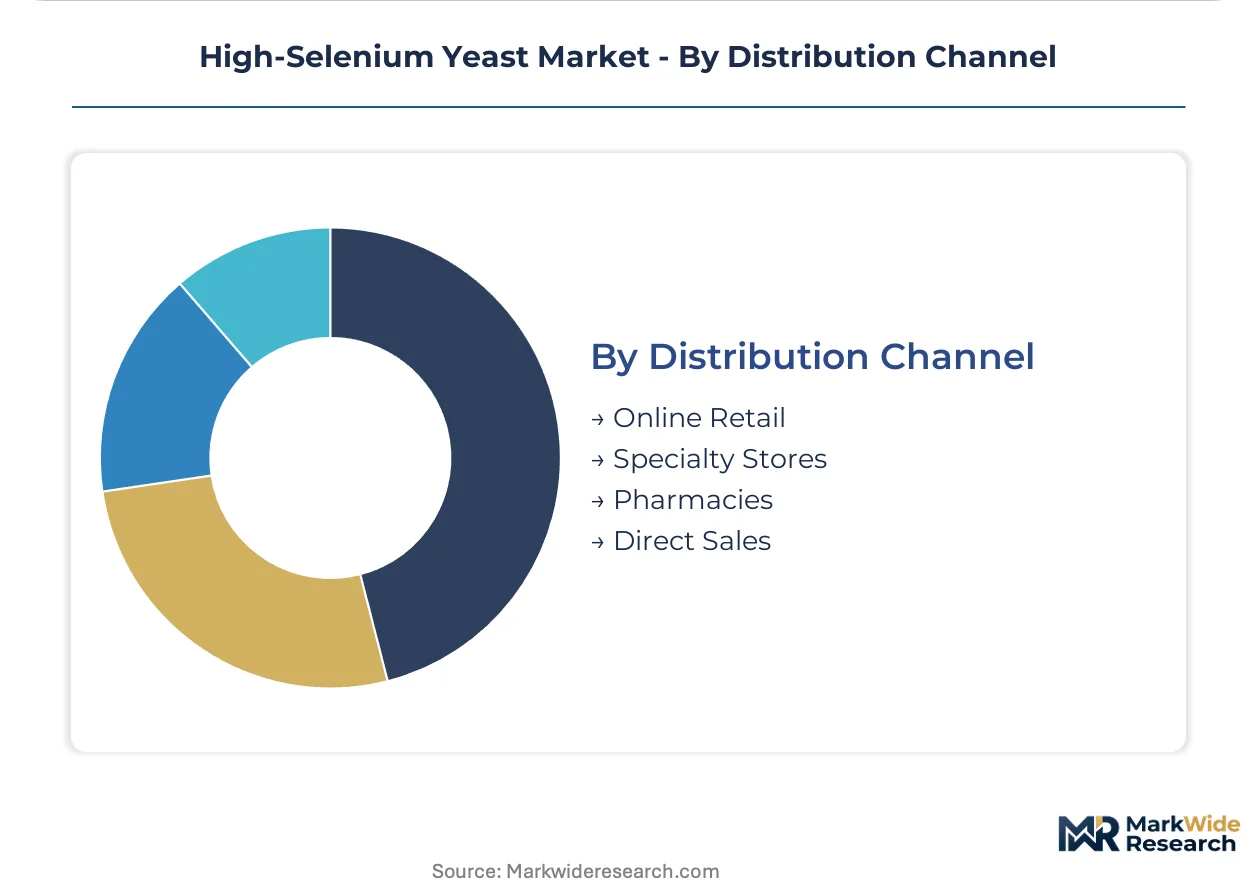
Distribution Channel:
Channel selection reflects buyer scale and technical confidence, with large integrators bypassing intermediaries while smaller operations rely on distributor technical support.
- Online Retail:E-commerce platforms serving individual consumers and small professional buyers. Amazon and specialized supplement marketplaces in Germany are consolidating selenium yeast capsule sales under private-label and third-party brand arrangements.
- Specialty Stores:Health food retailers and professional nutrition supply outlets. Staff training requirements favor branded products with established quality narratives over commodity positioning.
- Pharmacies:Regulated retail with pharmacist consultation requirements. European pharmacy chains are expanding private-label selenium offerings as category margins compress in prescription pharmaceuticals.
- Direct Sales:Manufacturer-to-buyer relationships eliminating distributor margins. North American poultry and swine integrators are consolidating procurement through volume commitments with fermentation specialists to secure supply priority.
Direct sales capture the largest margin pools; online retail is expanding most quickly as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Chinese fermentation clusters while North American buyers absorb import premiums during EU Green Deal transition periods.
United States
Poultry integrators in the Southeast are consolidating organic selenium procurement through direct manufacturer contracts to satisfy USDA organic meat labeling requirements. FDA GRAS self-affirmation pathways dominate dietary supplement channel entry, though NSF verification commands retail placement premiums. Kentucky-based fermentation research campuses anchor proprietary strain development programs serving North American feed compounders.
China
Domestic yeast producers are scaling output to serve aging-population nutraceutical demand through direct-to-consumer e-commerce platforms. NMPA registration requirements and GB standards enforce selenium content labeling thresholds that filter unqualified suppliers. Hubei province fermentation clusters supply regional premix formulators with certified organic selenium biomass.
Germany
EFSA feed additive evaluation frameworks are tightening purity thresholds for selenium yeast imports into European Union member states. EU Green Deal traceability mandates are pulling forward procurement cycles for certified organic selenium sources across German feed supply chains. Bavaria-based biotechnology infrastructure supports commercial-scale selenium bioaccumulation production.
Brazil
Vertically integrated protein producers are negotiating direct supply agreements to bypass import distributor markups during currency volatility periods. ANVISA regulatory pathways for pharmaceutical-grade selenium yeast remain underdeveloped relative to mature nutraceutical markets. São Paulo state feed compounders pilot modular bioreactor installations to reduce import dependency for time-sensitive premix formulations.
India
Price-sensitive layer operations continue sourcing inorganic selenium forms where regulatory enforcement remains fragmented, though export-oriented producers upgrade specifications. CDSCO regulatory pathways for selenium yeast in tablet and capsule formulations remain underdeveloped relative to mature markets. Maharashtra-based pharmaceutical excipient manufacturers represent first-mover opportunities for qualified suppliers.
High-Selenium Yeast Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with proprietary strain developers commanding premium positioning while scale-driven fermenters capture volume contracts. The vendor base clusters around three strategic archetypes: integrated biotechnology conglomerates with captive R&D infrastructure, specialized yeast producers with fermentation-drying assets, and diversified nutrition companies with distribution reach. Capacity expansion and backward integration into strain development represent the dominant competitive moves as supply timelines compress.
Among North American specialists, Alltech Inc and Lallemand Inc occupy positions within the integrated biotechnology tier, with the former anchoring proprietary research programs and the latter exemplifying vertically controlled fermentation and drying capabilities. Angel Yeast Co Ltd represents the scale-driven Chinese archetype, sitting within a domestic supply ecosystem serving regional premix formulators and direct-to-consumer nutraceutical channels.
| Leading Market Players |
|---|
| Alltech Inc |
| Lesaffre Group |
| Lallemand Inc |
| Angel Yeast Co Ltd |
| Novus International Inc |
| Archer Daniels Midland Company |
| Cypress Systems Inc |
| Pharma Nord Inc |
| Biorigin |
| Others |
Pricing and Supply Chain Analysis
Twenty-to-thirty-day fermentation cycle extensions during EU Green Deal traceability transitions are compressing spot-market availability and transferring pricing power toward German and Chinese biomass clusters with captive analytical capabilities.
Pricing Analysis
The customization-premium spread between pharmaceutical-grade selenomethionine certification and standard feed-grade biomass reaches three-to-five multiples, with FDA GRAS and EFSA feed additive documentation driving tier separation. Price differentiation hinges on organic selenomethionine purity thresholds and USDA organic certification status, while volume scale discounts anchor contract negotiations for North American poultry integrators. Pricing pressure intensifies in inorganic sodium selenite tiers as residue regulations accelerate displacement. Contract feed compounders exhibit highest price sensitivity; nutraceutical brands with direct-to-consumer channels absorb premium positioning.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Shanghai container terminals are amplifying landed costs for European and North American buyers sourcing from Hubei and Bavaria fermentation clusters. Supply concentrates in China, Germany, and the United States, with production drawing from pharmaceutical-grade glucose substrates and selenium dioxide feedstocks. Single-source vulnerability runs through proprietary Saccharomyces cerevisiae strain repositories held by integrated biotechnology conglomerates. Distribution runs through direct manufacturer relationships for large integrators and specialized distributor networks for regional compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high-selenium yeast market is entering a high-growth disruption phase as EU Green Deal traceability mandates and sodium selenite displacement converge, with fermentation capacity scarcity creating first-mover advantages for certified suppliers.
For Market Incumbents: Secure proprietary strain development programs in Kentucky and Bavaria research campuses to defend against modular bioreactor entrants in Brazil and Southeast Asia. Expand captive analytical capabilities to meet tightening EFSA purity thresholds and consolidate supplier relationships with vertically integrated poultry operations. For New Entrants and Emerging Players: CDSCO regulatory pathway gaps in Indian pharmaceutical excipient channels represent underserved white-space where qualified suppliers can establish first-mover positioning. Target precision livestock farming integration partnerships with real-time mineral monitoring system vendors as the most penetrable application wedge. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified nutrition conglomerates with underutilized fermentation assets and shallow selenium bioaccumulation expertise. Five-to-ten-year viability favors backward-integrated specialists with captive strain libraries. The signal to watch is EU Green Deal implementation phase acceleration triggering procurement timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Strain Development Program | Alltech Inc's Kentucky campus anchors multi-year Saccharomyces cerevisiae selection pipelines. |
| Modular Bioreactor Pilot Installation | São Paulo state feed compounders reduce import dependency for time-sensitive premix formulations. |
| CDSCO Regulatory Pathway Investment | Maharashtra pharmaceutical excipient manufacturers unlock first-mover advantages in tablet applications. |
| Direct Procurement Relationship Consolidation | North American poultry integrators bypass distributor markups through volume commitments with fermentation specialists. |
| USDA Organic Certification Expansion | Premium livestock product labeling requirements widen addressable market for certified organic selenium yeast. |
Research Methodology
Desk research of EFSA feed additive evaluation frameworks, FDA GRAS notification databases, and NMPA registration filings preceded structured interviews with fermentation R&D directors, feed compounder procurement leads, and nutraceutical brand managers. Secondary validation drew from customs trade data, SEC 10-K biotechnology disclosures, and GB standards documentation. Bottom-up capacity modeling triangulated against top-down premix formulation demand estimates across the analysis window.
Variance decomposition across organic selenium, inorganic selenium, and synthetic selenomethionine product tiers informed volume projections, with application splits in animal feed, nutraceuticals, and pharmaceuticals anchoring segmentation granularity. CAGRs derived from elasticity-adjusted substitution curves modeling sodium selenite displacement rates and EU Green Deal procurement acceleration. Strain development gestation periods and fermentation capacity utilization curves served as industry-specific forecast inputs throughout the modeling period.
Forecasts assume regulatory continuity in FDA GRAS self-affirmation pathways, EFSA feed additive evaluations, and NMPA nutraceutical registration regimes; material policy shifts would require re-modeling. Strain development cost inflation and fermentation specialist labor scarcity represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Fish Collagen Market
Nutritional Supplements
India Personalized Nutrition Market
Nutritional Supplements
Hangover Cure Products Market
Nutritional Supplements
Longevity and Anti-Aging Brain Health Supplements Market
Nutritional Supplements
Australia Collagen Peptides Market
Nutritional Supplements
North America Saffron Supplements Market
Nutritional Supplements
Apo-8 Carotenal Market
Nutritional Supplements
Enteral Nutrition Market
Nutritional Supplements
Custom Supplement Formulation Service Market
Nutritional Supplements
Soy Isoflavones Market
Nutritional Supplements
GLP-1 Hydration Product Market
Nutritional Supplements
Middle East and Africa Nutricosmetics Market
Nutritional Supplements
Global Oncology Nutrition Market
Nutritional Supplements
Raspberry Ketones Market
Nutritional Supplements
Health Ingredients Market
Nutritional Supplements
Diet Pills Market