
 Whey Basic Protein Isolates Market | 2026-2036
Whey Basic Protein Isolates Market Size, Share, and Industry Trends Forecast 2026-2036
Whey Basic Protein Isolates Market Analytics
Single-serve sachet and stick-pack formats are shifting buyer choice away from bulk canisters in the whey basic protein isolates space. Leprino Foods leverages its captive cheese-making infrastructure to secure raw whey streams at scale. Glanbia differentiates through sports nutrition brand ownership that pulls isolate demand upstream. Fonterra Co-operative Group anchors Oceania supply with integrated dairy processing across New Zealand and Australia.
Whey basic protein isolates are dairy-derived proteins refined to protein concentrations typically exceeding 90% on a dry basis, with minimal fat and lactose, produced through ion exchange or microfiltration for use in high-protein foods and supplements. The isolates segment leads value generation due to premium positioning in clinical and performance nutrition applications, while hydrolysates represent the fastest-growing product type as enzymatic pre-digestion addresses allergen sensitivity and absorption speed demands. Powder form dominates manufacturing economics, though ready-to-drink formats capture expanding convenience-oriented demand through health stores and online retail channels.
FDA food-labeling rules and EFSA health-claim frameworks govern protein content declarations and structure-function statements, compelling manufacturers to maintain batch-level analytical documentation. USDA organic certification and EU organic regulations create parallel supply chains with segregated processing and traceability requirements. Stakeholders must monitor evolving amino-acid profiling standards and clean-label expectations that determine supplier viability across athlete and health-conscious consumer segments.
Market Dynamics
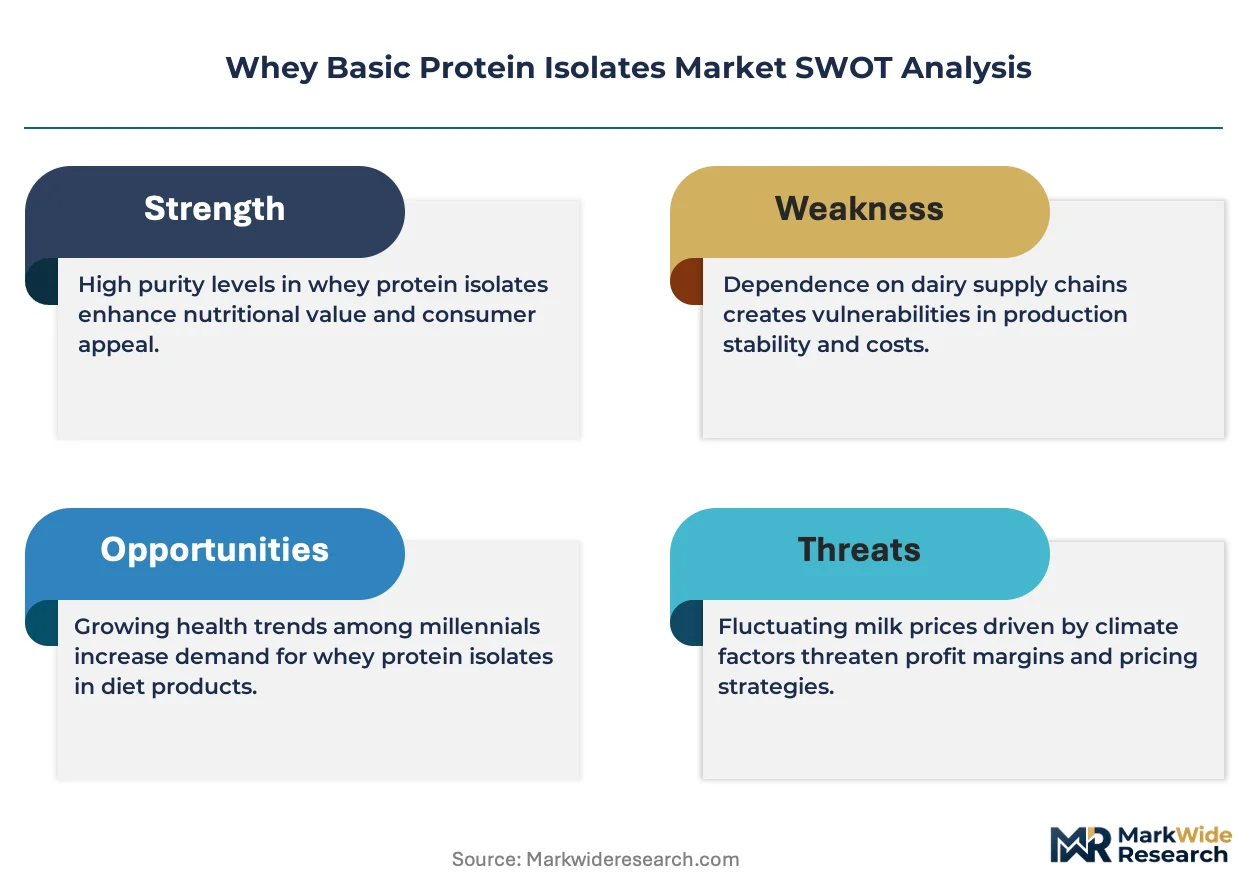
FDA and EFSA protein-labeling standards are compressing supplier margins by demanding batch-level amino-acid profiling documentation, forcing consolidation among isolate producers who lack in-house analytical laboratories.
Growth Catalysts
- Clean-label certification mandates:USDA organic and EU organic regulations are creating segregated supply chains that command premium pricing from health-conscious consumers in functional food applications.
- Enzymatic pre-digestion technology:Hydrolysate production through targeted proteolysis addresses allergen sensitivity demands in clinical nutrition and infant formula segments.
- United States fitness culture penetration:Sports nutrition brand consolidation pulls isolate demand upstream through direct supplier partnerships and volume commitments.
Market Restraints
- Raw whey supply concentration:Captive cheese-making infrastructure in select dairy cooperatives limits independent processor access to high-quality whey streams.
- Energy-intensive membrane filtration:Microfiltration and ion exchange processes face margin pressure from natural gas and electricity cost volatility in processing regions.
- Plant protein substitution:Pea and rice protein isolates capture formulation share in vegan-positioned sports nutrition and meal replacement categories.
Strategic Opportunities
- Ready-to-drink channel expansion:Convenience-oriented single-serve formats in health stores and direct-to-consumer platforms bypass traditional bulk canister distribution.
- EU Green Deal alignment:Carbon footprint labeling and sustainable dairy sourcing incentives reward processors with verified low-emission supply chains.
- Microbiome-targeted formulations:Prebiotic-protein combinations in gut health applications open formulation partnerships with digestive wellness brands.
Industry Challenges
- Proteomics analytical talent scarcity:Batch-level amino-acid profiling requires specialized food chemists and mass spectrometry operators in short supply across dairy processing regions.
- Legacy equipment retrofit costs:Existing spray-drying infrastructure requires capital-intensive upgrades to meet clean-label segregation and allergen-control standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whey Basic Protein Isolates Market |
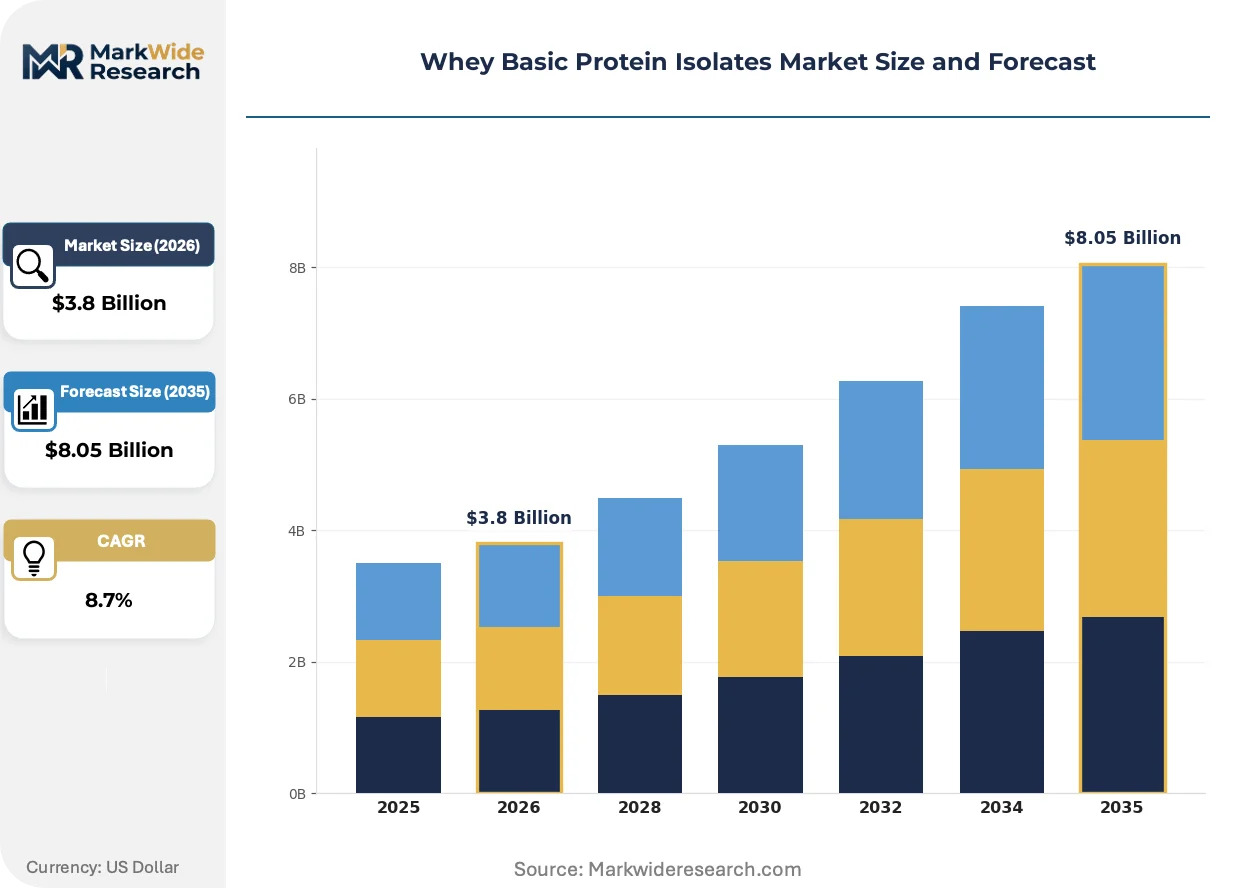
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrates, Isolates, Hydrolysates, Blends End User: Athletes, Fitness Enthusiasts, Health-Conscious Consumers, Vegan Options Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales Form: Powder, Liquid, Ready-to-Drink, Bars |
| Companies Covered | Koninklijke FrieslandCampina, Leprino Foods, Arla Foods, Milk Specialties Global, Davisco Foods International, Fonterra Co-operative Group, Hilmar Cheese Company, Agropur Ingredients, Glanbia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whey Basic Protein Isolates Market Evolving Landscape
Membrane filtration advances and enzymatic processing are compressing production economics while regulatory precision demands and channel fragmentation reshape competitive positioning across isolate supply chains.
Cross-flow microfiltration with ceramic membranes is rewriting purity-versus-yield tradeoffs in industrial-scale whey processing. Sports nutrition contract manufacturers are adopting these systems to reduce lactose carryover below 0.5% without protein denaturation. The technology is enabling smaller-batch flexibility that serves niche clinical nutrition specifications previously uneconomical at volume.
EFSA health-claim substantiation requirements are tightening structure-function statement documentation for protein products marketed across EU member states. Manufacturers must now maintain clinical trial evidence linking specific amino-acid profiles to claimed muscle maintenance benefits. German and French regulators are conducting coordinated enforcement sweeps that disqualify non-compliant products from e-commerce platforms.
Health practitioner channel partnerships are displacing traditional retail brokerage as the primary route to high-margin clinical nutrition segments. Registered dietitians and sports medicine physicians now specify isolate brands directly to patients, bypassing shelf-space competition. This pattern concentrates in United States metropolitan wellness clusters and Australian private practice networks where credentialing programs certify preferred supplier lists.
Whey Basic Protein Isolates Market Segmentation
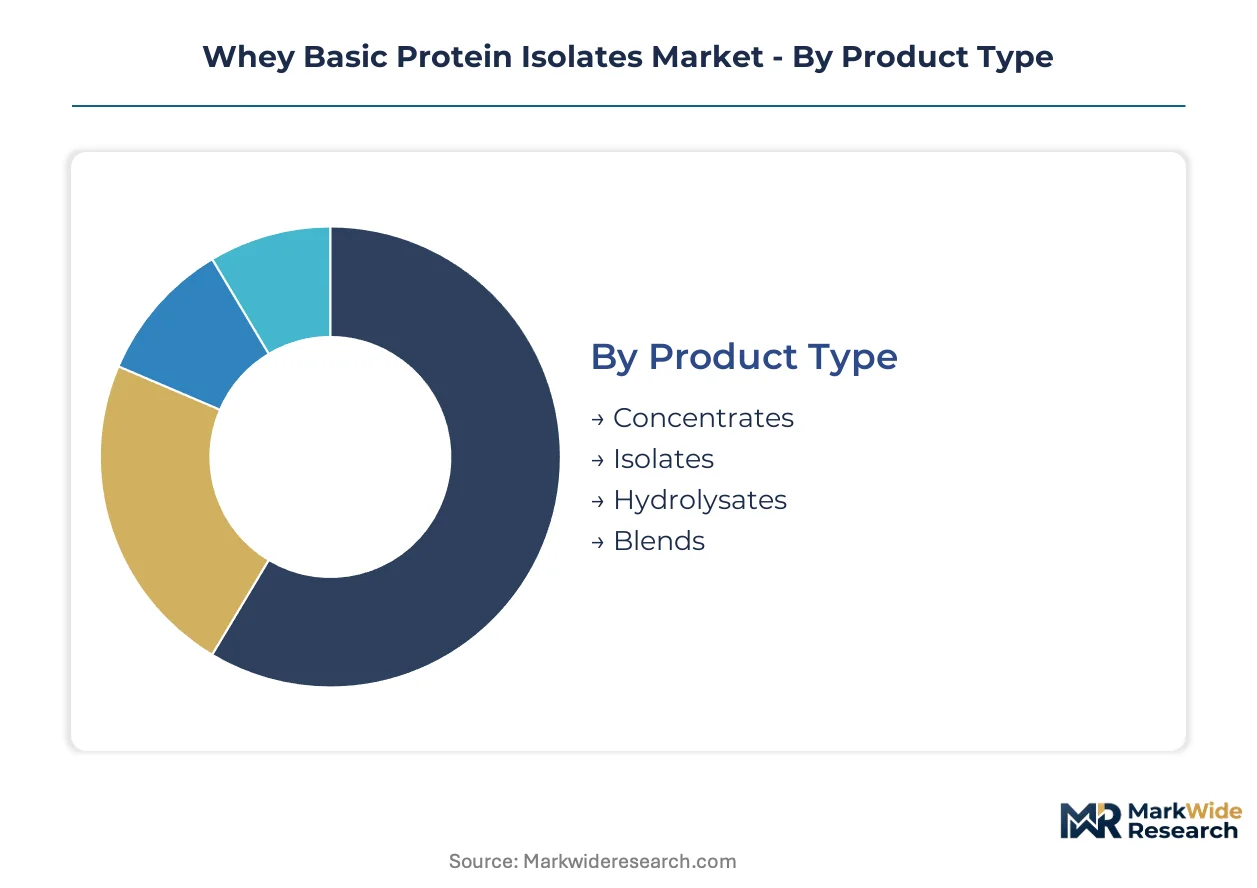
Segmentation in whey basic protein isolates determines capital allocation priorities across membrane filtration capacity, enzymatic processing lines, and packaging infrastructure. Each dimension reveals distinct margin structures and regulatory exposure that shape supplier positioning.
Product Type:
Capital intensity varies sharply across processing technologies, with ion exchange and microfiltration equipment representing the largest upfront investments.
- Isolates:Refined to protein concentrations exceeding 90% dry basis through ion exchange or cross-flow microfiltration, commanding premium positioning in clinical nutrition and performance applications where batch-level amino-acid documentation is mandatory. United States sports nutrition brands now specify isolate purity thresholds directly in supplier contracts, compressing margins for processors lacking in-house analytical laboratories.
- Hydrolysates:Produced through targeted enzymatic proteolysis that pre-digests protein chains for accelerated absorption and reduced allergenicity. Demand concentrates in infant formula and medical nutrition segments across Germany and France where EFSA health-claim substantiation requires clinical trial evidence linking specific peptide profiles to muscle maintenance benefits.
- Concentrates:Lower protein content (70-80%) retains more lactose and fat, serving cost-sensitive bakery and snack applications with simpler filtration requirements.
- Blends:Custom combinations of isolate, concentrate, and hydrolysate ratios tailored to specific brand positioning and price points.
Isolates absorb the bulk of installed membrane filtration capacity; hydrolysates are expanding most quickly as enzymatic processing addresses clinical nutrition specifications.
End User:
Customer type determines formulation complexity and certification requirements, with clinical and athletic segments demanding the most rigorous documentation.
- Athletes:Competitive and recreational competitors purchasing through sports nutrition brands and health practitioner channels, where registered dietitians specify isolate brands directly to patients in United States metropolitan wellness clusters.
- Fitness Enthusiasts:Regular gym attendees seeking convenience-oriented formats including single-serve sachets and ready-to-drink products through direct-to-consumer platforms.
- Health-Conscious Consumers:Broader demographic pursuing functional food integration, driving USDA organic and EU organic certification demand that creates segregated supply chains with premium pricing.
- Vegan Options:Plant-forward positioning that shifts formulation toward pea and rice protein isolates, capturing share in sports nutrition and meal replacement categories.
Athletes and fitness enthusiasts together dominate volume throughput; health-conscious consumers are climbing the fastest as clean-label certification penetrates mainstream retail.
Distribution Channel:
Channel selection dictates packaging format investments and margin capture, with direct and digital routes requiring distinct logistics infrastructure.
- Online Retail:Amazon, brand-owned sites, and specialty platforms enabling subscription models and personalized nutrition recommendations.
- Supermarkets:Mass retail placement demanding bulk canister formats and slotting fee negotiations that favor established suppliers with marketing budgets.
- Health Stores:GNC, Vitamin Shoppe, and independent retailers where practitioner partnerships and credentialing programs certify preferred supplier lists.
- Direct Sales:Multi-level marketing and practitioner-exclusive lines bypassing traditional retail brokerage for higher margin capture.
Online retail and health stores together command the steepest expansion trajectory; supermarkets retain the largest absolute volume but face share erosion to convenience-oriented channels.
Form:
Physical format shapes manufacturing economics and shelf-stability requirements, with powder dominating production scale and liquid formats demanding cold-chain investments.
- Powder:Spray-dried isolates in bulk canisters, sachets, and stick-packs offering lowest per-serving cost and longest shelf stability, though legacy equipment requires capital-intensive upgrades to meet clean-label segregation standards.
- Liquid:Concentrated protein solutions for industrial food manufacturing and beverage fortification, requiring refrigerated transport and shorter expiration windows.
- Ready-to-Drink:Single-serve bottles and cartons capturing convenience demand through health stores and direct-to-consumer platforms, bypassing traditional bulk canister distribution.
- Bars:Protein-fortified snack formats integrating isolates into bakery matrices for on-the-go consumption.
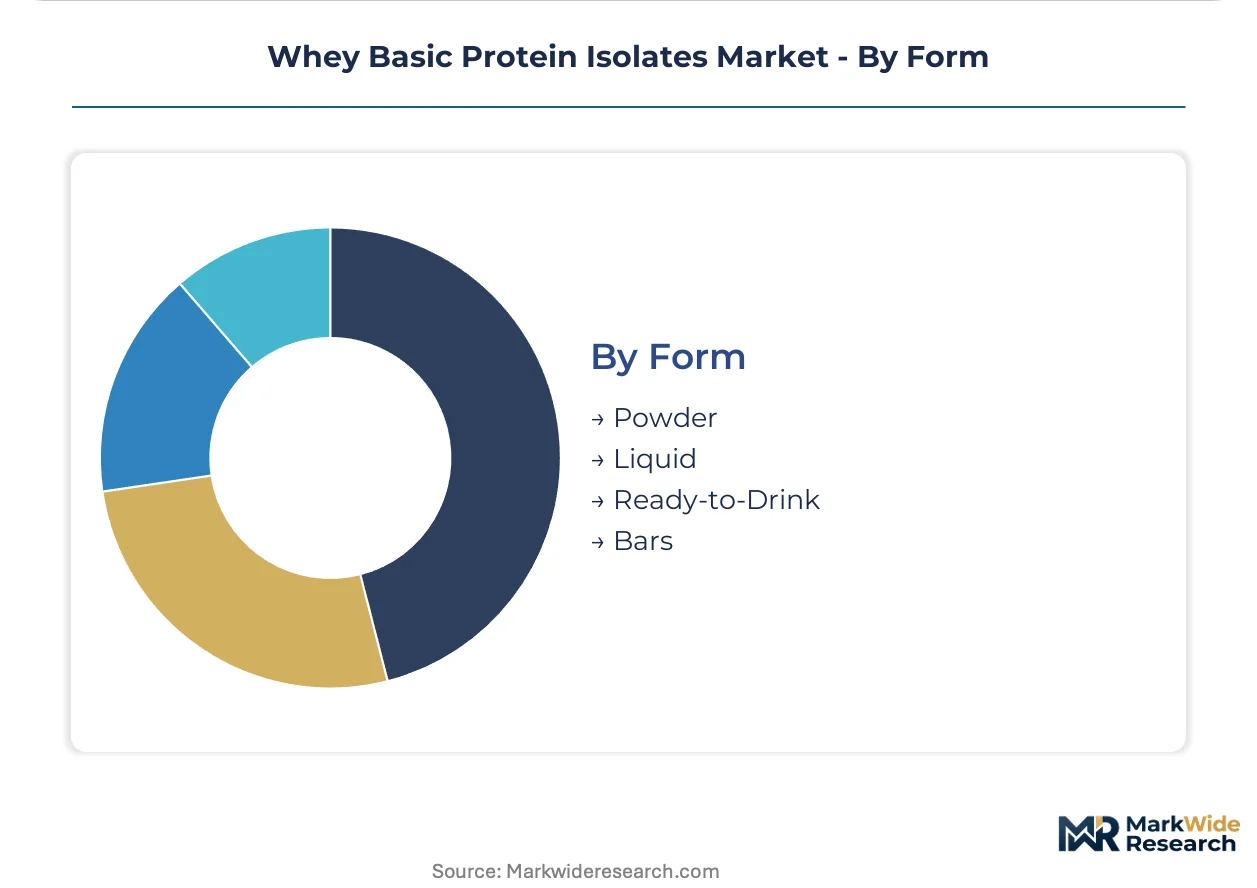
Powder retains the dominant share of production capacity; ready-to-drink formats are gaining share fastest as single-serve convenience reshapes purchasing patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in dairy-rich temperate zones while consumption clusters in fitness-centric urban markets. New Zealand and Australia dominate raw whey extraction through integrated cooperative structures. The United States, Germany, and United Kingdom absorb the bulk of finished isolate demand through sports nutrition and clinical nutrition channels.
United States
FDA food-labeling rules and sports nutrition brand consolidation pull isolate demand upstream through direct supplier partnerships. Registered dietitians in metropolitan wellness clusters now specify isolate brands directly to patients, bypassing traditional retail brokerage. California and Texas host the densest concentrations of contract manufacturing facilities serving practitioner-exclusive distribution channels.
Germany
EFSA health-claim substantiation requirements tighten structure-function statement documentation for protein products marketed across EU member states. German regulators coordinate with French authorities on enforcement sweeps that disqualify non-compliant products from e-commerce platforms. Bavaria anchors industrial-scale dairy processing with membrane filtration capacity serving clinical nutrition specifications.
New Zealand
Fonterra Co-operative Group leverages integrated dairy processing infrastructure across the North and South Islands to secure raw whey streams at scale. The country's national dairy regulator enforces strict traceability requirements that create segregated supply chains for organic certification. Canterbury and Waikato host the primary concentration of spray-drying and cross-flow microfiltration facilities.
United Kingdom
Clean-label certification mandates from USDA organic and EU organic regulations command premium pricing from health-conscious consumers in functional food applications. London and Southeast England concentrate demand through health practitioner channel partnerships and direct-to-consumer platforms. The Food Standards Agency maintains batch-level analytical documentation requirements that reshape supplier qualification protocols.
Australia
TGA oversight of therapeutic goods intersects with sports nutrition positioning as local brands pursue listed medicine status for high-purity isolates. Private practice networks in Sydney and Melbourne operate credentialing programs that certify preferred supplier lists for registered dietitians. Victoria and New South Wales host the bulk of ready-to-drink formulation and packaging infrastructure.
Whey Basic Protein Isolates Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation pressures mount as FDA and EFSA protein-labeling standards demand batch-level amino-acid profiling documentation that favors processors with in-house analytical laboratories. Three archetypes dominate: integrated dairy cooperatives with captive whey supply, sports nutrition brand owners pulling demand upstream, and independent processors reliant on spot whey markets. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure membrane filtration scale and enzymatic processing capabilities.
Within the integrated cooperative tier, Fonterra Co-operative Group and Arla Foods exemplify the archetype of dairy-origin conglomerates with backward control over raw whey streams. Glanbia occupies a distinct position as a brand-owner that pulls isolate demand upstream through sports nutrition portfolio ownership. Leprino Foods represents the specialist processor model leveraging captive cheese-making infrastructure to secure supply scale. These three anchors illustrate how production geography and channel integration determine competitive viability across purity thresholds and certification tiers.
| Leading Market Players |
|---|
| Koninklijke FrieslandCampina |
| Leprino Foods |
| Arla Foods |
| Milk Specialties Global |
| Davisco Foods International |
| Fonterra Co-operative Group |
| Hilmar Cheese Company |
| Agropur Ingredients |
| Glanbia |
| Others |
Value Network & Pricing Analysis
Captive cheese-making infrastructure in the United States and New Zealand anchors both supply security and pricing power for whey basic protein isolate processors, creating tiered margin structures that favor integrated cooperatives over independent spot-market buyers facing raw whey access constraints.
Pricing Analysis
Margin tightening in standard-grade isolates reflects energy-intensive membrane filtration costs and natural gas price volatility in processing regions. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic certified isolates from conventional grades and unbranded commodity powders. FDA batch-level amino-acid profiling documentation demands compress margins for processors lacking in-house analytical laboratories. Health-conscious consumers in functional food applications show lowest price sensitivity, while cost-sensitive bakery and snack manufacturers drive volume at economy tiers.
Supply Chain Analysis
Raw whey supply rests on integrated dairy cooperatives in New Zealand, the United States, and Australia with captive cheese-making infrastructure. Ion exchange resins, ceramic membrane modules, and enzymatic hydrolysis catalysts constitute critical processing inputs sourced from specialty chemical producers. Single-source vulnerability concentrates in Fonterra's dominance of Oceania raw whey extraction. Distribution runs through sports nutrition brand direct partnerships, health practitioner channels, and direct-to-consumer platforms bypassing traditional retail brokerage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Whey basic protein isolates represent a consolidation play as FDA and EFSA protein-labeling standards force weaker processors without in-house analytical capabilities toward exit or acquisition.
For Market Incumbents: Anchor membrane filtration scale in United States and New Zealand dairy clusters to secure raw whey streams against spot-market volatility. Invest in cross-flow microfiltration with ceramic membranes to reduce lactose carryover below 0.5% and serve niche clinical nutrition specifications. Deepen backward integration into captive cheese-making infrastructure to defend against independent processor consolidation. Pursue USDA organic and EU organic certification to capture premium pricing from health-conscious consumer segments. For New Entrants and Emerging Players: EU Green Deal carbon footprint labeling requirements in Germany and France open a window for processors with verified low-emission supply chains to displace incumbent commodity suppliers. Target ready-to-drink single-serve formats in direct-to-consumer platforms where convenience-oriented fitness enthusiasts bypass established bulk canister distribution. Enter through microbiome-targeted prebiotic-protein formulations partnering with digestive wellness brands in Australian private practice networks. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated dairy cooperatives seeking membrane filtration capacity and sports nutrition brand owners pulling isolate demand upstream. Long-term viability favors processors with in-house proteomics analytical laboratories and clean-label segregation infrastructure. Watch enzymatic hydrolysis technology maturation as the inflection signal determining hydrolysate margin capture in clinical nutrition segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Cheese-Making | Fonterra and Leprino Foods secure raw whey streams at scale, locking out independent spot-market competitors from high-quality inputs. |
| Ceramic Membrane Filtration Upgrade | Cross-flow microfiltration systems reduce lactose carryover below 0.5% without protein denaturation, enabling clinical nutrition tier entry. |
| USDA Organic Certification Investment | Segregated supply chains command premium pricing from health-conscious consumers in United States functional food applications. |
| Health Practitioner Channel Partnership | Registered dietitians in metropolitan wellness clusters specify isolate brands directly, bypassing shelf-space competition and capturing higher margins. |
| Enzymatic Hydrolysis Capacity Addition | Targeted proteolysis addresses EFSA health-claim substantiation requirements for infant formula and medical nutrition segments in Germany and France. |
Research Methodology
SEC filings from Glanbia and Fonterra, FDA food-labeling guidance documents, and EFSA health-claim substantiation databases formed the secondary backbone. Primary interviews with sports nutrition brand procurement directors, dairy cooperative supply chain managers, membrane filtration equipment specialists, and registered dietitians in United States metropolitan wellness clusters validated demand patterns. Bottom-up volume modeling across isolate, hydrolysate, concentrate, and blend product types triangulated against top-down dairy industry whey stream availability estimates.
Historical trendline analysis of whey protein ingredient pricing and sports nutrition finished goods consumption established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated product type, end user archetype, distribution channel, and physical form dimensions with protein concentration thresholds and certification tiers as industry-specific variables. CAGR derivation synthesized membrane filtration capacity expansion schedules, enzymatic processing technology adoption curves, and regulatory documentation requirement phase-ins.
The model assumes a particular technology adoption path; alternative pathways for ceramic membrane filtration scale-up would alter the outlook. Forecasts reflect assumptions regarding FDA amino-acid profiling enforcement intensity and EFSA health-claim substantiation evidentiary standards. Commodity whey pricing volatility, plant protein substitution acceleration, and proteomics analytical talent scarcity represent specific risk factors that could revise projections. A small set of triggers—regulatory enforcement sweeps, cooperative merger activity, and enzymatic hydrolysis yield breakthroughs—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Protein Powder Market
Nutritional Supplements
North America Dietary Supplements Market
Nutritional Supplements
Nutritional Lipids Market
Nutritional Supplements
Multivitamin and Mineral Supplements Market
Nutritional Supplements
Vietnam Collagen Supplements Market
Nutritional Supplements
Hair Growth Supplements Market
Nutritional Supplements
Bypass Fat Supplement Market
Nutritional Supplements
Calcium HMB Market
Nutritional Supplements
Krill Oil Market
Nutritional Supplements
Lactoferrin Market
Nutritional Supplements
Japan Dietary Supplements Market
Nutritional Supplements
Medium-Chain Triglycerides Market
Nutritional Supplements
Asia-Pacific Feed Prebiotics Market
Nutritional Supplements
Europe Omega 3 Market
Nutritional Supplements
Global Multivitamin Capsules and Tablets Market
Nutritional Supplements
Multi Nutritional Supplement Market