
 Austria Protein Supplements Market | 2026-2036
Austria Protein Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Austria Protein Supplements Market Outlook
Pea protein isolates is shifting toward whey protein concentrates across Austrian formulation labs as dairy-based alternatives regain cost competitiveness after two years of volatile legume pricing. The Hut Group leverages its Manchester-based supply infrastructure to dominate direct-to-consumer channels across German-speaking Europe. Glanbia PLC anchors its position through captive dairy processing in Ireland, securing whey concentrate streams for Austrian private-label contracts. Body Attack Sports Nutrition GmbH & Co. KG specializes in localized flavor profiles and portion formats calibrated for Alpine fitness culture.
Austria protein supplements comprise formulated nutritional products delivering isolated or concentrated protein macronutrients, typically processed through microfiltration, ion exchange, or enzymatic hydrolysis to achieve protein content between 70% and 95% by dry weight, designed primarily for muscle protein synthesis support and dietary protein augmentation. Whey protein occupies the dominant revenue position due to superior leucine bioavailability and established consumer trust, while pea protein segments accelerate fastest among vegan-adjacent fitness enthusiasts seeking hypoallergenic alternatives. Powder formulations sustain the largest volume share through cost efficiency and dosing flexibility, though ready-to-drink formats capture expanding margin pools in convenience-oriented urban channels.
Austria's Lebensmittelgesetzbuch framework and EU EFSA health claims regulations constrain permissible marketing language around muscle-building efficacy, compelling manufacturers to invest in clinical substantiation or retreat to generic wellness positioning. The EU F-Gas Regulation and national packaging ordinances further pressure producers to eliminate fluorinated greenhouse gas propellants in aerosol-dispensed products and transition toward monomaterial recyclable containers. Stakeholders must monitor evolving Novel Food consultations from Brussels that could reclassify emerging fermentation-derived proteins before committing to capacity expansion.
Market Dynamics
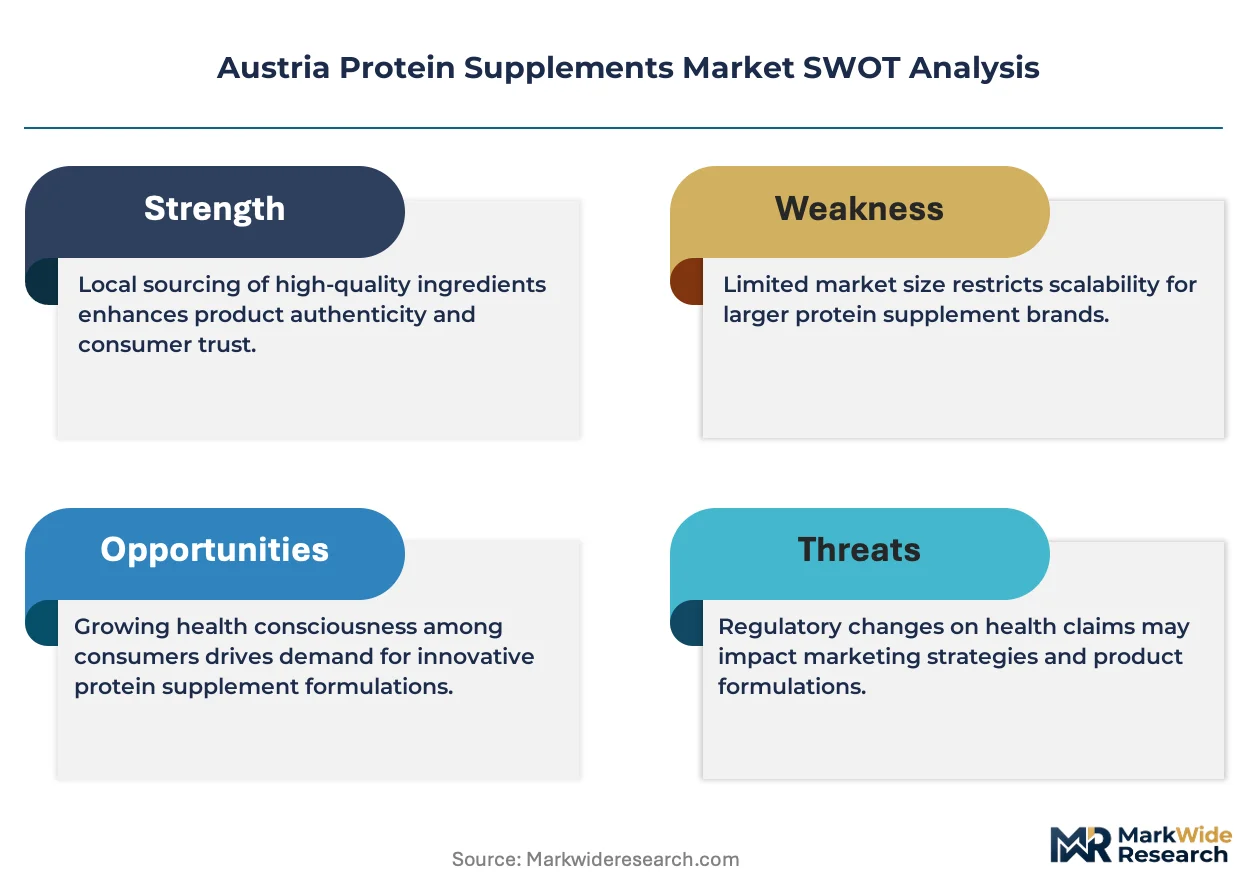
Lebensmittelgesetzbuch enforcement and EFSA health claim restrictions are compressing permissible marketing vocabulary for Austrian protein supplement manufacturers, forcing investment in clinical substantiation or retreat to generic wellness positioning.
Growth Catalysts
- Fitness Enthusiast Demographics:Gym participation among younger Austrian demographics is accelerating, creating concentrated demand clusters in Vienna and surrounding urban corridors where premium health clubs and specialized nutrition retailers operate.
- Novel Food Classification Pressure:Austria's national food safety regulator enforces strict plant-derived protein classifications, pushing manufacturers toward whey and casein reformulations with established regulatory clearance.
- Ready-to-Drink Format Expansion:Convenience-oriented urban channels in Austrian metropolitan areas are capturing expanding margin pools through portable protein delivery systems.
Market Restraints
- Legume Price Volatility:Two years of volatile pea protein input costs have destabilized plant-based formulation economics, shifting Austrian labs back toward dairy-derived alternatives.
- Supply Concentration Risk:Whey concentrate streams depend heavily on Irish dairy processing infrastructure, creating geographic single-point vulnerability for Austrian private-label contracts.
- EFSA Marketing Constraints:EU health claims regulations constrain muscle-building efficacy language, limiting differentiation through performance marketing.
Strategic Opportunities
- Urban Corridor Saturation:Vienna's dense clustering of premium health clubs presents white space for specialized nutrition retail expansion beyond current penetration levels.
- F-Gas Regulation Compliance:EU F-Gas Regulation phaseout of fluorinated greenhouse gas propellants creates first-mover advantage for manufacturers transitioning to monomaterial recyclable containers.
- Fermentation-Derived Proteins:Brussels Novel Food consultations may reclassify emerging fermentation-derived proteins, opening regulatory pathway for capacity expansion ahead of competitors.
Industry Challenges
- Clinical Substantiation Expertise:EFSA-compliant health claim documentation requires specialized regulatory affairs talent scarce in Austrian supplement manufacturing.
- Packaging Reconfiguration Costs:National packaging ordinances mandate elimination of multi-material containers, forcing capital deployment toward monomaterial production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Austria Protein Supplements Market |
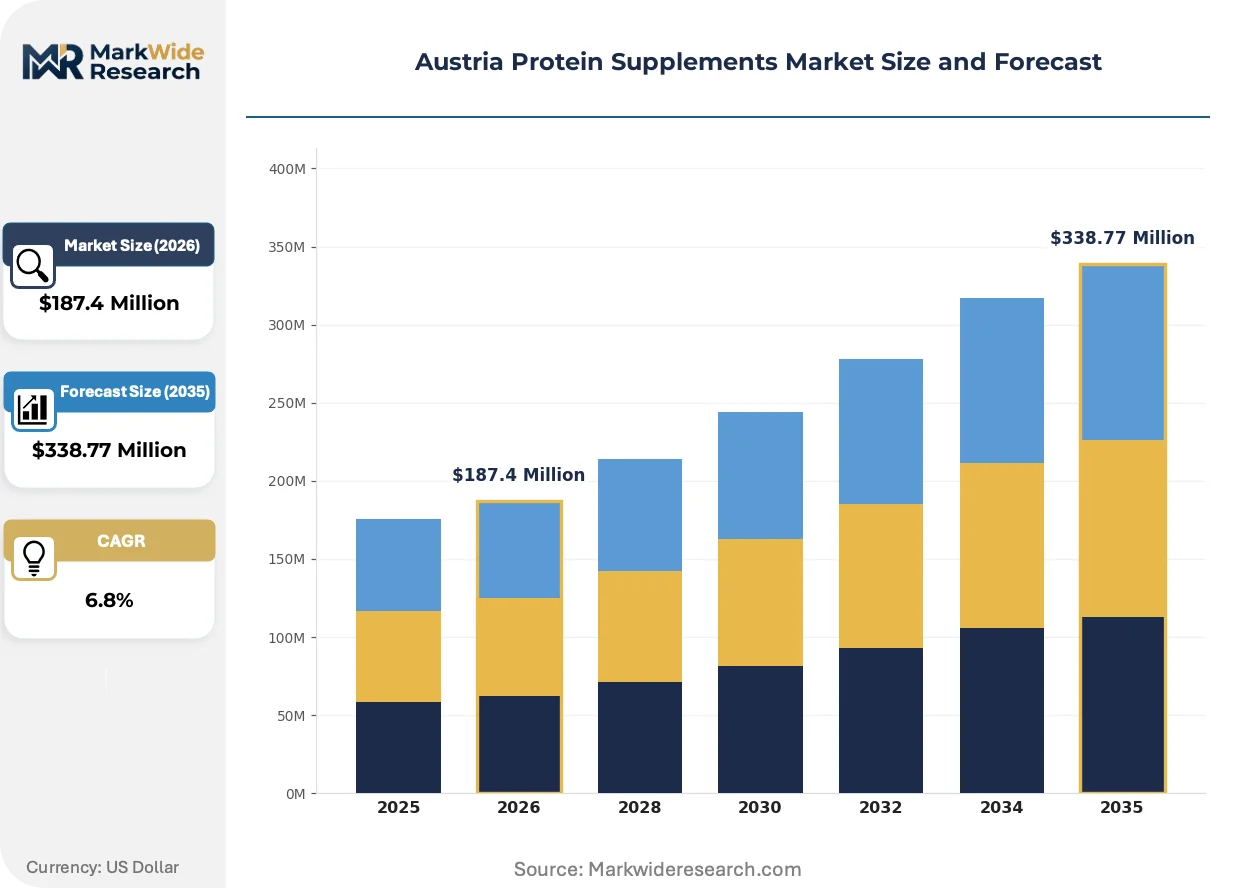
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Soy Protein, Pea Protein End User: Bodybuilders, Athletes, Fitness Enthusiasts, Seniors Form: Powder, Bar, Ready-to-Drink, Capsules Distribution Channel: Online Retail, Supermarkets, Health Stores, Gyms |
| Companies Covered | Bulk Powders, General Mills Inc., The Hut Group (Myprotein), Amway, MusclePharm Corporation, Glanbia PLC, Clif Bar & Company, Body Attack Sports Nutrition GmbH & Co. KG, Peeroton GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Austria Protein Supplements Market Strategic Shifts
Microfiltration and enzymatic hydrolysis advances are compressing production timelines while EU regulatory frameworks reshape competitive positioning around substantiation capabilities rather than marketing claims.
Precision fermentation for protein production is decentralizing supply chain control away from traditional agricultural inputs. Alpine fitness culture adopters in Austrian mountain regions are integrating these bioengineered proteins faster than urban counterparts. This technology is decentralizing raw material sourcing from dairy cooperatives and legume suppliers toward controlled bioreactor environments.
EU F-Gas Regulation mandates are eliminating fluorinated greenhouse gas propellants in aerosol-dispensed products by specified phaseout deadlines. Austrian manufacturers face compressed compliance timelines for reformulating delivery mechanisms and retooling production equipment. Ready-to-drink format producers bear disproportionate adaptation costs as propellant-dependent dispensing systems require complete redesign.
Direct-to-consumer channel migration is fragmenting traditional retail relationships in Austrian protein supplement distribution. Specialized nutrition retailers in Vienna's urban corridors are losing volume share to Manchester-based supply infrastructure serving German-speaking Europe. Fitness enthusiasts under 35 demonstrate highest channel-switching velocity, abandoning brick-and-mortar consultation for algorithm-driven personalization.
Austria Protein Supplements Market Segmentation
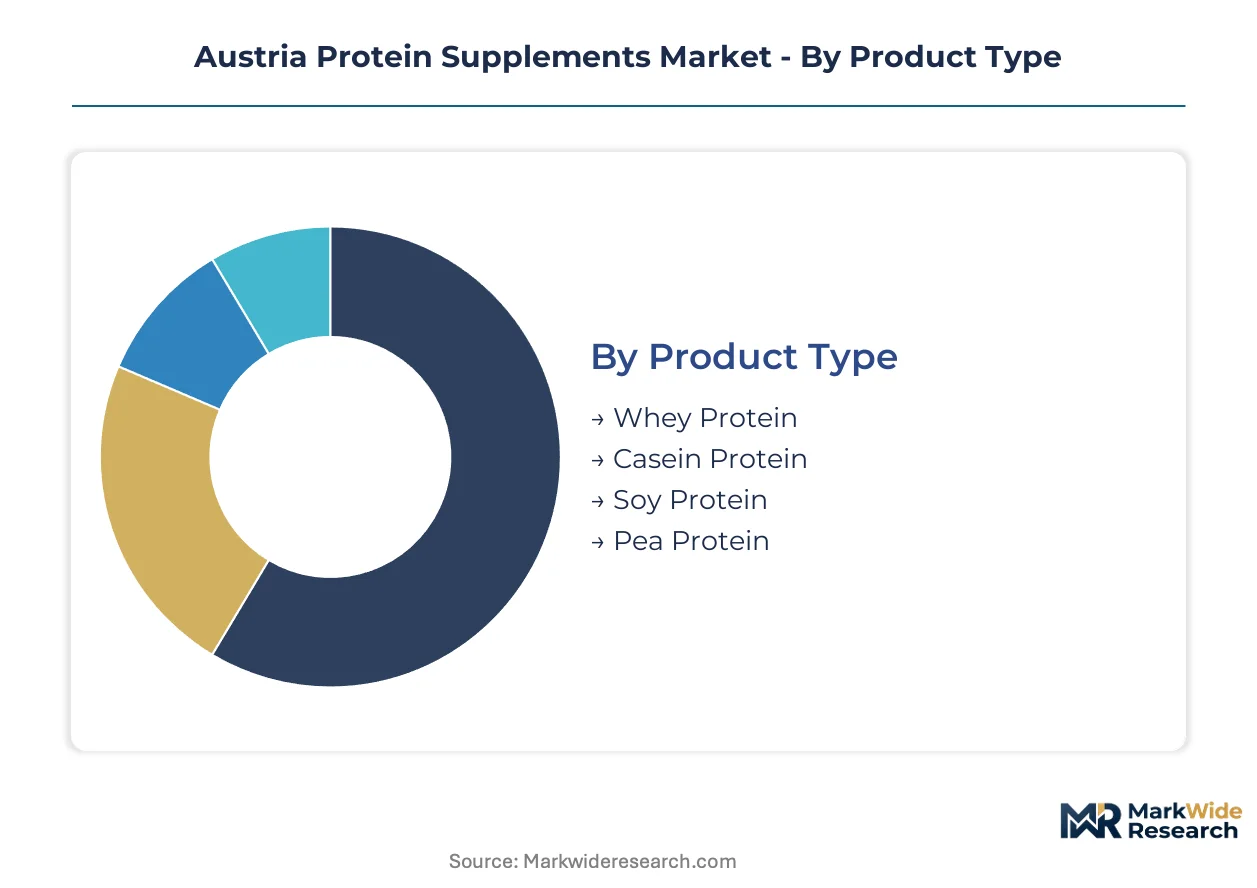
Austrian protein supplement purchasing patterns diverge sharply between performance-oriented gym culture and convenience-driven urban lifestyles. Segment boundaries increasingly blur as manufacturers reformulate across protein sources and delivery formats to capture cross-category buyers.
Product Type:
Protein source selection hinges on leucine bioavailability thresholds and regulatory clearance status under EFSA Novel Food frameworks.
- Whey Protein:Microfiltered and ion-exchanged concentrates deliver 70-90% protein by dry weight with superior leucine absorption kinetics. Demand clusters in Vienna's premium health clubs where bodybuilders prioritize rapid muscle protein synthesis support.
- Pea Protein:Isolates processed through enzymatic hydrolysis achieve hypoallergenic profiles with 80-85% protein content. Austrian vegan-adjacent fitness enthusiasts in Salzburg and Innsbruck drive fastest expansion despite volatile legume input pricing.
- Casein Protein:Micellar structures enable sustained amino acid release over 6-8 hours, appealing to overnight recovery protocols.
- Soy Protein:Concentrates and isolates from defatted soybean flakes serve cost-conscious segments with established allergen labeling.
Volume sits with whey protein; growth tilts toward pea protein.
End User:
Demographic targeting reflects distinct consumption occasions from competitive performance to age-related sarcopenia prevention.
- Fitness Enthusiasts:Recreational gym-goers seeking general body composition improvement represent the largest addressable population. Vienna's younger demographic cohorts exhibit highest participation rates and channel-switching velocity toward direct-to-consumer platforms.
- Bodybuilders:Competitive and amateur physique athletes demand precise macronutrient timing with 2-2.5g per kg bodyweight protein targets. Specialized nutrition retailers in Graz and Linz maintain dedicated consultation services for this segment.
- Athletes:Endurance and team sport competitors prioritize portable formats for training schedules.
- Seniors:Adults over 65 targeting sarcopenia mitigation through dietary protein augmentation.
Revenue concentrates with fitness enthusiasts; margin expansion favors bodybuilders.
Form:
Format economics determine manufacturing capital allocation between bulk powder infrastructure and aseptic liquid processing lines.
- Powder:Bulk containers and single-serve sachets deliver cost-efficient protein dosing at 15-30g per serving. Alpine fitness culture across Tyrol and Vorarlberg sustains highest per-capita consumption through traditional shake preparation rituals.
- Ready-to-Drink:UHT-processed beverages in monomaterial bottles capture urban convenience demand. Vienna metropolitan commuters drive steepest expansion trajectory despite F-Gas Regulation compliance costs for dispensing systems.
- Bar:Extruded and cold-pressed formats combine protein with carbohydrate matrices for meal replacement occasions.
- Capsules:Encapsulated isolates serve precision-dosing requirements with minimal digestive volume.
Unit economics favor powder; premiumization flows to ready-to-drink.
Distribution Channel:
Channel selection determines customer acquisition cost structures and brand positioning latitude under Lebensmittelgesetzbuch marketing constraints.
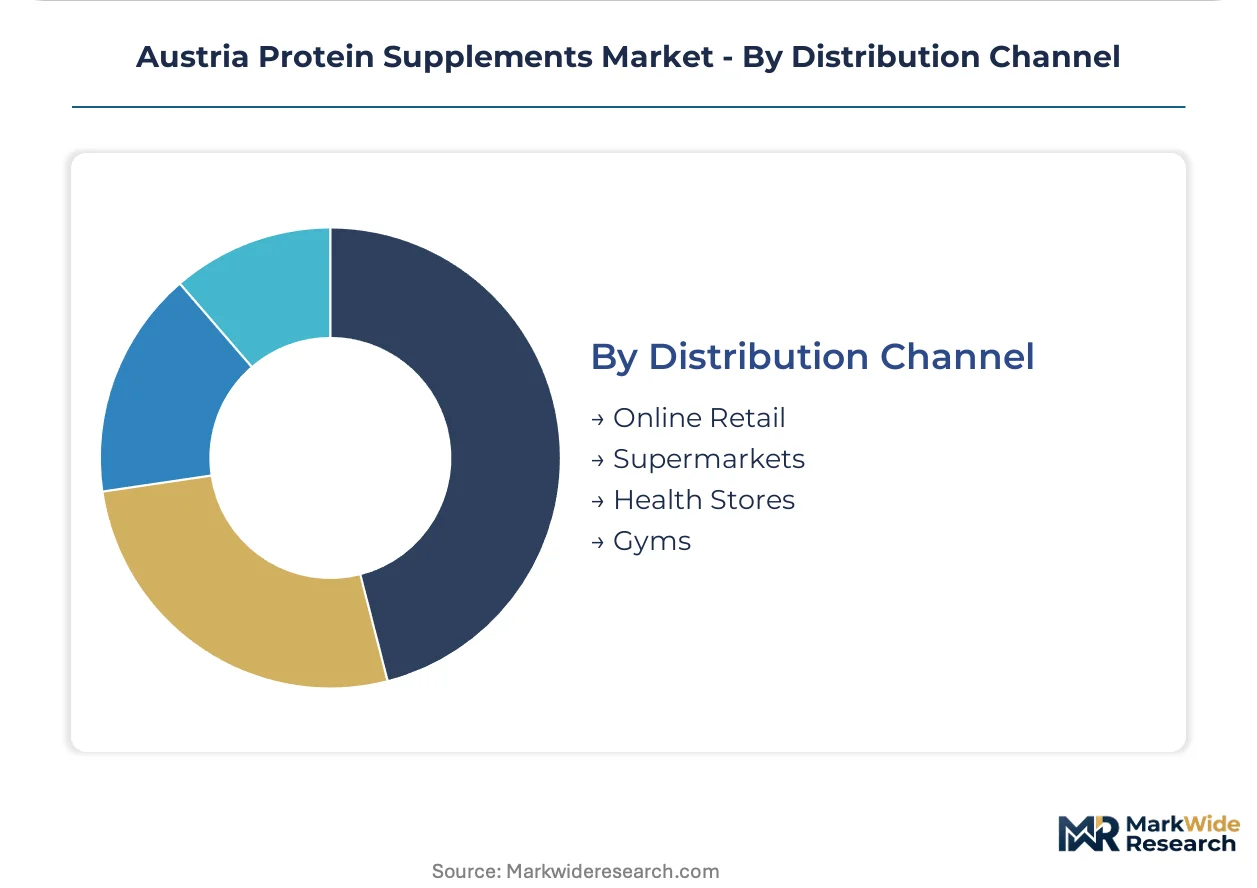
- Online Retail:Manchester-based supply infrastructure enables algorithm-driven personalization with subscription replenishment models. Austrian consumers under 35 demonstrate highest migration velocity from brick-and-mortar consultation to digital discovery.
- Health Stores:Specialized nutrition retailers in Vienna's urban corridors provide clinical substantiation guidance for EFSA-compliant product selection. Staff expertise justifies premium pricing for whey protein isolates and emerging fermentation-derived alternatives.
- Supermarkets:Mass-market placement requires simplified health claim positioning within generic wellness frameworks.
- Gyms:On-site vending and pro-shop distribution captures impulse consumption immediately post-workout.
Transaction volume dominates online retail; customer lifetime value peaks in health stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Austrian protein supplement demand concentrates in Vienna and surrounding urban corridors where premium health clubs and specialized nutrition retailers cluster densely. Younger demographics drive gym participation growth, creating concentrated consumption nodes that outpace rural per-capita spending. EFSA health claims regulations and national Lebensmittelgesetzbuch enforcement constrain marketing vocabulary uniformly across the federal territory.
Vienna
Fitness enthusiasts under 35 dominate consumption, with highest channel-switching velocity toward direct-to-consumer platforms. EFSA Novel Food classifications shape permissible product formulations entering Viennese retail. The capital's premium health club density supports specialized nutrition retailer expansion beyond current penetration levels.
Lower Austria
Commuter belt populations favor ready-to-drink formats for convenience-oriented consumption between Vienna employment centers and residential zones. National packaging ordinances mandate monomaterial recyclable containers, pressuring local distributors to reconfigure logistics. St. Pölten corridor retailers report fastest growth in portable protein delivery systems.
Upper Austria
Industrial manufacturing employment sustains steady demand for cost-efficient powder formulations among shift workers. EU F-Gas Regulation compliance deadlines accelerate propellant system redesign for aerosol-dispensed products. Linz metropolitan area health stores maintain dedicated consultation services for bodybuilder segments.
Styria
Alpine fitness culture across Graz and surrounding mountain regions integrates precision fermentation proteins faster than urban counterparts. Lebensmittelgesetzbuch enforcement requires clinical substantiation investment for muscle-building efficacy claims. Regional dairy processing infrastructure supports whey concentrate supply security.
Tyrol and Vorarlberg
Traditional shake preparation rituals sustain highest per-capita powder consumption through Alpine fitness culture. Volatile legume input pricing has destabilized plant-based formulation economics, shifting labs toward dairy-derived alternatives. Innsbruck and Bregenz urban centers capture expanding ready-to-drink margin pools despite higher compliance costs.
Austria Protein Supplements Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers reformulate across protein sources and delivery formats to capture cross-category buyers. The vendor base spans multinational dairy processors, specialized sports nutrition formulators, and direct-to-consumer platform operators. Three archetypes anchor competitive positioning: Irish dairy-integrated whey suppliers, Manchester-based digital-first distributors, and Alpine-culture-calibrated local specialists. M&A activity and regulatory compliance investment constitute the primary competitive moves, with EFSA substantiation requirements and F-Gas packaging mandates forcing capital deployment toward certification and retooling.
Among German-speaking regional specialists, Body Attack Sports Nutrition GmbH & Co. KG and Peeroton GmbH occupy positions calibrated for Alpine fitness culture preferences. The Hut Group's Manchester infrastructure exemplifies direct-to-consumer platform dominance across German-speaking Europe. Glanbia PLC anchors the dairy-integrated supply tier through Irish processing assets securing whey concentrate streams.
| Leading Market Players |
|---|
| Bulk Powders |
| General Mills Inc. |
| The Hut Group (Myprotein) |
| Amway |
| MusclePharm Corporation |
| Glanbia PLC |
| Clif Bar & Company |
| Body Attack Sports Nutrition GmbH & Co. KG |
| Peeroton GmbH |
| Others |
Value Chain & Pricing Dynamics
Fitness enthusiasts under 35 in Vienna's premium health clubs concentrate purchasing power toward subscription-based replenishment models, compressing spot-market pricing flexibility for legacy powder formats while elevating algorithm-driven personalized nutrition premiums.
Pricing Analysis
Volume concentrates in bulk whey protein powders serving cost-conscious gym-goers, while margins accrue to ready-to-drink formats and precision-dosed capsules. Three-tier pricing structure across premium isolates, standard concentrates, and economy blends separates clinical substantiation tiers under EFSA frameworks. Pricing pressure stems from Irish dairy input cost transmission and volatile legume protein economics, forcing reformulation trade-offs. Price sensitivity peaks among recreational fitness enthusiasts in commuter corridors; bodybuilders and competitive athletes exhibit lowest elasticity due to performance-dependent purchasing.
Supply Chain Analysis
Freight cost differentials between Irish dairy processing hubs and Austrian distribution centers compress margins on whey concentrate imports, favoring regional dairy cooperative partnerships. Raw material sourcing draws from Irish whey streams, Dutch pea protein isolates, and domestic Alpine dairy cooperatives. Single-source vulnerability concentrates in Irish captive processing infrastructure for private-label whey contracts. Distribution runs through Manchester-based direct-to-consumer platforms, Vienna health store networks, and supermarket mass-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation proteins are displacing legacy agricultural extraction methods, reconfiguring competitive advantage around bioreactor capacity and Novel Food regulatory navigation rather than dairy cooperative relationships or legume supply contracts.
For Market Incumbents: Deploy clinical substantiation investment as the primary defensive lever. Secure EFSA-compliant health claim documentation for muscle protein synthesis efficacy to differentiate against generic wellness positioning. Build captive bioreactor partnerships for fermentation-derived protein streams ahead of Brussels Novel Food reclassification, insulating against Irish dairy supply concentration risk and legume price volatility. For New Entrants and Emerging Players: Capture white space in Alpine fitness culture segments across Tyrol and Vorarlberg where traditional shake preparation rituals sustain powder demand yet incumbent presence remains thin. Target ready-to-drink convenience gaps in St. Pölten commuter corridors underserved by current distribution density. Enter through direct-to-consumer algorithm personalization, leveraging Manchester supply infrastructure for rapid market testing. For Investors and Strategic Acquirers: The window for entry favors fermentation-derived protein specialists with pending Novel Food consultations and established Austrian distribution relationships. Long-term viability hinges on regulatory navigation capabilities rather than brand equity. Watch Brussels Novel Food consultation outcomes as the critical inflection signal for capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Substantiation Investment | EFSA-compliant health claim documentation enables muscle-building efficacy marketing differentiation. |
| Bioreactor Capacity Partnership | Precision fermentation protein sourcing decentralizes supply from Irish dairy cooperative dependence. |
| Monomaterial Packaging Transition | F-Gas Regulation compliance eliminates fluorinated propellants and captures sustainability positioning. |
| Direct-to-Consumer Platform Buildout | Algorithm-driven personalization captures Vienna's under-35 fitness enthusiast channel-switching velocity. |
| Novel Food Regulatory Navigation | Brussels consultation engagement secures first-mover positioning for reclassified fermentation proteins. |
Study Parameters
Independent corroboration across sports nutrition formulators, regulatory affairs specialists at EFSA consultation participants, dairy processing procurement leads, and specialized health store operators underwrites the qualitative findings. Secondary validation draws from EU Novel Food consultation databases, Austrian Lebensmittelgesetzbuch enforcement records, Irish Dairy Board trade statistics, and customs data on protein isolate imports. Bottom-up demand modeling triangulates against top-down category sizing from retail audit channels.
Rate-of-change decomposition separates volume expansion from value premium capture across the projection horizon. Segmentation dimensions encompass protein source type, delivery format, end-user demographic, and distribution channel intensity. CAGRs derive from trend extrapolation of gym participation rates, protein consumption per capita trajectories, and channel migration velocities. Forecast inputs incorporate EFSA health claim approval timelines and F-Gas Regulation compliance cost curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Brussels Novel Food reclassification timing and Irish dairy cooperative capacity allocation shifts. Forecasts reflect documented assumptions on regulatory pathway clarity and input cost transmission elasticity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Africa Beta Glucan Market
Nutritional Supplements
Ferrous Fumarate Market
Nutritional Supplements
Andro Supplements Market
Nutritional Supplements
Chewable Energy Tablet Market
Nutritional Supplements
Folate Market
Nutritional Supplements
Organic Protein Powder Market
Nutritional Supplements
Testosterone Booster Market
Nutritional Supplements
Argentina Nutraceuticals Market
Nutritional Supplements
Stress Relief Supplements Market
Nutritional Supplements
Olive Supplements Market
Nutritional Supplements
Immunity Boosting Food Market
Nutritional Supplements
Activated Charcoal Supplement Market
Nutritional Supplements
Biotin Supplement Market
Nutritional Supplements
Global Nootropics Brain Supplements Market
Nutritional Supplements
Fish Protein Isolate Market
Nutritional Supplements
Inositol Market